
 Paper Tapes Market | 2026-2036
Paper Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Tapes Market Outlook
China's Jiangsu and Zhejiang provinces are adding coated paper tape capacity at scale, a build-out that is reshaping regional supply dynamics. 3M Company leverages its St. Paul R&D campus to sustain pressure-sensitive adhesive leadership across electronics assembly lines. tesa SE anchors European automotive masking applications through Hamburg-based formulation labs. Shurtape Technologies LLC competes aggressively in North American construction-grade masking through Hickory, North Carolina distribution centers.
Paper tapes are flexible strips of kraft, crepe, or flatback paper substrates coated with adhesive systems, typically specified by tensile strength, elongation at break, and temperature resistance thresholds for clean removal. They seal cartons, mask surfaces during industrial finishing, bond components in temporary assembly, and decorate educational or retail displays. Masking tape dominates volume in construction and automotive refinishing where residue-free removal commands premium positioning, while gummed tape accelerates fastest in corrugated packaging as fulfillment centers abandon plastic alternatives. Water-based adhesives lead on regulatory compliance trajectories; hot melt formulations retain cost advantages in high-speed carton sealing.
EPA guidelines on volatile organic compound emissions influence solvent-based adhesive formulations in U.S. manufacturing facilities. REACH registration requirements and the EU Green Deal's packaging waste directives compel European converters toward repulpable, plastic-free tape constructions. China's MEE enforces discharge standards on coating operations in the Yangtze River Delta. Stakeholders must monitor how fragmented national recycling certifications reshape product specifications and determine which adhesive chemistry investments align with tightening cross-border compliance.
Market Dynamics
E-commerce fulfillment centers are systematically abandoning plastic carton sealing tapes as sustainability mandates tighten across major logistics corridors, forcing adhesive converters to reconfigure coating lines for water-activated gummed formulations.
Growth Catalysts
- GB Standards Compliance:China's updated packaging recyclability regulations are pressuring converters toward repulpable adhesive chemistries that eliminate plastic film backings.
- Automotive Refinishing Demand:Temperature-resistant masking tapes specified for clean removal now anchor volume in collision repair networks across industrialized manufacturing bases.
- Corrugated Packaging Automation:High-speed carton sealing lines in fulfillment hubs are accelerating specification of reinforced water-activated tapes that bond instantly to recycled fiber surfaces.
Market Restraints
- Crude-Derived Input Volatility:Petroleum-based hot melt adhesive resins expose margin structures to naphtha price swings that converters cannot fully pass through.
- Coating Capacity Concentration:Jiangsu and Zhejiang provinces control disproportionate substrate coating capacity, creating single-source vulnerability for European and North American distributors.
- Solvent Adhesive Regulatory Friction:EPA volatile organic compound emission limits are forcing costly formulation transitions away from toluene-based systems in U.S. manufacturing facilities.
Strategic Opportunities
- Indian Pharmaceutical Export Packaging:Mumbai-Pune manufacturing clusters present underexploited demand for certified carton sealing tapes meeting international cold-chain documentation standards.
- EU Green Deal Tailwinds:Packaging waste directives and REACH registration requirements are creating first-mover advantage for converters offering plastic-free, repulpable tape constructions.
- Digital Print Convergence:Integration of variable-data printing directly onto gummed tape surfaces enables brand authentication and tracking without secondary labeling operations.
Industry Challenges
- Adhesive Formulation Expertise Gap:Shortage of polymer chemists specializing in starch-based and dextrin adhesive systems limits converter ability to scale water-activated production.
- Cross-Border Certification Complexity:Fragmented national recycling certifications require parallel testing protocols that extend product launch timelines by 8-14 months.
- Legacy Equipment Retrofit Costs:Converting solvent-based coating lines to water-based systems demands capital outlays that strain mid-tier manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Tapes Market |
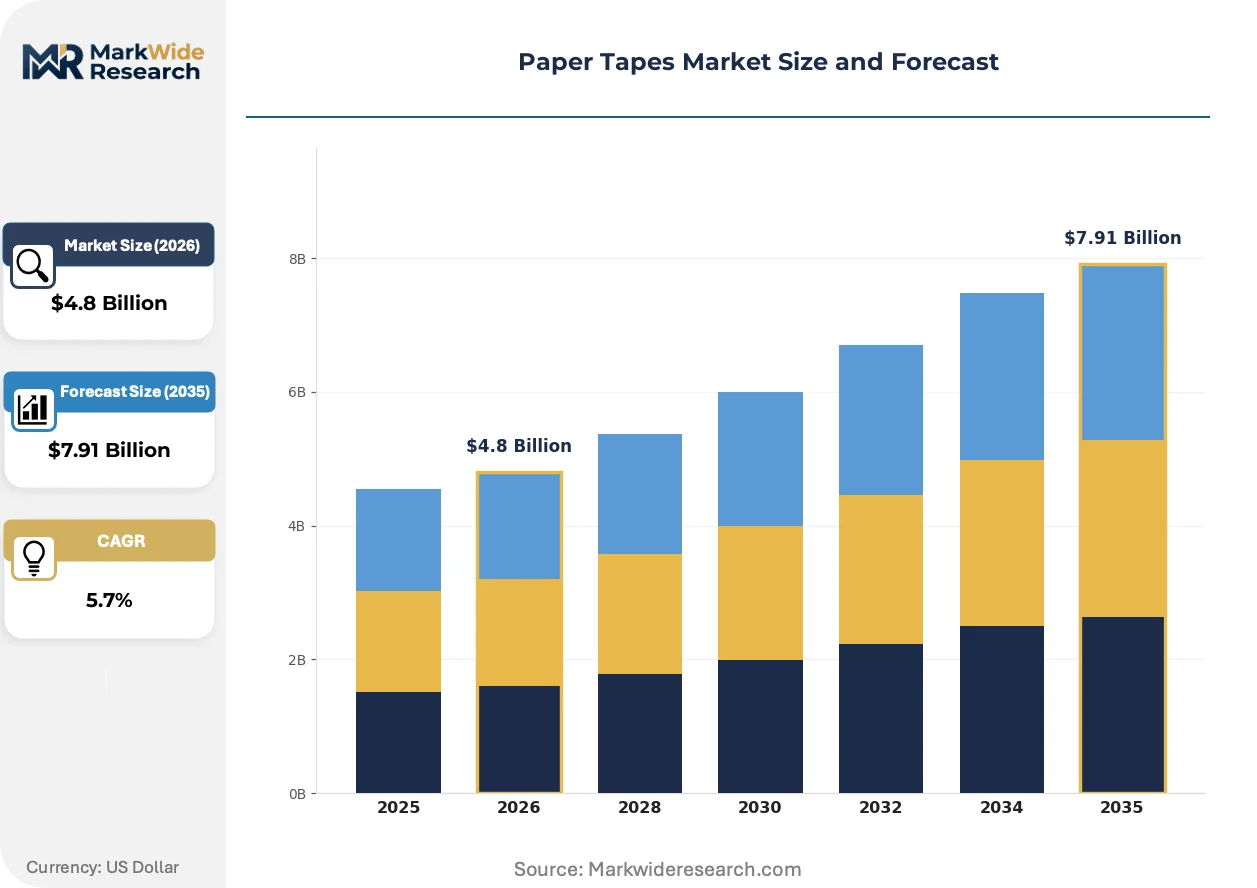
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Masking Tape, Double-Sided Tape, Gummed Tape, Specialty Tape Application: Electronics, Arts & Crafts, Packaging, Construction Adhesive Type: Water-Based, Solvent-Based, Hot Melt, Pressure Sensitive End User: Manufacturing, Retail, Education, Healthcare |
| Companies Covered | Nitto Denko Corporation, Avery Dennison Corporation, 3M Company, Scapa Group Ltd., Berry Global Inc., Shurtape Technologies LLC, tesa SE, Saint-Gobain Performance Plastics, Intertape Polymer Group Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Tapes Market Strategic Shifts
Adhesive chemistry and substrate engineering are converging to eliminate plastic components from tape constructions while maintaining performance thresholds that industrial buyers demand for high-speed automated applications.
Water-activated gummed tape is migrating from niche e-commerce applications to mainstream corrugated packaging lines as fulfillment operators face Scope 3 emissions scrutiny. Amazon and major third-party logistics providers now specify starch-based adhesives and unbleached kraft backings for outbound carton sealing. This migration is compressing demand for pressure-sensitive plastic tapes in the most volume-intensive packaging segments.
REACH registration requirements and the EU Green Deal's packaging waste directives are compelling European converters to eliminate silicone release liners and plastic film backings from tape constructions. The industrial consequence is accelerated R&D investment in direct-coated repulpable formulations that perform through temperature and humidity extremes. Automotive masking applications in Germany and France are most affected, with OEMs now auditing supplier sustainability credentials alongside technical specifications.
Consolidated buying by mega-fulfillment networks is compressing supplier margins and shifting procurement toward multi-year framework agreements with sustainability-linked pricing adjustments. Distributors serving mid-tier manufacturers are being disintermediated as Amazon, Walmart, and regional logistics operators contract directly with adhesive converters. This pattern is most visible in North American e-commerce corridors where packaging volume concentrates among fewer buyers demanding volume-scale pricing with carbon accounting documentation.
Paper Tapes Market Segmentation
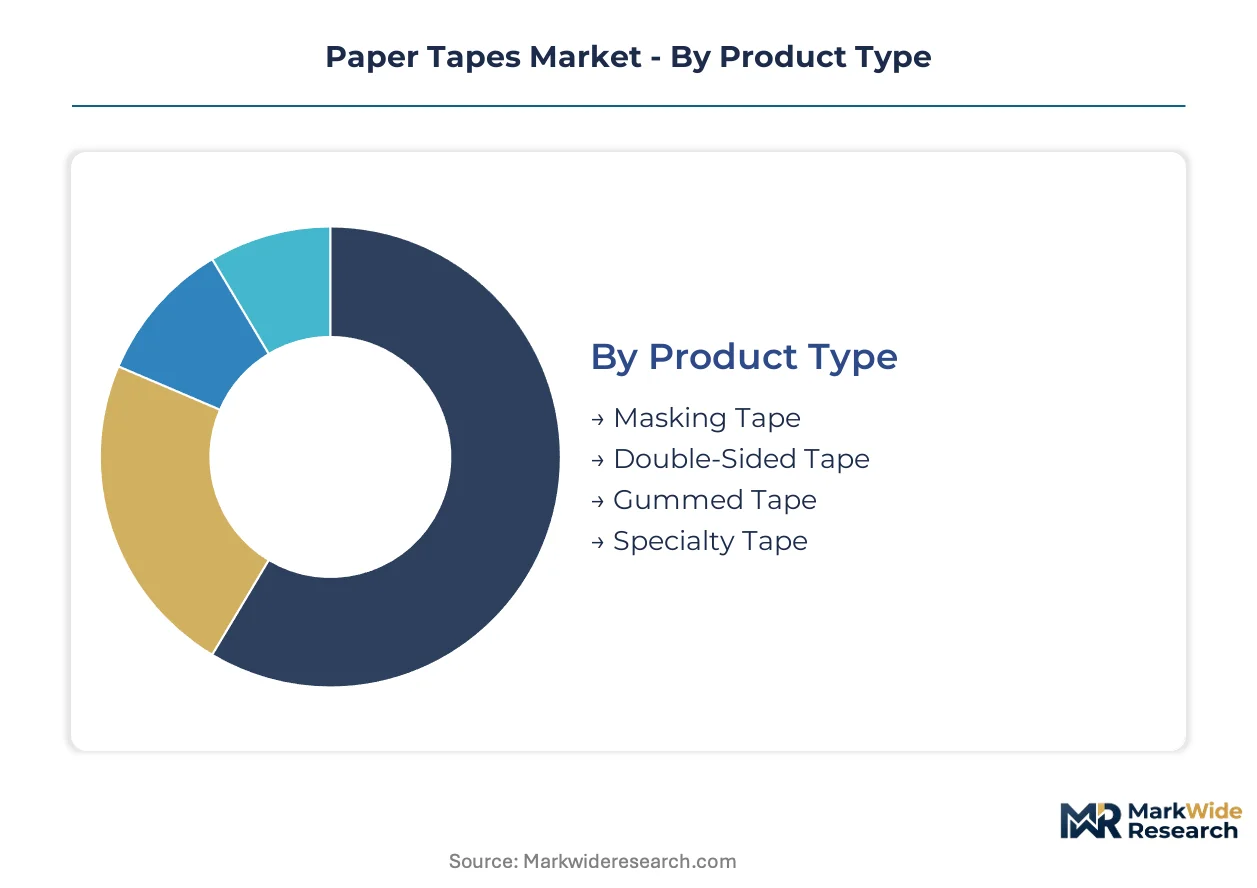
Paper tapes serve divergent performance requirements across industrial finishing, logistics automation, and consumer applications. Segmentation reveals how adhesive chemistry and substrate engineering align with specific end-use tolerances for temperature, humidity, and removal cleanliness.
Product Type:
Application severity and removal requirements determine which substrate-adhesive combinations capture volume across industrial and commercial segments.
- Masking Tape:Crepe paper substrates with rubber-based adhesives formulated for clean removal after baking cycles. Collision repair networks in Germany and the United States specify temperature-resistant grades that leave zero residue on automotive clear coats.
- Gummed Tape:Kraft paper backings with starch or dextrin adhesives activated by water contact. E-commerce fulfillment centers in China and India are migrating carton sealing specifications toward this construction to meet repulpability mandates.
- Double-Sided Tape:Tissue or flatback carriers coated with pressure-sensitive acrylics for bonding dissimilar surfaces in temporary assembly.
- Specialty Tape:Reinforced filaments, detectable substrates, or custom-printed constructions for pharmaceutical serialization and food safety traceability.
Masking tape commands the established base. The steepest expansion runs through gummed tape.
Application:
End-use environments impose distinct specification hierarchies that reshape adhesive formulation priorities and certification requirements.
- Packaging:Corrugated sealing applications demand instant tack on recycled fiber surfaces and reliable performance across humidity extremes. Water-activated formulations are displacing plastic pressure-sensitive tapes in Amazon and Walmart fulfillment networks.
- Construction:Surface protection and temporary holding applications prioritize tensile strength and clean removal from drywall, wood, and metal substrates. North American residential renovation cycles drive specification of UV-resistant masking grades.
- Electronics:Static-dissipative backings and low-outgassing adhesives protect sensitive components during assembly and rework operations.
- Arts & Crafts:Decorative washi and repositionable papers serve educational institutions and retail hobby channels with color variety and clean handling.
Packaging absorbs the dominant share of volume. Construction maintains the most resilient pricing power through specification stickiness.
Adhesive Type:
Regulatory pressure on volatile organic compound emissions and plastic content is restructuring which chemistries converters prioritize for capacity investment.
- Water-Based:Acrylic emulsion systems carried in aqueous solution, dominant in masking and labeling applications where EPA and REACH compliance is mandatory. Formulators in Jiangsu province are expanding coating capacity for water-based acrylics serving export markets.
- Hot Melt:Synthetic rubber and EVA block copolymers applied molten for instant bonding in high-speed carton sealing. Petroleum-derived resin inputs expose margin structures to naphtha price volatility that converters struggle to pass through.
- Solvent-Based:Natural rubber or synthetic elastomers dissolved in toluene or hexane, delivering superior tack and shear resistance. EPA emission limits are forcing costly line conversions in U.S. manufacturing facilities.
- Pressure Sensitive:Permanent-tack formulations requiring no activation, specified for electronics assembly and temporary holding where immediate adhesion is critical.
Water-based systems anchor the compliance-forward trajectory. Hot melt retains the largest installed base through cost advantages in high-volume sealing.
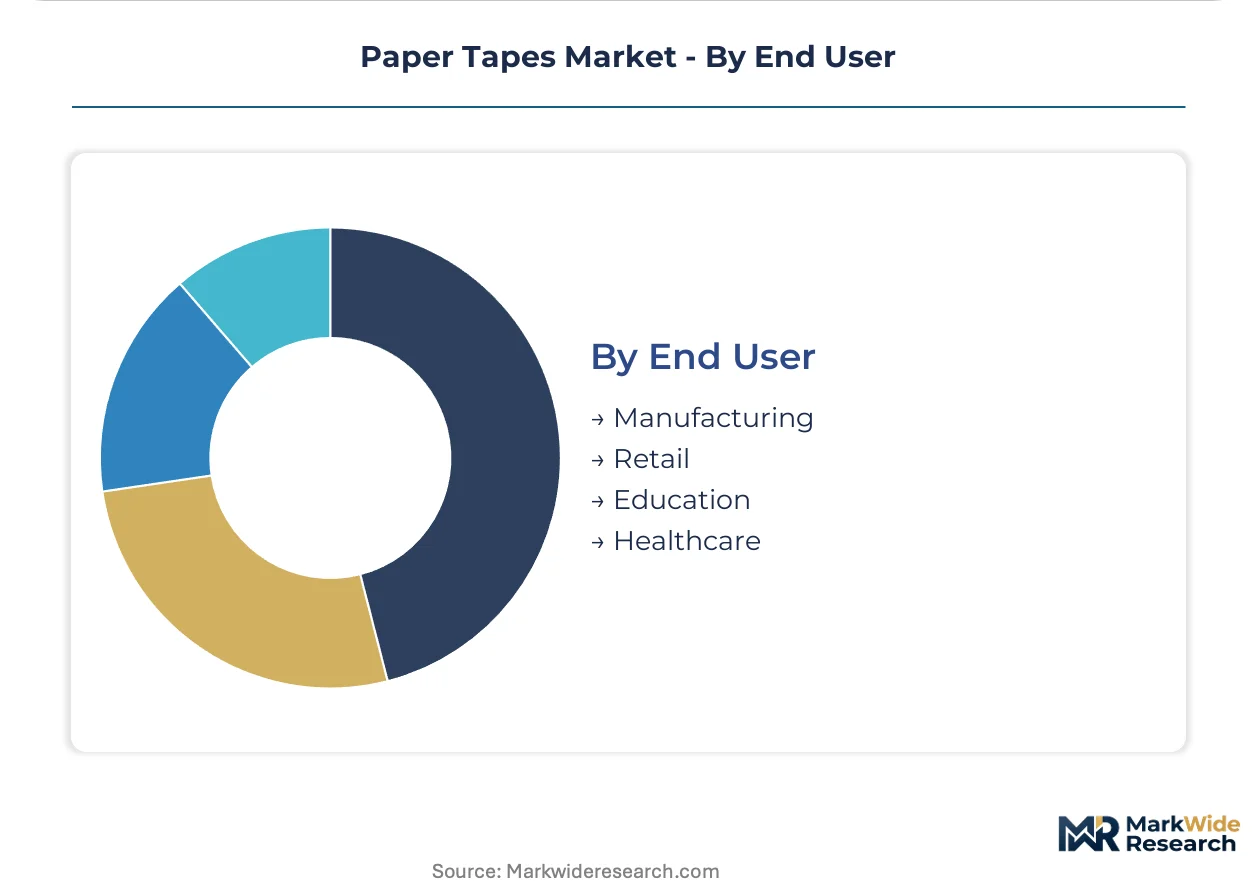
End User:
Procurement scale and specification authority concentrate differently across organizational buyers versus fragmented consumer channels.
- Manufacturing:Industrial buyers with formal qualification processes audit adhesive performance data, sustainability credentials, and supply assurance. Automotive OEMs in France and Germany now require carbon accounting documentation alongside technical specifications.
- Retail:Big-box and e-commerce distributors command volume-scale pricing with sustainability-linked contract adjustments, disintermediating traditional distribution layers.
- Education:School districts and institutional purchasers prioritize cost minimization and safety certification for student handling environments.
- Healthcare:Sterile packaging and device assembly applications demand lot traceability, biocompatibility testing, and validation protocols that limit qualified supplier pools.
Manufacturing concentrates the highest value per roll through performance premiums. Retail channels are gaining share fastest through consolidated procurement by mega-fulfillment networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GB standards enforcement by SAMR anchors supply-side adjustments across China's Jiangsu and Zhejiang coating corridors, while EPA emission protocols reshape formulation investments in U.S. manufacturing facilities.
United States
E-commerce fulfillment networks in the Midwest and Southeast are specifying water-activated gummed tape for carton sealing automation. EPA volatile organic compound limits are forcing solvent-based coating line conversions in Ohio and North Carolina facilities. Hickory, North Carolina distribution centers anchor Shurtape Technologies' construction-grade masking supply to residential renovation contractors.
China
Jiangsu and Zhejiang provinces are expanding coated paper tape capacity to serve domestic e-commerce and export pharmaceutical packaging demand. MEE discharge standards enforcement in the Yangtze River Delta is pressuring coating operations toward water-based adhesive systems. Suzhou and Hangzhou manufacturing clusters are reconfiguring production lines for repulpable GB-compliant constructions.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg are auditing supplier sustainability credentials alongside masking tape technical specifications. REACH registration requirements and EU Green Deal packaging waste directives are compelling converters toward plastic-free, repulpable formulations. Hamburg-based tesa SE formulation labs anchor European automotive masking applications for collision repair networks.
India
Mumbai-Pune manufacturing clusters in Maharashtra are driving demand for certified carton sealing tapes meeting international cold-chain documentation standards for pharmaceutical exports. BIS packaging material regulations are pressuring converters toward standardized adhesive performance testing. Gujarat-based coating facilities are expanding water-activated tape capacity to serve western industrial corridor export packaging lines.
Japan
Electronics assembly operations in Kanto and Kansai regions are specifying low-outgassing paper tapes for sensitive component protection during rework operations. METI circular economy guidelines are influencing adhesive converter R&D priorities toward recyclable constructions. Nagoya-area automotive suppliers are qualifying temperature-resistant masking grades for clean removal on clear coat finishes.
Paper Tapes Market Competitive Environment
Diversified adhesive conglomerates and regional coating specialists split the market between scale-driven formulation leadership and flexible regional service models. The vendor base organizes around three strategic archetypes: multinational diversified materials groups with integrated R&D campuses, mid-tier regional converters with coating line specialization, and niche players focused on certified pharmaceutical or automotive specifications. Competitive positioning hardens through backward integration into substrate manufacturing and multi-year framework agreements with consolidated e-commerce procurement networks.
Among diversified materials groups, 3M Company and tesa SE exemplify archetypes anchored by St. Paul and Hamburg R&D campuses respectively. Shurtape Technologies LLC occupies a position within the North American regional specialist tier. Nitto Denko Corporation represents the Asia-Pacific diversified adhesive conglomerate model with integrated electronics and industrial tape portfolios.
| Leading Market Players |
|---|
| Nitto Denko Corporation |
| Avery Dennison Corporation |
| 3M Company |
| Scapa Group Ltd. |
| Berry Global Inc. |
| Shurtape Technologies LLC |
| tesa SE |
| Saint-Gobain Performance Plastics |
| Intertape Polymer Group Inc. |
| Others |
Value Chain & Pricing Dynamics
Crude-derived naphtha volatility determines both the spread between hot melt and water-based adhesive pricing tiers and the geographic configuration of coating capacity investments. Converters exposed to petroleum-based resin inputs face margin compression that simultaneously widens premium-mid-economy pricing differentiation and accelerates backward integration into captive starch supply chains.
Pricing Analysis
Chinese Jiangsu and Zhejiang coating clusters price water-activated gummed tape at substantial discounts to German and U.S. equivalents due to integrated kraft substrate manufacturing. Price differentiation centers on repulpability certification grade and volume-scale contract tiers, with Amazon and Walmart procurement networks commanding sustainability-linked adjustments. Pricing pressure stems from consolidated e-buyer leverage disintermediating traditional distribution layers. Mid-tier manufacturers exhibit highest price sensitivity due to stranded solvent-based coating assets, while automotive OEMs absorb premium masking grades with limited negotiation scope.
Supply Chain Analysis
Petroleum-derived synthetic rubber and EVA block copolymers feed hot melt adhesive production, with naphtha cracking capacity concentrated in China, South Korea, and Saudi Arabia. Kraft pulp for substrates draws from Scandinavian and Southeast Asian fiber supply chains, while starch adhesive inputs hinge on corn and tapioca processing in the U.S. Midwest and Thailand. Single-source vulnerability concentrates in Jiangsu and Zhejiang coating corridors, where MEE discharge enforcement threatens regional supply continuity. Distribution runs through direct converter relationships with mega-fulfillment networks, bypassing traditional industrial distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has consolidated around Amazon, Walmart, and regional logistics operators contracting directly with adhesive converters, fragmenting traditional distribution margins and forcing suppliers into multi-year framework agreements with carbon accounting documentation requirements.
For Market Incumbents: Build formulation expertise moats in starch-based and dextrin adhesive systems to defend against polymer chemist shortages limiting water-activated production scale. Secure backward integration into kraft substrate manufacturing in Jiangsu corridor to reduce single-source exposure. Anchor multi-year procurement relationships with e-commerce fulfillment networks through sustainability-linked pricing mechanisms that lock in volume against emerging regional competitors. For New Entrants and Emerging Players: India's western industrial corridor around Mumbai-Pune manufacturing clusters offers underpenetrated demand for certified carton sealing tapes meeting international cold-chain documentation standards. Target pharmaceutical export packaging lines with BIS-compliant water-activated formulations as incumbents struggle with cross-border certification complexity extending launch timelines. Pursue direct technical sales to mid-tier fulfillment operators disintermediated from converter relationships. For Investors and Strategic Acquirers: EU Green Deal packaging waste directives and REACH registration requirements reshape the acquisition landscape toward converters with validated repulpable formulations and plastic-free construction capabilities. Five-to-ten year viability favors mid-tier specialists with coating line flexibility over diversified materials groups with stranded solvent-based assets. Monitor EPA enforcement actions on Ohio and North Carolina facilities as inflection indicators for distressed capacity availability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kraft Substrate Manufacturing | Captive supply of unbleached kraft backings secures GB standards compliance for Chinese export markets. |
| Water-Based Coating Line Conversion | EPA emission limits in U.S. facilities force costly retrofits that strain mid-tier manufacturer balance sheets. |
| Direct E-Commerce Fulfillment Contracts | Amazon and Walmart procurement networks disintermediate traditional distribution with sustainability-linked pricing. |
| Starch Adhesive R&D Partnership | Collaboration with polymer chemist programs addresses expertise gaps limiting water-activated production scale. |
| Indian Pharmaceutical Packaging Certification | BIS compliance for cold-chain documentation standards unlocks Mumbai-Pune export packaging demand. |
Study Parameters
A spread of perspectives from adhesive formulation chemists, corrugated packaging procurement directors, automotive collision repair network managers, and coating line operations supervisors converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through customs and trade data, SEC 10-K filings of diversified materials groups, and SAMR GB standards documentation. Bottom-up triangulation across regional coating capacity announcements and top-down reconciliation against end-use demand signals anchored volume estimates.
Demand-supply balance modeling across the projection horizon incorporated segmentation by adhesive chemistry type, substrate construction, end-use application severity, and regional regulatory cluster. CAGRs derived from elasticity-adjusted volume projections reflecting petroleum input price sensitivity and sustainability mandate acceleration curves. Forecast inputs included e-commerce fulfillment automation adoption rates, automotive refinishing cycle timing, and pharmaceutical export packaging certification timelines.
Macroeconomic conditions sit as an overlay; deviation in crude naphtha pricing, pulp fiber costs, or currency volatility in coating corridor economies would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement timing and buyer consolidation patterns. Cross-checking against IEA energy input benchmarks and OECD trade flow data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Tapes Market
Tapes
Sterilization Indicator Tape Market
Tapes
Self-Adhesive Tear Tape Market
Tapes
Wing Walk Tapes Market
Tapes
Mastic Tapes Market
Tapes
Global Seam Sealing Tapes Market
Tapes
Acoustic Tape Market
Tapes
Tabletop Tape Dispensers Market
Tapes
India Reflective Tapes Market
Tapes
Electrical Shielding Tape Market
Tapes
Differential Tapes Market
Tapes
Gaffers Tape Market
Tapes
Cable Wrapping Tapes Market
Tapes
Water Activated Tape Dispensers Market
Tapes
Lacing Tape Market
Tapes
Electronic Pressure Sensitive Tape Dispenser Market