
 Radiation Tester Market | 2026-2036
Radiation Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Radiation Tester Market Outlook
EU Basic Safety Standards Directive is expanding calibration mandates for radiation detection equipment deployed across member states. Mirion Technologies leverages its vertical integration in detector manufacturing to sustain pricing power in European nuclear utilities. Thermo Fisher Scientific anchors its position through R&D intensity in scintillation materials, while Kromek Group plc differentiates via cadmium-zinc-telluride semiconductor technology for medical imaging.
A radiation tester measures ionizing radiation exposure through detection of alpha, beta, gamma, and neutron emissions using gas-filled, scintillation, or semiconductor sensors, with sensitivity thresholds ranging from microsieverts to grays depending on application. These instruments serve critical functions in personnel safety compliance, environmental contamination mapping, and process control in nuclear facilities. Handheld detectors and digital dosimeters lead product category revenue due to portability requirements in field deployments, while wireless technology represents the fastest-expanding segment as utilities integrate real-time dose monitoring into plant control systems. Analog technology persists in budget-constrained government agency procurement, though margin pools concentrate in digital platforms with cloud-connected analytics.
FDA 21 CFR Part 1020 governs diagnostic x-ray system performance testing in U.S. healthcare settings, while EPA RadNet specifications shape environmental monitoring equipment standards. ISO 4037 and IEC 60580 provide international calibration protocols that manufacturers must satisfy for cross-border market access. Stakeholders must weigh semiconductor material transitions against existing scintillator supply chains when allocating capital to next-generation platform development.
Market Dynamics
Reactor fleet modernization across France and South Korea is compressing replacement cycles for legacy analog dosimeters, forcing incumbent suppliers to requalify digital platforms under tightened EU calibration mandates while semiconductor material transitions threaten existing scintillator supply chains.
Growth Catalysts
- EU Basic Safety Standards Directive:Expanded calibration mandates for environmental monitoring equipment deployed across member states are accelerating equipment refresh cycles in German industrial radiography operations.
- Cadmium-zinc-telluride semiconductors:Direct-conversion detector materials are displacing scintillator-based systems in medical imaging applications due to superior energy resolution at reduced form factors.
- Fukushima decommissioning services:Sustained demand for contamination mapping and personnel dose monitoring around the disabled Daiichi facility is concentrating procurement in high-sensitivity handheld platforms.
Market Restraints
- Helium-3 supply concentration:Neutron detection relies on gas sourced from aging nuclear warhead stockpiles, with procurement bottlenecks constraining production of multi-purpose survey meters.
- Scintillator crystal fabrication:Sodium iodide and bismuth germanate crystal growth requires specialized furnaces with limited supplier base concentrated in Japan and Ukraine.
- FDA 21 CFR Part 1020 compliance:Diagnostic x-ray system performance testing requirements create multi-year approval timelines for new healthcare platform introductions.
Strategic Opportunities
- Wireless real-time monitoring:Plant control system integration in French and South Korean nuclear utilities is absorbing cloud-connected analytics platforms that enable centralized dose tracking.
- India industrial radiography:Non-destructive testing expansion in pipeline construction and aerospace manufacturing is opening demand for portable gamma and x-ray detection equipment.
- ISO 4037 calibration protocols:International standard harmonization is reducing cross-border market access friction for manufacturers with multi-territory certification.
Industry Challenges
- Radiation safety physicist shortage:Qualified personnel for instrument calibration and regulatory interpretation are scarce in decommissioning-heavy markets like Japan.
- Legacy analog system integration:Digital dosimeter deployment requires backward compatibility with existing plant monitoring infrastructure, complicating wireless platform rollout.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiation Tester Market |
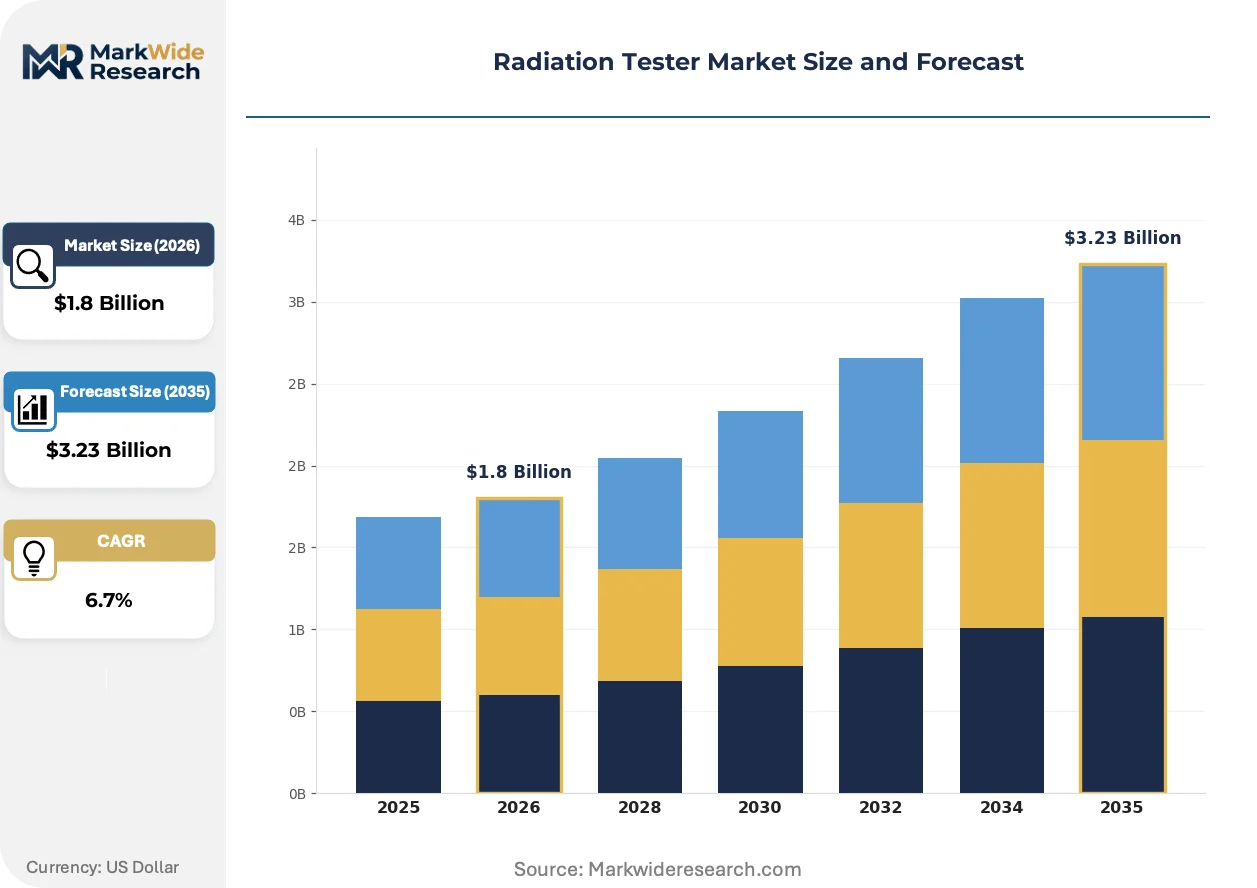
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Detectors, Scintillation Counters, Geiger-Müller Counters, Dosimeters Application: Environmental Monitoring, Healthcare, Nuclear Power, Research Laboratories End User: Government Agencies, Hospitals, Research Institutions, Industrial Sectors Technology: Analog Technology, Digital Technology, Wireless Technology, Portable Technology |
| Companies Covered | Mirion Technologies Inc., Thermo Fisher Scientific Inc., Fortive, AMETEK, Fuji Electric Co., Ltd., Teledyne FLIR LLC, Kromek Group plc, Ludlum Measurements, Inc., LANDAUER, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiation Tester Market Strategic Shifts
Semiconductor detector materials are actively displacing conventional scintillation technology across high-resolution applications, while regulatory calibration mandates in Europe and real-time connectivity requirements in Asian nuclear utilities are rewriting equipment specification standards.
Cadmium-zinc-telluride semiconductor technology is absorbing market share in medical imaging and security screening segments where energy discrimination directly impacts diagnostic accuracy. Cardiology departments and baggage screening operations in North American and European airports are prioritizing direct-conversion platforms despite unit cost premiums. The structural consequence is absorbing margin pools from legacy sodium iodide supply chains as manufacturers reallocate R&D capital to epitaxial growth processes.
EPA RadNet specifications are tightening detection sensitivity thresholds for environmental monitoring equipment deployed across the United States, with particulate air monitoring stations now requiring lower minimum detectable concentrations for iodine and cesium isotopes. Equipment vendors must requalify sampling and analysis systems under revised performance criteria. The stationary environmental monitoring segment is responding with extended-duration detector deployments and automated spectral analysis software to reduce manual review burden.
Utility procurement departments are consolidating vendor relationships from fragmented regional suppliers toward single-source agreements with full-service radiation safety platform providers. This concentration is displacing independent calibration laboratories and small-batch dosimeter manufacturers in European and North American markets. The shift is most visible in French nuclear power operations where fleet-wide standardization on digital dosimeter formats is eliminating analog equipment maintenance overhead.
Radiation Tester Market Segmentation
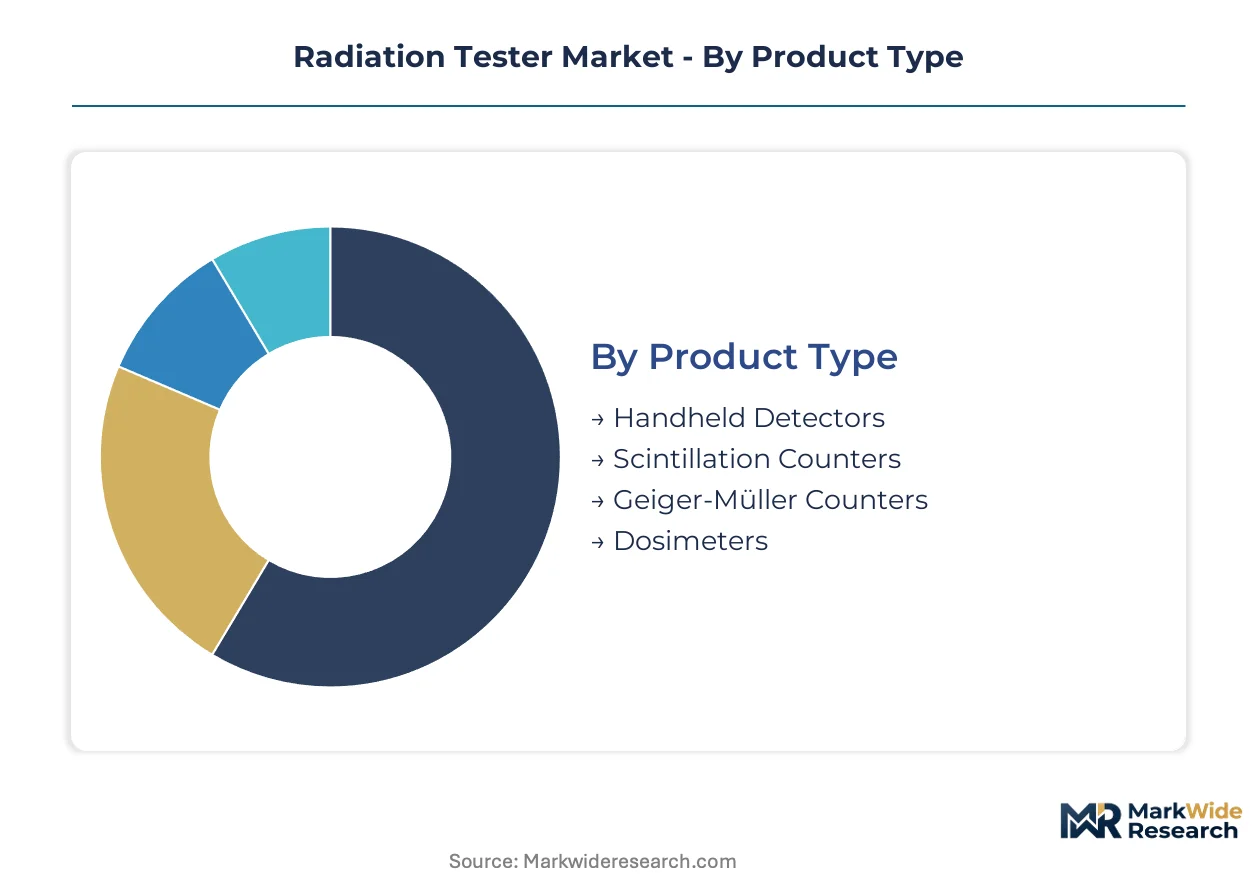
Radiation tester procurement patterns diverge sharply between field-deployable standalone units and plant-integrated embedded systems. Equipment specification standards now hinge on whether instruments operate as portable safety tools or feed data directly into centralized monitoring architectures.
Product Type:
Handheld detectors and dosimeters function as standalone safety instruments for individual personnel, while scintillation and Geiger-Müller counters increasingly embed into facility-wide monitoring networks.
- Handheld Detectors:Battery-powered units with silicon photodiode or PIN diode sensors detect gamma and x-ray emissions in the 10 keV to 3 MeV range. Demand clusters around Fukushima decommissioning services in Japan and German industrial radiography operations where field contamination mapping requires immediate visual readout capability.
- Dosimeters:Personal monitoring badges and electronic dosimeters track cumulative exposure over work shifts using thermoluminescent or semiconductor elements. French and South Korean nuclear utilities are replacing analog film badges with digital platforms that transmit real-time dose data to plant safety offices.
- Scintillation Counters:Sodium iodide crystal-based systems offer high sensitivity for low-level environmental contamination detection. These instruments anchor EPA RadNet station deployments across the United States.
- Geiger-Müller Counters:Gas-filled tubes operating in avalanche mode provide robust alpha and beta detection for routine survey applications. Government agencies in budget-constrained procurement cycles favor these units for their mechanical simplicity and minimal calibration requirements.
Volume placements concentrate in handheld detectors and dosimeters; the faster expansion belongs to dosimeters with wireless connectivity.
Application:
Cost tiers separate high-precision medical diagnostics from ruggedized industrial safety equipment, with environmental monitoring commanding premium pricing for extended-duration deployment capability.
- Healthcare:Diagnostic imaging suites and radiotherapy departments require calibrated instruments for x-ray system performance verification under FDA 21 CFR Part 1020. Cadmium-zinc-telluride semiconductor detectors are displacing scintillator-based quality assurance tools in cardiology and mammography settings.
- Nuclear Power:Reactor operations, fuel handling, and maintenance activities demand multi-purpose survey meters with neutron detection capability. Fleet modernization in France and South Korea is compressing replacement cycles for legacy analog equipment.
- Environmental Monitoring:Air sampling stations and water analysis laboratories track iodine, cesium, and strontium isotopes using high-purity germanium or sodium iodide spectrometers. The EU's updated Basic Safety Standards Directive is tightening calibration requirements for equipment deployed across member states.
- Research Laboratories:Academic and government research facilities utilize specialized detectors for materials characterization and radiochemistry applications. Procurement emphasizes modular platforms with software-defined spectral analysis capabilities.
Revenue concentrates in nuclear power and healthcare applications; environmental monitoring is climbing the fastest as regulatory detection thresholds tighten.
End User:
Customer type determines procurement channel structure, with government agencies favoring lowest-bid contracts while industrial sectors prioritize vendor technical support and calibration service bundling.
- Industrial Sectors:Non-destructive testing contractors in pipeline construction and aerospace manufacturing require portable gamma and x-ray detection equipment. India's expanding industrial radiography market is opening demand for equipment with ISM-band wireless data transmission.
- Hospitals:Radiology departments and medical physics groups purchase integrated quality assurance platforms with automated reporting software. These buyers emphasize FDA compliance documentation and vendor training programs.
- Government Agencies:National laboratories, emergency response teams, and environmental protection departments procure multi-instrument kits under multi-year framework agreements. Analog technology persists in these channels due to simplified procurement specifications.
- Research Institutions:Universities and national research centers acquire specialized detectors for particle physics and materials science applications. These buyers prioritize energy resolution specifications and open-source software compatibility over cost optimization.
Procurement volume centers on industrial sectors and hospitals; government agencies represent the steepest expansion trajectory as civil defense and emergency preparedness programs expand instrument stockpiles.
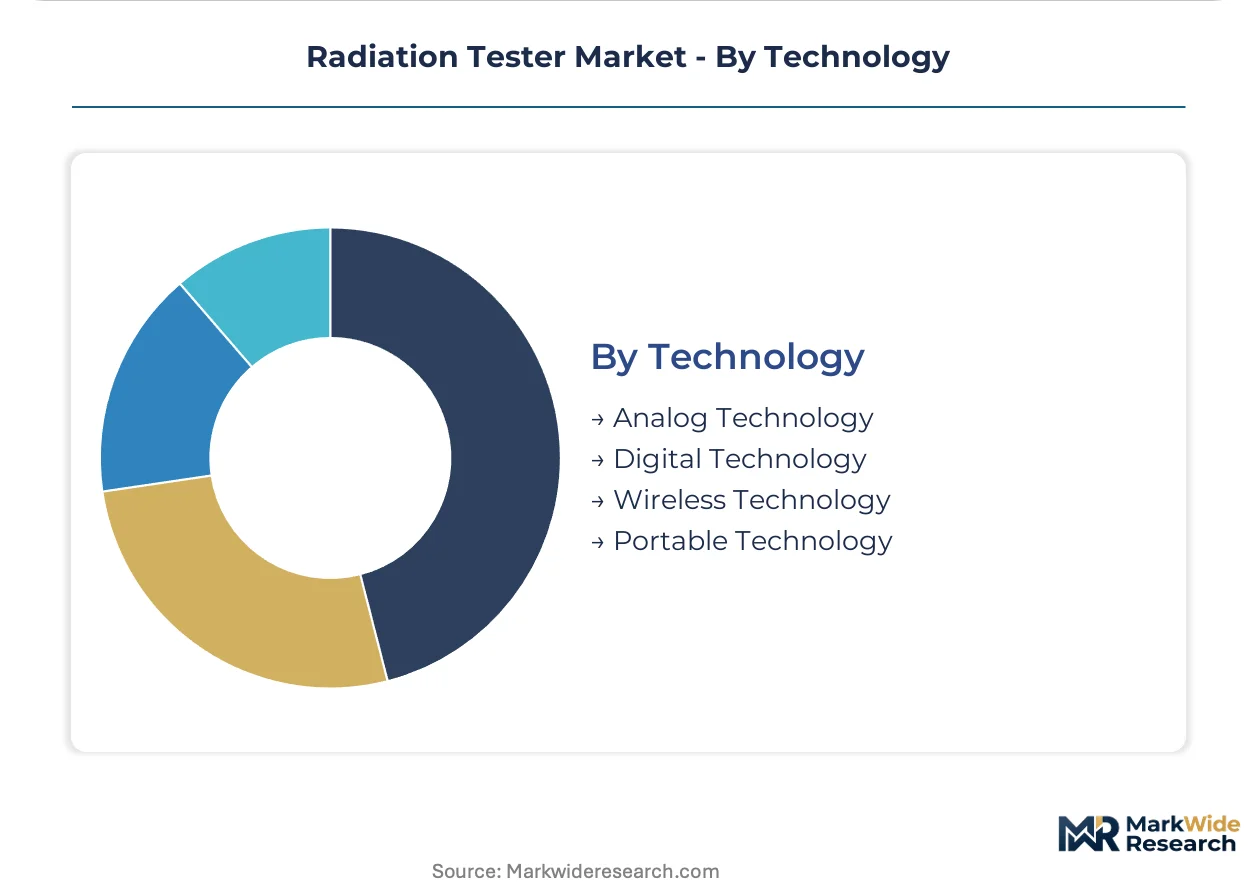
Technology:
Supply concentration in semiconductor detector manufacturing is shifting competitive advantage toward vendors with in-house crystal growth and epitaxial deposition capabilities.
- Digital Technology:Microprocessor-controlled instruments with LCD displays and data logging memory are replacing analog meters in professional safety applications. These platforms enable dose history tracking and alarm threshold programming for complex work environments.
- Wireless Technology:Bluetooth and Wi-Fi enabled detectors transmit real-time readings to plant control systems and cloud analytics platforms. French nuclear utilities are standardizing on these formats for fleet-wide dose monitoring integration.
- Portable Technology:Battery-optimized designs with ruggedized enclosures serve field deployment requirements in decommissioning and environmental survey operations. Weight and ergonomic considerations drive specification priorities in this segment.
- Analog Technology:Electromechanical meters with needle indicators persist in educational settings and budget-constrained government procurement. Margin compression in this segment is forcing smaller manufacturers toward component supply or calibration service roles.
Equipment shipments concentrate in digital and portable technologies; wireless platforms are gaining share fastest as utility procurement specifications mandate real-time connectivity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
French nuclear power zones and South Korean industrial complexes anchor procurement concentration, with EU regulatory harmonization and Asian reactor modernization compressing equipment replacement cycles across distinct national frameworks.
United States
EPA RadNet station upgrades and healthcare diagnostic imaging expansion drive equipment demand. FDA 21 CFR Part 1020 governs x-ray system performance verification protocols. California and Texas host the densest clusters of environmental monitoring contractors servicing federal air quality networks.
Germany
Industrial radiography operations in pipeline construction and automotive manufacturing absorb portable detection equipment. The EU's updated Basic Safety Standards Directive tightens calibration mandates for environmental monitoring instruments. Bavaria's nuclear power plants and Baden-Württemberg's precision engineering centers concentrate procurement volume.
France
Reactor fleet modernization across EDF's nuclear installations accelerates digital dosimeter replacement. ANSM and ASN oversight shapes radiation safety equipment certification requirements. The Provence-Alpes-Côte d'Azur region and Normandy host decommissioning services clusters demanding high-sensitivity handheld platforms.
Japan
Fukushima Daiichi decommissioning services sustain demand for contamination mapping and personnel dose monitoring. METI regulations govern occupational exposure limits in nuclear facilities. The Tohoku region surrounding the disabled facility and Kanto's research laboratories concentrate equipment deployment.
South Korea
KHNP reactor fleet expansion and maintenance cycles compress replacement timelines for legacy analog systems. MFDS and KINS standards shape medical and industrial radiation detection equipment approval. The Busan-Ulsan industrial corridor and Daejeon-Sejong research cluster anchor procurement concentration.
Radiation Tester Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidation pressures favor vendors with captive detector manufacturing and multi-territory certification capabilities. Three archetypes dominate: integrated safety platform providers, semiconductor detector specialists, and regional calibration service bundlers. Competitive moves center on backward integration into crystal growth and strategic partnerships for wireless connectivity modules.
Among US-based diversified technology conglomerates, Thermo Fisher Scientific and AMETEK exemplify scale-driven positions through R&D intensity and portfolio breadth. Mirion Technologies represents the integrated platform archetype with in-house detector manufacturing. Kromek Group plc occupies a specialist position in direct-conversion semiconductor technology. These three anchors illustrate the strategic divergence between conglomerate scale and focused technology differentiation.
| Leading Market Players |
|---|
| Mirion Technologies Inc. |
| Thermo Fisher Scientific Inc. |
| Fortive |
| AMETEK |
| Fuji Electric Co., Ltd. |
| Teledyne FLIR LLC |
| Kromek Group plc |
| Ludlum Measurements, Inc. |
| LANDAUER |
| Others |
Value Chain & Pricing Dynamics
Cadmium-zinc-telluride epitaxial growth transitions are simultaneously elevating unit production costs and concentrating detector manufacturing among vendors with captive crystal growth capabilities, compressing margins for scintillator-dependent competitors while rewarding backward-integrated specialists.
Pricing Analysis
Short lead-time premiums command pricing power for wireless-enabled digital dosimeters as French and South Korean nuclear utilities compress procurement cycles under fleet modernization timelines. Three-tier pricing structure across premium, standard, and economy levels separates cloud-connected analytics platforms from standalone digital units and legacy analog meters. Cost compression in the analog tier is intensifying because government agency procurement specifications favor lowest-bid simplicity over performance. Industrial radiography contractors in Germany and India exhibit the highest price sensitivity, while hospital radiology departments prioritize FDA compliance documentation and vendor training bundles over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale utility demand for fleet-standardized dosimeter platforms, while independent distributors serve fragmented industrial radiography and research laboratory segments. Crystal growth capacity concentrates in Japan and Ukraine for sodium iodide and bismuth germanate scintillators, with epitaxial deposition capabilities clustering in the United States and Germany for compound semiconductors. Manufacturing draws from helium-3 gas stockpiles, specialized furnace equipment, and high-purity germanium feedstock. Single-source vulnerability in neutron detection gas supply creates procurement bottlenecks constraining multi-purpose survey meter production. Distribution runs through authorized calibration service bundlers in European markets and direct technical sales teams in Asian nuclear utility sectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating toward integrated platform providers as semiconductor material transitions and tightened EU calibration mandates force scintillator-dependent competitors toward component supply or exit.
For Market Incumbents: To counter margin compression from cadmium-zinc-telluride displacement of legacy scintillator systems, deepen backward integration into epitaxial growth processes and secure captive helium-3 supply agreements through national laboratory partnerships. Fleet standardization contracts in French nuclear operations represent the priority lever for locking out regional calibration service competitors. For New Entrants and Emerging Players: The EU's updated Basic Safety Standards Directive opens a window for calibration-as-a-service platforms that bypass capital-intensive detector manufacturing entirely. India's industrial radiography expansion and Japan's radiation safety physicist shortage present the most penetrable white-space targets. A software-defined spectral analysis overlay strategy allows entry without competing on sensor hardware. For Investors and Strategic Acquirers: Re-rating potential sits with semiconductor detector specialists given wireless real-time monitoring adoption in Asian nuclear utilities. Long-term viability over the next decade favors vendors with multi-territory ISO 4037 certification and in-house crystal growth capabilities. Watch for helium-3 supply release announcements from warhead stockpile management programs as the inflection signal for neutron detection platform profitability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epitaxial Growth | Captive cadmium-zinc-telluride production secures margin pools in medical imaging segments. |
| Wireless Platform Certification | Bluetooth-enabled dosimeter approval under KINS and ASN standards unlocks South Korean and French utility procurement. |
| Calibration Service Bundling | Multi-year service contracts with German industrial radiography operators displace fragmented regional laboratories. |
| Helium-3 Supply Partnership | National laboratory agreements mitigate neutron detection production bottlenecks for multi-purpose survey meters. |
| Software-Defined Spectral Analysis | Automated isotope identification reduces manual review burden in EPA RadNet environmental monitoring deployments. |
Study Parameters
Document review covered FDA 21 CFR Part 1020 filings, EPA RadNet performance specifications, EU Basic Safety Standards Directive implementation guidance, and IEC 60580 calibration protocols, complemented by interviews with nuclear utility safety officers, industrial radiography contractors, hospital medical physicists, and semiconductor detector manufacturing engineers. Secondary validation drew from customs trade data for scintillator crystal imports, SEC filings of diversified technology conglomerates, and national regulatory agency equipment approval databases. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Historical shipment data cross-referenced against expert panel input on replacement cycle compression and technology transition timelines shaped the analytical framework. Segmentation dimensions modeled include product type, application, end user, and technology across the projection horizon. CAGRs derived from regression analysis of equipment procurement patterns and regulatory mandate implementation schedules. Forecast inputs incorporated reactor fleet modernization timelines in France and South Korea, Fukushima decommissioning service duration assumptions, and semiconductor material transition adoption curves in medical imaging.
Caveats apply where helium-3 supply release schedules, EU calibration mandate enforcement intensity, or semiconductor detector yield improvements could materially shift the outlook. Forecasts reflect documented assumptions about utility procurement consolidation behavior and regulatory harmonization progress. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Semiconductor Bond Testing Market
Test and Measurement
LAMEA Semiconductor Metrology and Inspection Market
Test and Measurement
Fluorometers Market
Test and Measurement
Electrical Testing Services Market
Test and Measurement
Test and Measurement Sensors Market
Test and Measurement
Over-The-Air (OTA) Testing Market
Test and Measurement
Global 5G Test Equipment Market
Test and Measurement
E-Beam Wafer Inspection System Market
Test and Measurement
Impact Testing Machine Market
Test and Measurement
Battery Testing Market
Test and Measurement
LCR Meter Market
Test and Measurement
Optical Fiber Network Latency and Time Synchronization Test Equipment Market
Test and Measurement
X-Ray Inspection System for Secondary Battery Market
Test and Measurement
Precision Measuring Tools Market
Test and Measurement
Asia-Pacific Laser Interferometer Market
Test and Measurement
Clamp Meters Market