
 Lithium Metal Anode Dendrite Growth Visualization Test Platforms Market | 2026-2036
Lithium Metal Anode Dendrite Growth Visualization Test Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Metal Anode Dendrite Growth Visualization Test Platforms Market Insights
Solid polymer electrolytes replacing liquid carbonate systems is realigning platform specifications toward operando cell designs. Metrohm leverages its electrochemical instrumentation heritage to anchor European laboratory demand. Bio-Logic Science Instruments specializes in potentiostat-integrated visualization rigs that dominate French and Swiss research clusters. Gamry Instruments competes on compact benchtop systems suited for university settings with constrained capital budgets.
Lithium metal anode dendrite growth visualization test platforms are electrochemical diagnostic systems that integrate high-resolution imaging modalities with controlled cell environments to observe lithium filament propagation during charge cycling, typically operating at sub-micron resolution under inert atmosphere conditions. These tools serve battery scientists seeking to correlate plating morphology with cell failure modes before commercial scale-up. Optical microscopy systems occupy the largest installed base due to lower capital barriers, though electron microscopy tools capture the fastest expansion as manufacturers demand nanoscale crack-path resolution. In-situ visualization technology leads R&D investment flows, while ex-situ analysis retains stable demand in quality control settings where throughput trumps temporal resolution.
The EU Battery Regulation and REACH compliance frameworks mandate dendrite-related safety documentation for lithium metal cells entering European markets, directly shaping platform procurement specifications. FDA and NHTSA guidelines in the United States increasingly reference solid-state battery validation protocols that require visualization evidence for transportation safety filings. Japan's METI coordinates national standards through JIS committees that specify imaging resolution benchmarks for anode characterization. Stakeholders must weigh the trade-off between platform capital intensity and the regulatory liability of undetected dendrite defects as cell energy densities climb.
Market Dynamics
The transition from liquid electrolyte to solid-state cell architectures is compressing platform refresh cycles as laboratories retool for operando imaging requirements. Battery developers now demand simultaneous electrochemical control and sub-micron optical resolution, forcing equipment suppliers to merge previously separate instrumentation categories.
Growth Catalysts
- EU Battery Regulation:Mandates dendrite-related safety documentation for lithium metal cells entering European markets, compelling manufacturers to invest in visualization infrastructure before commercialization.
- Japan METI consortia:Coordinate national R&D funding that prioritizes dendrite suppression technologies for next-generation electric vehicle cells, concentrating demand among domestic research clusters.
- Solid polymer electrolytes:Replace liquid carbonate systems across solid-state battery development programs, requiring new operando cell designs that integrate directly with visualization platforms.
Market Restraints
- Helium supply concentration:Cryogenic electron microscopy systems depend on helium-3 and helium-4 isotopes sourced primarily from Qatar and the United States, exposing buyers to price volatility and export restriction risk.
- Technical resolution ceiling:Optical microscopy platforms face hard physical limits around 200-nanometer resolution, insufficient for detecting early-stage dendrite nucleation that precedes cell failure.
- REACH compliance friction:Registration requirements for imported lithium metal samples create procedural delays that extend platform commissioning timelines by four to eight weeks for European laboratories.
Strategic Opportunities
- India battery R&D:Underpenetrated relative to installed base in Japan and Germany, with BIS standards development creating first-mover advantage for platform vendors establishing local service networks.
- AI-assisted image analysis:Converges with hardware platforms to automate dendrite classification, reducing skilled operator burden and enabling higher-throughput screening protocols for quality control applications.
- US IRA manufacturing credits:Incentivize domestic solid-state battery production, generating visualization demand from new cell fabrication facilities requiring in-house failure analysis capabilities.
Industry Challenges
- Cross-disciplinary talent scarcity:Platform operation requires simultaneous expertise in electrochemistry, optics, and vacuum systems, with universities producing insufficient hybrid-trained graduates.
- ISO 17025 accreditation timelines:Laboratories seeking certified testing status face eighteen-to-twenty-four-month validation periods for dendrite visualization protocols, delaying revenue generation from contract testing services.
- Legacy data format incompatibility:Proprietary image formats from incumbent instrument vendors resist integration with emerging open-source analysis pipelines, fragmenting research collaboration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Metal Anode Dendrite Growth Visualization Test Platforms Market |
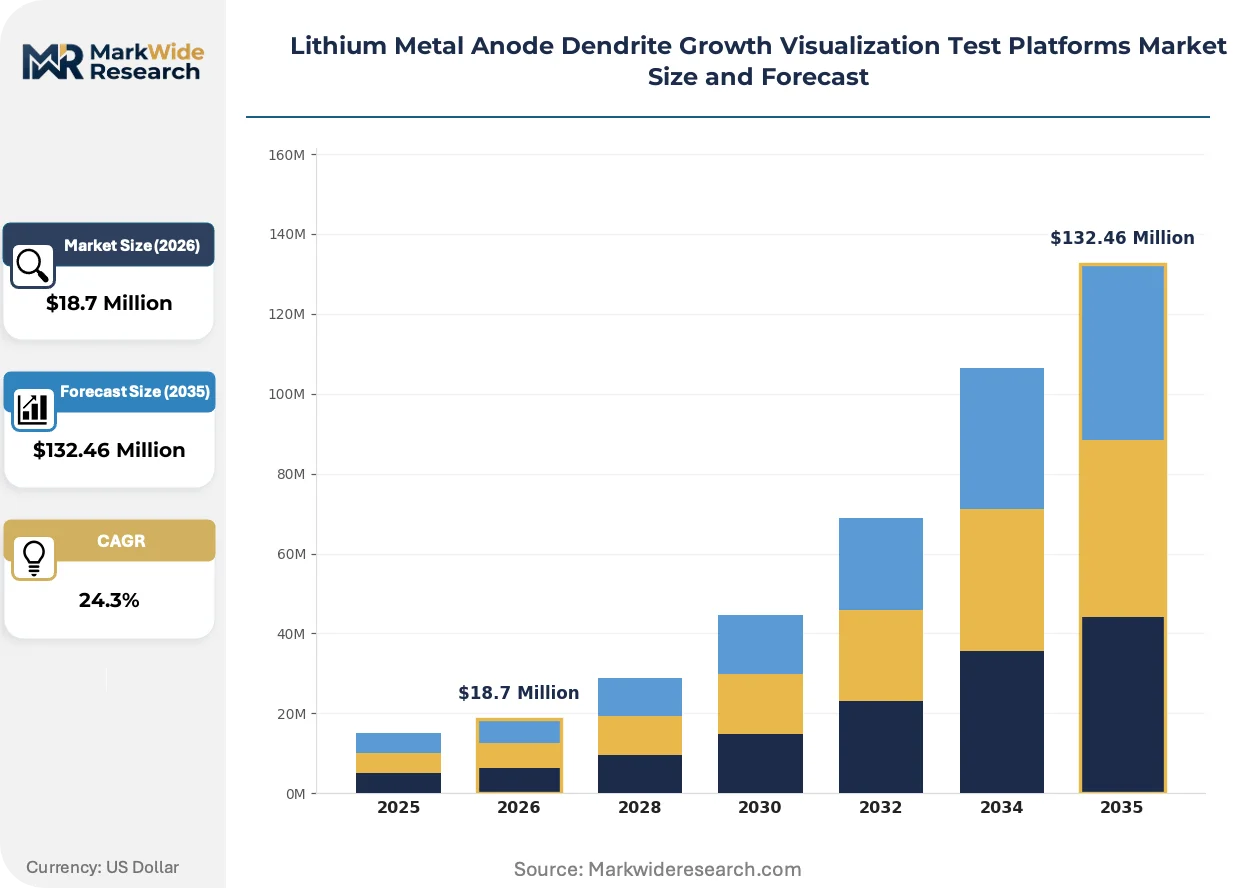
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $132.46 Million |
| CAGR (2026 – 2036) | 24.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Microscopy Systems, Electron Microscopy Tools, X-ray Tomography Devices, Scanning Probe Instruments Technology: In-Situ Visualization, Real-Time Monitoring, Ex-Situ Analysis, High-Resolution Imaging Application: Battery Research, Quality Control, Failure Analysis, Safety Testing, Material Development End User: Academic Institutions, Research Laboratories, Battery Manufacturers, Material Scientists |
| Companies Covered | Metrohm, Bio-Logic Science Instruments, Gamry Instruments, Ametek, Keysight Technologies, Bruker, Thermo Fisher Scientific, Hitachi High-Tech, ZEISS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Metal Anode Dendrite Growth Visualization Test Platforms Market Trends and Innovations
Instrumentation convergence is dissolving boundaries between electrochemical workstations and imaging systems, creating unified platforms that capture temporal and spatial data simultaneously. This integration is compressing experimental timelines and altering how battery scientists validate cell designs.
Raman spectroscopy is integrating with optical microscopy platforms to enable chemical identification of dendrite composition during live cycling. Solid-state battery developers in Germany and Japan are adopting these hybrid systems at accelerating rates. The technology is integrating electrochemical and spectroscopic data streams into single analytical workflows, reducing the need for separate ex-situ material characterization.
REACH compliance deadlines for battery safety documentation are tightening across the European Union, with ECHA guidance specifically referencing dendrite growth characterization for lithium metal chemistries. Manufacturers must submit visualization evidence as part of substance safety dossiers. Solid-state cell developers face the most acute compliance burden, driving procurement of automated documentation systems that generate audit-ready image archives.
Buyers are consolidating vendor relationships around full-stack platform providers rather than assembling discrete components from multiple suppliers. University laboratories with constrained capital budgets particularly favor single-source procurement that bundles hardware, software, and maintenance contracts. This preference shift is most visible in the United States, where NSF and DOE grant funding increasingly requires demonstrated interoperability between instrumentation modules.
Lithium Metal Anode Dendrite Growth Visualization Test Platforms Market Segmentation
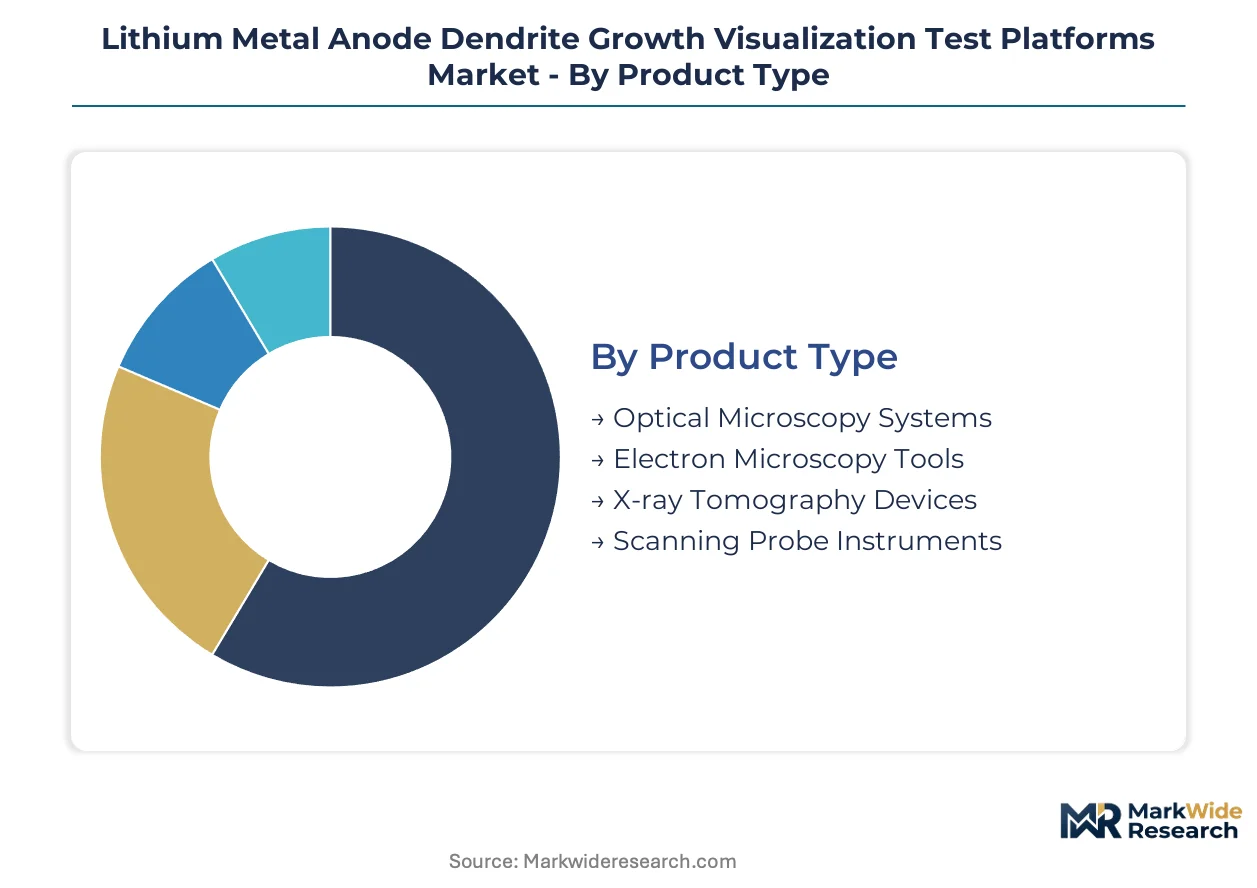
Platform segmentation reveals how technical specifications align with distinct procurement budgets and experimental workflows across battery R&D ecosystems. Understanding these divides helps suppliers calibrate feature sets against buyer capabilities and regulatory documentation requirements.
Product Type:
Supply concentrates among electron microscopy specialists in Germany and Japan, while optical platform vendors compete on price in North American university markets.
- Optical Microscopy Systems:These platforms employ confocal and interference contrast techniques to capture lithium plating morphology at sub-micron resolution under controlled atmosphere conditions. Demand clusters in Japanese METI-funded consortia and German solid-state battery programs where budget constraints favor multi-station laboratory deployments over single high-end units.
- Electron Microscopy Tools:Cryogenic transmission electron microscopy enables nanoscale crack-path resolution for dendrite nucleation studies, requiring helium-cooled sample stages and vacuum-compatible cell fixtures. Battery manufacturers in Stuttgart and Toyota City prioritize these systems for pre-commercial safety validation where undetected defects carry regulatory liability.
- X-ray Tomography Devices:Synchrotron-linked systems at Argonne National Laboratory and RIKEN provide non-destructive 3D reconstruction of dendrite networks through intact cell housings.
- Scanning Probe Instruments:Atomic force microscopy platforms map surface roughness evolution during lithium stripping cycles, serving material scientists at ETH Zurich and MIT.
Today's leader: Optical Microscopy Systems. Tomorrow's challenger: Electron Microscopy Tools.
Technology:
Cost tiers separate academic laboratories from commercial battery developers, with in-situ platforms commanding 3-4x the capital expenditure of ex-situ alternatives.
- In-Situ Visualization:Operando cell designs integrate electrochemical cycling with continuous imaging, capturing dendrite propagation dynamics during actual charge-discharge events. Japanese automotive cell developers and German solid-state startups dominate procurement, driven by EU Battery Regulation documentation requirements and METI performance benchmarks.
- Real-Time Monitoring:Automated image acquisition pipelines with AI-assisted defect classification reduce operator burden for high-throughput screening protocols. US DOE-funded facilities and Korean battery R&D centers adopt these systems to accelerate failure mode cataloging before scale-up decisions.
- Ex-Situ Analysis:Post-mortem examination of cycled cells retains stable demand in quality control settings where throughput priorities override temporal resolution needs.
- High-Resolution Imaging:Sub-10-nanometer resolution platforms serve fundamental materials science investigations at national laboratories and elite research universities.
Procurement is shifting toward In-Situ Visualization as solid-state architectures displace liquid electrolyte development programs.
Application:
Volume concentrates in battery research, though safety testing applications are climbing the fastest as commercialization timelines compress.
- Battery Research:Fundamental dendrite suppression studies at Tsukuba, Jülich, and Berkeley National Laboratory consume the largest installed base of visualization platforms. Academic and government laboratory demand focuses on correlating electrolyte chemistry with plating morphology to guide materials selection before pilot production.
- Quality Control:Incoming inspection of lithium metal foil and separator materials uses standardized imaging protocols to catch surface defects that nucleate dendrite growth. Korean and Chinese cell manufacturers are expanding these capabilities as production scales toward electric vehicle supply contracts.
- Failure Analysis:Root-cause investigation of field-returned cells employs visualization evidence to distinguish manufacturing defects from design limitations.
- Safety Testing:Regulatory submission packages for transportation and stationary storage applications require documented dendrite characterization under abuse conditions.
- Material Development:Solid polymer electrolyte and artificial SEI layer candidates undergo iterative screening against benchmark lithium morphologies.
Margin structures favor Battery Research today, while Safety Testing represents the steepest expansion trajectory as certification requirements tighten.
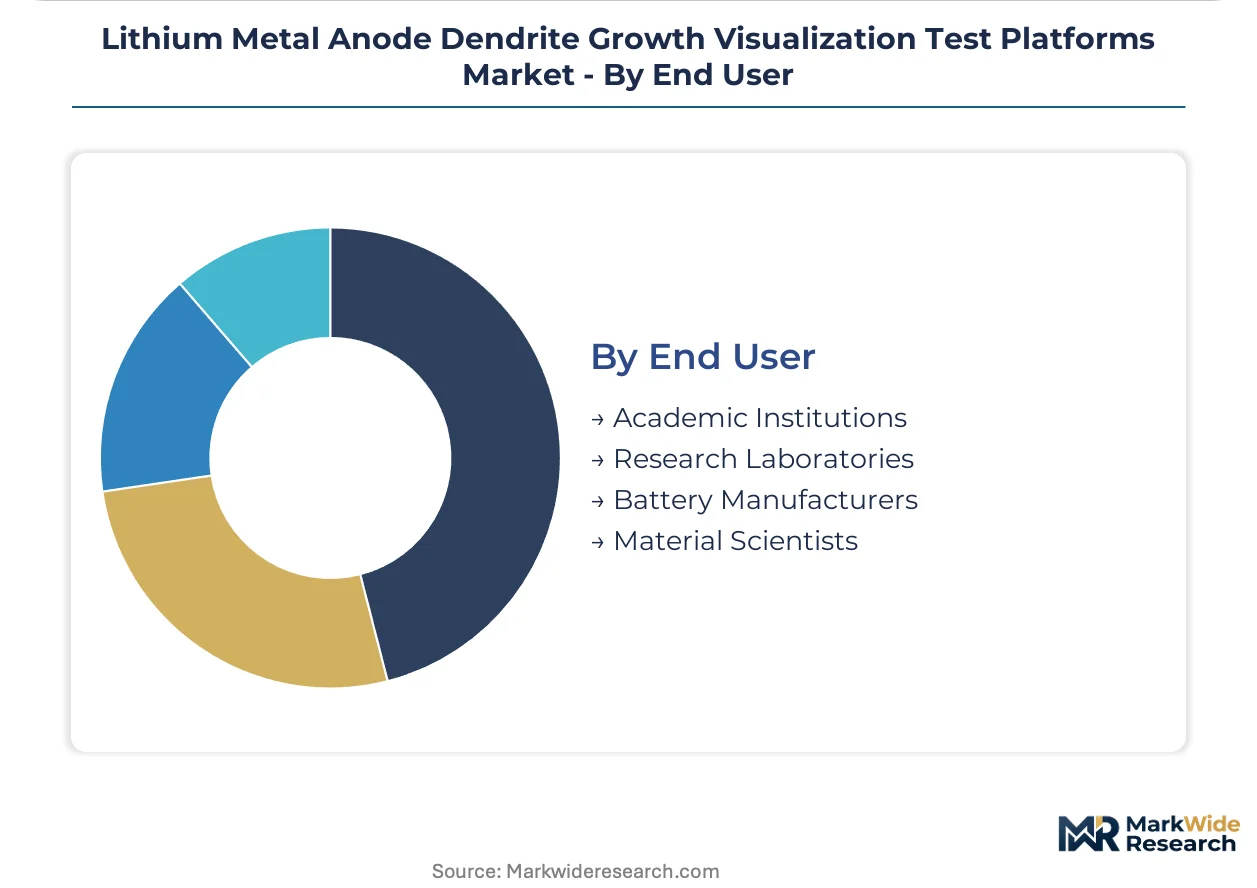
End User:
Customer type determines service intensity, with battery manufacturers demanding 24-hour response contracts unavailable to academic purchasers.
- Academic Institutions:NSF and European Research Council grants fund visualization infrastructure at Carnegie Mellon, TU Munich, and Tohoku University where graduate student operation keeps labor costs minimal. These buyers prioritize modular upgrade paths and open-source software compatibility over turnkey integration.
- Research Laboratories:National facilities including Argonne, NIMS, and Fraunhofer IKTS operate centralized visualization cores serving multiple principal investigators. Shared-instrument models spread capital burden while demanding robust scheduling software and cross-training protocols.
- Battery Manufacturers:Samsung SDI, QuantumScape, and Solid Power maintain captive visualization capabilities for proprietary cell development, generating the highest per-site revenue for platform vendors through premium service contracts.
- Material Scientists:Electrolyte and anode substrate suppliers at BASF, Mitsui Chemicals, and 3M use visualization data to validate product specifications for downstream cell customers.
Today's leader: Academic Institutions. Tomorrow's challenger: Battery Manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Toyota City anchors visualization platform procurement as Japanese automotive cell developers accelerate solid-state battery timelines. Stuttgart and Berlin clusters drive German demand through EU Battery Regulation compliance mandates. Boston and Berkeley laboratories concentrate US research funding, while Bengaluru emerges as India's primary R&D hub under BIS standards development.
Japan
METI consortia coordinate national R&D funding that prioritizes dendrite suppression for next-generation electric vehicle cells. JIS committees specify imaging resolution benchmarks for anode characterization that shape platform procurement specifications. Toyota City and Tsukuba host the densest concentration of visualization installations, serving Toyota, Panasonic, and national laboratory networks.
Germany
Solid-state battery developers in Stuttgart and Munich expand platform procurement as EU Battery Regulation tightens safety verification requirements. ECHA guidance mandates dendrite-related documentation for lithium metal cells entering European markets. Fraunhofer IKTS and Jülich Research Centre operate centralized visualization cores serving multiple industrial and academic principal investigators.
United States
NSF and DOE grant funding requires demonstrated interoperability between instrumentation modules, consolidating vendor relationships around full-stack providers. NHTSA guidelines reference solid-state battery validation protocols requiring visualization evidence for transportation safety filings. Argonne National Laboratory and Lawrence Berkeley National Laboratory maintain synchrotron-linked tomography systems for non-destructive 3D reconstruction.
India
BIS standards development for lithium metal cell safety creates first-mover advantage for platform vendors establishing local service networks. The country's national electrochemical research programs under DST funding prioritize operando imaging capabilities. Bengaluru and Hyderabad clusters host emerging battery R&D centers at IISc and IIT facilities with constrained capital budgets favoring modular optical platforms.
South Korea
Samsung SDI and LG Energy Solution maintain captive visualization capabilities for proprietary cell development, generating premium service contract demand. MFDS coordination with automotive safety regulators references visualization data for transportation battery certification. Daejeon-Sejong corridor hosts KAIST and KIST facilities adopting AI-assisted image analysis for high-throughput screening protocols.
Lithium Metal Anode Dendrite Growth Visualization Test Platforms Market Competitive Landscape
Global majors compete with regional champions across electrochemical instrumentation heritage and imaging specialization dimensions. The vendor base separates into three tiers: full-stack platform providers bundling hardware, software, and maintenance; modular component suppliers serving university laboratories with constrained capital budgets; and microscopy specialists integrating vacuum-compatible cell fixtures for nanoscale resolution requirements. Dominant competitive moves include strategic partnerships between electrochemical workstation manufacturers and imaging system vendors, plus geographic expansion through local service network establishment in underpenetrated markets.
Among Swiss and French precision instrumentation specialists, Metrohm and Bio-Logic Science Instruments exemplify the electrochemical heritage archetype, leveraging potentiostat integration to anchor European laboratory demand. Gamry Instruments occupies a position within the compact benchtop tier suited for academic settings. These three entities represent contrasting approaches to the instrumentation convergence trend dissolving boundaries between electrochemical workstations and imaging systems.
| Leading Market Players |
|---|
| Metrohm |
| Bio-Logic Science Instruments |
| Gamry Instruments |
| Ametek |
| Keysight Technologies |
| Bruker |
| Thermo Fisher Scientific |
| Hitachi High-Tech |
| ZEISS |
| Others |
Pricing and Supply Chain Analysis
Family-owned precision instrumentation specialists in Germany and Switzerland anchor mid-tier supply, their conservative balance sheet management limiting aggressive price competition even as Asian competitors expand service networks. Their ownership structure sustains premium pricing discipline for electrochemical heritage platforms while constraining capacity expansion that might destabilize helium-cooled electron microscopy segments.
Pricing Analysis
Helium isotope costs pass through directly to cryogenic electron microscopy platform pricing, with Qatar and US supply concentration amplifying volatility for buyers lacking long-term offtake contracts. Three-tier pricing structure across premium, standard, and economy levels separates full-stack bundled providers from modular component vendors and refurbished optical systems. Cost compression in university-facing benchtop segments is intensifying because Indian and Korean manufacturers are expanding distribution. Academic institutions exhibit highest price sensitivity, while battery manufacturers prioritize 24-hour service response over capital expenditure minimization.
Supply Chain Analysis
Dual-sourcing requirements for helium-3 and helium-4 isotopes mandate multi-supplier qualification among cryogenic platform buyers, though Qatar and US production concentration limits genuine supply diversification. German, Japanese, and Swiss manufacturers dominate precision electrochemical workstation supply, drawing from specialized vacuum component foundries in Bavaria and precision optics clusters in Jena. Single-source vulnerability concentrates in helium supply chains, with export restriction risk from Qatar and US strategic reserve releases. Distribution runs through direct sales teams for battery manufacturers and academic distributors for university laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story: solid-state battery commercialization timelines are compressing procurement toward premium operando platforms with integrated AI-assisted documentation capabilities.
For Market Incumbents: Deploy certification investment as the primary defensive lever. Pursue ISO 17025 accreditation for visualization protocols to lock in contract testing revenue from EU Battery Regulation compliance workflows. Deepen backward integration into vacuum-compatible cell fixture manufacturing to defend margin position against modular component suppliers. The threat of open-source image analysis pipelines fragmenting research collaboration demands proprietary software lock-in through bundled maintenance contracts. For New Entrants and Emerging Players: The gap between premium full-stack providers and economy refurbished optical platforms creates white-space opportunity. Target India's underpenetrated battery R&D clusters where BIS standards development is creating first-mover advantage for local service network establishment. Focus on modular upgrade paths for IISc and IIT facilities with constrained capital budgets. The most penetrable segment is AI-assisted image analysis software layered onto existing hardware installations. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap electrochemical workstation specialists lacking imaging integration capabilities. The five-to-ten-year viability window favors acquisition targets with established METI or EU Battery Regulation reference customer relationships. Target firms with captive helium sourcing contracts or alternative cryogenic cooling technologies. Watch for inflection in US IRA manufacturing credit deployment timelines as signal for domestic solid-state battery visualization demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assisted Image Analysis Integration | Automates dendrite classification for Samsung SDI and LG Energy Solution high-throughput screening protocols. |
| Helium Supply Contract Securement | Mitigates Qatar export restriction exposure for Bruker and Thermo Fisher Scientific cryogenic platform lines. |
| ISO 17025 Accreditation Investment | Enables Fraunhofer IKTS and Jülich Research Centre contract testing revenue from EU compliance workflows. |
| India Service Network Establishment | Captures BIS standards development first-mover advantage at IISc Bengaluru and IIT Hyderabad clusters. |
| Operando Cell Design Patent Portfolio | Protects Metrohm and Bio-Logic integration moats as solid-state architectures displace liquid electrolyte programs. |
Research Methodology
Multiple input streams — primary interviews with platform engineering directors, battery manufacturer R&D heads, and national laboratory instrumentation officers; secondary validation through SEC filings of electrochemical instrumentation vendors, METI funding disclosure databases, and EU Battery Regulation implementation guidance — were reconciled against customs records of helium isotope imports and vacuum component trade flows. Bottom-up unit economics for optical, electron, and X-ray platform categories were triangulated with top-down market sizing from national research funding allocations.
Historical procurement patterns from Japanese METI consortia and German solid-state battery programs were cross-referenced against expert panel inputs from Stuttgart, Toyota City, and Boston clusters. Segmentation modeling spanned product type, technology tier, application workflow, and end-user archetype across the projection horizon. CAGR derivation incorporated equipment replacement cycles compressing from liquid electrolyte to solid-state architectures, helium price volatility scenarios, and AI-assisted image analysis adoption curves. Industry-specific forecast inputs included EU Battery Regulation documentation deadline phasing and US IRA manufacturing credit facility commissioning timelines.
Caveats apply where helium supply disruption, REACH compliance friction extension, or solid-state battery commercialization delays could materially shift the outlook. Forecasts reflect assumptions regarding METI funding continuity, ECHA guidance stability, and cross-disciplinary talent pipeline expansion. Deviation in EU Battery Regulation enforcement intensity or US NHTSA solid-state validation protocol finalization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
IoT Testing Equipment Market
Test and Measurement
Test Rig Market
Test and Measurement
Digital Thickness Gauge Market
Test and Measurement
Semiconductor Bond Testing Market
Test and Measurement
Simulation and Test Data Management Market
Test and Measurement
Circuit Tracer Market
Test and Measurement
Protective Earth Resistance Meter Market
Test and Measurement
LAN Tester Market
Test and Measurement
AI-Enabled Testing Tools Market
Test and Measurement
Power Electronics GaN and SiC Device Reliability Test Systems Market
Test and Measurement
Video Test Equipment Market
Test and Measurement
Noise Vibration Harshness (NVH) Testing Market
Test and Measurement
Hardware-Assisted Verification Market
Test and Measurement
Data Center Testing Market
Test and Measurement
Battery Capacity Testers Market
Test and Measurement
AI-Assisted NDT Data Analytics and Defect Characterization Platforms Market