
 Portable Appliance Tester (PAT) Market | 2026-2036
Portable Appliance Tester (PAT) Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Appliance Tester (PAT) Market Analytics
China's expanding electronics manufacturing corridor is reshaping regional supply dynamics for portable appliance testers. Megger Group Limited leverages its century-long heritage in electrical testing to sustain premium positioning across European utility channels. Fluke Corporation anchors North American industrial demand through dense calibration service networks. Seaward Electronic Ltd. specializes in compact, battery-operated units that dominate UK contractor toolkits.
A portable appliance tester is an electrical safety instrument designed to verify the integrity of power cords, plugs, and internal insulation through programmed sequences of ground continuity, insulation resistance, and earth leakage measurements, typically outputting pass/fail determinations against IEC 61543 or equivalent national standards. Its primary purpose is to prevent electric shock and fire hazards in workplaces where movable equipment undergoes repeated handling and environmental stress. Smart testers incorporating Bluetooth logging and cloud-based record retention are capturing the fastest expansion, while analog units remain entrenched in price-sensitive developing markets where technician familiarity outweighs connectivity needs. Automated test sequences with barcode asset tracking command the strongest margin pools, particularly among facility managers overseeing multi-site compliance portfolios.
IEC 61543 standards, OSHA electrical safety mandates, and EU CE marking requirements collectively dictate minimum test intervals, calibration protocols, and documentation retention that directly determine replacement demand and upgrade cycles. Germany's KBA and France's CNIL have both issued sector-specific guidance on data-logging PAT devices that influences product development roadmaps for manufacturers seeking unified European type approval. Stakeholders must monitor how evolving cybersecurity frameworks for connected test equipment reshape hardware architecture and certification costs without eroding field durability expectations.
Market Dynamics
Factory automation across Germany's manufacturing belt is compressing replacement cycles for portable appliance testers, while the EU's tightened Workplace Safety Directive mandates shorter inspection intervals that force equipment upgrades.
Growth Catalysts
- EU Workplace Safety Directive:Mandatory inspection interval reductions across industrial facilities trigger systematic tester replacement programs. Facility managers must upgrade to compliant equipment.
- Battery-operated compact units:Contractor mobility requirements in commercial building maintenance drive preference for lightweight, field-portable designs with extended operational runtime.
- Cloud-based record retention:Bluetooth-enabled testers with automated logging streamline multi-site compliance documentation for facility management portfolios.
Market Restraints
- Calibration service concentration:North American industrial demand depends on dense third-party calibration networks that limit vendor switching flexibility.
- Analog unit entrenchment:Price-sensitive developing markets retain technician preference for non-digital interfaces, slowing smart tester penetration.
- IEC 61543 compliance costs:Certification and type approval expenses for connected test equipment strain mid-tier manufacturer margins.
Strategic Opportunities
- China's electronics manufacturing corridor:Expanding production clusters create regional supply hub potential for Asia-Pacific distribution.
- Automated barcode asset tracking:Multi-site facility managers seek integrated test-sequence and inventory management systems for compliance oversight.
- Cybersecurity framework adaptation:Evolving hardware architecture standards for connected test equipment create first-mover certification advantages.
Industry Challenges
- Technician certification gaps:Smart tester operation requires digital literacy training that legacy electrical safety personnel often lack.
- Legacy system integration:Cloud-logging PAT devices must interface with existing enterprise asset management platforms without disrupting field durability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Appliance Tester (PAT) Market |
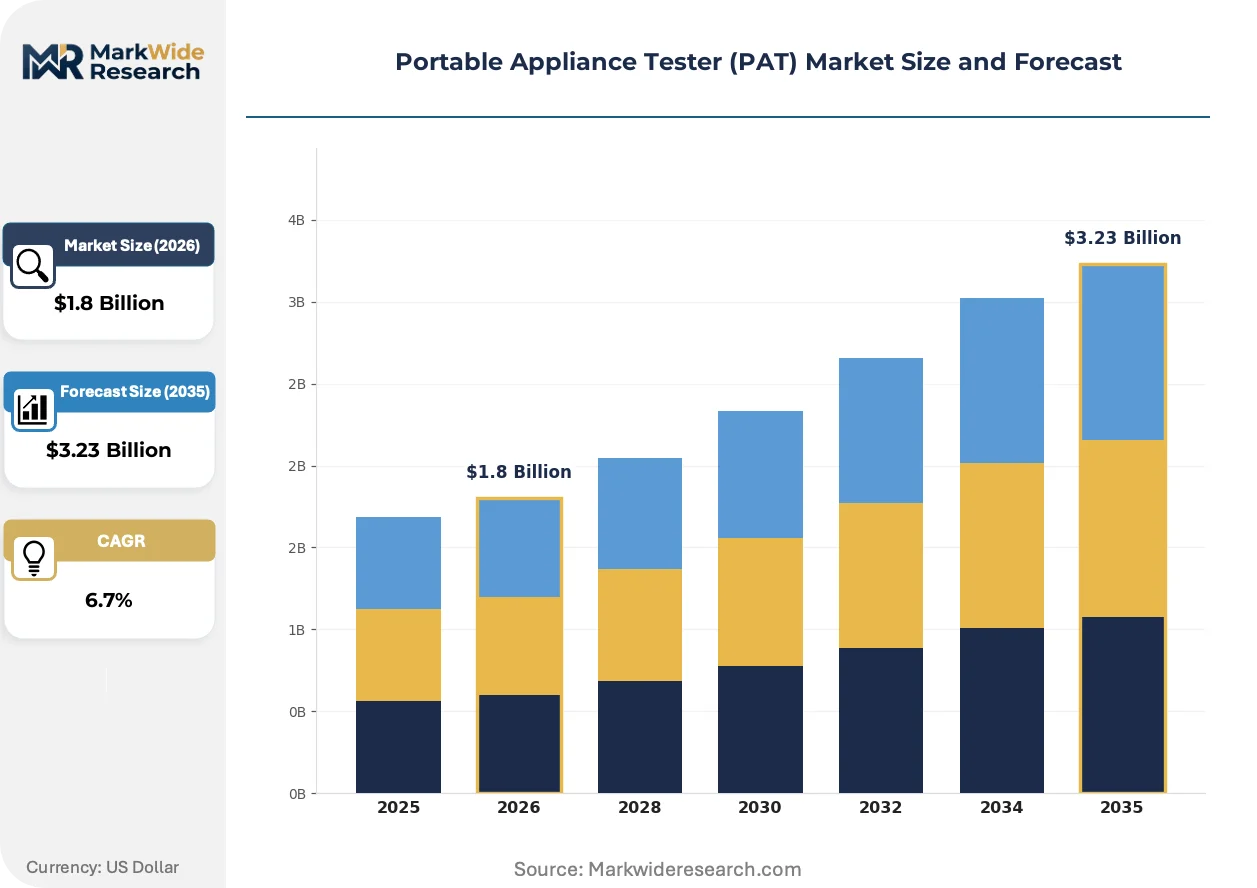
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog, Digital, Smart, Automated Application: Commercial Establishments, Industrial Facilities, Residential Use, Educational Institutions Technology: Ground Continuity Testing, Insulation Resistance Testing, Functional Testing, Earth Leakage Testing End User: Facility Managers, Safety Inspectors, Technicians, Quality Control Personnel |
| Companies Covered | Megger Group Limited, Metrel, Fluke Corporation, Yokogawa Electric Corporation, Anritsu Corporation, Keysight Technologies, Seaward Electronic Ltd., Tektronix, Inc., Rohde & Schwarz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Appliance Tester (PAT) Market Evolving Landscape
Smart connectivity and automated compliance documentation are redefining how portable appliance testers deliver value beyond basic safety verification, compressing the gap between field testing and enterprise record management.
Bluetooth-enabled data logging is digitizing how inspection records flow from factory floors to compliance databases. Automotive and electronics manufacturers with multi-site operations are adopting these units fastest. The technology is digitizing asset management workflows that previously required manual transcription and paper filing.
Germany's KBA and France's CNIL have issued sector-specific guidance on data-logging PAT devices that shapes unified European type approval requirements. Manufacturers must now architect hardware for both electrical safety and data protection compliance. Connected test equipment faces certification timelines that lag behind product development cycles.
Facility managers now bundle tester procurement with calibration service contracts rather than purchasing hardware separately. Industrial maintenance channels are unbundling equipment sales from ongoing compliance support. This pattern is most visible in Germany's manufacturing belt where factory automation demands predictable operational expenditure structures.
Portable Appliance Tester (PAT) Market Segmentation
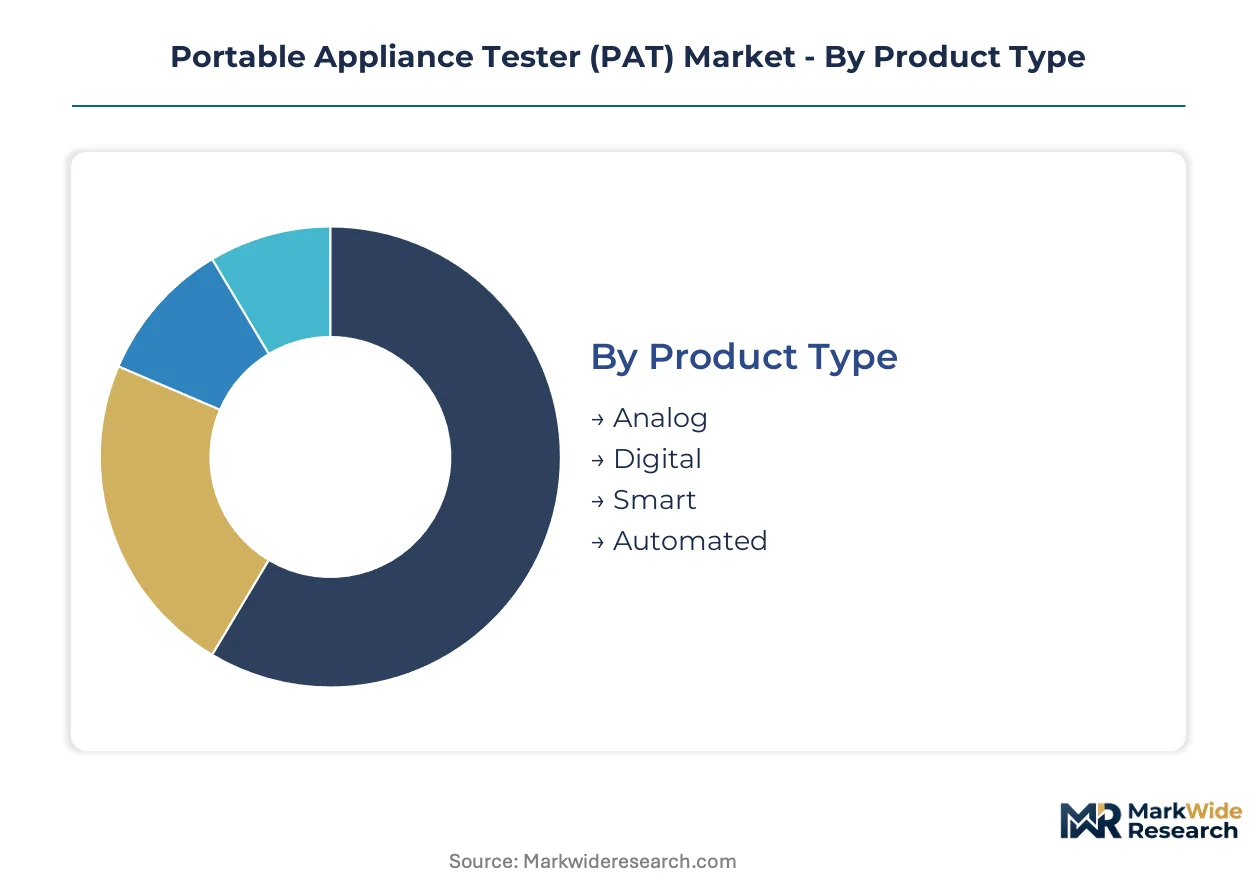
Segmentation in the PAT market reveals distinct equipment lifecycles and buyer priorities across product architectures and operational contexts. Replacement cycles vary from decades for basic analog units to under five years for cloud-connected smart systems, creating tiered revenue streams for manufacturers.
Product Type:
Cycle times compress sharply across this spectrum, with analog units persisting for fifteen-plus years while smart testers face obsolescence within three to five years due to software and connectivity upgrades.
- Digital:Microprocessor-controlled units with LCD readouts and programmable test sequences dominate mid-market procurement in Germany's manufacturing belt. Facility managers favor these for balance of accuracy and capital efficiency where cloud connectivity remains non-essential.
- Smart:Bluetooth-enabled testers with automated logging and cloud-based record retention capture the steepest expansion trajectory. Automotive and electronics manufacturers with multi-site operations drive demand for seamless compliance documentation workflows.
- Analog:Needle-display units with manual interpretation persist in price-sensitive developing markets where technician familiarity outweighs digital interface requirements.
- Automated:Barcode-integrated systems with asset tracking command premium positioning among facility managers overseeing multi-site compliance portfolios.
Digital units anchor the volume base while smart testers gain share at the steepest rate.
Application:
Cost tiers separate this category, with industrial facilities absorbing premium pricing for automated systems while residential and educational buyers prioritize capital efficiency.
- Industrial Facilities:Factory automation across Germany's manufacturing belt compresses replacement cycles for high-duty testers. EU Workplace Safety Directive mandates for shorter inspection intervals force systematic equipment upgrades.
- Commercial Establishments:Contractor mobility requirements in building maintenance drive preference for lightweight, battery-operated designs with extended operational runtime.
- Educational Institutions:Training programs require durable, intuitive interfaces that accommodate varying technician skill levels.
- Residential Use:Landlord compliance obligations in rental property portfolios generate steady demand for entry-level digital units.
Industrial facilities absorb the highest equipment spend per site while commercial establishments represent the broadest addressable base.
Technology:
Volume concentration favors foundational safety tests, though margin pools deepen where multiple test modalities integrate into unified workflows.
- Earth Leakage Testing:Differential current measurement detects insulation degradation before shock hazards materialize. IEC 61543 mandates elevate this to mandatory status across EU industrial installations.
- Insulation Resistance Testing:Megohm measurement of internal wiring integrity commands premium positioning in high-voltage industrial contexts where arc-flash prevention dominates safety protocols.
- Ground Continuity Testing:Low-resistance path verification forms the baseline requirement for all PAT certification regimes.
- Functional Testing:Operational verification under load conditions completes comprehensive safety protocols for critical equipment.
Ground continuity testing anchors universal compliance requirements while earth leakage testing deepens margin capture in industrial segments.
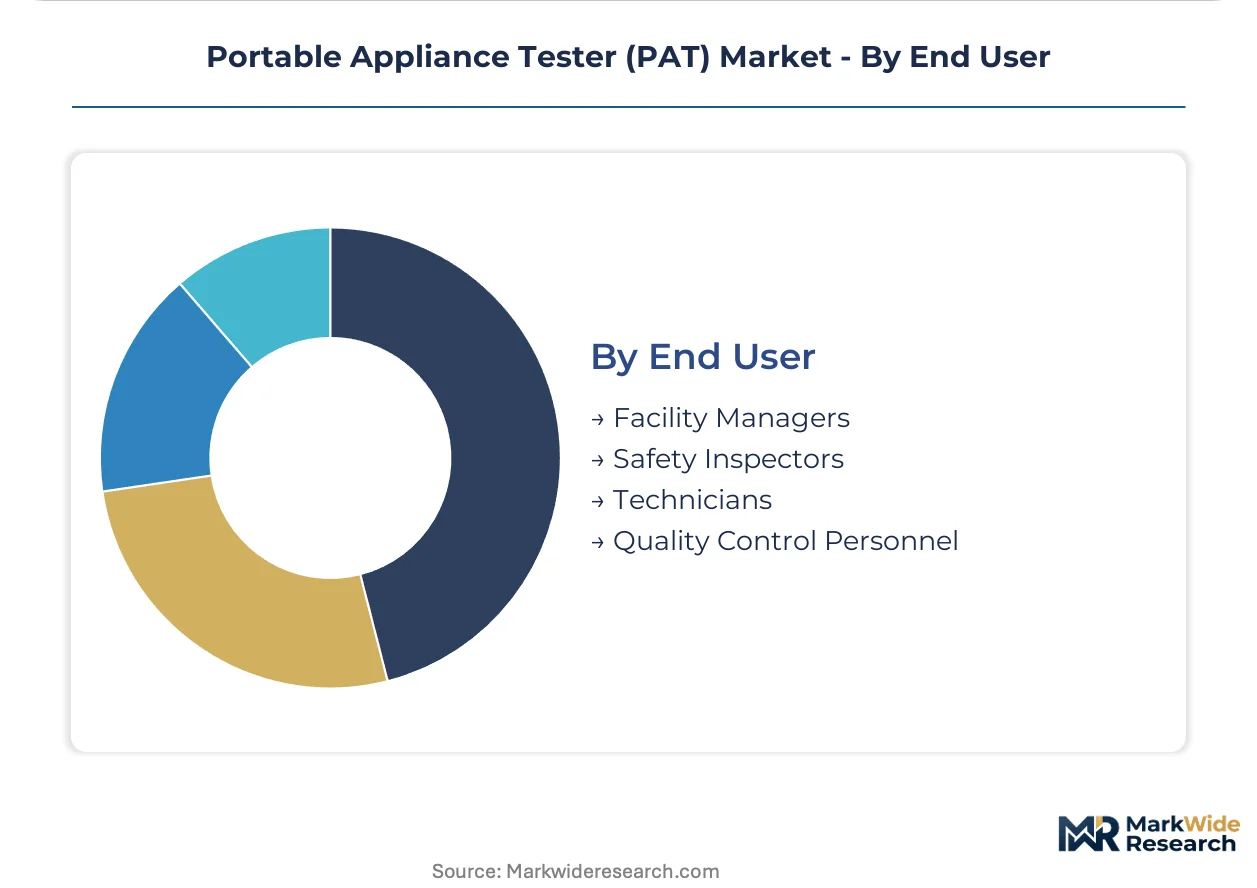
End User:
Customer type determines procurement authority and service contract attachment rates, with facility managers controlling capital budgets and technicians influencing replacement specifications.
- Facility Managers:Multi-site portfolio oversight drives demand for cloud-integrated systems with centralized compliance dashboards. Procurement bundles increasingly include calibration service contracts.
- Safety Inspectors:Regulatory enforcement roles require certified, traceable equipment with audit-ready documentation capabilities.
- Technicians:Field operatives prioritize ergonomic portability and intuitive interface design for high-volume daily testing.
- Quality Control Personnel:Manufacturing line integration demands automated pass-fail determination with direct MES system connectivity.
Facility managers control capital deployment decisions while technicians shape replacement specifications through operational feedback.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's KBA anchors the regulatory framework shaping European portable appliance tester requirements, while factory automation across the continent compresses equipment replacement cycles. National regulators in France, the United Kingdom, and China have issued complementary guidance on data-logging test equipment.
Germany
Factory automation across Bavaria and Baden-Württemberg drives recurring tester replacement cycles among automotive suppliers and precision machinery builders. The KBA's sector-specific guidance on data-logging PAT devices shapes unified European type approval requirements. Stuttgart's manufacturing belt concentrates demand for automated barcode-integrated systems serving multi-site compliance portfolios.
France
Commercial building maintenance contractors in Île-de-France prioritize lightweight battery-operated units for high-mobility inspection routines. The CNIL has issued data protection guidance for connected test equipment that influences hardware architecture decisions. Lyon and Grenoble host electronics manufacturers adopting Bluetooth-enabled testers with cloud-based record retention.
United Kingdom
Landlord compliance obligations across England's rental property portfolios generate steady demand for entry-level digital units. HSE electrical safety enforcement mandates systematic inspection programs in commercial and industrial premises. Greater Manchester and Birmingham contractor toolkits favor compact, field-portable designs from established domestic suppliers.
China
Expanding electronics manufacturing corridors in Guangdong and Jiangsu provinces reshape regional supply dynamics for portable appliance testers. The country's national standardization body aligns GB standards with IEC 61543 for export-oriented production. Shenzhen's component ecosystem supports rapid product development cycles for both domestic consumption and Asia-Pacific distribution.
United States
OSHA electrical safety mandates drive systematic compliance programs across industrial facilities in the Midwest and Southeast. Dense third-party calibration networks limit vendor switching flexibility for North American industrial buyers. Texas and Ohio manufacturing clusters absorb premium pricing for automated systems with direct MES integration.
Portable Appliance Tester (PAT) Market Competitive Landscape
Capability concentration sits with heritage electrical testing specialists; scale advantage sits with diversified instrumentation conglomerates. The vendor base organizes into three tiers: century-old European specialists commanding premium utility channels, North American calibration-anchored industrial suppliers, and Asia-Pacific component-integrated manufacturers. Two dominant competitive moves define current positioning: bundling hardware procurement with long-term calibration service contracts, and architecting cybersecurity-compliant connectivity modules for unified European type approval.
Among heritage European specialists, Megger Group Limited and Seaward Electronic Ltd. occupy positions shaped by century-long or regionally dominant track records in electrical safety verification. Fluke Corporation anchors the North American industrial tier through calibration service network density. These three exemplify how geographic origin and channel structure determine competitive positioning more than product specification differentiation alone.
| Leading Market Players |
|---|
| Megger Group Limited |
| Metrel |
| Fluke Corporation |
| Yokogawa Electric Corporation |
| Anritsu Corporation |
| Keysight Technologies |
| Seaward Electronic Ltd. |
| Tektronix, Inc. |
| Rohde & Schwarz |
| Others |
Value Network & Pricing Analysis
Component concentration in China's Guangdong and Jiangsu provinces anchors cost structures for portable appliance tester manufacturers, with Shenzhen's electronics ecosystem determining where margin pools accumulate among smart connectivity modules and battery-operated compact designs.
Pricing Analysis
Price spreads of forty to sixty percent separate German-manufactured automated systems from entry-level Asian digital units. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling. Pricing pressure stems from mid-tier manufacturers absorbing IEC 61543 compliance costs for connected equipment. Commercial contractors exhibit highest price sensitivity, while industrial facility managers prioritize calibration service integration over unit cost.
Supply Chain Analysis
Electronics manufacturing services in Taiwan and mainland China hold dominant contract-manufacturing capacity for PAT device assembly. Microprocessor sourcing draws from South Korean and Taiwanese foundries, while lithium-ion battery cells feed from Chinese and South Korean suppliers. Single-source vulnerability concentrates in Bluetooth module chipsets for smart tester variants. Distribution runs through industrial maintenance channels and electrical safety equipment distributors serving contractor toolkits and facility management procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Portable appliance tester markets are approaching a platform-economics inflection where cloud-based record retention and enterprise asset management interoperability determine competitive survival rather than hardware specifications alone.
For Market Incumbents: Build switching-cost moats through calibration service contract bundling that locks facility managers into multi-year compliance support relationships. Deepen backward integration into cloud software modules to capture recurring revenue streams. Defend against emerging Asia-Pacific component-integrated manufacturers by accelerating cybersecurity-compliant connectivity certification ahead of unified European type approval timelines.
For New Entrants and Emerging Players: India's price-sensitive developing markets present the most penetrable white-space opportunity where analog unit entrenchment creates opening for affordable digital alternatives. Target UK landlord compliance obligations in England's rental property portfolios with entry-level battery-operated designs. Pursue calibration-as-a-service partnerships with established distributors to bypass dense third-party network barriers in North America.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed electrical testing specialists holding dense European utility channel relationships. Five-to-ten year viability hinges on successful cloud-platform transition rather than hardware margin maintenance. Monitor German KBA and France CNIL regulatory guidance evolution as signal for certification cost inflection that reshapes competitive economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Platform Integration | Bluetooth-enabled data logging transforms field testing into enterprise compliance workflows for multi-site facility managers. |
| Cybersecurity Certification Investment | Hardware architecture adaptation to KBA and CNIL data protection guidance secures unified European type approval positioning. |
| Calibration Service Expansion | Predictable operational expenditure structures attract Germany's manufacturing belt factory automation procurement. |
| Geographic Manufacturing Footprint | Shenzhen component ecosystem proximity accelerates product development cycles for Asia-Pacific distribution. |
| Strategic Partnership with EMS Providers | Taiwanese and Chinese contract manufacturers enable cost-competitive smart tester production at scale. |
Research Methodology
Initial hypotheses were tested against primary input from electrical safety compliance officers, facility maintenance directors, calibration service technicians, and industrial procurement managers and refined through secondary validation against IEC standards documentation, OSHA enforcement records, EU Workplace Safety Directive amendments, and customs trade data for electrical testing equipment. Bottom-up segment sizing triangulated with top-down macroeconomic indicators across the analysis window.
Demand-supply-balance framing anchored the analytical framework across product type, application, technology, and end user dimensions over the projection horizon. CAGRs derived from replacement cycle compression rates in Germany's manufacturing belt and smart tester adoption curves in automotive multi-site operations. Modeled inputs included factory automation penetration indices and regulatory inspection interval mandate changes.
The forecast holds incumbent behavior within observed patterns; aggressive cloud-platform investments by heritage European specialists or rapid calibration network buildouts by Asia-Pacific entrants would shift outcomes. Quarterly review of KBA guidance updates, CNIL data protection rulings, and Shenzhen component pricing indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Flash Point Tester Market
Test and Measurement
Impact Testing Machine Market
Test and Measurement
Global Laser Tracker Market
Test and Measurement
Leak Testing Machine Market
Test and Measurement
Europe Signal Generator Market
Test and Measurement
Automated Calibration-as-a-Service Platforms for Test and Measurement Assets Market
Test and Measurement
Global Bench Scale Market
Test and Measurement
One-Box Testers Market
Test and Measurement
Electronic Test Instrument Market
Test and Measurement
Bursting Strength Tester Market
Test and Measurement
Semiconductor Metrology and Inspection Market
Test and Measurement
EMC Electromagnetic Compatibility Test Laboratory Market
Test and Measurement
State Transition Testing Market
Test and Measurement
Thin Film Metrology Systems Market
Test and Measurement
Continuous Methane Monitoring and Leak Detection Test Equipment Market
Test and Measurement
Chiplet Integration and Die-to-Die Interconnect Test Solutions Market