
 Battery CT Inspection Market | 2026-2036
Battery CT Inspection Market Size, Share, and Industry Trends Forecast 2026-2036
Battery CT Inspection Market Insights
Tungsten is shifting toward microfocus X-ray tubes as manufacturers seek finer resolution for detecting lithium-ion electrode delamination. ZEISS leverages its metrology heritage to dominate high-end battery research installations across German automotive clusters. Nikon sustains competitive positioning through specialized CT systems optimized for prismatic cell geometries. Waygate Technologies extends its industrial inspection portfolio into gigafactory quality lines with automated defect recognition.
Battery CT inspection employs X-ray computed tomography to generate three-dimensional volumetric reconstructions of electrochemical cells, revealing internal defects such as separator folds, electrode misalignment, and electrolyte voids at resolutions below one micrometer. The technology serves critical functions in safety validation, manufacturing yield improvement, and forensic analysis of thermal runaway failures. Computed Tomography anchors the technology mix due to its unmatched spatial resolution for dense cathode materials, while In-Line Inspection emerges as the fastest-expanding service category as gigafactories integrate real-time feedback loops. Offline Inspection retains margin concentration in premium aerospace and defense battery certification programs where throughput speed matters less than analytical depth.
FDA oversight of medical device batteries and UN 38.3 transport testing protocols shape baseline safety requirements for CT validation workflows in the United States. ECHA's REACH restrictions on cobalt sourcing and the EU Battery Regulation's digital passport mandates are forcing European manufacturers to deploy traceable inspection data architectures. China's GB standards for power battery safety, enforced by SAMR, mandate specific internal defect detection capabilities that favor domestic CT equipment procurement. Stakeholders must monitor how divergent national certification requirements for solid-state cell architectures will fragment equipment specifications and service protocols.
Market Dynamics
The transition from offline laboratory analysis to inline production monitoring is compressing inspection cycle times and forcing equipment vendors to reengineer CT systems for throughput speeds exceeding 100 cells per minute.
Growth Catalysts
- UN 38.3 Transport Testing:Updated lithium battery shipping protocols mandate volumetric defect documentation, compelling manufacturers in Germany and China to install CT validation stations before export certification.
- Solid-State Cell Commercialization:Next-generation solid electrolyte architectures require sub-micron resolution to detect ceramic layer delamination, pulling microfocus tube technology into mainstream battery production.
- Gigafactory Scale Economics:South Korean and Japanese cylindrical cell producers are integrating real-time feedback loops that automatically reject misaligned electrode stacks before downstream assembly.
Market Restraints
- Tungsten Supply Concentration:Microfocus X-ray tube anodes depend on tungsten sourced primarily from Chinese mining operations, exposing equipment manufacturers to input cost volatility and export restriction risk.
- Technical Throughput Ceiling:Current CT reconstruction algorithms cannot process high-density cathode materials at speeds matching laser welding or electrolyte filling stations, creating inline inspection bottlenecks.
- Regulatory Fragmentation:Divergent certification requirements between China's GB standards, EU Battery Regulation digital passport mandates, and US FDA medical device battery oversight force redundant validation workflows.
Strategic Opportunities
- India Battery Manufacturing:PLI scheme subsidies for domestic cell production create first-mover advantage for CT equipment vendors establishing local service infrastructure ahead of capacity ramp.
- Second-Life Battery Grading:End-of-life electric vehicle battery repurposing requires rapid internal state assessment, opening a service category distinct from manufacturing quality control.
- AI-Assisted Defect Recognition:Machine learning convergence with volumetric imaging enables automated classification of separator folds and electrolyte voids without human radiologist interpretation.
Industry Challenges
- Multiphysics Simulation Talent:CT system optimization requires expertise spanning X-ray physics, computational geometry, and battery electrochemistry, a skill combination scarce in industrial metrology labor pools.
- Legacy MES Integration:Gigafactory quality data architectures built on proprietary automotive manufacturing execution systems resist seamless incorporation of three-dimensional volumetric inspection outputs.
- Calibration Drift Management:Thermal cycling in high-throughput production environments degrades CT geometric accuracy, demanding continuous reference standard protocols that interrupt production flow.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery CT Inspection Market |
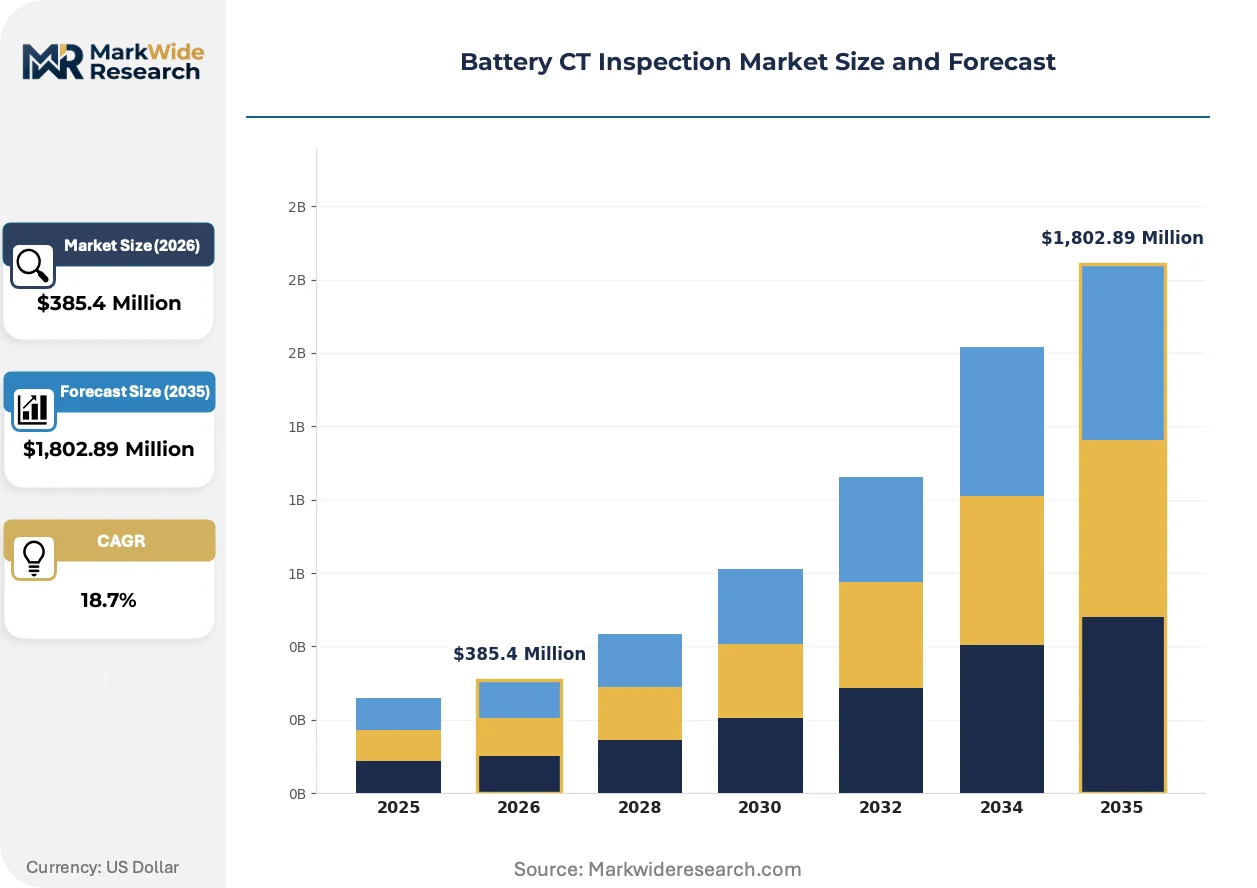
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,802.89 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Computed Tomography, Digital X-Ray, Ultrasonic Testing, Electromagnetic Testing Service Type: In-Line Inspection, Offline Inspection, Quality Assurance, Maintenance Services End User: Battery Manufacturers, Research Institutes, Automotive OEMs, Aerospace Companies Application: Safety Testing, Quality Control, Research & Development, Prototyping |
| Companies Covered | ZEISS, Nikon, Excillum, North Star Imaging, Lumafield, Waygate Technologies, Varex Imaging, Avonix Imaging, VisiConsult, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery CT Inspection Market Trends and Innovations
Computational reconstruction algorithms and artificial intelligence classification are collapsing the latency between image acquisition and defect disposition, enabling closed-loop manufacturing control that was technically impossible five years ago.
Phase-contrast CT imaging is expanding into battery inspection applications where conventional absorption contrast fails to distinguish soft separator materials from electrolyte-filled pores. European research installations at German automotive clusters are piloting these systems for solid-state ceramic electrolyte characterization. The technology is expanding into production environments as grating manufacturing costs decline and laboratory-validated protocols transfer to industrial equipment.
China's SAMR enforcement of updated GB standards for power battery safety is mandating specific internal defect detection capabilities that domestic equipment suppliers are engineering into turnkey inspection stations. The industrial consequence is a procurement preference for locally manufactured CT systems that ship with pre-validated compliance documentation. Battery producers in Shenzhen and Ningbo are responding by specifying domestic equipment for new capacity, compressing market access for foreign vendors.
Automotive OEMs are unbundling inspection service contracts from equipment purchase agreements, creating a subscription revenue stream for specialized CT analytics providers. Equipment vendors in Japan and Germany are responding with outcome-based pricing tied to defect escape rates rather than hardware depreciation schedules. This model is most visible in South Korean cylindrical cell supply chains, where battery producers outsource entire quality stations to inspection specialists bearing performance guarantees.
Battery CT Inspection Market Segmentation
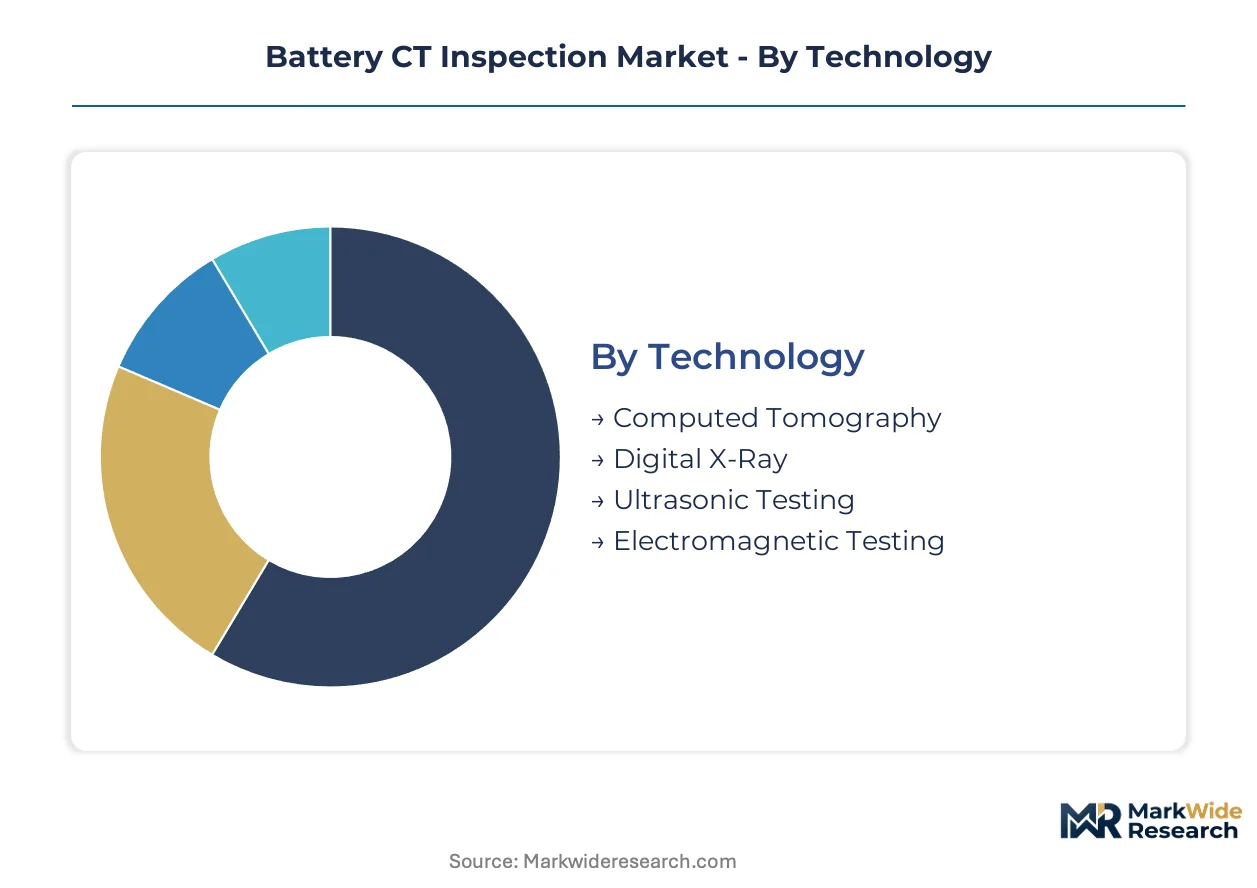
Battery CT inspection segments diverge sharply by buyer sophistication and throughput requirements. Equipment selection hinges on whether the purchase serves laboratory research, gigafactory quality stations, or transport certification workflows.
Technology:
Resolution requirements and material density dictate technology selection across cathode chemistries and cell form factors.
- Computed Tomography:Volumetric reconstruction algorithms generate three-dimensional maps of electrode stacks, separator alignment, and electrolyte distribution at sub-micron precision. Demand concentrates in German and Chinese electric vehicle battery plants where UN 38.3 transport protocols mandate internal defect documentation before export certification.
- Digital X-Ray:Two-dimensional projection imaging delivers rapid pass-fail screening for gross defects like casing cracks or terminal misalignment. South Korean cylindrical cell producers deploy these systems at welding stations where speed exceeds diagnostic depth.
- Ultrasonic Testing:Acoustic impedance mapping detects delamination in soft pouch cells without ionizing radiation exposure. European solid-state battery pilots favor this modality for ceramic electrolyte layer validation.
- Electromagnetic Testing:Eddy current arrays identify conductive particle contamination in electrode coatings during slurry casting operations.
Computed Tomography leads on scale; Digital X-Ray leads on momentum.
Service Type:
Capital deployment strategy separates integrated equipment buyers from outsourced quality service subscribers.
- In-Line Inspection:Real-time CT scanning with automated rejection protocols feeds directly into manufacturing execution systems. Japanese and South Korean gigafactories are climbing the fastest adoption trajectory as electrode alignment tolerances tighten.
- Offline Inspection:Laboratory-grade volumetric analysis with extended reconstruction times supports forensic failure investigation and regulatory submission documentation. Aerospace battery certification programs in Germany sustain premium pricing for this category.
- Quality Assurance:Contracted defect escape rate guarantees shift capital burden from battery producers to inspection service providers.
- Maintenance Services:Preventive calibration protocols and tube replacement schedules minimize unplanned downtime in continuous production environments.
In-Line Inspection commands capital allocation; Offline Inspection commands margin.
End User:
Procurement authority and technical specification depth vary dramatically across buyer categories.
- Battery Manufacturers:Cell producers in Shenzhen and Ningbo specify turnkey CT stations with pre-validated compliance to SAMR-enforced GB standards, favoring domestic equipment procurement.
- Research Institutes:German automotive clusters and European university consortia drive microfocus tube development for solid-state electrolyte characterization.
- Automotive OEMs:Volkswagen, BMW, and BYD unbundle inspection service contracts from equipment purchases, creating subscription revenue streams for specialized analytics providers.
- Aerospace Companies:Satellite and defense battery programs require extended documentation trails that sustain offline inspection margins despite low throughput.
Battery Manufacturers dominate volume; Research Institutes dominate specification influence.
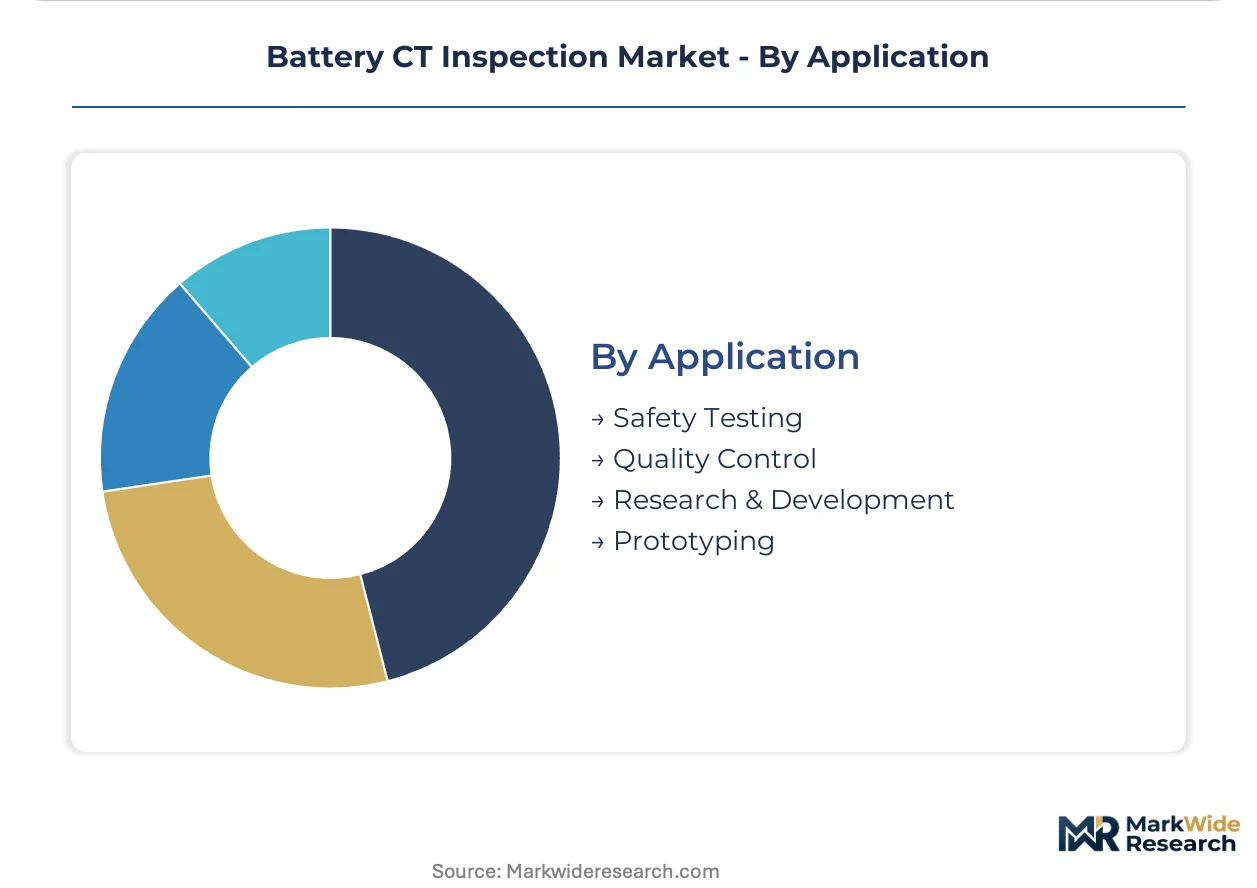
Application:
Regulatory mandate intensity and economic return timeline shape application prioritization.
- Safety Testing:UN 38.3 transport certification and FDA medical device battery oversight create non-negotiable demand for volumetric defect documentation. Chinese export-oriented producers face compliance deadlines that compress procurement cycles.
- Quality Control:Inline rejection of misaligned electrode stacks before downstream assembly protects yield in high-speed cylindrical cell lines. South Korean producers integrate these systems with laser welding stations.
- Research & Development:Solid-state ceramic electrolyte delamination detection pulls phase-contrast CT from laboratory pilots toward production-scale equipment.
- Prototyping:Rapid iteration on cell designs requires flexible inspection protocols that accommodate varying form factors and chemistries without line reconfiguration.
Safety Testing anchors procurement budgets; Quality Control anchors operational integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive clusters anchor CT inspection demand as BMW and Volkswagen unbundle quality service contracts from equipment purchases. Battery producers in Shenzhen and Ningbo deploy domestic turnkey stations to satisfy SAMR-enforced GB standards. South Korean cylindrical cell lines integrate real-time feedback loops that reject misaligned electrode stacks before downstream assembly.
China
Domestic equipment procurement accelerates as SAMR enforcement of updated GB standards mandates specific internal defect detection capabilities. Battery producers in Shenzhen and Ningbo specify turnkey CT stations with pre-validated compliance documentation, compressing market access for foreign vendors. The Pearl River Delta concentration of gigafactory construction drives fastest-expanding inline inspection adoption.
Germany
ZEISS leverages metrology heritage to dominate high-end battery research installations across automotive clusters. ECHA's REACH restrictions on cobalt sourcing and EU Battery Regulation digital passport mandates force traceable inspection data architectures. Bavarian research consortia pilot phase-contrast CT systems for solid-state ceramic electrolyte characterization.
South Korea
Cylindrical cell producers integrate real-time feedback loops climbing fastest adoption trajectory as electrode alignment tolerances tighten. Domestic quality stations outsource to inspection specialists bearing performance guarantees through outcome-based pricing models. Busan-Ulsan industrial corridors concentrate gigafactory quality line investments.
United States
FDA oversight of medical device batteries and UN 38.3 transport testing protocols shape baseline safety requirements for CT validation workflows. Michigan and California battery production facilities face compliance deadlines compressing procurement cycles for volumetric defect documentation. Automotive OEMs unbundle inspection service contracts creating subscription revenue streams.
Japan
Nikon sustains competitive positioning through specialized CT systems optimized for prismatic cell geometries. METI industrial standards push sub-micron resolution requirements for next-generation solid electrolyte architectures. Nagoya-Tokyo manufacturing corridors concentrate inline scanning investments for electrode alignment defect detection.
Battery CT Inspection Market Competitive Landscape
Global majors compete with regional champions across metrology heritage and industrial inspection portfolios. Equipment vendors fragment across three tiers: precision optics specialists leveraging microscopy expertise, industrial automation conglomerates extending non-destructive testing portfolios, and domestic Chinese fabricators engineering turnkey compliance stations. Strategic moves concentrate on AI-assisted defect recognition partnerships and outcome-based pricing models tied to defect escape rates rather than hardware depreciation schedules.
Within the precision optics tier, ZEISS and Nikon exemplify divergent specialization vectors—German metrology heritage against Japanese prismatic geometry optimization. Waygate Technologies occupies a position representing industrial automation conglomerates extending non-destructive testing portfolios into gigafactory quality lines. These three anchors illustrate how competitive positioning separates research-grade installations from high-throughput production environments.
| Leading Market Players |
|---|
| ZEISS |
| Nikon |
| Excillum |
| North Star Imaging |
| Lumafield |
| Waygate Technologies |
| Varex Imaging |
| Avonix Imaging |
| VisiConsult |
| Others |
Pricing and Supply Chain Analysis
Gigafactory procurement teams in Shenzhen and Ningbo specifying turnkey CT stations with pre-validated SAMR compliance documentation are forcing equipment vendors to absorb certification costs upfront, compressing hardware margins while elevating service-attachment pricing power.
Pricing Analysis
Input-cost pass-through from Chinese tungsten sourcing volatility is reshaping equipment pricing structures across microfocus X-ray tube tiers. Three-tier pricing structure across premium, standard, and economy levels separates ZEISS research-grade installations from Waygate Technologies gigafactory lines and domestic Chinese turnkey stations. Cost compression in standard-tier systems is intensifying because SAMR-mandated defect detection capabilities require identical imaging hardware regardless of vendor origin. Battery manufacturers in South Korea exhibit lowest price sensitivity due to outcome-based contracting with guaranteed defect escape rates.
Supply Chain Analysis
Regional distribution centers in Shanghai, Stuttgart, and Detroit anchor hub-and-spoke patterns for CT system spare parts and tube replacement inventory. Manufacturing concentrates in Germany, Japan, and China. Microfocus X-ray tube anodes draw from tungsten feedstock, high-voltage power electronics, and precision motion stages. Single-source vulnerability in Chinese tungsten mining operations exposes equipment lead times to export restriction risk. Distribution runs through authorized service depots co-located with automotive cluster geographies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds on regulatory milestones, with UN 38.3 transport testing protocol updates mandating volumetric defect documentation ahead of every export certification cycle.
For Market Incumbents: To counter domestic Chinese equipment vendors engineering pre-validated GB compliance into turnkey stations, ZEISS and Nikon should deepen backward integration into microfocus tube production and establish captive calibration centers in Busan-Ulsan corridors. Certification investment in SAMR-recognized validation protocols represents the critical defensive lever. For New Entrants and Emerging Players: Inspection service providers unbundled from equipment purchases offer the most penetrable channel, particularly for automotive OEMs in Michigan and California seeking subscription-based defect escape rate guarantees. Second-life battery grading facilities in India present white-space demand for rapid internal state assessment distinct from manufacturing quality control. A go-to-market angle anchored to PLI scheme subsidy timelines in Indian cell manufacturing clusters accelerates initial contract velocity. For Investors and Strategic Acquirers: Asymmetric upside sits with AI-assisted defect recognition software specialists possessing training datasets from cylindrical cell geometries. Long-term viability in this market hinges on algorithmic differentiation rather than hardware fabrication scale. Acquisition targets should demonstrate deployed machine learning classification for separator fold detection with proven false-positive rates. The inflection signal to watch is automotive OEM willingness to outsource entire quality stations under performance guarantees rather than capital equipment purchases.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assisted Defect Recognition Partnership | Machine learning convergence with volumetric imaging collapses latency between acquisition and automated classification at Japanese prismatic cell lines. |
| Outcome-Based Pricing Model Deployment | Subscription revenue tied to defect escape rates shifts capital burden from South Korean battery producers to inspection specialists. |
| Domestic Turnkey Compliance Station Engineering | Pre-validated SAMR documentation bundled with CT hardware compresses foreign vendor access in Shenzhen-Ningbo procurement. |
| Phase-Contrast CT Production Transfer | Laboratory-validated grating protocols moving to industrial equipment enable solid-state ceramic electrolyte characterization at German automotive clusters. |
| Second-Life Battery Grading Service Launch | End-of-life electric vehicle battery repurposing opens inspection demand distinct from manufacturing quality control in Indian PLI corridors. |
Research Methodology
Bottom-up gigafactory capacity modeling reconciled against top-down CT equipment shipment tracking forms the analytical core of this study. Primary interviews with quality engineering directors at cylindrical cell producers, metrology procurement leads at German automotive OEMs, and service operations managers at inspection specialists combined with secondary validation from SAMR GB standard filings, UN 38.3 transport certification databases, and SEC equipment vendor disclosures. Triangulation across these sources anchored volume estimates.
Historical trendline analysis of electrode alignment defect detection adoption rates informed projection frameworks across the analysis window. Segmentation dimensions modeled include technology type, service delivery model, end-user procurement authority, and application regulatory intensity. CAGRs derived from equipment shipment trajectories weighted by cathode chemistry transition timelines and solid-state cell commercialization curves. Phase-contrast CT pilot installations at Bavarian research consortia provided technology diffusion benchmarks.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to tungsten supply restriction events and divergent solid-state cell certification requirements across Chinese GB, EU Battery Regulation, and US FDA frameworks. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Global Video Extensometer Market
Test and Measurement
Shock Test Machines Market
Test and Measurement
Tensile Testing Machine Market
Test and Measurement
Laser Interferometer Market
Test and Measurement
Circuit Tracer Market
Test and Measurement
Edge Computing Enclosure Environmental Stress Test Equipment Market
Test and Measurement
Height Measurement Devices Market
Test and Measurement
Chiplet Integration and Die-to-Die Interconnect Test Solutions Market
Test and Measurement
Failure Analysis Equipment Market
Test and Measurement
Scratch Testers Market
Test and Measurement
Capacitance Meter Market
Test and Measurement
Global Inspection Machines Market
Test and Measurement
State Transition Testing Market
Test and Measurement
Test Benches Market
Test and Measurement
Rohs Tester Market
Test and Measurement
Advanced Probe Card and Wafer Probing Test Systems Market