
 Fluorometers Market | 2026-2036
Fluorometers Market Size, Share, and Industry Trends Forecast 2026-2036
Fluorometers Market Analysis
Pharmaceutical companies are gaining procurement share as academic institutions retrench capital budgets, and the fluorometer demand base is bifurcating between high-volume drug discovery buyers and fragmented research laboratory purchasers. Thermo Fisher Scientific leverages its Life Sciences Solutions segment to dominate North American pharmaceutical accounts with integrated fluorescence detection platforms. Horiba sustains technology leadership in laser-based architectures through its Kyoto-centered spectroscopy R&D operations. Danaher Corporation anchors clinical diagnostics deployment via its Beckman Coulter fluorescence workflow instruments in hospital and reference laboratory channels.
Fluorometers are optical instruments that measure fluorescence intensity by exciting sample molecules with a defined wavelength of light and quantifying emitted photons at longer wavelengths, typically operating with detection limits in the picomolar range for DNA, protein, and small-molecule assays. Bench-top fluorometers occupy the largest installed base due to their thermal stability and multi-mode flexibility, while portable and handheld formats represent the fastest-growing configuration as environmental agencies and field biologists demand ruggedized, battery-powered units for on-site water quality and contaminant screening. LED-based technology leads unit shipments for cost-sensitive academic and environmental segments, whereas laser-based systems command premium positioning in pharmaceutical quality control and genomics applications where excitation specificity determines assay validity.
FDA 21 CFR Part 11 electronic records requirements shape instrument software architecture and validation documentation for US clinical and pharmaceutical end users, while REACH and RoHS frameworks in Europe restrict hazardous substance content in optical components and electronics, compelling redesigns of lamp housings and detector assemblies. ISO 17025 accreditation standards drive calibration and traceability investments across third-party testing laboratories that operate fluorescence-based analytical services. Stakeholders must monitor evolving EPA method compliance for dissolved organic carbon and chlorophyll fluorescence measurements, as regulatory method updates directly determine replacement cycles and feature specifications for environmental monitoring procurement.
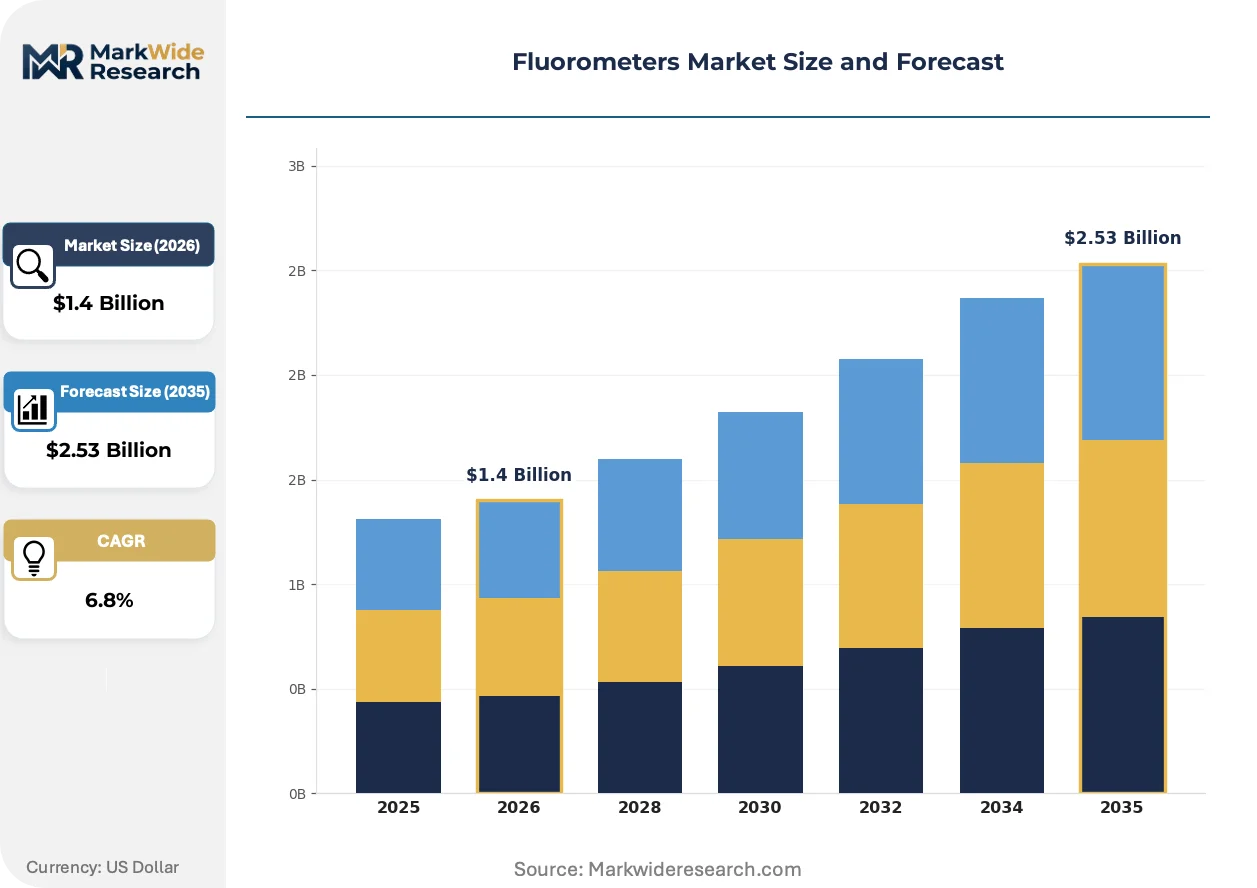
Market Dynamics
Pharmaceutical procurement concentration is restructuring fluorometer demand, with high-throughput screening workflows displacing fragmented academic purchasing and forcing vendors to reconfigure service models around validated, GMP-compliant instrument platforms.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records mandates in the United States are accelerating replacement cycles among pharmaceutical quality control laboratories seeking compliant fluorescence detection systems.
- LED miniaturization:Solid-state excitation sources are expanding environmental field deployment by enabling battery-operated, handheld units for water quality monitoring.
- German research clusters:Dense academic-industrial concentration around Munich and Heidelberg sustains bench-top and multi-channel system procurement despite broader European budget constraints.
Market Restraints
- Xenon lamp supply volatility:Optical component sourcing from concentrated Asian manufacturing hubs creates lead time uncertainty for lamp-based fluorometer producers.
- Laser cost structure:Gas and solid-state laser architectures impose capital barriers that constrain adoption outside premium pharmaceutical and genomics segments.
- REACH substance restrictions:ECHA frameworks limiting mercury and cadmium in optical housings force redesign investments that compress margins on entry-level instruments.
Strategic Opportunities
- India environmental monitoring:Central Pollution Control Board mandates for dissolved organic carbon measurement are opening procurement channels for portable fluorescence systems.
- CRSD-aligned carbon accounting:European sustainability disclosure rules are creating demand for fluorometer-based bioprocess monitoring in biofuel and synthetic biology applications.
- AI-integrated spectral analysis:Machine learning deconvolution algorithms are converging with bench-top hardware to enable multiplexed assay panels previously requiring laboratory information management systems.
Industry Challenges
- ISO 17025 metrology expertise:Accredited calibration capabilities for picomolar-range traceability remain scarce, creating bottlenecks for third-party testing laboratory expansion.
- Legacy LIMS integration:Hospital and reference laboratory fluorescence workflows require costly middleware development to connect new instruments with entrenched data management infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluorometers Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bench-top Fluorometers, Portable Fluorometers, Handheld Fluorometers, Multi-channel Fluorometers End User: Academic Institutions, Research Laboratories, Environmental Agencies, Pharmaceutical Companies Technology: LED-based Fluorometers, Laser-based Fluorometers, Fiber Optic Fluorometers, Modular Fluorometers Application: Clinical Diagnostics, Environmental Monitoring, Food Safety Testing, Industrial Applications |
| Companies Covered | Thermo Fisher Scientific, Horiba, Agilent Technologies, PerkinElmer, Danaher Corporation, Bio-Rad Laboratories, Xylem Inc., Berthold Technologies, Promega Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluorometers Market Emerging Trajectories
Fluorometer architecture is bifurcating between pharmaceutical-grade laser specificity and environmental LED portability, with software validation and field ruggedization emerging as parallel innovation vectors reshaping competitive requirements.
Time-resolved fluorescence detection is displacing steady-state intensity measurements in high-value pharmaceutical applications. Drug discovery groups at contract research organizations are adopting lanthanide chelate and semiconductor quantum dot assays that exploit microsecond-scale emission lifetimes. This displacement is compressing demand for traditional filter-based bench-top units in quality control settings while expanding service contract attach rates for technical support.
REACH Annex XVII amendments restricting per- and polyfluoroalkyl substances are compelling optical coating reformulations. Fluorometer manufacturers sourcing interference filters and lens assemblies from European suppliers must validate alternative thin-film deposition chemistries. German and French environmental monitoring agencies are accelerating procurement timelines to secure compliant instruments ahead of enforcement phase-ins.
Consolidated purchasing through group procurement organizations is replacing individual laboratory buying authority in North American hospital systems. Integrated delivery networks are negotiating enterprise fluorescence platform contracts that bundle reagents, service, and data analytics. This concentration is most visible in Texas and California health systems where reference laboratory consolidation has reduced vendor count per metropolitan area.
Fluorometers Market Segmentation
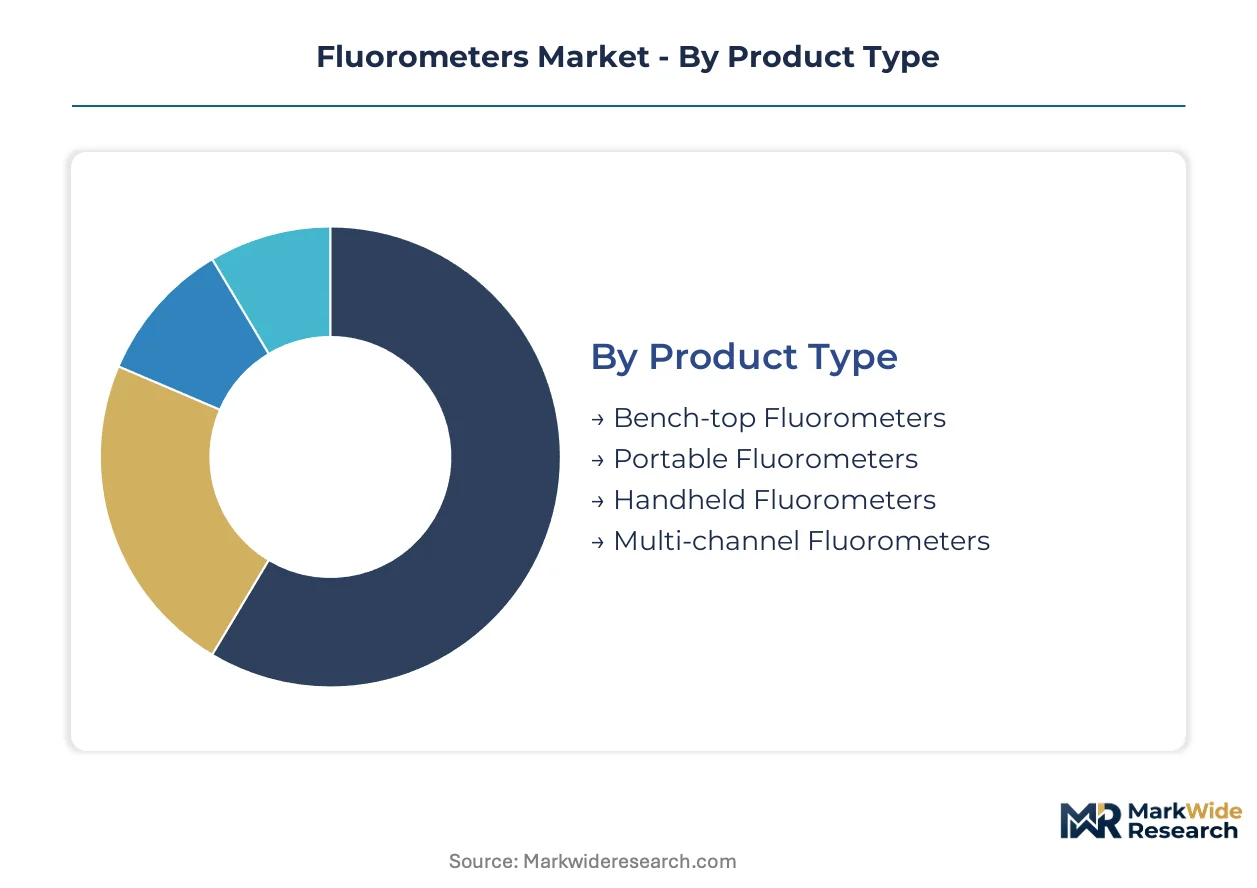
Fluorometer procurement channels diverge sharply between validated pharmaceutical workflows and fragmented academic purchasing, with product configuration and technology choices directly determining margin structure and service attach rates across end-use verticals.
Product Type:
Channel mix varies by portability tier, with bench-top units flowing through distributor networks to institutional accounts while portable formats bypass traditional channels via direct environmental agency contracts.
- Bench-top Fluorometers:Thermal-stabilized optical benches with multi-mode detection capabilities serve pharmaceutical quality control and German academic clusters around Munich and Heidelberg. Procurement concentrates through group purchasing organizations in consolidated hospital systems, with FDA 21 CFR Part 11 validation requirements driving replacement cycles.
- Portable Fluorometers:Battery-powered units with ruggedized housings enable Central Pollution Control Board-mandated dissolved organic carbon screening across Indian watershed monitoring programs. Environmental agencies in France and Germany are accelerating procurement ahead of REACH Annex XVII enforcement phase-ins for optical coating compliance.
- Handheld Fluorometers:Single-parameter field units with simplified interfaces target water quality technicians requiring chlorophyll fluorescence measurements without laboratory infrastructure.
- Multi-channel Fluorometers:Parallel detection architectures support high-throughput screening workflows at contract research organizations, with service contracts representing critical margin contribution.
By volume, bench-top fluorometers lead. By growth pace, portable fluorometers are climbing the fastest.
End User:
Customer concentration reshapes vendor economics, with pharmaceutical procurement displacing academic fragmentation and forcing platform consolidation around GMP-compliant instrument lines.
- Academic Institutions:Capital budget retrenchment across European universities is compressing unit volumes while extending replacement cycles for existing bench-top installations.
- Research Laboratories:Fragmented purchasing authority persists in biotechnology startups and independent testing facilities, sustaining distributor margins on entry-level LED systems.
- Environmental Agencies:EPA method compliance requirements for dissolved organic carbon and chlorophyll measurements determine feature specifications and replacement timing for field-deployable units.
- Pharmaceutical Companies:Integrated fluorescence detection platforms with validated software architectures command premium positioning, with electronic records mandates accelerating quality control laboratory upgrades.
Pharmaceutical companies now dominate value capture. Environmental agencies are expanding most quickly as regulatory monitoring mandates proliferate.
Technology:
Excitation source selection determines application tier, with LED architectures serving cost-sensitive volumes and laser systems anchoring premium pharmaceutical segments.
- LED-based Fluorometers:Solid-state excitation with broad spectral output dominates academic and environmental procurement, with miniaturization enabling handheld form factors for field biologists.
- Laser-based Fluorometers:Gas and solid-state architectures with narrow linewidth excitation support genomics quality control and time-resolved fluorescence detection at contract research organizations.
- Fiber Optic Fluorometers:Remote sensing configurations with probe-based sampling enable in-line bioprocess monitoring for biofuel and synthetic biology applications under CSRD-aligned carbon accounting frameworks.
- Modular Fluorometers:Component-swappable platforms allow research laboratories to reconfigure detection channels without full instrument replacement, extending effective service life.
LED-based systems lead by installed base. Laser-based fluorometers command the steepest expansion trajectory in pharmaceutical quality control.
Application:
Use case specificity dictates validation burden and software architecture, with clinical and pharmaceutical applications requiring FDA-compliant electronic records while environmental monitoring prioritizes field ruggedization.
- Clinical Diagnostics:Fluorescence-based immunoassays and nucleic acid detection in hospital and reference laboratories require middleware integration with entrenched LIMS infrastructure.
- Environmental Monitoring:Dissolved organic carbon and chlorophyll fluorescence measurements drive portable unit procurement through EPA method compliance and European Water Framework Directive implementation.
- Food Safety Testing:Mycotoxin and pathogen detection applications sustain demand for bench-top systems with multi-mode flexibility in third-party testing laboratories.
- Industrial Applications:Process analytical technology deployments in pharmaceutical manufacturing and biotechnology production require in-line fluorescence monitoring with ISO 17025 traceability.
Clinical diagnostics holds the largest revenue pool. Environmental monitoring is gaining share fastest as regulatory monitoring networks expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's distribution dominance for analytical instrumentation across Northern Europe. German research clusters around Munich and Heidelberg sustain bench-top fluorometer procurement despite broader European budget constraints.
United States
Pharmaceutical quality control laboratories in Massachusetts and New Jersey drive replacement cycles for FDA 21 CFR Part 11 compliant fluorescence detection systems. EPA method compliance for dissolved organic carbon measurements determines procurement specifications for environmental monitoring agencies. The Boston-Cambridge biotech corridor anchors high-throughput screening demand at contract research organizations.
Germany
REACH Annex XVII amendments restricting per- and polyfluoroalkyl substances are compelling optical coating reformulations for fluorometer manufacturers. ECHA frameworks limiting mercury and cadmium in optical housings force redesign investments across Baden-Württemberg instrument fabricators. The Munich-Heidelberg academic-industrial concentration sustains multi-channel system deployment despite European university capital budget retrenchment.
India
Central Pollution Control Board mandates for dissolved organic carbon measurement are opening procurement channels for portable fluorescence systems. The country's national environmental regulator is accelerating watershed monitoring program deployments across Maharashtra and Karnataka. Field biologists in the Western Ghats region are adopting battery-powered handheld units for on-site water quality screening.
China
Dual carbon goals under the national climate framework are creating demand for fluorometer-based bioprocess monitoring in biofuel applications. The Ministry of Ecology and Environment is tightening enforcement of dissolved organic carbon measurement standards for surface water quality. Yangtze River Delta research institutes are expanding laser-based fluorescence detection procurement for genomics quality control.
France
ANSM and CNIL oversight of clinical diagnostics is shaping software validation requirements for hospital laboratory fluorescence workflows. CSRD-aligned sustainability disclosure rules are expanding procurement for bioprocess monitoring instrumentation. The Paris-Saclay research cluster sustains academic demand for modular fluorometer platforms despite national research funding pressures.
Fluorometers Market Vendor Landscape
Listed leaders compete with private specialists across validated pharmaceutical workflows and fragmented academic purchasing channels. Thermo Fisher Scientific and Danaher Corporation anchor the publicly traded tier with integrated life sciences platforms, while Horiba and Berthold Technologies occupy family-owned or privately held positions in spectroscopy specialization. Three archetypes dominate: diversified conglomerates with fluorescence detection as one segment, pure-play analytical instrumentation specialists, and reagent-integrated platform providers. Consolidation through acquisition of niche fluorescence technology developers and backward integration into optical component supply represent the dominant competitive vectors reshaping vendor economics.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Danaher Corporation exemplify scale-driven platform strategies that bundle instruments, reagents, and service contracts. Horiba represents the specialized spectroscopy archetype with concentrated R&D operations in Kyoto. Among reagent-integrated providers, Promega Corporation occupies a position linking fluorescence detection hardware with assay chemistry workflows. These three company groupings illustrate how competitive positioning diverges between pharmaceutical-grade validation requirements and cost-sensitive environmental field deployment.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Horiba |
| Agilent Technologies |
| PerkinElmer |
| Danaher Corporation |
| Bio-Rad Laboratories |
| Xylem Inc. |
| Berthold Technologies |
| Promega Corporation |
| Others |
Supply Flow & Price Mechanics
FDA 21 CFR Part 11 validation requirements simultaneously gate supplier qualification and stratify price tiers, compelling pharmaceutical buyers to absorb certification premiums while environmental segments exploit LED commoditization to compress hardware margins.
Pricing Analysis
Volume-discount tiering separates pharmaceutical procurement through multi-year service bundles from academic spot purchasing of bench-top units. Three-tier pricing structure across premium, standard, and economy levels reflects excitation source specificity, with laser-based systems commanding validation premiums and LED architectures competing on capital efficiency. Cost compression in environmental handhelds is intensifying because battery miniaturization and solid-state component commoditization erode differentiation. Academic laboratories exhibit highest price sensitivity, while pharmaceutical quality control operations prioritize compliance over unit economics.
Supply Chain Analysis
Inventory lead times for xenon lamp assemblies have extended unpredictably as optical component sourcing concentrates in China, Japan, and South Korea. German and Swiss precision optics suppliers anchor high-end interference filter production, while detector electronics draw from Taiwanese semiconductor foundries. Single-source vulnerability in mercury-free lamp housings intensifies as REACH Annex XVII enforcement compels redesign cycles. Distribution runs through specialized analytical instrumentation distributors to institutional accounts, with direct contracting emerging for environmental agency procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service contract attach rates are expanding faster than hardware shipments as pharmaceutical buyers demand validated calibration and technical support over instrument replacement cycles.
For Market Incumbents: Secure ISO 17025-accredited metrology capabilities before third-party laboratory expansion bottlenecks escalate, and deepen backward integration into optical coating supply to preempt REACH-driven component shortages. Laser architecture specialists face displacement risk from time-resolved fluorescence detection adoption at contract research organizations. For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for fluorescence-based clinical diagnostics instruments offer regulatory arbitrage against entrenched pharmaceutical platform vendors. Portable environmental monitoring in India and fiber-optic bioprocess configurations for European biofuel applications represent the most penetrable white spaces. Direct agency contracting bypasses distributor margin capture. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life sciences conglomerates seeking to divest non-core spectroscopy units with pharmaceutical service contract backlogs. Long-term viability hinges on software validation architecture rather than hardware differentiation. Watch for EPA method updates as inflection indicators triggering replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Certification Fast-Track | FDA 21 CFR Part 11 validation accelerates pharmaceutical procurement decisions and locks out uncertified competitors. |
| Backward Integration into Optical Components | In-house production of REACH-compliant interference filters insulates margins from ECHA-driven supplier disruption. |
| Service Contract Bundling | Multi-year technical support agreements with pharmaceutical quality control laboratories generate recurring revenue exceeding hardware margins. |
| Geographic Expansion into Environmental Agency Channels | Direct contracting with India's Central Pollution Control Board bypasses distributor overhead and captures portable system demand. |
| AI-Integrated Spectral Analysis Development | Machine learning deconvolution algorithms enable multiplexed assay panels previously requiring laboratory information management systems. |
Methodological Framework
The analysis maps bench-top, portable, handheld, and multi-channel fluorometer configurations, each validated through instrument procurement managers at pharmaceutical quality control laboratories, environmental agency field operations directors, academic research facility administrators, and third-party testing laboratory technical directors. Primary interview insights combined with secondary validation from FDA 510(k) filings, EPA method compliance documentation, ECHA REACH substance restriction updates, and ISO 17025 accreditation registries. Bottom-up unit shipment estimates triangulated against top-down fluorescence detection platform revenue disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. Segmentation dimensions modeled include product portability tier, excitation source technology, end-user vertical, and application specificity. CAGRs derived from replacement cycle analysis, regulatory mandate timing, and technology diffusion patterns. Forecast inputs incorporated pharmaceutical high-throughput screening expansion rates and environmental monitoring network deployment schedules.
Decision-makers should treat outputs as directional under assumptions of sustained REACH enforcement and stable xenon lamp supply; material deviation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Transformer Testing Equipment Market
Test and Measurement
Digital Weighing Terminal Market
Test and Measurement
Shape Measuring Devices Market
Test and Measurement
Smart Contact Lens Optical and Telemetry Test Equipment Market
Test and Measurement
Fogging Tester Market
Test and Measurement
Active Dosimeter Market
Test and Measurement
Circuit Tracer Market
Test and Measurement
5G Testing Devices Market
Test and Measurement
Data Acquisition Equipment Market
Test and Measurement
Permeability Testing Machine Market
Test and Measurement
Gloss Meters Market
Test and Measurement
Network Tester Market
Test and Measurement
Volte Testing Market
Test and Measurement
Mud Test Equipment Market
Test and Measurement
Semiconductor Metrology and Inspection Market
Test and Measurement
In-Circuit Test Market