
 Glycoprotein Market | 2026-2036
Glycoprotein Market Size, Share, and Industry Trends Forecast 2026-2036
Glycoprotein Market Foresight
ISO 17025 accreditation is rotating as the critical qualification gate for analytical service providers entering the glycoprotein characterization space. Thermo Fisher Scientific leverages its mass spectrometry portfolio to dominate high-resolution glycan profiling workflows. Roche sustains competitive positioning through integrated diagnostics-to-therapeutics capabilities in glycoprotein biomarker applications. Agilent Technologies anchors its presence in capillary electrophoresis systems that pharmaceutical quality control labs specify for glycan heterogeneity analysis.
Glycoproteins are proteins bearing covalently attached carbohydrate chains, typically synthesized through mammalian cell culture expression systems requiring precise control of pH, temperature, and nutrient feed to achieve target glycoforms for therapeutic efficacy. Monoclonal antibodies occupy the largest value pool given their established manufacturing infrastructure and regulatory familiarity, while recombinant proteins represent the fastest-expanding category as biosimilar developers seek glycoengineered alternatives to originator molecules. Therapeutic applications command premium pricing due to batch release testing burdens, whereas diagnostic tests compete on throughput scale with compressed margin structures.
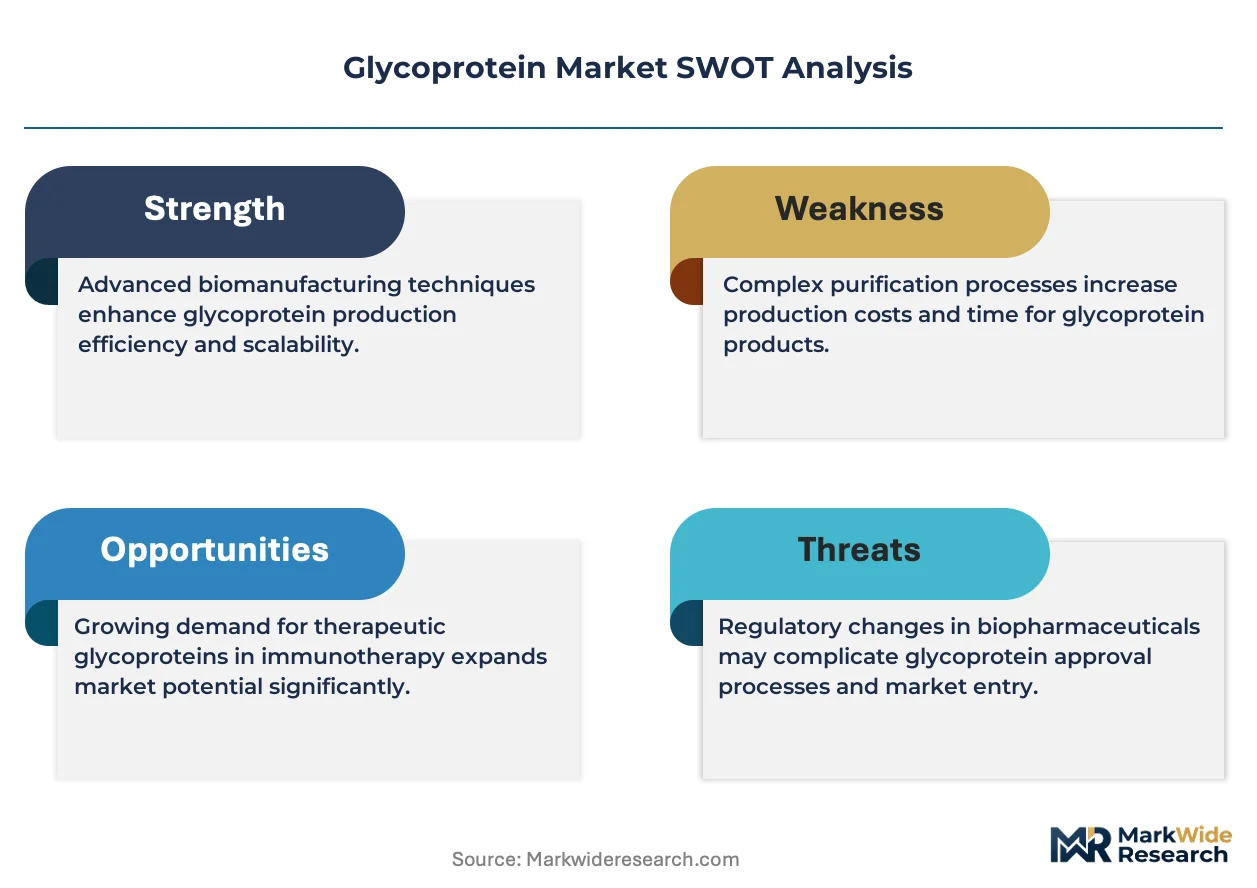
FDA, EMA, and WHO collectively enforce tightening glycan characterization standards that determine market access for biosimilar developers and contract manufacturers. The FDA's updated guidance on analytical similarity for glycosylated products demands orthogonal methods including mass spectrometry and liquid chromatography, elevating capital requirements for laboratory infrastructure. Stakeholders must monitor evolving pharmacopeial monographs and invest in multi-attribute method platforms before regulatory deadlines harden into compliance barriers.
Market Dynamics
FDA and EMA tightening of glycan comparability standards is forcing biopharmaceutical manufacturers to rebuild analytical workflows around orthogonal mass spectrometry and liquid chromatography methods, compressing timelines for biosimilar entrants.
Growth Catalysts
- WHO Prequalification Pathway:Accelerated market access for glycoprotein vaccines in low-income countries drives contract manufacturing organization expansion into multi-product biologics facilities.
- Glycoengineered Yeast Platforms:Humanized glycosylation pathways in Pichia pastoris reduce mammalian cell culture dependency and shorten development timelines for recombinant protein candidates.
- Japan's Regenerative Medicine Framework:PMDA streamlined review for glycoprotein-based cell therapies attracts foreign sponsors to Tokyo-Osaka manufacturing clusters.
Market Restraints
- Heparin Supply Concentration:Porcine intestinal mucosa sourcing from China creates raw material vulnerability for anticoagulant glycoprotein production.
- Glycan Microheterogeneity Control:Batch-to-batch consistency in mammalian expression systems requires expensive process analytical technology investments that mid-tier developers cannot absorb.
- EMA Biosimilar Immunogenicity Requirements:Extended clinical glycan characterization studies delay European market entry by 18-24 months versus FDA pathways.
Strategic Opportunities
- Site-Specific Conjugation:Chemoenzymatic glycan remodeling enables antibody-drug conjugate developers to achieve homogeneous drug-to-antibody ratios previously unattainable through random lysine or cysteine chemistry.
- India CDMO Expansion:CDSCO manufacturing license reforms and PLI scheme biotechnology incentives position Bangalore-Hyderabad corridors for glycoprotein contract production.
- Continuous Bioprocessing:Perfusion cell culture integration with real-time glycan monitoring collapses facility footprint requirements for emerging biotech entrants.
Industry Challenges
- Glycobiology Talent Scarcity:Mass spectrometry glycan interpretation expertise concentrates in Boston, Basel, and Singapore, creating recruitment bottlenecks for secondary hubs.
- Multi-Attribute Method Validation:Simultaneous glycan, charge variant, and size exclusion analysis demands cross-functional analytical development teams that most quality control organizations lack.
- Reference Standard Procurement:WHO International Standards for glycoprotein therapeutics face allocation delays that stall biosimilar analytical similarity exercises.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glycoprotein Market |
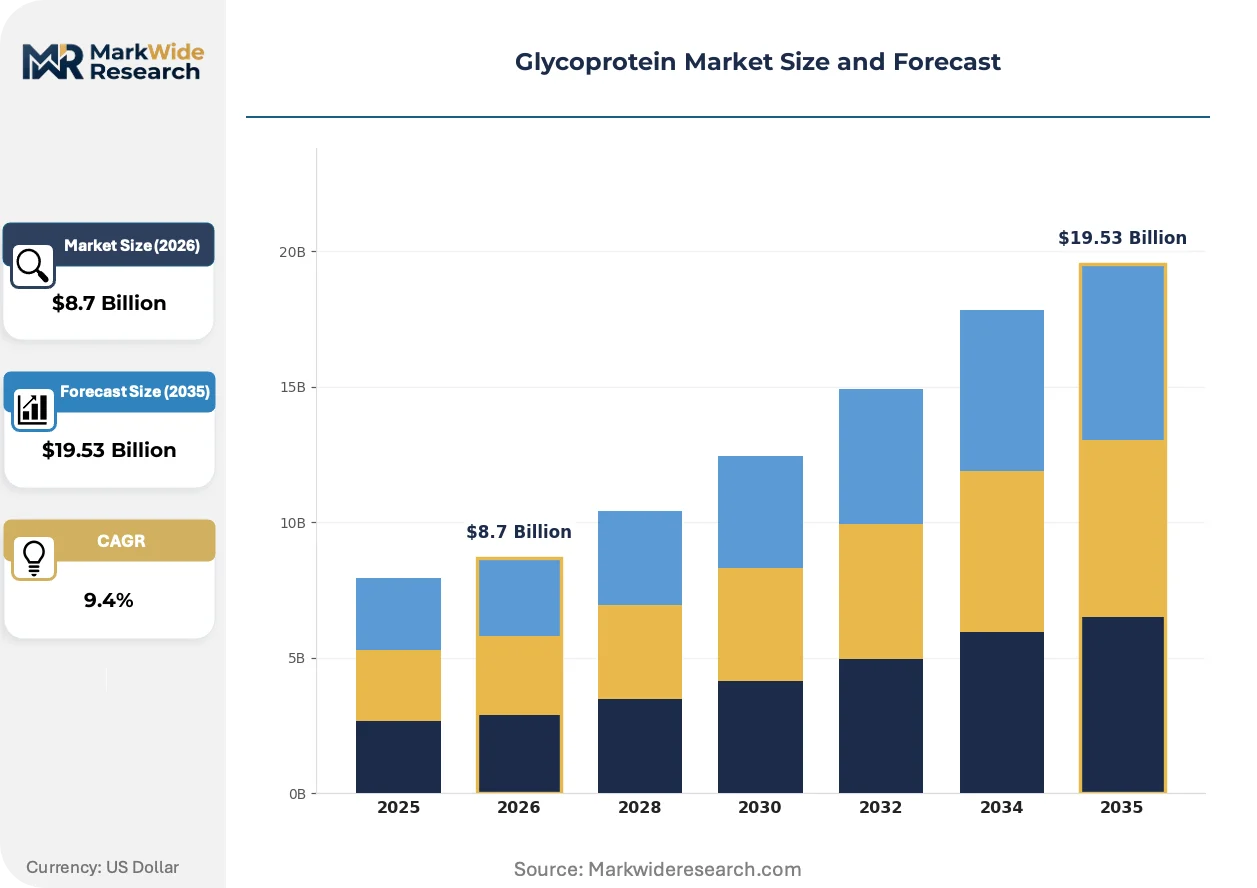
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Recombinant Proteins, Glycosylated Peptides, Conjugated Vaccines Application: Therapeutic Applications, Diagnostic Tests, Biopharmaceutical Development, Research Studies End User: Pharmaceutical Companies, Academic Institutions, Biotechnology Firms, Contract Research Organizations Delivery Mode: Injectable Solutions, Lyophilized Formulations, Oral Formulations, Intravenous Solutions |
| Companies Covered | Thermo Fisher Scientific, Roche, Agilent Technologies, Waters Corporation, Danaher Corporation, Merck KGaA, Bio-Rad Laboratories, Takara Bio, Bruker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glycoprotein Market Shifts & Advancements
Mass spectrometry instrumentation is fragmenting into specialized glycoproteomics configurations, while regulatory convergence around ICH Q5E comparability guidelines compresses regional analytical divergence. These forces reshape capital allocation and partnership structures.
High-resolution native mass spectrometry is bifurcating glycoprotein characterization into intact-mass screening workflows versus site-specific glycopeptide mapping protocols. Large-cap biopharmaceutical developers deploy both in parallel for regulatory submissions, whereas emerging biotechs prioritize intact-mass methods to conserve capital. This technology split is compressing the addressable market for mid-tier analytical service providers lacking either capability depth.
EMA's updated Guideline on Similarity for Glycosylated Proteins mandates orthogonal glycan release methods for biosimilar applications, elevating capital requirements for European contract testing laboratories. The industrial consequence is consolidation among analytical service providers as ISO 17025 accreditation becomes a non-negotiable procurement filter. Biosimilar developers targeting Germany and France now pre-qualify laboratories 18 months ahead of planned submission dates to secure capacity.
Biopharmaceutical procurement teams now unbundle glycan characterization from comprehensive CMC packages, awarding discrete method development and validation contracts to specialized analytical shops. This disintermediation of full-service CDMO relationships fragments vendor concentration in the United States, where Boston and San Francisco biotech clusters actively cultivate multi-vendor analytical strategies. The shift is most visible among Series B-stage companies optimizing burn rates through competitive bidding for release testing.
Glycoprotein Market Segmentation
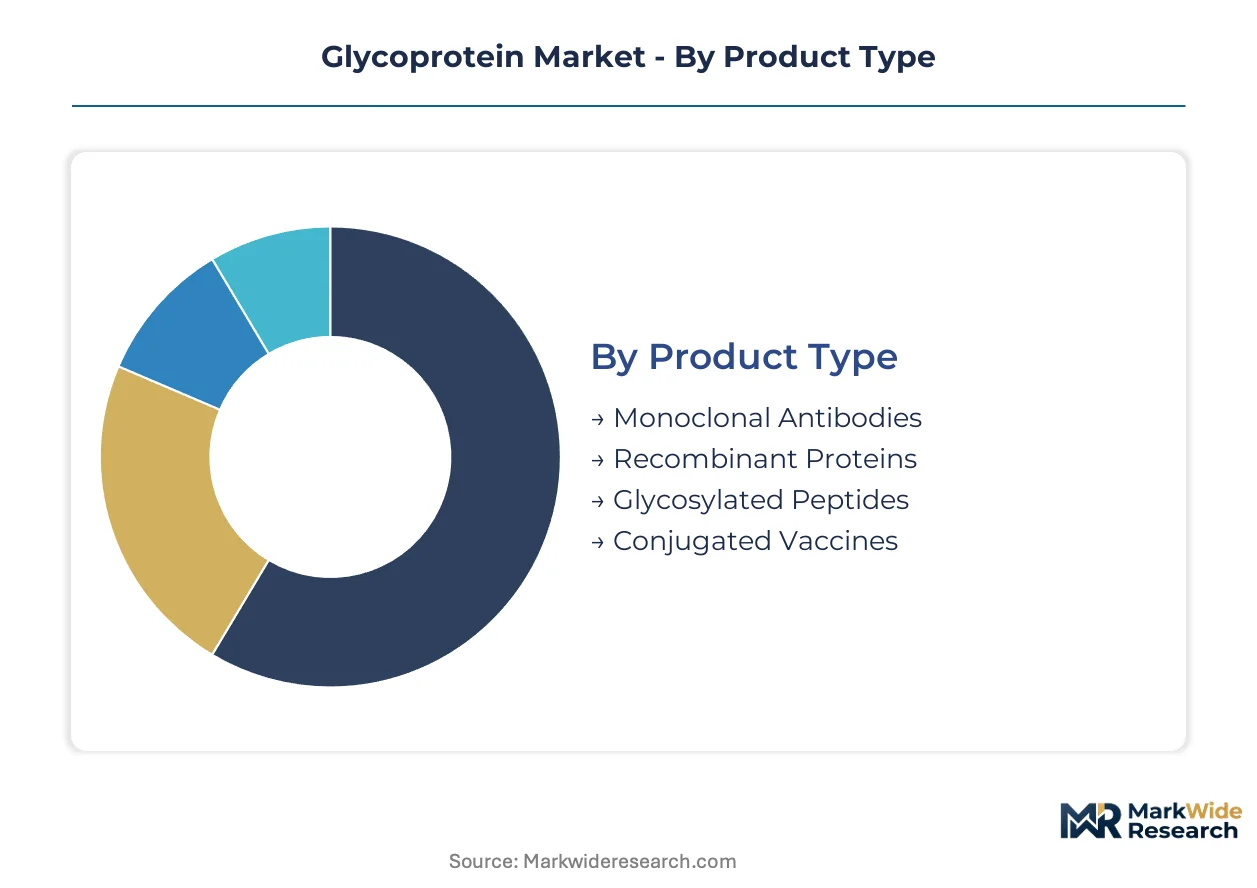
Glycoprotein market segmentation reveals divergent margin structures and regulatory burdens across product categories. Channel strategy varies sharply between high-touch therapeutic applications and high-throughput diagnostic workflows.
Product Type:
Monoclonal antibodies flow through established biopharmaceutical distribution networks requiring cold chain validation, while recombinant proteins increasingly route through specialized CDMO partnerships for glycoengineering customization.
- Monoclonal Antibodies:These therapeutics carry complex N-linked glycan structures that determine antibody-dependent cellular cytotoxicity and complement-dependent cytotoxicity. Manufacturing concentrates in the United States, Germany, and Japan where FDA, EMA, and PMDA enforce stringent glycan comparability standards for biosimilar substitution. Originators defend position through proprietary cell line glycoengineering.
- Recombinant Proteins:Engineered glycosylation profiles in erythropoietin, interferon, and blood factors enable improved half-life and reduced immunogenicity. Expansion concentrates in Bangalore-Hyderabad CDMO corridors where CDSCO manufacturing license reforms attract foreign sponsors seeking cost-advantaged glycoprotein production.
- Glycosylated Peptides:Short-chain therapeutics with site-specific glycan attachments for metabolic stability. Academic spinouts in Boston and Basel dominate early-stage development.
- Conjugated Vaccines:Polysaccharide-protein conjugates requiring precise glycan density for T-cell dependent immunity. WHO prequalification drives procurement in low-income country immunization programs.
Monoclonal antibodies dominate installed base. Recombinant proteins is where expansion concentrates.
Application:
Cost tier separation between premium-priced therapeutics and compressed-margin diagnostics shapes R&D allocation and partnership structures.
- Therapeutic Applications:Oncology, autoimmune, and hematology indications command premium pricing contingent on exhaustive batch release testing for glycan microheterogeneity. FDA and EMA biosimilar guidance demands orthogonal analytical methods that elevate capital requirements for market entry.
- Diagnostic Tests:Glycoprotein biomarkers for cancer screening and infectious disease detection compete on throughput scale with narrow margin structures. Agilent Technologies capillary electrophoresis systems anchor quality control workflows in high-volume reference laboratories.
- Biopharmaceutical Development:Cell line selection and glycoengineering optimization for lead candidate nomination. Thermo Fisher Scientific mass spectrometry platforms dominate analytical service provider procurement.
- Research Studies:Academic and government-funded investigations into glycobiology mechanisms and disease associations. Funding concentration in NIH and EU Horizon Europe programs.
Therapeutic applications capture value pool depth. Diagnostic tests is where volume scale concentrates.
End User:
Customer type determines procurement sophistication, with pharmaceutical companies demanding integrated CMC packages and academic institutions unbundling analytical services.
- Pharmaceutical Companies:Large-cap developers maintain captive glycan characterization capabilities while mid-tier firms outsource to ISO 17025-accredited analytical shops. Roche leverages integrated diagnostics-to-therapeutics positioning across biomarker and therapeutic portfolios.
- Biotechnology Firms:Series B-stage companies optimize burn rates through competitive bidding for discrete method development and validation contracts. Multi-vendor analytical strategies fragment vendor concentration in Boston and San Francisco clusters.
- Academic Institutions:University core facilities and principal investigator laboratories drive fundamental glycobiology research. Glycobiology talent scarcity concentrates recruitment competition in Boston, Basel, and Singapore.
- Contract Research Organizations:Specialized analytical service providers face consolidation pressure as EMA biosimilar immunogenicity requirements extend characterization timelines. Pre-qualification now occurs 18 months ahead of planned submission dates.
Pharmaceutical companies anchor procurement value. Biotechnology firms is where vendor fragmentation accelerates.
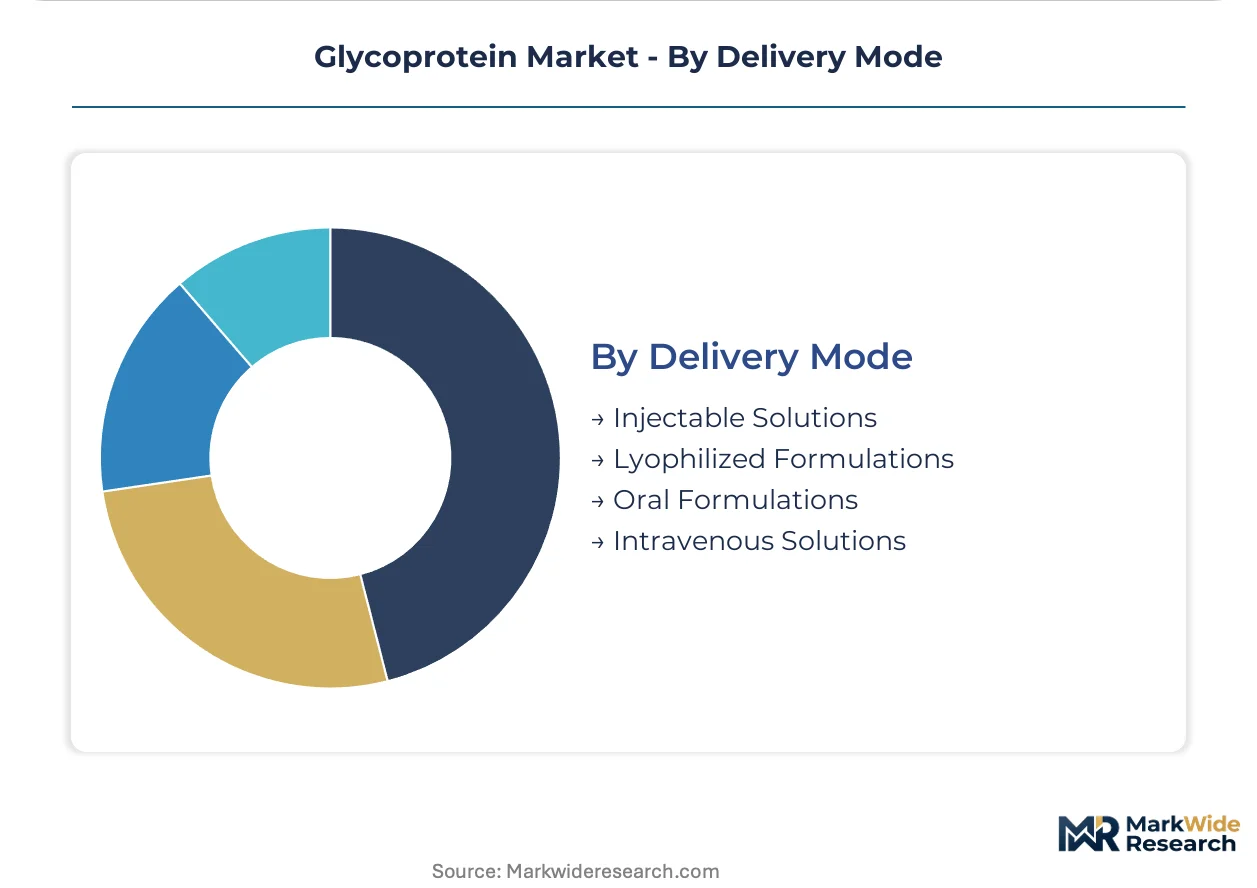
Delivery Mode:
Supply concentration in sterile injectable manufacturing creates capability bottlenecks, while oral formulation development targets patient compliance advantages.
- Injectable Solutions:Prefilled syringes and vials for monoclonal antibody administration require aseptic processing and cold chain distribution. Facility investments concentrate in United States and German manufacturing clusters with established FDA and EMA inspection histories.
- Lyophilized Formulations:Freeze-dried presentations extend shelf stability for temperature-sensitive glycoproteins. CDMO expansion in India targets this capability gap for export markets.
- Oral Formulations:Gastrointestinal stability challenges limit current applications to research-stage candidates. Tokyo-Osaka regenerative medicine clusters explore novel delivery technologies.
- Intravenous Solutions:Hospital-administered infusions for high-dose oncology and immunology indications. Infusion center networks in United States and Japan concentrate demand.
Injectable solutions dominate commercial infrastructure. Lyophilized formulations is where capacity expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biopharmaceutical manufacturing incentives and precision medicine infrastructure investments are concentrating glycoprotein production capacity in specific national clusters. Regulatory harmonization efforts across FDA, EMA, and PMDA jurisdictions are reshaping where developers locate analytical validation and commercial manufacturing operations.
United States
FDA biosimilar guidance tightening glycan comparability standards is elevating capital requirements for analytical infrastructure. The agency's updated analytical similarity protocols demand orthogonal mass spectrometry and liquid chromatography methods that compress timelines for market entrants. Greater Boston and San Francisco biotech clusters concentrate Series B-stage companies pursuing multi-vendor analytical strategies to optimize development burn rates.
Germany
EMA Guideline on Similarity for Glycosylated Proteins mandates orthogonal glycan release methods that extend biosimilar characterization timelines by 18-24 months versus FDA pathways. ISO 17025 accreditation has become a non-negotiable procurement filter for contract testing laboratories serving German sponsors. Frankfurt-Rhine-Main and Munich manufacturing corridors anchor European glycoprotein production capacity with established inspection histories.
Japan
PMDA streamlined review pathways for regenerative medicine products are attracting foreign sponsors to Tokyo-Osaka manufacturing clusters. The country's glycoprotein-based cell therapy framework offers accelerated market access contingent on glycan characterization rigor. Kanto and Kansai regions concentrate perfusion cell culture facilities with real-time glycan monitoring capabilities.
India
CDSCO manufacturing license reforms and PLI scheme biotechnology incentives are positioning Bangalore-Hyderabad corridors for glycoprotein contract production. The country's national pharmaceutical regulator has aligned with WHO prequalification standards for multi-product biologics facilities. CDMO expansion targets lyophilized formulation capabilities for temperature-sensitive glycoprotein export markets.
Switzerland
Swissmedic maintains stringent glycan characterization requirements that reinforce the country's precision medicine infrastructure advantages. Basel anchors integrated diagnostics-to-therapeutics capabilities with concentration in glycoprotein biomarker applications. The regulatory environment supports high-complexity biologics manufacturing for European and global distribution.
Glycoprotein Market Competitive Landscape
Player mix skews toward diversified analytical instrumentation conglomerates with orthogonal technology portfolios. Market structure concentrates around entities possessing integrated mass spectrometry, liquid chromatography, and capillary electrophoresis capabilities. Two strategic archetypes dominate: full-platform conglomerates offering end-to-end glycoprotein characterization workflows, and specialized analytical shops competing on ISO 17025-accredited method development velocity. Dominant competitive moves include strategic partnerships with biosimilar developers for pre-qualified analytical capacity, and technology licensing arrangements for glycoengineered yeast platform access.
Among diversified analytical instrumentation providers, Thermo Fisher Scientific, Roche, and Agilent Technologies occupy positions representing distinct competitive vectors. Thermo Fisher Scientific exemplifies the full-platform conglomerate archetype through mass spectrometry portfolio breadth. Roche sits within integrated diagnostics-to-therapeutics positioning across biomarker and therapeutic applications. Agilent Technologies represents capillary electrophoresis specialization that pharmaceutical quality control laboratories specify for glycan heterogeneity analysis.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Roche |
| Agilent Technologies |
| Waters Corporation |
| Danaher Corporation |
| Merck KGaA |
| Bio-Rad Laboratories |
| Takara Bio |
| Bruker Corporation |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation contracts with mammalian cell culture facilities lock in both supply access and price visibility for biosimilar developers navigating FDA and EMA glycan comparability deadlines. These arrangements tether pricing to raw material indexation while insulating sponsors from heparin supply volatility originating in Chinese porcine intestinal mucosa sourcing.
Pricing Analysis
Cost-plus contracts with raw material indexation dominate glycoprotein manufacturing agreements, particularly for mammalian cell culture media and chromatography resins. Three-tier pricing structure across premium, standard, and economy levels separates originator-grade glycoengineered products from biosimilar tiers and research-use materials. Pricing pressure stems from EMA immunogenicity study extensions that compress European margins versus FDA pathways. Mid-tier biotechnology firms exhibit highest price sensitivity, driving competitive bidding for discrete analytical validation contracts.
Supply Chain Analysis
Inbound logistics costs through Shanghai-Ningbo and Rotterdam-Antwerp corridors strain temperature-controlled biologics distribution, with container availability fluctuations disrupting cold chain integrity for lyophilized formulations. Manufacturing concentrates in United States, Germany, and India, with Bangalore-Hyderabad corridors drawing foreign sponsor investment through CDSCO reforms. Raw material dependencies span Chinese heparin precursors, German chromatography media, and Japanese perfusion bioreactor components. Single-source vulnerability in porcine-derived anticoagulant inputs creates structural risk. Distribution runs through pharmaceutical cold chain networks with validated thermal packaging.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across analytical service provision creates acquisition opportunities as ISO 17025 accreditation barriers consolidate vendor tiers. Unbundling of glycan characterization from full-service CDMO packages generates niche entry points for specialized method development shops.
For Market Incumbents: Fortify analytical infrastructure through captive mass spectrometry capacity additions in Boston and Basel corridors. Prioritize backward integration into glycoengineered yeast platform licensing to offset mammalian cell culture cost inflation. Defend against emerging biotech procurement teams fragmenting vendor relationships through competitive bidding. For New Entrants and Emerging Players: Lead with site-specific conjugation method development services targeting antibody-drug conjugate developers in San Francisco and Cambridge clusters. White-space opportunity concentrates in continuous bioprocessing real-time glycan monitoring for emerging biotechnology entrants. Penetrate through ISO 17025-accredited rapid validation offerings that compress pre-qualification timelines. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors analytical service providers with orthogonal capability depth across mass spectrometry and capillary electrophoresis. Long-term viability hinges on regulatory convergence around ICH Q5E comparability guidelines. Acquisition targets include mid-tier laboratories with pending ISO 17025 accreditation and established biosimilar sponsor relationships. Monitor WHO International Standards allocation delays as inflection signal for biosimilar analytical similarity bottlenecks.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 17025 Accreditation Investment | EMA tightening transforms accreditation into non-negotiable procurement filter for German sponsors. |
| Multi-Attribute Method Platform Deployment | Simultaneous glycan and charge variant analysis reduces quality control laboratory footprint requirements. |
| Glycoengineered Yeast Platform Licensing | Pichia pastoris humanized glycosylation pathways shorten recombinant protein development timelines. |
| Continuous Bioprocessing Integration | Perfusion cell culture with real-time monitoring collapses facility capital requirements for emerging entrants. |
| Pre-Qualified Analytical Capacity Reservation | Eighteen-month advance contracting secures release testing slots for EMA biosimilar submissions. |
Research Methodology
Initial hypotheses were tested against primary input from biopharmaceutical development executives, regulatory affairs leads, quality control laboratory directors, and contract manufacturing procurement managers and refined through secondary validation. FDA guidance documents, EMA scientific guidelines, WHO prequalification standards, and pharmacopeial monographs anchored regulatory trajectory assessments. Bottom-up modeling of analytical service provider capacity and top-down triangulation against biopharmaceutical R&D expenditure patterns ensured cross-verification.
Variance decomposition across product type, application, end user, and delivery mode dimensions structured the analytical framework throughout the forecast period. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion constraints. Modeled inputs included biosimilar pipeline progression through FDA and EMA review pathways, CDSCO manufacturing license reform implementation timelines, and glycoengineering technology adoption curves.
Underlying assumptions cover regulatory convergence around ICH Q5E comparability guidelines, with deviation risk concentrated in EMA immunogenicity study timeline extensions and WHO International Standards allocation delays. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Non-Receptor Tyrosine Kinase Inhibitors Market
Biopharmaceuticals
Paediatric Oncology Therapeutics Market
Biopharmaceuticals
Human Immunodeficiency Virus (HIV) Drugs Market
Biopharmaceuticals
Single-Domain Antibody Platforms Market
Biopharmaceuticals
Latin America Insulin Pens Market
Biopharmaceuticals
Biopharmaceutical Oral Drug Delivery Market
Biopharmaceuticals
Tuberculosis Biomarkers Market
Biopharmaceuticals
Global Carboprost Tromethamine Market
Biopharmaceuticals
Interleukin-6 (IL-6) Inhibitors Market
Biopharmaceuticals
Theranostics Market
Biopharmaceuticals
Global Biopharmaceutical Fermentation Systems Market
Biopharmaceuticals
Progesterone Market
Biopharmaceuticals
Inactivated Vaccines Market
Biopharmaceuticals
Biological Drugs Market
Biopharmaceuticals
Ocular Tuberculosis Therapeutics Market
Biopharmaceuticals
Global Blood Product Market