
 Global Clinical Trial Supply Market | 2026-2036
Global Clinical Trial Supply Market Size, Share, and Industry Trends Forecast 2026-2036
Global Clinical Trial Supply Market Foresight
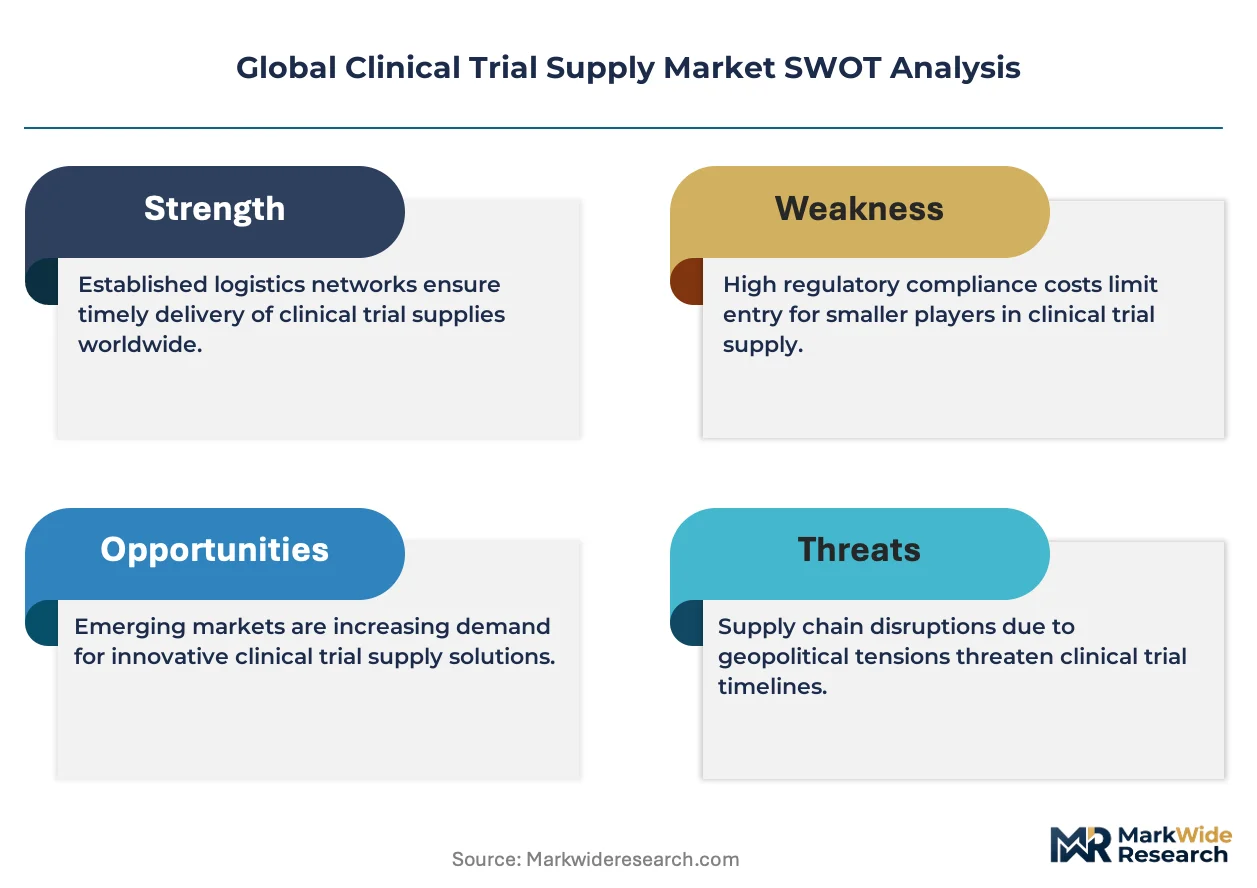
Comparator sourcing revenue is reconfiguring margin pools across the clinical trial supply chain. Thermo Fisher Scientific Inc. leverages its end-to-end laboratory infrastructure to control upstream comparator manufacturing. Catalent Inc. anchors high-complexity packaging and distribution networks across North America and Europe. Almac Group specializes in patient-centric supply strategies that differentiate its service portfolio in oncology trials.
Clinical trial supply encompasses the procurement, manufacturing, packaging, labeling, storage, and distribution of investigational medicinal products, placebos, and comparators under temperature-controlled conditions, typically requiring maintenance between 2°C and 8°C for biologics and -20°C to -80°C for cell therapies, ensuring chain-of-custody documentation from production site to patient administration. Packaging materials command stable margin pools due to serialization mandates and tamper-evident requirements, while storage solutions represent the fastest-growing segment as cryogenic logistics expands for gene therapy trials. Phase III trials generate the largest absolute demand volumes, though bioavailability studies are gaining share through adaptive trial designs that compress development timelines.
The FDA enforces current good manufacturing practice standards that govern comparator drug qualification and label verification, while the EMA's Falsified Medicines Directive mandates end-to-end traceability across European trial networks. WHO guidelines on temperature monitoring provide the baseline framework that national regulators in Japan, South Korea, and Brazil reference for local compliance. Stakeholders must monitor how decentralized trial models reshape last-mile distribution requirements and whether regulatory divergence between the FDA and EMA on direct-to-patient shipping creates compliance fragmentation.
Market Dynamics
Decentralized trial models are fragmenting traditional distribution hierarchies and forcing sponsors to rebuild logistics networks around direct-to-patient delivery rather than site-centric supply chains.
Growth Catalysts
- Gene therapy pipelines:Cell and gene therapy trials require cryogenic logistics infrastructure that commands premium service margins and extends contract durations.
- FDA's updated good distribution practice guidance:Stricter chain-of-custody documentation mandates are driving sponsor investment in qualified logistics providers with validated temperature monitoring systems.
- Oncology trial concentration:Immuno-oncology protocols generate recurring demand for patient-specific drug pooling and adaptive supply strategies across major trial clusters in the United States, Germany, and China.
Market Restraints
- Comparator drug scarcity:Patent-protected originator products face allocation restrictions from manufacturers prioritizing commercial supply over clinical trial demand.
- Specialized cold chain infrastructure:Ultra-low temperature storage assets for cell therapies require capital deployment that smaller regional depots cannot finance.
- EMA-FDA regulatory divergence:Inconsistent direct-to-patient shipping authorization rules between European and American regulators force sponsors to maintain parallel distribution workflows.
Strategic Opportunities
- Latin American trial expansion:Brazil's ANVISA has streamlined import licensing for investigational products, opening patient recruitment pools outside saturated North American and Western European sites.
- Real-time temperature monitoring convergence:Integration of IoT sensors with blockchain verification creates auditable chain-of-custody records that satisfy both FDA and EMA inspection protocols.
- Home nursing service partnerships:Direct-to-patient trial models require last-mile clinical support that logistics providers can bundle with drug delivery to capture service revenue.
Industry Challenges
- Qualified person shortage:EMA mandates require named individuals with specific pharmaceutical logistics certification to oversee European trial releases, creating hiring bottlenecks.
- Legacy depot management systems:Sponsor technology stacks built for site-centric distribution lack API connectivity with patient-facing delivery platforms and mobile health applications.
- Multi-protocol inventory optimization:Adaptive trial designs with frequent arm modifications strain forecasting models originally built for fixed-protocol Phase III programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Clinical Trial Supply Market |
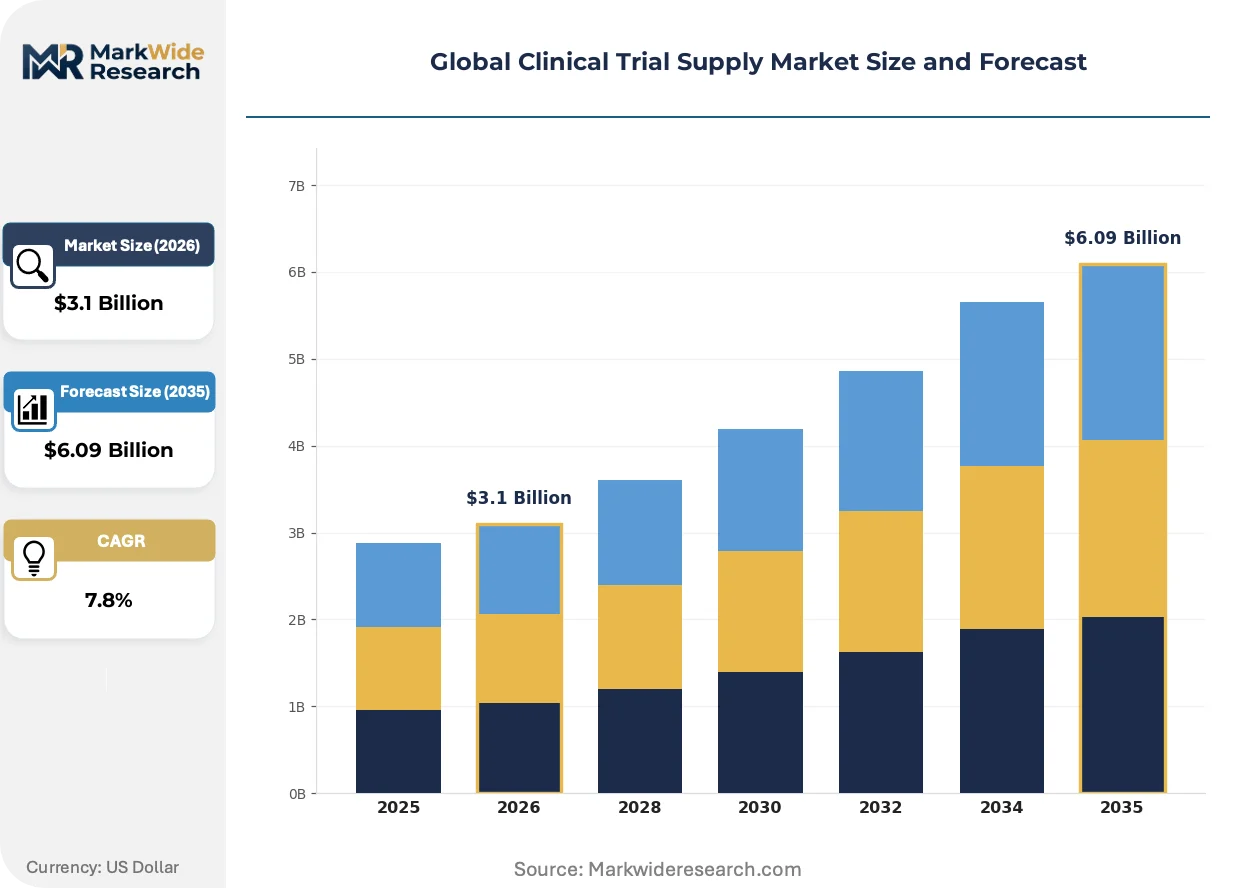
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $6.09 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Packaging Materials, Storage Solutions, Labeling Systems, Temperature Control Devices, Distribution Equipment Application: Phase I Trials, Phase II Trials, Phase III Trials, Bioavailability Studies, Post-Market Surveillance End User: Contract Research Organizations, Pharmaceutical Manufacturers, Biotechnology Firms, Academic Research Centers, Government Agencies Distribution Channel: Direct Sales, Third-Party Logistics, Online Platforms, Wholesale Distributors, Specialty Suppliers |
| Companies Covered | Thermo Fisher Scientific Inc., Catalent Inc., Almac Group, PCI Pharma Services, Parexel International Corporation, UPS Healthcare, Marken, Piramal Pharma Solutions, Sharp Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Clinical Trial Supply Market Shifts & Advancements
Digital integration across temperature monitoring, patient adherence tracking, and inventory forecasting is compressing the traditional separation between clinical operations and supply chain functions.
Blockchain-enabled verification is collapsing the documentation burden for cross-border trial shipments. Sponsors running multi-regional oncology protocols are adopting distributed ledger systems to synchronize customs clearance records across United States, German, and Chinese regulatory submissions. This technology is collapsing reconciliation delays that previously added weeks to comparator drug release timelines.
EMA's Falsified Medicines Directive serialization mandates are forcing packaging line retrofits across European contract manufacturing networks. The regulation requires unit-level traceability from production through patient administration, eliminating batch-level tracking that previously sufficed for clinical supplies. High-complexity oncology trials with patient-specific dosing are most affected, driving investment in automated label verification systems.
Site-less trial recruitment is redirecting patient enrollment away from academic medical centers toward community-based investigators and home health networks. This channel shift eliminates the consolidated demand patterns that traditional depot networks were optimized to serve. The United States exhibits the most pronounced behavioral change, with sponsors in immuno-oncology and rare disease indications leading the transition.
Global Clinical Trial Supply Market Segmentation
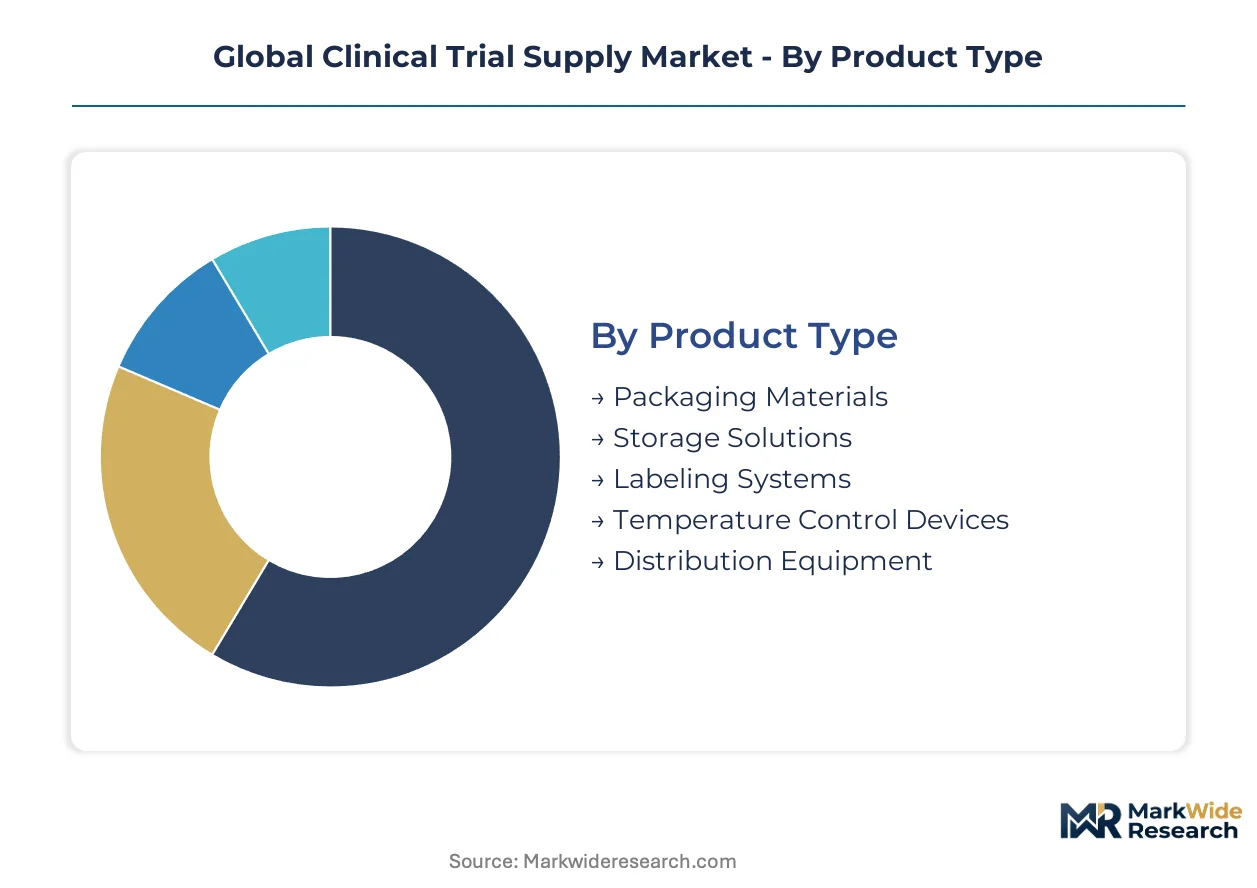
Segmentation in clinical trial supply reveals how specialized infrastructure requirements fragment procurement decisions across temperature sensitivity, trial complexity, and regulatory jurisdiction. Each dimension carries distinct margin profiles and vendor qualification thresholds that reshape competitive positioning.
Product Type:
Mature packaging and labeling systems anchor revenue stability while cryogenic storage solutions emerge as the highest-margin expansion corridor.
- Packaging Materials:Tamper-evident containers, serialization-enabled cartons, and patient-specific blister packs constitute the foundational layer. Demand concentrates in oncology trials across the United States and Germany where EMA Falsified Medicines Directive compliance mandates unit-level traceability.
- Storage Solutions:Ultra-low temperature freezers, liquid nitrogen dewars, and validated cold rooms preserve chain-of-custody for cell therapies. Cryogenic infrastructure commands premium contract durations in gene therapy hubs clustered around Boston and Basel.
- Labeling Systems:Automated print-and-apply stations integrate with clinical trial management platforms.
- Temperature Control Devices:Data loggers and wireless sensors enable real-time monitoring during transit.
- Distribution Equipment:Insulated shippers and phase-change materials protect payload integrity across last-mile delivery.
Packaging Materials retains volume leadership; Storage Solutions holds the steepest expansion curve.
Application:
Cost tier stratification separates high-volume Phase III logistics from adaptive design studies that compress forecasting timelines.
- Phase III Trials:Large-scale randomized protocols generate absolute demand peaks for comparator sourcing and multi-site distribution networks. Sponsors in China and the United States deploy centralized depot models to serve hundreds of investigative sites simultaneously.
- Phase I Trials:First-in-human studies require small-batch manufacturing with rapid protocol amendment turnaround. Biotechnology firms in Cambridge and South San Francisco drive demand for flexible manufacturing slots.
- Phase II Trials:Dose-ranging studies balance patient recruitment velocity with supply flexibility.
- Bioavailability Studies:Crossover designs demand precise comparator matching and abbreviated distribution windows.
- Post-Market Surveillance:Risk evaluation and mitigation strategies extend supply obligations beyond approval.
Phase III Trials commands procurement volume; Bioavailability Studies gains share through adaptive trial compression.
End User:
Customer type fragmentation reflects divergent outsourcing depth across sponsor scale and therapeutic focus.
- Contract Research Organizations:Full-service providers integrate supply chain management with patient recruitment and data capture. IQVIA and Parexel maintain qualified depot networks spanning the United States, Germany, and China to serve global protocol requirements.
- Pharmaceutical Manufacturers:Large-cap sponsors deploy hybrid models combining captive manufacturing with third-party logistics for geographic reach. Pfizer and Roche invest in regional distribution centers to protect comparator allocation priority.
- Biotechnology Firms:Emerging sponsors lack capital for cold chain infrastructure and rely on contract manufacturing organizations.
- Academic Research Centers:University hospitals manage site-level inventory for investigator-initiated trials.
- Government Agencies:NIH and equivalent bodies fund multi-site consortia with centralized procurement mandates.
Contract Research Organizations capture outsourcing momentum; Biotechnology Firms expands most quickly through venture-funded pipeline growth.
Distribution Channel:
Supply concentration varies by channel control depth, with direct relationships commanding qualification priority for temperature-sensitive shipments.
- Third-Party Logistics:Specialized providers such as World Courier and Marken maintain GDP-compliant networks with validated temperature mapping. These partnerships dominate cross-border movements where FDA and EMA inspection protocols require documented chain-of-custody.
- Direct Sales:Equipment manufacturers such as Stirling Ultracold and Cytiva sell storage hardware directly to sponsor facilities. Direct relationships prevail in capital-intensive categories where installation validation and service contracts extend engagement duration.
- Online Platforms:Digital procurement portals aggregate catalog purchasing for standard consumables.
- Wholesale Distributors:Regional wholesalers serve site-level replenishment for non-specialized supplies.
- Specialty Suppliers:Niche vendors provide comparator sourcing and clinical packaging services.
Third-Party Logistics anchors cross-border volume; Direct Sales climbs fastest through captive equipment deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Depot networks and qualified logistics infrastructure concentrate in jurisdictions with the densest active trial footprints and most stringent pharmaceutical distribution regulations. The United States, Germany, China, Japan, and Brazil each anchor distinct supply chain configurations shaped by local regulatory frameworks and therapeutic research specializations.
United States
Immuno-oncology and rare disease protocols drive the highest per-trial logistics spend globally. FDA updated good distribution practice guidance mandates enhanced chain-of-custody documentation for direct-to-patient shipments. The Boston-Cambridge corridor hosts the densest concentration of cell therapy developers requiring cryogenic infrastructure.
Germany
EMA Falsified Medicines Directive serialization requirements force packaging line retrofits across European contract manufacturing networks. The Basel region anchors comparator sourcing operations for multi-regional oncology trials. German logistics providers maintain GDP-compliant networks serving as the primary distribution hub for continental European protocols.
China
NMPA regulatory convergence with international standards accelerates multi-national sponsor investment in local depot infrastructure. Shanghai and Beijing cluster the majority of domestic biotech firms running Phase I-III programs. Import licensing reforms streamline investigational product entry for global protocols with Chinese participation.
Japan
PMDA inspection protocols demand documented temperature monitoring systems that exceed WHO baseline guidelines. The Kanto region concentrates clinical packaging operations serving Asia-Pacific trial networks. Japanese sponsors prioritize qualified logistics partnerships for comparator drugs sourced from European and North American manufacturers.
Brazil
ANVISA streamlined import licensing procedures open patient recruitment pools outside saturated North American and Western European sites. São Paulo anchors the majority of qualified depot capacity serving Latin American trial expansion. Regional sponsors leverage Brazilian regulatory efficiency to compress protocol startup timelines.
Global Clinical Trial Supply Market Competitive Landscape
Integrated service conglomerates and specialized clinical logistics providers split the market along the fault line of end-to-end control versus functional depth. Three archetypes dominate: diversified laboratory and supply conglomerates with captive manufacturing assets; pure-play clinical packaging and distribution specialists; and healthcare-forward logistics carriers with temperature-validated networks. Consolidation pressure intensifies as gene therapy pipelines demand cryogenic capabilities that smaller regional depots cannot finance independently.
Within the integrated conglomerate tier, Thermo Fisher Scientific Inc. and Catalent Inc. exemplify strategic positioning built upon laboratory infrastructure extension into upstream comparator manufacturing and high-complexity packaging networks. Almac Group occupies a position among patient-centric supply specialists differentiated through oncology trial service configurations. These three entities anchor the competitive structure that smaller regional providers and healthcare logistics entrants must navigate through niche specialization or geographic focus.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Catalent Inc. |
| Almac Group |
| PCI Pharma Services |
| Parexel International Corporation |
| UPS Healthcare |
| Marken |
| Piramal Pharma Solutions |
| Sharp Services |
| Others |
Supply & Pricing Matrix
Comparator manufacturing concentration in Switzerland and Germany anchors premium pricing tiers for oncology trials, while cryogenic logistics capacity scarcity in the United States and China shifts margin pools toward ultra-low temperature storage providers. EMA serialization mandates and FDA chain-of-custody requirements add compliance premiums that sponsors cannot negotiate away.
Pricing Analysis
FDA good distribution practice guidance dictates the pricing tier structure across clinical trial supply services. Three-tier pricing structure across premium, standard, and economy levels separates qualified cold chain providers with validated temperature monitoring from regional depots lacking cryogenic assets. Price differentiation rests on GDP certification grade and geographic delivery complexity. Cost compression in standard-tier packaging services is intensifying because EMA Falsified Medicines Directive retrofits force capital redeployment. Biotechnology firms exhibit highest price sensitivity due to venture funding constraints; large-cap pharmaceutical manufacturers absorb compliance premiums with minimal procurement friction.
Supply Chain Analysis
Catalent, Thermo Fisher Scientific, and Almac Group hold dominant contract manufacturing capacity across North American and European clinical packaging networks. Supply concentrates in the United States, Germany, and China where qualified depot infrastructure aligns with dense trial footprints. Raw material dependencies span pharmaceutical-grade excipients, serialization-enabled packaging substrates, and liquid nitrogen for cryogenic preservation. Single-source vulnerability in comparator drug allocation from patent-protected originator manufacturers threatens protocol continuity. Distribution runs through third-party logistics partnerships with GDP-validated temperature mapping rather than sponsor-captive networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene therapy pipeline expansion represents an early-cycle adoption tailwind as cell therapy developers build cryogenic infrastructure ahead of commercialization curves. Penetration remains shallow outside Boston and Basel clusters.
For Market Incumbents: Entrench comparator sourcing relationships through backward integration into originator allocation agreements. Add cryogenic capacity in the Boston-Cambridge corridor where cell therapy developers concentrate. Vertical integration into patient-centric last-mile services defends against pure-play logistics entrants targeting decentralized trial models.
For New Entrants and Emerging Players: Latin American depot infrastructure presents the most penetrable white-space opportunity as ANVISA licensing reforms accelerate. Brazil and Mexico lack qualified cold chain density relative to trial recruitment growth. Home nursing service bundling with direct-to-patient drug delivery offers a differentiated go-to-market angle against established site-centric providers.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap clinical packaging specialists with EMA serialization compliance and oncology trial expertise. Long-term viability hinges on cryogenic capability buildout as gene therapies advance through Phase III. Watch FDA-EMA regulatory convergence on direct-to-patient shipping authorization as the signal for supply chain consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Infrastructure Expansion | Boston and Basel developers require validated ultra-low temperature networks for cell therapy commercialization. |
| Blockchain Verification Integration | FDA and EMA inspection protocols favor distributed ledger systems for cross-border chain-of-custody documentation. |
| Home Nursing Service Partnerships | Direct-to-patient trial models bundle clinical support with drug delivery to capture service revenue pools. |
| EMA Serialization Retrofit Completion | Falsified Medicines Directive mandates eliminate batch-level tracking for unit-level traceability in oncology trials. |
| Latin American Depot Establishment | ANVISA import licensing reforms open patient recruitment pools outside saturated North American sites. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with clinical operations directors, regulatory affairs leads, comparator sourcing managers, and third-party logistics procurement officers; and secondary validation through FDA guidance documents, EMA regulatory submissions, ClinicalTrials.gov protocol registries, and WHO temperature monitoring guidelines. Bottom-up demand modeling across trial phase, therapeutic area, and temperature sensitivity tiers triangulated against top-down market sizing.
Forecast inputs include gene therapy pipeline progression, decentralized trial adoption velocity, and regulatory divergence between FDA and EMA direct-to-patient authorization frameworks. Segmentation dimensions span product type, application, end user, and distribution channel with regional regulatory cluster overlays. CAGRs derive from trial initiation trends, comparator scarcity indices, and cryogenic logistics capacity expansion schedules across the analysis window.
The forecast holds incumbent behavior within observed patterns; aggressive moves by healthcare-forward logistics carriers or technology-enabled supply chain entrants would shift outcomes beyond modeled ranges. Quarterly review of FDA-EMA regulatory harmonization progress, gene therapy Phase III conversion rates, and comparator allocation priority changes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Research
AI in Clinical Trials Market
Clinical Research
Humanized Mice Model Market
Clinical Research
AI-Based Clinical Trials Solution Provider Market
Clinical Research
Clinical Trial Logistics and Direct-to-Patient Delivery Platforms Market
Clinical Research
North America Clinical Trials Market
Clinical Research
Healthcare Europe Clinical Data Analytics Market
Clinical Research
India CRO Market
Clinical Research
Clinical Trials Outsourcing Market
Clinical Research
Global Clinical Trial Management Systems Market
Clinical Research
Ecoa, Esource & Clinical Trials Market
Clinical Research
Clinical Trial Management Services Market
Clinical Research
Global Clinical Trial Supply Management Market
Clinical Research
Atopic Dermatitis Clinical Trials Market
Clinical Research
Clinical Trial Patient Recruitment Services Market
Clinical Research
Global in Vivo Toxicology Market
Clinical Research
Asia-Pacific Contract Research Organization Market