
 Healthcare Europe Clinical Data Analytics Market | 2026-2036
Healthcare Europe Clinical Data Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Europe Clinical Data Analytics Market Insights
Cloud-native infrastructure is rebalancing total cost of ownership for clinical data analytics deployments across European health systems. IBM Corporation leverages its Watson Health platform to anchor hybrid cloud deployments in Nordic hospital networks. Oracle Corporation sustains competitive positioning through embedded database architectures that streamline regulatory audit trails for pharmaceutical clients. Philips Healthcare specializes in acute-care analytics, dominating cardiac and intensive-care data integration workflows across Benelux institutions.
Healthcare Europe clinical data analytics encompasses software solutions, services, and platforms that ingest, normalize, and analyze structured and unstructured clinical data from electronic health records, medical imaging systems, and connected diagnostic devices, typically processing datasets exceeding millions of patient encounters to generate actionable intelligence for care optimization. The primary commercial purpose centers on reducing clinical variation, accelerating trial recruitment, and enabling value-based reimbursement models across national health systems. Software Solutions currently leads product-type revenue, reflecting persistent hospital preference for integrated platforms over point tools. Cloud-Based deployment is expanding fastest among research institutions, driven by multi-site collaboration requirements and elastic compute needs for genomic-scale datasets.
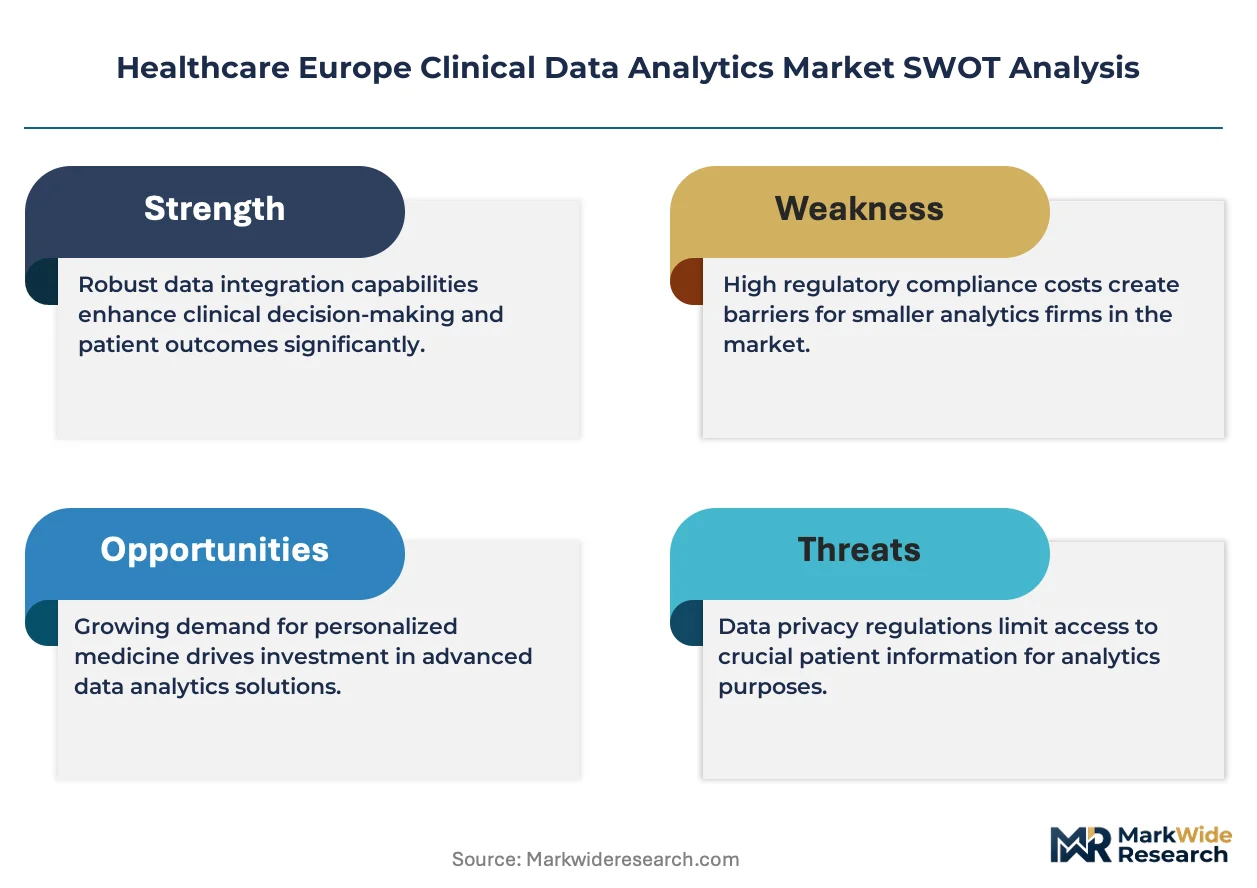
EMA's evolving guidance on real-world evidence submission, GDPR's health data processing constraints, and the EU AI Act's risk-classification framework for clinical decision-support tools collectively elevate compliance engineering to a core purchasing criterion. These regulatory layers favor vendors with pre-certified quality management systems and established European data residency architectures. Stakeholders must weigh interoperability mandates against sovereignty requirements as member states implement divergent national health cloud strategies.
Market Dynamics
GDPR and the EU AI Act are forcing healthcare data infrastructure rebuilds across European hospital networks, with compliance engineering now consuming larger procurement budgets than core analytics functionality. Vendors must embed privacy-by-design architectures to remain eligible for NHS Digital tenders.
Growth Catalysts
- NHS Digital Interoperability Mandates:United Kingdom hospital trusts must replace legacy data infrastructure by 2025, creating immediate replacement demand for cloud-native analytics platforms with FHIR-compliant data exchange capabilities.
- EMA Real-World Evidence Guidance:Pharmaceutical sponsors now submit real-world data packages for regulatory decisions, expanding the addressable market for clinical data aggregation and normalization services across European trial sites.
- Genomic-Scale Computing Elasticity:Research institutions processing multi-terabyte genomic datasets require cloud-based deployment models that expand compute resources on demand, accelerating migration from on-premise server farms.
Market Restraints
- Cross-Border Data Localization Requirements:Member state health cloud strategies mandate divergent data residency rules, fragmenting vendor architectures and inflating compliance costs for pan-European deployments.
- Specialized Talent Scarcity:Health informaticists with dual competencies in clinical workflows and machine learning engineering command premium compensation, constraining implementation velocity for mid-tier hospital networks.
- Legacy System Technical Debt:Decades-old electronic health record systems in German and French public hospitals lack standardized APIs, requiring expensive middleware development for analytics integration.
Strategic Opportunities
- Benelux Acute-Care Analytics:Cardiac and intensive-care data integration workflows remain underpenetrated in Belgian and Dutch regional hospitals, offering first-mover advantages for specialized platform vendors.
- EU AI Act Risk-Class Certification:Pre-certified clinical decision-support tools gain automatic preference in public procurement frameworks, rewarding early compliance investments with sustained competitive moats.
- Federated Learning Architectures:Privacy-preserving machine learning techniques enable multi-site collaboration without raw data movement, addressing GDPR constraints while unlocking cross-border research consortiums.
Industry Challenges
- Interoperability Standard Fragmentation:Competing health data exchange protocols across European member states force vendors to maintain multiple integration codebases, diluting engineering resources.
- AI Model Validation Timelines:Clinical decision-support algorithms require extensive prospective validation studies before hospital adoption, extending sales cycles and deferring revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Europe Clinical Data Analytics Market |
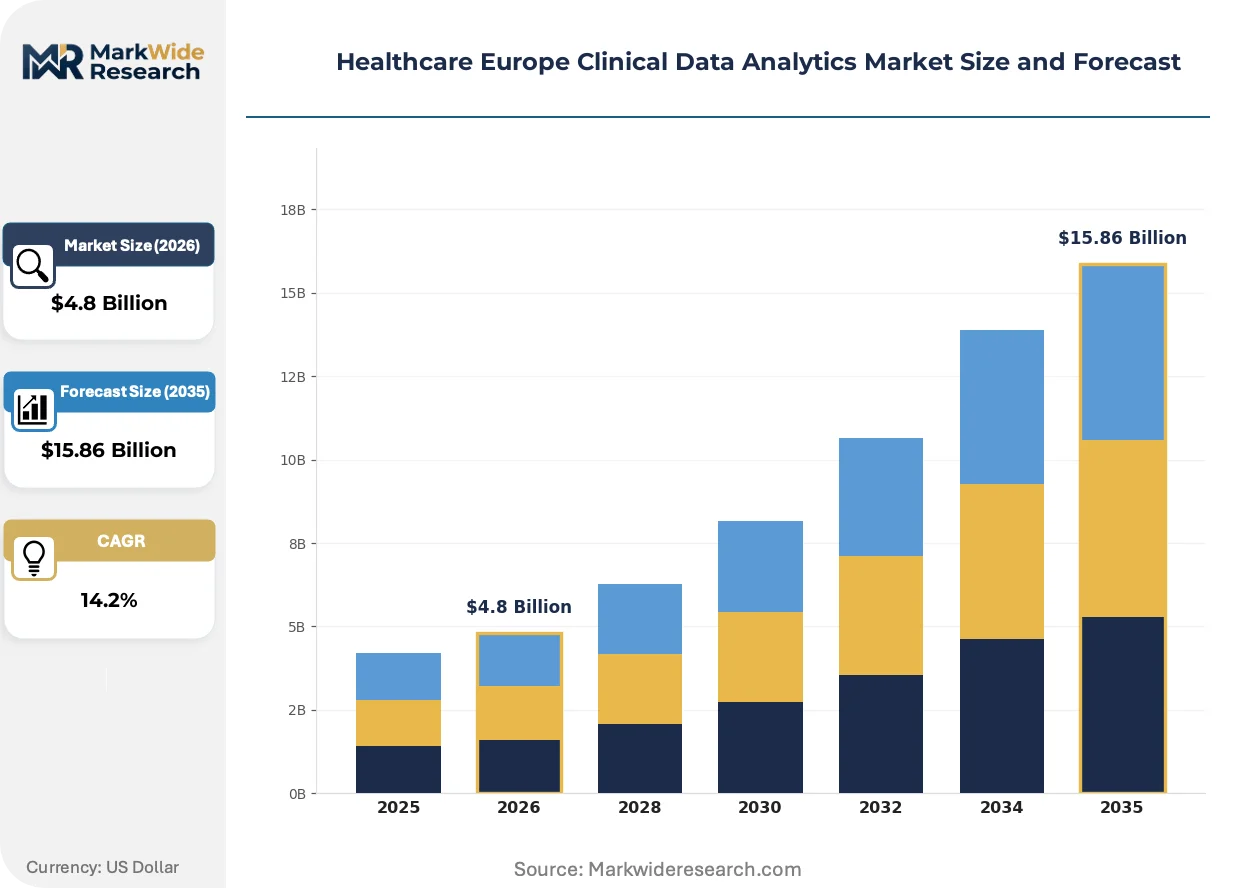
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
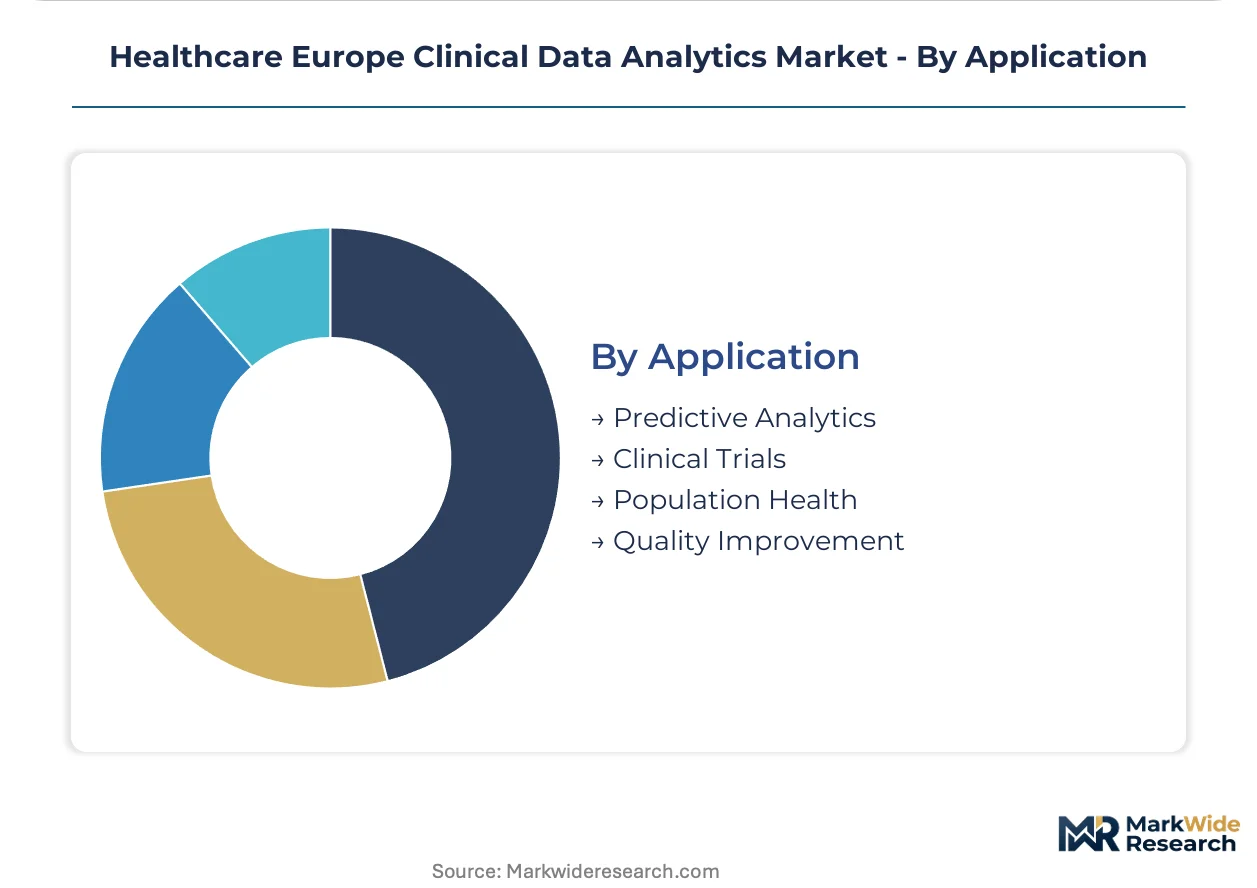
| Segmentation | Product Type: Software Solutions, Consulting Services, Data Management Tools, Analytics Platforms End User: Hospitals, Diagnostic Labs, Research Institutions, Pharmaceutical Companies Deployment: On-Premises, Cloud-Based, Hybrid Solutions, Managed Services Application: Predictive Analytics, Clinical Trials, Population Health, Quality Improvement |
| Companies Covered | IBM Corporation, Oracle Corporation, Cerner Corporation, McKesson Europe AG, Optum, Inc., IQVIA, Philips Healthcare, Siemens Healthineers, Allscripts Healthcare, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Europe Clinical Data Analytics Market Trends and Innovations
Federated analytics architectures are displacing centralized data lakes as the dominant technical paradigm for multi-site clinical research, driven by privacy regulations that prohibit raw patient data aggregation across institutional boundaries.
Synthetic data generation is rewriting how pharmaceutical sponsors access representative patient cohorts for algorithm training. Vendors in Germany and Switzerland now supply statistically validated synthetic records that mirror real disease progression patterns without privacy exposure. Bayer and Roche have integrated these tools into early-phase trial design, compressing patient recruitment timelines by eliminating data access negotiations with individual hospitals.
The EU AI Act's risk-classification framework for clinical decision-support tools imposes mandatory conformity assessments on high-risk applications. Medical device manufacturers must maintain post-market surveillance systems and algorithm change control protocols to retain CE marking. French notified bodies have developed specialized audit programs for machine learning-based diagnostic software, creating certification bottlenecks that favor vendors with pre-established quality management systems.
Subscription-based platform licensing is displacing perpetual software purchases in Nordic hospital procurement. Danish and Swedish regional health authorities now negotiate multi-year analytics service contracts with outcome-linked renewal clauses, transferring implementation risk to vendors. This model concentrates purchasing power among large hospital networks while squeezing margins for point-solution providers lacking comprehensive service capabilities.
Healthcare Europe Clinical Data Analytics Market Segmentation
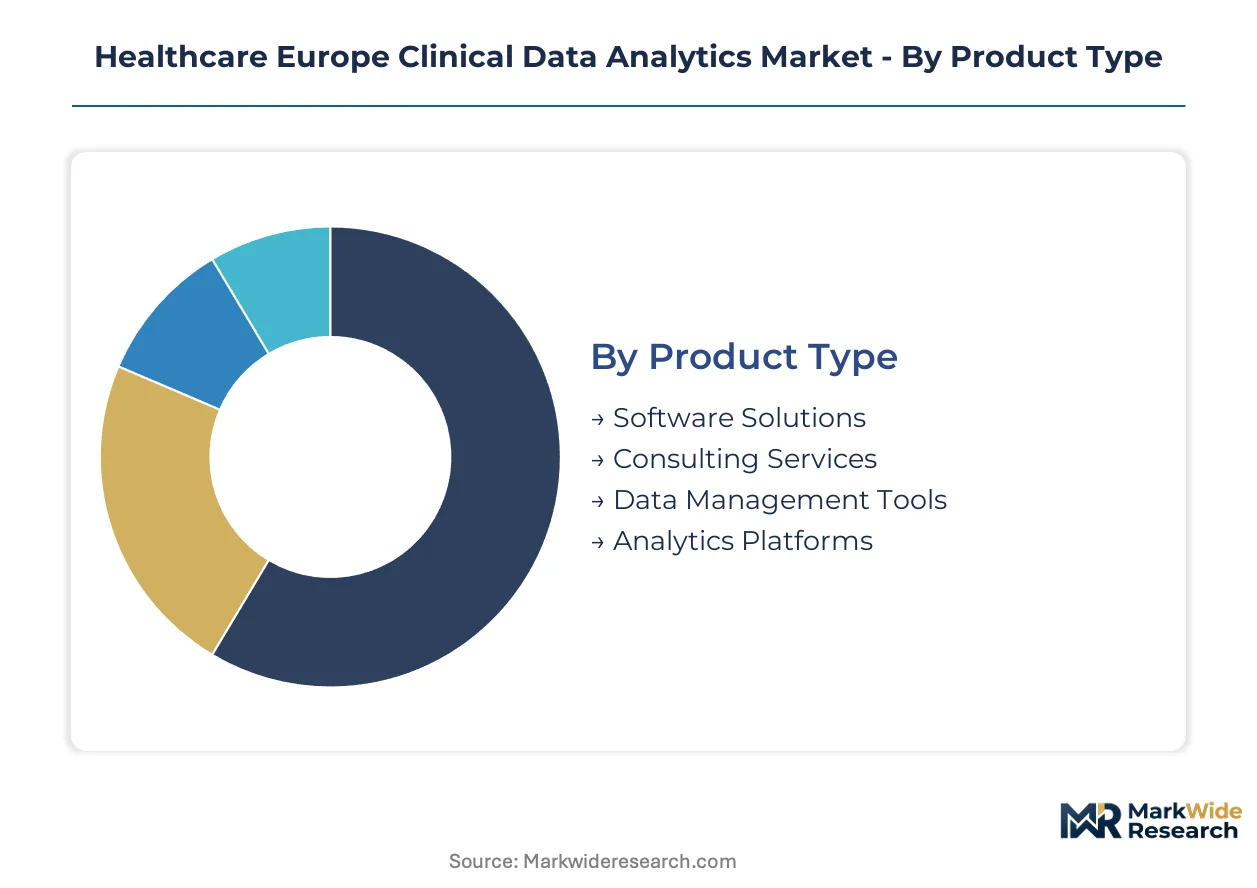
European health systems exhibit divergent procurement priorities across product architectures, deployment models, and clinical use cases. Segmentation reveals where NHS Digital mandates, EMA evidence requirements, and GDPR compliance burdens concentrate purchasing power and vendor investment.
Product Type:
Hospital procurement teams distinguish vendors by integration depth versus standalone functionality, with total cost of ownership calculations now weighting compliance engineering above core analytics capabilities.
- Software Solutions:Integrated platforms ingest, normalize, and analyze structured and unstructured clinical data from electronic health records and medical imaging systems. German and French hospital networks favor these for operational efficiency gains, though legacy system technical debt inflates implementation timelines. Volume sits with Software Solutions; growth tilts toward Analytics Platforms.
- Analytics Platforms:Specialized architectures process genomic-scale datasets and real-world evidence packages for pharmaceutical sponsors. Cloud-native elasticity attracts research institutions across Denmark and Sweden handling multi-terabyte computational workloads.
- Consulting Services:Implementation support for FHIR-compliant data exchange and GDPR privacy-by-design architectures.
- Data Management Tools:Middleware solutions bridging decades-old electronic health record systems lacking standardized APIs.
Revenue concentrates in integrated platforms; specialized analytics architectures expand most quickly.
End User:
Buying centers range from centralized NHS procurement frameworks to fragmented regional hospital networks, with regulatory sophistication determining vendor qualification thresholds.
- Hospitals:Acute-care institutions dominate cardiac and intensive-care data integration workflows across Benelux, driven by quality improvement mandates and value-based reimbursement models. United Kingdom hospital trusts face replacement deadlines for legacy data infrastructure. Procurement volume clusters with Hospitals; expansion tilts toward Research Institutions.
- Research Institutions:Multi-site genomic consortiums require federated learning architectures that enable collaboration without raw data movement, satisfying GDPR constraints while unlocking cross-border partnerships.
- Pharmaceutical Companies:EMA real-world evidence submissions drive demand for clinical data aggregation and normalization services across European trial sites.
- Diagnostic Labs:Connected diagnostic device integration for predictive analytics and population health surveillance.
Installed base remains hospital-centric; research institutions gain share fastest.
Deployment:
Data residency requirements and compute elasticity needs create a three-way split between sovereignty, scalability, and risk-transfer preferences.
- Cloud-Based:Elastic compute resources expand on demand for genomic-scale datasets, with Nordic hospital procurement shifting toward subscription-based service contracts with outcome-linked renewal clauses. Research institutions across the Netherlands and Belgium lead migration from on-premise server farms.
- Hybrid Solutions:Architectures split sensitive patient data processing on-premise while leveraging cloud analytics for non-identifiable cohort studies, addressing divergent member state health cloud strategies.
- On-Premises:German public hospitals maintain captive infrastructure for GDPR compliance and audit trail control.
- Managed Services:Danish and Swedish regional health authorities transfer implementation risk to vendors through multi-year analytics service contracts.
On-premise retains installed base dominance; cloud deployment climbs the fastest.
Application:
Clinical and financial incentives align differently across operational optimization, regulatory submission, and reimbursement redesign use cases.
- Predictive Analytics:Algorithms forecasting patient deterioration and readmission risk require extensive prospective validation studies before hospital adoption, extending sales cycles. French notified bodies have developed specialized audit programs for machine learning-based diagnostic software, creating certification bottlenecks.
- Clinical Trials:Real-world evidence packages for EMA regulatory decisions expand addressable market for data aggregation services, with synthetic data generation compressing patient recruitment timelines by eliminating hospital access negotiations.
- Population Health:Surveillance systems tracking disease progression patterns across regional cohorts for NHS Digital interoperability mandates.
- Quality Improvement:Intensive-care and cardiac workflow optimization tools dominating Benelux acute-care analytics procurement.
Quality improvement holds current deployment share; clinical trials applications gain momentum fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United Kingdom hospital trusts concentrate immediate procurement volume as NHS Digital interoperability mandates force legacy infrastructure replacement by 2025 deadline.
United Kingdom
NHS Digital mandates drive cloud-native platform procurement across England's hospital trusts. GDPR health data processing constraints elevate privacy-by-design architectures to core purchasing criteria. London-based academic medical centers pioneer federated learning deployments for multi-site genomic research consortiums.
Germany
Public hospital networks accelerate predictive analytics adoption to reduce clinical variation and optimize operational efficiency. The country's national data protection authority enforces strict health data residency requirements favoring hybrid cloud architectures. Bavarian university hospitals lead genomic-scale computing investments for pharmaceutical research partnerships.
France
Hospital networks prioritize cardiac and intensive-care data integration workflows under value-based reimbursement models. ANSM and CNIL coordinate oversight of machine learning-based diagnostic software certification, creating specialized audit bottlenecks. Paris-region public hospitals concentrate procurement of acute-care analytics platforms.
Netherlands
Research institutions processing multi-terabyte genomic datasets require elastic cloud compute resources expanding on demand. EMA real-world evidence guidance drives pharmaceutical sponsors toward Dutch trial sites with advanced data aggregation capabilities. Amsterdam and Rotterdam academic medical centers anchor cross-border federated learning consortiums.
Sweden
Regional health authorities negotiate multi-year analytics service contracts transferring implementation risk to vendors. GDPR constraints push adoption of privacy-preserving machine learning techniques enabling collaboration without raw data movement. Stockholm-based hospital networks pioneer subscription-based platform licensing with outcome-linked renewal clauses.
Healthcare Europe Clinical Data Analytics Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors embed compliance engineering capabilities to satisfy EU AI Act and GDPR procurement requirements. The vendor base organizes around three tiers: integrated platform providers with hybrid cloud architectures, specialized acute-care analytics specialists, and pharmaceutical-focused data aggregation services. Two archetypes capture premium positioning: legacy health IT vendors leveraging embedded database relationships, and research-oriented platforms offering genomic-scale elasticity. M&A activity concentrates on federated learning capabilities and synthetic data generation tools.
Among integrated platform providers, IBM Corporation and Oracle Corporation occupy positions anchored by hybrid cloud deployments and regulatory audit trail architectures respectively. Philips Healthcare exemplifies the acute-care specialization archetype through cardiac and intensive-care workflow dominance. These three entities represent contrasting competitive vectors: cloud-native infrastructure, embedded compliance systems, and clinical domain depth.
| Leading Market Players |
|---|
| IBM Corporation |
| Oracle Corporation |
| Cerner Corporation |
| McKesson Europe AG |
| Optum, Inc. |
| IQVIA |
| Philips Healthcare |
| Siemens Healthineers |
| Allscripts Healthcare |
| Others |
Pricing and Supply Chain Analysis
Captive cloud infrastructure investments by IBM Corporation and Oracle Corporation anchor supply positions while enabling subscription-based pricing power across Nordic and German hospital networks. These vertically integrated architectures compress middleware costs for buyers while locking in multi-year service contracts that transfer implementation risk to vendors.
Pricing Analysis
Volume concentrates in subscription-based platform licensing while margins concentrate in specialized acute-care analytics modules. Three-tier pricing structure across premium FHIR-compliant platforms, standard interoperability tools, and economy middleware solutions reflects certification grade and customization depth. Cost compression in the economy tier intensifies because NHS Digital mandates standardize procurement specifications. Research institutions exhibit lowest price sensitivity due to grant-funded genomic computing budgets.
Supply Chain Analysis
Reverse-logistics flows for decommissioned on-premise servers create refurbishment opportunities for German public hospitals migrating to hybrid architectures. Software development concentrates in Ireland, Germany, and the Netherlands, while cloud infrastructure draws from hyperscaler regions in Frankfurt, Dublin, and Amsterdam. Single-source vulnerability rests on NVIDIA GPU supply for genomic-scale computing clusters. Distribution runs through GPO contracts and NHS Digital procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around vendors with pre-certified EU AI Act compliance, forcing point-solution providers toward acquisition or exit as procurement frameworks favor comprehensive service capabilities.
For Market Incumbents: Anticipate margin compression from synthetic data generation entrants by embedding federated learning architectures into existing platforms. Acquire specialized acute-care analytics firms in Benelux to defend against Philips Healthcare's cardiac workflow dominance. Prioritize CE marking investments under French notified body audit programs to maintain procurement eligibility. For New Entrants and Emerging Players: Enter via underpenetrated Belgian and Dutch regional hospitals lacking intensive-care data integration capabilities. Target pharmaceutical sponsors seeking EMA real-world evidence packaging services as the most penetrable segment. Pursue cloud-native deployment positioning to bypass legacy system technical debt barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated platform providers seeking federated learning capabilities or synthetic data generation tools. Five-to-ten year viability favors vendors with established European data residency architectures and pre-certified quality management systems. Monitor NHS Digital tender awards and French ANSM certification bottlenecks as inflection indicators for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Pre-Certification | French notified body audits create competitive moats for compliant clinical decision-support tools. |
| Federated Learning Integration | Privacy-preserving architectures unlock cross-border genomic research consortiums under GDPR constraints. |
| Synthetic Data Generation Capability | Bayer and Roche partnerships demonstrate compression of patient recruitment timelines for pharmaceutical sponsors. |
| Hybrid Cloud Deployment | German data residency requirements favor architectures splitting sensitive processing from cloud analytics. |
| Outcome-Linked Service Contracts | Danish and Swedish regional authorities transfer implementation risk while concentrating purchasing power. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews with hospital procurement managers, biomedical engineers, GPO contracts managers, and pharmaceutical regulatory affairs leads. EMA submission databases, NHS Digital tender archives, and hospital procurement databases provided validation. Bottom-up facility-level modeling triangulated against top-down national health spending allocations.
Granularity extended to deployment model, end-user institution type, clinical application, and national regulatory cluster across the projection horizon. CAGRs derived from segment-level growth trajectory modeling incorporating EMA real-world evidence guidance adoption curves and NHS Digital interoperability mandate implementation schedules. Genomic-scale computing demand elasticity and GDPR compliance cost inflation served as key forecast inputs.
Revisions become necessary when EU AI Act enforcement timelines accelerate, member state health cloud strategies diverge further, or federated learning technical standards crystallize. Practitioners should monitor French ANSM certification queue lengths and NHS Digital tender award patterns for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Research
Non-Alcoholic Steatohepatitis Clinical Trials Market
Clinical Research
Europe Clinical Trials Market
Clinical Research
Preclinical CRO Market
Clinical Research
Clinical Trial Patient Recruitment Services Market
Clinical Research
US Virtual Clinical Trials Market
Clinical Research
Global Virtual Clinical Trials Market
Clinical Research
US Clinical Trials Market
Clinical Research
Esource and Clinical Trials Market
Clinical Research
AI-Based Clinical Trial Solutions for Patient Matching Market
Clinical Research
Clinical Trial Biorepository and Archiving Solutions Market
Clinical Research
India CRO Market
Clinical Research
Clinical Data Analytics Market
Clinical Research
Clinical Trial Logistics and Direct-to-Patient Delivery Platforms Market
Clinical Research
Atopic Dermatitis Clinical Trials Market
Clinical Research
Edema Clinical Trials Market
Clinical Research
Clinical Trials Market