

Real World Evidence Linkage Services Market Size, Share, and Industry Trends Forecast 2026-2036
Real World Evidence Linkage Services Market Insights
Buyer concentration among pharmaceutical manufacturers is pivoting toward a broader mix of contract research organizations and health technology assessors seeking outsourced linkage capabilities. IQVIA leverages its global data asset network to sustain competitive positioning across multiple therapeutic areas. Optum anchors its offering through deep integration with UnitedHealth Group's payer and provider infrastructure. Flatiron Health specializes in oncology-specific linkage workflows that differentiate its platform from generalized competitors.
Real world evidence linkage services encompass the technical processes of connecting disparate health datasets—electronic health records, claims registries, pharmacy dispensations, and mortality indices—through deterministic and probabilistic matching algorithms to enable longitudinal patient trajectory analysis at scale. These services deploy privacy-preserving record linkage protocols with match rates typically exceeding 95% accuracy to support regulatory-grade evidence generation for drug safety, effectiveness, and value demonstration. Data Integration services dominate current revenue flows as foundational infrastructure investments, while Machine Learning applications within patient matching and outcome prediction represent the fastest-expanding technology segment. Reporting & Analytics commands premium pricing due to specialized biostatistical expertise and customized regulatory formatting requirements.
FDA guidance on real-world evidence standards and EMA's DARWIN EU network are tightening data quality and provenance requirements, directly shaping vendor qualification criteria and procurement timelines. HealthVerity navigates this landscape through blockchain-anchored data lineage certification, while Aetion positions its platform around FDA-validated analytics methodologies for coverage and reimbursement decisions. Stakeholders must monitor evolving interoperability mandates from ONC and the European Health Data Space regulation to anticipate infrastructure investment priorities.
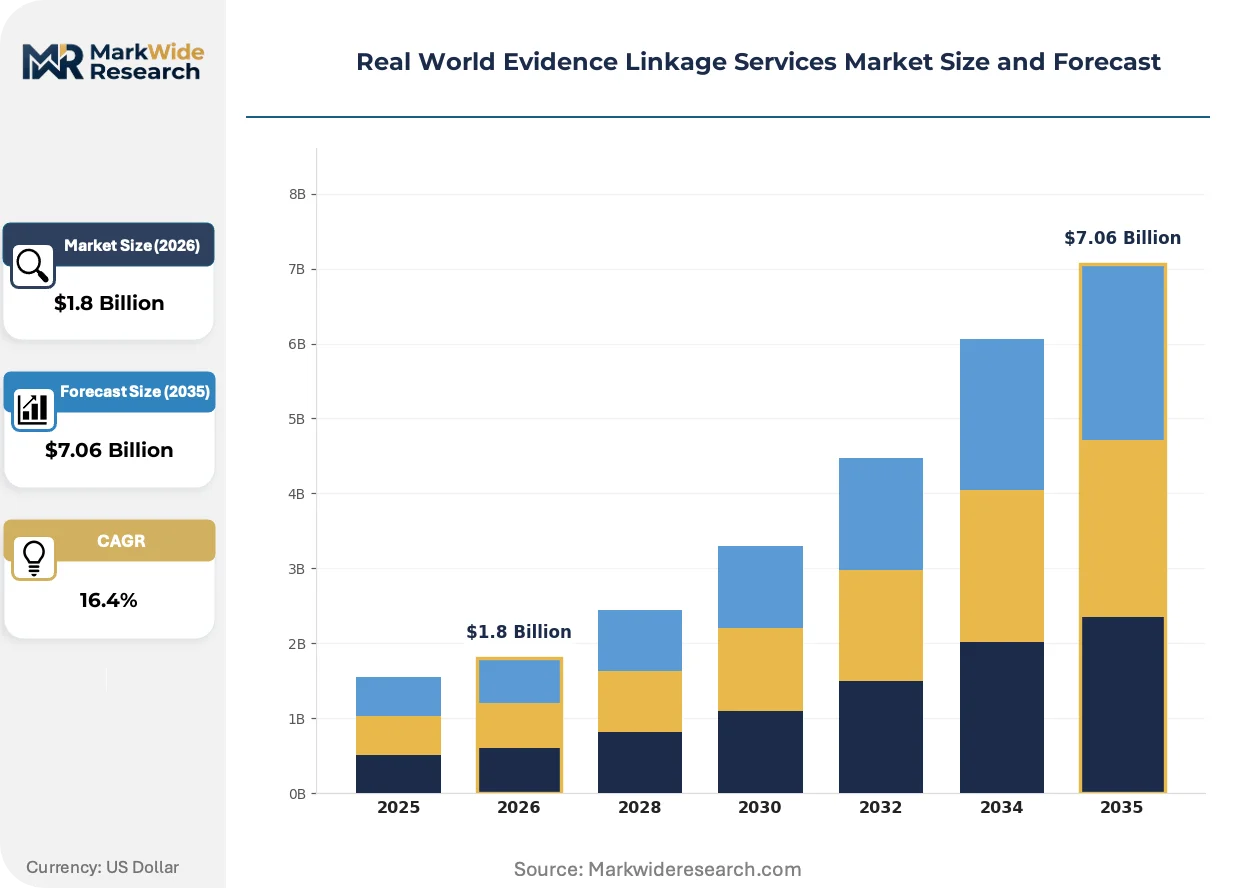
Market Dynamics
Pharmaceutical manufacturers are consolidating vendor relationships around platforms capable of FDA-validated analytics and EMA-compliant data provenance, compressing procurement timelines and raising technical qualification barriers for specialized linkage providers.
Growth Catalysts
- FDA 21st Century Cures Act framework:This statute mandates expanded use of real-world evidence in regulatory submissions, compelling drug sponsors to invest in compliant data linkage infrastructure for accelerated approval pathways.
- Post-market surveillance requirements:Safety monitoring obligations under pharmacovigilance guidelines are driving demand for longitudinal patient tracking across fragmented health data sources.
- Electronic health record maturation:United States integrated delivery networks now maintain sufficiently standardized data architectures to enable large-scale deterministic matching at population scale.
Market Restraints
- Privacy-preserving computation costs:Federated analytics and secure multi-party computing impose substantial infrastructure overhead, limiting deployment to well-capitalized enterprise buyers.
- Specialized talent scarcity:Biostatisticians with dual expertise in record linkage algorithms and regulatory submission formatting command premium compensation, constraining service expansion.
- Cross-border data transfer friction:GDPR restrictions on European health data movement create structural barriers to building transnational patient cohorts for multinational trials.
Strategic Opportunities
- European Health Data Space regulation:This forthcoming framework will establish standardized health data access and portability rules, opening federated linkage opportunities across EU member state repositories.
- Oncology-specific workflow specialization:Complex longitudinal tracking needs in immuno-oncology and combination therapy monitoring create premium service tiers for vendors with disease-domain expertise.
- Blockchain-anchored lineage certification:Immutable audit trails for data provenance are emerging as a procurement differentiator for sponsors facing intensified regulatory scrutiny.
Industry Challenges
- Interoperability standard fragmentation:FHIR implementation variations across health systems force costly custom integration engineering for each new data partner.
- Match rate validation complexity:Demonstrating 95%+ accuracy in probabilistic linkage requires ground-truth datasets that remain scarce for rare disease populations.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Real World Evidence Linkage Services Market Trends and Innovations
Machine learning architectures are actively restructuring how patient records are matched and validated, compressing processing timelines while raising accuracy thresholds that reshape competitive differentiation among service providers.
Probabilistic matching algorithms augmented by neural network embeddings are overtaking traditional deterministic rules-based approaches in large-scale linkage operations. Contract research organizations deploying these systems report reduced manual review overhead for ambiguous record pairs. The structural consequence is a compression of project timelines from months to weeks for million-patient cohort assembly.
EMA's DARWIN EU network implementation is tightening data quality and metadata requirements for evidence submitted through its distributed analytics platform. Pharmaceutical sponsors must now demonstrate algorithmic transparency and reproducibility in their linkage methodologies. Oncology and rare disease therapeutic areas face the steepest compliance ramps given smaller sample sizes and higher match accuracy requirements.
Outcome-based contracting for evidence generation services is displacing traditional time-and-materials arrangements in sponsor-vendor relationships. Biotechnology companies with limited internal data science capacity are bundling linkage, analytics, and regulatory formatting into fixed-fee deliverables. This shift is most pronounced in the United States, where integrated payer-provider networks enable clearer attribution of evidence value to coverage decisions.
Real World Evidence Linkage Services Market Segmentation
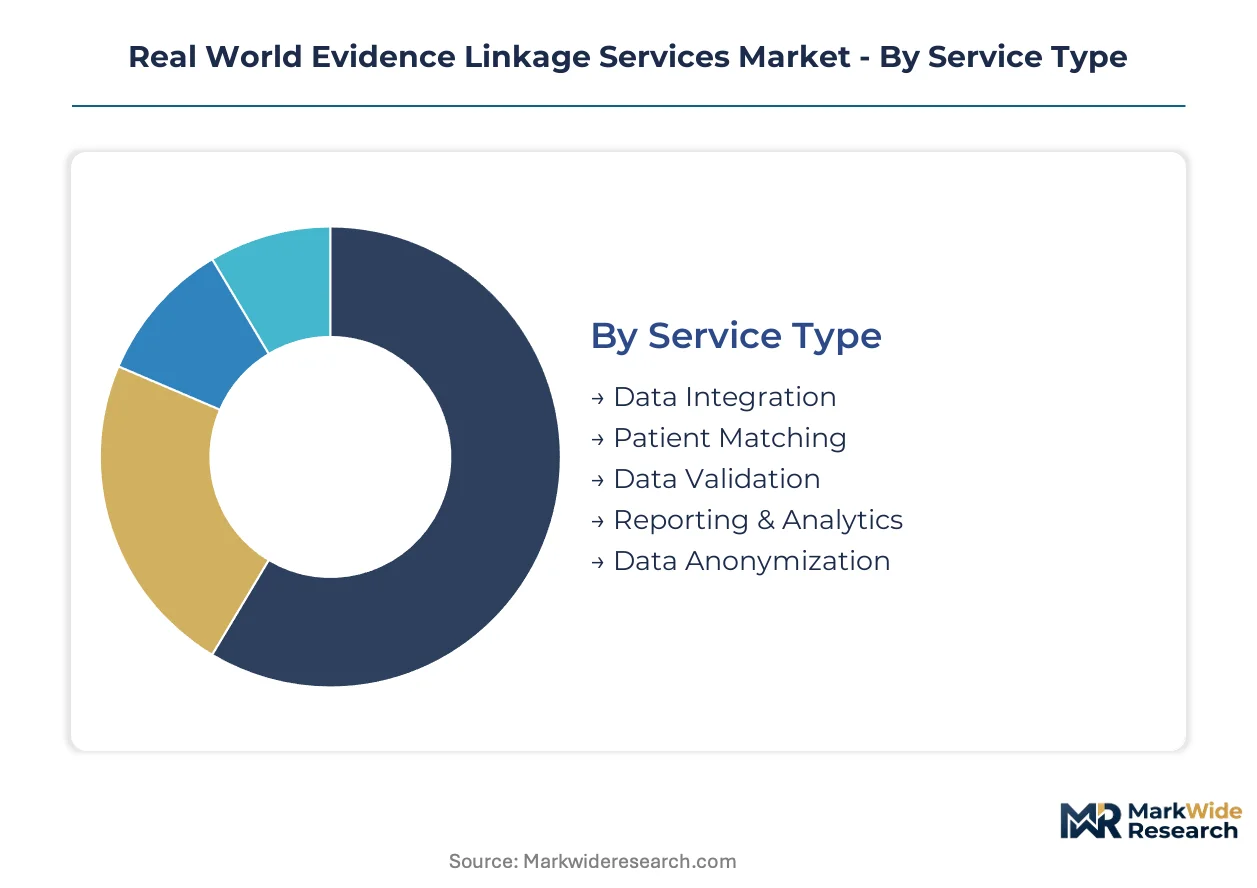
Service differentiation in real world evidence linkage reflects divergent capital requirements across technical infrastructure, specialized talent, and regulatory compliance layers. Procurement patterns increasingly favor integrated platforms that bundle multiple service tiers rather than point solutions.
Service Type:
Data Integration commands the heaviest upfront infrastructure investment, requiring federated data architecture and persistent compute resources for multi-source harmonization.
- Data Integration:Foundational pipeline engineering connecting EHR, claims, pharmacy, and mortality registries through standardized terminologies. Pharmaceutical manufacturers in the United States drive procurement for integrated delivery network partnerships. EHR maturation across integrated delivery networks enables deterministic matching at population scale.
- Patient Matching:Probabilistic and deterministic algorithms for longitudinal patient identity resolution across fragmented data sources. Demand concentrates among contract research organizations assembling external control arms for regulatory submissions. FDA-validated match rate thresholds above 95% accuracy impose specialized biostatistical talent costs.
- Data Validation:Quality assurance protocols ensuring completeness, consistency, and timeliness of linked datasets. Public health agencies utilize these services for surveillance-grade evidence requirements.
- Reporting & Analytics:Biostatistical analysis and regulatory-formatted evidence packages for HTA and payer submissions. Premium pricing reflects scarce expertise in FDA and EMA submission formatting.
- Data Anonymization:Privacy-preserving transformation techniques maintaining analytical utility while satisfying HIPAA and GDPR constraints. European Health Data Space preparation is accelerating procurement.
Data Integration absorbs the bulk of installed capacity; Patient Matching is expanding most quickly.
Technology:
Technology selection follows application complexity, with machine learning architectures requiring substantial GPU infrastructure and specialized model development expertise.
- Machine Learning:Neural network embeddings for probabilistic matching and outcome prediction. Neural architectures compress million-patient cohort assembly from months to weeks. Biotechnology companies with limited internal data science capacity are bundling ML-powered linkage into fixed-fee deliverables.
- Natural Language Processing:Unstructured clinical narrative extraction and coding for phenotyping and endpoint capture. Oncology-specific NLP workflows differentiate specialized vendors from generalized competitors.
- Blockchain:Immutable audit trails for data provenance certification under intensified regulatory scrutiny. HealthVerity navigates FDA and EMA requirements through blockchain-anchored lineage.
- Cloud Computing:Scalable distributed infrastructure for federated analytics and secure multi-party computation. Privacy-preserving computation costs limit deployment to well-capitalized enterprise buyers.
- Data Encryption:Cryptographic protection for data at rest and in transit across organizational boundaries. GDPR restrictions on European health data movement elevate encryption requirements for cross-border transfers.
Machine Learning captures the largest share of new technology investment; Blockchain is climbing the fastest amid provenance compliance demands.
Use Case:
Use case prioritization reflects regulatory pressure gradients, with pharmacovigilance and regulatory submissions commanding premium pricing due to compliance urgency.
- Clinical Outcome Analysis:Comparative effectiveness research using real-world treatment patterns and outcomes. Flatiron Health specializes in oncology-specific longitudinal tracking for immuno-oncology monitoring.
- Pharmacovigilance:Post-market safety surveillance across distributed health data sources. Safety monitoring obligations under FDA and EMA guidelines drive longitudinal patient tracking demand.
- Health Economics Research:Cost-effectiveness and budget impact modeling for payer and HTA negotiations. IQVIA leverages global data assets for multi-territory value demonstration.
- Market Access Studies:Evidence generation supporting reimbursement and formulary placement. Outcome-based contracting is displacing time-and-materials arrangements in sponsor-vendor relationships.
- Regulatory Submissions:FDA and EMA-compliant evidence packages for accelerated approval pathways. Aetion positions its platform around FDA-validated analytics methodologies for coverage decisions.
Pharmacovigilance holds the deepest incumbent investment; Regulatory Submissions is gaining share fastest under 21st Century Cures Act mandates.
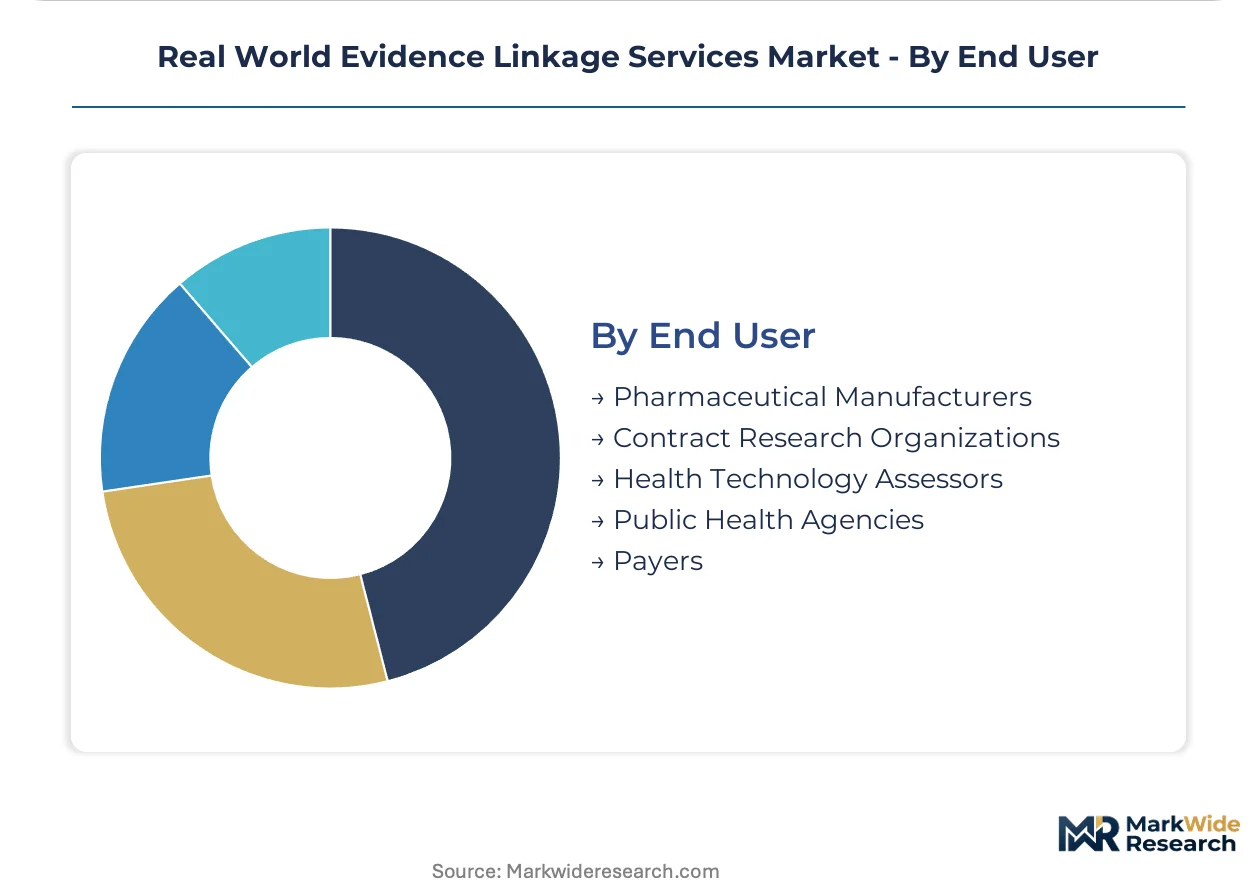
End User:
End user segmentation reveals divergent procurement sophistication, with pharmaceutical manufacturers consolidating vendor relationships while smaller buyers seek bundled outsourcing.
- Pharmaceutical Manufacturers:Integrated drug sponsors with internal RWE capabilities and direct regulatory accountability. Consolidation around platforms capable of FDA-validated analytics and EMA-compliant data provenance is compressing procurement timelines.
- Contract Research Organizations:Outsourced service providers assembling evidence for sponsor clients. CROs are pivoting toward broader linkage capabilities to capture expanded sponsor outsourcing.
- Health Technology Assessors:Evidence evaluation bodies requiring standardized analytical outputs for reimbursement decisions. NICE, ICER, and similar bodies drive formatting standardization requirements.
- Public Health Agencies:Government surveillance and population health monitoring programs. CDC and ECDC utilization focuses on rare disease and safety signal detection.
- Payers:Insurance and pharmacy benefit managers utilizing RWE for coverage policy and formulary management. Optum anchors offerings through deep integration with UnitedHealth Group infrastructure.
Pharmaceutical Manufacturers dominate current procurement volume; Contract Research Organizations are scaling fastest as sponsors externalize linkage capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical manufacturers in the United States command the largest procurement volumes for linkage services, while European sponsors navigate stricter data governance frameworks. The analysis identifies five countries where regulatory-grade evidence generation concentrates.
United States
Integrated payer-provider networks and mature electronic health record infrastructure enable deterministic matching at population scale. FDA's 21st Century Cures Act mandates expanded real-world evidence use in regulatory submissions, compressing vendor qualification timelines. Greater Boston and the San Francisco Bay Area host dense clusters of biotechnology sponsors outsourcing linkage capabilities to specialized platforms.
Germany
Health technology assessors at IQWiG drive demand for standardized analytical outputs supporting reimbursement negotiations. EMA's DARWIN EU network implementation tightens data provenance requirements for sponsors submitting through distributed analytics platforms. The Rhine-Ruhr metropolitan region concentrates contract research organizations scaling linkage operations for pan-European trials.
United Kingdom
NICE evaluations require regulatory-formatted evidence packages that command premium pricing from vendors with submission expertise. NHS Digital's infrastructure investments in federated analytics are opening procurement pathways for privacy-preserving record linkage. London anchors the largest concentration of health economics consultancies bundling linkage and analytics services.
Switzerland
Swissmedic's alignment with EMA standards positions the country as a gateway for sponsors seeking streamlined European regulatory pathways. Roche and Novartis headquarters drive substantial internal and outsourced evidence generation demand. The Basel metropolitan area concentrates pharmaceutical data science operations spanning clinical development and post-market surveillance.
Japan
PMDA's evolving real-world evidence guidelines are prompting domestic sponsors to invest in compliant linkage infrastructure for accelerated approval pathways. The country's universal health insurance claims database offers longitudinal tracking capabilities rare in Asian markets. Tokyo and Osaka metropolitan areas host the principal clusters of contract research organizations building linkage competencies for oncology and rare disease trials.
Real World Evidence Linkage Services Market Competitive Landscape
United States-based platforms anchor one tier through deep integration with payer and provider infrastructure; European specialists hold differentiated positions around EMA compliance and data governance capabilities. The vendor base organizes into three tiers: integrated data asset owners, disease-domain specialists, and emerging federated analytics platforms. Two strategic archetypes dominate competitive positioning—horizontal scale players leveraging global data networks versus vertical specialists concentrating on therapeutic-area workflows. Consolidation pressures are compressing procurement timelines, while outcome-based contracting arrangements are displacing traditional time-and-materials relationships.
Within the integrated data asset tier, IQVIA and Optum exemplify scale-driven positioning through captive infrastructure and network effects. Flatiron Health occupies a specialist position representing the disease-domain archetype, with its platform exemplifying oncology-specific workflow differentiation. These three entities illustrate the structural split between horizontal breadth and vertical depth that characterizes competitive dynamics across procurement negotiations.
| Leading Market Players |
|---|
| IQVIA |
| Optum |
| Merative |
| Flatiron Health |
| TriNetX |
| Veradigm |
| Aetion |
| HealthVerity |
| Oracle |
| Others |
Pricing and Supply Chain Analysis
Biostatistician compensation premiums flow downstream through project-based pricing tiers, with FDA-validated match rate thresholds above 95% accuracy separating premium regulatory-grade contracts from standard data integration engagements. Privacy-preserving computation infrastructure costs concentrate in cloud computing and federated analytics deployments, compressing margins for vendors serving mid-cap biotechnology sponsors while integrated platforms serving pharmaceutical manufacturers capture pricing power through captive UnitedHealth Group and IQVIA network infrastructure.
Pricing Analysis
Volume concentrates in Data Integration services absorbing foundational infrastructure investments, while margin accretion clusters in Reporting and Analytics where biostatistical expertise and customized FDA and EMA submission formatting command premium positioning. Price differentiation separates certified regulatory-grade packages from standard analytical outputs, with FDA-validated methodologies and blockchain-anchored data lineage certification driving tier stratification. Pricing pressure stems from outcome-based contracting displacing time-and-materials arrangements, compressing realized rates for biotechnology companies bundling linkage and analytics into fixed-fee deliverables. Contract research organizations exhibit highest price sensitivity due to sponsor pass-through constraints; pharmaceutical manufacturers with direct regulatory accountability demonstrate lowest sensitivity to secure compliant provenance documentation.
Supply Chain Analysis
GPU infrastructure supply for machine learning model training rests on NVIDIA and AMD semiconductor fabrication concentrated in Taiwan and South Korea, with cloud computing capacity expansion tethered to hyperscaler data center buildouts across the United States, Germany, and United Kingdom. Raw material dependencies span specialized biostatistical talent pools, deterministic matching algorithm licenses, and FHIR interoperability middleware. Supply chain risk centers on single-source vulnerability in neural network embedding frameworks and scarce ground-truth validation datasets for rare disease populations. Distribution runs through direct enterprise sales to pharmaceutical manufacturers and health technology assessors, with channel partnerships through contract research organizations capturing mid-market biotechnology demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized biostatistician scarcity props pricing across all service tiers, with FDA-validated match rate thresholds above 95% accuracy functioning as the binding capacity constraint compressing vendor expansion timelines.
For Market Incumbents: To counter outcome-based contracting compression, anchor platform differentiation through blockchain-anchored data lineage certification and deepen integration with UnitedHealth Group or IQVIA captive infrastructure. Prioritize certification investment in EMA DARWIN EU network compliance to preempt procurement consolidation around provenance-qualified vendors.
For New Entrants and Emerging Players: Cloud-native federated analytics platforms offer the most penetrable entry vector for mid-cap biotechnology sponsors seeking bundled linkage and regulatory formatting without legacy infrastructure overhead. Target oncology-specific workflow specialization where Flatiron Health's vertical concentration leaves whitespace for immuno-oncology combination therapy monitoring tools. Pursue partnership-first go-to-market positioning with contract research organizations scaling external control arm assembly capabilities.
For Investors and Strategic Acquirers: European Health Data Space regulation finalization is the leading indicator that federated linkage infrastructure demand will accelerate across EU member state repositories. Five-to-ten year viability favors platforms combining disease-domain expertise with regulatory compliance certification over pure-play data integration vendors. Acquisition target archetype: specialized oncology or rare disease workflow vendors with FDA-validated methodologies and existing EMA submission track records. Monitor EMA DARWIN EU network procurement timelines as the inflection signal for provenance-compliance premium realization.
| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain-Anchored Data Lineage Certification | Immutable audit trails satisfy intensified FDA and EMA provenance scrutiny, differentiating vendor qualification. |
| Oncology-Specific Workflow Specialization | Complex immuno-oncology longitudinal tracking commands premium pricing from sponsors facing combination therapy evidence requirements. |
| Federated Analytics Platform Expansion | Privacy-preserving computation enables GDPR-compliant cross-border cohort assembly for multinational trial sponsors. |
| Outcome-Based Contracting Transition | Fixed-fee deliverables align vendor incentives with biotechnology sponsor value demonstration needs. |
| EMA DARWIN EU Network Compliance Investment | Algorithmic transparency and reproducibility certification opens procurement pathways for distributed analytics platform submissions. |
Research Methodology
Independent corroboration across pharmaceutical manufacturer RWE strategy leads, contract research organization evidence generation directors, and health technology assessor analytical methodology specialists underwrites the qualitative findings. Secondary validation drew from FDA real-world evidence guidance documents, EMA DARWIN EU network implementation specifications, ClinicalTrials.gov registry entries, and ONC interoperability mandate filings. Bottom-up service tier sizing and top-down pharmaceutical R&D expenditure allocation triangulate market dimension estimates.
Rate-of-change decomposition across the analysis window segments expansion by service type, technology deployment, use case regulatory pressure gradient, and end user procurement sophistication. Modeled dimensions span Data Integration through Data Anonymization service tiers, Machine Learning through Data Encryption technology categories, Clinical Outcome Analysis through Regulatory Submissions use cases, and Pharmaceutical Manufacturers through Payers end user segments. CAGRs derive from pharmaceutical manufacturer outsourcing velocity, EMA and FDA submission volume trends, and electronic health record maturation trajectories across integrated delivery networks.
Inputs from primary stakeholder interviews and secondary regulatory filings were available through the study window; gaps in rare disease ground-truth validation dataset availability introduce uncertainty bands around probabilistic match rate accuracy claims. Forecasts reflect assumptions regarding European Health Data Space implementation timelines and FDA 21st Century Cures Act enforcement consistency. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.