
 Preclinical CRO Market | 2026-2036
Preclinical CRO Market Size, Share, and Industry Trends Forecast 2026-2036
Preclinical CRO Market Analysis
EU REACH chemical safety mandates and FDA Good Laboratory Practice enforcement is consolidating quality expectations across outsourced preclinical programs. Charles River Laboratories anchors North American toxicology capacity through extensive vivarium networks. WuXi AppTec leverages integrated chemistry and biology platforms to capture sponsor workflows from target validation through IND filing. Lonza differentiates its position with specialized biologics safety assessment capabilities in European and Asian facilities.
Preclinical CRO services encompass outsourced pharmacology, toxicology, pharmacokinetic, and bioanalytical evaluation of drug candidates before human clinical trials, typically requiring species-specific in vivo protocols, GLP-compliant study conduct, and histopathological endpoints to generate regulatory submission data. The service portfolio generates revenue through toxicology studies and bioanalysis, where long-duration carcinogenicity and reproductive assessments command premium pricing due to specialized pathology expertise and extended facility occupancy. Animal models and imaging technologies represent expanding technology segments as sponsors demand translational biomarkers and non-invasive efficacy readouts to de-risk later-stage development.
FDA, EMA, and OECD GLP frameworks mandate standardized documentation, facility inspection, and personnel qualification for preclinical data accepted in New Drug Applications, directly shaping CRO accreditation requirements and sponsor vendor selection criteria. China's NMPA and Japan's PMDA impose additional regional study acceptance rules that fragment compliance architectures for multinational programs. Sponsors must evaluate CRO partners against evolving regulatory inspection frequencies and cross-border data transfer restrictions as portfolio complexity intensifies.
Market Dynamics
GLP data integrity enforcement from FDA and EMA is compressing vendor qualification timelines while biotech sponsors consolidate testing volumes toward accredited facilities with proven inspection histories. This regulatory tightening is accelerating market concentration around large-platform CROs capable of sustaining multi-year certification investments.
Growth Catalysts
- EMA Good Laboratory Practice harmonization:Cross-border study acceptance rules are reducing redundant testing for sponsors running parallel US-EU submission strategies.
- Biologics pipeline expansion:Cell and gene therapy developers require species-specific immunotoxicology expertise that in-house labs rarely maintain.
- China NMPA study acceptance reforms:Multinational sponsors now route Asian-market filings through domestic Chinese facilities rather than duplicating protocols elsewhere.
Market Restraints
- Primate supply concentration:Cambodia and Mauritius source restrictions are creating procurement bottlenecks for reproductive toxicology programs.
- Histopathologist scarcity:Specialized veterinary pathologist training programs produce insufficient graduates to staff expanding carcinogenicity study demand.
- Facility certification lag:OECD GLP inspectorate backlogs extend new vivarium accreditation timelines beyond sponsor pipeline urgency.
Strategic Opportunities
- India CDSCO pathway alignment:Domestic toxicology capacity remains underdeveloped relative to growing sponsor interest in local IND submissions.
- Organ-on-chip convergence:Microphysiological systems paired with traditional in vivo protocols are creating hybrid validation service lines.
- Japan PMDA nonclinical data reciprocity:Streamlined study acceptance for foreign-generated data reduces redundant testing for Asia-Pacific market entry.
Industry Challenges
- GLP auditor retention:Qualified study directors command premium compensation as sponsor audit frequency intensifies.
- Legacy data system migration:Paper-based archive facilities face multi-year digitization timelines to meet real-time regulatory inspection demands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Preclinical CRO Market |
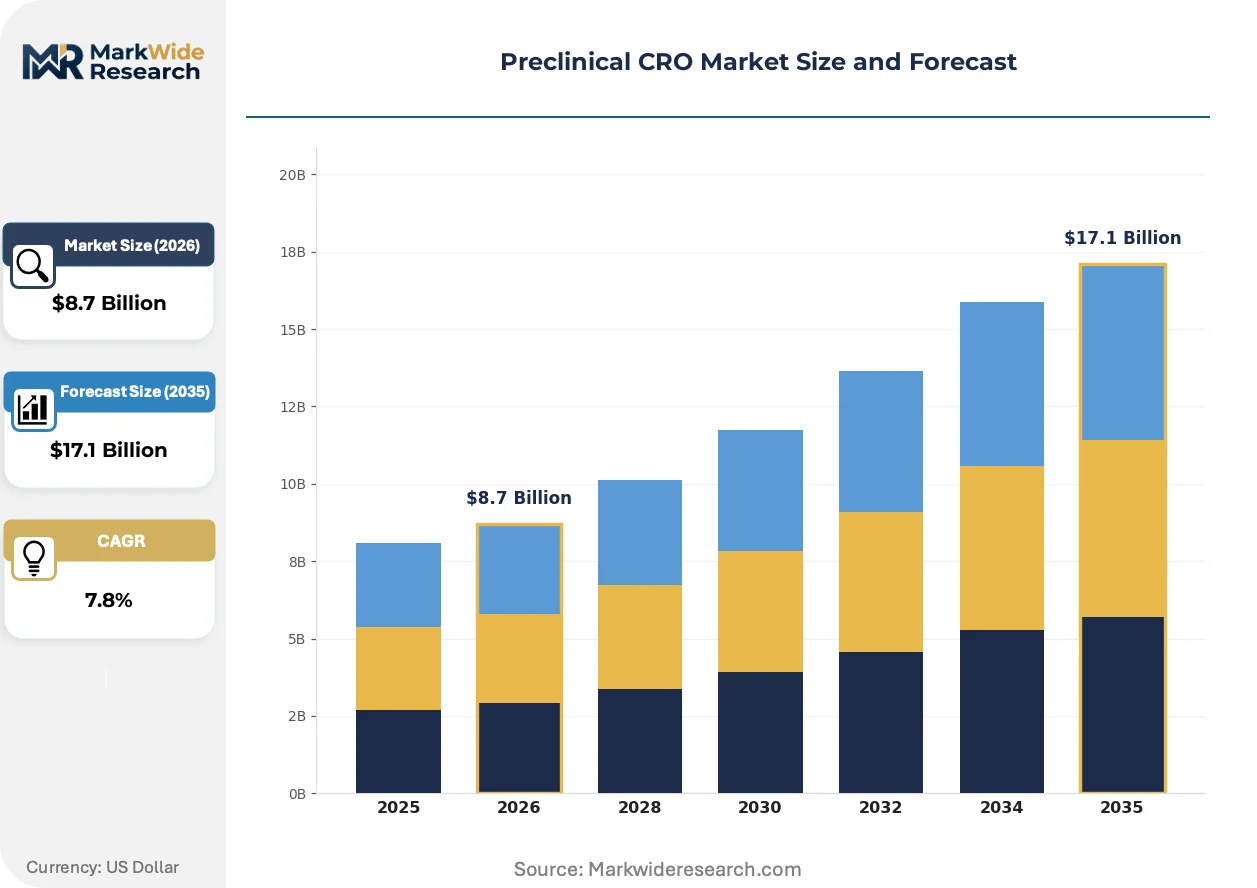
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Bioanalysis, Toxicology Studies, Pharmacokinetics, Study Management Technology: In Vitro Models, Animal Models, Imaging Technologies, Assay Development End User: Pharmaceutical Companies, Biotech Firms, Academic Institutions, Government Agencies Application: Drug Discovery, Efficacy Testing, Safety Assessment, Regulatory Support |
| Companies Covered | Eurofins Scientific, ICON plc, Charles River Laboratories International, Thermo Fisher Scientific, Medpace Holdings, Laboratory Corporation of America, Lonza, Inotiv, WuXi AppTec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Preclinical CRO Market Emerging Trajectories
Preclinical workflows are absorbing computational and biological tool convergence that compresses study timelines while expanding endpoint sensitivity. These shifts are redrawing capability boundaries between CRO tiers and sponsor in-house functions.
Artificial intelligence pathology platforms are automating quantitative histomorphometry and lesion detection across rodent and non-rodent tissues. Large CROs deploy these tools to accelerate peer review cycles and reduce inter-pathologist variability. The technology is automating routine screening tasks while reallocating senior pathologist attention toward complex mechanistic interpretation.
FDA's enhanced data integrity guidance is mandating audit trail completeness and raw data accessibility for electronic capture systems. Sponsors now disqualify CROs with fragmented legacy informatics architectures. Small and mid-size toxicology providers face capital-intensive compliance upgrades or strategic exit.
Sponsor procurement teams are unbundling long-term master service agreements into modular statement-of-work contracts tied to discrete study milestones. Biotech companies favor this structure to preserve cash runway flexibility. The pattern is most pronounced among venture-backed sponsors in Massachusetts and California clusters.
Preclinical CRO Market Segmentation
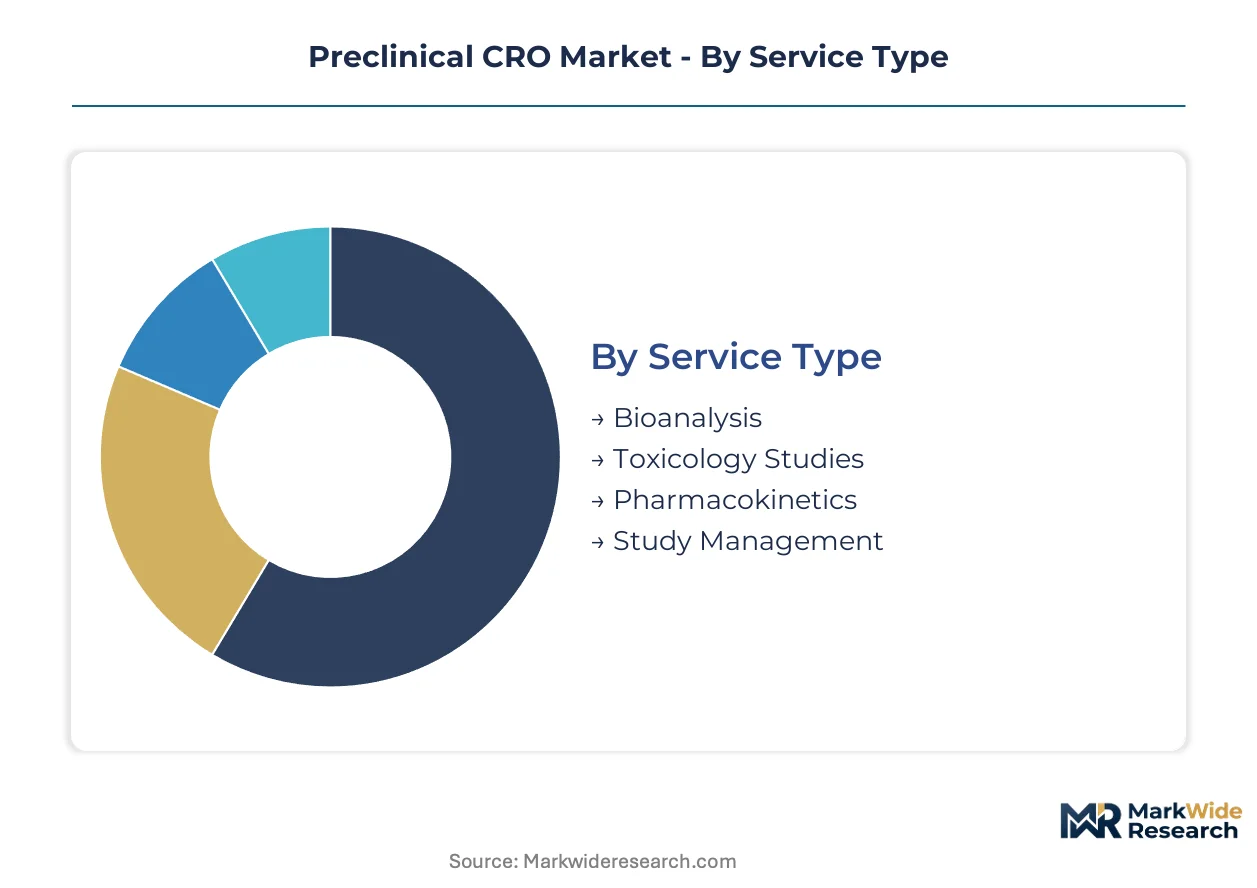
Preclinical CRO procurement decisions hinge on therapeutic modality, regulatory pathway complexity, and the availability of species-specific expertise. Sponsors match service configurations to development stage, with early discovery programs prioritizing flexibility and IND-enabling studies demanding accredited GLP infrastructure.
Service Type:
Buyers segment contracts primarily by study duration and pathology intensity, with carcinogenicity and reproductive toxicology commanding premium pricing due to extended facility occupancy and specialized expertise requirements.
- Toxicology Studies:These encompass acute, subchronic, and chronic safety assessments across rodent and non-rodent species, requiring GLP-compliant protocols and histopathological endpoints. Demand concentrates in the United States and China as sponsors seek large-animal facilities with proven FDA and NMPA inspection histories for IND and NDA submissions.
- Bioanalysis:Quantitative measurement of drug concentrations and biomarkers in biological matrices supports pharmacokinetic modeling and regulatory filings. Biotech firms in Massachusetts and California clusters favor modular contracts for bioanalytical services to preserve cash runway flexibility during early development.
- Pharmacokinetics:ADME characterization and drug-drug interaction studies generate data for dosing regimen design.
- Study Management:Program oversight, regulatory submission preparation, and vendor coordination functions for integrated preclinical campaigns.
Volume sits with Toxicology Studies; growth tilts toward Bioanalysis as biologics pipelines expand and immunogenicity testing demands intensify.
Technology:
Technology selection tracks the convergence of computational tools with biological systems, where sponsors evaluate platforms based on translational validity and regulatory acceptability.
- Animal Models:Species-specific in vivo protocols remain the regulatory gold standard for safety assessment, with primate and canine models essential for biologics immunotoxicology. Procurement bottlenecks in Cambodia and Mauritius source restrictions are constraining reproductive toxicology program timelines.
- Imaging Technologies:Non-invasive efficacy readouts including MRI, PET, and optical imaging enable longitudinal biomarker tracking and reduce animal usage. Cell and gene therapy developers in Basel and Boston metropolitan areas are driving adoption for translational de-risking.
- In Vitro Models:Cell-based assays and organ-on-chip systems support early mechanistic screening.
- Assay Development:Custom analytical method creation for novel therapeutic modalities and biomarker quantification.
Revenue concentrates in Animal Models; capability investment is climbing fastest in Imaging Technologies as sponsors demand real-time efficacy monitoring.
End User:
Customer type determines contract structure, with large pharmaceutical sponsors favoring multi-year master service agreements and emerging biotechs preferring milestone-based engagements.
- Biotech Firms:Venture-backed developers outsource early-stage drug evaluation to extend cash runway and access specialized toxicology expertise rarely maintained in-house. These sponsors are unbundling traditional agreements into discrete statement-of-work contracts tied to specific study milestones.
- Pharmaceutical Companies:Established sponsors consolidate testing volumes toward accredited facilities with proven inspection histories as FDA and EMA data integrity enforcement intensifies. Internal capacity constraints on cell and gene therapy safety assessment are driving externalization.
- Academic Institutions:Non-commercial research programs requiring GLP-compliant study conduct for investigator-initiated trials.
- Government Agencies:Public health and defense-related toxicology and efficacy evaluation contracts.
Contract value concentrates with Pharmaceutical Companies; sponsor expansion is occurring fastest among Biotech Firms as cell and gene therapy pipelines mature.
Application:
Application scope aligns with regulatory submission requirements, where safety assessment and regulatory support generate recurring revenue while discovery services exhibit higher churn.
- Safety Assessment:GLP toxicology and safety pharmacology studies generate regulatory submission data for INDs, NDAs, and BLAs. FDA and EMA guideline tightening on data integrity is compressing vendor qualification timelines toward facilities with sustained certification investments.
- Drug Discovery:Target validation, lead optimization, and early pharmacology screening support pipeline replenishment. Integrated chemistry and biology platforms in Shanghai and San Diego are capturing sponsor workflows from target identification through candidate nomination.
- Efficacy Testing:Disease model characterization and proof-of-concept pharmacology for mechanism validation.
- Regulatory Support:Submission preparation, agency interaction, and compliance consulting for multinational filing strategies.
Revenue stability sits with Safety Assessment; service line expansion is gaining share fastest in Drug Discovery as artificial intelligence pathology platforms compress study timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston and San Francisco anchor North American preclinical CRO activity, while Basel, Shanghai, and Cambridge UK form complementary concentration nodes across Europe and Asia-Pacific.
United States
FDA GLP enforcement and biotech venture funding concentrate demand in Massachusetts and California corridors. Charles River Laboratories maintains extensive vivarium networks across the Northeast and Mid-Atlantic. Greater Boston sponsors increasingly unbundle master service agreements into milestone-based contracts to preserve cash runway.
China
NMPA study acceptance reforms and domestic biologics pipeline expansion drive facility investment in Shanghai and Suzhou. WuXi AppTec leverages integrated chemistry and biology platforms to capture sponsor workflows from target validation through IND filing. Yangtze River Delta CROs now handle multinational sponsor filings previously routed through Singapore or Australia.
Germany
EMA REACH chemical safety mandates and specialized biologics toxicology demand support facility expansion in Baden-Württemberg and Bavaria. Lonza differentiates its European position with cell and gene therapy safety assessment capabilities. Basel-area sponsors route immunotoxicology programs through southern German facilities to access large-animal expertise.
Switzerland
Swissmedic GLP reciprocity agreements and biologics headquarters concentration create outsourcing demand in Basel and Zurich metropolitan areas. Roche and Novartis vendor qualification programs compress CRO selection timelines toward accredited facilities with sustained inspection histories. The Basel biotech cluster increasingly demands real-time imaging endpoints for translational de-risking.
United Kingdom
MHRA post-Brexit data acceptance rules and Cambridge-Oxford biotech corridor expansion sustain CRO demand in southeast England. Academic spinouts from Imperial College London and University of Cambridge increasingly outsource early pharmacology screening to preserve internal capacity for later-stage assets. London-based venture funds favor modular contracting structures for portfolio company preclinical programs.
Preclinical CRO Market Vendor Landscape
Premium-margin players sit above commodity-margin players across GLP certification depth and pathology specialization depth. Large-platform CROs capable of sustaining multi-year certification investments capture sponsor consolidation toward accredited facilities. Three archetypes dominate: integrated platform providers spanning chemistry through IND filing, specialized toxicology houses with species-specific expertise, and regional niche players serving domestic regulatory pathways. Competitive moves center on M&A for pathology talent acquisition and vivarium capacity expansion in primate-accessible jurisdictions.
Within the integrated platform tier, Charles River Laboratories and WuXi AppTec exemplify scale-driven positioning across North American and Asian markets respectively. Lonza occupies a specialist position anchored in European biologics safety assessment. Eurofins Scientific represents the analytical services extension archetype, while ICON plc and Medpace Holdings sit within the clinical-preclinical convergence segment. Thermo Fisher Scientific, Laboratory Corporation of America, and Inotiv each anchor distinct competitive vectors across laboratory equipment integration, diagnostic-adjacent toxicology, and mid-scale specialized services.
| Leading Market Players |
|---|
| Eurofins Scientific |
| ICON plc |
| Charles River Laboratories International |
| Thermo Fisher Scientific |
| Medpace Holdings |
| Laboratory Corporation of America |
| Lonza |
| Inotiv |
| WuXi AppTec |
| Others |
Supply Flow & Price Mechanics
Veterinary pathologist concentration in the United States and Western Europe creates labor-cost differentials that stratify pricing tiers across GLP-accredited and non-accredited facilities. Sponsors purchasing carcinogenicity and reproductive toxicology studies face premium spreads reflecting histopathologist scarcity and extended facility occupancy requirements.
Pricing Analysis
Outcome-based pricing anchored to regulatory submission success commands premium multiples over standard per-study contracting. Pricing stratifies across FDA-inspected, OECD GLP-accredited, and non-certified facility tiers based on audit trail completeness and raw data accessibility. Cost compression in mid-tier toxicology services is intensifying as biotech sponsors consolidate volumes toward large-platform CROs with sustained certification investments. Venture-backed developers in Massachusetts and California clusters exhibit highest price sensitivity, favoring modular milestone-based contracts over master service agreements.
Supply Chain Analysis
Primate supply rests on Cambodian and Mauritian breeding facilities, with Chinese and Southeast Asian vivarium networks expanding to capture NMPA study demand. Critical inputs span purpose-bred canines, genetically engineered rodent strains, and specialized histopathology reagents. Single-source vulnerability in non-human primate procurement creates reproductive toxicology program bottlenecks when export restrictions activate. Distribution runs through direct sponsor-CRO contracting for IND-enabling studies, with regional hub models emerging for multi-site toxicology campaigns.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The preclinical CRO market functions as a cost-of-compliance story where FDA and EMA GLP data integrity enforcement erects barrier-to-entry moats favoring accredited incumbents with sustained inspection histories.
For Market Incumbents: To counter sponsor procurement unbundling into discrete milestone contracts, large-platform CROs should deepen pathology talent retention through equity-linked compensation structures and expand primate-accessible vivarium capacity in NMPA-inspected jurisdictions. Certification investment in real-time data capture systems preserves vendor qualification advantages as FDA audit trail requirements tighten. For New Entrants and Emerging Players: Digital-channel routes through AI pathology platform licensing offer lower-capital entry points than full GLP infrastructure buildout. White-space targets include hybrid organ-on-chip validation services for cell and gene therapy developers and modular bioanalytical contracts for Massachusetts and California biotech clusters. A specialist positioning in immunotoxicology for biologics pipelines avoids direct competition with integrated platform incumbents. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale toxicology specialists possessing OECD GLP accreditation and primate supply agreements, given sponsor consolidation toward accredited facilities. Long-term viability across the analysis window favors targets with digitized archive systems and multi-regulatory inspection histories. The signal to watch is NMPA study acceptance reform pace, which would accelerate valuation premiums for China-based GLP infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| GLP Certification Investment | FDA and EMA inspection readiness secures sponsor vendor qualification for IND-enabling studies. |
| Primate Facility Expansion | Cambodia and Mauritius supply agreements de-risk reproductive toxicology program timelines. |
| AI Pathology Platform Deployment | Automated histomorphometry accelerates peer review cycles and reduces inter-pathologist variability. |
| Modular Contract Structuring | Milestone-based engagements preserve cash runway flexibility for venture-backed biotech sponsors. |
| Multi-Regional Accreditation | NMPA, FDA, and EMA inspection histories capture parallel US-EU-Asia submission strategies. |
Methodological Framework
Document review covered FDA 483 inspection observations, EMA GLP compliance reports, and OECD mutual acceptance of data agreements, complemented by interviews with preclinical study directors, regulatory affairs leads at biotech sponsors, veterinary pathologists, and CRO procurement officers. Secondary validation drew from ClinicalTrials.gov IND filings, NMPA drug approval databases, SEC 10-K disclosures from publicly traded CROs, and trade data on laboratory animal imports. Bottom-up service line revenue estimates triangulated against top-down pharmaceutical R&D outsourcing expenditure trends.
Segment-level outputs across toxicology studies, bioanalysis, and pharmacokinetics were modeled over the projection horizon, with therapeutic modality splits for small molecules, biologics, and cell and gene therapies. CAGRs were derived from sponsor pipeline forecasts, facility capacity expansion announcements, and regulatory inspection frequency trends. Industry-specific inputs included primate supply constraints, histopathologist graduation rates from veterinary schools, and GLP inspectorate backlog durations.
The model holds under sustained FDA and EMA data integrity enforcement; deviation in NMPA study acceptance reciprocity or primate export restriction severity would shift regional demand patterns. Forecasts reflect assumptions on certification investment continuity and sponsor outsourcing rate trajectories. A small set of triggers—primate supply disruption, GLP auditor compensation inflation, and organ-on-chip regulatory acceptance timelines—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Research
Clinical Trial Logistics and Direct-to-Patient Delivery Platforms Market
Clinical Research
Europe Clinical Trials Market
Clinical Research
Atopic Dermatitis Clinical Trials Market
Clinical Research
Generative AI in Clinical Trials Market
Clinical Research
Patient-Reported Outcome Data Monetization Market
Clinical Research
Clinical Data Analytics Market
Clinical Research
AI-Assisted Clinical Trial Protocol Design Market
Clinical Research
Early Phase Clinical Trial Outsourcing Market
Clinical Research
Clinical Trials Outsourcing Market
Clinical Research
US Virtual Clinical Trials Market
Clinical Research
Pharmacovigilance Outsourcing Market
Clinical Research
India CRO Market
Clinical Research
AI-Based Clinical Trial Solutions for Patient Matching Market
Clinical Research
Clinical Trial Investigative Site Network Market
Clinical Research
Global in Silico Clinical Trials Market
Clinical Research
Humanized Mice Model Market