
 North America Clinical Trials Market | 2026-2036
North America Clinical Trials Market Size, Share, and Industry Trends Forecast 2026-2036
North America Clinical Trials Market Outlook
Asset-light contract structures and site-less trial financing is narrowing the competitive field for mid-sized contract research organizations. IQVIA leverages its integrated data backbone and site network to sustain dominance across Phase II-III oncology studies. ICON plc anchors its position through therapeutic specialization in rare diseases and complex biologics. Charles River Laboratories differentiates with laboratory services bundled into early-stage development programs.
Clinical trials constitute systematically designed biomedical investigations that evaluate safety, efficacy, and pharmacokinetic profiles of investigational drugs, devices, or biologics in human subjects under controlled protocols with predefined endpoints, randomization, and regulatory oversight. These studies generate evidence required for marketing authorization and treatment guideline formulation across healthcare systems. Oncology indications command the largest share of active protocols due to pipeline density and precision medicine biomarker complexity. Pediatric population trials represent a structurally underserved segment with orphan drug incentives and FDA pediatric exclusivity provisions expanding sponsor commitment. Government grants as a funding source face budgetary constraints while pharmaceutical company direct funding grows proportionally with internal pipeline prioritization.
FDA oversight through Investigational New Drug applications and Good Clinical Practice standards governs protocol design, patient safety monitoring, and data integrity requirements across all trials conducted in the United States. Health Canada and PMRA enforce parallel frameworks with ICH E6(R2) harmonization enabling cross-border protocol execution. Stakeholders must monitor evolving FDA guidance on artificial-intelligence-enabled endpoints and real-world evidence integration as these reshape trial design economics and regulatory submission pathways.
Market Dynamics
Decentralized trial infrastructure is compressing site dependency and redistributing clinical data capture across patient homes, retail pharmacies, and mobile nursing networks. FDA guidance on digital health technologies is accelerating protocol redesign toward remote-first methodologies.
Growth Catalysts
- Digital Health Technology Frameworks:FDA guidance on remote data capture and wearable-enabled endpoints is enabling sponsors to redesign protocols around decentralized patient monitoring. This reduces site burden while expanding geographic recruitment reach.
- Precision Medicine Biomarker Complexity:Oncology pipelines increasingly require companion diagnostic integration and genomic stratification. This complexity demands specialized North American site networks with molecular profiling capabilities.
- Orphan Drug Incentives:FDA pediatric exclusivity provisions and rare disease tax credits are expanding sponsor commitment to structurally underserved pediatric and rare disease populations.
Market Restraints
- Principal Investigator Scarcity:Qualified investigators concentrate in major academic medical centers across Boston, New York, and San Francisco. Site activation timelines stretch as sponsor competition intensifies for limited investigator bandwidth.
- Regulatory Fragmentation Across US-Canada Border:Health Canada and FDA maintain divergent requirements for digital endpoint validation. Cross-border protocol execution requires duplicate regulatory submissions and separate quality management systems.
- Laboratory Services Cost Volatility:Specialized bioanalytical testing for complex biologics depends on concentrated North American lab capacity. Pricing pressure mounts as biopharma sponsors consolidate preferred provider agreements.
Strategic Opportunities
- Site-less Trial Financing Models:Asset-light contract structures are narrowing the competitive field for mid-sized contract research organizations. New entrants can capture share by specializing in remote patient management and direct-to-patient logistics.
- Real-World Evidence Integration:FDA guidance on artificial-intelligence-enabled endpoints is creating pathways for claims-grade data from electronic health records and claims databases. This convergence of clinical and real-world data streams enables adaptive trial designs.
- Mid-Atlantic Corridor Expansion:Pennsylvania, Maryland, and North Carolina offer underserved patient populations with established research infrastructure. Sponsors can diversify beyond saturated Northeast and West Coast markets.
Industry Challenges
- Decentralized Data Integrity:Remote data capture from patient-owned devices introduces source data verification complexity. Quality assurance teams must reconcile wearable outputs with traditional electronic data capture systems.
- Specialized Talent Acquisition:Clinical data scientists with artificial intelligence and machine learning expertise command premium compensation. Trial sponsors compete with technology firms for scarce hybrid skill profiles.
- Legacy System Integration:Electronic data capture platforms from the 2010s require substantial middleware investment to interface with modern decentralized trial management systems. Technical debt slows deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Clinical Trials Market |
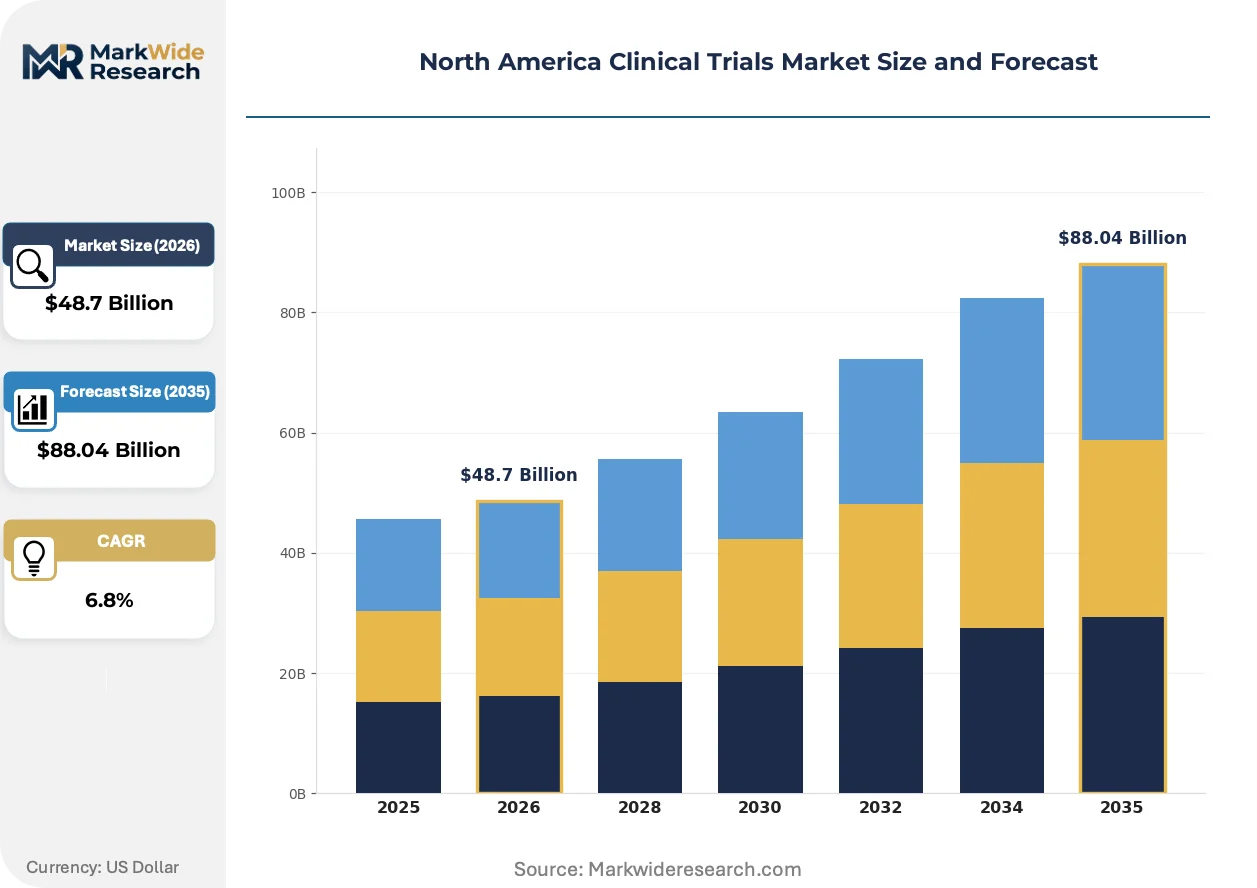
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Study Design: Randomized Controlled Trials, Observational Studies, Clinical Trials Phases, Cohort Studies Patient Type: Pediatric Population, Adult Participants, Geriatric Patients, Healthy Individuals Indication: Cardiovascular Disorders, Oncology, Neurological Conditions, Infectious Diseases Funding Source: Government Grants, Pharmaceutical Companies, Non-Profit Organizations, Academic Institutions |
| Companies Covered | IQVIA, ICON plc, Parexel International, Syneos Health, Charles River Laboratories, Medpace Holdings, WuXi AppTec, Thermo Fisher Scientific, Laboratory Corp of America Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Clinical Trials Market Strategic Shifts
Clinical trial execution is pivoting from centralized site dependency toward patient-centric models enabled by digital infrastructure. Three interconnected developments are compressing traditional operational timelines and redistributing competitive advantage.
Decentralized clinical trial platforms are migrating from pilot programs to standard deployment across Phase II-III oncology studies. Mid-sized biopharmaceutical sponsors now mandate remote monitoring capabilities in site selection criteria. This technology is migrating from early-adopter oncology indications into cardiovascular and metabolic disease protocols.
FDA guidance on digital health technologies for remote data capture is mandating protocol redesign across IND-submitted studies. The framework requires validation of patient-owned device outputs against traditional clinical assessments. Biopharmaceutical sponsors in the United States are responding by embedding digital endpoint scientists into clinical development teams.
Direct-to-patient logistics networks are displacing traditional site-based recruitment and retention models. Specialized courier services and mobile nursing providers are capturing value previously retained by academic medical centers. This channel shift is most visible in rare disease trials where geographic dispersion of patients previously limited enrollment feasibility.
North America Clinical Trials Market Segmentation
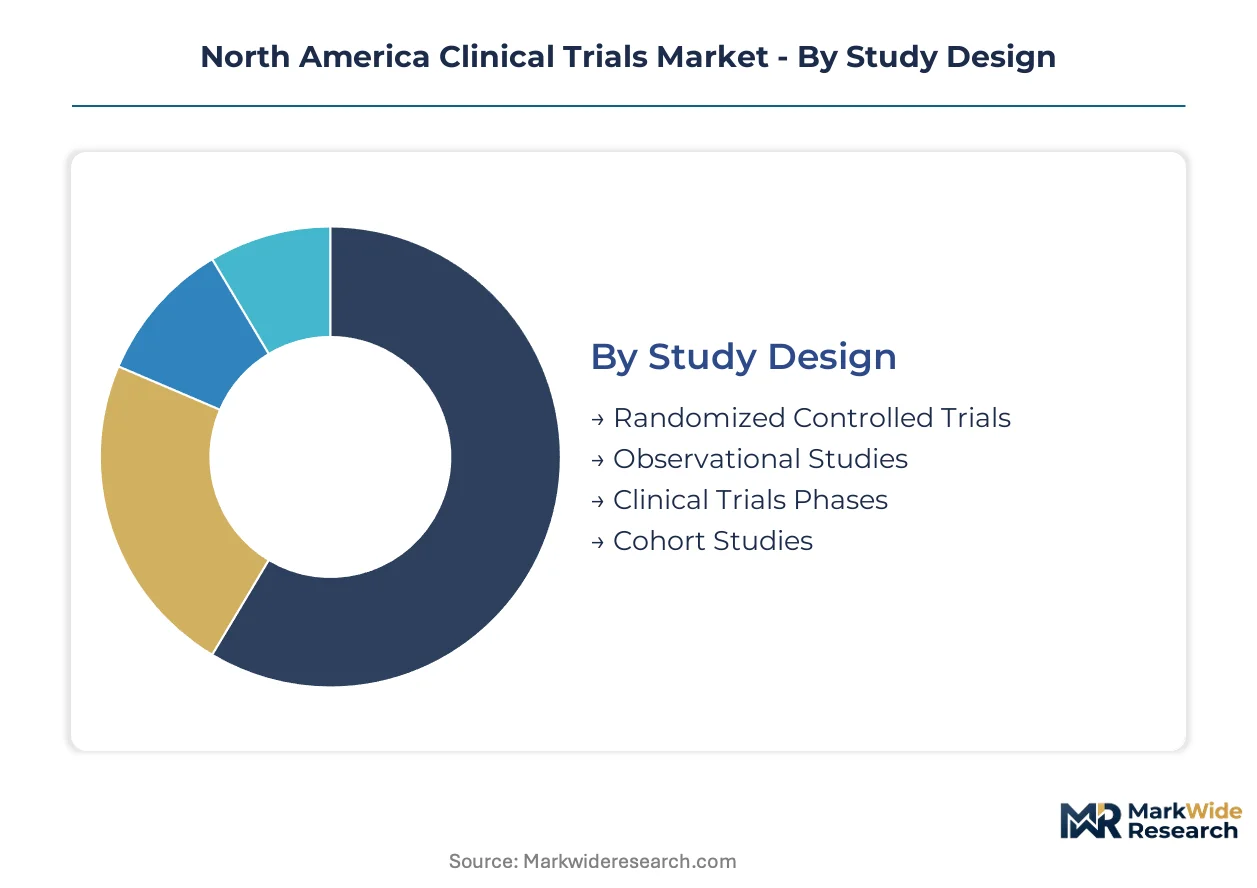
Clinical trial segmentation in North America reflects divergent regulatory pathways, patient access constraints, and therapeutic investment priorities. Sponsors configure study designs and funding models to align with FDA approval timelines and site network capabilities across the United States and Canada.
Study Design:
Mature randomized methodologies dominate regulatory submissions while emerging decentralized formats reshape operational economics.
- Randomized Controlled Trials:The gold-standard design employs controlled arms with placebo or active comparator groups to establish causal efficacy. Demand concentrates in Phase III oncology protocols across Massachusetts and California academic medical centers, driven by FDA's stringent evidentiary requirements for novel therapeutic approvals.
- Clinical Trials Phases:Sequential progression from Phase I safety through Phase III efficacy evaluation structures development pipelines. Sponsors in the Mid-Atlantic corridor prioritize Phase II-III transitions where biomarker stratification and adaptive enrollment protocols accelerate patient identification.
- Observational Studies:Non-interventional designs capture real-world treatment patterns and long-term safety profiles. Post-marketing commitments and FDA-mandated risk evaluation strategies expand deployment across cardiovascular and metabolic indications.
- Cohort Studies:Longitudinal tracking of defined patient populations identifies disease progression patterns and treatment response heterogeneity. Academic consortia leverage electronic health record networks in Pennsylvania and North Carolina to assemble retrospective cohorts with reduced recruitment burden.
Randomized Controlled Trials retain volume leadership; Clinical Trials Phases holds the steepest expansion curve.
Patient Type:
Regulatory incentives and unmet medical need reshape recruitment priorities across age-stratified populations.
- Adult Participants:The standard enrollment population for most therapeutic categories, spanning 18-65 years with protocol-specific inclusion criteria. Cardiovascular and metabolic trials in Texas and Florida draw from large insured populations with established site relationships.
- Pediatric Population:Structurally underserved segment requiring specialized consent procedures and age-appropriate formulation development. FDA pediatric exclusivity provisions and rare disease incentives concentrate investment in academic children's hospitals across Boston, Philadelphia, and Toronto.
- Geriatric Patients:Enrollment targets patients over 65 with comorbidity profiles reflecting real-world treatment populations. Alzheimer's and Parkinson's protocols in the Northeast corridor face intensified competition for qualified neurologist investigators.
- Healthy Individuals:Phase I pharmacokinetic and safety studies rely on compensated volunteers without underlying disease. Specialized units in Maryland and Wisconsin maintain screening databases to accelerate first-in-human program initiation.
Adult Participants dominates enrollment volume; Pediatric Population is gaining share fastest through regulatory incentive expansion.
Indication:
Therapeutic focus areas align with pipeline density, biomarker complexity, and reimbursement potential across North American healthcare systems.
- Oncology:Precision medicine protocols require companion diagnostic integration and genomic stratification. New York and San Francisco site networks command premium investigator fees due to concentrated molecular profiling capabilities and competitive sponsor demand.
- Neurological Conditions:Alzheimer's, multiple sclerosis, and rare neurodegenerative disorders present enrollment challenges from diagnostic heterogeneity. Direct-to-patient logistics and mobile nursing networks are displacing traditional site dependency for geographically dispersed populations.
- Cardiovascular Disorders:Large endpoint trials with hard clinical outcomes require extensive follow-up infrastructure. Cleveland Clinic and Mayo Clinic anchor site networks for heart failure and arrhythmia device studies.
- Infectious Diseases:Vaccine and antimicrobial development surged through pandemic-era funding, with residual capacity now redirecting toward antimicrobial resistance and emerging pathogen preparedness. Government grants from NIH and BARDA sustain platform trial infrastructure.
Oncology retains volume leadership; Neurological Conditions holds the steepest expansion curve.
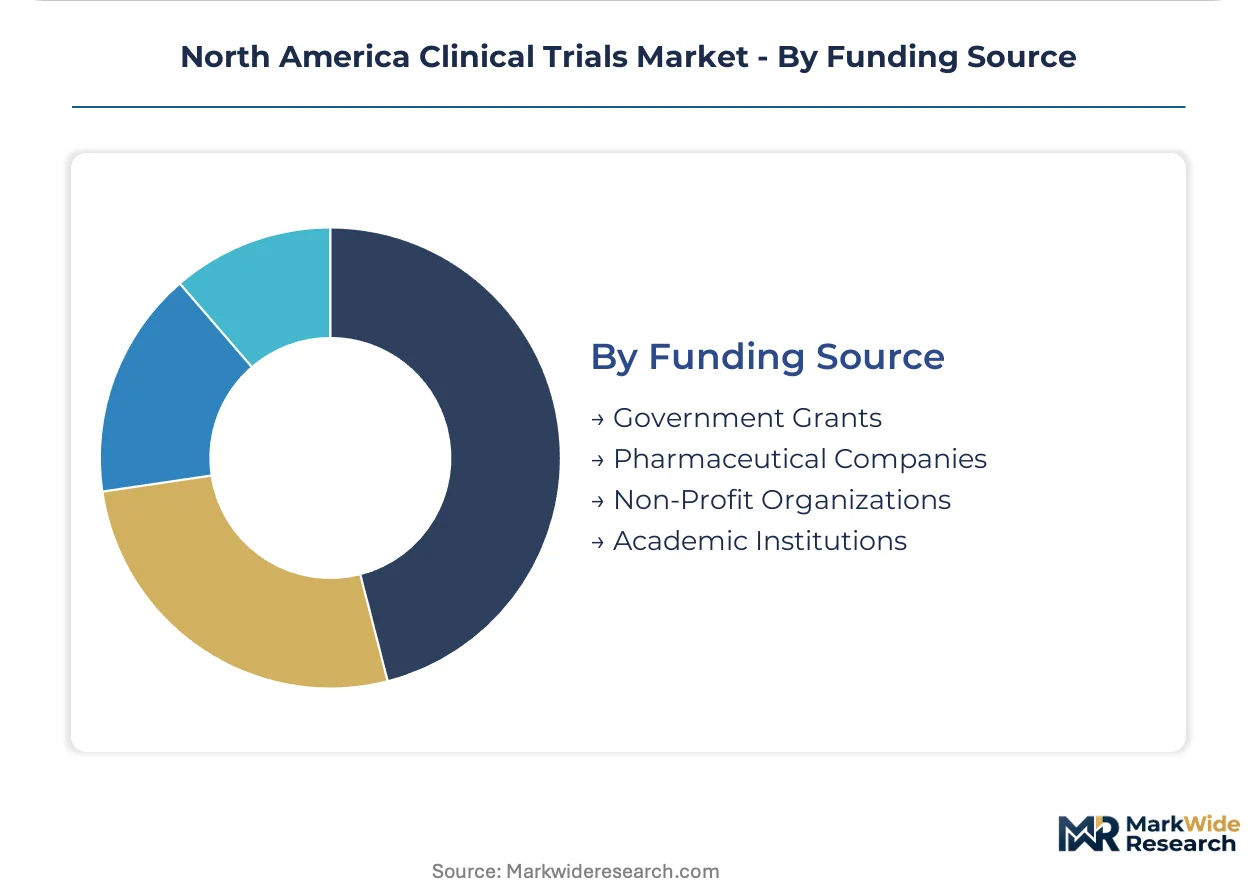
Funding Source:
Sponsor mix determines trial design flexibility, publication rights, and commercialization pathways.
- Pharmaceutical Companies:Internal pipeline prioritization drives the majority of late-stage development investment. Large-cap sponsors consolidate preferred provider agreements with IQVIA, ICON, and Charles River Laboratories to secure site access and data integration capabilities.
- Government Grants:NIH, NCI, and CIHR funding supports investigator-initiated studies and platform trial infrastructure. Budgetary constraints and appropriation uncertainty compress multi-year program planning horizons.
- Academic Institutions:University medical centers leverage endowment and institutional funding for early-phase mechanistic studies. Harvard, Stanford, and University of Toronto anchor collaborative networks with preferred industry partnership terms.
- Non-Profit Organizations:Disease-focused foundations channel patient advocacy resources toward rare and underserved indications. Cystic fibrosis and muscular dystrophy consortia demonstrate sustained commitment through patient registry and natural history study investment.
Pharmaceutical Companies retain volume leadership; Academic Institutions holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net service exports from North American clinical trial operations exceed imports by a substantial margin, with United States-based contract research organizations delivering protocol management to European and Asian sponsors. Canada imports specialized bioanalytical capacity from United States laboratory networks while exporting patient recruitment services through Health Canada-aligned academic centers. Mexico remains a net importer of Good Clinical Practice auditing and regulatory consulting services.
United States
FDA Investigational New Drug filings and decentralized trial infrastructure drive protocol concentration across the Mid-Atlantic and Northeast corridors. The agency's guidance on digital health technologies for remote data capture mandates wearable-enabled endpoint validation. Massachusetts and California academic medical centers anchor Phase II-III oncology studies with integrated molecular profiling capabilities.
Canada
Health Canada and PMRA parallel frameworks enable cross-border protocol execution with ICH E6(R2) harmonization. The regulator maintains divergent requirements for digital endpoint validation compared to FDA standards. Ontario and Quebec academic consortia leverage electronic health record networks to assemble retrospective cohorts with reduced recruitment burden.
Mexico
Cost-advantaged site activation and expanding investigator training programs attract mid-sized biopharmaceutical sponsors seeking geographic diversification. COFEPRIS regulatory alignment with ICH standards streamlines protocol submission pathways. Mexico City and Guadalajara metropolitan areas concentrate contract research organization delivery centers serving United States sponsors.
North America Clinical Trials Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in laboratory services and patient logistics. The vendor base compresses into three tiers: full-service contract research organizations with integrated data infrastructure, mid-sized therapeutic specialists competing on rare disease expertise, and laboratory services providers bundling bioanalytical testing into early-stage programs. Consolidation accelerates through preferred provider agreements and site network acquisitions. Asset-light financing models for decentralized trials narrow the competitive field for traditional mid-sized players.
Among full-service platform operators, IQVIA and ICON plc exemplify divergent strategic positioning within the integrated tier. IQVIA occupies a position anchored by proprietary real-world data infrastructure spanning claims databases and electronic health records. ICON plc represents therapeutic specialization archetypes concentrated in rare diseases and complex biologics. Charles River Laboratories sits within the laboratory-centric segment, bundling bioanalytical services into preclinical and early clinical development programs.
| Leading Market Players |
|---|
| IQVIA |
| ICON plc |
| Parexel International |
| Syneos Health |
| Charles River Laboratories |
| Medpace Holdings |
| WuXi AppTec |
| Thermo Fisher Scientific |
| Laboratory Corp of America Holdings |
| Others |
Value Chain & Pricing Dynamics
The I-95 pharmaceutical logistics corridor connects Boston's academic medical centers to Philadelphia's site networks, with freight cost volatility compressing margins for mid-sized contract research organizations while concentrating pricing power among integrated platform operators with captive logistics capabilities.
Pricing Analysis
Biopharmaceutical sponsors anchor contract pricing through preferred provider agreements that stratify across full-service, functional service provider, and laboratory services tiers. Price differentiation rests on therapeutic specialization depth and proprietary real-world data integration rather than commodity site access. Cost compression in Phase II-III oncology protocols is intensifying as sponsor consolidation reduces vendor pools. Emerging biotech sponsors demonstrate highest price sensitivity, while large-cap pharmaceutical companies prioritize data integration capabilities over rate negotiation.
Supply Chain Analysis
Extended payment terms from sponsor-side procurement teams are squeezing working capital for mid-sized contract research organizations, forcing supply-chain finance facility adoption. Laboratory capacity concentrates in the United States, Canada, and select European markets with FDA-aligned quality systems. Specialized bioanalytical testing for complex biologics draws from concentrated North American lab networks. Single-source vulnerability in molecular profiling capabilities creates bottlenecks for precision medicine protocols. Distribution runs through academic medical center procurement committees and direct-to-patient logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA guidance on artificial-intelligence-enabled endpoints is accelerating protocol redesign, creating high-growth disruption as decentralized trial infrastructure displaces traditional site dependency.
For Market Incumbents: Insulate proprietary data infrastructure through exclusive site network acquisitions and real-world evidence platform integration. Large contract research organizations must consolidate preferred provider status before sponsor procurement centralization eliminates mid-tier vendors. Vertical integration into direct-to-patient logistics capabilities protects margin compression from retail pharmacy and mobile nursing entrants. For New Entrants and Emerging Players: The Mid-Atlantic corridor offers underpenetrated patient populations with established research infrastructure in Pennsylvania, Maryland, and North Carolina. Pediatric and rare disease protocols present accessible entry points where regulatory incentives expand sponsor commitment. A go-to-market strategy anchored by therapeutic specialization in neurological conditions bypasses saturated oncology competition. For Investors and Strategic Acquirers: Asset-light decentralized trial specialists with demonstrated FDA digital endpoint validation capabilities represent priority acquisition targets. Long-term viability hinges on convergence of clinical and real-world data streams over the coming decade. Watch for FDA artificial-intelligence guidance finalization as the inflection signal for platform consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Decentralized Trial Platform Deployment | FDA digital health guidance mandates remote data capture validation across IND-submitted protocols. |
| Real-World Evidence Integration | Artificial-intelligence-enabled endpoints create pathways for claims-grade electronic health record data. |
| Therapeutic Specialization Acquisition | Rare disease expertise commands premium investigator fees in structurally underserved pediatric populations. |
| Site Network Consolidation | Preferred provider agreements with Massachusetts and California academic medical centers secure oncology access. |
| Direct-to-Patient Logistics Buildout | Mobile nursing networks displace traditional site dependency for geographically dispersed rare disease trials. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with drug development executives, regulatory affairs leads, clinical operations directors, and site principal investigators; and secondary validation through FDA Investigational New Drug filings, ClinicalTrials.gov protocol registries, Health Canada submission databases, and academic medical center procurement records. Bottom-up site activation and enrollment velocity estimates triangulated against top-down sponsor expenditure and contract research organization revenue disclosures.
Forecast inputs across the projection horizon incorporated study design segmentation, patient type stratification, therapeutic indication pipeline density, and funding source mix. Modeled dimensions included protocol phase, decentralized versus centralized operational format, biomarker complexity tier, and regional regulatory cluster. CAGRs were derived from sponsor pipeline prioritization trajectories, site network capacity expansion plans, and digital health technology adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive platform consolidation moves by large-cap contract research organizations would shift outcomes beyond modeled ranges. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Research
Esource and Clinical Trials Market
Clinical Research
Clinical Trial Logistics and Direct-to-Patient Delivery Platforms Market
Clinical Research
Clinical Trial Biorepository and Archiving Solutions Market
Clinical Research
Synthetic Clinical Trial Data Market
Clinical Research
Early Phase Clinical Trial Outsourcing Market
Clinical Research
India Preclinical CRO Market
Clinical Research
Real World Evidence Linkage Services Market
Clinical Research
Non-Alcoholic Steatohepatitis Clinical Trials Market
Clinical Research
US Clinical Trials Market
Clinical Research
Global Virtual Clinical Trials Market
Clinical Research
Edema Clinical Trials Market
Clinical Research
Clinical Data Analytics Market
Clinical Research
Clinical Trials Site Management Organizations Market
Clinical Research
Omics-Based Clinical Trials Market
Clinical Research
Global in Silico Clinical Trials Market
Clinical Research
Clinical Trial Logistics Market