
 Early Childhood Education Market | 2026-2036
Early Childhood Education Market Size, Share, and Industry Trends Forecast 2026-2036
Early Childhood Education Market Insights
Premium accreditation standards is rotating demand toward centers with National Association for the Education of Young Children credentials and comparable tier-one certifications. Bright Horizons Family Solutions leverages its employer-sponsored partnership model to secure stable enrollment pipelines. KinderCare Learning Companies anchors its position through proprietary curriculum development and scaled operational systems. Goddard Systems differentiates via franchised owner-operators who compete on localized community trust.
Early childhood education encompasses structured learning and care programs for children from birth through age eight, typically delivered through center-based facilities with defined staff qualifications, curriculum frameworks, and safety protocols including specified child-to-adult supervision ratios. These programs serve foundational cognitive, social, and physical development purposes that precondition later academic and workforce outcomes. Preschools occupy the largest revenue pool among product type segments, while play-based teaching methodology captures the fastest enrollment growth as developmental science validates experiential learning over direct instruction. Parent-paid tuition dominates end-user funding in private provision, though government bodies channel substantial public investment through voucher and direct-service mechanisms.
The U.S. Office of Child Care administers Child Care and Development Fund block grants that shape state-level subsidy eligibility and provider reimbursement rates, while the U.S. Department of Education coordinates Preschool Development Grant competitions that incentivize quality-rating system adoption. China's Ministry of Education enforces kindergarten operation standards through GB codes that mandate facility specifications and teaching credentials. Stakeholders must monitor how subsidy adequacy thresholds and credential requirements evolve, as these parameters determine which provider business models achieve sustainable unit economics.
Market Dynamics
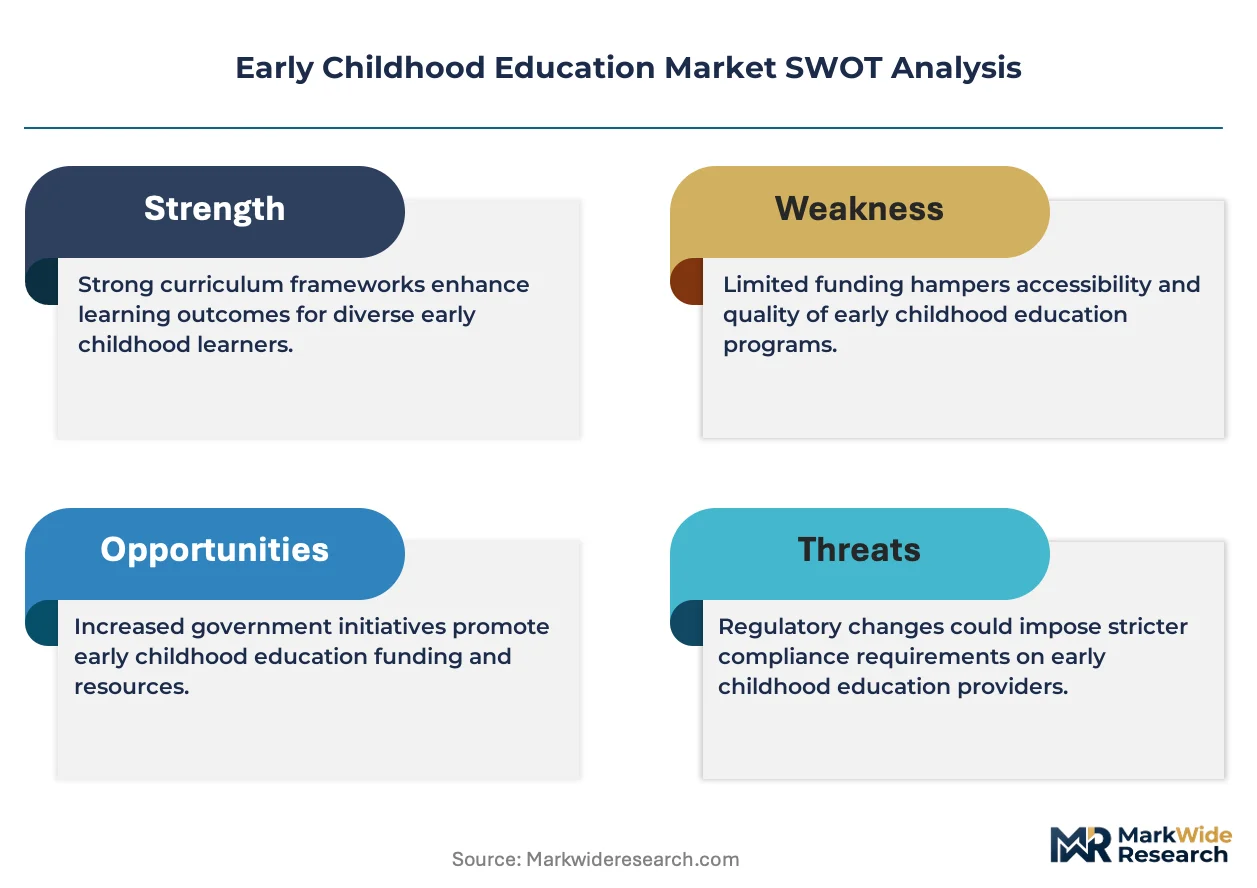
The Early Childhood Education Market is undergoing structural compression as dual-income household formation intensifies demand for licensed center-based care while regulatory ratchets tighten operational economics through mandated staff-to-child ratios and credential requirements.
Growth Catalysts
- Head Start Performance Standards:The U.S. Department of Health and Human Services mandates comprehensive developmental screening and family engagement protocols that elevate quality baselines and drive enrollment toward accredited providers.
- Urban China Household Formation:Megacity migration in Shanghai, Beijing, and Shenzhen concentrates demand for premium kindergarten slots as disposable income thresholds cross tuition affordability tipping points.
- Play-Based Pedagogy Validation:Developmental neuroscience findings on experiential learning are accelerating curriculum adoption across Montessori and Reggio Emilia methodologies in private preschool networks.
Market Restraints
- Real Estate Cost Concentration:Center-based facilities in metropolitan cores face commercial lease escalation that compresses unit economics below viable thresholds for independent operators.
- Workforce Credential Scarcity:Bachelor-degree requirements for lead teachers under Child Care Development Fund quality set-asides constrain hiring pools and inflate compensation costs.
- Informal Care Substitution:Unlicensed home-based providers and grandparent care arrangements absorb price-sensitive demand segments that would otherwise flow to formal centers.
Strategic Opportunities
- Employer-Sponsored Partnership Models:Fortune 500 corporations are contracting directly with provider networks for on-site or near-site early learning benefits that secure enrollment pipelines.
- India Tier-2 City Penetration:Underdeveloped preschool infrastructure in secondary cities like Pune, Ahmedabad, and Jaipur offers first-mover positioning before national curriculum standardization.
- Digital Assessment Integration:Converging learning management platforms with developmental tracking tools enables outcome documentation that satisfies accreditation bodies and justifies premium pricing.
Industry Challenges
- Staff Turnover Velocity:Early educator burnout and compensation gaps relative to K-12 teaching roles force continuous recruitment cycles that destabilize classroom continuity.
- Multi-Site Compliance Complexity:Franchise operators must synchronize state-level licensing variations, fire safety inspections, and food service certifications across distributed center portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Early Childhood Education Market |
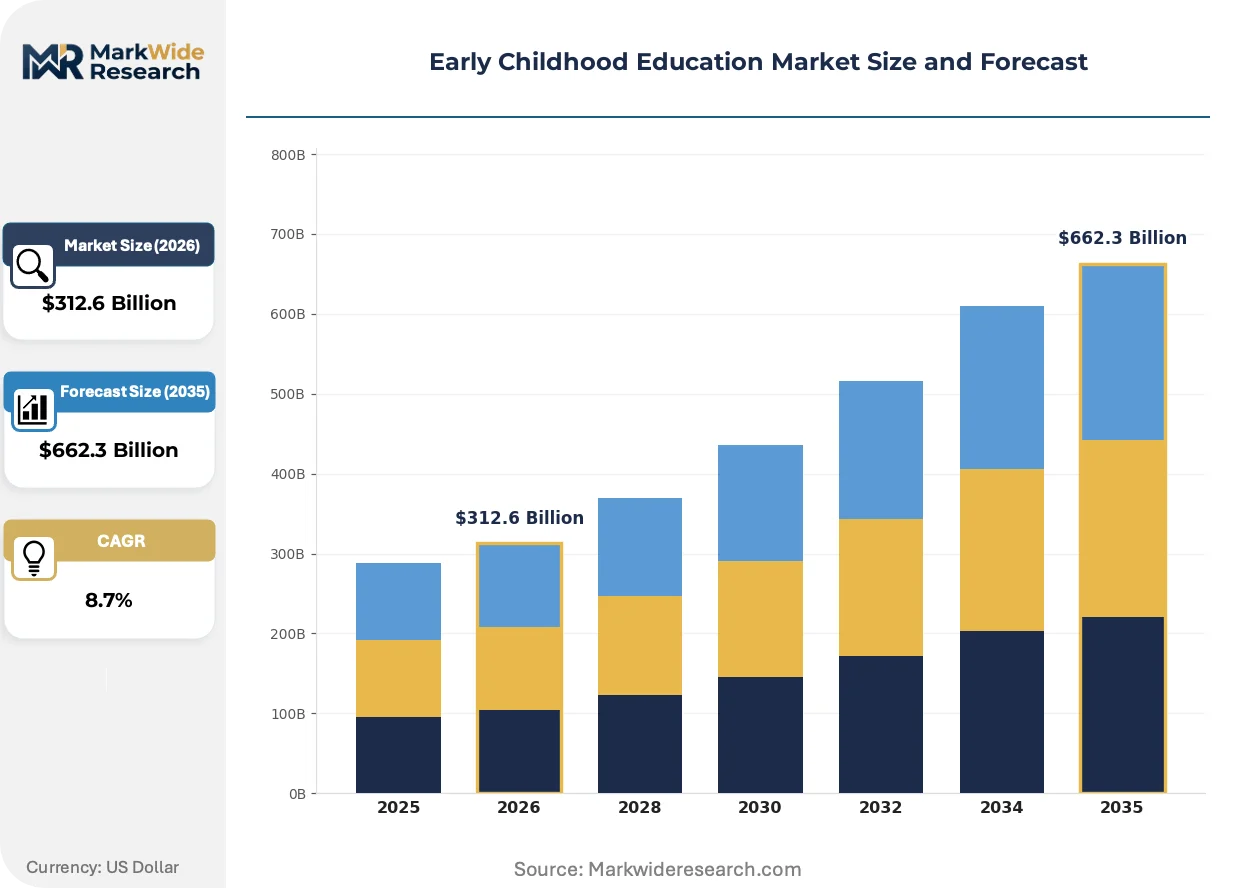
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $662.3 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Preschools, Daycare Centers, Nursery Schools, Parent Education Programs Teaching Methodology: Montessori, Waldorf, Reggio Emilia, Traditional, Play-based Age Group: Infants, Toddlers, Preschoolers, Pre-Kindergarten End User: Parents, Educational Institutions, Government Bodies, Community Organizations |
| Companies Covered | Bright Horizons Family Solutions, KinderCare Learning Companies, Learning Care Group, Primrose Schools, Goddard Systems, The Learning Experience, Spring Education Group, Cadence Education, Childtime Learning Centers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Early Childhood Education Market Trends and Innovations
Technology-mediated observation tools and data-driven developmental tracking are compressing traditional assessment cycles while regulatory transparency mandates force operational digitization across provider tiers.
Adaptive learning platforms embedded within classroom management software are decomposing the role of static curriculum binders by enabling real-time developmental milestone tracking. Center directors in employer-sponsored networks are deploying these systems fastest. The technology is decomposing annual parent-teacher conferences into continuous digital feedback loops that reshape retention economics.
China's Ministry of Education GB codes for kindergarten facility specifications and teaching credentials are tightening enforcement through provincial inspection regimes. Non-compliant operators face license revocation with limited appeal pathways. Private chains in Guangdong and Jiangsu provinces are consolidating to amortize compliance infrastructure across multi-site portfolios.
Parent purchasing patterns are fragmenting across subscription-based enrichment add-ons and à-la-carte extended-day services that unbundle traditional tuition packages. Urban dual-income households in the United States are selecting providers based on real-time mobile app visibility into daily activities and photo documentation. This behavioral shift concentrates enrollment in technology-enabled centers that operationalize transparency as a competitive attribute.
Early Childhood Education Market Segmentation
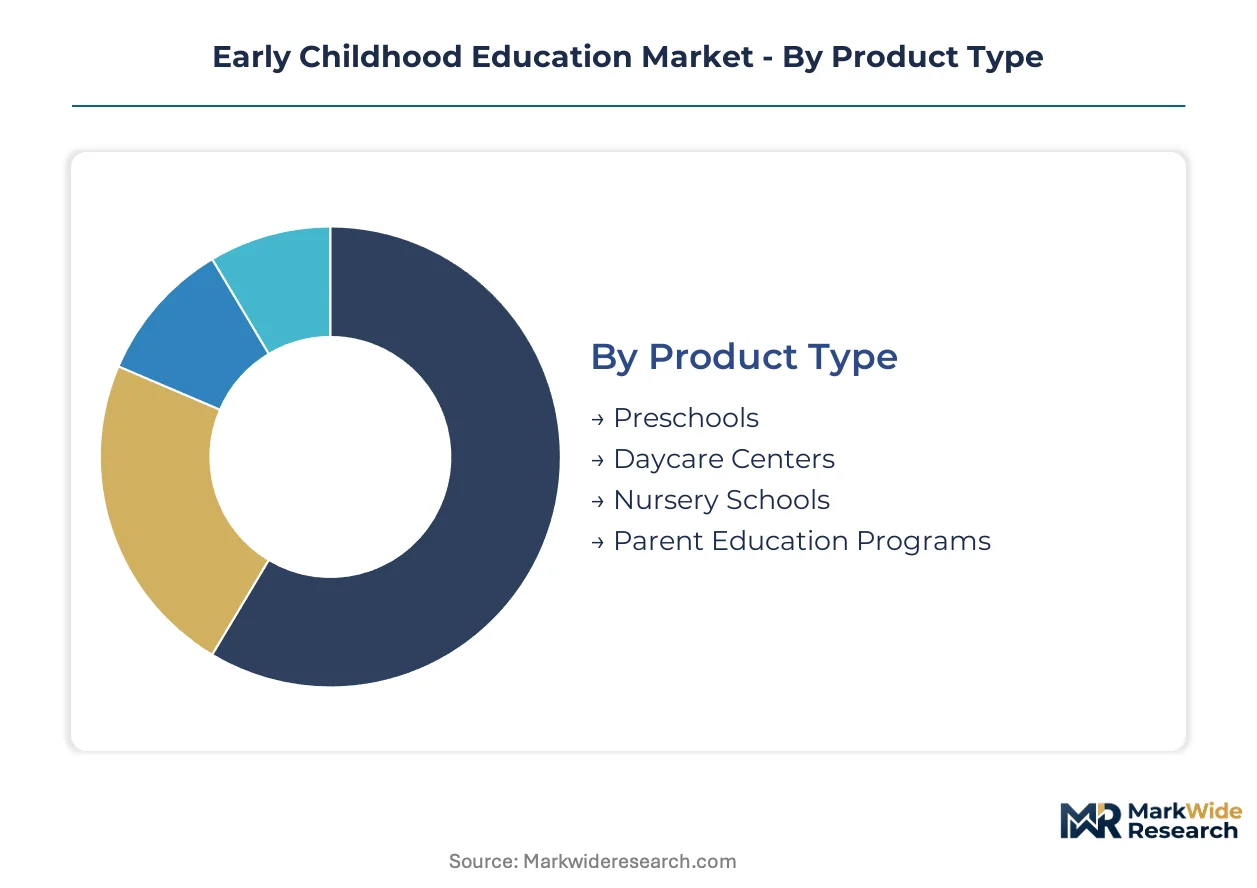
Segmentation in early childhood education reveals how provider business models align with distinct demand pockets and regulatory frameworks. Product format and pedagogical approach determine capital intensity and staffing requirements, while age targeting shapes curriculum design and facility specifications.
Product Type:
Preschools concentrate in urban cores where dual-income households drive premium tuition capacity, while daycare centers distribute more broadly across suburban corridors serving working-class families.
- Preschools:Structured learning environments for children ages three to five emphasize kindergarten-readiness curricula with defined literacy and numeracy milestones. Demand clusters in Shanghai, Beijing, and Shenzhen where disposable income thresholds cross premium tuition affordability tipping points. China's Ministry of Education GB codes mandate facility specifications and teaching credentials that filter out independent operators.
- Daycare Centers:Extended-hours facilities providing custodial care alongside developmental activities serve infants through preschool ages. U.S. Child Care Development Fund subsidies concentrate enrollment in low-income urban neighborhoods where voucher reimbursement rates determine provider viability. Workforce credential scarcity under quality set-asides constrains expansion.
- Nursery Schools:Half-day programs emphasizing socialization and emergent literacy serve two-to-four-year-olds in middle-income communities. Parent-paid tuition dominates outside subsidized markets.
- Parent Education Programs:Workshops and home-visit services targeting caregiver skill development operate through community health networks. Government contracts fund most provision.
Preschools command the established base. The steepest expansion runs through daycare centers.
Teaching Methodology:
Pedagogical differentiation separates premium providers from commodity competitors, with experiential approaches capturing affluent urban demand while traditional methods dominate subsidy-dependent markets.
- Montessori:Child-directed learning within prepared environments emphasizes sensory materials and mixed-age classrooms. Accreditation through Association Montessori Internationale or American Montessori Society commands tuition premiums in U.S. coastal metros and European capitals. Teacher certification requirements limit scalable replication.
- Waldorf:Arts-integrated, play-centered curriculum delays formal academics until age seven. Steiner school networks concentrate in Germany, Netherlands, and Scandinavian markets where public funding integration varies.
- Reggio Emilia:Project-based emergent curriculum originating in Northern Italy emphasizes documentation and environmental design. U.S. private preschools adopt aesthetic principles without full municipal integration.
- Traditional:Teacher-directed instruction with standardized scope-and-sequence dominates U.S. Head Start and state pre-K programs. Compliance with performance standards drives curriculum selection.
- Play-based:Experiential learning through structured exploration gains validation from developmental neuroscience. Fastest enrollment growth occurs in private networks seeking differentiation from academic-heavy alternatives.
Traditional methodology anchors public provision. Play-based approaches are climbing the fastest among private networks.
Age Group:
Infant care commands the highest per-slot costs due to mandated staff ratios, while pre-K enrollment concentrates in government-funded universal programs.
- Infants:Care for children under twelve months requires one-to-four staff ratios under most licensing regimes. Real estate and labor costs compress margins below toddler and preschool segments.
- Toddlers:Twelve-to-thirty-six-month programming bridges custodial care and early learning. Parent willingness-to-pay peaks in this segment as workforce re-entry pressures intensify.
- Preschoolers:Three-to-five-year-old enrollment represents the largest revenue pool across product types. Curriculum standardization enables operational scale.
- Pre-Kindergarten:Four-year-old targeted programming aligns with public school transition goals. U.S. state-funded universal pre-K expansions displace private market share in participating jurisdictions.
Preschoolers command the established base. Pre-Kindergarten is gaining share fastest through public funding expansion.
End User:
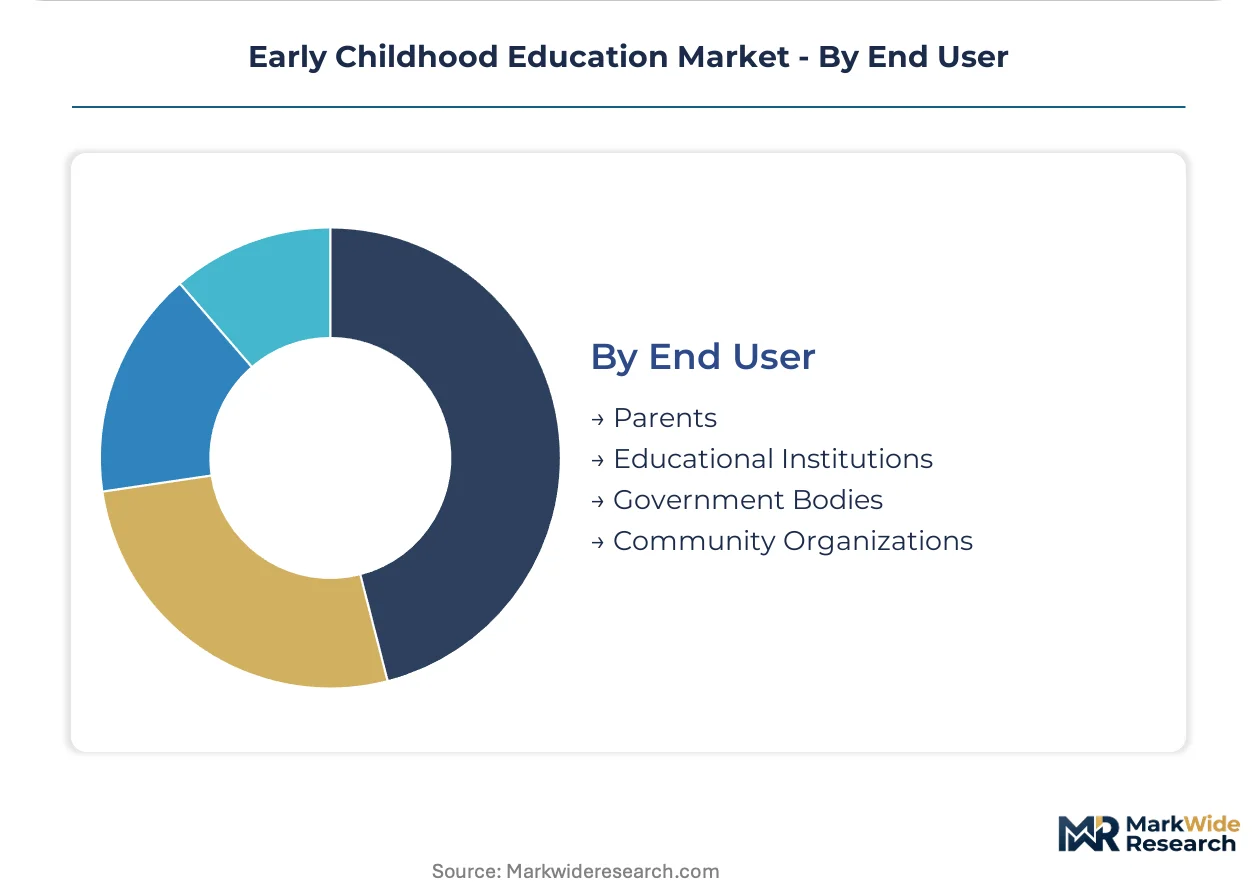
Funding source segmentation determines pricing power and regulatory exposure, with parent-paid tuition offering margin flexibility while government contracting demands compliance infrastructure.
- Parents:Direct tuition payment dominates private center revenue in the United States and urban China. Mobile app transparency and photo documentation increasingly influence provider selection.
- Educational Institutions:University-affiliated and employer-sponsored centers secure enrollment pipelines through institutional contracts. Bright Horizons leverages this channel.
- Government Bodies:Voucher reimbursement and direct service contracts fund provision for low-income families. U.S. Office of Child Care block grants shape state subsidy structures.
- Community Organizations:Non-profit and faith-based providers access facility subsidies and volunteer labor. Multi-site compliance complexity constrains scalable growth.
Parents command the established base. Government Bodies show the steepest funding trajectory through early learning expansion initiatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Early childhood education services trade primarily through domestic provision rather than cross-border delivery, with foreign direct investment and curriculum licensing substituting for physical service exports. Capital flows concentrate toward high-income markets with favorable regulatory treatment of private provision.
United States
Dual-income household formation in metropolitan corridors drives center-based enrollment growth, particularly in employer-sponsored benefit arrangements. The U.S. Department of Health and Human Services administers Head Start performance standards that mandate developmental screening and family engagement protocols. Enrollment clusters concentrate in suburban Washington D.C., Boston-Cambridge, and Seattle where median household incomes cross premium tuition thresholds.
China
Megacity migration concentrates demand for kindergarten slots in Shanghai, Beijing, and Shenzhen as disposable income growth enables premium private preschool uptake. The Ministry of Education enforces GB codes for facility specifications and teaching credentials through provincial inspection regimes. Guangdong and Jiangsu provinces witness rapid private chain consolidation as operators amortize compliance infrastructure across multi-site portfolios.
United Kingdom
Working parent demand for extended-hours provision intensifies in Greater London and Southeast commuter belts where nursery cost-to-income ratios strain household budgets. Ofsted inspection frameworks and Early Years Foundation Stage standards regulate quality benchmarks and staff qualification requirements. Manchester and Birmingham see emerging premium provider entry as regional economic development diversifies beyond London gravity.
India
Tier-2 city household formation in Pune, Ahmedabad, and Jaipur creates first-mover opportunities before national curriculum standardization tightens operational requirements. The Ministry of Women and Child Development coordinates Integrated Child Development Services and preschool education integration under Anganwadi expansion programs. Hyderabad and Bengaluru technology corridors concentrate employer-sponsored creche demand from IT sector workforce expansion.
Germany
Reunification-era birth rate recovery and maternal workforce re-entry pressures intensify Kita (daycare) slot scarcity in Berlin, Hamburg, and Munich metropolitan regions. The Federal Ministry for Family Affairs enforces quality standards through Kita-Gesetz frameworks that mandate pedagogical staff ratios and continuing education requirements. North Rhine-Westphalia and Bavaria concentrate private provider expansion where municipal supply gaps persist despite public investment commitments.
Early Childhood Education Market Competitive Landscape
Listed leaders compete with private specialists across capital access and operational scale dimensions, producing a tiered structure where employer-sponsored networks and franchised systems occupy distinct competitive positions. Consolidation pressure intensifies as multi-site operators achieve compliance cost amortization advantages over independent centers. Three archetypes dominate: employer-partnership platforms securing enrollment pipelines through corporate contracts, curriculum-franchise systems scaling through owner-operator networks, and regional roll-up platforms consolidating fragmented local markets. Dominant competitive moves center on geographic densification through acquisition and technology platform deployment for parent engagement and regulatory documentation.
Within the employer-partnership archetype, Bright Horizons Family Solutions and KinderCare Learning Companies anchor distinct positioning approaches, while Goddard Systems exemplifies the franchised owner-operator model competing on localized community trust. These three entities represent the primary structural alternatives for capital deployment in center-based early childhood education, with each archetype carrying distinct regulatory exposure and unit economics profiles.
| Leading Market Players |
|---|
| Bright Horizons Family Solutions |
| KinderCare Learning Companies |
| Learning Care Group |
| Primrose Schools |
| Goddard Systems |
| The Learning Experience |
| Spring Education Group |
| Cadence Education |
| Childtime Learning Centers |
| Others |
Pricing and Supply Chain Analysis
Forty-five to sixty-day lead times for Montessori-certified teaching materials and sensory equipment from Italian and Dutch suppliers concentrate procurement cycles around seasonal enrollment windows, compressing margin flexibility for independent operators while amplifying pricing power for multi-site networks with forward-contracted inventory positions.
Pricing Analysis
Parent-paid tuition anchors a three-tier pricing structure across premium, standard, and economy levels, with NAEYC accreditation and employer-sponsored partnership status commanding measurable premiums over state-subsidized provision. Price differentiation rests on staff credential density and real estate location quality rather than curriculum content alone. Cost compression in economy-tier daycare centers is intensifying because voucher reimbursement rate stagnation forces trade-offs between ratio compliance and wage levels. Government-contracted providers exhibit highest price sensitivity due to fixed reimbursement schedules, while corporate-sponsored centers serving Fortune 500 campuses demonstrate lowest sensitivity.
Supply Chain Analysis
Inventory cycles for imported Montessori apparatus and Reggio Emilia documentation materials stretch 45-60 days, creating working capital intensity that filters out undercapitalized entrants. Manufacturing concentrates in Italy, Netherlands, and China for specialized learning materials, while consumable supplies draw from domestic distributors. Raw material dependencies include FSC-certified hardwoods for sensory materials, non-toxic paints and finishes, and fire-rated upholstery fabrics. Single-source vulnerability runs through European accreditation bodies for teacher certification programs. Distribution runs through regional educational supply cooperatives and direct manufacturer relationships for premium networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across urban submarkets creates consolidation opportunities as dual-income household formation outpaces licensed seat supply in dense metropolitan corridors.
For Market Incumbents: Compound geographic density through targeted acquisition of independent centers in supply-constrained zip codes before state-level quality-rating system adoption raises compliance barriers. Vertical integration into teacher credentialing programs addresses workforce scarcity while locking in staffing pipelines. Defensive positioning requires technology platform deployment for real-time parent engagement before transparency expectations harden into retention prerequisites. For New Entrants and Emerging Players: NAEYC accreditation fast-track programs enable rapid credibility establishment in employer-sponsored benefit channels where procurement cycles favor pre-qualified networks. White-space concentration exists in India tier-2 cities and German Kita supply gaps where municipal provision lags demand. Go-to-market positioning should emphasize play-based pedagogy differentiation against academic-heavy alternatives in premium parent-paid segments. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across technology-integrated center portfolios as adaptive learning platform deployment becomes table stakes for accreditation maintenance. Long-term viability favors regional roll-up platforms with compliance infrastructure amortization advantages over fragmented independents. Acquisition target archetype: multi-site operators with 8-15 centers in supply-constrained metropolitan corridors. Signal to watch: state-level universal pre-K expansion announcements that displace private market share in participating jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Employer Partnership Expansion | Direct contracting with Fortune 500 HR benefits teams secures enrollment pipelines and reduces customer acquisition costs. |
| Adaptive Learning Platform Deployment | Real-time developmental tracking satisfies NAEYC documentation requirements while enabling premium tuition positioning. |
| Regional Center Consolidation | Multi-site operators amortize compliance infrastructure across portfolios under tightening GB code and state licensing regimes. |
| Teacher Credentialing Pipeline Investment | In-house CDA and bachelor's completion programs address workforce scarcity constraining expansion in subsidy-dependent markets. |
| Tier-2 City Geographic Expansion | First-mover positioning in Pune, Ahmedabad, and Jaipur precedes national curriculum standardization that will raise barriers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of U.S. Office of Child Care subsidy reports, China Ministry of Education GB code enforcement bulletins, and state-level quality-rating system documentation. Center directors, early childhood curriculum specialists, employer benefits managers, and municipal licensing officers provided operational perspective. Head Start performance standard filings and Preschool Development Grant award databases supplied program-level data. Bottom-up enrollment modeling triangulated against top-down household formation projections.
Segmentation dimensions modeled include product type, teaching methodology, age group, and end-user funding source across the projection horizon. CAGRs derived from enrollment elasticity to household income thresholds and regulatory seat-capacity expansion schedules. Forecast inputs incorporated staff-to-child ratio compliance costs and real estate lease escalation patterns in target metropolitan corridors.
The analysis sits within stated boundaries; outcomes outside sustained dual-income household formation or subsidy reimbursement rate stability would require recalibration. Forecasts reflect documented assumptions regarding credential requirement trajectories and inspection enforcement intensity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Education & Training
Executive Coaching Certification Market
Education & Training
Saudi Arabia E-Learning Market
Education & Training
Global Micro-Learning Market
Education & Training
Corporate Training Services Market
Education & Training
Language Learning Software Market
Education & Training
Global Edutainment Centers Market
Education & Training
Global Learning Management Systems (LMS) Market
Education & Training
VR Education Market
Education & Training
Europe Digital Education Market
Education & Training
Global Digital Education Market
Education & Training
English Learning App Market
Education & Training
Early Education Production Market
Education & Training
Oman Private K-12 Market
Education & Training
Digital Educational Publishing Market
Education & Training
United States Soft Skills Training Market
Education & Training
IT Training Market