
 Global Digital Education Market | 2026-2036
Global Digital Education Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Education Market Foresight
Certification-grade course offerings is bifurcating the competitive landscape into premium credential providers and volume-access platforms. Coursera Inc leverages university partnerships to sustain its position in degree-qualifying programs. Udemy Inc competes through marketplace breadth, anchoring its model in vocational and creative skill courses. BYJU'S dominates K-12 supplementary tutoring in India through localized curriculum alignment and aggressive geographic expansion.
Digital education encompasses technology-mediated content delivery, learner analytics, and credential verification systems operating across synchronous and asynchronous modalities. Cloud infrastructure enables real-time personalization through learning management systems that track competency progression and adaptive assessment pathways. Corporate training and skill development segments are absorbing the fastest platform investment as employers internalize measurable ROI from certified upskilling. Higher education represents the most mature revenue pool, though margin compression from free-to-freemium competition is redirecting vendor focus toward enterprise licensing.
The EU AI Act and GDPR impose algorithmic transparency and data minimization obligations on adaptive learning platforms serving European learners. India's Digital Personal Data Protection Act and China's MIIT cybersecurity standards create fragmented compliance architectures that increase operational complexity for cross-border providers. Stakeholders must monitor evolving accreditation equivalency frameworks that will determine whether digital credentials achieve parity with traditional degrees in regulated professions.
Market Dynamics
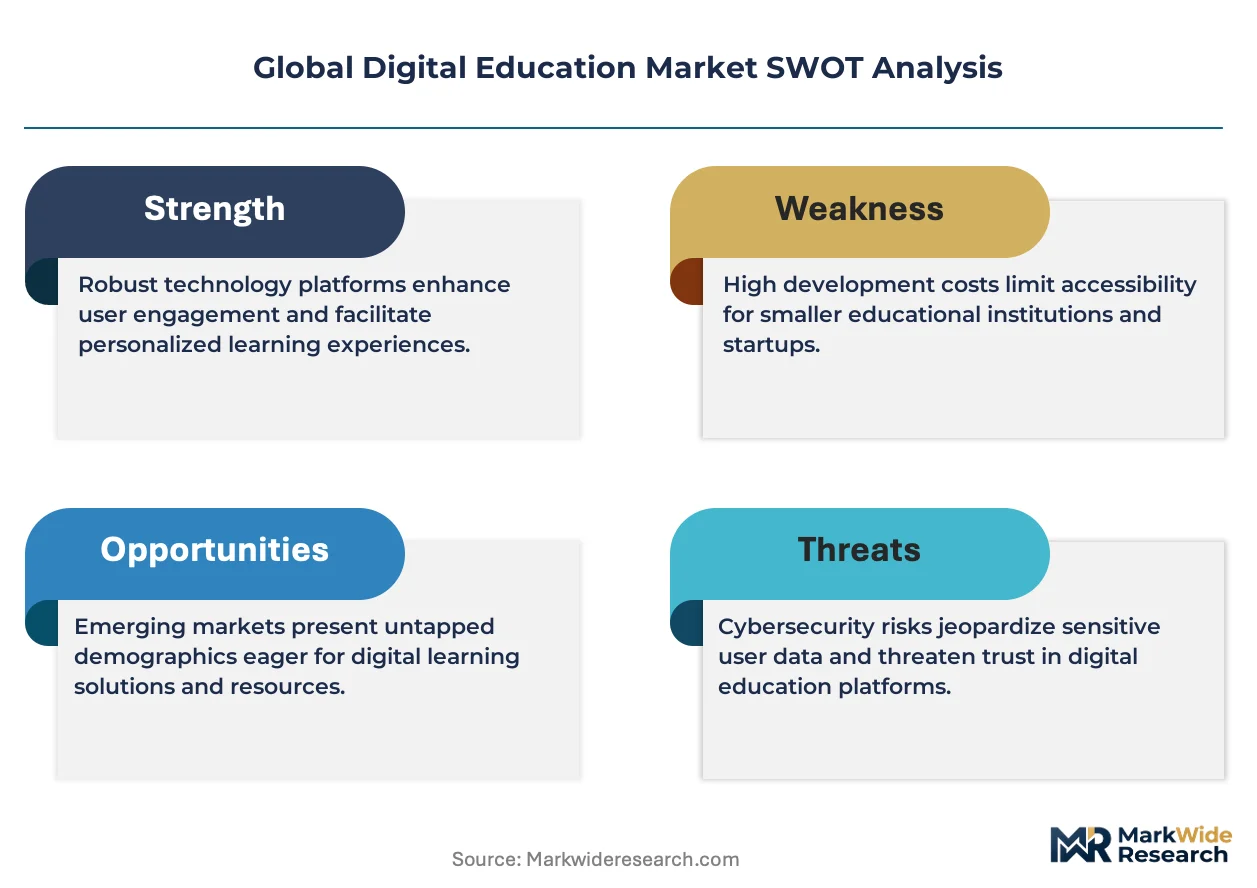
Certification-grade credentialing is concentrating demand around university-backed degree programs and enterprise-authorized skill badges, compressing margins for generalist content libraries while amplifying pricing power for accredited providers.
Growth Catalysts
- India's Digital Personal Data Protection Act:Mandates learner consent frameworks that legitimize platform data monetization, reducing regulatory uncertainty for foreign providers entering tier-2 and tier-3 cities.
- Corporate L&D budget expansion:Fortune 500 training departments are absorbing platform subscriptions at scale, prioritizing measurable competency outcomes over seat-time metrics.
- Low-cost smartphone penetration:Android device affordability below $100 is unlocking asynchronous learning access across India's secondary urban centers.
Market Restraints
- Cloud infrastructure cost volatility:AWS, Azure, and Google Cloud pricing fluctuations compress SaaS margins for video-heavy course delivery.
- EU algorithmic transparency mandates:The EU AI Act imposes explainability requirements on adaptive learning engines, increasing compliance engineering overhead.
- Free-to-freemium substitution:YouTube tutorial ecosystems and open-source MOOC archives siphon price-sensitive learners from paid certification pathways.
Strategic Opportunities
- Vietnam and Indonesia expansion:Government digital literacy campaigns in these markets replicate India's tier-city penetration model for first-mover platforms.
- Blockchain credential verification:Decentralized identity standards enable cross-border degree equivalency, unlocking regulated profession licensing in nursing, accounting, and engineering.
- Employer-sponsored tuition models:US tax-advantaged education benefits under Section 127 are redirecting individual subscription revenue toward enterprise licensing contracts.
Industry Challenges
- Instructional design talent scarcity:Competency-based curriculum architects command premium compensation, constraining platform content velocity.
- Legacy LMS integration friction:SAP SuccessFactors and Workday Learning API mismatches delay enterprise deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Education Market |
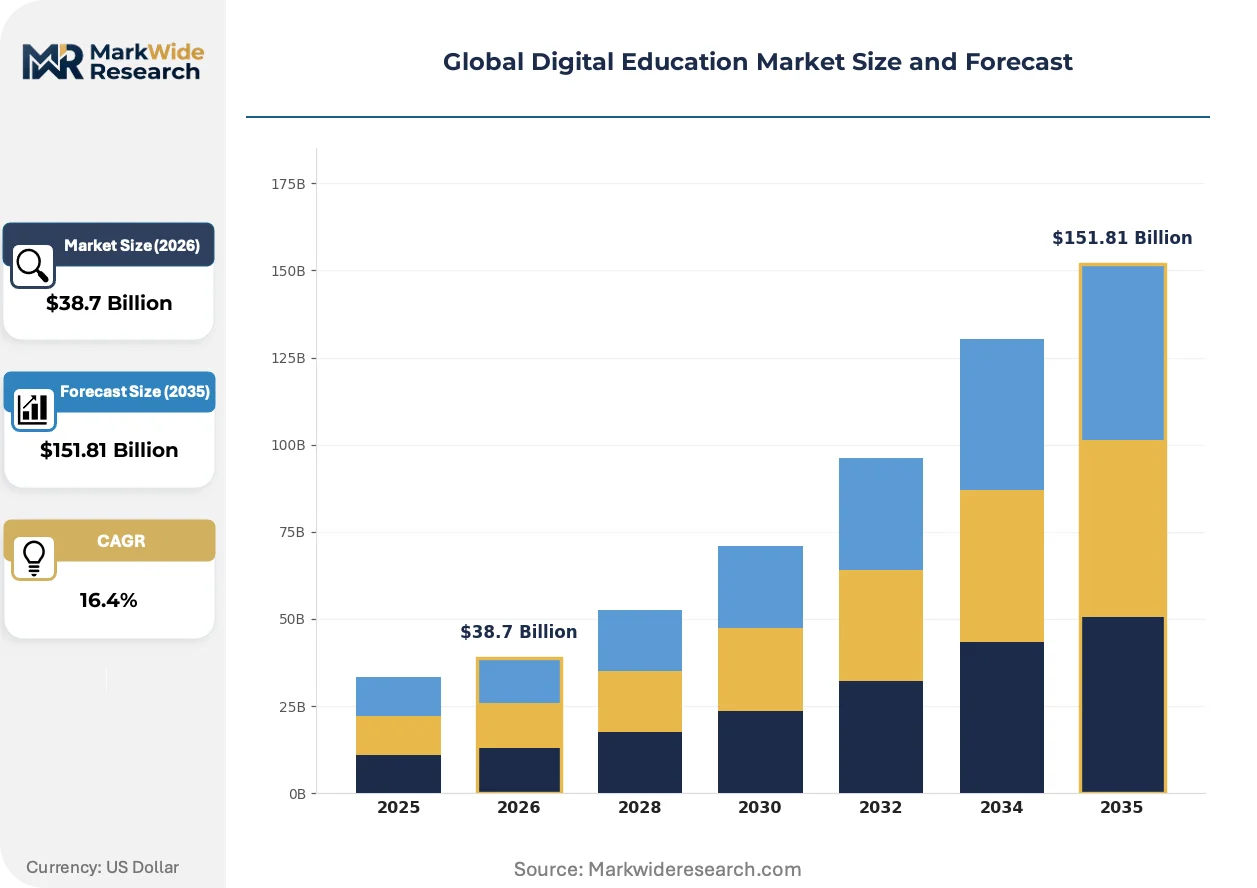
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $151.81 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Learning Management Systems, Virtual Classrooms, eBooks, Assessment Tools, Collaboration Platforms Application: K-12 Schools, Higher Education, Corporate Training, Skill Development, Language Learning End User: Students, Educators, Training Professionals, Corporate Learners, Freelancers Deployment: Cloud-Based, On-Premise, Hybrid, Mobile, SaaS Platforms |
| Companies Covered | Coursera Inc, Udemy Inc, Pluralsight LLC, Udacity Inc, edX Inc, BYJU’S, LinkedIn Learning, 2U Inc, Alison, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Education Market Shifts & Advancements
Generative AI is compressing content production cycles while regulatory fragmentation around learner data is forcing architectural divergence between regional platform deployments.
Adaptive assessment engines powered by large language models are supplanting static multiple-choice evaluations. Corporate training buyers are adopting these systems within eighteen-month procurement cycles. The technology is enabling real-time competency gap identification that compresses traditional certification timelines from semesters to weeks.
The EU AI Act's algorithmic transparency requirements are mandating explainable decision trails for automated grading systems. Platform providers must now document feature attribution for every learner progression recommendation. European higher education institutions are responding by bifurcating their technology stacks between adaptive and rule-based assessment modules.
Employer-sponsored micro-credential stacking is displacing individual degree pursuit as the dominant procurement model. Channel disintermediation is visible as HRIS platforms embed learning marketplaces directly into talent management workflows. This shift is most pronounced in US technology and financial services sectors where skills-based hiring protocols have displaced degree requirements.
Global Digital Education Market Segmentation
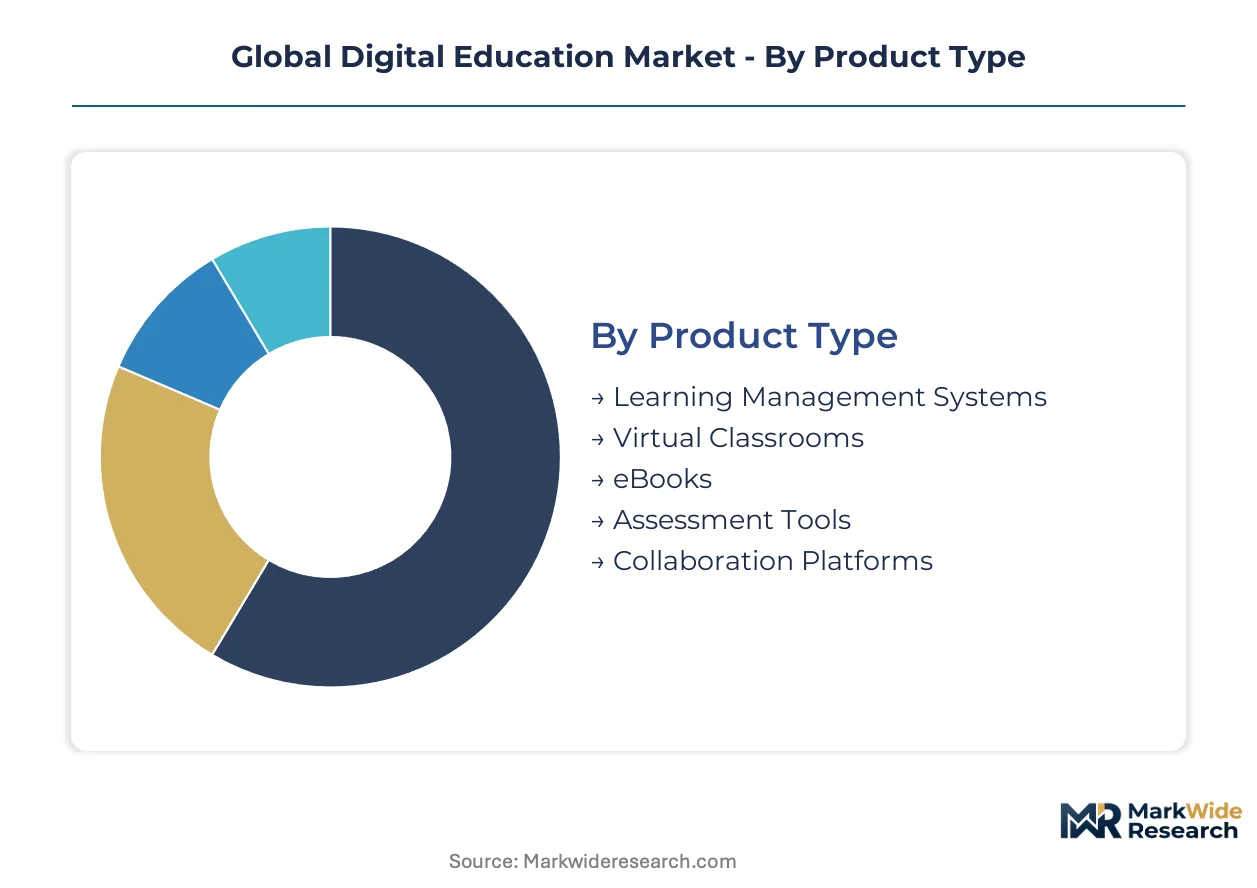
Segmentation in digital education reveals how procurement authority, technical infrastructure, and learner demographics fragment platform monetization. Channel strategy must align with whether buyers are institutional IT departments, HR functions, or individual consumers.
Product Type:
Channel distribution varies sharply by product complexity—enterprise LMS flows through direct sales, while assessment tools and collaboration platforms increasingly embed within HRIS and productivity suites.
- Learning Management Systems:Centralized content delivery infrastructure with competency tracking, SCORM/xAPI compliance, and multi-tenant administration. Demand concentrates at Fortune 500 firms replacing legacy SAP SuccessFactors deployments, driven by measurable ROI requirements from CLOs. LMS dominates installed base. Assessment Tools is where expansion concentrates.
- Virtual Classrooms:Real-time video conferencing with breakout rooms, whiteboarding, and attendance analytics. Higher education institutions in India and Indonesia absorb these for remote degree programs, pressured by government digital literacy mandates and campus capacity constraints.
- eBooks:DRM-protected digital textbooks with annotation layers and offline sync. K-12 districts in US states with open educational resource mandates.
- Assessment Tools:Adaptive testing engines with automated grading and plagiarism detection. Corporate training departments seeking competency verification.
- Collaboration Platforms:Project-based learning workspaces with peer review workflows. Freelancer and vocational training segments.
LMS captures the majority of enterprise contract value. Assessment Tools and Collaboration Platforms are climbing the fastest as skills-based hiring protocols expand.
Application:
Cost tier stratification separates premium degree-qualifying programs from volume-access vocational content, with corporate training occupying the middle ground on per-learner spend.
- K-12 Schools:Supplementary tutoring platforms with localized curriculum alignment and parental dashboards. India's tier-2 and tier-3 cities absorb these through low-cost smartphone penetration, accelerated by government digital literacy campaigns. K-12 dominates installed base. Corporate Training is where expansion concentrates.
- Higher Education:Degree-qualifying programs with university accreditation and credit transferability. European institutions under GDPR and EU AI Act compliance pressure, bifurcating technology stacks between adaptive and rule-based systems.
- Corporate Training:Enterprise-authorized skill badges with measurable competency outcomes. Fortune 500 L&D departments prioritizing ROI metrics over seat-time.
- Skill Development:Vocational and creative courses with marketplace breadth. Price-sensitive learners facing free-to-freemium substitution from YouTube tutorials.
- Language Learning:Speech recognition-powered conversational practice. Individual subscribers and employer-sponsored tuition models.
Higher Education retains the most mature revenue pool. Corporate Training represents the steepest expansion trajectory as enterprise licensing displaces individual subscriptions.
End User:
Customer type determines pricing power—institutional buyers negotiate site licenses while freelancers and students face tiered freemium gates.
- Students:Degree-seeking learners accessing university-partnered platforms. India's secondary urban centers through affordable Android devices. Students dominate installed base. Corporate Learners is where expansion concentrates.
- Educators:Instructional designers and faculty requiring curriculum authoring tools. Scarcity of competency-based architects commanding premium platform pricing.
- Training Professionals:L&D specialists managing enterprise upskilling programs. US tax-advantaged Section 127 benefits redirecting procurement.
- Corporate Learners:Employees consuming employer-sponsored micro-credentials. HRIS-embedded learning marketplaces in technology and financial services.
- Freelancers:Independent workers purchasing vocational courses. Marketplace platforms with breadth over accreditation depth.
Students and Educators constitute the largest addressable population. Corporate Learners are gaining share fastest as channel disintermediation accelerates.
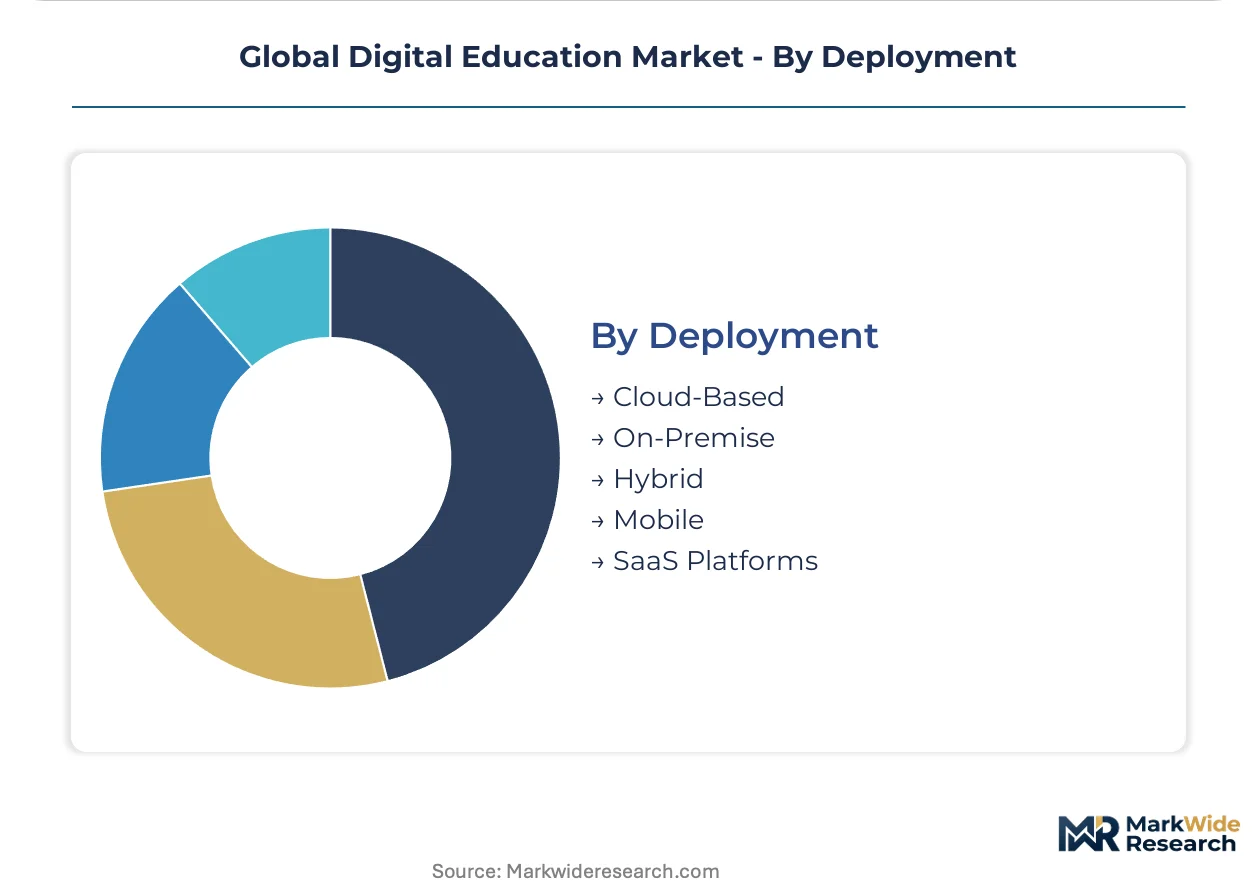
Deployment:
Supply concentration in hyperscale cloud infrastructure shapes margin structure, with SaaS platforms capturing pricing power over self-managed deployments.
- Cloud-Based:Multi-tenant architecture with elastic compute scaling and real-time personalization. European providers under GDPR data minimization and algorithmic transparency mandates from the EU AI Act. Cloud-Based dominates installed base. SaaS Platforms is where expansion concentrates.
- On-Premise:Single-tenant installations with direct infrastructure control. Regulated industries with data residency requirements.
- Hybrid:Mixed workloads with sensitive data on-premise and compute-intensive tasks cloud-resident. China's MIIT cybersecurity standards creating architectural divergence.
- Mobile:Native iOS and Android applications with offline content sync. India's sub-$100 smartphone penetration unlocking asynchronous access.
- SaaS Platforms:Subscription-managed services with API-first integration into HRIS and productivity suites. Workday Learning and SAP SuccessFactors ecosystem embedding.
Cloud-Based deployments retain majority share. SaaS Platforms are expanding most quickly as enterprise buyers prioritize integration velocity over customization depth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border platform licensing now exceeds physical textbook exports as the primary education trade flow, with regulatory divergence determining where providers localize infrastructure versus operate remotely.
United States
Corporate learning and development budgets at Fortune 500 firms absorb platform subscriptions at scale, with Section 127 tuition benefits redirecting individual spending toward employer-sponsored models. The FCC oversees broadband infrastructure subsidies that expand rural learner access. Austin and Seattle technology corridors host headquarters for enterprise-focused SaaS providers embedding assessment tools directly into HRIS workflows.
India
Government digital literacy campaigns and sub-$100 Android penetration unlock asynchronous learning across tier-2 and tier-3 cities. The Digital Personal Data Protection Act mandates consent frameworks that reduce regulatory uncertainty for foreign providers entering secondary urban markets. Bangalore and Hyderabad anchor K-12 supplementary tutoring platforms through localized curriculum alignment and aggressive geographic expansion.
Germany
Dual vocational education systems create institutional demand for competency-verification platforms that integrate with chamber of commerce certification pathways. The EU AI Act and GDPR impose algorithmic transparency and data minimization obligations on adaptive learning engines serving European learners. Berlin and Munich higher education institutions bifurcate technology stacks between adaptive and rule-based assessment modules to satisfy explainability requirements.
China
MIIT cybersecurity standards and data residency requirements fragment platform architectures for cross-border providers, favoring domestic operators with localized infrastructure. The dual carbon goals accelerate cloud efficiency investments for video-heavy course delivery. Shanghai and Beijing edtech clusters concentrate development of AI-powered tutoring systems under tighter regulatory oversight than international counterparts.
Brazil
ANVISA regulates digital health education content while central bank payment rails enable installment subscription models for price-sensitive learners. Federal university distance learning programs absorb virtual classroom infrastructure for degree completion in underserved interior states. São Paulo and Rio de Janeiro corporate training departments prioritize Portuguese-language skill badges for finance and technology sector upskilling.
Global Digital Education Market Competitive Landscape
Listed leaders compete with private specialists across capitalization and governance structures, creating a tiered market where public companies access growth capital for platform scaling while venture-backed operators pursue geographic expansion before liquidity events. The vendor base spans three strategic archetypes: university-partnered degree providers, marketplace platforms with vocational breadth, and enterprise-authorized credential issuers. Dominant competitive moves include strategic partnerships with higher education institutions for accreditation parity and API-first embedding into HRIS ecosystems to disintermediate direct procurement.
Within the university-partnered tier, Coursera Inc and edX Inc occupy positions anchored by degree-qualifying program pipelines. Among marketplace operators with vocational breadth, Udemy Inc and Pluralsight LLC exemplify models prioritizing content velocity over accreditation depth. BYJU'S represents the geographic specialist archetype, with its structure concentrated on K-12 supplementary tutoring through localized curriculum alignment.
| Leading Market Players |
|---|
| Coursera Inc |
| Udemy Inc |
| Pluralsight LLC |
| Udacity Inc |
| edX Inc |
| BYJU'S |
| LinkedIn Learning |
| 2U Inc |
| Alison |
| Others |
Supply & Pricing Matrix
Enterprise licensing contracts with multi-year seat commitments lock in both cloud infrastructure access and predictable per-learner economics for Fortune 500 training departments navigating AWS pricing volatility.
Pricing Analysis
Corporate L&D buyers anchor SaaS subscription tiers that stratify across certification-grade, professional development, and volume-access levels. Price differentiation hinges on accreditation depth and measurable competency outcomes versus seat-time metrics. Cost compression in the vocational content tier intensifies because YouTube tutorial ecosystems siphon price-sensitive learners. Individual subscribers exhibit highest price sensitivity while enterprise procurement officers negotiate site licenses with integration guarantees.
Supply Chain Analysis
Hyperscale cloud regions in the United States, Ireland, and Singapore underpin platform delivery architectures for real-time personalization. Content production draws from instructional design talent pools concentrated in India and Eastern Europe, with automated grading engines resting on large language model APIs. Single-source vulnerability concentrates around AWS, Azure, and Google Cloud pricing coordination. Distribution runs through direct enterprise sales for LMS deployments and API-first embedding into Workday Learning and SAP SuccessFactors ecosystems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market exhibits cyclical recovery characteristics as corporate training budgets rebound from pandemic-era compression and employer-sponsored tuition models expand under US Section 127 tax advantages.
For Market Incumbents: Compound platform stickiness through deeper HRIS integration and proprietary assessment credentialing that raises switching costs. Free-to-freemium substitution from open-source MOOC archives threatens margin sustainability in the vocational tier. Vertical integration into instructional design talent pipelines preserves content velocity against competency-based architect scarcity.
For New Entrants and Emerging Players: Anchor in Vietnam and Indonesia government digital literacy campaigns that replicate India's tier-city penetration model with lower competitive density. White-space opportunity concentrates in blockchain credential verification for cross-border degree equivalency in regulated professions. Go-to-market leverage rests on chamber of commerce partnerships for vocational certification pathways.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among enterprise-authorized credential issuers with HRIS-embedded distribution. Long-term viability favors platforms demonstrating measurable competency ROI for corporate CLOs rather than consumer subscription models. Acquisition target archetype: assessment tool specialists with adaptive engine IP. The signal to watch is accreditation equivalency framework rulings that determine digital credential parity with traditional degrees.
| Strategic Initiative | Industry Significance |
|---|---|
| HRIS Ecosystem Integration | API-first embedding into Workday Learning and SAP SuccessFactors disintermediates direct procurement channels. |
| Blockchain Credential Verification | Decentralized identity standards unlock cross-border licensing in nursing, accounting, and engineering professions. |
| Adaptive Assessment Engine Deployment | Large language model-powered grading compresses certification timelines from semesters to weeks for corporate buyers. |
| Geographic Expansion to Secondary Cities | Tier-2 and tier-3 penetration in India, Vietnam, and Indonesia leverages sub-$100 smartphone adoption curves. |
| Regulatory Compliance Architecture | Bifurcated technology stacks between adaptive and rule-based systems satisfy EU AI Act explainability mandates. |
Research Methodology
A standing panel of chief learning officers, instructional design directors, HRIS integration specialists, and corporate procurement managers provided ongoing calibration against platform deployment timelines and budget cycle realities. Primary fieldwork combined structured interviews with secondary validation through SEC filings, hyperscaler capex disclosures, and government digital literacy campaign documentation. Bottom-up learner adoption modeling and top-down enterprise contract value triangulation anchored segmentation outputs.
Consistency checks validated volume and value projections against external benchmarks across the analysis window. The analytical framework modeled deployment mode, organization size, vertical industry, integration complexity, and regional regulatory cluster. CAGRs derived from historical platform subscription trajectories and corporate L&D budget growth patterns, with inputs including GDPR compliance cost estimates and India's Digital Personal Data Protection Act implementation timelines.
Underlying assumptions cover sustained corporate training budget expansion and accreditation equivalency progression, with deviation risk concentrated in cloud infrastructure pricing volatility and free-to-freemium substitution acceleration. Practitioners should keep alternative scenarios live as EU AI Act enforcement intensity and India tier-city penetration rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Distance Learning and Online Education
Online Tutoring Market
Distance Learning and Online Education
MOOC Market
Distance Learning and Online Education
Europe E-Learning Market
Distance Learning and Online Education
Online K-12 Education Market
Distance Learning and Online Education
Cloud-Based Training Software Market
Distance Learning and Online Education
Africa E-Learning Market
Distance Learning and Online Education
E-Learning Market
Distance Learning and Online Education
Global Self-Paced E-Learning Market
Distance Learning and Online Education
Online Tutoring Services Market
Distance Learning and Online Education
Digital Course Recorder Market
Distance Learning and Online Education
Europe MOOC Market
Distance Learning and Online Education
Massive Open Online Courses Market
Distance Learning and Online Education
GCC Massive Open Online Course (MOOC) Market
Distance Learning and Online Education
Saudi Arabia E-Learning Market
Distance Learning and Online Education
GCC E-Learning Market
Distance Learning and Online Education
Global Online Tutoring Software Market