
 Global Learning Management Systems (LMS) Market | 2026-2036
Global Learning Management Systems (LMS) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Learning Management Systems (LMS) Market Foresight
Enterprise digital literacy is rotating toward AI-augmented instructional design, forcing LMS vendors to rebuild core architectures around adaptive learning engines. SAP Litmos leverages its parent company's ERP installed base to embed training workflows inside existing enterprise resource planning environments. Docebo anchors its competitive position through native generative AI content creation tools that reduce course development cycles for multinational employers.
A Learning Management System constitutes a software application for administering, documenting, tracking, and delivering educational courses or training programs, typically supporting SCORM or xAPI content interoperability standards alongside multi-tenant cloud architectures. Cloud-based deployment now dominates new procurement as organizations abandon on-premise server maintenance for elastic AWS, Azure, or Google Cloud infrastructure. Skill development use cases within large enterprises represent the fastest-expanding margin pool, while academic institutions sustain longer sales cycles with lower annual contract values.
The EU AI Act and GDPR impose algorithmic transparency requirements on adaptive learning systems processing European employee data, compelling vendors to build explainable recommendation engines. The US Department of Education's enforcement of Section 508 accessibility standards shapes federal and state procurement specifications, filtering out non-compliant bidders. Stakeholders must evaluate how emerging interoperability mandates from ISO and IEC technical committees will redefine competitive moats around proprietary content formats.
Market Dynamics
Enterprise learning architectures are undergoing forced reconstruction as generative AI engines displace static content repositories, compelling vendors to rebuild core platforms around real-time adaptive personalization rather than scheduled course delivery.
Growth Catalysts
- HIPAA Compliance Mandates:Healthcare systems across the United States face documented workforce certification requirements that drive SaaS-based procurement for auditable training records.
- OSHA Workforce Rules:Industrial employers must maintain verifiable safety training logs, creating recurring platform subscriptions tied to regulatory inspection cycles.
- AI-Augmented Instructional Design:Adaptive learning engines now automate content sequencing, reducing manual curriculum development labor for multinational training departments.
Market Restraints
- Data Localization Requirements:GDPR and EU AI Act provisions force European deployments onto region-specific cloud infrastructure, fragmenting vendor economics.
- SCORM Interoperability Lock-in:Legacy content formats create switching costs that delay platform migrations even when superior alternatives emerge.
- Enterprise IT Integration Complexity:ERP embedding requires specialized implementation partnerships that concentrate supply among systems integrators.
Strategic Opportunities
- India Workforce Development:Central government skilling initiatives and state-level education technology procurement create greenfield SaaS adoption curves.
- xAPI Telemetry Convergence:Learning record stores merging with HR analytics platforms enable outcome-linked training investment justification.
- Micro-Credentialing Standards:ISO technical committee work on portable digital badges opens interoperability revenue streams for compliant vendors.
Industry Challenges
- Prompt Engineering Talent Scarcity:Generative AI content tools require instructional designers with hybrid pedagogical and technical capabilities that remain scarce.
- Section 508 Accessibility Certification:Federal procurement filters in the United States disqualify platforms lacking screen-reader compatibility and keyboard navigation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Learning Management Systems (LMS) Market |
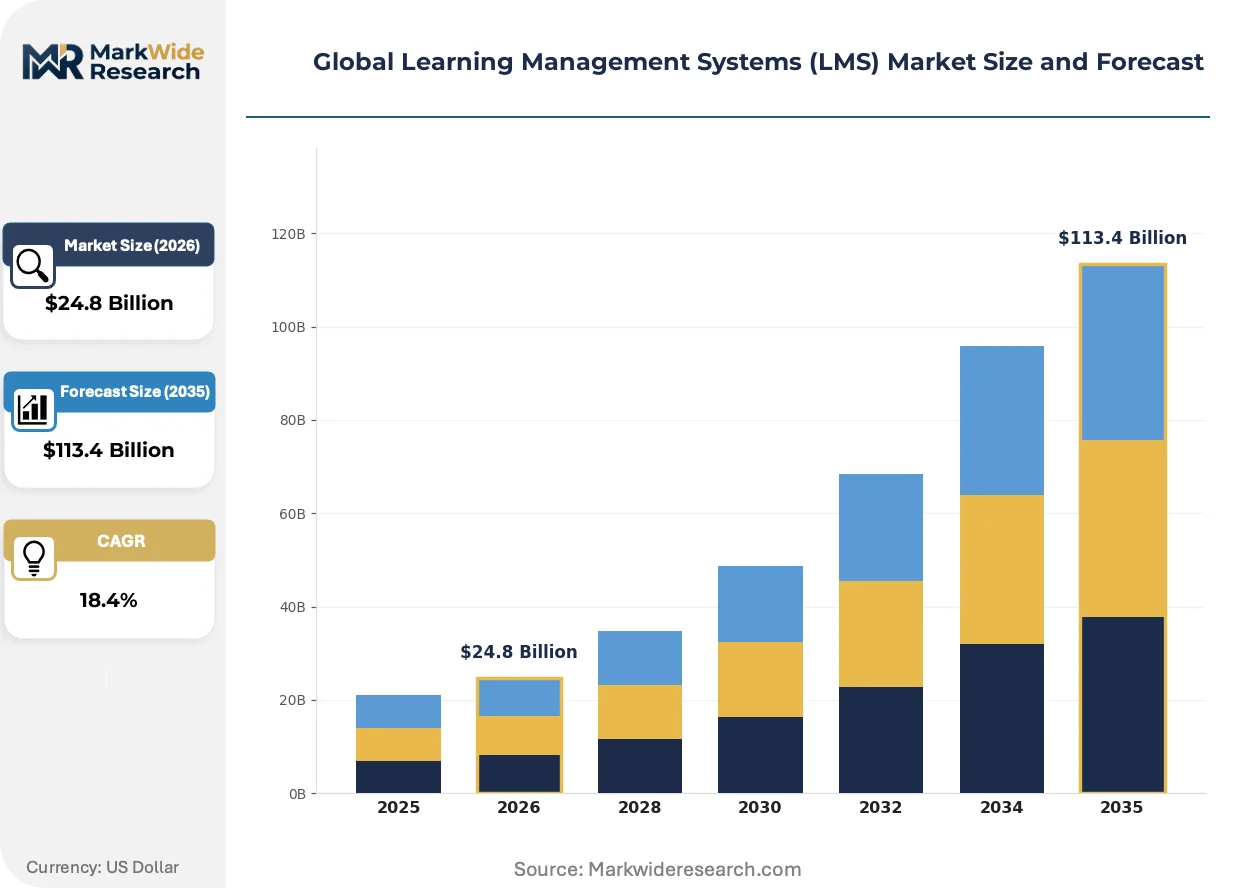
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $113.4 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Hosted Solution Type: Content Management, Performance Management, Compliance Management, Virtual Classroom, Social Learning Use Case: Corporate Training, Employee Onboarding, Skill Development, Customer Education, Partner Training End User: SMEs, Large Enterprises, Government Agencies, Nonprofit Organizations, Academic Institutions |
| Companies Covered | SAP Litmos, Absorb LMS, Docebo, 360Learning, TalentLMS, D2L Brightspace, CYPHER Learning, LearnUpon, Adobe Learning Manager, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Learning Management Systems (LMS) Market Shifts & Advancements
Learning platform architectures are splitting between monolithic enterprise suites and composable API-first stacks, with procurement patterns diverging sharply by organization size and technical maturity.
Generative AI content engines now compose assessments, simulations, and multilingual variants from source documents. Large employers with distributed workforces adopt these tools fastest, compressing course production timelines from weeks to hours. The technology is bifurcating vendor strategies between those building native capabilities and those partnering with foundation model providers.
The EU AI Act mandates explainable logic for algorithmic recommendations affecting European employees. Vendors must document decision pathways for adaptive learning paths and skill gap predictions. Healthcare and financial services verticals face the steepest compliance ramps as they process sensitive worker performance data.
Subscription fatigue among mid-market buyers is fragmenting procurement toward modular point solutions. HR departments now assemble best-of-breed stacks for content authoring, delivery, and analytics rather than accepting bundled suites. This pattern concentrates in the United States where venture-backed startups compete aggressively on single-feature excellence.
Global Learning Management Systems (LMS) Market Segmentation
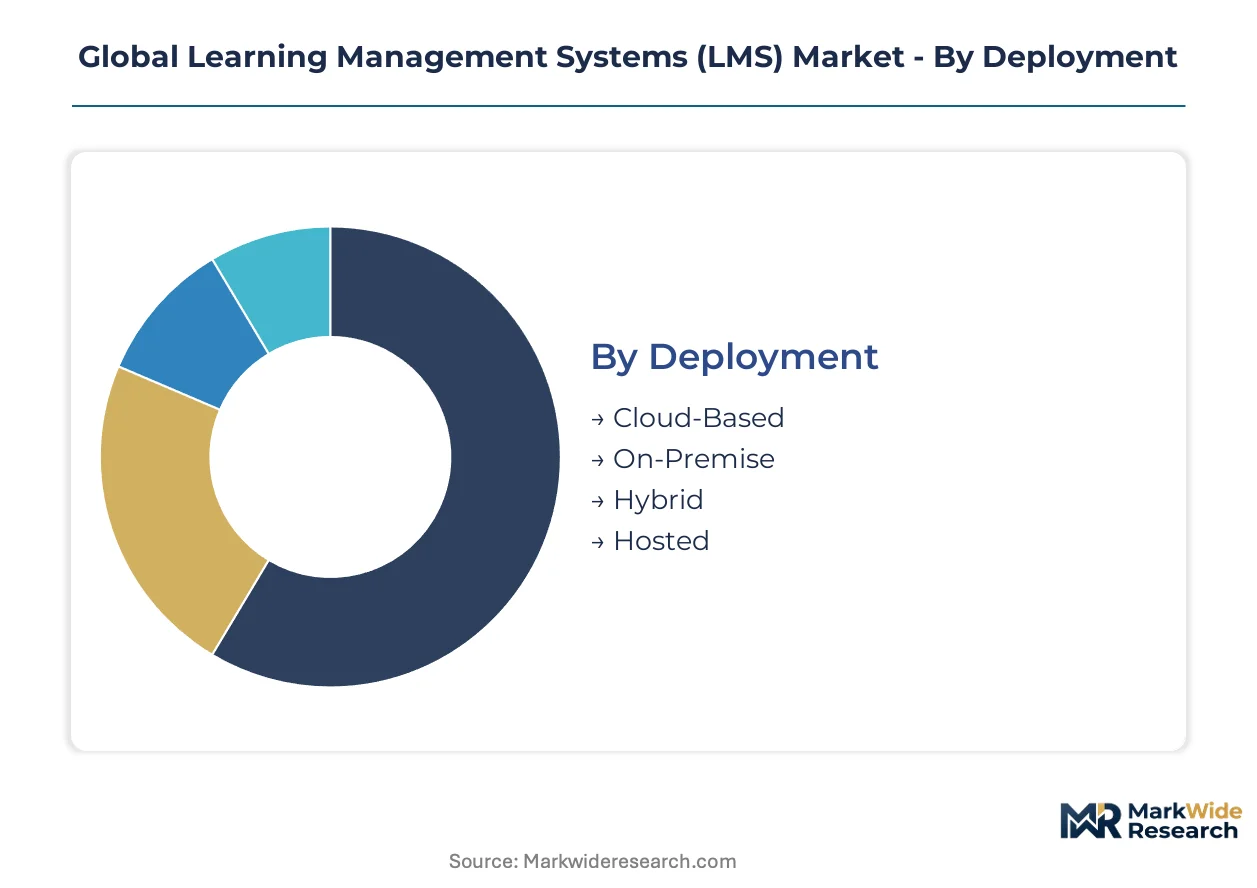
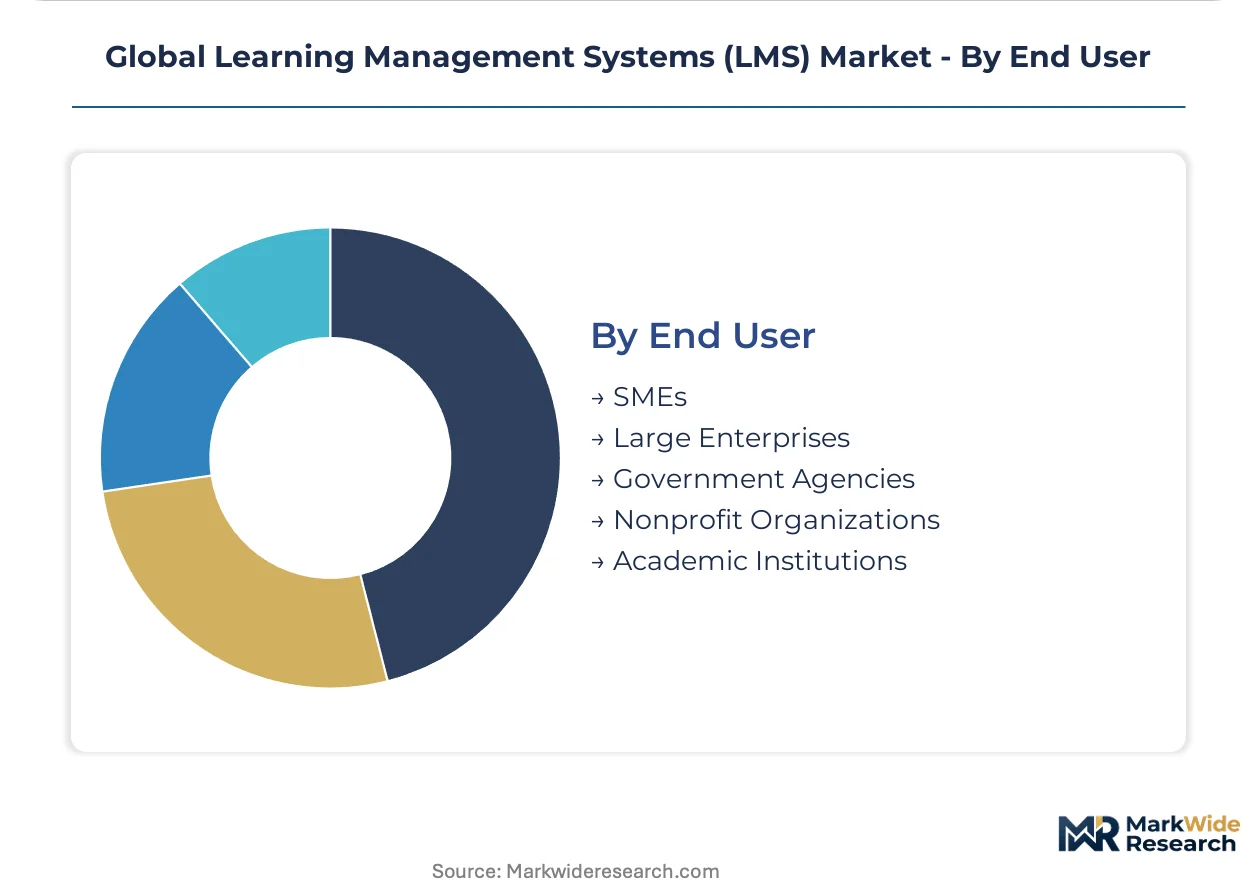
Segmentation in the LMS market reveals how procurement patterns split across technical architectures, regulatory workloads, and organizational scale. Buyers select deployment models and solution types based on data sovereignty requirements, compliance audit intensity, and integration complexity with existing HR systems.
Deployment:
GDPR and EU AI Act data localization rules force European buyers toward region-locked cloud infrastructure, while HIPAA and OSHA audit trails drive US healthcare and industrial employers toward specific hosting configurations.
- Cloud-Based:Multi-tenant SaaS architectures on AWS, Azure, or Google Cloud dominate new procurement. US healthcare systems select these for elastic scaling during compliance audit seasons, with HIPAA Business Associate Agreements mandatory in vendor contracts.
- On-Premise:Dedicated server installations within organizational data centers persist in defense contracting and classified government training. The US Department of Defense and similar agencies mandate air-gapped environments for sensitive workforce certification.
- Hybrid:Split architectures keep sensitive personnel records on local servers while pushing content delivery to cloud edge nodes. German automotive manufacturers and French pharmaceutical firms deploy this model to satisfy works council data access requirements under CNIL guidelines.
- Hosted:Single-tenant managed deployments on vendor-controlled infrastructure serve mid-market buyers lacking internal IT capacity. Indian state education departments and Brazilian federal agencies favor this model for predictable subscription economics without operational burden.
Cloud-Based handles the majority of throughput; Hybrid is gaining share fastest as European data residency rules tighten.
Solution Type:
Cost tier differentiation separates enterprise suites from modular point solutions, with compliance automation commanding premium pricing against content authoring tools.
- Content Management:Authoring environments supporting SCORM and xAPI packaging with version control and multilingual variant generation. Large multinational employers in the United States compress course production cycles using generative AI tools embedded in these platforms.
- Compliance Management:Automated certification tracking with audit-ready reporting for HIPAA, OSHA, and FDA training mandates. US hospital systems and medical device manufacturers treat this as non-discretionary spend with dedicated budget lines.
- Performance Management:Skill gap analytics linking learning completion to competency frameworks and succession planning. Talent-intensive sectors including professional services and technology deploy these for retention-linked development programs.
- Virtual Classroom:Synchronous delivery with breakout rooms, whiteboarding, and attendance verification. Academic institutions and corporate universities maintain these for cohort-based professional certification programs.
- Social Learning:Peer-to-peer knowledge sharing with expert identification and user-generated content curation. Technology sector employers with distributed engineering teams adopt these to capture informal technical knowledge transfer.
Compliance Management captures the highest contract values; Content Management is expanding most quickly as generative AI reduces production labor.
Use Case:
Application intensity varies by workforce mobility, with high-churn scenarios driving recurring platform subscriptions against one-time implementation projects.
- Corporate Training:Continuous upskilling programs tied to business unit performance metrics. Financial services firms in New York and London deploy these for regulatory recertification cycles with quarterly completion deadlines.
- Employee Onboarding:Structured orientation workflows integrating HRIS data with role-specific learning paths. Technology sector employers with rapid hiring velocity automate these to reduce time-to-productivity for software engineering cohorts.
- Skill Development:Competency-based progression linking micro-credentials to promotion eligibility. Indian IT services firms and German manufacturing apprenticeships scale these for workforce transformation initiatives.
- Customer Education:External-facing academies driving product adoption and renewal rates. SaaS vendors in the United States treat these as revenue-generating functions with dedicated customer success ownership.
- Partner Training:Certification programs for reseller and implementation partner ecosystems. Enterprise software vendors including SAP and Salesforce maintain these to ensure consistent service delivery quality across third-party channels.
Corporate Training absorbs the largest platform investment; Skill Development shows the steepest expansion trajectory as national workforce development programs scale.
End User:
Customer type determines sales cycle length and annual contract value, with procurement authority concentrated differently across organizational scale.
- Large Enterprises:Global deployments with multi-year contracts, custom integration requirements, and dedicated customer success resources. Fortune 500 manufacturers and healthcare systems in the United States represent the core revenue base for established vendors.
- SMEs:Rapid implementation with standardized configurations and per-user pricing. UK mid-market professional services firms and Australian healthcare clinics select these for compliance automation without enterprise overhead.
- Academic Institutions:Semester-aligned procurement with extended evaluation cycles and consortium purchasing. US state university systems and Indian central universities drive volume through shared service agreements.
- Government Agencies:Federal and state procurement with Section 508 accessibility mandates and security clearance requirements. US federal civilian agencies and defense contractors maintain separate vendor qualification processes.
- Nonprofit Organizations:Grant-funded implementations with donor reporting requirements and volunteer management integration. International development NGOs and US community health centers operate on constrained budgets with high user volume.
Large Enterprises dominate vendor revenue concentration; Government Agencies are climbing the fastest on contract value as federal workforce modernization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare systems in the United States deploy LMS platforms for HIPAA-mandated workforce certification, while European manufacturers prioritize GDPR-compliant skill tracking under works council agreements. Indian IT services firms scale cloud-based training for government skilling initiatives, creating divergent procurement patterns across major economies.
United States
Hospital networks and medical device manufacturers drive SaaS procurement for auditable OSHA and HIPAA training records. The Department of Education enforces Section 508 accessibility standards that filter federal and state procurement specifications. Boston's healthcare technology corridor and Austin's enterprise software cluster host concentrated vendor implementation partnerships.
Germany
Automotive manufacturers and industrial employers adopt hybrid deployments to satisfy works council data access requirements under CNIL-aligned German privacy frameworks. The EU AI Act mandates explainable logic for algorithmic skill gap predictions affecting German workforces. Stuttgart's automotive engineering cluster and Munich's industrial software ecosystem anchor regional LMS integration expertise.
India
Central government skilling initiatives and state-level education technology procurement create greenfield SaaS adoption curves for IT services and manufacturing apprenticeships. The PLI scheme for electronics manufacturing drives workforce transformation programs requiring scalable certification platforms. Bangalore's technology services corridor and Hyderabad's IT cluster concentrate platform deployment for multinational employer training operations.
United Kingdom
Mid-market professional services firms select standardized configurations for compliance automation without enterprise overhead costs. GDPR provisions shape cloud infrastructure decisions for London-based financial services training departments. The City of London's financial services cluster and Manchester's professional services hub drive demand for regulatory recertification cycles with quarterly completion deadlines.
Japan
Large manufacturers deploy performance management modules linking learning completion to competency frameworks and succession planning. METI workforce development programs encourage platform adoption for aging workforce knowledge transfer initiatives. Tokyo's corporate headquarters concentration and Osaka's manufacturing belt sustain multi-year enterprise contracts with custom integration requirements.
Global Learning Management Systems (LMS) Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with ERP-embedded platforms commanding premium positioning against modular point solutions. Consolidation pressure intensifies as generative AI capabilities separate architecture-rebuilt vendors from legacy repository providers. Two strategic archetypes dominate: enterprise suite vendors leveraging parent-company installed bases, and API-first specialists assembling best-of-breed stacks. Competitive moves concentrate on M&A for AI talent acquisition and strategic partnerships for regional cloud infrastructure compliance.
Within the ERP-anchored tier, SAP Litmos exemplifies parent-company platform embedding, while Docebo occupies a position among native AI content creation specialists. Absorb LMS represents the mid-market standardized configuration archetype serving rapid implementation demand. These three vendors illustrate how competitive positioning splits between integration depth and feature velocity.
| Leading Market Players |
|---|
| SAP Litmos |
| Absorb LMS |
| Docebo |
| 360Learning |
| TalentLMS |
| D2L Brightspace |
| CYPHER Learning |
| LearnUpon |
| Adobe Learning Manager |
| Others |
Supply & Pricing Matrix
Per-seat SaaS subscription contracts with annual renewal clauses lock in multi-year revenue visibility for vendors while capping buyer cost exposure. HIPAA-compliant healthcare systems in the United States and GDPR-bound European manufacturers negotiate these terms to balance audit-ready infrastructure access against budget predictability.
Pricing Analysis
Long-term subscription contracts dominate enterprise procurement, with three-tier pricing structure across premium, standard, and economy levels tied to feature depth and support tiers. Price differentiation rests on compliance certification grade (HIPAA Business Associate Agreement, EU AI Act algorithmic transparency) and integration complexity with SAP or Oracle ERP environments. Cost compression in the mid-market tier is intensifying because venture-backed point solutions compete aggressively on single-feature excellence. SMEs exhibit highest price sensitivity, while Fortune 500 healthcare systems accept premium tiers for dedicated customer success resources.
Supply Chain Analysis
Just-in-time cloud resource provisioning prevails across vendor operations, with AWS, Azure, and Google Cloud capacity scaling elastically to match compliance audit season demand spikes. Software development concentrates in the United States, India, and Ireland, with technical support hubs distributed to cover timezone requirements. Raw material dependencies center on GPU compute instances for generative AI training, open-source machine learning frameworks, and SCORM/xAPI content interoperability libraries. Single-source vulnerability runs through hyperscaler infrastructure concentration. Distribution runs through direct sales teams for enterprise accounts and self-service portals for mid-market buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The LMS market is entering a cyclical recovery phase as federal workforce development incentives in the United States and India's PLI scheme for electronics manufacturing drive platform procurement. Compliance mandate intensity serves as the cyclical driver, with HIPAA, OSHA, and EU AI Act enforcement creating non-discretionary budget lines.
For Market Incumbents: Secure AI engineering talent through targeted acquisition of adaptive learning specialists before foundation model providers capture the instructional design layer. Lock in ERP integration partnerships with SAP and Oracle to defend against modular point solutions eroding enterprise account control. Vertical integration into proprietary content formats creates switching costs that delay platform migrations. For New Entrants and Emerging Players: Micro-credentialing interoperability for ISO-compliant digital badges represents the most penetrable service-layer gap where incumbents under-serve. Target Indian state education departments and Brazilian federal agencies with hosted deployment models that eliminate IT operational burden. Lead with generative AI content creation tools that compress course production timelines from weeks to hours. For Investors and Strategic Acquirers: Capital is best deployed toward API-first specialists with native adaptive learning engines rather than legacy repository providers facing architecture reconstruction costs. The acquisition target archetype combines xAPI telemetry convergence capabilities with HR analytics platform integration. The signal to watch is EU AI Act enforcement intensity affecting algorithmic recommendation transparency requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Generative AI Content Engine Development | Native capabilities reduce course production labor for multinational employers using Docebo-style tools. |
| ERP Embedded Training Workflows | SAP Litmos leverages parent-company installed base to embed learning inside existing enterprise environments. |
| xAPI Learning Record Store Integration | Merging telemetry with HR analytics platforms enables outcome-linked training investment justification. |
| Regional Cloud Infrastructure Partnerships | GDPR and EU AI Act compliance requires explainable recommendation engines on European-hosted infrastructure. |
| Section 508 Accessibility Certification | Federal procurement filters in the United States disqualify platforms lacking screen-reader compatibility. |
Research Methodology
Operator-level perspectives from chief learning officers, HRIS integration specialists, instructional designers, and compliance audit managers anchored the qualitative base. Primary interviews combined with secondary validation from SEC filings of publicly traded LMS vendors, hyperscaler capex disclosures from AWS and Azure, and federal procurement databases from USASpending.gov. Bottom-up and top-down triangulation cross-checked vendor-reported metrics against customer-side deployment scale.
Sensitivity analysis tested forecast robustness across deployment model adoption curves, generative AI capability diffusion rates, and regulatory enforcement intensity variations. Segmentation dimensions modeled include deployment architecture, solution type, use case intensity, and end-user scale tier across the projection horizon. CAGRs were derived from installed base growth, expansion revenue per account, and new logo acquisition velocity in healthcare and manufacturing verticals.
Underlying assumptions cover sustained HIPAA and OSHA enforcement intensity, EU AI Act implementation timelines, and cloud infrastructure cost trajectories, with deviation risk concentrated in generative AI talent scarcity and SCORM interoperability lock-in persistence. Revision becomes warranted when federal workforce development incentive funding crosses threshold reductions or when xAPI adoption accelerates beyond baseline assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Learning Management Systems (LMS)
Global Classroom Management Software Market
Learning Management Systems (LMS)
Qatar E-Learning Management System Market
Learning Management Systems (LMS)
Global Mobile Learning Market
Learning Management Systems (LMS)
Global Corporate M-Learning Market
Learning Management Systems (LMS)
Healthcare LMS Software Market
Learning Management Systems (LMS)
School Management System Market
Learning Management Systems (LMS)
E-Learning Solutions Market
Learning Management Systems (LMS)
Global Training Software Market
Learning Management Systems (LMS)
Managed Learning Service Market
Learning Management Systems (LMS)
Corporate Learning Management System Market
Learning Management Systems (LMS)
Smart Learning Systems Market
Learning Management Systems (LMS)
Global Exam Management Software Market
Learning Management Systems (LMS)
Asia-Pacific Learning Management Systems Market