
 Oman Private K-12 Market | 2026-2036
Oman Private K-12 Market Size, Share, and Industry Trends Forecast 2026-2036
Oman Private K-12 Market Analytics
AI-powered adaptive learning platforms are reshaping how private K-12 institutions in Oman deliver personalized instruction and track student progress. ABQ Education Group leverages its multi-campus network to sustain technology integration across its schools. British School Muscat anchors premium positioning through its established International Baccalaureate offering. Knowledge Gate International School differentiates via STEM-focused programming and modern campus infrastructure.
Oman private K-12 education encompasses independently operated primary and secondary institutions serving students from kindergarten through grade twelve, typically charging tuition fees and operating outside the government-funded public system with class sizes ranging from fifteen to thirty pupils. These schools primarily prepare students for university admission abroad or local higher education, with curricula aligned to international examination boards. International Schools command the highest fee tiers and attract expatriate families seeking globally transferable credentials, while British Curriculum Schools occupy a mature but stable position serving both local elites and foreign residents. Cambridge Program enrollment is expanding fastest among mid-fee institutions responding to parent demand for recognized qualifications without premium pricing.
The Ministry of Education in Oman governs private school licensing, curriculum approval, and teacher qualification standards, while the country's national education strategy pushes toward greater localization of administrative leadership in foreign-branded institutions. Compliance with these evolving requirements shapes capital allocation decisions for school operators considering campus expansion or curriculum diversification. Stakeholders must monitor regulatory shifts around Omani national curriculum integration mandates and their impact on pricing power and enrollment mix.
Market Dynamics
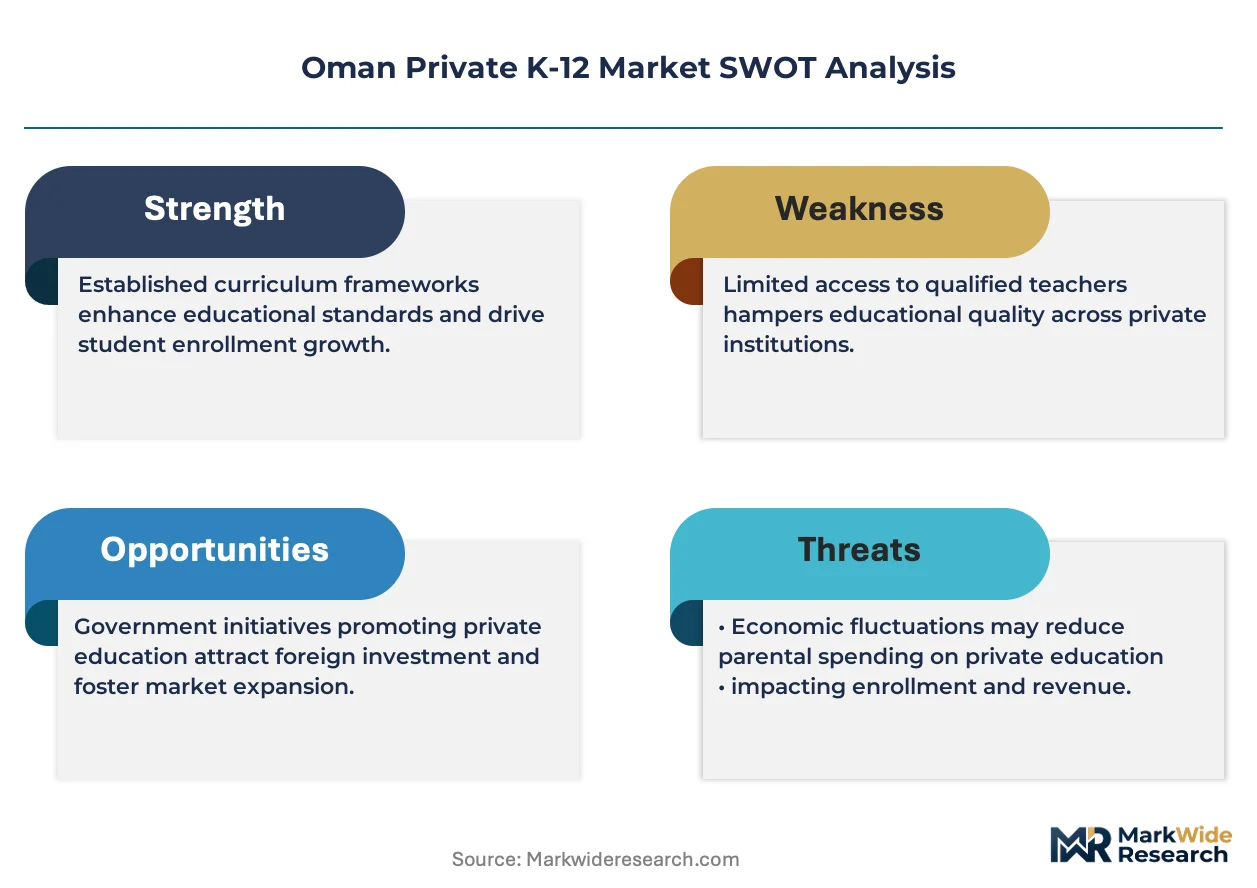
The Ministry of Education's updated private school licensing framework is tightening quality standards and forcing capital reallocation toward compliance infrastructure across Oman's private K-12 sector.
Growth Catalysts
- Expatriate workforce expansion:Oil and gas sector families are clustering in Muscat Governorate and demanding internationally transferable credentials for their children.
- STEM curriculum mandates:National education strategy priorities are accelerating adoption of science and technology programming in mid-fee institutions.
- AI-powered adaptive platforms:Personalized instruction tools are reducing per-student instructional costs while improving learning outcome tracking.
Market Restraints
- Teacher qualification requirements:Ministry of Education standards for administrative localization are compressing the available talent pool for leadership roles.
- Campus infrastructure costs:Modern facility requirements for licensing approval demand substantial upfront capital deployment in Muscat's concentrated real estate market.
- Public school substitution:Government-funded alternatives with zero tuition create pricing ceiling pressure on mid-tier private operators.
Strategic Opportunities
- Al Batinah region penetration:Industrial corridor growth outside Muscat Governorate is creating underserved demand pockets for mid-fee Cambridge Program institutions.
- Blended learning convergence:Integration of physical campus infrastructure with remote instruction platforms is enabling enrollment scale without proportional facility expansion.
- Diplomatic mission demand:International corporate headquarters clustering is sustaining premium-tier pricing power for International Baccalaureate offerings.
Industry Challenges
- Localization compliance timelines:Omani national curriculum integration mandates are forcing curriculum redesign cycles that disrupt established examination preparation sequences.
- Administrative talent pipeline:The shortage of Omani nationals with international school leadership experience is slowing ownership transition requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oman Private K-12 Market |
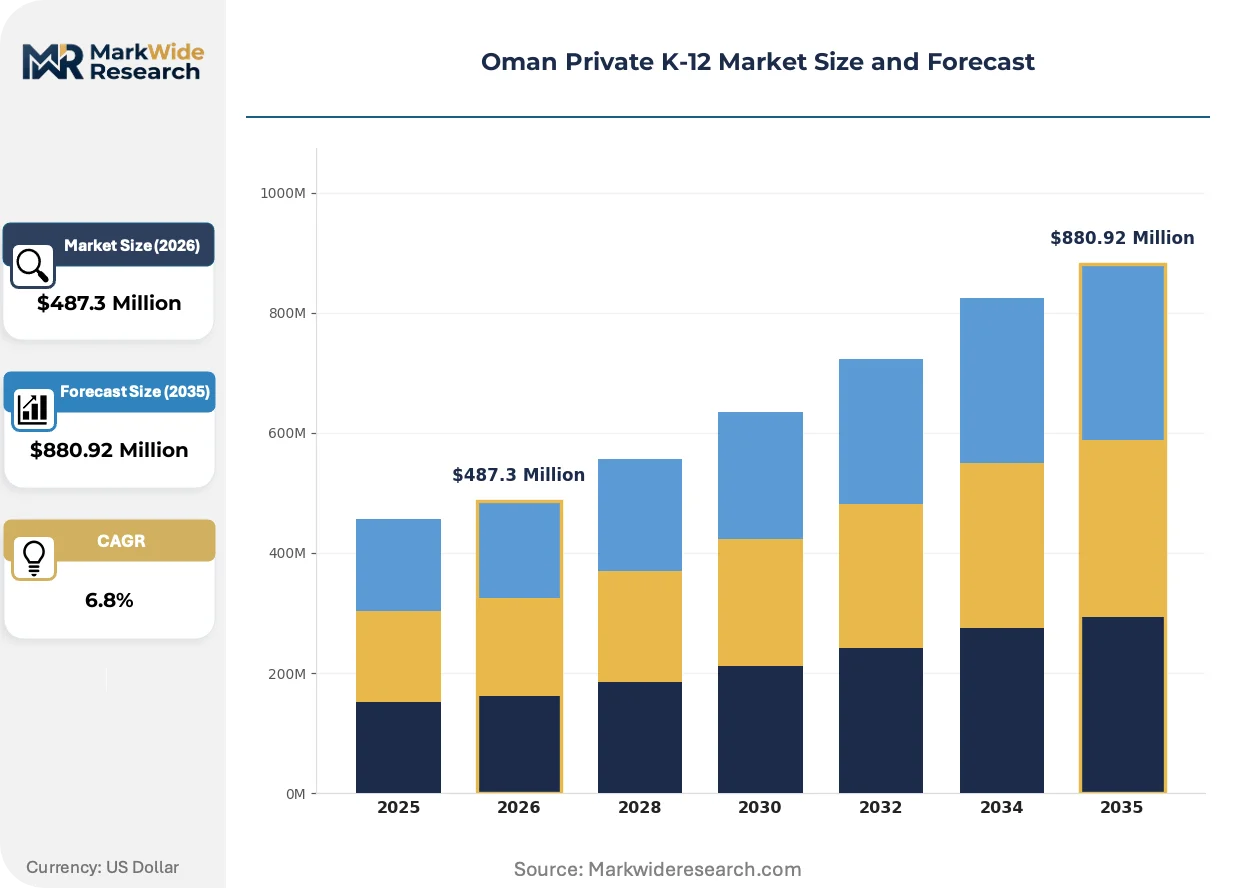
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | School Type: International Schools, National Schools, British Curriculum Schools, American Curriculum Schools Enrollment Size: Small Schools, Medium Schools, Large Schools, Mega Schools Tuition Fee Tier: Low Fee, Mid Fee, High Fee, Premium Fee Curriculum Offered: IB Program, Cambridge Program, Omani National Curriculum, Montessori Program |
| Companies Covered | A'Soud Global School, ABQ Education Group, British School Muscat, Indian School Seeb, Indian School Darsait, Indian School Muscat, Knowledge Gate International School, Qatar Private School, American International School of Muscat, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oman Private K-12 Market Evolving Landscape
Digital infrastructure investment is compressing operational cost structures while regulatory localization mandates are reshaping ownership and curriculum requirements across Oman's private K-12 landscape.
Learning management systems with embedded assessment analytics are digitizing how private K-12 institutions track student progress and personalize instruction delivery. Mid-fee schools in Muscat Governorate are deploying these platforms fastest to compete with premium-tier alternatives. This technology shift is digitizing the traditional teacher-parent communication channel and enabling real-time academic intervention.
The Ministry of Education's administrative localization requirements are mandating Omani national leadership in foreign-branded school operations. This policy is forcing curriculum and governance restructuring across British Curriculum Schools and International Schools alike. Premium institutions with established multi-campus networks are responding by accelerating leadership development programs to meet compliance deadlines.
Parent preference is rotating toward STEM-focused programming and recognized international examination boards without premium pricing. Mid-fee Cambridge Program institutions in Muscat and Al Batinah are capturing this demand shift from traditional British Curriculum alternatives. This behavioral change is most visible among expatriate families in the oil and gas sector seeking globally transferable credentials at controlled cost points.
Oman Private K-12 Market Segmentation
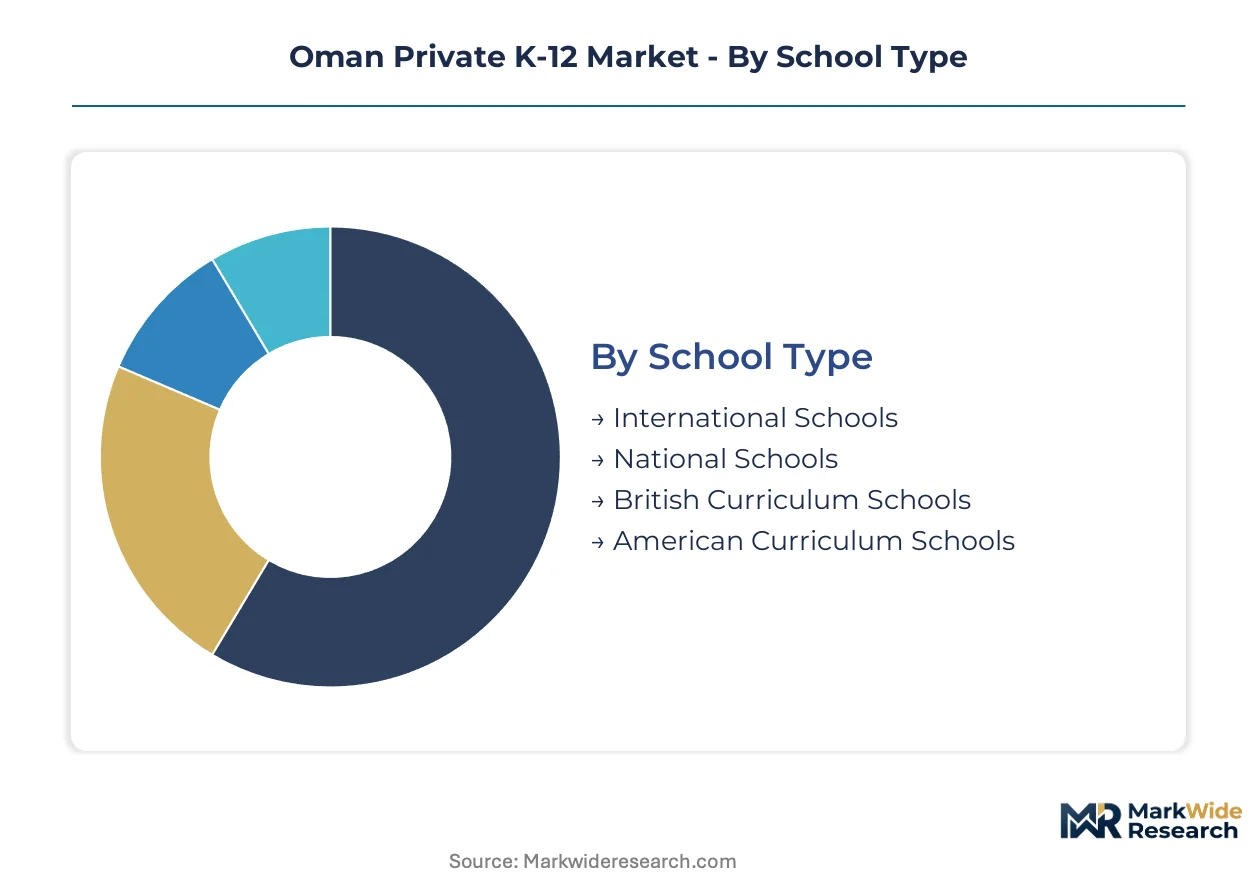
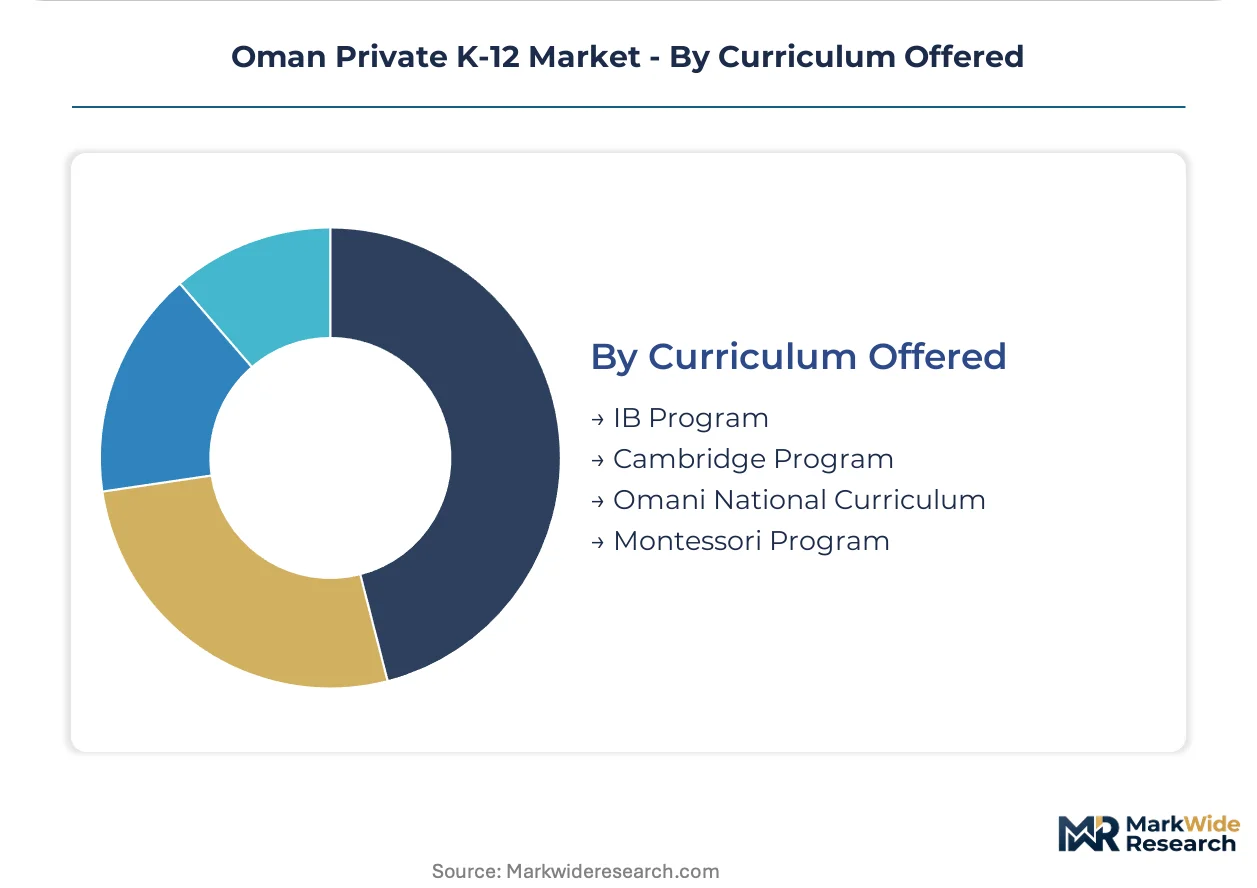
Segmentation reveals how Oman's private K-12 operators allocate capital across distinct demand pockets. School type and curriculum choices determine pricing power and enrollment stability in a market shaped by expatriate workforce needs and Ministry of Education compliance requirements.
School Type:
After-sales service intensity varies sharply across school types, with international institutions requiring sustained parent relationship management and examination board liaison support that national alternatives rarely match.
- International Schools:These institutions deliver globally recognized curricula with extensive extracurricular programming and university counseling services. Demand concentrates in Muscat Governorate among diplomatic missions and multinational corporate headquarters, where families prioritize credential transferability and English-medium instruction.
- National Schools:These schools blend Omani national curriculum requirements with private operational autonomy, serving local families seeking quality alternatives to public education. Enrollment growth in Al Batinah and Dhofar regions is accelerating as industrial corridor expansion creates new demand pockets outside the capital.
- British Curriculum Schools:Established operators with mature examination preparation sequences and localized administrative structures.
- American Curriculum Schools:Institutions aligned to US diploma standards, attracting North American expatriate families in the oil and gas sector.
By volume, National Schools lead enrollment. By growth pace, International Schools are ahead.
Enrollment Size:
Operational cost structures scale non-linearly with enrollment size, as fixed administrative and compliance costs distribute across larger student bodies while facility requirements step up at threshold points.
- Small Schools:Institutions with under 300 students operating with lean administrative teams and limited curriculum breadth. These operators struggle to amortize compliance costs across small revenue bases, concentrating in niche religious or alternative education segments.
- Medium Schools:Campuses serving 300-800 students with balanced cost efficiency and personalized attention. These institutions capture the fastest enrollment growth in Muscat's mid-fee segment, where parents trade premium facilities for manageable class sizes and recognized qualifications.
- Large Schools:Established operators with 800-1,500 students and dedicated facilities for science laboratories, sports, and performing arts.
- Mega Schools:Multi-campus networks or single-site institutions exceeding 1,500 students with centralized procurement and shared administrative functions.
By student count, Medium Schools dominate new enrollment. By revenue concentration, Mega Schools capture disproportionate share.
Tuition Fee Tier:
Fee stratification directly maps to curriculum prestige and facility capital intensity, with premium tiers requiring sustained reinvestment to maintain positioning against public school substitution.
- Premium Fee:Annual tuition exceeding 10,000 OMR serving the highest-income expatriate and Omani elite families. International Baccalaureate offerings and purpose-built campuses in Muscat's diplomatic quarter anchor this segment's positioning.
- High Fee:Pricing between 5,000-10,000 OMR attracting professional-class families prioritizing recognized examination boards. British Curriculum Schools with established track records dominate this tier, though Cambridge Program alternatives are gaining traction.
- Mid Fee:Annual charges of 2,500-5,000 OMR where Cambridge Program expansion is steepest.
- Low Fee:Sub-2,500 OMR pricing serving cost-conscious families with basic facilities and limited extracurricular programming.
By enrollment volume, Mid Fee institutions lead. By margin expansion, Premium Fee tier is climbing fastest.
Curriculum Offered:
Curriculum choice determines examination board relationships, teacher recruitment requirements, and parent expectations around university placement outcomes that shape long-term enrollment stability.
- Cambridge Program:IGCSE and A-Level qualifications delivering globally recognized credentials at controlled cost points. Mid-fee institutions across Muscat and Al Batinah are expanding Cambridge offerings fastest, responding to parent demand for examination rigor without premium pricing.
- IB Program:International Baccalaureate's comprehensive framework requiring substantial teacher training investment and small class ratios. Premium-tier International Schools in Muscat Governorate anchor this curriculum's presence, with diploma recognition driving demand among families anticipating university admission abroad.
- Omani National Curriculum:Ministry-mandated content with Arabic-medium instruction serving families prioritizing local cultural integration.
- Montessori Program:Early childhood-focused methodology with limited penetration beyond kindergarten levels in Oman's market.
By school count, Cambridge Program leads. By parent preference shift, IB Program is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Private K-12 education demand flows from Muscat Governorate toward emerging industrial corridors in Al Batinah and Dhofar, with enrollment growth tracking expatriate workforce distribution across Oman's economic zones.
Muscat Governorate
Diplomatic missions and international corporate headquarters concentrate demand for premium-tier International Baccalaureate offerings in Oman's capital. The Ministry of Education enforces updated licensing frameworks that tighten quality standards for new campus approvals. Al Qurum and Madinat Sultan Qaboos host the densest cluster of established British Curriculum Schools serving oil and gas sector families.
Al Batinah Region
Industrial corridor expansion along the coastal strip generates underserved demand for mid-fee Cambridge Program institutions. The Ministry of Education's administrative localization requirements apply uniformly across all governorates, compressing leadership talent availability. Sohar Port and the surrounding free zone attract manufacturing investment that brings expatriate families seeking internationally transferable credentials.
Dhofar Governorate
Salalah's logistics hub and port modernization create incremental enrollment opportunities outside traditional demand centers. National education strategy priorities for STEM curriculum integration apply here with identical compliance timelines. The city's emerging status as a regional shipping gateway draws technical specialists from South Asia and East Africa.
Ad Dakhiliyah Governorate
Nizwa's university town character sustains demand for secondary schools preparing students for higher education admission. The Ministry of Education mandates Omani national curriculum integration regardless of regional market size. Local agricultural and heritage tourism economies limit expatriate population scale compared to coastal industrial zones.
Dhahirah Governorate
Ibri's position at the junction of desert and mountain economies creates niche demand for affordable private alternatives to public education. Teacher qualification requirements from the Ministry of Education raise operational barriers proportionally with enrollment scale. The region functions as a transit corridor rather than a destination for international workforce deployment.
Oman Private K-12 Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Oman's private K-12 sector, with multi-campus networks leveraging centralized procurement against single-site institutions emphasizing curriculum differentiation. The market structure tilts toward consolidation among established operators with proven examination track records. Three archetypes dominate: multi-campus education groups with technology integration capabilities, single-site premium institutions anchored by International Baccalaureate authorization, and mid-fee Cambridge Program specialists targeting cost-conscious expatriate families. Competitive moves center on campus expansion into underserved regions and strategic partnerships with international examination boards.
Within the multi-campus network tier, ABQ Education Group occupies a position representing scale-driven operational integration across multiple Omani locations. British School Muscat exemplifies the premium single-site archetype through its established International Baccalaureate positioning in Muscat Governorate. Knowledge Gate International School sits within the STEM-focused differentiation segment, anchoring modern infrastructure investment as a competitive vector.
| Leading Market Players |
|---|
| A'Soud Global School |
| ABQ Education Group |
| British School Muscat |
| Indian School Seeb |
| Indian School Darsait |
| Indian School Muscat |
| Knowledge Gate International School |
| Qatar Private School |
| American International School of Muscat |
| Others |
Value Network & Pricing Analysis
The Port of Salalah logistics corridor shapes cost dynamics across Oman's private K-12 sector, concentrating supply-side leverage among Muscat-based facility developers while downstream price differentiation tracks curriculum prestige and campus infrastructure tiers.
Pricing Analysis
Cost-plus contracts with Ministry of Education compliance indexation dominate capital expenditure agreements for new campus development. Three-tier pricing structure across premium, standard, and economy levels segments annual tuition from sub-2,500 OMR to above 10,000 OMR, with International Baccalaureate authorization and purpose-built science laboratories as primary price differentiation drivers. Cost compression in the mid-fee tier is intensifying because Cambridge Program alternatives expand without proportional facility investment. Expatriate oil and gas families exhibit highest price sensitivity, while diplomatic mission households show least elasticity.
Supply Chain Analysis
Upstream feedstock for campus construction draws from UAE, India, and China for steel, HVAC systems, and educational technology hardware. Specialized inputs include laboratory equipment from Germany, learning management platforms from North American SaaS providers, and examination board licensing from UK-based assessment bodies. Single-source vulnerability concentrates in international curriculum accreditation, where British and IB authorization bodies control essential certification pathways. Distribution runs through established education groups with centralized procurement functions serving multi-campus networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oman's private K-12 market rewards operators who control scarce administrative talent pipelines, as Ministry of Education localization mandates compress the available leadership pool faster than training programs can replenish it.
For Market Incumbents: Entrench market position by accelerating Omani national leadership development programs ahead of compliance deadlines, and secure exclusive examination board partnerships that emerging competitors cannot replicate. The administrative localization requirement poses the most immediate threat to foreign-branded operations. Vertical integration into teacher training academies represents the critical defensive lever for sustaining operational continuity. For New Entrants and Emerging Players: Al Batinah industrial corridor penetration offers the most accessible white-space opportunity, where manufacturing-driven expatriate enrollment growth outpaces established school supply. Mid-fee Cambridge Program positioning captures parent demand for transferable credentials without premium infrastructure requirements. A blended learning go-to-market model enables enrollment scale with deferred facility capital deployment. For Investors and Strategic Acquirers: Single-site premium institutions with IB authorization and established university placement track records represent the highest-conviction acquisition archetype. Long-term viability hinges on regulatory compliance positioning rather than pure enrollment growth. The signal to watch is Ministry of Education acceleration of ownership transition timelines for foreign-branded schools.| Strategic Initiative | Industry Significance |
|---|---|
| Administrative Localization Program | Accelerates Omani national leadership placement to meet Ministry of Education compliance mandates. |
| Cambridge Curriculum Expansion | Captures mid-fee demand from oil and gas sector families seeking cost-controlled credential transferability. |
| Multi-Campus Network Consolidation | Centralizes procurement and shared services across ABQ Education Group's distributed Omani locations. |
| Blended Learning Infrastructure | Integrates physical campuses with remote instruction platforms to scale enrollment without proportional facility investment. |
| STEM Programming Differentiation | Aligns with national education strategy priorities while attracting expatriate families to Knowledge Gate International School. |
Research Methodology
Desk research of Ministry of Education licensing records, examination board enrollment statistics, and industrial zone workforce reports preceded structured interviews with private school operators, curriculum coordinators, and facilities procurement managers. Primary fieldwork with education group executives and regulatory compliance officers combined with secondary validation against customs data for educational equipment imports and Omani national statistics on expatriate population distribution. Bottom-up enrollment modeling and top-down market sizing triangulated volume estimates across the analysis window.
Assumptions held fixed include Ministry of Education regulatory timelines, oil and gas sector employment levels in Muscat Governorate, and examination board authorization standards; varied parameters included industrial corridor expansion pace and administrative localization enforcement intensity. Segmentation dimensions modeled encompass school type, curriculum offered, tuition fee tier, and enrollment size band. CAGRs derived from enrollment trend extrapolation moderated by capacity constraint analysis and competitive entry probability assessment. Forecast inputs incorporated expatriate workforce projections from Sohar Port and Salalah logistics hub development timelines.
The forecast holds incumbent behavior within observed patterns; aggressive campus expansion by UAE-based education groups or accelerated public school quality improvements would shift outcomes beyond modeled ranges. Cross-checking against Gulf Cooperation Council education sector investment flows is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Primary and Secondary Education
Saudi Arabia Private K12 Education Market
Primary and Secondary Education
Europe K12 Education Market
Primary and Secondary Education
Oman Private K12 Education Market
Primary and Secondary Education
Qatar Private K12 Education Market
Primary and Secondary Education
North America K-12 Furniture Market
Primary and Secondary Education
Back to School Market
Primary and Secondary Education
North America K12 Education Market
Primary and Secondary Education
Asia-Pacific School Furniture Market
Primary and Secondary Education
GCC Private K12 Education Market
Primary and Secondary Education
In-Person Learning Market
Primary and Secondary Education
UAE Private K12 Education Market
Primary and Secondary Education
K-12 Education Market