
 IT Training Market | 2026-2036
IT Training Market Size, Share, and Industry Trends Forecast 2026-2036
IT Training Market Intelligence
Cloud-native skill scarcity is rotating enterprise learning budgets toward intensive certification programs. Microsoft Corporation leverages its Azure ecosystem to bundle training with cloud consumption contracts, sustaining platform stickiness across Fortune 500 accounts. Amazon Web Services anchors its market position through role-based certification ladders that dominate DevOps and solutions architect pipelines. Coursera competes via university partnerships that credential mid-career transitions into data engineering and cybersecurity roles.
IT Training encompasses structured pedagogy for software development, infrastructure management, and information security competencies, typically delivered through modular curricula with hands-on labs and proctored assessments. Its primary commercial purpose is closing workforce capability gaps that obstruct technology adoption and operational resilience. Certificate Programs and Bootcamps capture the fastest expansion as employers prioritize demonstrated competency over traditional degree proxies. Cloud Computing subject matter commands premium pricing due to vendor-specific certification requirements and scarce instructor talent. Corporate end users represent the deepest margin pool through multi-year enterprise licensing arrangements.
Federal workforce directives from the US Office of Personnel Management, EU Digital Skills Framework targets, and India's National Education Policy shape procurement standards and curriculum accreditation requirements across their respective jurisdictions. OSHA guidelines for remote learning ergonomics and data privacy obligations under GDPR and state-level US privacy statutes constrain platform architecture and content delivery design. Stakeholders must monitor how generative AI tooling alters the shelf life of technical credentials and whether vendor-specific certification ecosystems fragment or consolidate around portable skill standards.
Market Dynamics
Generative AI integration into software development workflows is compressing legacy skill half-lives and forcing enterprises into accelerated reskilling cycles. Cloud migration mandates across federal and commercial IT departments are amplifying workforce certification budgets as operational resilience depends on verified competency.
Growth Catalysts
- EU Digital Skills Framework targets:Mandatory upskilling quotas for technology sector employment are driving procurement of accredited certificate programs across member states.
- DevOps pipeline automation:Container orchestration and infrastructure-as-code adoption is creating sustained demand for Kubernetes and Terraform certification tracks.
- Defense contractor compliance:United States federal cybersecurity directives mandate cleared personnel maintain current certifications, sustaining premium training procurement.
Market Restraints
- Instructor talent scarcity:Cloud-native subject matter expertise concentrates in hyperscaler employment, limiting independent training provider capacity expansion.
- Certification inflation:Vendor-specific credential proliferation fragments employer recognition and dilutes return-on-investment for individual learners.
- Remote proctoring costs:Identity verification infrastructure and anti-cheating technology impose fixed cost burdens on low-margin certificate programs.
Strategic Opportunities
- India National Education Policy integration:Vocational credit transfer mechanisms between universities and industry certifications open formal education channel partnerships.
- AI-augmented personalized learning:Adaptive curriculum engines that compress time-to-competency for mid-career transitions into data engineering roles.
- Micro-credential stacking:Modular badging systems that aggregate into portable skill passports, reducing vendor lock-in for enterprise buyers.
Industry Challenges
- Generative AI tooling obsolescence:Rapid capability evolution in coding assistants shortens effective shelf life of programming curriculum, forcing continuous content refresh cycles.
- Multi-cloud complexity:Enterprises operating across AWS, Azure, and Google Cloud platforms require cross-vendor competency mapping that training providers struggle to standardize.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IT Training Market |
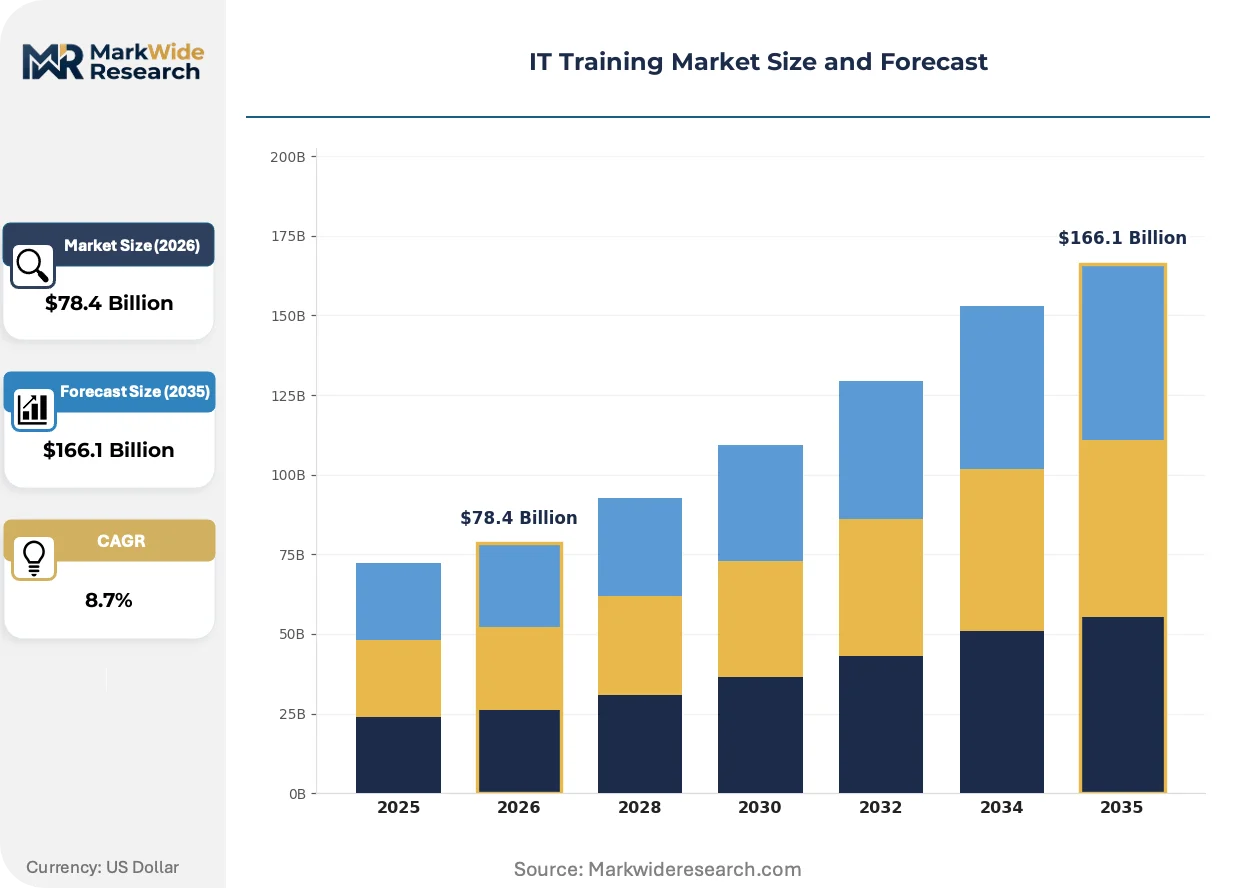
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $166.1 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Delivery Mode: Online, In-Person, Hybrid, Blended End User: Corporates, Educational Institutions, Professionals, Students Course Type: Certificate Programs, Bootcamps, Workshops, Degree Courses Subject Area: Programming, Cybersecurity, Data Science, Cloud Computing |
| Companies Covered | Pluralsight, Coursera, LinkedIn Learning, Udacity, Skillsoft Corporation, Microsoft Corporation, Amazon Web Services, NIIT Limited, Oracle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IT Training Market Strategic Shifts & Innovations
Immersive simulation technology is reshaping how technical competency is verified, moving assessment from multiple-choice testing toward performance-based evaluation in sandboxed environments. This shift is altering instructor-to-learner ratios and platform infrastructure requirements.
Virtual lab environments is miniaturizing the capital requirements for hands-on infrastructure training. Mid-market enterprises previously priced out of dedicated hardware labs are adopting browser-based sandbox platforms for network engineering and cybersecurity exercises. This technology is compressing the cost structure of certification delivery and expanding addressable demand among budget-constrained government agencies.
GDPR Article 32 security training mandates are hardening data protection curriculum requirements across European Union member states. Financial services and healthcare verticals face explicit documentation obligations for workforce privacy education. Germany and France are witnessing accelerated procurement of ISO 27001-aligned certification programs as supervisory authorities intensify enforcement.
Skills-based hiring protocols are displacing degree requirements in technology recruitment. Fortune 500 technology teams are eliminating four-year degree filters in favor of demonstrated portfolio work and vendor certifications. This behavioral shift is most visible in United States metropolitan technology corridors where labor market tightness forces credential flexibility.
IT Training Market Segmentation
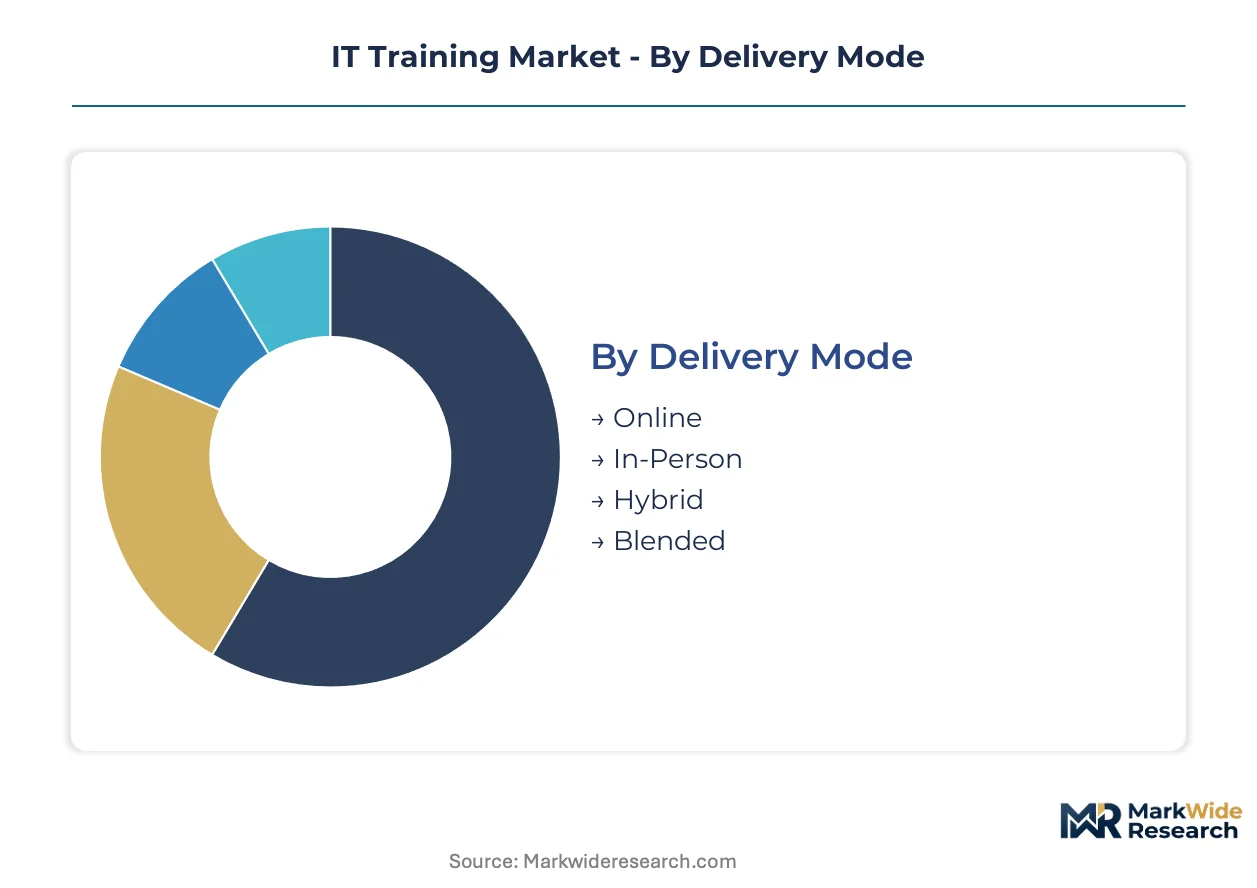
IT Training procurement patterns diverge sharply across delivery infrastructure, buyer sophistication, and credential type. Regulatory mandates on data residency and workforce verification reshape how enterprises allocate budgets across these dimensions.
Delivery Mode:
GDPR Article 32 security training mandates and OSHA remote learning ergonomics guidelines create divergent compliance burdens across delivery formats.
- Online:Browser-based platforms deliver asynchronous modules with AI-proctored assessments. United States federal contractors favor this mode for cleared personnel recertification under compressed timelines.
- In-Person:Physical classroom delivery with hands-on hardware labs dominates cybersecurity and network engineering tracks where sandboxed environments require instructor oversight.
- Hybrid:Synchronous virtual sessions supplemented by scheduled in-person intensives balance cost control with competency verification needs.
- Blended:Self-paced digital content interwoven with live workshops allows enterprises to customize pacing for heterogeneous skill baselines within teams.
Online handles the majority of throughput; Bootcamps delivered through Hybrid formats are climbing the fastest on share.
End User:
Budget authority and procurement velocity separate these buyer categories more than content requirements.
- Corporates:Multi-year enterprise licensing arrangements generate the deepest margin pools, with Fortune 500 technology teams prioritizing vendor-specific cloud certifications for platform stickiness.
- Educational Institutions:Universities and community colleges integrate vocational credit transfer mechanisms under India's National Education Policy, formalizing pathways between academic degrees and industry credentials.
- Professionals:Mid-career transitions into data engineering and cybersecurity roles drive demand for intensive certificate programs with demonstrated ROI.
- Students:Pre-employment credential accumulation concentrates in programming and cloud fundamentals, often subsidized by national digital skills initiatives.
Corporates command the largest absolute spend; Professionals are expanding most quickly as skills-based hiring protocols displace degree requirements.
Course Type:
Time-to-competency and employer recognition hierarchies stratify pricing power across these formats.
- Certificate Programs:Modular curricula with proctored assessments and digital badging align with ISO 27001-aligned compliance documentation requirements in Germany and France.
- Bootcamps:Intensive immersive formats compress legacy skill acquisition into 12-16 week cycles, responding to generative AI's compression of technical credential shelf lives.
- Workshops:Single-topic deep dives on emerging tools serve vendor-specific certification maintenance requirements for cleared defense personnel.
- Degree Courses:Traditional academic programs with embedded industry certifications face enrollment pressure from faster, employer-recognized alternatives.
Certificate Programs absorb the dominant share of enterprise procurement; Bootcamps show the steepest expansion trajectory.
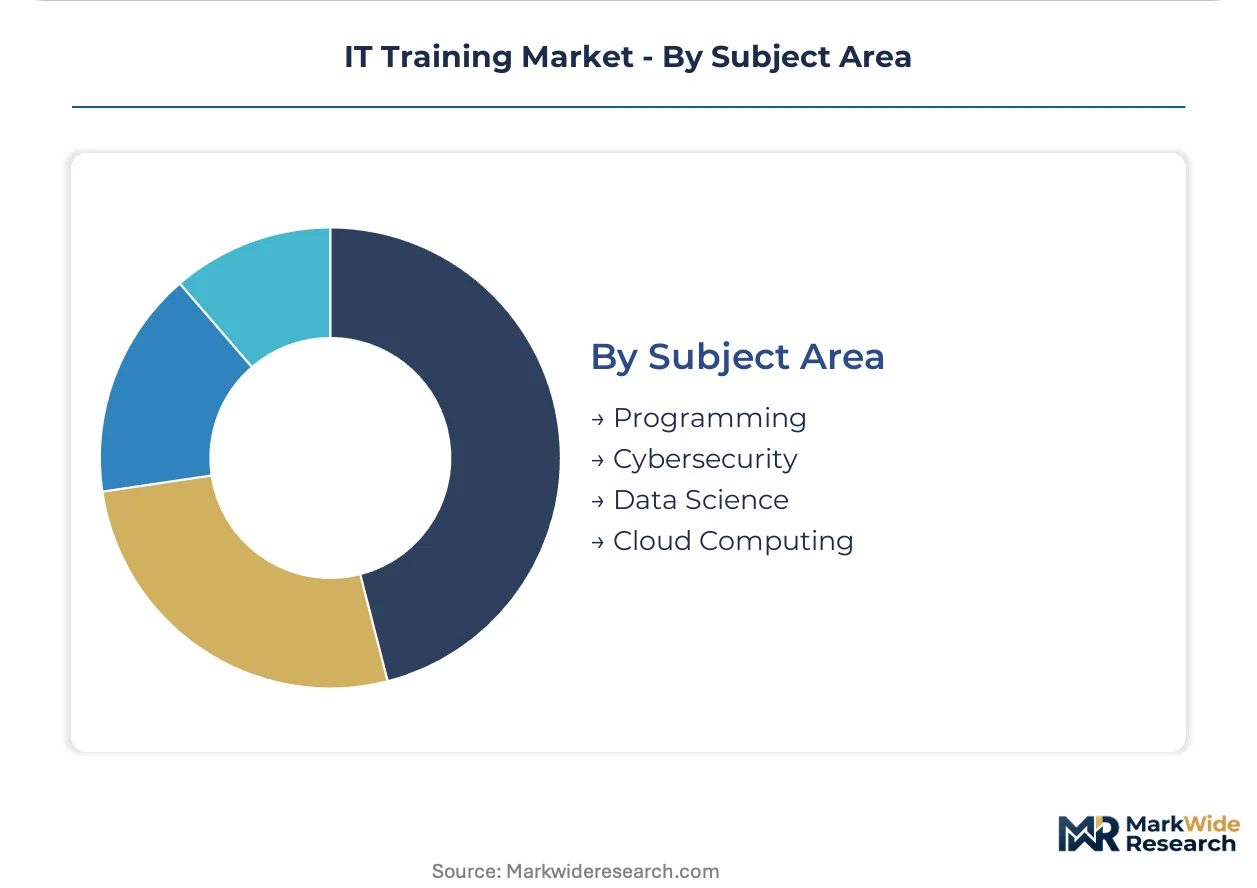
Subject Area:
Instructor talent scarcity and vendor-specific certification ecosystems concentrate margin capture unevenly across technical domains.
- Programming:Curriculum refresh cycles accelerate as coding assistants from hyperscalers obsolete legacy language training, forcing continuous content investment.
- Cybersecurity:United States federal directives mandate current certifications for cleared personnel, sustaining premium pricing for accredited programs.
- Data Science:University partnerships through platforms like Coursera credential mid-career transitions, though employer preference shifts toward portfolio demonstration over credential accumulation.
- Cloud Computing:Vendor-specific certification requirements across AWS, Azure, and Google Cloud platforms create fragmented competency mapping challenges for multi-cloud enterprises.
Cloud Computing commands the highest pricing tiers; Cybersecurity is gaining share fastest as regulatory enforcement intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium training procurement in the United States commands pricing multiples unavailable to providers serving price-sensitive Indian enterprise accounts. This asymmetry reflects divergent regulatory enforcement intensity and defense contractor concentration.
United States
Federal cybersecurity directives from the Office of Personnel Management sustain premium pricing for cleared personnel certification programs. Defense contractors in the Washington DC metro corridor and Huntsville, Alabama maintain mandatory recertification cycles that compress procurement timelines. Corporate buyers in Silicon Valley and Seattle technology clusters prioritize vendor-specific cloud credentials for platform stickiness.
Germany
GDPR Article 32 security training mandates and ISO 27001-aligned supervisory authority enforcement accelerate procurement of data protection curriculum. Industrial automation hubs in Bavaria and Baden-Württemberg drive demand for operational technology cybersecurity credentials. Frankfurt's financial services concentration requires documented workforce privacy education under intensified regulatory scrutiny.
India
The National Education Policy vocational credit transfer mechanism formalizes pathways between university degrees and industry certifications. NIIT Limited and domestic providers scale delivery through Bangalore and Hyderabad technology corridors. Mumbai and Delhi-NCR financial services clusters sustain demand for risk management and data governance training.
United Kingdom
Skills-based hiring protocols displace degree requirements across London fintech and Manchester digital services clusters. Coursera university partnerships credential mid-career transitions into data engineering roles. Financial Conduct Authority operational resilience expectations amplify enterprise training budgets for cybersecurity and cloud competency verification.
Japan
METI digital transformation targets and aging workforce demographics compress reskilling timelines for legacy enterprise IT departments. Tokyo and Osaka manufacturing conglomerates mandate cloud-native certification for supplier ecosystem integration. Cybersecurity curriculum procurement accelerates under 2024 critical infrastructure protection amendments.
IT Training Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the IT training market. Hyperscaler-owned certification ecosystems dominate premium-tier pricing through vendor-specific credential requirements. Independent platform providers compete on curriculum breadth and university partnership networks. Specialist bootcamp operators capture mid-market share through intensive format compression. Consolidation pressure intensifies as generative AI tooling shortens content shelf lives and forces continuous refresh investment.
Within the hyperscaler-owned tier, Microsoft Corporation and Amazon Web Services exemplify platform-integrated training bundling that sustains enterprise account stickiness. Coursera occupies a position bridging academic credentialing and industry certification for mid-career transition markets. These three anchors represent divergent strategic postures: captive ecosystem control, cloud consumption attachment, and university partnership scalability.
| Leading Market Players |
|---|
| Pluralsight |
| Coursera |
| LinkedIn Learning |
| Udacity |
| Skillsoft Corporation |
| Microsoft Corporation |
| Amazon Web Services |
| NIIT Limited |
| Oracle Corporation |
| Others |
Cost & Logistics Intelligence
Multi-year enterprise licensing arrangements lock in supply access for corporate training procurement while anchoring price visibility across certification refresh cycles. These contracts bundle vendor-specific cloud credentials with consumption commitments, compressing negotiation leverage for independent training providers competing against hyperscaler-owned ecosystems.
Pricing Analysis
The customization-premium spread separates standard self-paced modules from configured-to-order enterprise deployments with dedicated instructor pools and bespoke curriculum alignment. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with ISO 27001-aligned programs commanding substantial uplifts over uncredentialed alternatives. Pricing pressure stems from generative AI tooling shortening content shelf lives and forcing continuous refresh investment. Government agencies and educational institutions exhibit highest price sensitivity, while defense contractors under federal compliance mandates accept premium tiers without volume negotiation.
Supply Chain Analysis
Inbound logistics costs for physical training infrastructure concentrate around specialized hardware procurement from Taiwan, South Korea, and Germany for cybersecurity sandbox labs and network engineering equipment. Cloud-native instructor talent draws from hyperscaler employment pools in the United States and India, creating single-source vulnerability for independent providers seeking scalable delivery capacity. Distribution runs through direct enterprise sales teams for Fortune 500 accounts, supplemented by channel partnerships with systems integrators for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IT Training functions as a service-attach opportunity where recurring certification maintenance revenue expands faster than initial credential acquisition, with compliance-driven refresh cycles generating predictable annuity streams.
For Market Incumbents: Secure hyperscaler certification exclusivity through co-development agreements that embed training modules directly into cloud consumption contracts. Consolidate instructor talent pools in Bangalore and Hyderabad through acquisition of regional specialist providers, defending against margin erosion from AI-augmented adaptive learning platforms that compress time-to-competency without human instruction. For New Entrants and Emerging Players: Differentiate on micro-credential stacking architectures that aggregate modular badges into portable skill passports, reducing vendor lock-in for multi-cloud enterprises. Target India's National Education Policy vocational credit transfer corridor as the most penetrable geography, partnering with state universities to formalize pathways between academic degrees and industry certifications. For Investors and Strategic Acquirers: Specialist bootcamp operators with intensive format compression capabilities and established defense contractor relationships represent the highest-conviction acquisition archetype. Watch for inflection signals in generative AI tooling adoption rates that compress technical credential shelf lives below twelve-month refresh thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Augmented Curriculum Development | Adaptive learning engines from hyperscalers compress time-to-competency for mid-career data engineering transitions. |
| University Partnership Formalization | Coursera's credit transfer mechanisms under India's National Education Policy open formal education channel access. |
| Defense Contractor Certification Exclusivity | Federal cybersecurity directives from the Office of Personnel Management sustain premium pricing for cleared personnel programs. |
| Micro-Credential Stacking Architecture | Modular badging systems reduce vendor lock-in for enterprise buyers operating across AWS, Azure, and Google Cloud platforms. |
| Virtual Lab Environment Miniaturization | Browser-based sandbox platforms expand addressable demand among budget-constrained government agencies previously priced out of hardware labs. |
Research Approach
A standing panel of chief learning officers, IT procurement directors, certification program managers, and hyperscaler training ecosystem leads provided ongoing calibration across the research window. Primary fieldwork combined structured interviews with these stakeholders against secondary validation from SEC filings, hyperscaler capex disclosures, and ISO certification registry data. Bottom-up enrollment and revenue estimates triangulated against top-down addressable workforce calculations.
Consistency checks validated volume and value outputs against external benchmarks from national digital skills initiatives and federal training procurement databases. The analytical framework modeled delivery mode, end user sophistication, course type intensity, and subject area complexity across the projection horizon. CAGRs derived from segment-level enrollment trajectories, pricing elasticity assumptions, and vendor-specific certification refresh cycle frequencies.
Forecasts assume regulatory continuity in United States federal cybersecurity directives, EU Digital Skills Framework targets, and India's National Education Policy; material policy shifts would require re-modeling. Generative AI capability evolution and certification inflation dynamics represent specific risk factors that could revise trajectory assumptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Corporate Training and Talent Development
Corporate Training Services Market
Corporate Training and Talent Development
Corporate Leadership Training Market
Corporate Training and Talent Development
Corporate eLearning Market
Corporate Training and Talent Development
Talent As a Service Market
Corporate Training and Talent Development
United States HR Professional Service Market
Corporate Training and Talent Development
Corporate Training Market
Corporate Training and Talent Development
Europe Executive Search (Headhunting) Market
Corporate Training and Talent Development
Competency-Based Education Spending Market
Corporate Training and Talent Development
Global Sales Training Market
Corporate Training and Talent Development
Asia-Pacific Management Consulting Services Market
Corporate Training and Talent Development
France Outplacement Services Market
Corporate Training and Talent Development
Asia Pacific Strategic Consulting Services Market
Corporate Training and Talent Development
Asia Pacific HR Professional Services Market
Corporate Training and Talent Development
Middle East and Africa Management Consulting Services Market
Corporate Training and Talent Development
Canada Outplacement Services Market
Corporate Training and Talent Development
Europe Management Consulting Services Market