
 Europe Digital Education Market | 2026-2036
Europe Digital Education Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Digital Education Market Analytics
Enterprise buyer concentration is pivoting as multinational corporations consolidate vendor relationships around integrated learning suites rather than fragmented point solutions. Pearson Plc leverages its institutional assessment heritage to anchor long-term contracts with universities and government bodies. Coursera Inc. competes through credential partnerships with European business schools. Cisco Systems Inc. extends its networking infrastructure dominance into digital classroom hardware and security layers.
Digital education encompasses software platforms, content repositories, and connected hardware that deliver structured instruction through internet-connected devices, typically requiring cloud hosting, API interoperability, and learner analytics dashboards. Learning Management Systems occupy the mature core where procurement cycles run long and switching costs protect incumbents. Mobile Learning Solutions represent the fastest-expanding segment as smartphone-first delivery reaches vocational and rural learners previously excluded from desktop-dependent formats.
The EU Digital Education Action Plan and GDPR jointly shape platform architecture, mandating cross-border interoperability while restricting learner data processing. ECHA guidelines on chemical safety training and country-level accreditation requirements from Germany's KBA and France's ANSM further fragment compliance obligations. Stakeholders must monitor evolving CSRD reporting obligations that will soon require documented workforce reskilling metrics from listed employers.
Market Dynamics
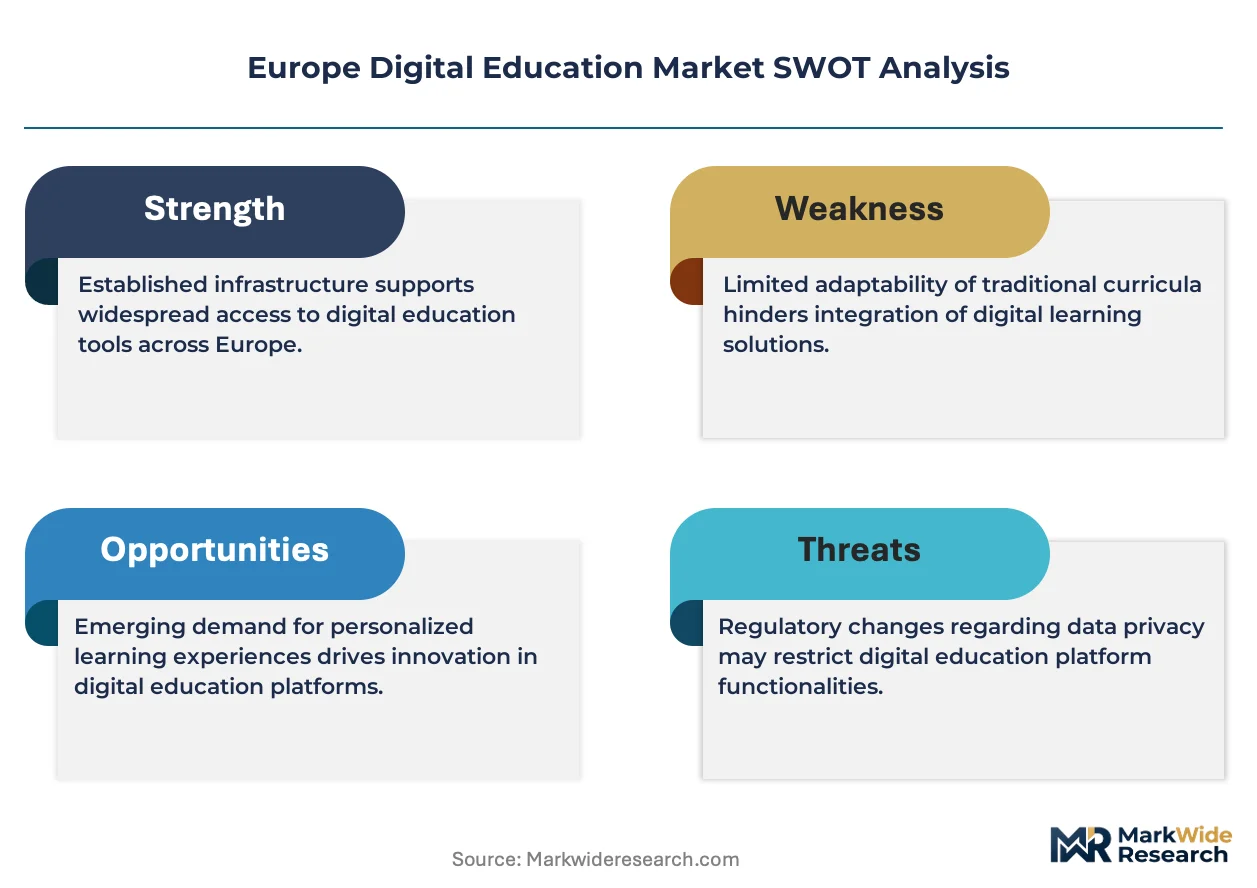
Corporate learning procurement is consolidating around integrated suites as fragmented point solutions face switching-cost pressure from buyers demanding unified learner analytics and credential portability across borders.
Growth Catalysts
- EU Digital Education Action Plan:Cross-border interoperability mandates are accelerating platform standardization, reducing vendor lock-in friction for institutions operating across member states.
- Hybrid learning infrastructure:Sustained public investment in Germany, France, and the United Kingdom is expanding addressable institutional budgets for connected classroom hardware and cloud-hosted systems.
- Smartphone-first delivery:Mobile Learning Solutions are capturing vocational and rural learner segments previously excluded by desktop-dependent formats, extending platform reach into underserved populations.
Market Restraints
- GDPR compliance architecture:Restrictions on learner data processing and cross-border transfer create engineering overhead that slows feature rollout cycles for analytics-dependent platforms.
- Accreditation fragmentation:Divergent requirements from Germany's KBA, France's ANSM, and country-level vocational bodies force redundant content localization and certification mapping.
- Long procurement cycles:Learning Management Systems face extended institutional sales timelines averaging 18-24 months, compressing vendor cash conversion and raising customer acquisition costs.
Strategic Opportunities
- Eastern European expansion:Poland, Romania, and Bulgaria present underpenetrated markets where EU cohesion funding for workforce development is expanding platform addressable demand.
- CSRD reporting mandates:Documented workforce reskilling metrics will soon become mandatory disclosure items for listed employers, creating compliance-driven demand for certified training tracking systems.
- AI-assisted personalization:Convergence of generative models with learner analytics dashboards enables adaptive content sequencing at scale, differentiating premium platform tiers.
Industry Challenges
- Interoperability engineering:API standardization across legacy institutional systems requires specialized integration teams, constraining vendor scaling and extending implementation timelines.
- Cybersecurity credentialing:ECHA guidelines on chemical safety training and sector-specific protocols demand continuous content recertification, raising ongoing compliance costs for content repositories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Digital Education Market |
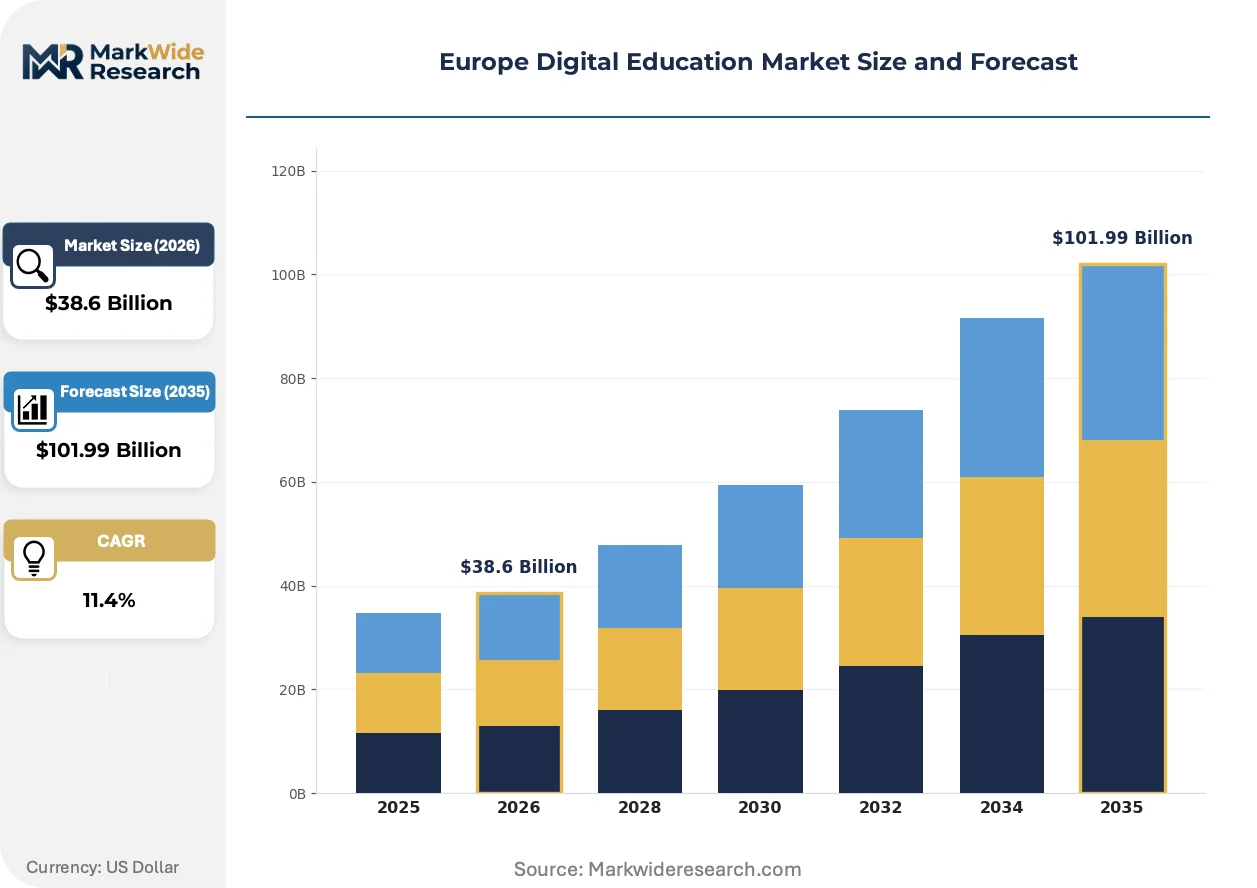
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $101.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: e-Learning Platforms, Mobile Learning Solutions, Virtual Classrooms, Learning Management Systems End User: K-12 Schools, Higher Education Institutions, Corporate Clients, Government Organizations Delivery Mode: Asynchronous Learning, Synchronous Learning, Blended Learning, Self-Paced Courses Pricing Model: Subscription-Based, Pay-Per-Course, Freemium, License Fee |
| Companies Covered | Pearson Plc, Instructure Holdings Inc., Adobe Inc., Coursera Inc., Cegos Group, Skillsoft Corp., Cisco Systems Inc., D2L Corp., City and Guilds Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Digital Education Market Evolving Landscape
Generative AI and immersive technologies are compressing content production timelines while regulatory pressure on data sovereignty is reshaping cloud architecture decisions across the vendor base.
Adaptive learning algorithms are overtaking static course sequencing as the dominant instructional design paradigm. Vocational training providers in Germany and the Netherlands are deploying these systems at scale to reduce time-to-competency for manufacturing certifications. The technology is overtaking traditional fixed-curriculum models by compressing credential completion timelines while maintaining assessment rigor.
CSRD disclosure requirements are mandating documented workforce reskilling metrics from listed employers. Industrial consequence includes procurement preference shifting toward platforms with embedded compliance reporting and audit-ready learner record systems. Financial services and industrial conglomerates headquartered in Frankfurt and Paris are most affected, driving vendor roadmaps toward integrated ESG reporting modules.
Subscription-based workforce upskilling is displacing perpetual license models in corporate training budgets. Chief Learning Officers at multinational manufacturers are consolidating vendor relationships around integrated suites rather than fragmented point solutions. This pattern is most visible in the United Kingdom and Nordic markets where procurement functions have centralized learning technology spend under shared services frameworks.
Europe Digital Education Market Segmentation
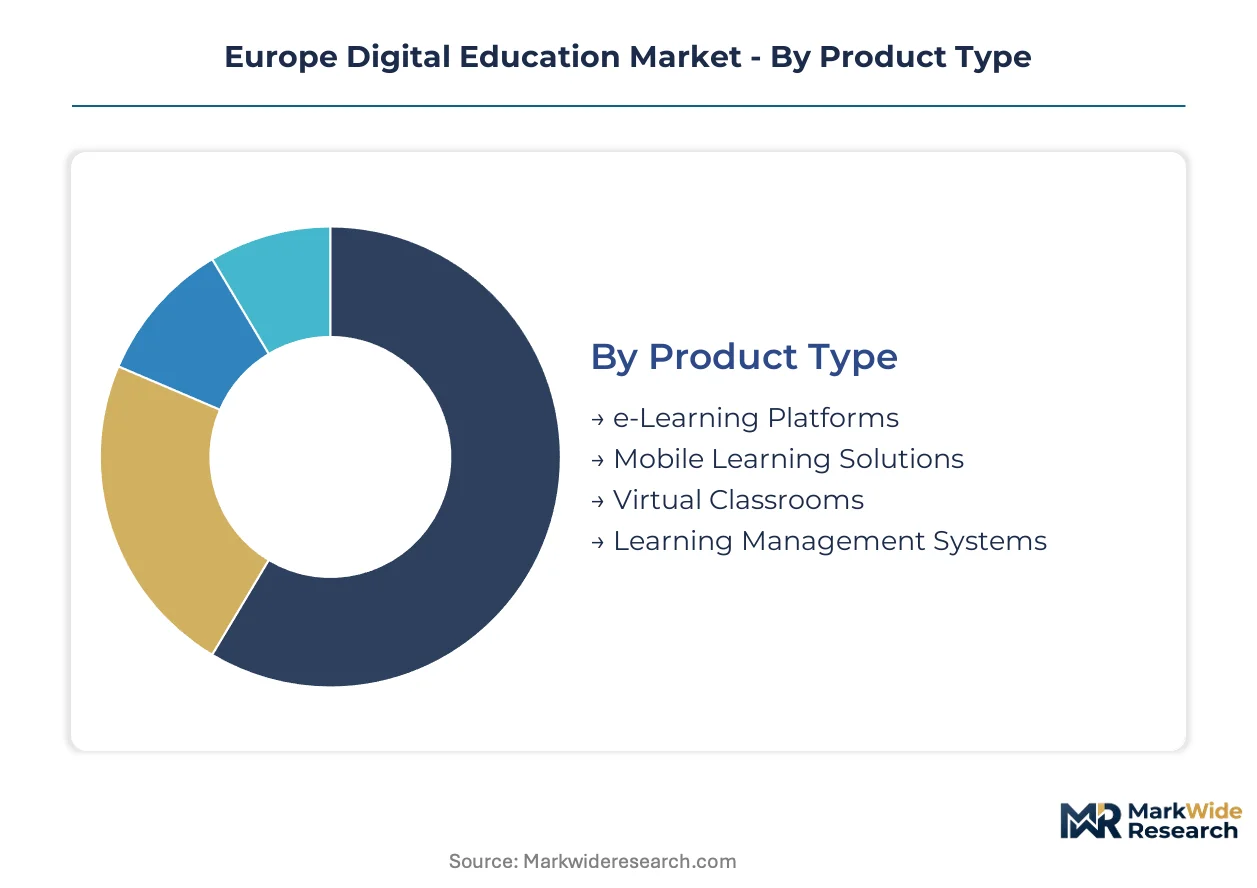
Segmentation in the Europe Digital Education Market reveals divergent procurement patterns across institutional buyers and delivery formats. Procurement cycles, compliance obligations, and learner demographics create distinct commercial profiles that vendors must navigate.
Product Type:
Budget scale and technical maturity separate buyers across these platform categories.
- Learning Management Systems:Cloud-hosted institutional platforms with embedded assessment engines and LTI-compliant interoperability. German universities and French grandes écoles anchor procurement volumes, though 18-24 month sales cycles compress vendor cash conversion.
- Mobile Learning Solutions:Smartphone-native delivery architectures optimized for intermittent connectivity and microlearning formats. Vocational training networks in Poland and rural learner populations across Romania and Bulgaria are expanding addressable demand fastest.
- e-Learning Platforms:Content repositories with structured curricula and credentialing pathways.
- Virtual Classrooms:Real-time video conferencing with breakout rooms and collaborative whiteboarding.
Volume sits with Learning Management Systems; growth tilts toward Mobile Learning Solutions.
End User:
Funding sources and procurement autonomy create sharply different customer economics.
- Higher Education Institutions:Degree-granting universities with multi-year platform contracts and research-driven content partnerships. United Kingdom Russell Group members and Dutch technical universities concentrate spending on integrated suites with embedded analytics.
- Corporate Clients:Workforce development programs with subscription-based procurement and ESG-linked reporting requirements. Frankfurt and Paris-headquartered industrial conglomerates are mandating audit-ready reskilling metrics ahead of CSRD disclosure deadlines.
- K-12 Schools:Regional authority-managed procurement with fragmented decision-making.
- Government Organizations:EU cohesion-funded workforce development and civil service training programs.
Revenue concentrates in Higher Education Institutions; margin expansion favors Corporate Clients.
Delivery Mode:
Scheduling flexibility versus instructional intensity shapes platform architecture requirements.
- Blended Learning:Integrated synchronous and asynchronous components with physical classroom coordination. German vocational academies and Dutch polytechnics are deploying these systems at scale to compress time-to-competency for manufacturing certifications.
- Asynchronous Learning:Self-scheduled content access with automated progress tracking and competency-based advancement. Corporate training departments across Nordic shared services frameworks prefer this mode for geographically distributed workforces.
- Synchronous Learning:Real-time instructor-led sessions requiring low-latency infrastructure.
- Self-Paced Courses:Fixed curriculum with learner-controlled progression speed.
Adoption tilts toward Blended Learning; infrastructure investment flows to Asynchronous Learning.
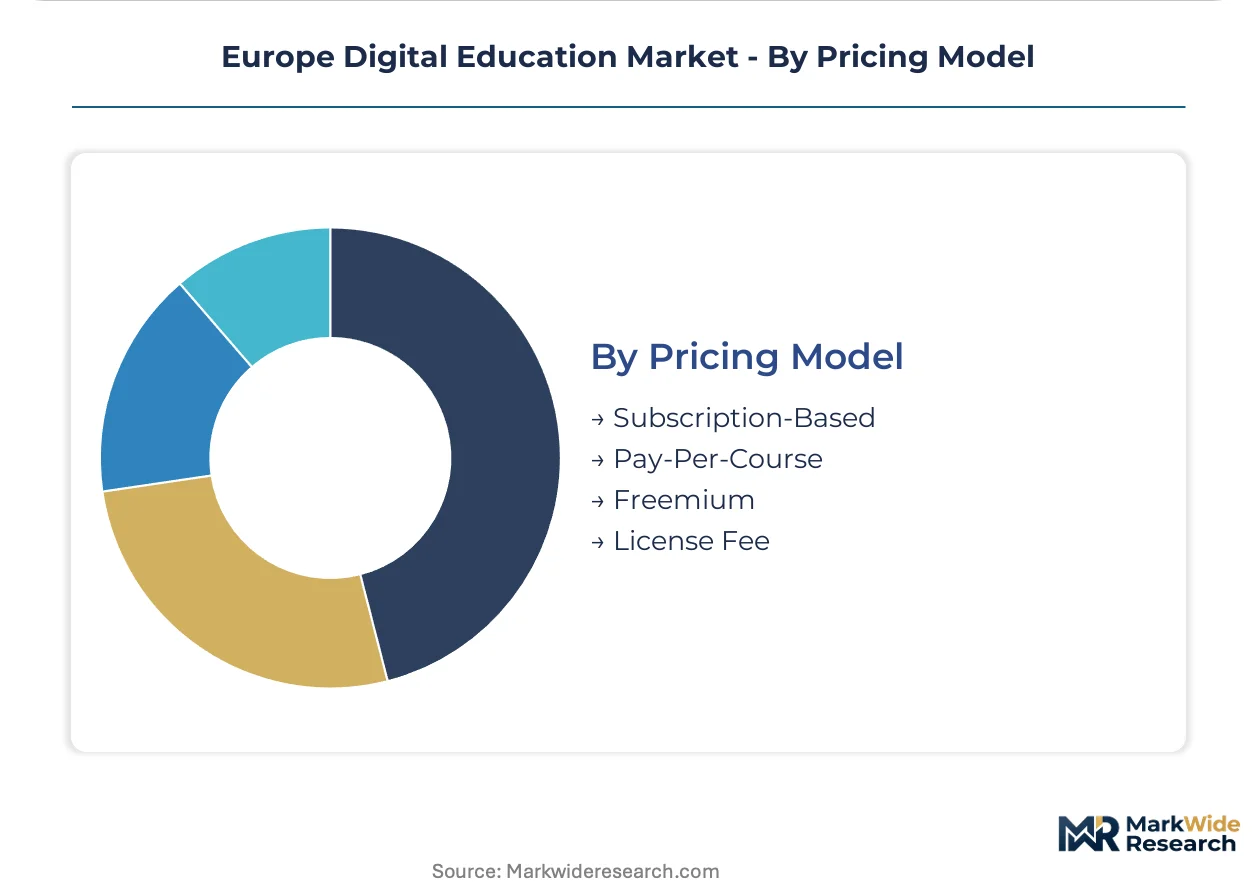
Pricing Model:
Cash flow predictability and customer lifetime value separate these commercial structures.
- Subscription-Based:Recurring revenue contracts with tiered feature access and usage-scaled pricing. Chief Learning Officers at multinational manufacturers are consolidating vendor relationships around these models, displacing perpetual licenses in United Kingdom and Nordic procurement frameworks.
- Freemium:Base functionality at no cost with premium feature unlocks and credential verification fees. Individual learners and small vocational training providers in Eastern Europe are converting to paid tiers at accelerating rates.
- Pay-Per-Course:Transactional single-purchase access without ongoing platform commitment.
- License Fee:Perpetual or term-limited institutional deployment rights with maintenance add-ons.
Revenue stability favors Subscription-Based; user acquisition efficiency sits with Freemium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Public funding for hybrid learning infrastructure anchors demand concentration across Western Europe, while EU cohesion mechanisms channel investment toward Eastern European workforce development networks.
Germany
Manufacturing vocational academies and dual-education systems drive procurement of blended learning platforms with competency-tracking features. KBA accreditation requirements for automotive and chemical safety training mandate localized content certification. The Ruhr industrial corridor and Bavarian automotive clusters are deploying AI-assisted personalization systems to compress time-to-competency for technician certifications.
United Kingdom
Russell Group universities and centralized NHS training programs anchor institutional demand for integrated learning suites with embedded analytics. GDPR compliance architecture shapes vendor selection criteria for cloud-hosted systems. London's financial services sector and Manchester's media-tech cluster are mandating CSRD-ready workforce reskilling metrics ahead of disclosure deadlines.
France
Grandes écoles and civil service training networks concentrate spending on credential-verification platforms with cross-border portability. ANSM guidelines for pharmaceutical and medical device training create specialized content requirements. The Paris-Saclay research cluster and Lyon biotech corridor are consolidating vendor relationships around subscription-based workforce upskilling models.
Poland
EU cohesion funding for workforce development is expanding platform addressable demand in vocational training networks previously underserved by desktop-dependent formats. The country's national education ministry procurement frameworks prioritize mobile-first delivery architectures. The Silesian manufacturing belt and Warsaw metropolitan area are capturing accelerated investment in smartphone-native learning solutions for rural learner populations.
Netherlands
Dutch technical universities and polytechnics anchor procurement of adaptive learning algorithms for manufacturing certification programs. CE marking requirements for educational hardware influence connected classroom infrastructure decisions. The Eindhoven high-tech corridor and Rotterdam logistics hub are deploying blended learning systems at scale to reduce credential completion timelines while maintaining assessment rigor.
Europe Digital Education Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-assisted personalization and mobile-native delivery architectures. The vendor base stratifies across three tiers: institutional assessment heritage providers, cloud-native credential platforms, and networking infrastructure specialists extending into connected classroom hardware. Competitive dynamics center on M&A consolidation of point solutions into integrated suites and strategic partnerships with European business schools for credential portability.
Within the institutional assessment tier, Pearson Plc and City and Guilds Group exemplify heritage-driven positioning anchored by long-term university and government contracts. Coursera Inc. occupies a position representing the cloud-native credential platform archetype, while Cisco Systems Inc. sits within the infrastructure extension tier. These three companies collectively illustrate the competitive vectors reshaping vendor relationships as multinational corporations consolidate around unified learner analytics and cross-border credential portability.
| Leading Market Players |
|---|
| Pearson Plc |
| Instructure Holdings Inc. |
| Adobe Inc. |
| Coursera Inc. |
| Cegos Group |
| Skillsoft Corp. |
| Cisco Systems Inc. |
| D2L Corp. |
| City and Guilds Group |
| Others |
Value Network & Pricing Analysis
GDPR compliance architecture gates qualified supply and premium-tier pricing access for European digital education vendors, as platforms bearing CE marking and certified data sovereignty command subscription premiums from German universities and French grandes écoles while uncertified providers face margin compression in Eastern European price-sensitive segments.
Pricing Analysis
Volume concentrates in Learning Management Systems where 18-24 month procurement cycles compress margins, while margin expansion sits with Corporate Clients demanding CSRD-ready audit trails. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification depth and analytics sophistication. Pricing pressure stems from EU cohesion-funded tenders in Poland and Romania favoring mobile-native freemium conversion. K-12 regional authorities exhibit highest price sensitivity; Frankfurt-headquartered industrial conglomerates show lowest.
Supply Chain Analysis
Reverse-logistics flows for connected classroom hardware refurbishment center on Netherlands distribution hubs serving German vocational academies and UK Russell Group campuses. Cloud infrastructure draws from Ireland, Germany, and Sweden data center clusters. Content production rests on freelance instructional designer networks across Portugal and Spain. Single-source vulnerability concentrates in LTI-compliant interoperability middleware. Distribution runs through direct enterprise sales teams for institutional contracts and mobile app stores for individual learners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's digital education market represents a consolidation play as CSRD disclosure mandates force subscale point-solution vendors toward acquisition or exit.
For Market Incumbents: Deepen vertical integration into AI-assisted personalization R&D to defend against cloud-native credential platforms eroding premium-tier pricing. Anchor long-term contracts with ANSM and KBA certification requirements to raise switching costs for French and German institutional buyers. Acquire mobile-native specialists in Poland and Romania to capture EU cohesion-funded expansion before subscription models mature. For New Entrants and Emerging Players: Vocational training networks in Bulgaria and Romania present the most penetrable white-space as smartphone-first delivery displaces desktop-dependent legacy platforms. Target blended learning deployments for German manufacturing certifications where adaptive algorithms compress time-to-competency. Partner with Cisco Systems Inc. channel partners for connected classroom hardware bundling to bypass 18-24 month direct sales cycles. For Investors and Strategic Acquirers: CSRD audit-ready reskilling metric adoption by Frankfurt and Paris-listed employers is the leading indicator that workforce development platforms will command valuation premiums over content repositories. Five-to-ten year viability favors vendors with embedded compliance reporting and cross-border credential portability. Monitor ECHA guideline expansion into new chemical safety training verticals as inflection signal for content recertification demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified learner analytics satisfy multinational procurement consolidation around integrated suites rather than fragmented point solutions. |
| Acquisition of Specialist Firm | Mobile-native specialists in Eastern Europe extend reach into EU cohesion-funded vocational networks previously excluded by desktop formats. |
| Strategic Partnership | Credential partnerships with European business schools differentiate premium tiers through cross-border portability for corporate clients. |
| Geographic Expansion | Poland and Romania capture underpenetrated demand as EU cohesion funding channels investment toward workforce development infrastructure. |
| Product Launch | AI-assisted personalization modules enable adaptive content sequencing that compresses German manufacturing certification timelines. |
Research Methodology
Document review covered EU Digital Education Action Plan implementation reports, GDPR compliance filings, and CSRD disclosure drafts, complemented by interviews with Chief Learning Officers at multinational manufacturers, platform engineering directors, procurement leads at German vocational academies, and channel partners for connected classroom hardware. Secondary validation drew from ECHA training guideline updates, KBA accreditation documentation, ANSM pharmaceutical training protocols, and EU cohesion fund allocation databases. Bottom-up segment sizing triangulated against top-down market aggregation.
Revenue and user projections across the modeling period employed a demand-side analytical framework segmented by product type, end user, delivery mode, and pricing model, with additional dimensioning by country-level regulatory cluster. CAGRs derived from historical trajectory analysis adjusted for policy implementation timelines and technology adoption S-curves. Forecast inputs incorporated EU Digital Education Action Plan interoperability mandate rollout schedules and CSRD disclosure obligation phasing for listed employers.
Caveats apply where ECHA guideline expansion into new chemical safety verticals or GDPR enforcement variation across member states could materially shift the outlook for content recertification costs and cross-border data transfer permissions. Practitioners should monitor CSRD audit-ready platform adoption rates among Frankfurt and Paris-headquartered employers for early signals of compliance-driven procurement preference shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Distance Learning and Online Education
Europe E-Learning Market
Distance Learning and Online Education
Saudi Arabia E-Learning Market
Distance Learning and Online Education
Online Tutoring Services Market
Distance Learning and Online Education
Cloud-Based Training Software Market
Distance Learning and Online Education
Global Self-Paced E-Learning Market
Distance Learning and Online Education
Digital Course Recorder Market
Distance Learning and Online Education
Massive Open Online Courses Market
Distance Learning and Online Education
Online K-12 Education Market
Distance Learning and Online Education
Global Virtual Classroom Market
Distance Learning and Online Education
Global Online Tutoring Software Market
Distance Learning and Online Education
United States E-Learning Market
Distance Learning and Online Education
Africa E-Learning Market
Distance Learning and Online Education
Remote Learning Technology Spending Market
Distance Learning and Online Education
GCC Massive Open Online Course (MOOC) Market
Distance Learning and Online Education
E-Learning Market
Distance Learning and Online Education
MOOC Market