
 Digital Educational Publishing Market | 2026-2036
Digital Educational Publishing Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Educational Publishing Market Analysis
Modular course packaging is pivoting how institutions evaluate procurement, shifting from full-semester bundles to discrete competency-based modules. Pearson Plc leverages its assessment infrastructure to anchor premium positioning in credential-bearing segments. McGraw Hill LLC competes through adaptive learning engines that personalize remediation pathways. Coursera Inc. specializes in stackable micro-credentials that extend addressable demand beyond traditional degree seekers.
Digital educational publishing encompasses the creation, distribution, and licensing of curriculum-aligned content delivered through internet-connected platforms, typically encoded in EPUB 3, HTML5, or proprietary SCORM/xAPI formats for interoperability across learning management systems. Its primary commercial purpose is to replace or supplement print textbooks with searchable, multimedia-enriched, analytics-captured materials that reduce per-student distribution costs while enabling real-time performance tracking. Learning Management Systems dominate institutional spending due to their role as centralized delivery infrastructure, while Interactive Content captures expanding margin pools as publishers layer simulation and gamification atop static assets. Mobile delivery is the fastest-growing mode as smartphone-first learners in emerging markets bypass desktop-dependent workflows.
The U.S. Department of Education enforces accessibility standards under Section 508 and the ADA, compelling publishers to maintain WCAG 2.1 compliance for federal procurement eligibility. The EU AI Act imposes transparency obligations on adaptive tutoring systems, requiring disclosure of automated decision-making logic that shapes learner pathways. India's BIS certification framework for educational software is tightening data localization requirements that affect cross-border content hosting. Stakeholders must monitor how divergent regulatory timelines for AI governance reshape platform architecture costs and geographic rollout sequencing.
Market Dynamics
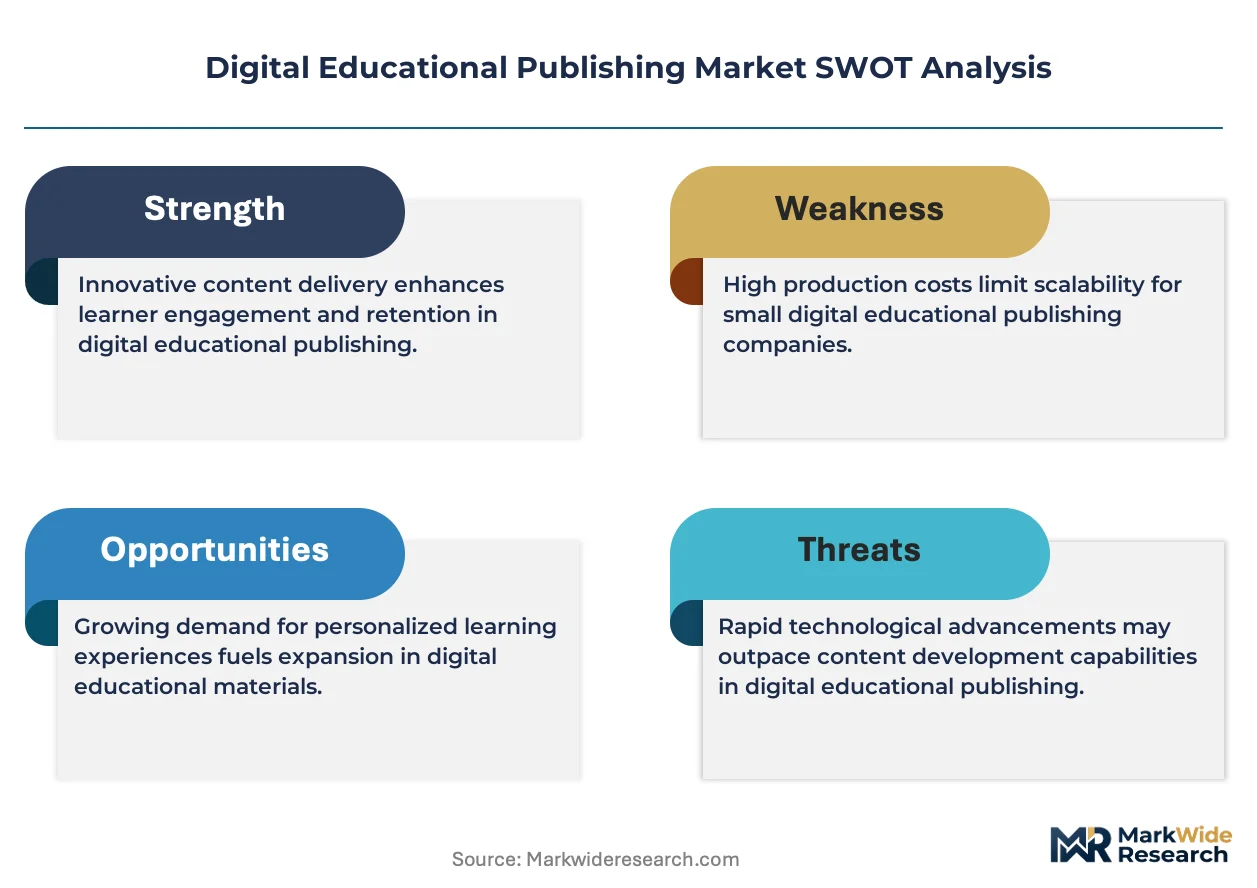
Cloud migration in K-12 infrastructure is compressing procurement cycles and forcing publishers to re-architect delivery models around API-first platforms rather than static file distribution.
Growth Catalysts
- EU AI Act transparency mandates:Publishers investing in explainable recommendation engines gain preferential access to European institutional procurement frameworks.
- India BIS certification pathways:Domestic digital literacy programs create certified vendor pools for state-level learning platform deployments.
- SCORM-to-xAPI migration:Learning record stores enable granular competency tracking that justifies premium module pricing over bundled textbooks.
Market Restraints
- Cloud infrastructure cost volatility:AWS and Azure pricing fluctuations compress margins for publishers delivering video-heavy adaptive content.
- Data localization mandates:India's tightening BIS requirements force redundant hosting architectures that duplicate operational overhead.
- Accessibility compliance burden:WCAG 2.1 remediation for legacy EPUB assets requires specialized labor pools that concentrate in high-cost urban centers.
Strategic Opportunities
- Stackable micro-credential expansion:Workforce development boards in Germany and Singapore are funding short-form certification programs that bypass traditional degree pathways.
- AI-human tutoring hybrids:Converging natural language processing with synchronous video instruction opens premium pricing tiers for high-stakes exam preparation.
- Mobile-first emerging markets:Smartphone penetration in Nigeria and Indonesia enables direct-to-learner distribution that circumvents institutional procurement bottlenecks.
Industry Challenges
- Learning engineer talent scarcity:The intersection of instructional design and data science commands salary premiums that strain mid-tier publisher staffing models.
- Legacy LMS integration friction:Blackboard and Moodle customizations require bespoke middleware development that extends implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Educational Publishing Market |
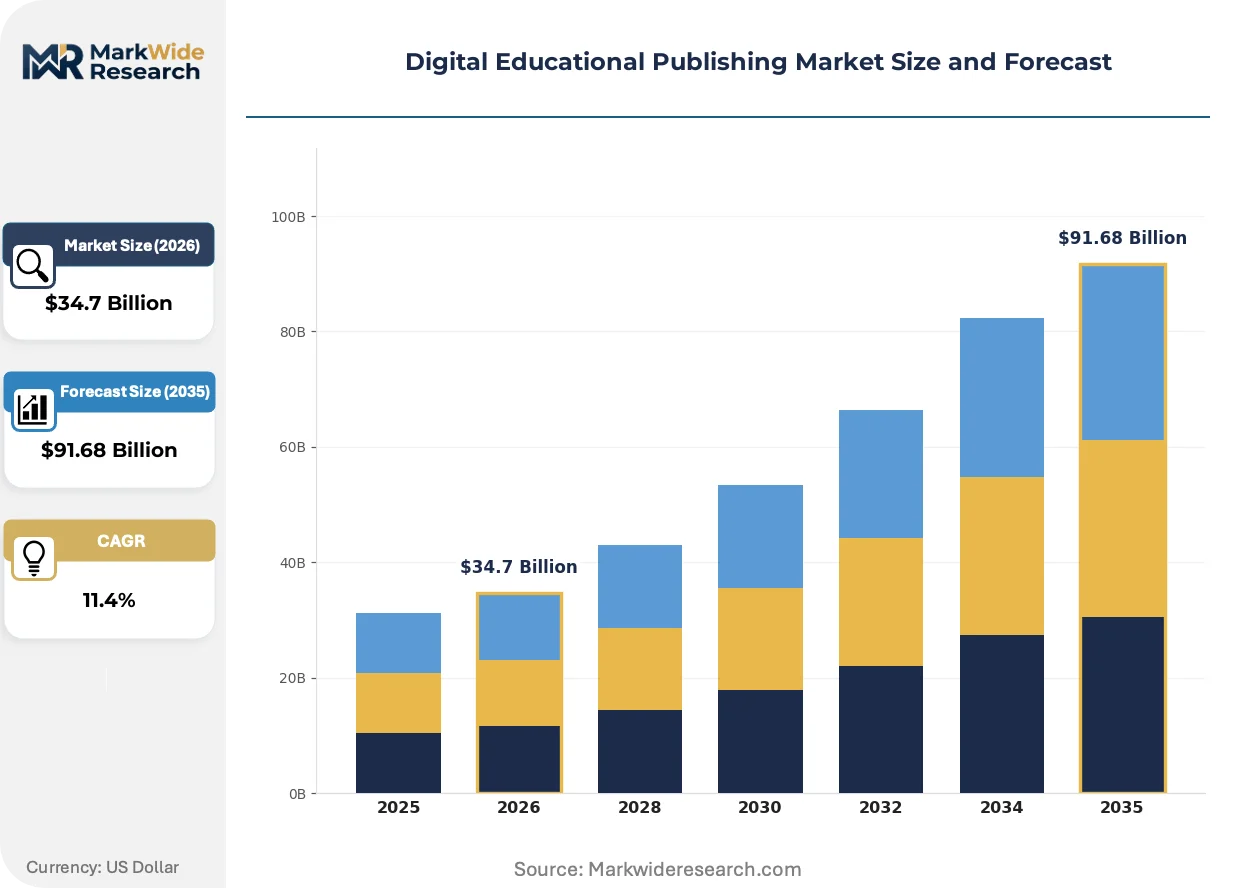
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $91.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: E-Books, Learning Management Systems, Interactive Content, Assessments Customer Type: Educational Institutions, Corporates, Government Agencies, Individuals End User: Students, Educators, Trainers, Professionals Delivery Mode: Online, Offline, Hybrid, Mobile |
| Companies Covered | Pearson Plc, McGraw Hill LLC, Scholastic Corp., John Wiley and Sons Inc., Houghton Mifflin Harcourt Co., Georg von Holtzbrinck GmbH, Cengage Learning Holdings II Inc., Oxford University Press, Coursera Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Educational Publishing Market Emerging Trajectories
Algorithmic personalization is rewriting content economics by replacing one-to-many textbook models with dynamically assembled learning pathways that respond to individual proficiency signals.
xAPI data standards are unifying previously siloed learning interactions across mobile apps, virtual labs, and assessment platforms. State university systems in Texas and California are mandating interoperable analytics as a procurement prerequisite. This unifying architecture is compressing vendor lock-in advantages and enabling multi-publisher content bundles within single learner dashboards.
The EU AI Act is imposing algorithmic transparency requirements on adaptive tutoring systems that automate pathway selection. Publishers must now document decision logic for content sequencing that shapes learner progression. European vocational training platforms are responding by hiring compliance officers and restructuring black-box recommendation engines into rule-based systems with auditable parameters.
Competency-based procurement is displacing seat-time contracts in corporate learning budgets. Fortune 500 training departments are unbundling annual subscriptions into discrete skill-verification purchases tied to job role requirements. This behavioral shift is most visible in financial services and healthcare verticals where regulatory continuing education mandates create predictable demand for stackable modules.
Digital Educational Publishing Market Segmentation
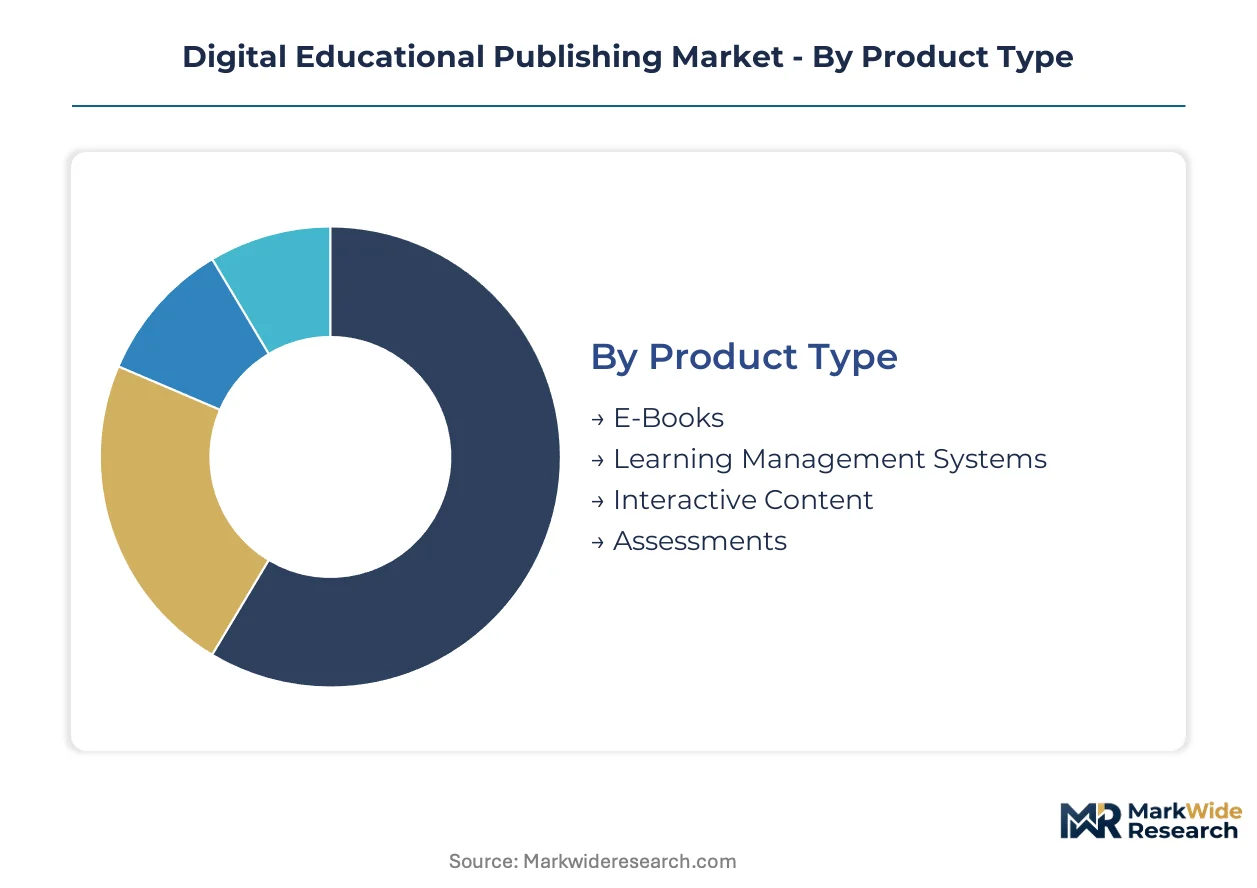
Publishers configure product portfolios around distinct procurement rhythms. Institutional buyers prioritize interoperability and administrative control, while individual learners respond to accessibility and price elasticity. These divergent decision logics fragment addressable demand across four structural dimensions.
Product Type:
Budget authority and integration complexity separate high-investment infrastructure plays from content licensing opportunities.
- Learning Management Systems:Centralized delivery platforms encoded in SCORM or xAPI formats anchor institutional technology stacks. K-12 districts in Texas and California mandate these systems as procurement prerequisites, compressing vendor selection timelines around interoperability certifications.
- Interactive Content:Simulation layers and gamification modules command premium pricing by replacing static textbooks with proficiency-responsive experiences. Corporate training departments in financial services verticals unbundle annual subscriptions into discrete skill-verification purchases tied to regulatory mandates.
- E-Books:EPUB 3 and HTML5-encoded searchable texts reduce per-student distribution costs while enabling WCAG 2.1 accessibility compliance for federal procurement eligibility.
- Assessments:Credential-bearing evaluation engines leverage analytics infrastructure to justify premium positioning in competency-based segments.
Learning Management Systems lead on scale; Interactive Content leads on momentum.
Customer Type:
Contract structure and purchasing cycle duration vary sharply across buyer categories.
- Educational Institutions:Universities and school districts negotiate multi-year enterprise licenses with API-first architecture requirements. India's state-level digital literacy programs are accelerating certified vendor pool formation for platform deployment.
- Corporates:Fortune 500 training departments are displacing seat-time contracts with discrete skill-verification purchases. Procurement concentrates in healthcare and financial services verticals where continuing education mandates create predictable module demand.
- Government Agencies:Federal and state entities enforce accessibility standards under Section 508 and ADA, compelling WCAG 2.1 compliance for contract eligibility.
- Individuals:Direct-to-learner distribution in Nigeria and Indonesia bypasses institutional bottlenecks through smartphone-first mobile delivery.
Educational Institutions anchor volume commitment; Individuals expand most quickly through emerging market penetration.
End User:
Functional role determines interface complexity and analytics depth requirements.
- Students:Primary content consumers requiring personalized remediation pathways through adaptive learning engines. Mobile delivery modes dominate in smartphone-first emerging markets.
- Professionals:Workforce participants pursuing stackable micro-credentials funded by German and Singaporean workforce development boards. Demand concentrates in certification programs bypassing traditional degree pathways.
- Educators:Instructors leveraging real-time performance tracking to adjust instructional sequencing within learning management dashboards.
- Trainers:Corporate facilitators deploying synchronous video instruction converged with natural language processing for high-stakes exam preparation.
Students represent the largest addressable base; Professionals generate the steepest pricing expansion.
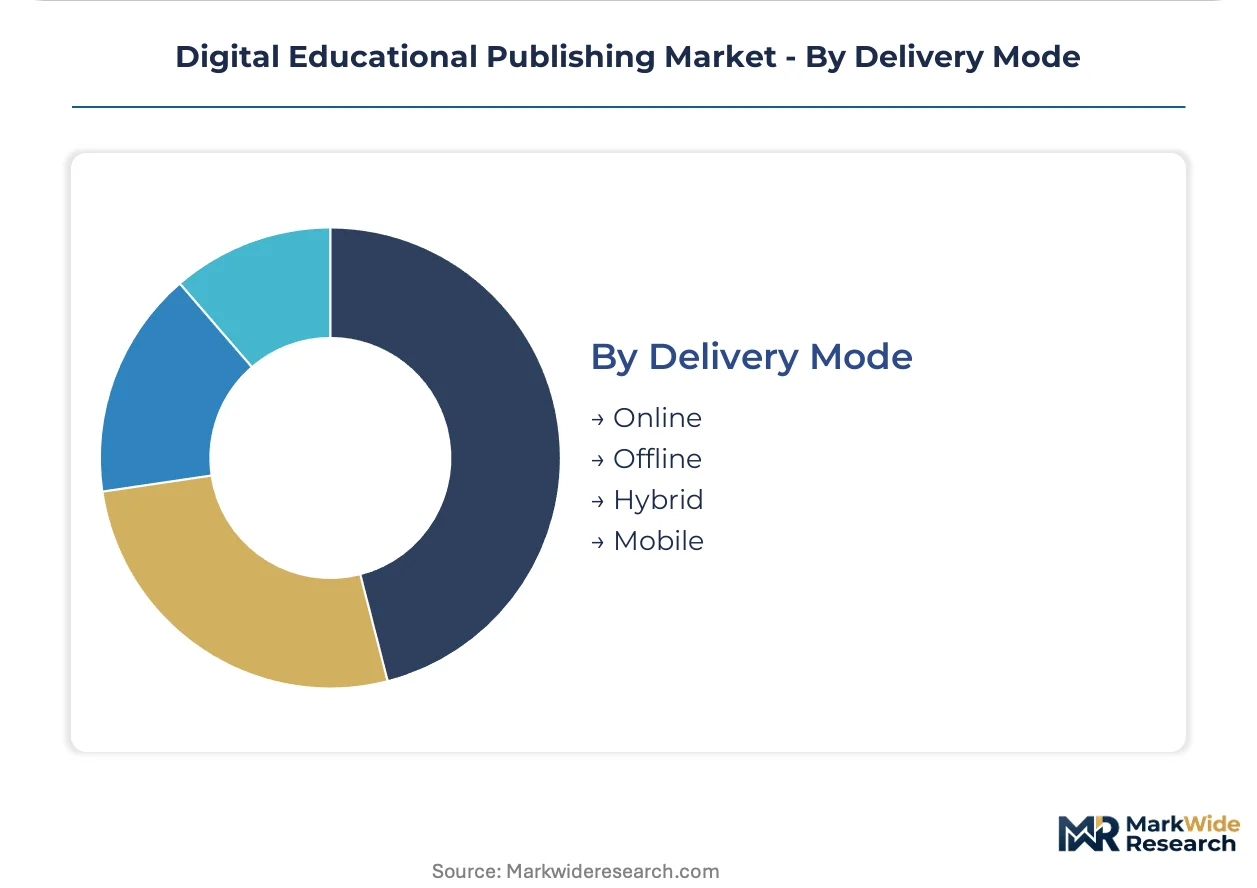
Delivery Mode:
Connectivity infrastructure and device penetration patterns shape geographic rollout sequencing.
- Mobile:Smartphone-dependent workflows enable direct distribution in Indonesia and Nigeria where desktop penetration lags. Publishers re-architect content for smaller screens and intermittent connectivity.
- Online:Cloud-based platforms require stable broadband and generate AWS and Azure hosting cost volatility that compresses margins for video-heavy adaptive content.
- Hybrid:Blended synchronous and asynchronous formats accommodate institutional flexibility requirements while maintaining administrative oversight capabilities.
- Offline:Downloadable content packages serve connectivity-constrained environments with periodic synchronization to learning record stores.
Online delivery dominates current institutional spending; Mobile gains share fastest through emerging market smartphone penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The digital educational publishing industry traces its commercial origins to the United States, where early learning management systems and adaptive content platforms first achieved enterprise scale through federal education technology grants and venture capital deployment in the 1990s.
United States
K-12 districts in Texas and California mandate interoperability certifications that compress vendor selection timelines around API-first platforms. The Department of Education enforces Section 508 and ADA accessibility standards that compel WCAG 2.1 compliance for federal procurement eligibility. Silicon Valley and Boston clusters host the densest concentrations of adaptive learning engine developers.
Germany
Workforce development boards fund stackable micro-credential programs that bypass traditional degree pathways in financial services and healthcare verticals. The EU AI Act imposes transparency obligations on automated tutoring systems requiring auditable decision logic. Berlin and Munich serve as headquarters for vocational training platforms restructuring black-box recommendation engines into rule-based architectures.
India
State-level digital literacy programs accelerate certified vendor pool formation for learning platform deployments across government schools. BIS certification frameworks tighten data localization requirements affecting cross-border content hosting architectures. Bangalore and Hyderabad clusters concentrate engineering talent for mobile-first content re-architected for intermittent connectivity.
United Kingdom
Universities negotiate multi-year enterprise licenses with granular analytics prerequisites for learner dashboard integration. GDPR compliance frameworks shape data governance protocols for cross-border student information flows. London and Oxford anchor credential-bearing assessment infrastructure serving Commonwealth education markets.
Singapore
Workforce development agencies channel public funding toward short-form certification programs targeting mid-career professionals in technology and finance sectors. SkillsFuture credit subsidies reduce price elasticity for individual learners pursuing direct-to-consumer module purchases. The city-state functions as regional headquarters for publishers targeting Southeast Asian smartphone-first emerging markets.
Digital Educational Publishing Market Vendor Landscape
Premium-margin players sit above commodity-margin players across assessment infrastructure and adaptive engine capabilities, with credential-bearing segments commanding pricing multiples over static content licensing. The vendor base organizes into three tiers: integrated platform providers owning delivery infrastructure, specialized content studios licensing modular assets, and assessment-centric operators monetizing analytics engines. Consolidation pressure concentrates among mid-tier publishers lacking proprietary learning record store architectures. Dominant competitive moves include strategic partnerships with cloud infrastructure providers and portfolio diversification into workforce micro-credentials.
Within the integrated platform tier, Pearson Plc and McGraw Hill LLC occupy positions anchored by assessment infrastructure and adaptive learning engines respectively. Coursera Inc. exemplifies the micro-credential specialist archetype targeting degree-adjacent professional learners. Georg von Holtzbrinck GmbH represents European-origin diversified publishing houses navigating EU AI Act compliance restructuring. These three entities collectively illustrate how geographic origin and corporate structure shape strategic positioning across credential-bearing and infrastructure-centric market segments.
| Leading Market Players |
|---|
| Pearson Plc |
| McGraw Hill LLC |
| Scholastic Corp. |
| John Wiley and Sons Inc. |
| Houghton Mifflin Harcourt Co. |
| Georg von Holtzbrinck GmbH |
| Cengage Learning Holdings II Inc. |
| Oxford University Press |
| Coursera Inc. |
| Others |
Supply Flow & Price Mechanics
API-first platform integration anchors supply positioning and pricing power for publishers serving institutional procurement frameworks. Cloud infrastructure providers and adaptive content studios structure delivery architectures around SCORM-to-xAPI migration investments, compressing margins for video-heavy deployments while enabling premium module pricing for competency-tracking capabilities.
Pricing Analysis
Subscription-based SaaS tiers with per-seat licensing dominate institutional contracts, separating premium assessment-anchored platforms from standard content repositories and economy-grade e-book libraries. Price differentiation hinges on certification grade for federal procurement eligibility and customization depth for legacy LMS integration. Pricing pressure stems from AWS and Azure cost volatility compressing margins for publishers delivering simulation-layered content. K-12 districts exhibit highest price sensitivity due to compressed annual budgets, while corporate training departments in financial services verticals demonstrate lowest elasticity tied to regulatory compliance mandates.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and India anchor hub-and-spoke patterns for cloud-based platform delivery and mobile-first content localization. Content production draws from instructional design labor pools concentrated in Boston and Bangalore, plus middleware engineering clusters in Berlin and Hyderabad. Single-source vulnerability concentrates in hyperscaler hosting dependencies for video-intensive adaptive engines. Distribution runs through API-first platform marketplaces and direct enterprise licensing channels, with mobile app stores gaining share in Nigeria and Indonesia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act compounds procurement demand by mandating explainable recommendation engines for institutional eligibility, restructuring platform architecture investments across European vocational training markets.
For Market Incumbents: Hedge against margin compression by deepening proprietary learning record store architectures that reduce middleware dependency for Blackboard and Moodle customizations. Consolidate assessment infrastructure capabilities to defend premium positioning as SCORM-to-xAPI migration accelerates price transparency across competency-tracking segments. Channel control through certified vendor pool formation in India's state-level digital literacy programs offers defensive moat construction against emerging platform entrants. For New Entrants and Emerging Players: India's BIS certification pathways open a window for domestic engineering clusters to capture state-level learning platform deployments ahead of cross-border publishers facing data localization friction. White-space concentration sits in mobile-first direct-to-learner distribution across Nigeria and Indonesia, where smartphone penetration bypasses institutional procurement bottlenecks. Workforce development board funding in Germany and Singapore creates penetrable entry points for stackable micro-credential specialists targeting mid-career professionals in technology verticals. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier publishers lack proprietary analytics infrastructure and depend on third-party learning record store licensing. Long-term viability favors assessment-centric operators with credential-bearing capabilities and adaptive engine IP over static content licensing studios. The signal to watch is EU AI Act compliance restructuring costs forcing distressed asset availability among vocational training platforms with black-box recommendation legacy systems.| Strategic Initiative | Industry Significance |
|---|---|
| Explainable AI Engine Restructuring | EU AI Act transparency mandates compel rule-based architecture investments for European procurement eligibility. |
| Mobile-First Content Re-architecture | Smartphone penetration in Nigeria and Indonesia enables direct distribution circumventing institutional bottlenecks. |
| xAPI Learning Record Store Development | Granular competency tracking justifies premium module pricing over bundled textbook licensing models. |
| Workforce Micro-Credential Expansion | German and Singaporean development board funding creates predictable demand for stackable certification programs. |
| Data Localization Infrastructure Deployment | India's BIS requirements force redundant hosting architectures that concentrate vendor selection around domestic engineering clusters. |
Methodological Framework
Bottom-up institutional procurement modeling reconciled against top-down cloud infrastructure spending tracking forms the analytical core of this study. Primary interviews with learning management system procurement officers, instructional design directors, platform integration engineers, and workforce development board administrators combined with secondary validation from SEC filings of publicly traded publishers, ED.gov federal procurement databases, EU AI Act implementation guidance documents, and BIS certification registry records. Triangulation across stakeholder input and documentary sources ensures segmentation integrity across product type, customer category, and delivery mode dimensions.
Historical trendline analysis of learning platform adoption curves and content licensing contract structures informed projection framework construction across the analysis window. Segmentation modeling incorporated deployment model, organization size, vertical specialization, integration complexity, and regional regulatory cluster dimensions. CAGRs derived from fitted growth curves adjusted for procurement cycle compression effects and cloud migration acceleration patterns specific to K-12 and corporate training verticals.
Revisions become necessary when EU AI Act enforcement timelines shift, India's BIS certification requirements expand scope, or hyperscaler pricing volatility exceeds modeled bandwidth assumptions. Forecasts reflect documented assumptions regarding interoperability mandate adoption rates and mobile-first learner penetration trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Education & Training
Global Admissions Software Market
Education & Training
Africa E-Learning Market
Education & Training
Healthcare LMS Software Market
Education & Training
Asia Big Data Analytics in Education Market
Education & Training
GCC Private K12 Education Market
Education & Training
Global Dyslexia Treatment Market
Education & Training
Flipped Classroom Market
Education & Training
Kindergarten Books Market
Education & Training
Global IoT in Education Market
Education & Training
Online Tutoring Services Market
Education & Training
Global Classroom Management Software Market
Education & Training
Poland Higher Education Market
Education & Training
Higher Education Technology Market
Education & Training
VR Education Market
Education & Training
Edtech Market
Education & Training
Global Gamification in Education Market