
 Corporate Training Services Market | 2026-2036
Corporate Training Services Market Size, Share, and Industry Trends Forecast 2026-2036
Corporate Training Services Market Analytics
Enterprise learning procurement is tilting toward subscription-based digital platforms that displace traditional classroom contracts. Skillsoft leverages its content library depth to anchor long-term enterprise relationships across regulated industries. Coursera competes through university credential partnerships that extend its reach into degree-adjacent corporate pathways. Wilson Learning Worldwide specializes in behavioral-skills workshops that sustain premium pricing in leadership development segments.
Corporate training services encompass structured instructional programs delivered to employed adults to close competency gaps, enhance productivity, or satisfy compliance obligations, typically measured through completion rates, knowledge-retention scores, and on-the-job performance deltas. Delivery mode has fragmented sharply, with virtual and hybrid formats now dominating volume while in-person retains margin concentration in senior management cohorts. Industry vertical segmentation shows technology and finance sectors leading procurement spend, whereas healthcare represents the fastest-growing demand pool as clinical credentialing requirements multiply.
The US Department of Labor, OSHA, and state workforce development boards shape procurement through mandatory safety training, apprenticeship standards, and eligible training provider lists that gate vendor access to public funds. EU frameworks including the CSRD and GDPR indirectly steer training investment by mandating sustainability literacy and data-protection certification across covered enterprises. Stakeholders must monitor how AI-generated content regulation evolves, as pending legislative definitions of acceptable training-data usage will reshape content-development economics and vendor liability structures.
Market Dynamics
AI-powered adaptive learning platforms are collapsing the traditional classroom-to-digital migration timeline from years to quarters, forcing vendors to restructure delivery economics around perpetual subscription models rather than discrete course contracts.
Growth Catalysts
- OSHA Safety Mandates:US federal contractor compliance rules sustain large procurement volumes across healthcare and manufacturing sectors, with annual recertification requirements locking in recurring revenue streams.
- Healthcare Workforce Expansion:Clinical credentialing requirements are multiplying across hospital systems, driving demand for specialized compliance training at scale.
- Generative AI Content Engines:Automated curriculum development is compressing production cycles from months to weeks, enabling rapid deployment of customized enterprise programs.
Market Restraints
- Content Development Cost Inflation:Specialized subject-matter expertise in regulated industries commands premium labor rates, squeezing vendor margins on complex certification programs.
- Platform Concentration Risk:A handful of dominant learning management system providers control enterprise distribution channels, creating gatekeeper dependencies for content publishers.
- Skills Assessment Standardization Gaps:Absence of universally accepted competency benchmarks across industries fragments procurement and complicates ROI demonstration.
Strategic Opportunities
- EU CSRD Sustainability Literacy Mandate:Covered enterprises must certify employees on environmental reporting standards, creating a compliance-driven training category with guaranteed demand.
- Micro-Credential Stackability:Modular digital badges that accumulate into portable qualifications are opening pathways between corporate training and formal degree programs.
- Virtual Reality Simulation Convergence:Immersive hazardous-environment training for oil, gas, and healthcare applications is reducing liability exposure while improving knowledge retention metrics.
Industry Challenges
- Instructional Design Talent Scarcity:Competition for professionals who blend pedagogy with data analytics is intensifying as platforms race to personalize learning pathways.
- Legacy System Integration Friction:Enterprise HR information systems often lack API compatibility with modern adaptive platforms, delaying deployment and inflating implementation costs.
- Cross-Border Certification Recognition:Professional licenses and safety credentials frequently fail to transfer across state or national boundaries, complicating multinational workforce development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corporate Training Services Market |
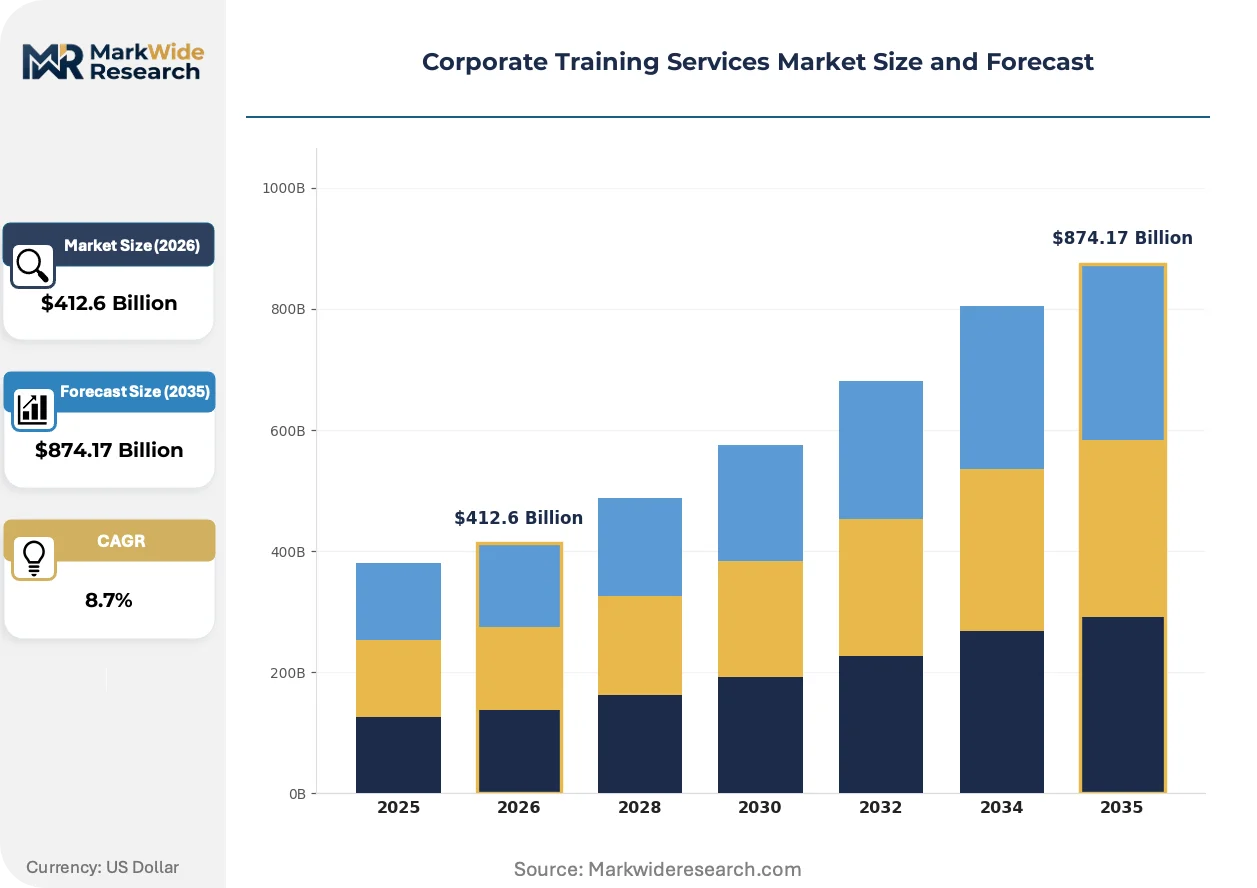
| Market Size in 2026 | $412.6 Billion |
| Market Size in 2035 | $874.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Online Courses, Workshops, Coaching, Assessment Services Industry Vertical: Technology, Finance, Healthcare, Manufacturing Delivery Mode: In-Person, Virtual, Hybrid, Blended Audience Level: Entry-Level, Mid-Level, Senior Management, Executives |
| Companies Covered | Skillsoft, Dale Carnegie Training, LinkedIn Learning, Coursera, Udemy, FranklinCovey, GP Strategies, Korn Ferry, Wilson Learning Worldwide, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corporate Training Services Market Evolving Landscape
Generative AI and immersive simulation technologies are compressing the traditional instructional design cycle while regulatory mandates in sustainability and data protection are creating entirely new training categories with compulsory purchase characteristics.
Adaptive learning algorithms are collapsing the cost structure of personalized instruction by automating real-time difficulty adjustment based on learner performance data. Fortune 500 HR departments are deploying these systems across technical and compliance curricula within single fiscal cycles. The technology is collapsing the historical trade-off between training scale and individualization, enabling mass-customized certification at unit economics previously reserved for generic content libraries.
The EU AI Act establishes mandatory risk-management training obligations for organizations deploying high-risk artificial intelligence systems in employment contexts. Covered enterprises must document workforce competency in algorithmic oversight and bias detection. Financial services and HR technology vendors operating in Europe face immediate procurement pressure to certify implementation teams or risk operational suspension.
Enterprise buyers are consolidating vendor relationships around integrated platforms that combine content libraries, skills analytics, and credential verification in single contracts. Traditional standalone workshop providers and specialized compliance trainers are losing access to procurement committees that prefer unified sourcing. This concentration is most visible in United States federal contracting, where eligible training provider list requirements favor established platforms with established government sales infrastructure.
Corporate Training Services Market Segmentation
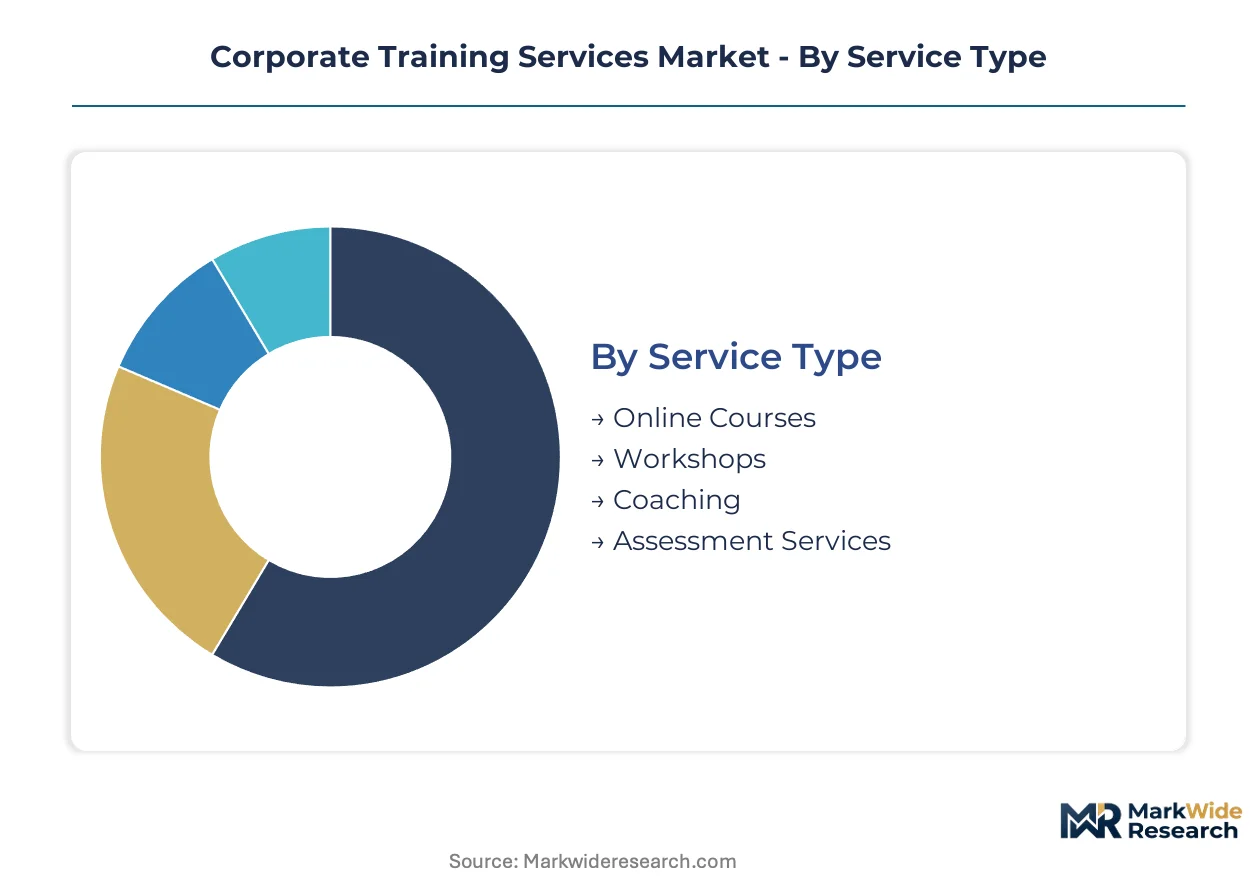
Corporate training procurement decisions fragment sharply across service formats, industry compliance requirements, delivery infrastructure, and workforce seniority tiers. Vendors must configure modular offerings that map to these intersecting dimensions or risk exclusion from enterprise vendor lists.
Service Type:
Organizations deploy distinct service formats depending on whether the objective is knowledge transfer, behavioral change, or compliance verification.
- Online Courses:Self-paced digital modules with automated progress tracking dominate technical and regulatory curricula. Healthcare systems in the United States purchase these at scale to satisfy OSHA-mandated annual recertification for clinical staff.
- Workshops:Facilitated group sessions concentrate in leadership development and team dynamics applications. Finance sector demand sustains premium pricing for behavioral-skills intensives delivered to mid-level managers.
- Coaching:One-on-one executive development engagements command the highest per-learner economics. Senior management cohorts in technology firms drive procurement of personalized leadership coaching.
- Assessment Services:Psychometric testing and competency benchmarking validate training ROI for procurement committees. Federal contractors rely on these to document workforce qualification for compliance audits.
The dominant share belongs to Online Courses, while Coaching is closing the gap fastest as executive development budgets expand.
Industry Vertical:
Regulatory intensity and workforce skill half-lives create divergent spending patterns across sectors.
- Technology:Continuous upskilling on emerging platforms drives subscription-based procurement of adaptive learning systems. Silicon Valley employers prioritize micro-credential stackability to retain engineering talent.
- Healthcare:Clinical credentialing mandates multiply as patient-safety regulations tighten. Hospital systems allocate expanding workforce development budgets to specialized compliance training at scale.
- Finance:Risk management certification and ethics training sustain recurring revenue streams. SEC disclosure requirements and anti-money laundering protocols mandate regular staff retraining.
- Manufacturing:Safety-critical environments require hazardous-material handling certification and equipment operation permits. OSHA compliance rules lock in annual recertification contracts.
Healthcare is expanding most quickly, though Technology retains the largest absolute procurement volume.
Delivery Mode:
Platform economics and learner cohort characteristics determine format selection.
- Virtual:Synchronous remote instruction collapsed cost-per-learner metrics during enterprise digital transformation. Fortune 500 HR departments now deploy virtual formats across technical curricula within single fiscal cycles.
- Hybrid:Blended schedules combine self-paced digital content with scheduled live sessions. Mid-level management development programs favor this format for flexibility without sacrificing facilitator interaction.
- In-Person:Physical classroom delivery concentrates in senior executive cohorts and hazardous-environment simulation. Premium pricing persists where relationship-building or hands-on equipment training is non-negotiable.
- Blended:Integrated pathways alternate between digital modules and face-to-face application sessions. Healthcare systems adopt blended structures to balance scale with clinical skills verification.
Virtual delivery holds the dominant share, while Hybrid is gaining share fastest as enterprises optimize between cost and engagement.
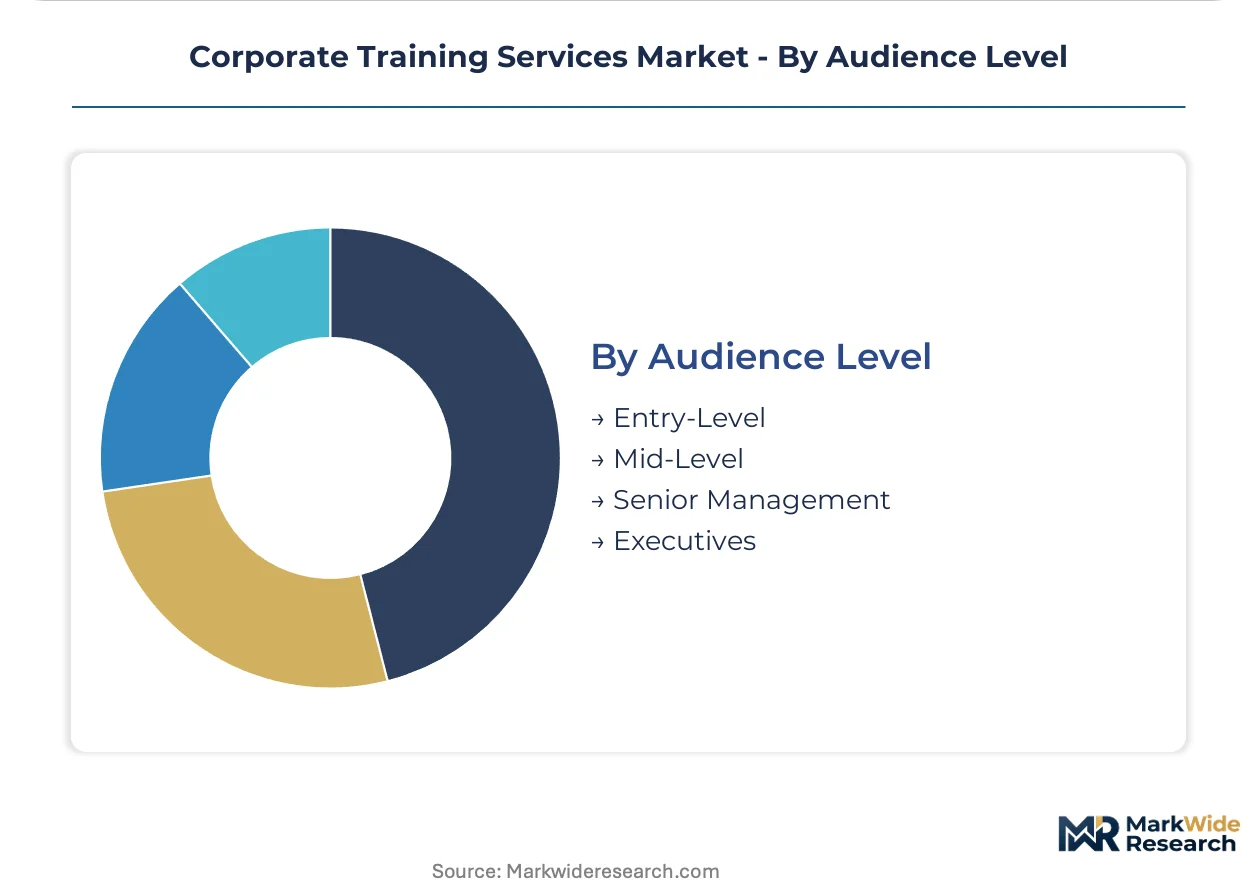
Audience Level:
Career stage dictates content complexity, delivery format, and procurement authority.
- Entry-Level:Foundational onboarding and compliance baseline training for new hires. High volume, standardized content, and automated assessment characterize this tier.
- Mid-Level:Functional specialization and cross-functional project management skill-building. Technology and finance sectors concentrate spending here to fill pipeline gaps.
- Senior Management:Strategic leadership and organizational change management development. Small cohort sizes sustain premium pricing for customized executive programs.
- Executives:Board-level governance, stakeholder communication, and enterprise transformation leadership. Personalized coaching and peer learning networks dominate procurement.
Mid-Level training commands the dominant share, while Executive development is climbing the fastest as succession planning intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA mandates in the United States sustain the largest procurement volumes for corporate training services worldwide. Federal contractor compliance rules and state-level professional licensing requirements lock in recurring revenue streams across healthcare and manufacturing sectors.
United States
Hospital systems in Texas and California expand workforce development budgets to meet patient-safety mandates from the Department of Health and Human Services. OSHA annual recertification requirements for clinical staff and hazardous-material handlers create predictable demand cycles. Federal contractor rules in Virginia and Maryland sustain large procurement volumes through eligible training provider lists.
Germany
Industrial manufacturers in Bavaria and North Rhine-Westphalia prioritize dual vocational training pathways certified by the Federal Institute for Vocational Education and Training. The EU CSRD sustainability literacy mandate drives new compliance-driven procurement among covered enterprises. Automotive clusters in Stuttgart and Wolfsburg anchor demand for technical upskilling on emerging production platforms.
China
State-owned enterprises in the Yangtze River Delta accelerate digital transformation training under MIIT workforce development guidelines. The country's national standardization administration mandates periodic safety recertification for high-risk industrial operations. Technology corridors in Shenzhen and Hangzhou concentrate demand for AI and cloud competency programs.
India
IT services exporters in Karnataka and Telangana scale technical certification programs to maintain global delivery competitiveness. The national skills qualification framework administered by the Ministry of Skill Development and Entrepreneurship standardizes competency benchmarks. Bengaluru and Hyderabad anchor concentrated demand for project management and data analytics training.
United Kingdom
Financial services firms in London and Edinburgh sustain premium spending on risk management and ethics certification under Financial Conduct Authority guidelines. The apprenticeship levy mandates structured training investment across qualifying employers. Fintech clusters in London and Manchester drive demand for regulatory technology and compliance training.
Corporate Training Services Market Competitive Landscape
Content-library aggregators and adaptive-platform specialists split the market between scale-driven volume plays and premium customization tiers. Consolidation pressure favors integrated vendors offering unified content, analytics, and credential verification. Three archetypes dominate: legacy publishers transitioning to subscription models, university-affiliated credential platforms, and behavioral-skills workshop providers. Competitive moves center on strategic partnerships with enterprise HR systems and portfolio diversification into adjacent credentialing services.
Within the content-aggregator tier, Skillsoft leverages library depth to anchor long-term enterprise relationships across regulated industries. Coursera occupies a position exemplifying university-credential partnerships that extend reach into degree-adjacent corporate pathways. Wilson Learning Worldwide sits within the behavioral-skills specialization, sustaining premium positioning in leadership development segments where facilitator-led delivery retains pricing power.
| Leading Market Players |
|---|
| Skillsoft |
| Dale Carnegie Training |
| LinkedIn Learning |
| Coursera |
| Udemy |
| FranklinCovey |
| GP Strategies |
| Korn Ferry |
| Wilson Learning Worldwide |
| Others |
Value Network & Pricing Analysis
The Trans-Pacific fiber-optic corridor carries cloud-based learning platform traffic between US West Coast data centers and Asian enterprise clients, with bandwidth cost fluctuations compressing margins for subscription-based training providers while amplifying price spreads between standardized content libraries and configured compliance programs.
Pricing Analysis
The customization-premium spread separates commodity subscription tiers from enterprise-configured deployments. SaaS-tiered pricing dominates, with differentiation driven by certification level (OSHA-mandated safety tiers vs. general professional development) and customization depth for healthcare compliance workflows. Cost compression in standardized content libraries intensifies as generative AI reduces production cycles, while hospital systems and federal contractors show lowest price sensitivity due to mandated procurement requirements.
Supply Chain Analysis
Upstream feedstock for corporate training services centers on instructional design talent and cloud infrastructure capacity concentrated in the United States, India, and Ireland. Content development draws from specialized subject-matter expertise in clinical safety, financial risk management, and data protection law. Single-source vulnerability persists around dominant learning management system platforms that gate enterprise distribution. Distribution runs through direct enterprise sales teams and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
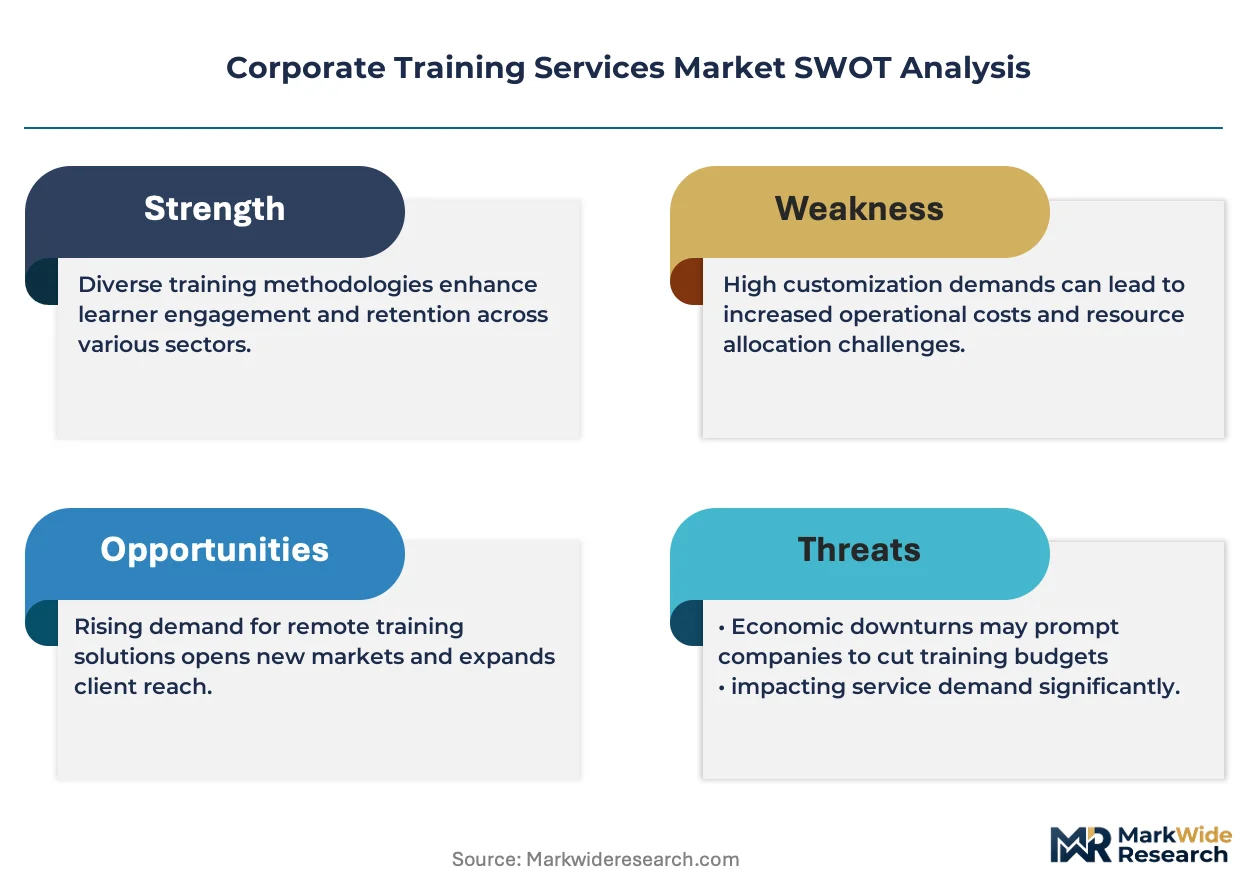
This market rewards vendors who control scarce instructional design capabilities blending pedagogy with adaptive algorithm development, as platform competition intensifies for professionals capable of architecting personalized learning pathways at scale.
For Market Incumbents: Pre-empt margin erosion in standardized content tiers by deepening proprietary assessment analytics capabilities and securing exclusive integration partnerships with dominant HR information system providers. Threat from generative AI content engines demands accelerated investment in algorithmic personalization IP that commoditized libraries cannot replicate. For New Entrants and Emerging Players: Establish a beachhead in EU CSRD sustainability literacy certification, where compulsory purchase characteristics and limited incumbent specialization create immediate procurement access. Target mid-market manufacturing enterprises in Germany and France with modular micro-credential offerings that satisfy emerging environmental reporting mandates without requiring full platform displacement. For Investors and Strategic Acquirers: Behavioral-skills workshop specialists with established facilitator networks and premium enterprise relationships represent the most defensible acquisition archetype. Long-term viability hinges on conversion to hybrid delivery models that preserve pricing power while capturing scale efficiencies. Monitor OSHA regulatory expansion into new industry verticals as inflection signal for compliance-driven demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Adaptive Platform Integration | Unifies content libraries with HRIS systems to reduce procurement friction for hospital systems. |
| Micro-Credential Stackability | Links corporate training modules to university degree pathways for technology sector talent retention. |
| VR Simulation Deployment | Reduces liability exposure for oil and gas operators through immersive hazardous-environment certification. |
| EU CSRD Compliance Certification | Captures mandatory sustainability literacy procurement from covered enterprises under reporting mandates. |
| AI Content Engine Investment | Compresses curriculum development cycles from months to weeks for customized enterprise programs. |
Research Methodology
The analysis maps online course platforms, facilitated workshops, executive coaching engagements, and assessment services, each validated through chief learning officers, HR procurement directors, compliance training managers, and platform engineering leads, combined with SEC filings from publicly traded vendors, OSHA regulatory dockets, EU official journal entries, and hospital procurement database extracts, with bottom-up enrollment data triangulated against top-down enterprise spending estimates.
Assumptions held fixed include prevailing OSHA enforcement intensity, EU regulatory implementation timelines, and cloud infrastructure cost trajectories, while variables tested across the projection horizon encompass AI content generation adoption curves, healthcare workforce expansion rates, and cross-border credential recognition frameworks. Segmentation dimensions modeled cover service format, industry vertical, delivery mode, and audience seniority tier, with CAGRs derived from regression analysis against historical procurement patterns and workforce development budget allocations.
Stress conditions across federal contractor compliance rule modifications, generative AI regulatory definitions, and healthcare credentialing mandate expansion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these bounded assumptions and acknowledge that AI-generated content liability rulings or platform concentration enforcement actions could materially revise trajectory. Quarterly review of OSHA regulatory bulletins, EU AI Act implementation guidance, and hospital system workforce development budget disclosures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Corporate Training and Talent Development
IT Training Market
Corporate Training and Talent Development
Corporate Workforce Development Training Market
Corporate Training and Talent Development
Asia Pacific Strategic Consulting Services Market
Corporate Training and Talent Development
Integrated Talent Management Market
Corporate Training and Talent Development
Asia-Pacific Management Consulting Services Market
Corporate Training and Talent Development
Corporate Training Market
Corporate Training and Talent Development
Asia Pacific HR Professional Services Market
Corporate Training and Talent Development
Asia-Pacific Corporate Training Market
Corporate Training and Talent Development
Executive Coaching Certification Market
Corporate Training and Talent Development
Frontline Workers Training Market
Corporate Training and Talent Development
Middle East and Africa Management Consulting Services Market
Corporate Training and Talent Development
Global Sales Training Market
Corporate Training and Talent Development
Competency-Based Education Spending Market
Corporate Training and Talent Development
Europe Corporate Training Market
Corporate Training and Talent Development
Talent As a Service Market
Corporate Training and Talent Development
Europe Executive Search (Headhunting) Market