
 US Child Care Market | 2026-2036
US Child Care Market Size, Share, and Industry Trends Forecast 2026-2036
US Child Care Market Intelligence
Early childhood educator shortages is reorganizing capacity expansion across the US child care landscape. Bright Horizons Family Solutions leverages corporate partnership contracts to anchor employer-sponsored center placement. KinderCare competes through scale advantages in center-based real estate acquisition. Primrose Schools differentiates via proprietary curriculum standardization across franchise locations.
US child care encompasses licensed supervision, developmental programming, and early education delivery for children from infancy through age twelve, typically operating under state-mandated staff-to-child ratios and facility safety codes. Center-based care commands the largest revenue share due to higher per-slot pricing and regulatory compliance costs that home-based providers absorb less efficiently. After-school programs represent the fastest-expanding service type as school district partnerships extend operational hours. Corporate subsidies within payment models concentrate margin pools among employers seeking workforce retention leverage.
State licensing boards, the federal Office of Child Care, and Head Start Performance Standards collectively govern caregiver ratios, facility inspections, and curriculum benchmarks across jurisdictions. OSHA workplace safety rules and state fire codes further constrain physical plant requirements. Stakeholders must monitor pending federal child care subsidy legislation and evolving state pre-K expansion timelines to align capacity investments with reimbursement rate shifts.
Market Dynamics
Early childhood educator shortages are compressing capacity expansion timelines across the US child care landscape, forcing operators to restructure compensation models and recruitment pipelines while federal subsidy rate negotiations lag behind wage inflation.
Growth Catalysts
- Head Start Performance Standards:Federal curriculum mandates are elevating credential requirements and creating demand for qualified instructional staff across center-based providers.
- Healthcare sector employers:Hospital systems and health networks are expanding on-site child care benefits to reduce nursing turnover and shift-work absenteeism.
- Suburban Texas-Florida-North Carolina corridor:Young family migration into these metropolitan peripheries is concentrating new center demand in fast-growing exurban counties.
Market Restraints
- Wage-cost spiral:State minimum wage escalations and competing retail-sector hourly rates are compressing operating margins without proportional subsidy adjustments.
- Real estate concentration:Zoning restrictions in high-income municipalities limit center siting options, pushing development toward lower-density jurisdictions with weaker demand density.
- Home-based substitute threat:Informal family care networks and unlicensed home providers capture price-sensitive segments during economic stress periods.
Strategic Opportunities
- Rural underserved tracts:Child Care and Development Block Grant expansion into non-metropolitan counties creates first-mover positioning for quality-rated providers.
- Employer-sponsored channel innovation:Corporate partnership models allow operators to secure multi-year revenue commitments and reduce enrollment volatility.
- After-school convergence:District partnership contracts for extended-day programming open incremental revenue streams without full center capex requirements.
Industry Challenges
- CDA credential pipeline gaps:Community college early childhood programs produce insufficient graduates to replace retiring educators and fill expansion slots.
- State licensing timeline compression:Multi-month inspection backlogs delay revenue commencement for completed construction projects.
- Legacy payroll-benefits integration:Fragmented back-office systems across franchise networks obstruct real-time labor cost visibility and compliance tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Child Care Market |
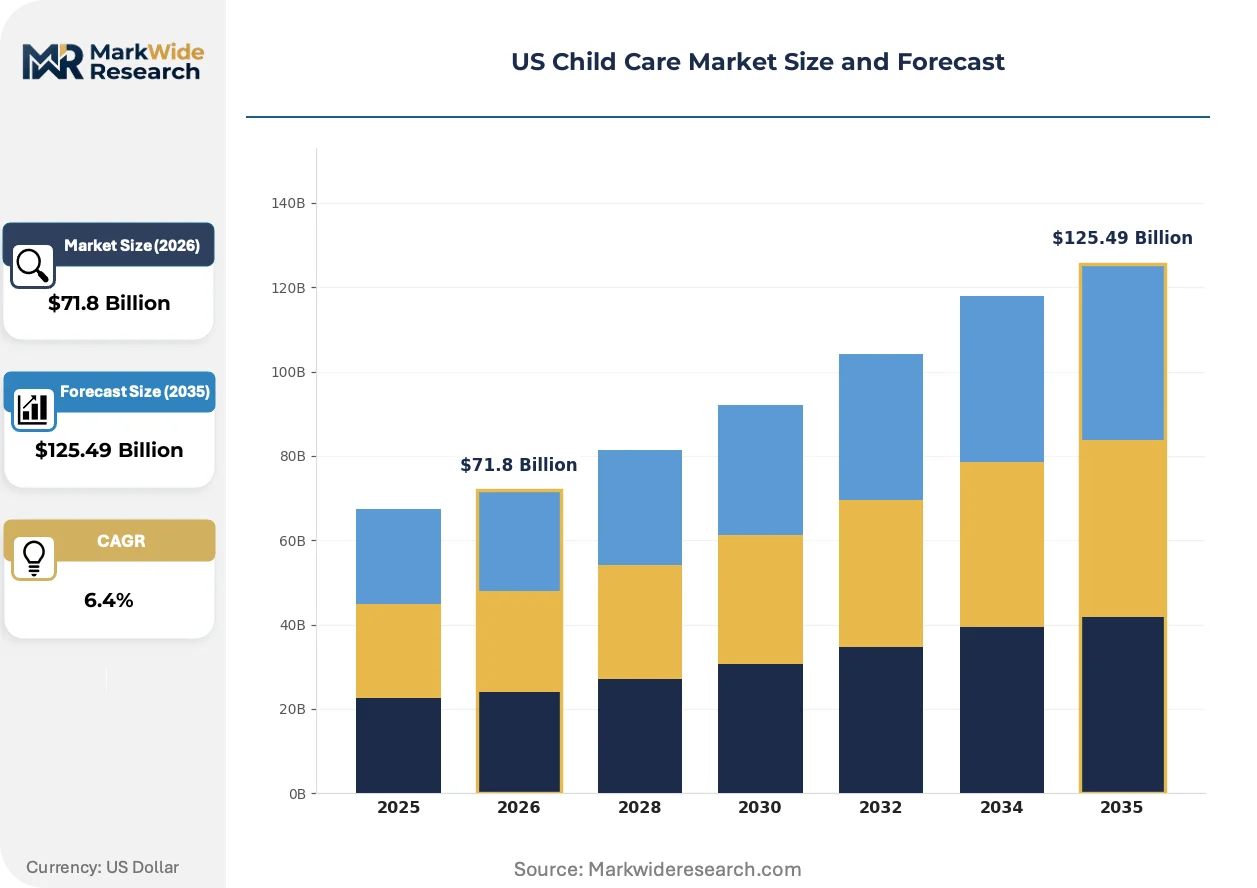
| Market Size in 2026 | $71.8 Billion |
| Market Size in 2035 | $125.49 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Daycare Centers, Family Child Care, After-School Programs, Preschool Services Age Group: Infants, Toddlers, Preschoolers, School-Age Children Care Setting: Home-Based, Center-Based, Community Programs, Hybrid Models Payment Model: Public Funding, Private Pay, Corporate Subsidies, Sliding Scale Fees |
| Companies Covered | The Goddard School, Kiddie Academy, Learning Care Group, The Learning Experience Academy of Early Education, Lightbridge Academy, Bright Horizons Family Solutions, Primrose Schools, Children's Lighthouse, KinderCare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Child Care Market Strategic Shifts & Innovations
Digital administrative tools and data-driven family engagement platforms are compressing operational overhead while reshaping how providers demonstrate developmental outcomes to subsidy administrators and corporate sponsors.
Child care management software is miniaturizing back-office functions through automated attendance tracking, integrated state reporting, and parent communication portals. Medium-sized center chains are adopting these platforms fastest, replacing paper-based systems within twelve-to-eighteen month implementation windows. This technology is miniaturizing the administrative staff footprint required per licensed slot, allowing operators to redirect labor budgets toward classroom educator wages.
OSHA workplace safety enforcement and state fire code amendments are tightening physical plant requirements for indoor air quality and emergency egress systems. Compliance costs are rising fastest for older facilities in legacy urban locations where retrofitting competes with demolition economics. Center operators in Massachusetts and California are responding by consolidating into purpose-built suburban facilities rather than renovating aging inventory.
Subscription-based family engagement apps are displacing traditional daily paper reports and periodic parent-teacher conferences. Urban dual-income households are driving adoption, expecting real-time developmental milestone updates and photo documentation. This behavioral shift is most visible in Seattle, Austin, and Denver markets where technology-sector parents normalize always-on connectivity expectations across service categories.
US Child Care Market Segmentation
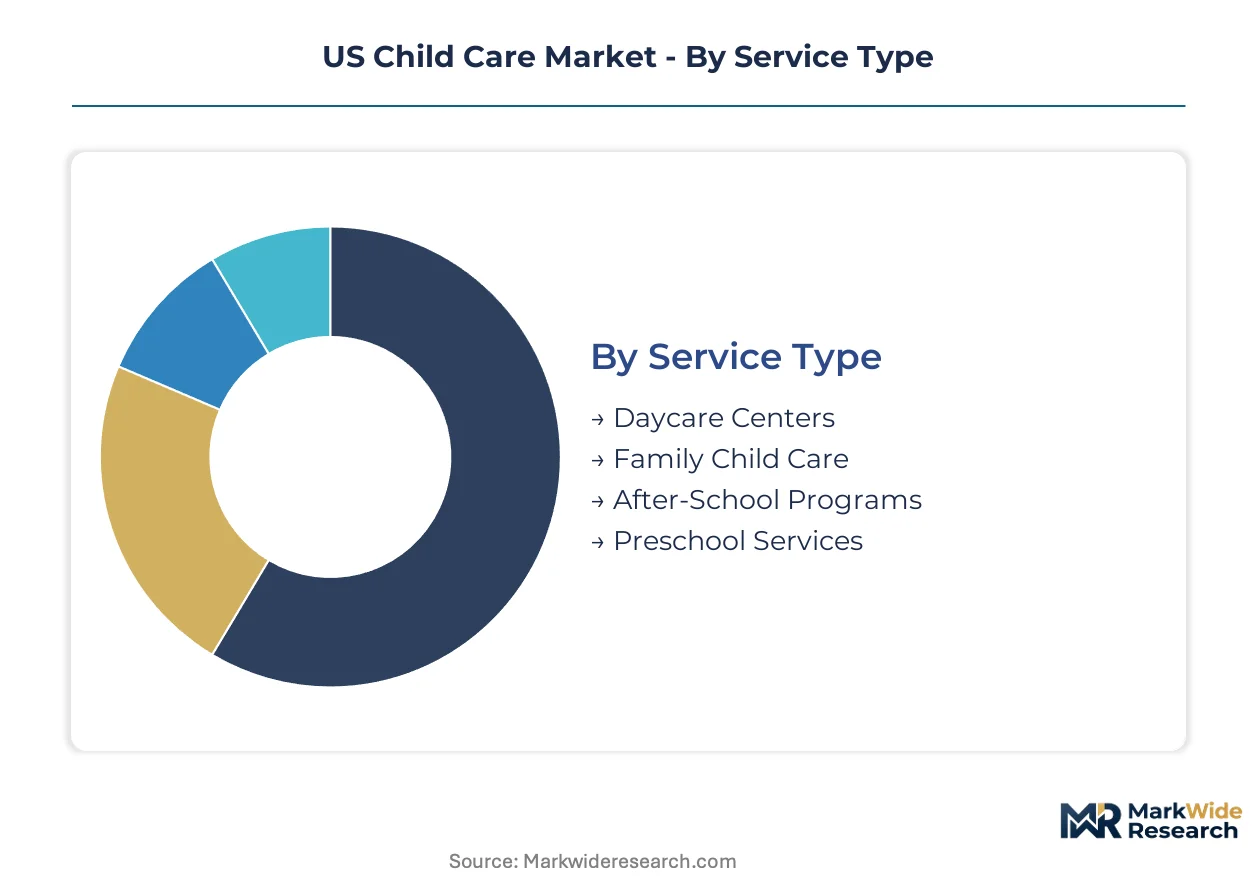
Segmentation in the US child care market reveals how regulatory frameworks, family demographics, and employer benefit structures fragment demand across distinct operational models. Understanding these divides allows operators to align capacity investments with reimbursement mechanisms and geographic concentration patterns.
Service Type:
Domestic demand patterns vary sharply between institutional and informal care channels, with export-oriented corporate contract models emerging through employer-sponsored networks.
- Daycare Centers:Licensed facilities operating under state-mandated staff-to-child ratios deliver full-day supervision and developmental programming. Demand concentrates in suburban metropolitan corridors across Texas, Florida, and North Carolina where young family migration accelerates and dual-income households require extended coverage hours.
- Family Child Care:Small-scale, home-based operations serving limited enrollment under state licensing thresholds. Texas and Florida exurban counties show expanding capacity as zoning restrictions push providers toward lower-density jurisdictions with weaker commercial real estate competition.
- After-School Programs:Extended-day services bridging school dismissal and parent availability through district partnerships or independent operators.
- Preschool Services:Structured early education programming emphasizing kindergarten readiness and developmental milestone tracking.
Daycare Centers hold the largest share; momentum sits with After-School Programs.
Age Group:
Cost tier stratification separates infant care—commanding premium pricing due to stringent ratio requirements—from more scalable school-age segments.
- Infants:Children under twelve months requiring the most intensive supervision ratios, typically one caregiver per four children under OSHA workplace safety and state licensing rules. Operating margins compress fastest here as wage-cost spirals outpace federal subsidy rate adjustments.
- Toddlers:Children aged one to three years transitioning from individual care routines toward group-based developmental activities. North Carolina's Research Triangle and Austin metropolitan peripheries show concentrated new center demand as technology-sector employers expand on-site benefits.
- Preschoolers:Three to five-year-olds participating in structured early education aligned with Head Start Performance Standards.
- School-Age Children:Five to twelve-year-olds requiring before-school, after-school, or summer coverage.
Infants generate the highest per-slot revenue; Preschoolers are climbing the fastest as state pre-K expansion timelines accelerate.
Care Setting:
Volume distribution reflects real estate accessibility constraints, with center-based capacity concentrating where zoning permits commercial child care and home-based filling regulatory gaps.
- Home-Based:Residential operations serving small cohorts under family child care licensing exemptions or formal certification. Captures price-sensitive segments during economic stress periods, particularly in rural underserved tracts where Child Care and Development Block Grant expansion creates first-mover positioning.
- Center-Based:Purpose-built or retrofitted commercial facilities achieving scale through multiple classrooms and standardized curricula. Massachusetts and California operators are consolidating into suburban facilities rather than renovating aging urban inventory as OSHA fire code amendments tighten.
- Community Programs:Non-profit or faith-based operations leveraging donated space and volunteer labor.
- Hybrid Models:Blended delivery combining physical center attendance with virtual family engagement and home-based enrichment activities.
Center-Based commands dominant volume; Hybrid Models show the steepest expansion trajectory as digital administrative tools compress operational overhead.
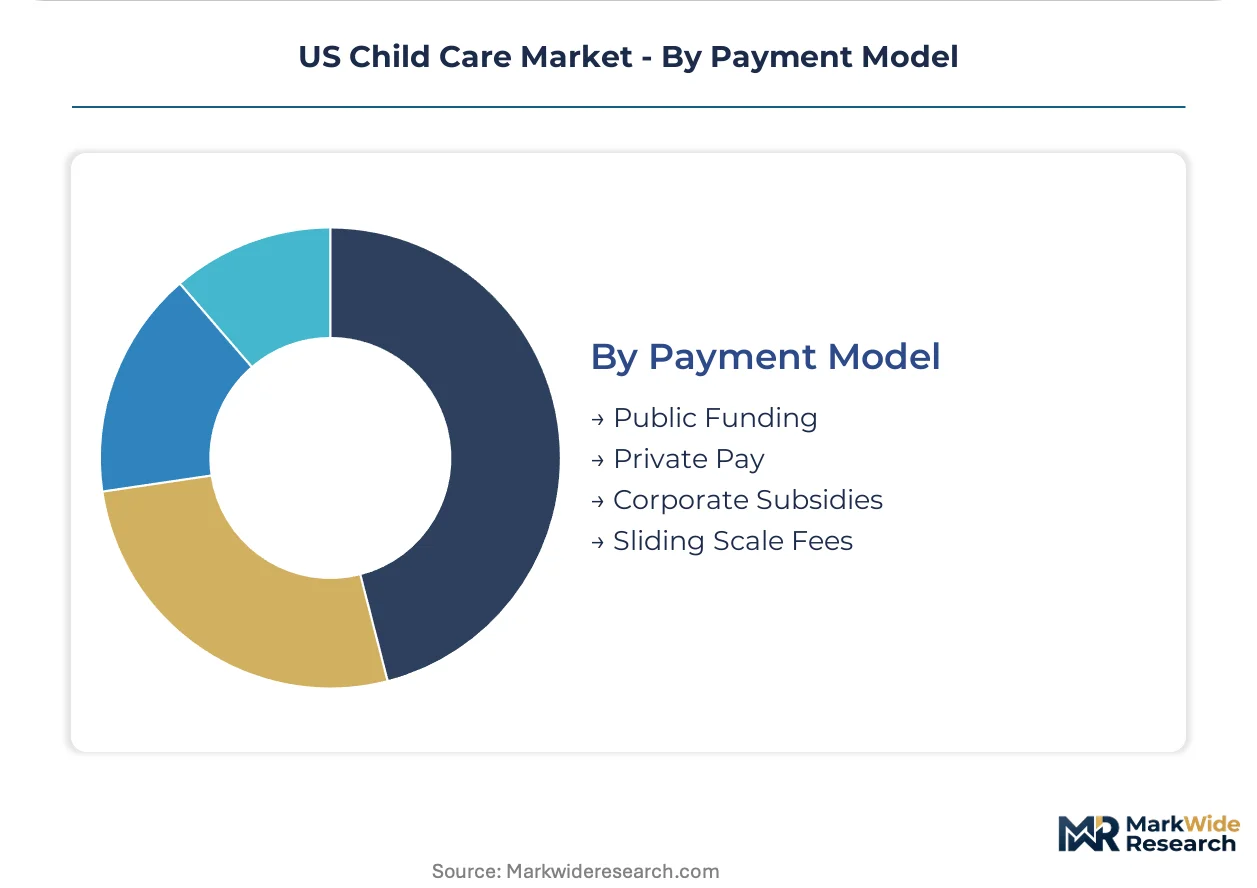
Payment Model:
Customer type fragmentation separates public reimbursement-dependent operators from private-pay premium providers and corporate contract channels securing multi-year revenue commitments.
- Public Funding:Subsidized slots financed through federal Child Care and Development Fund allocations, state pre-K programs, and Head Start grants. Reimbursement rate negotiations lag behind wage inflation, compressing provider participation in high-cost metropolitan markets.
- Private Pay:Full-fee families absorbing market rates without subsidy support. Concentrates in high-income municipalities where zoning restrictions limit supply and dual-income technology-sector households normalize premium pricing.
- Corporate Subsidies:Employer-sponsored benefits covering partial or full tuition through direct center operation or third-party contracts. Healthcare sector employers—hospital systems and health networks—are expanding fastest to reduce nursing turnover and shift-work absenteeism.
- Sliding Scale Fees:Tiered pricing structures adjusting family contributions based on verified income thresholds.
Private Pay retains the largest share; Corporate Subsidies are gaining share fastest as workforce retention leverage drives benefit expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Massachusetts and California child care markets sits roughly 40% above Texas and Florida metros, yet wage-cost spirals and OSHA fire code amendments are compressing margins fastest in these high-rent jurisdictions. This geographic asymmetry is redirecting capital toward suburban corridors where young family migration outpaces regulatory escalation.
Texas
Exurban counties surrounding Dallas-Fort Worth and Houston absorb the nation's fastest center-based capacity expansion as technology-sector employers anchor corporate partnerships. The Texas Workforce Commission administers Child Care and Development Block Grant distribution with reimbursement rates trailing private-pay premiums by widening margins. Austin's Research Triangle periphery concentrates new employer-sponsored center development targeting nursing and shift-work populations.
Florida
Miami-Dade and Orange County zoning restrictions push providers toward lower-density jurisdictions with weaker commercial real estate competition. The Florida Department of Children and Families operates multi-month licensing inspection backlogs that delay revenue commencement for completed construction. Tampa Bay and Jacksonville metropolitan peripheries show expanding family child care capacity as home-based operators capture price-sensitive segments.
North Carolina
The Research Triangle and Charlotte metropolitan corridors concentrate demand from dual-income technology and healthcare households. North Carolina's Division of Child Development and Early Education tightens credential requirements under federal Head Start Performance Standards alignment. Raleigh-Durham suburban counties attract first-mover quality-rated providers positioning for Child Care and Development Block Grant rural expansion.
California
Bay Area and Los Angeles operators face OSHA workplace safety enforcement and state fire code amendments tightening indoor air quality and emergency egress requirements. The California Department of Social Services licenses facilities under staff-to-child ratios that compress infant-care operating margins fastest. Sacramento and Central Valley suburban markets attract consolidating chains abandoning legacy urban retrofit economics.
Massachusetts
Greater Boston's high-income municipalities impose zoning restrictions that limit center siting options and sustain premium private-pay pricing. The Massachusetts Department of Early Education and Care enforces curriculum benchmarks exceeding federal Head Start baselines. Route 128 suburban corridors concentrate purpose-built facility construction as operators abandon aging urban inventory.
US Child Care Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the US child care landscape, with curriculum standardization and digital administrative tools separating premium-positioned chains from scale-driven operators. The market structure fragments across national franchise networks, regional center chains, and independent family child care providers competing for subsidy-dependent and private-pay segments. Three archetypes dominate: employer-sponsored contract specialists leveraging corporate revenue commitments, franchise systems standardizing proprietary curricula across dispersed locations, and scale-driven operators consolidating real estate acquisition in fast-growing metropolitan corridors. Competitive moves concentrate on multi-year corporate partnership securing and suburban facility consolidation in Texas-Florida-North Carolina migration corridors.
Within the employer-sponsored contract tier, Bright Horizons Family Solutions and KinderCare exemplify archetypes securing workforce retention leverage through hospital system and technology-sector partnerships. Primrose Schools occupies a position in the curriculum-standardization archetype, anchoring franchise differentiation through proprietary early education programming. These three operators represent contrasting strategic postures: corporate channel anchoring, scale-driven real estate consolidation, and pedagogical standardization across dispersed locations.
| Leading Market Players |
|---|
| The Goddard School |
| Kiddie Academy |
| Learning Care Group |
| The Learning Experience Academy of Early Education |
| Lightbridge Academy |
| Bright Horizons Family Solutions |
| Primrose Schools |
| Children's Lighthouse |
| KinderCare |
| Others |
Cost & Logistics Intelligence
Center-based capacity utilization above eighty percent in suburban Texas-Florida-North Carolina corridors anchors pricing power for institutional operators while compressing margins for fragmented home-based competitors lacking scale economies in regulatory compliance and back-office automation.
Pricing Analysis
The customization-premium spread between corporate-sponsored slots and standard private-pay enrollment widens as employer contracts absorb administrative overhead and guarantee utilization rates. Three-tier pricing structure across premium employer-sponsored, standard private-pay, and economy subsidy-dependent levels stratifies the market, with wage-cost spirals and lagging federal reimbursement adjustments intensifying pressure on the subsidy tier. Technology-sector parents in Austin and Seattle show lowest price sensitivity, accepting premium positioning for real-time engagement apps and proprietary curricula, while rural families dependent on Child Care and Development Block Grants face acute affordability constraints.
Supply Chain Analysis
Inventory-strategy preferences favor just-in-time educator recruitment pipelines over strategic credential stockpiling, exposing operators to acute shortages when community college graduation cycles misalign with expansion timelines. Labor supply draws from Mexico, the Philippines, and domestic career-changer pipelines, with physical plant inputs resting on regional construction markets in Texas, Florida, and North Carolina. Single-source vulnerability concentrates in specialized early childhood educator certification bodies, while distribution runs through state licensing boards and employer benefit administrators rather than traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Employer-sponsored child care benefits represent a service-attach opportunity where recurring corporate contract revenue expands faster than per-slot tuition growth, embedding operators into workforce retention infrastructure.
For Market Incumbents: Fortify suburban real estate positions in Research Triangle and Dallas-Fort Worth exurban corridors where young family migration concentrates demand density. Deepen backward integration into proprietary educator training academies to bypass community college pipeline gaps threatening expansion timelines. Secure multi-year hospital system partnerships to lock in utilization guarantees against home-based substitute threats during economic stress periods. For New Entrants and Emerging Players: Anchor in rural underserved tracts where Child Care and Development Block Grant expansion creates first-mover positioning without incumbent saturation. Target after-school program district partnerships as the most penetrable segment, requiring minimal capital expenditure compared to full center development. Pursue healthcare sector employers as anchor clients, leveraging shift-work absenteeism reduction narratives to secure corporate sponsorship commitments. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among employer-sponsored contract specialists with multi-year corporate commitments and standardized curriculum platforms. Long-term viability hinges on operators demonstrating workforce retention leverage metrics to benefits administrators. Monitor federal child care subsidy legislation progression as the critical inflection signal for reimbursement rate adjustments that would revalue subsidy-dependent operator portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Corporate Partnership Expansion | Multi-year employer contracts with hospital systems reduce enrollment volatility and stabilize revenue recognition. |
| Educator Pipeline Development | In-house CDA credential academies bypass community college capacity constraints threatening expansion timelines. |
| Digital Platform Integration | Subscription-based family engagement apps capture technology-sector parents demanding real-time developmental milestone tracking. |
| Suburban Facility Consolidation | Purpose-built construction in Texas-Florida-North Carolina corridors escapes OSHA fire code retrofit costs burdening legacy urban inventory. |
| After-School Program Diversification | District partnership contracts open incremental revenue streams without full center capital expenditure requirements. |
Research Approach
Desk research of state licensing board filings, federal Head Start Performance Standards documentation, and employer benefits survey data preceded structured interviews with child care center operators, corporate benefits administrators, early childhood educator training program directors, and state Child Care and Development Fund administrators. Primary fieldwork combined telephone and video interviews with secondary validation against OSHA enforcement records, real estate development permits, and subsidy reimbursement rate databases. Bottom-up enrollment modeling and top-down market sizing triangulated volume estimates across service type, age group, and payment model segmentations.
Variance-decomposition across the projection horizon isolates volume drivers from pricing dynamics, with analytical frameworks modeling service type, age cohort, care setting, and payment mechanism as core segmentation dimensions. CAGRs derive from enrollment capacity expansion trajectories, reimbursement rate adjustment scenarios, and metropolitan migration pattern correlations. Industry-specific forecast inputs include state pre-K expansion timelines, employer benefits adoption curves, and educator credential pipeline graduation rates.
Decision-makers should treat outputs as directional under assumptions of continued young family migration into suburban Texas-Florida-North Carolina corridors and stable federal subsidy authorization levels; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as Head Start Performance Standards enforcement intensity and state minimum wage escalation trajectories evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Education & Training
E-Learning Solutions Market
Education & Training
Online Language Learning Market
Education & Training
Global Training Software Market
Education & Training
Edutainment Market
Education & Training
North America K-12 Furniture Market
Education & Training
Edtech Market
Education & Training
Global Virtual Training and Simulation Market
Education & Training
Global Mechatronics and Robotics Courses Market
Education & Training
Digital Course Recorder Market
Education & Training
K-12 Education Market
Education & Training
Poland Higher Education Market
Education & Training
HSE Consulting Training Services Market
Education & Training
School Information Management System Market
Education & Training
E-Learning Market
Education & Training
United States E-Learning Market
Education & Training
RPA Platform Training Market