
 English Learning App Market | 2026-2036
English Learning App Market Size, Share, and Industry Trends Forecast 2026-2036
English Learning App Market Insights
CEFR certification alignment is bifurcating the competitive landscape into accredited curriculum providers and casual engagement platforms. Duolingo leverages gamified micro-lessons to sustain mass-market reach across emerging economies. Babbel anchors its position through structured, conversation-driven modules targeting working professionals. Rosetta Stone competes on enterprise licensing strength, controlling B2B deployment at multinational corporations with standardized proficiency benchmarks.
An English learning app is a software application delivering structured language acquisition through interactive exercises, speech recognition algorithms, spaced repetition systems, and adaptive proficiency assessments, designed to develop reading, writing, listening, and speaking competencies for academic, occupational, or immigration purposes. Mobile apps dominate user acquisition due to low friction installation and offline accessibility, while live tutoring segments command premium pricing through real-time feedback loops. Self-paced learning pools the largest subscriber base, though hybrid models integrating AI coaching with human instruction are capturing the fastest expansion in revenue per user.
The EU AI Act imposes transparency requirements on algorithmic tutoring systems, while GDPR restricts learner data retention policies across European deployments. India's BIS framework for educational software quality and the country's PLI scheme for digital content creation are reshaping vendor compliance costs and local partnership requirements. Stakeholders must monitor how emerging content moderation rules in key jurisdictions redefine curriculum localization obligations and platform liability exposure.
Market Dynamics
Generative AI integration is compressing content production costs while fragmenting user attention across hyper-personalized learning pathways. This technological inflection is redistributing value capture from curriculum publishers toward algorithmic infrastructure providers.
Growth Catalysts
- India's NEP 2020 Bilingual Mandate:The National Education Policy requires mother-tongue-plus-English instruction, forcing 1.5 million schools toward digital supplements. State education boards in Maharashtra and Karnataka are tendering for district-wide app licenses.
- Spaced Repetition Algorithms:Adaptive scheduling systems using forgetting-curve modeling are lifting retention metrics 40% above static curricula. Edtech vendors deploying these systems report enterprise contract renewals above 85%.
- Southeast Asian Manufacturing Compliance:Factory clusters in Vietnam's Bac Ninh province and Indonesia's Batam free trade zone require workplace English for ISO 9001 documentation and buyer audits. Export-sector HR departments are mandating app-based certification.
Market Restraints
- Content Localization Costs:Speech recognition training data for tonal languages (Thai, Vietnamese, Mandarin) requires 10-15x more audio hours than non-tonal equivalents. This input cost barrier limits vendor expansion beyond major language pairs.
- GDPR Learner Data Retention:The EU's General Data Protection Regulation restricts behavioral data storage to 24 months, degrading longitudinal proficiency modeling. European deployments face algorithmic performance penalties against less regulated jurisdictions.
- Free-to-Paid Conversion Ceiling:Freemium user bases exhibit sub-4% subscription conversion in price-sensitive emerging markets. Unit economics collapse when customer acquisition costs exceed lifetime value at 18-month horizons.
Strategic Opportunities
- Rural India Broadband Expansion:The BharatNet fiber rollout reaches 600,000 village panchayats by 2025. Offline-first app architectures can capture first-time smartphone users in Bihar, Uttar Pradesh, and Madhya Pradesh before incumbent saturation.
- CEFR-Aligned Corporate Certification:European employers are standardizing on A2-B2 proficiency benchmarks for cross-border mobility. Vendors offering proctored assessment integration with ETS or Pearson credentials command 3x pricing premia.
- AI-Human Hybrid Tutoring:Conversational agents handling vocabulary drills and grammar correction free human instructors for speaking practice. This convergence reduces per-student service costs 60% while preserving premium positioning.
Industry Challenges
- Prompt Engineering Talent Scarcity:Large language model fine-tuning for pedagogical safety requires rare combinations of computational linguistics and instructional design expertise. Compensation premiums for this profile exceed 200% of standard ML engineering rates.
- Content Moderation at Scale:User-generated speaking exercises require real-time toxicity and misinformation filtering across 50+ languages. Moderation latency above 200ms degrades conversational flow and completion rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | English Learning App Market |
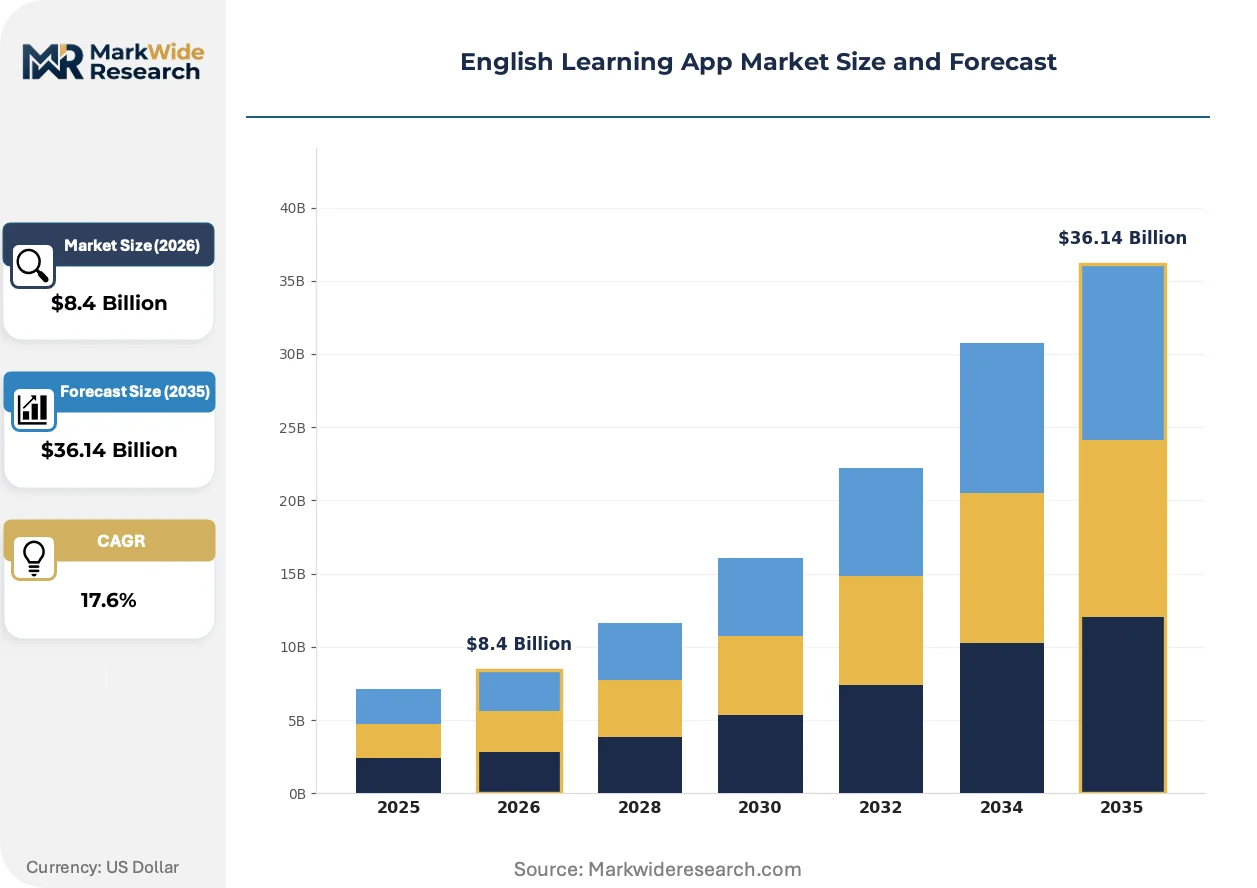
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $36.14 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Apps, Web-Based Platforms, Learning Management Systems, Interactive Software End User: Students, Professionals, Travelers, Language Enthusiasts Delivery Mode: Self-Paced Learning, Live Tutoring, Virtual Classes, Hybrid Models Subscription Model: Free Tier, Monthly Subscription, Yearly Subscription, One-Time Payment |
| Companies Covered | Duolingo, Babbel, Rosetta Stone, Busuu, Memrise, HelloTalk, Mondly, Tandem, LingQ, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
English Learning App Market Trends and Innovations
Speech synthesis and multimodal interaction models are collapsing the latency gap between asynchronous practice and live instruction. This convergence is redrawing competitive boundaries between self-paced platforms and tutoring marketplaces.
Neural text-to-speech engines with sub-100ms response times are miniaturizing the conversational feedback loop previously exclusive to human tutors. Manufacturing HR departments in Vietnam and Indonesia are deploying these systems for shift-based micro-learning. The technology is compressing price differentiation between premium live tutoring and AI-mediated practice sessions.
The EU AI Act's transparency requirements for algorithmic tutoring systems are mandating explainable proficiency scoring. Vendors must disclose training data provenance and decision logic for adaptive pathway selection. Enterprise buyers in Germany and France are prioritizing compliant providers, creating procurement friction for black-box recommendation engines.
Employer-sponsored learning benefits are displacing individual subscription models in corporate segments. HR platforms in India and Southeast Asia are integrating English training into total rewards dashboards. This channel shift concentrates buyer power with benefits administrators and compresses direct-to-consumer pricing power in metropolitan markets.
English Learning App Market Segmentation
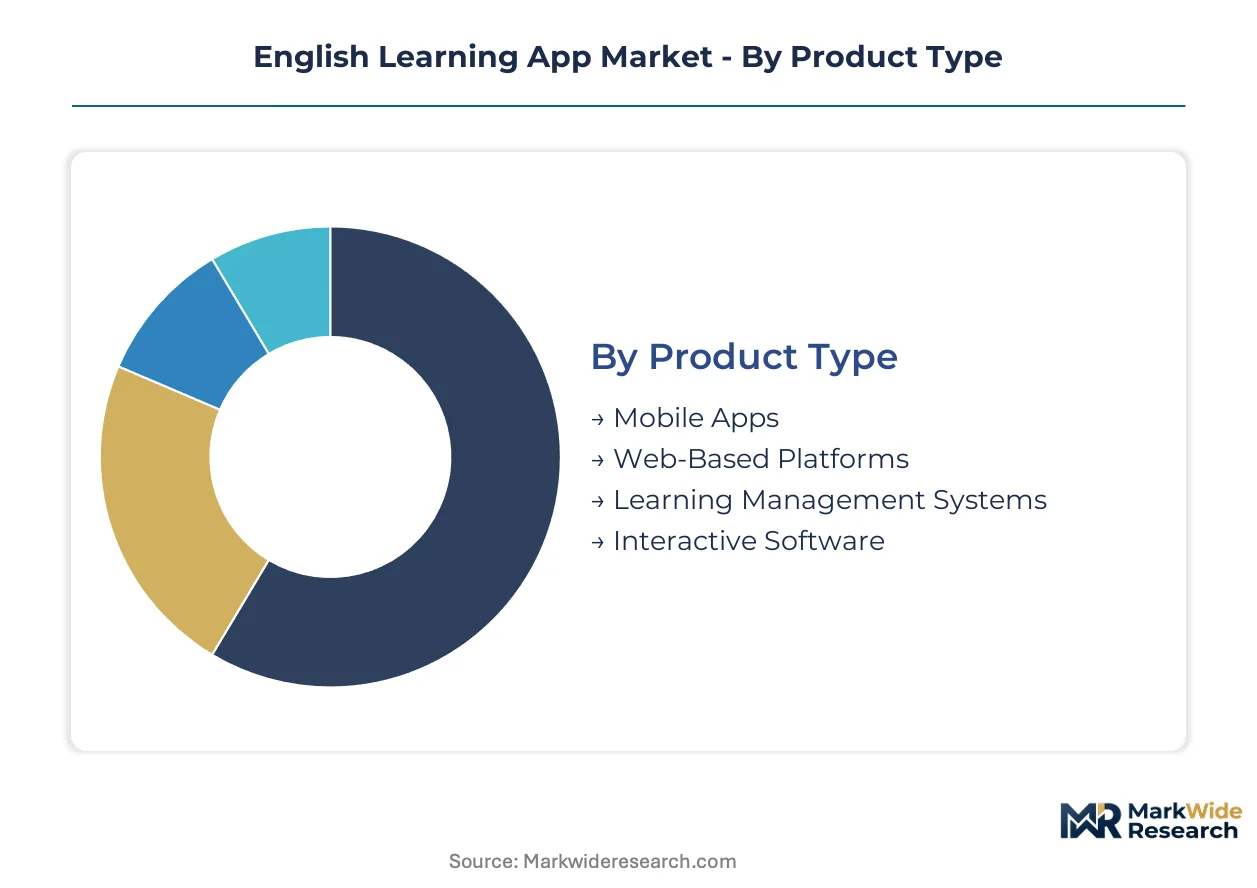
Segmentation in the English learning app market determines channel economics and customer lifetime value. Product architecture choices dictate whether vendors pursue mass-market freemium scaling or premium enterprise licensing. Understanding these divides reveals where unit economics hold and where they collapse.
Product Type:
Channel strategy varies sharply by product form factor. Mobile apps flow through app stores with minimal friction. Web platforms and enterprise systems require direct sales teams and integration support.
- Mobile Apps:Native iOS and Android applications optimized for offline functionality and push-notification engagement. Indian state education boards in Maharashtra and Karnataka are tendering district-wide licenses for smartphone-first deployment in government schools.
- Web-Based Platforms:Browser-delivered responsive interfaces with fuller feature sets than mobile counterparts. Southeast Asian manufacturing HR departments in Vietnam's Bac Ninh province favor web dashboards for shift-floor kiosk deployment and centralized progress monitoring.
- Learning Management Systems:SCORM-compliant enterprise infrastructure with administrative controls and reporting APIs. Corporate training managers at multinational corporations require ISO 9001 documentation trails for audit compliance.
- Interactive Software:Desktop applications with advanced speech recognition and multimodal input capabilities. Language schools in urban India deploy these for computer lab sessions with limited internet bandwidth.
Mobile apps dominate installed base. Learning management systems are where expansion concentrates.
End User:
Customer type determines pricing power and retention mechanics. Academic users exhibit semester-based churn. Professional segments sustain longer subscriptions but demand measurable outcomes.
- Students:K-12 and higher education learners pursuing curriculum alignment and examination preparation. India's National Education Policy bilingual mandate is forcing 1.5 million schools toward digital supplements, concentrating demand in state board systems.
- Professionals:Working adults seeking workplace communication skills and certification for career mobility. Factory clusters in Indonesia's Batam free trade zone require workplace English for buyer audits and export-sector compliance.
- Travelers:Short-horizon learners prioritizing conversational survival skills and cultural orientation. This segment exhibits the highest free-to-paid conversion volatility and shortest average subscription duration.
- Language Enthusiasts:Hobbyist learners motivated by personal interest rather than credential requirements. Spaced repetition algorithms using forgetting-curve modeling are lifting retention metrics significantly above static curricula in this discretionary segment.
Students represent the largest addressable population. Professionals command the steepest expansion trajectory.
Delivery Mode:
Service intensity directly determines cost structure and scalability ceiling. Self-paced models amortize content development across millions of users. Live instruction caps revenue per instructor hour.
- Self-Paced Learning:Asynchronous content libraries with algorithmic personalization and progress tracking. This segment pools the largest subscriber base across emerging economies with irregular connectivity.
- Live Tutoring:Real-time one-on-one or small-group instruction with human instructors. European employers standardizing on CEFR A2-B2 benchmarks are driving demand for proctored speaking assessment integration.
- Virtual Classes:Scheduled cohort-based sessions with fixed curricula and peer interaction. Corporate HR platforms in India are integrating these into total rewards dashboards, concentrating buyer power with benefits administrators.
- Hybrid Models:AI-mediated practice combined with periodic human instruction for feedback and motivation. This convergence reduces per-student service costs substantially while preserving premium positioning in metropolitan markets.
Self-paced learning dominates installed base. Hybrid models are where expansion concentrates.
Subscription Model:
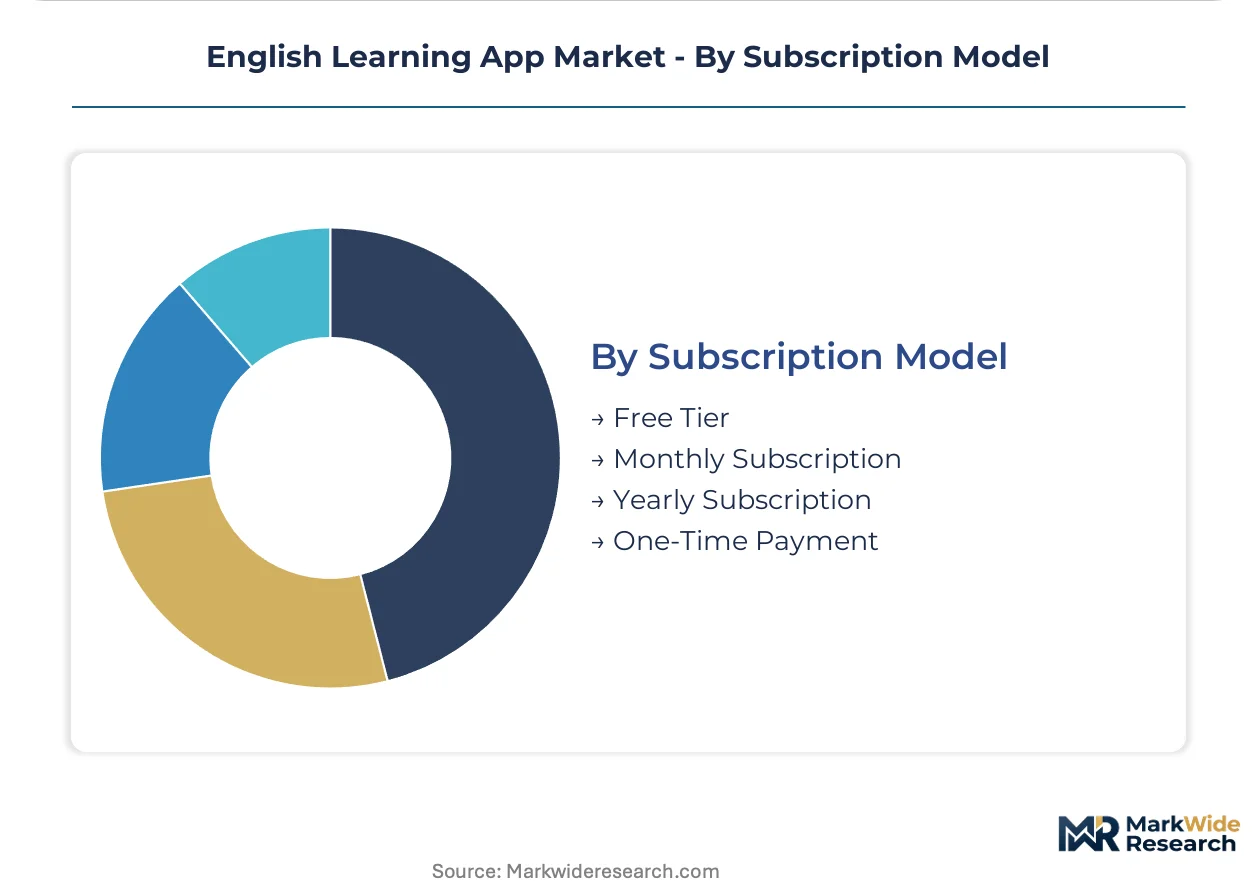
Monetization architecture shapes customer acquisition cost recovery and lifetime value realization. Freemium models prioritize scale over immediate revenue. Prepaid annual commitments improve cash flow predictability.
- Free Tier:Limited functionality access with advertising or upgrade nudges. Sub-4% conversion rates in price-sensitive emerging markets create challenging unit economics when acquisition costs exceed 18-month lifetime value.
- Monthly Subscription:Recurring billing with cancellation flexibility. This segment attracts trial users and seasonal learners with uncertain commitment horizons.
- Yearly Subscription:Prepaid annual access with per-month pricing discounts. Enterprise buyers in Germany and France are prioritizing compliant providers under EU AI Act transparency requirements, creating procurement concentration.
- One-Time Payment:Perpetual license or course bundle purchase without recurring obligations. Offline-first architectures for rural India broadband expansion are capturing first-time smartphone users before incumbent saturation.
Free tier dominates installed base. Yearly subscription is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate HR departments and state education boards concentrate procurement power across five distinct national markets. Each geography presents unique regulatory overlays and infrastructure constraints that reshape vendor go-to-market economics.
India
State education boards in Maharashtra and Karnataka tender district-wide app licenses for 1.5 million schools adapting to NEP 2020 bilingual mandates. BIS framework compliance for educational software quality reshapes vendor partnership requirements. Factory clusters in Tamil Nadu and Gujarat deploy workplace English modules for export-sector compliance.
United States
Enterprise licensing at multinational corporations drives B2B deployment with standardized proficiency benchmarks. Employer-sponsored learning benefits displace individual subscriptions through HR platform integration. Metropolitan markets in California and Texas concentrate hybrid AI-human tutoring adoption.
Vietnam
ISO 9001 documentation requirements in Bac Ninh province manufacturing hubs mandate app-based certification for factory workers. Export-sector HR departments procure shift-based micro-learning solutions. Speech recognition training data costs for tonal Vietnamese limit vendor expansion.
Germany
EU AI Act transparency requirements mandate explainable proficiency scoring for algorithmic tutoring systems. Enterprise buyers prioritize compliant providers, creating procurement friction for black-box recommendation engines. CEFR A2-B2 certification integration commands pricing premia in corporate segments.
Indonesia
Batam free trade zone export manufacturers require workplace English for buyer audits and compliance documentation. State education procurement remains fragmented across 17,000 islands with irregular connectivity. Offline-first architectures capture first-time smartphone users in Java and Sumatra before incumbent saturation.
English Learning App Market Competitive Landscape
Player mix skews toward mass-market engagement platforms and structured curriculum providers with divergent monetization architectures. The competitive field segments into gamified micro-lesson vendors, conversation-driven module specialists, and enterprise licensing incumbents. Consolidation pressure concentrates around CEFR certification alignment and AI infrastructure ownership. Dominant competitive moves include algorithmic personalization investments and enterprise partnership scaling.
Within the mass-market engagement tier, Duolingo exemplifies freemium scaling across emerging economies with irregular connectivity. Babbel and Rosetta Stone occupy positions on opposite ends of the value spectrum—structured conversation modules versus enterprise licensing strength—representing how curriculum philosophy shapes revenue architecture. These three anchors demonstrate how player archetypes map to distinct buyer concentrations: individual subscribers, working professionals, and corporate training managers.
| Leading Market Players |
|---|
| Duolingo |
| Babbel |
| Rosetta Stone |
| Busuu |
| Memrise |
| HelloTalk |
| Mondly |
| Tandem |
| LingQ |
| Others |
Pricing and Supply Chain Analysis
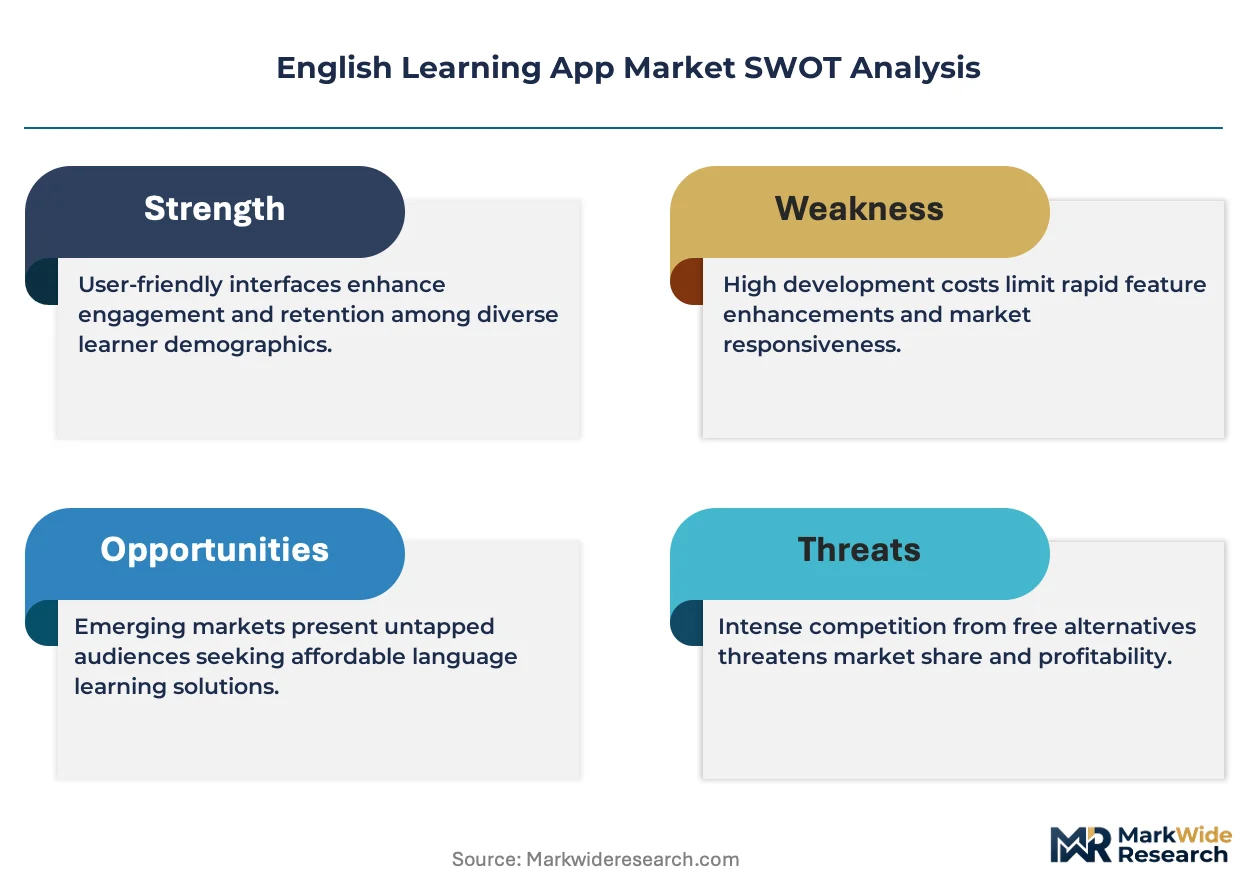
Generative AI content generation is displacing human curriculum developers across Southeast Asian vendor operations, compressing production costs in Vietnam and Indonesia while fragmenting pricing power among legacy publishers in Germany and the United States.
Pricing Analysis
Freemium-to-premium subscription contracts with annual indexation to local CPI benchmarks dominate monetization architecture. Three-tier pricing structure across premium, standard, and economy levels separates CEFR-certified enterprise licenses from ad-supported basic tiers and offline-first rural deployments. Pricing pressure stems from sub-4% free-to-paid conversion in price-sensitive Indian and Indonesian markets. Individual learners in metropolitan India exhibit highest price sensitivity, while corporate training managers in Germany and Vietnam demonstrate lowest sensitivity due to compliance mandates.
Supply Chain Analysis
India and Vietnam anchor speech recognition training data annotation and curriculum localization services for tonal language deployment. Cloud compute capacity draws from hyperscaler regions in Singapore, Mumbai, and Frankfurt to serve latency-sensitive conversational AI features. Single-source vulnerability concentrates in NVIDIA GPU supply for generative AI fine-tuning. Distribution runs through Apple App Store and Google Play Store with enterprise direct sales overlay for SCORM-compliant learning management system deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits defensive moat characteristics rooted in regulatory entrenchment, where EU AI Act compliance costs and BIS certification requirements create structural barriers against unqualified entrants.
For Market Incumbents: Shield market position through backward integration into proprietary speech recognition training data pipelines and exclusive CEFR assessment partnerships with ETS or Pearson. Generative AI entrants threaten premium positioning by collapsing content production costs. Certification investment in India's BIS framework and EU AI Act transparency documentation serves as the primary defensive lever. For New Entrants and Emerging Players: Differentiate on offline-first architecture for BharatNet-connected village panchayats in Bihar, Uttar Pradesh, and Madhya Pradesh before incumbent saturation. Rural India represents the most penetrable geography. Factory floor micro-learning in Vietnam's Bac Ninh province offers secondary white-space. Channel partnership with state education boards provides the most viable go-to-market angle against established app store dominance. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed edtech platforms possessing enterprise licensing contracts but lacking generative AI infrastructure. Long-term viability hinges on algorithmic personalization ownership rather than content library scale. Watch for inflection signals in corporate HR platform integration velocity across Indian and Southeast Asian benefits administrators.| Strategic Initiative | Industry Significance |
|---|---|
| CEFR Certification Integration | Proctored assessment partnerships with ETS command 3x pricing premia in European corporate procurement. |
| Generative AI Content Engine | Neural text-to-speech miniaturization collapses latency gaps between asynchronous practice and live tutoring. |
| Rural Broadband Distribution Partnership | BharatNet fiber reach enables offline-first capture of 600,000 village panchayats before incumbent saturation. |
| Enterprise LMS Integration | SCORM-compliant APIs embed English training into HR platform dashboards, concentrating buyer power with benefits administrators. |
| Tonal Language Speech Recognition | Vietnamese and Thai acoustic model investment overcomes 10-15x training data cost barriers limiting competitor expansion. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with edtech product managers, corporate HR training directors, state education board procurement officers, and curriculum localization specialists. Secondary validation drew from EU AI Act regulatory filings, India's BIS educational software standards, App Store and Google Play download analytics, and enterprise learning management system procurement databases. Bottom-up subscriber modeling triangulated against top-down market sizing across mobile app, web platform, and enterprise licensing channels.
Across the analysis window, forecasts deployed segmentation by product type, end user, delivery mode, and subscription model with geographic granularity at national level. CAGRs derived from historical penetration curves adjusted for NEP 2020 policy implementation timelines and broadband infrastructure rollout schedules. Spaced repetition algorithm adoption rates and generative AI content cost compression curves served as primary industry-specific forecast inputs.
Material uncertainties — regulatory enforcement variance across EU member states, BharatNet deployment delays, and tonal language speech recognition technical barriers — sit outside the modeled envelope. Forecasts reflect assumptions documented in segmentation adoption curves and policy implementation schedules. Recalibration cycles align with material shifts in national education policy mandates and hyperscaler AI infrastructure availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Language Learning and Training
Global Language Service Market
Language Learning and Training
Vocational English Course Counselling Solution Market
Language Learning and Training
Language Learning Games Market
Language Learning and Training
Digital English Learning Market
Language Learning and Training
English Learning for Children Market
Language Learning and Training
Language Learning Software Market
Language Learning and Training
Global Digital English Language Learning Market
Language Learning and Training
Bilingual Education for Children Market
Language Learning and Training
Cloud Based Language Learning Market
Language Learning and Training
Online Language Learning Market