
 Language Learning Software Market | 2026-2036
Language Learning Software Market Size, Share, and Industry Trends Forecast 2026-2036
Language Learning Software Market Analysis
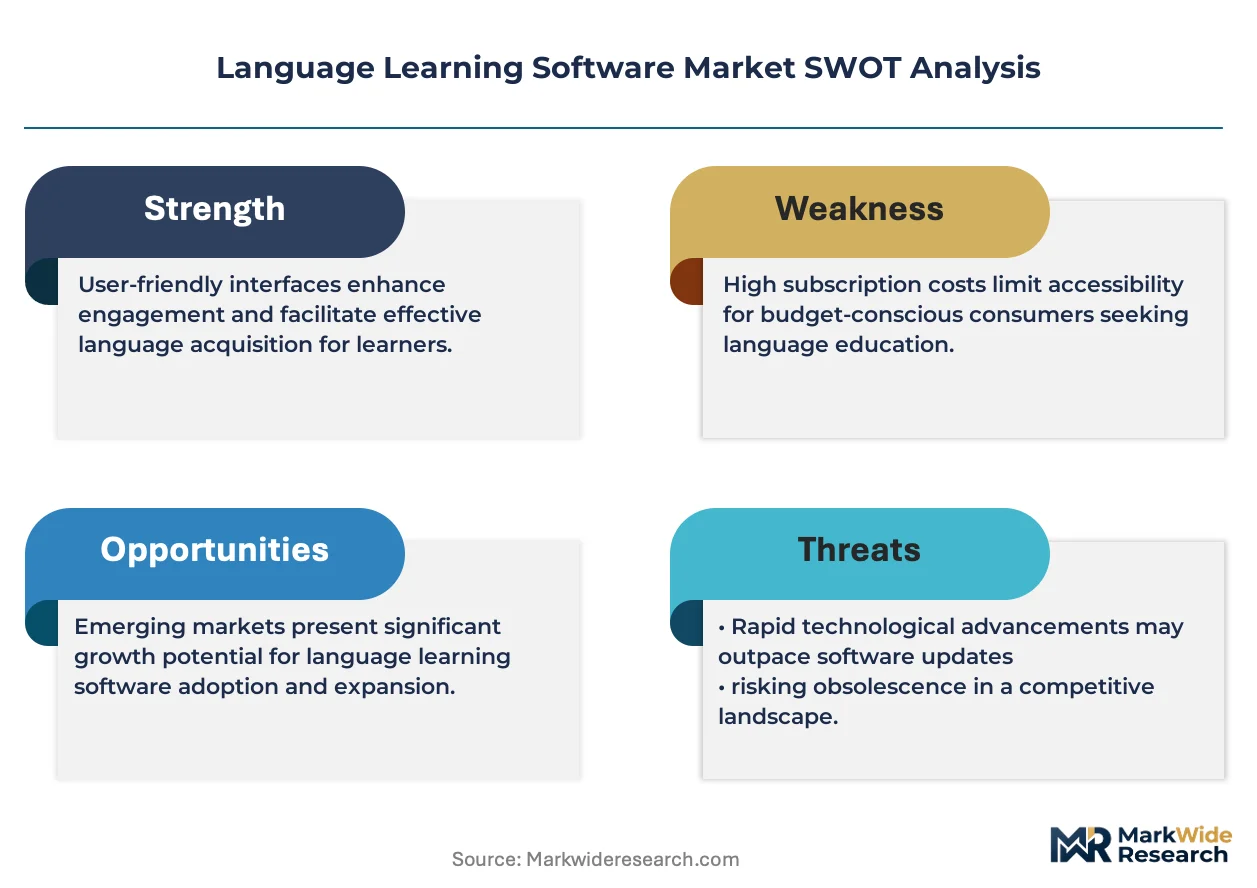
Subscription-based recurring revenue models is tilting competitive dynamics toward platforms with superior user retention economics. Duolingo Inc leverages freemium conversion mechanics to sustain low customer acquisition costs across mass-market language learners. Babbel anchors its position through premium subscription tiers targeting professionals with structured curriculum depth. Rosetta Stone competes in institutional channels where enterprise licensing and government contracts yield longer contract durations.
Language learning software encompasses digital platforms that deliver structured linguistic instruction through algorithmic personalization, speech recognition engines, and spaced repetition protocols designed to accelerate vocabulary retention and grammatical fluency. Mobile application platforms now dominate consumer engagement metrics due to fragmented daily usage patterns and push-notification-driven habit formation. Gamification methodologies capture disproportionate attention share among younger demographics, while corporate target user segments generate higher lifetime value through bulk licensing arrangements. Video lessons and interactive exercises constitute the primary content type investments for platforms seeking to differentiate through immersive multimodal instruction.
The European Union's GDPR framework constrains how language platforms collect and process learner biometric data from speech recognition modules, while the EU AI Act imposes transparency obligations on algorithmic tutoring systems deployed across member states. In the United States, COPPA compliance requirements shape product design decisions for platforms serving K-12 students under thirteen years of age. Stakeholders must weigh regulatory compliance investments against the pace of generative AI integration in personalized curriculum generation.
Market Dynamics
Generative AI integration is compressing curriculum development cycles while forcing platforms to restructure data governance frameworks around biometric speech processing and algorithmic transparency mandates.
Growth Catalysts
- Defense procurement concentration:United States intelligence agencies sustain multi-year contracts for mission-critical language proficiency platforms, creating stable demand anchors for institutional-grade software vendors.
- GDPR biometric exemptions:European Union regulatory clarity on learner voice data processing enables speech recognition engine deployment across member state education ministries without legal ambiguity.
- Cloud-native migration:K-12 and higher education procurement channels are abandoning legacy on-premise installations in favor of SaaS delivery models with lower total cost of ownership.
Market Restraints
- Input cost volatility:GPU compute costs for training large language models fluctuate with semiconductor foundry capacity constraints, compressing margins for AI-native curriculum generation features.
- Supply concentration risk:Cloud infrastructure dependency on hyperscaler data centers in Virginia, Frankfurt, and Singapore creates single-point-of-failure exposure for platform uptime guarantees.
- Regulatory friction:COPPA compliance requirements in the United States fragment product architecture, forcing separate codebases for under-thirteen learners versus adult segments.
Strategic Opportunities
- Underpenetrated vocational segments:Blue-collar workforce language training for logistics and hospitality verticals remains underserved by current premium-focused platform pricing.
- Regulatory tailwind:India's National Education Policy mandates multilingual digital learning infrastructure, creating procurement windows for adaptive language platforms in state school systems.
- Channel innovation:Employer-sponsored learning benefits platforms are emerging as distribution intermediaries, bypassing direct-to-consumer acquisition costs for corporate language training contracts.
Industry Challenges
- Computational linguist scarcity:Platform engineering teams face acute hiring constraints for specialists combining NLP expertise with pedagogical design experience.
- Integration complexity:Enterprise learning management system APIs require bespoke middleware development, extending implementation timelines for institutional deployments.
- Certification timeline compression:Rapidly evolving AI Act transparency obligations in Europe force continuous compliance re-certification cycles for algorithmic tutoring modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Language Learning Software Market |
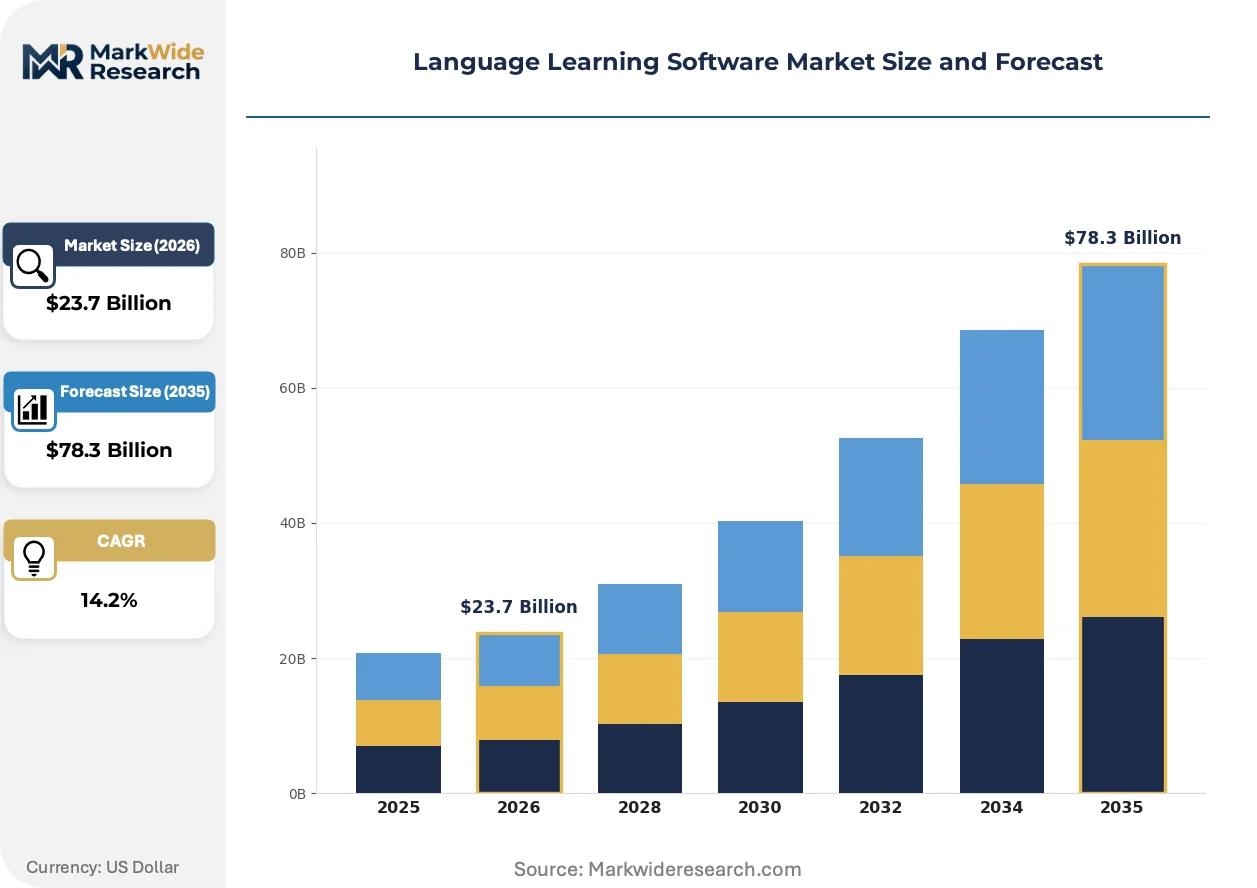
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $78.3 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Web, Mobile Application, Desktop Software, Hybrid Learning Methodology: Gamification, Immersion, Traditional Education, Self-Study Target User: Students, Professionals, Tourists, Corporate Content Type: Video Lessons, Interactive Exercises, Audio Resources, Textbooks |
| Companies Covered | Duolingo Inc, Babbel, Rosetta Stone, Busuu, Memrise, HelloTalk, Lingodeer, Mango Languages, Berlitz Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Language Learning Software Market Emerging Trajectories
Adaptive learning architectures are fundamentally altering how linguistic competency gets measured, certified, and monetized across consumer and institutional buyer segments.
Spaced repetition algorithms are migrating from fixed-interval scheduling toward dynamic memory decay modeling calibrated to individual learner forgetting curves. Higher education publishers and corporate training departments are adopting these systems at accelerating velocity. The technology is migrating from supplementary vocabulary tools into core curriculum infrastructure, compressing traditional semester-based language course structures into self-paced proficiency tracks.
EU AI Act transparency obligations now require algorithmic tutoring systems deployed across member states to disclose training data provenance and decision logic to end-users. This regulatory layer adds compliance overhead but creates competitive differentiation for platforms with auditable personalization engines. K-12 procurement channels in Germany and France are prioritizing vendors with documented conformity assessments over opaque black-box alternatives.
Consumption patterns among mass-market learners have fragmented into micro-session behaviors driven by mobile push-notification triggers rather than scheduled study blocks. Platform engagement metrics now prioritize daily active user retention over course completion rates as the dominant health indicator. This behavioral shift is most visible in East Asian markets where commute-time learning applications command disproportionate screen time share during morning and evening transit hours.
Language Learning Software Market Segmentation
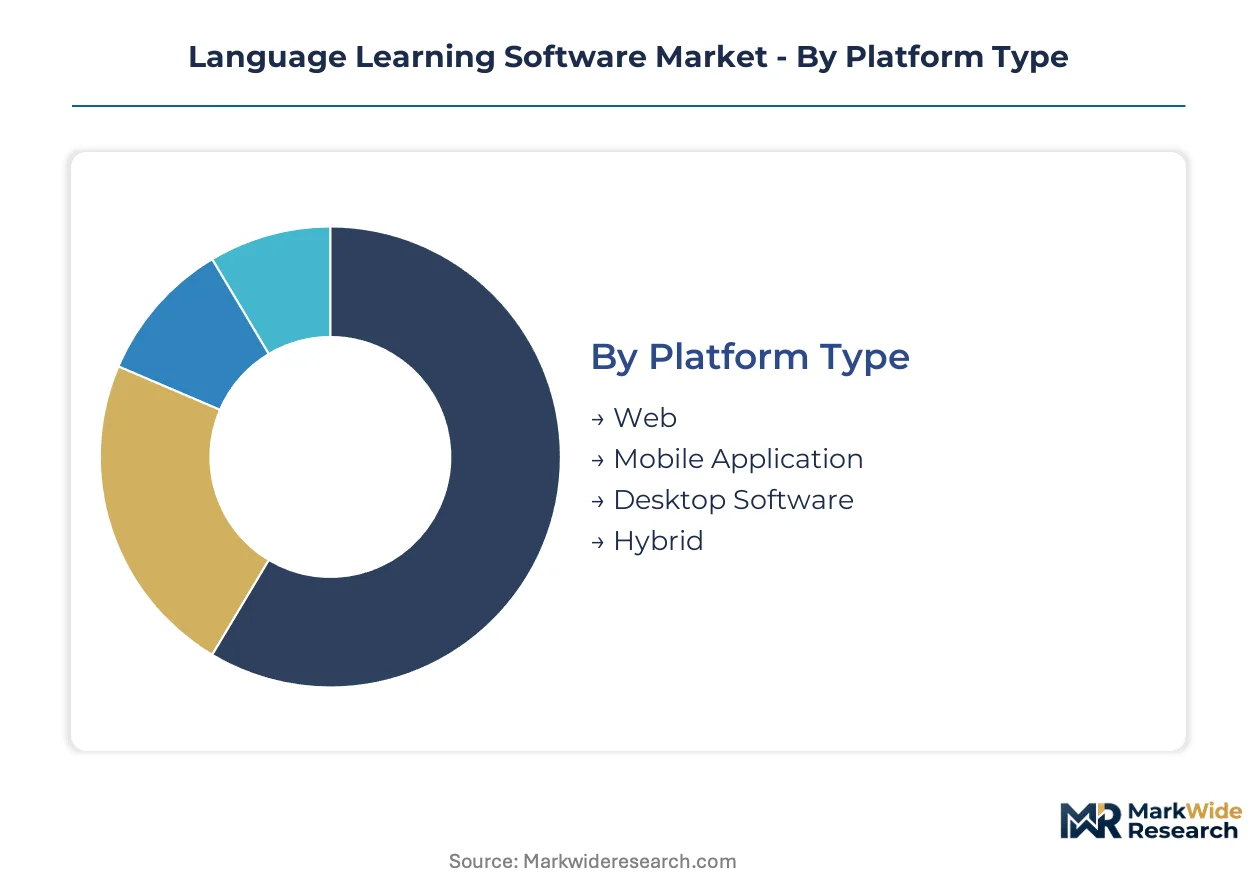
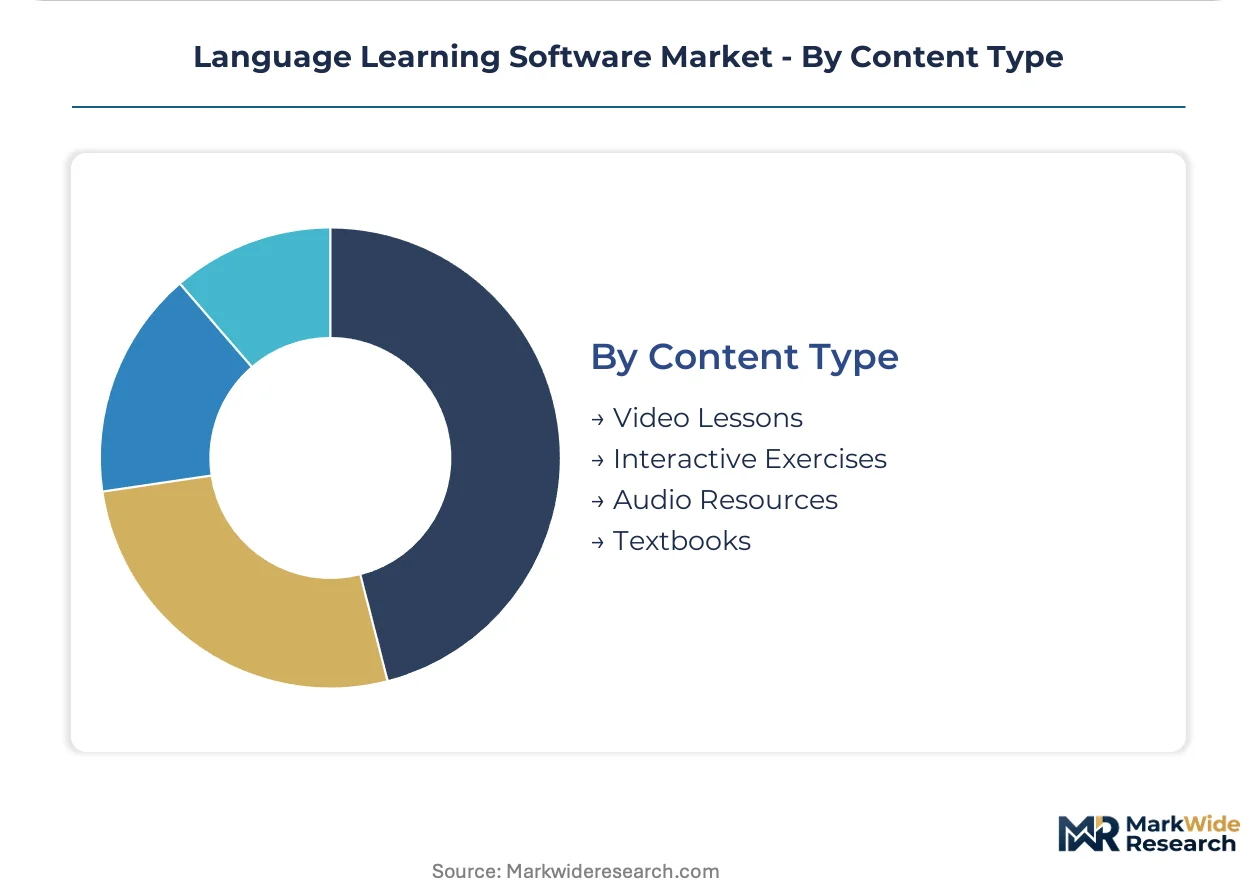
Segmentation in language learning software reveals how delivery architecture, pedagogical approach, and user context shape procurement decisions across consumer and institutional channels. Platform vendors must align feature development with distinct behavioral patterns that vary sharply between mobile-first commuters and enterprise training administrators.
Platform Type:
Mature deployment models coexist with emerging hybrid architectures as organizations balance accessibility against data sovereignty requirements.
- Mobile Application:Native iOS and Android clients dominate daily active user metrics through push-notification habit formation and offline content caching. Commute-time learners in East Asian urban corridors sustain the highest session frequency, though screen size constraints limit complex grammatical instruction depth.
- Web:Browser-based delivery anchors institutional procurement for K-12 and higher education due to zero-install deployment and centralized administrative dashboards. United States school districts prioritize web platforms for COPPA compliance management across shared device environments.
- Desktop Software:Legacy on-premise installations persist in defense and intelligence agency environments where air-gapped networks preclude cloud connectivity. These deployments require physical media distribution and local biometric data processing.
- Hybrid:Synchronized web-mobile-desktop experiences are gaining traction among corporate training departments seeking seamless progress tracking across employee device ecosystems.
Mobile Application retains volume leadership; Hybrid holds the steepest expansion curve.
Learning Methodology:
Pedagogical differentiation clusters around engagement mechanics versus outcome accountability, with cost tier determining access to human instructor oversight.
- Gamification:Badge systems, streak counters, and competitive leaderboards drive retention among younger demographics and casual learners. Spaced repetition algorithms integrate with reward loops to sustain daily active usage without external motivation structures.
- Immersion:Virtual reality environments and conversational AI tutors simulate target-language contexts for professionals requiring rapid deployment readiness. Defense contractors in the United States specify immersion modules for pre-deployment linguistic preparation.
- Traditional Education:Structured curriculum sequencing with formal assessment gates aligns with university credit-bearing programs and government certification requirements in Germany and France.
- Self-Study:Unguided resource libraries serve price-sensitive tourists and hobbyist learners with irregular study schedules.
Gamification commands the largest user base; Immersion is climbing the fastest as enterprise budgets expand.
Target User:
Customer type segmentation maps directly to lifetime value divergence, with bulk licensing arrangements outperforming individual subscription economics.
- Corporate:Employer-sponsored training programs generate the highest per-seat revenue through customized curriculum alignment with industry-specific terminology. Multinational logistics and hospitality employers mandate cross-border communication skills at scale.
- Students:K-12 and university procurement channels prioritize administrative analytics and learning management system integration over consumer-grade engagement features.
- Professionals:Individual subscribers seeking career advancement accept premium pricing for certification-aligned content and live tutoring access.
- Tourists:Short-term travelers drive seasonal demand spikes for phrase-focused modules with offline functionality.
Corporate segments dominate revenue concentration; Professionals show the most resilient subscription retention.
Content Type:
Content investment priorities reflect a margin structure favoring scalable digital production over perishable live instruction.
- Video Lessons:Native-speaker dialogues with contextual cultural annotations anchor premium subscription tiers. Production costs concentrate in subtitle localization and dialect variation coverage.
- Interactive Exercises:Algorithmic personalization engines generate adaptive question sequences calibrated to individual proficiency gaps. GDPR-compliant voice biometric processing enables speech recognition feedback in EU member states.
- Audio Resources:Podcast-style content serves commute-time learners with passive listening optimization for pronunciation acquisition.
- Textbooks:Digital workbook formats persist in formal education channels requiring printable assessment materials and offline study options.
Video Lessons retain production budget leadership; Interactive Exercises are gaining share fastest through AI personalization integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Language learning software demand concentrates in net-importing education economies where foreign language acquisition drives workforce competitiveness. Export-oriented service sectors in emerging markets generate parallel procurement for cross-border communication tools. Government digitization mandates and defense procurement programs create divergent regulatory environments across major national markets.
United States
Defense and intelligence agencies sustain multi-year contracts for mission-critical language proficiency platforms, creating stable demand anchors for institutional-grade vendors. COPPA compliance requirements shape product architecture for K-12 segments, forcing separate codebases for under-thirteen learners. Silicon Valley clusters concentrate AI-native curriculum development while Virginia data centers host cloud infrastructure for federal contracts.
Germany
EU AI Act transparency obligations require algorithmic tutoring systems to disclose training data provenance and decision logic to end-users. K-12 procurement channels in Bavaria and North Rhine-Westphalia prioritize vendors with documented conformity assessments over opaque alternatives. Berlin-Brandenburg hosts regulatory technology consultancies specializing in GDPR-compliant biometric speech processing for education ministries.
India
National Education Policy mandates multilingual digital learning infrastructure, creating procurement windows for adaptive platforms in state school systems. Central Board of Secondary Education guidelines encourage software localization across 22 scheduled languages. Karnataka and Telangana clusters concentrate engineering talent for speech recognition engine development serving domestic and export markets.
China
MIIT standards govern educational software data localization requirements, constraining cross-border cloud deployment architectures. Dual carbon goals accelerate energy-efficient data center construction for online learning platforms in Yangtze River Delta hubs. Beijing-Tianjin-Hebei corridor concentrates state-affiliated language training contracts for diplomatic and trade negotiation preparedness.
United Kingdom
Office for Students quality standards shape university procurement for credit-bearing language programs with formal assessment gates. London-Southeast corridor concentrates corporate training demand from financial services and legal sectors requiring certification-aligned content. EdTech export initiatives promote domestic platform licensing to Commonwealth education systems.
Language Learning Software Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying speech recognition engines and adaptive algorithm modules. The vendor base organizes around three strategic archetypes: freemium mass-market operators, premium subscription specialists, and institutional licensing incumbents. Competitive dynamics center on user retention economics and contract duration rather than raw subscriber acquisition. M&A activity targets AI personalization capabilities and regional content libraries.
Within the freemium archetype, Duolingo Inc exemplifies low customer acquisition cost mechanics through gamified engagement loops. Babbel occupies a position in premium subscription tiers targeting professionals with structured curriculum depth. Rosetta Stone anchors institutional channel competition where enterprise licensing and government contracts yield extended contract durations.
| Leading Market Players |
|---|
| Duolingo Inc |
| Babbel |
| Rosetta Stone |
| Busuu |
| Memrise |
| HelloTalk |
| Lingodeer |
| Mango Languages |
| Berlitz Corporation |
| Others |
Supply Flow & Price Mechanics
GPU foundry capacity in Taiwan and South Korea anchors cost structures for AI-native curriculum generation, concentrating margin pools in platforms with captive speech recognition development rather than third-party API licensing.
Pricing Analysis
Corporate training departments anchor subscription pricing through multi-year enterprise licensing with customized curriculum alignment. Pricing stratifies across premium certification-aligned tiers, mid-market professional subscriptions, and freemium mass-market entry points. Cost compression in consumer segments intensifies as GPU compute expenses fluctuate with semiconductor foundry constraints. Tourist and casual learner segments exhibit highest price sensitivity, while defense procurement channels demonstrate lowest elasticity due to mission-critical requirements.
Supply Chain Analysis
Cloud infrastructure concentration in Virginia, Frankfurt, and Singapore creates single-point-of-failure exposure for platform uptime guarantees. Speech recognition engine development draws from engineering talent clusters in Karnataka and Telangana, while content production feeds from native-speaker recording studios across Berlin, London, and Beijing. Tariff exposure between United States and Chinese data center equipment suppliers constrains hardware procurement flexibility. Distribution runs through direct-to-consumer app stores, institutional procurement portals, and emerging employer-sponsored learning benefits platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generative AI integration is compressing curriculum development cycles while forcing continuous compliance re-certification under EU AI Act transparency mandates, creating a high-growth disruption window for adaptive platforms.
For Market Incumbents: Harden data governance frameworks around biometric speech processing to preempt GDPR enforcement actions in German and French education ministries. Consolidate AI personalization capabilities through targeted acquisition of adaptive algorithm specialists, defending against margin erosion from GPU compute cost volatility. For New Entrants and Emerging Players: Blue-collar workforce segments in logistics and hospitality verticals offer underpenetrated procurement channels with lower competitive density than premium professional tiers. India's state school systems under National Education Policy multilingual mandates present accessible institutional entry points. Employer-sponsored learning benefits platforms provide bypass distribution for corporate contract acquisition without direct-to-consumer marketing spend. For Investors and Strategic Acquirers: Capital is best deployed toward speech recognition engine specialists with documented GDPR conformity assessments and existing education ministry relationships. Long-term viability favors platforms with auditable personalization architectures over opaque black-box alternatives. Watch for EU AI Act enforcement patterns in Bavaria and North Rhine-Westphalia as inflection indicators for regulatory compliance premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Generative AI Curriculum Integration | Compresses content development timelines while triggering EU AI Act transparency compliance investments. |
| GDPR-Conformant Biometric Processing | Unlocks procurement eligibility in German and French K-12 channels prioritizing auditable systems. |
| Enterprise LMS API Development | Reduces implementation friction for corporate training departments with bespoke middleware requirements. |
| India State School Localization | Captures procurement windows under National Education Policy multilingual infrastructure mandates. |
| Employer Benefits Platform Partnership | Bypasses direct-to-consumer acquisition costs through emerging corporate distribution intermediaries. |
Methodological Framework
A spread of perspectives from platform engineering directors, education ministry procurement officers, corporate training administrators, and speech recognition specialists converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC filings, hyperscaler capex disclosures, App Annie engagement metrics, and EU regulatory transparency databases. Bottom-up segment sizing and top-down macroeconomic triangulation anchored volume and value estimates.
Demand-supply balance modeling across the projection horizon integrated deployment architecture, pedagogical methodology, target user segment, and content type dimensions with regional adoption pattern differentiation. CAGRs derived from fitted growth curves applied to segment-specific baseline penetrations. AI personalization integration velocity and defense procurement contract renewal rates served as key forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native entrants or hyperscaler platform bundling would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Language Learning and Training
Language Learning Games Market
Language Learning and Training
English Learning for Children Market
Language Learning and Training
Global Digital English Language Learning Market
Language Learning and Training
Bilingual Education for Children Market
Language Learning and Training
Cloud Based Language Learning Market
Language Learning and Training
Global Language Service Market
Language Learning and Training
Vocational English Course Counselling Solution Market
Language Learning and Training
English Learning App Market
Language Learning and Training
Digital English Learning Market
Language Learning and Training
Online Language Learning Market