
 Saudi Arabia E-Learning Market | 2026-2036
Saudi Arabia E-Learning Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia E-Learning Market Intelligence
Subscription-based access to software-defined learning paths is decoupling content ownership from institutional procurement in Saudi Arabia. Bakkah Learning leverages its specialized corporate training modules to anchor enterprise relationships across the Kingdom. Oreed differentiates through localized Arabic-language courseware that dominates public-sector tenders. Noon competes by extending its consumer e-commerce brand into affordable individual learner subscriptions.
E-Learning in Saudi Arabia denotes digitally delivered educational content accessed through internet-connected devices, typically employing SCORM-compliant interoperability standards and adaptive bitrate streaming to accommodate variable bandwidth conditions across urban and remote areas. Its primary purpose centers on scalable workforce reskilling and K-12 supplementary instruction aligned with national human-capital objectives. Learning Management Systems represent the most mature segment with established margin pools from enterprise renewals, while AI-Powered Learning captures the fastest structural growth as Saudi universities integrate automated tutoring engines. Mobile Learning occupies a specialized niche serving dispersed rural populations and commuting professionals in Dammam and Mecca corridors.
SFDA oversight of healthcare continuing education credits and MOE accreditation requirements for K-12 supplementary platforms shape product standards and market access thresholds for domestic providers. The CITC regulates data localization mandates that constrain foreign cloud-hosted solutions while creating procurement advantages for Saudi-domiciled infrastructure. Stakeholders must monitor how forthcoming personal data protection frameworks alter cross-border content licensing terms and learner analytics practices.
Market Dynamics
Saudi Vision 2030 workforce localization mandates are restructuring employer obligations across the Kingdom, forcing enterprises to replace expatriate knowledge with digitally upskilled Saudi nationals and accelerating procurement of scalable training infrastructure.
Growth Catalysts
- SFDA Continuing Education Mandates:Healthcare practitioners must complete accredited digital modules for license renewal, creating recurring demand for specialized clinical content platforms.
- Corporate Workforce Localization:Nitaqat program quotas compel private-sector employers to invest in Arabic-language reskilling programs for Saudi national hires.
- Cloud Infrastructure Deployment:CITC data localization requirements favor Saudi-domiciled LMS hosting, steering procurement toward domestic cloud providers.
Market Restraints
- Bandwidth Asymmetry:Variable connectivity quality between Riyadh-Jeddah corridors and remote governorates limits synchronous video delivery to dispersed learners.
- Content Localization Costs:SCORM-compliant Arabic courseware development requires specialized instructional design talent that commands premium compensation.
- Foreign Platform Restrictions:CITC cross-border data transfer constraints block international SaaS providers from competing for government tenders.
Strategic Opportunities
- AI-Powered Adaptive Tutoring:Saudi universities are piloting automated assessment engines that personalize STEM remediation at scale.
- Rural Mobile Penetration:Commuting professionals in Dammam and Mecca corridors represent underserved demand for offline-synced microlearning modules.
- Public-Sector Digitalization:MOE accreditation pathways for supplementary K-12 platforms open procurement channels for curriculum-aligned providers.
Industry Challenges
- Interoperability Fragmentation:Legacy institutional systems resist seamless LTI 1.3 integration with modern cloud LMS architectures.
- Credential Recognition Delays:MOE and SFDA accreditation timelines stretch 12-18 months, freezing product launches for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia E-Learning Market |
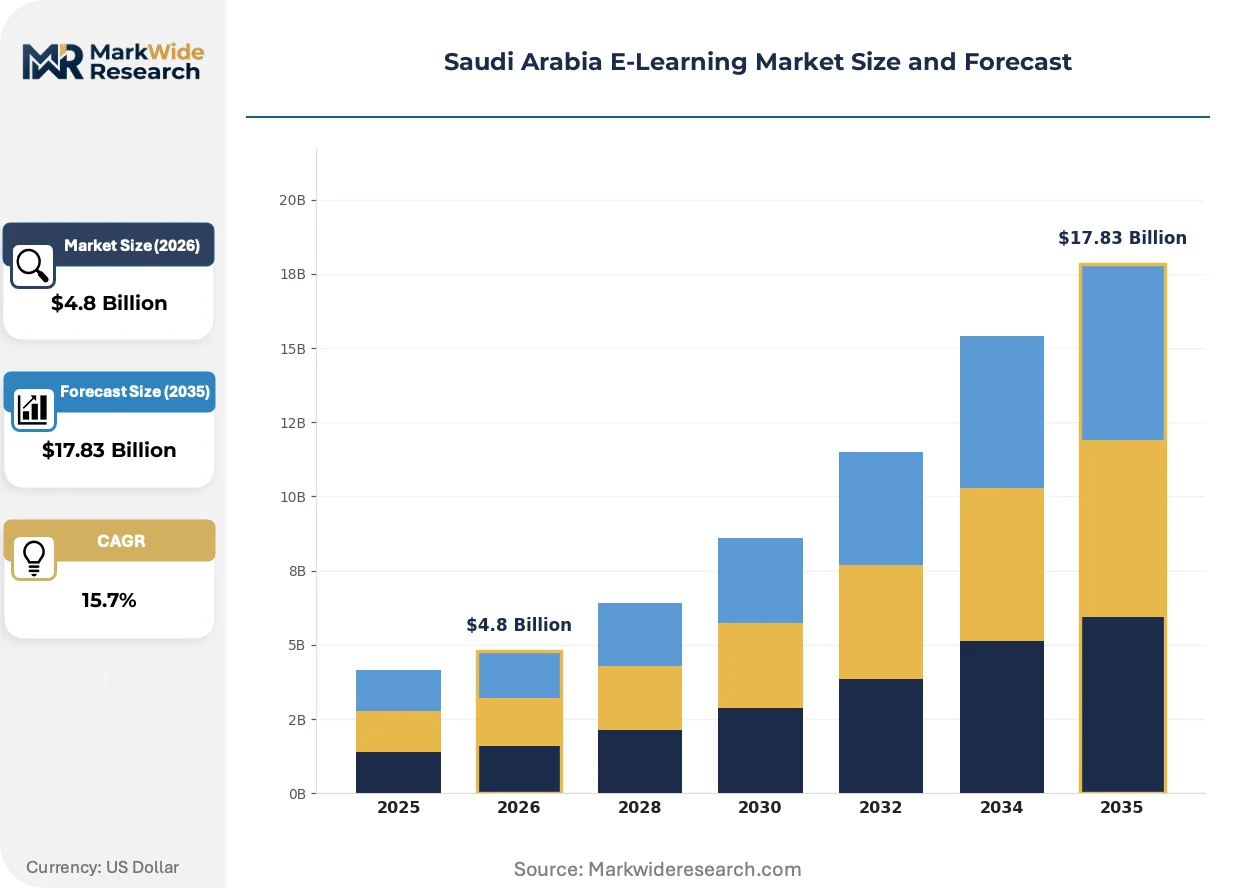
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $17.83 Billion |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Courseware, Learning Management Systems, Virtual Classrooms, Assessment Tools Delivery Mode: Self-Paced, Instructor-Led, Blended Learning, Mobile Learning End User: Academic Institutions, Corporate Sector, Government, Individual Learners Technology: AI-Powered Learning, Augmented Reality, Virtual Reality, Cloud Computing |
| Companies Covered | Rwaq, Bakkah Learning, Oreed, Blue Ocean Academy, Corpoladder, Disprz, EduNova, Nokhbah Academy, Noon, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia E-Learning Market Strategic Shifts & Innovations
Generative AI is compressing content production cycles while regulatory pressure on data sovereignty reshapes vendor selection criteria. Procurement patterns are tilting toward subscription access over perpetual licensing.
Adaptive learning algorithms are expanding into corporate compliance training by dynamically adjusting module difficulty based on real-time assessment performance. Major employers in Riyadh's financial district are piloting these systems for anti-money laundering certification. The technology is expanding into scenarios previously served by instructor-led workshops, compressing per-learner delivery costs.
CITC data localization enforcement is compelling foreign platform operators to establish Saudi-based server infrastructure or forfeit public-sector contracts. This regulatory shift advantages domestic cloud providers with existing Kingdom presence. Healthcare and education segments are responding by inserting data residency clauses into all RFP specifications.
Enterprise buyers are consolidating vendor relationships around integrated talent management suites that embed learning analytics within performance review workflows. Standalone LMS contracts are losing share to bundled HCM platforms. This pattern is most visible among conglomerates executing Vision 2030 workforce transformation programs.
Saudi Arabia E-Learning Market Segmentation
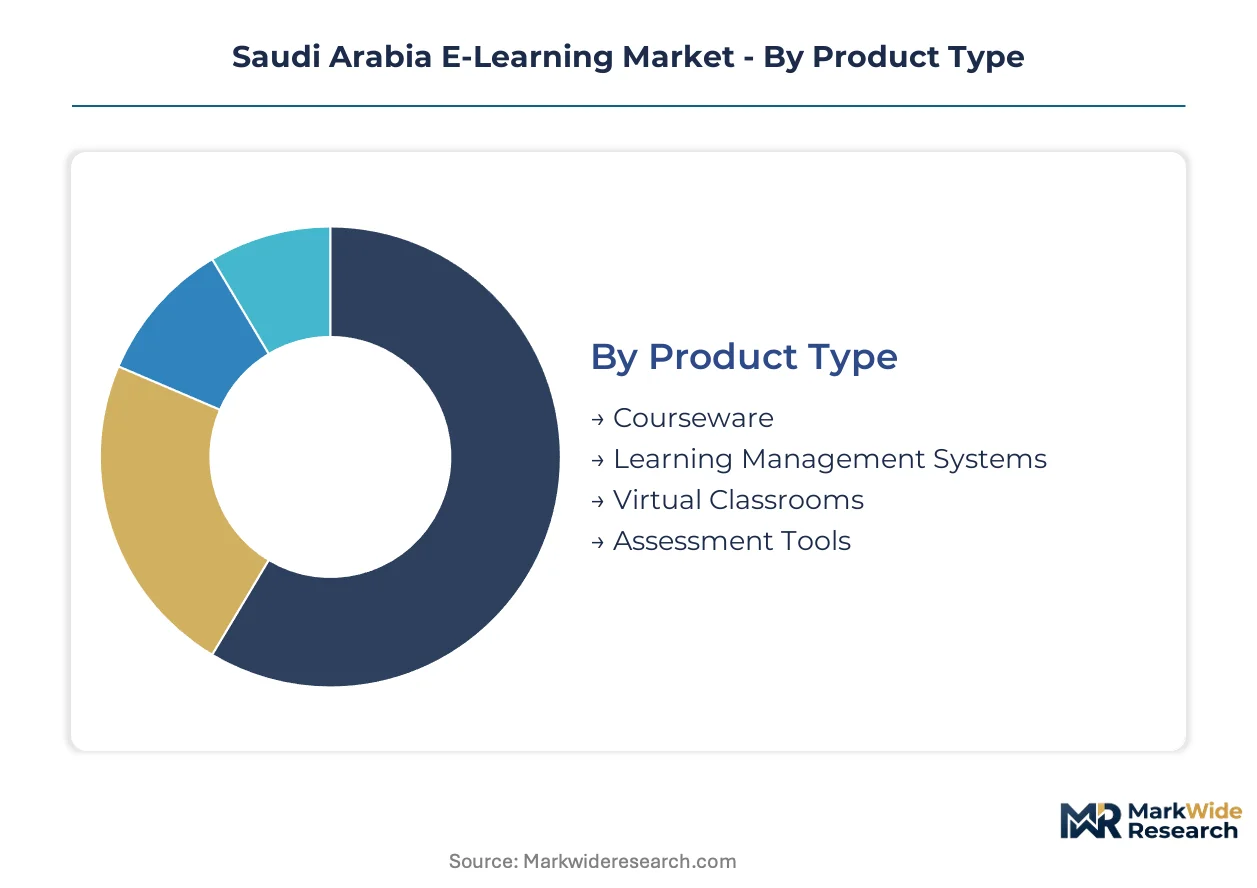
Saudi Arabia's e-learning market segments reflect divergent procurement priorities across enterprise, government, and consumer channels. Understanding these divides clarifies where infrastructure investments concentrate versus where content licensing dominates revenue capture.
Product Type:
Volume concentrates in standardized platforms, while premium margins flow to specialized content and assessment layers.
- Learning Management Systems:Cloud-hosted platforms with SCORM and LTI 1.3 interoperability anchor enterprise procurement in Riyadh and Jeddah. CITC data localization mandates steer contracts toward Saudi-domiciled hosting infrastructure, entrenching renewal revenue for established providers.
- Courseware:Arabic-language instructional modules command development premiums due to scarce instructional design talent, yet dominate public-sector tenders requiring MOE accreditation alignment. Demand clusters where Nitaqat workforce localization mandates force rapid Saudi national upskilling.
- Virtual Classrooms:Synchronous video delivery platforms serving remote governorates face bandwidth asymmetry constraints between urban corridors and dispersed learners.
- Assessment Tools:Automated proctoring and competency validation engines integrated with SFDA continuing education credit tracking.
Today's leader: Learning Management Systems. Tomorrow's challenger: Courseware.
Delivery Mode:
Enterprise buyers prioritize scheduling flexibility, while rural penetration demands offline resilience.
- Self-Paced:Asynchronous module access decouples learning from instructor availability, absorbing the bulk of corporate compliance training volume across Saudi conglomerates executing Vision 2030 workforce transformation.
- Mobile Learning:Offline-synced microlearning modules capture commuting professionals in Dammam and Mecca corridors where connectivity fluctuates. This segment climbs fastest as smartphone penetration extends into rural governorates.
- Blended Learning:Hybrid formats preserving instructor touchpoints for high-stakes certification programs in healthcare and finance.
- Instructor-Led:Synchronous virtual delivery constrained to bandwidth-stable urban centers and premium executive education.
Self-Paced commands current procurement volumes. Mobile Learning shows the steepest expansion trajectory.
End User:
Corporate mandates drive infrastructure spending, while individual subscriptions scale through consumer platform brand extension.
- Corporate Sector:Nitaqat program quotas compel private-sector employers to fund Arabic-language reskilling platforms, making this the revenue anchor for LMS vendors and custom courseware developers.
- Government:MOE and SFDA accreditation requirements create procurement gatekeeping that favors domestic providers with established regulatory relationships and localized content libraries.
- Academic Institutions:Saudi universities piloting AI-powered adaptive tutoring engines for STEM remediation at scale.
- Individual Learners:Price-sensitive demand accessed through consumer e-commerce platform extensions and subscription marketplaces.
Corporate Sector anchors platform economics. Government tenders shape vendor survival.
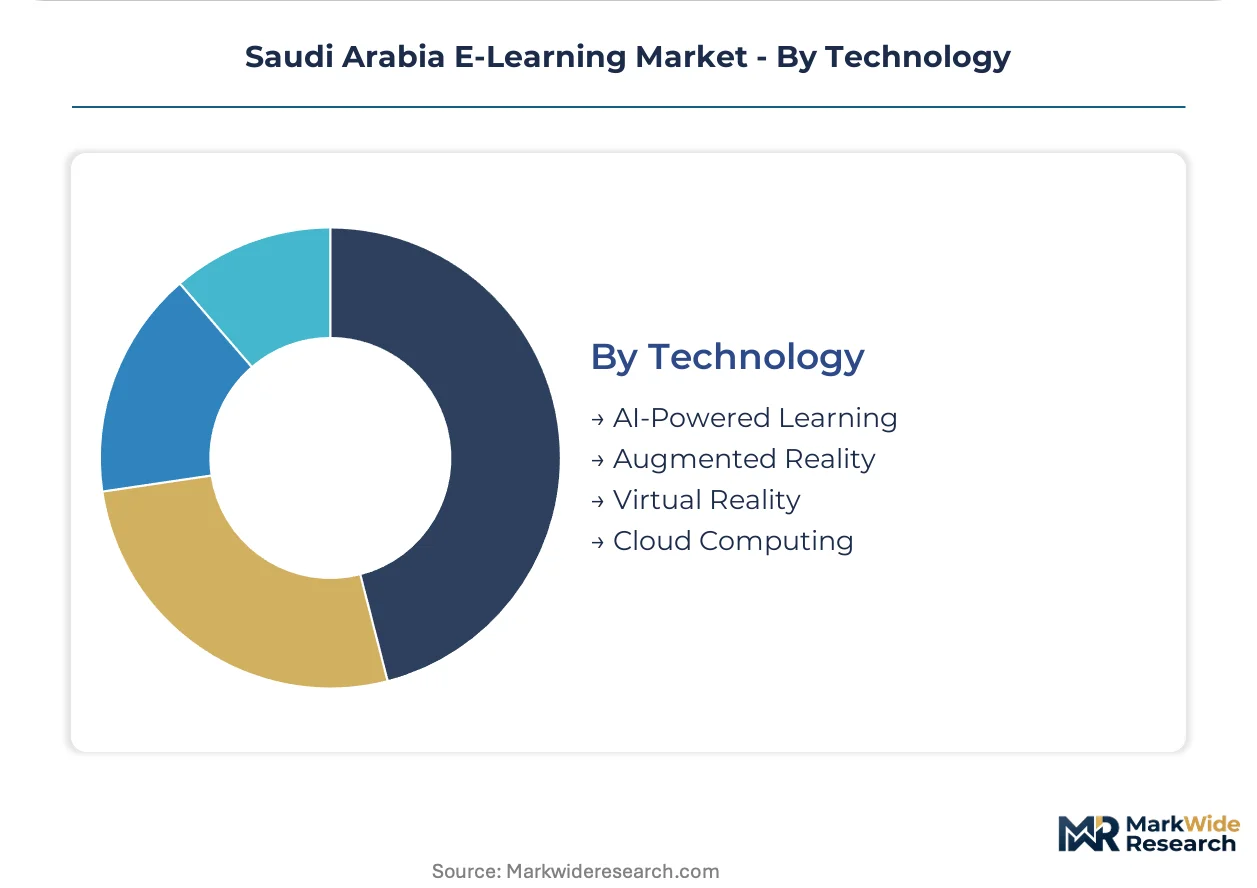
Technology:
Established infrastructure layers fund current operations, while emerging interfaces capture pilot budgets.
- Cloud Computing:Saudi-domiciled server infrastructure mandated by CITC data localization requirements underpins all scalable delivery, creating procurement advantages for domestic cloud providers with Kingdom presence.
- AI-Powered Learning:Automated assessment engines personalizing module difficulty in real-time are expanding from university pilots into corporate compliance scenarios including anti-money laundering certification in Riyadh's financial district.
- Augmented Reality:Spatial overlays for technical training in energy and industrial maintenance applications.
- Virtual Reality:Immersive simulations for high-risk procedural training in healthcare and aviation.
Cloud Computing enables current scale. AI-Powered Learning defines next-generation competitive differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia outpaces UAE in enterprise LMS procurement velocity, while Egypt's public-sector digitization lags both Gulf markets by several years. The Kingdom's regulatory environment creates distinct competitive dynamics across Middle Eastern e-learning corridors.
Saudi Arabia
Riyadh and Jeddah concentrate cloud-hosted LMS demand from financial services and healthcare employers. SFDA continuing education mandates for medical practitioners create recurring revenue pools for accredited platform providers. The Eastern Province's petrochemical employers deploy Arabic-language compliance modules under Nitaqat workforce localization quotas.
United Arab Emirates
Dubai's free-zone headquarters economy generates cross-border corporate training demand serving regional operations. MOHAP healthcare credentialing requirements mirror Saudi SFDA frameworks but with faster accreditation timelines. Abu Dhabi's sovereign wealth-backed education initiatives attract international platform operators seeking Gulf expansion beachheads.
Egypt
Cairo's university density supports blended learning pilots bridging campus instruction with digital supplementation. The country's national pharmaceutical regulator mandates periodic professional development without specifying delivery modalities. Alexandria's medical faculty clusters represent underserved demand for Arabic-language clinical continuing education platforms.
Jordan
Amman's tech outsourcing sector drives English-language technical skills training procurement from BPO employers. The country's central bank oversees fintech certification frameworks that increasingly specify digital delivery options. Zarqa's industrial zone employers experiment with mobile microlearning for shift-worker compliance training.
Kuwait
Kuwait City's government ministries generate tender volume for MOE-aligned K-12 supplementary platforms. The country's civil service commission mandates digital literacy modules for public-sector promotion eligibility. Hawally's private school clusters represent concentrated demand for LMS infrastructure with Arabic interface localization.
Saudi Arabia E-Learning Market Key Industry Players
Top-tier vendors anchor enterprise LMS renewals in Riyadh and Jeddah, while mid-tier courseware specialists compete for MOE accreditation pathways. The vendor base stratifies across three archetypes: domestic cloud infrastructure operators, Arabic content localization specialists, and consumer platform brand extenders. Consolidation pressure intensifies as enterprise buyers favor integrated talent management suites over standalone LMS contracts. Strategic partnerships between domestic hosting providers and international software licensors accelerate under CITC data localization enforcement.
Among domestic specialists, Bakkah Learning occupies a position within the corporate training archetype, while Oreed exemplifies the public-sector courseware localization tier. Noon represents the consumer brand extension vector into individual learner subscriptions. These three anchors illustrate how vendor positioning maps to procurement channel segmentation across Saudi Vision 2030 workforce transformation programs.
| Leading Market Players |
|---|
| Rwaq |
| Bakkah Learning |
| Oreed |
| Blue Ocean Academy |
| Corpoladder |
| Disprz |
| EduNova |
| Nokhbah Academy |
| Noon |
| Others |
Cost & Logistics Intelligence
Backward integration into Saudi-domiciled cloud infrastructure anchors both supply security and pricing power for domestic Learning Management System providers, as CITC data localization mandates compel foreign operators to establish Kingdom-based server presence or forfeit public-sector tenders.
Pricing Analysis
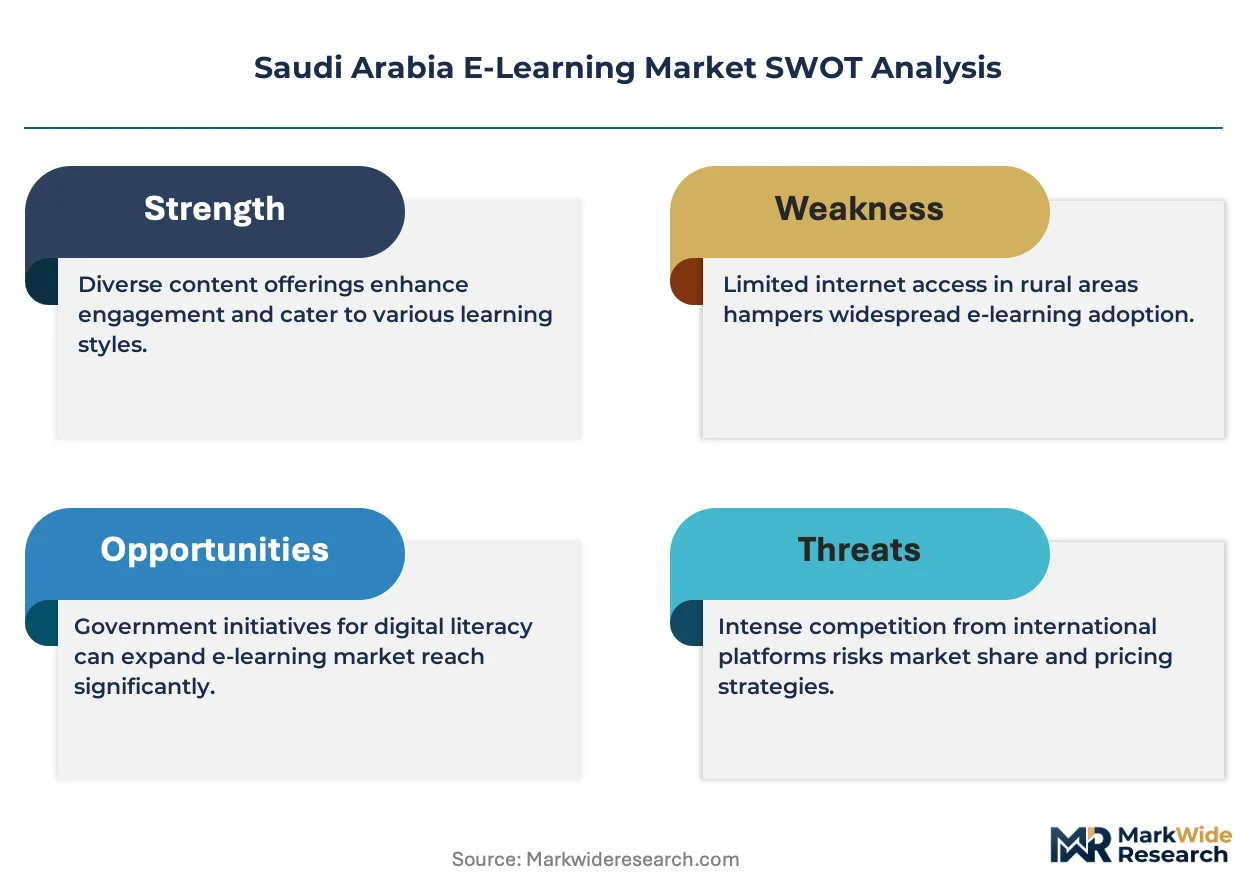
Capacity additions in Riyadh and Jeddah are reshaping price floors for cloud-hosted LMS subscriptions as domestic providers expand server infrastructure. Three-tier pricing structure across premium enterprise, standard mid-market, and economy individual learner levels stratifies by customization depth and SFDA or MOE accreditation status. Cost compression in the standard tier is intensifying because international SaaS vendors must absorb data localization compliance overhead. Government tenders show least price sensitivity due to regulatory gatekeeping, while individual learners accessed through consumer platform extensions demonstrate highest elasticity.
Supply Chain Analysis
Freight costs for hardware server imports from Taiwan, South Korea, and the United States feed into capital expenditure structures for Saudi cloud infrastructure buildouts. Content production draws from scarce Arabic instructional design talent concentrated in Riyadh and Cairo, plus licensed SCORM authoring tools from European and North American software houses. Single-source vulnerability sits with specialized clinical content libraries for SFDA-accredited healthcare continuing education. Distribution runs through direct enterprise sales teams for large employers and channel partnerships with systems integrators for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Saudi e-learning rests on automation compressing Arabic content production cycles and enterprise buyers consolidating around integrated talent management suites that command premium pricing over standalone LMS contracts.
For Market Incumbents: Anchor renewal revenue through embedding learning analytics within HR performance review workflows, as enterprise buyers abandon standalone LMS contracts for bundled HCM platforms. Deepen regulatory relationships with SFDA and MOE accreditation teams to extend 12-18 month approval timelines into competitive moats. Counter emerging AI-powered adaptive tutoring entrants by acquiring automated assessment engine capabilities before university pilots scale into corporate compliance demand. For New Entrants and Emerging Players: CITC data localization enforcement in Saudi Arabia opens a window for domestic cloud infrastructure operators to capture public-sector LMS tenders previously served by foreign SaaS providers. Target rural mobile learning penetration in Dammam and Mecca corridors where offline-synced microlearning modules address bandwidth asymmetry constraints underserved by urban-focused incumbents. Pursue white-label Arabic courseware development partnerships with established providers lacking instructional design capacity. For Investors and Strategic Acquirers: Consolidation pressure builds where enterprise buyers demand integrated talent management suites that combine learning, performance, and succession planning in single-vendor relationships. Long-term viability favors vendors with established MOE and SFDA accreditation pathways and captive Arabic content libraries. Watch for inflection when AI-powered adaptive tutoring pilots at Saudi universities receive scale funding and expand into corporate compliance training procurement.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Accreditation Investment | Unlocks recurring revenue from healthcare practitioner license renewal mandates. |
| AI-Powered Tutoring Platform Launch | Captures STEM remediation demand as Saudi universities automate personalized instruction. |
| Domestic Cloud Infrastructure Buildout | Secures public-sector procurement eligibility under CITC data localization requirements. |
| Arabic Courseware Library Acquisition | Accelerates MOE alignment and Nitaqat workforce localization content delivery. |
| Mobile Microlearning Partnership | Penetrates Dammam and Mecca commuting corridors with offline-synced modules. |
Research Approach
Multiple input streams — structured interviews with LMS procurement officers at Saudi conglomerates, regulatory affairs leads at SFDA and MOE, channel partners distributing cloud infrastructure, and instructional design specialists — were reconciled against secondary validation from CITC policy disclosures, SFDA continuing education credit databases, hyperscaler Saudi data center announcements, and enterprise SaaS contract filings. Bottom-up segment sizing across product type, delivery mode, end user, and technology dimensions was triangulated with top-down market boundary checks.
Data-stream reconciliation anchored analytical framework construction across the analysis window, modeling deployment model, organization size, vertical sector, and regional adoption pattern as core segmentation dimensions. CAGRs were derived from trend extrapolation of enterprise LMS renewal rates, AI-powered learning pilot conversion timelines, and mobile learning smartphone penetration curves. Forecast inputs incorporated Nitaqat workforce localization quota enforcement schedules and MOE supplementary platform accreditation pipeline visibility.
Revisions become necessary when CITC data localization enforcement intensity shifts, SFDA continuing education credit requirements expand to new practitioner categories, or generative AI content production disruption accelerates beyond current pilot scopes. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Distance Learning and Online Education
Global Self-Paced E-Learning Market
Distance Learning and Online Education
Digital Marketing Courses Market
Distance Learning and Online Education
Europe Digital Education Market
Distance Learning and Online Education
Digital Course Recorder Market
Distance Learning and Online Education
E-Learning Market
Distance Learning and Online Education
United States E-Learning Market
Distance Learning and Online Education
Remote Learning Technology Spending Market
Distance Learning and Online Education
Online K-12 Education Market
Distance Learning and Online Education
Online Tutoring Services Market
Distance Learning and Online Education
Africa E-Learning Market
Distance Learning and Online Education
Europe MOOC Market
Distance Learning and Online Education
Massive Open Online Courses Market
Distance Learning and Online Education
Online Tutoring Market
Distance Learning and Online Education
GCC Massive Open Online Course (MOOC) Market
Distance Learning and Online Education
Global Digital Education Market
Distance Learning and Online Education
Homeschooling Market