
 VPX SBC Market | 2026-2036
VPX SBC Market Size, Share, and Industry Trends Forecast 2026-2036
VPX SBC Market Analytics
The EU Green Deal's embodied carbon tracking requirements for defense supply chains is shifting procurement criteria toward energy-efficient embedded architectures. Curtiss-Wright leverages its long-standing relationships with U.S. prime contractors to sustain program-level design wins. Abaco Systems anchors its position through specialized signal processing modules for electronic warfare applications. Kontron competes aggressively in European telecommunications infrastructure with industrial-temperature VPX variants.
VPX single board computers are ruggedized embedded computing platforms conforming to the VITA 46/48/65 standards, featuring high-speed serial interconnects through backplane fabric and conduction-cooled aluminum chassis designed for shock and vibration tolerance in deployed environments. Their primary purpose is hosting mission-critical processing in military avionics, radar, and communications systems where commercial-grade hardware fails. OpenVPX architectures lead the technology landscape due to interoperability mandates from the U.S. Department of Defense, while VPX3 form factors dominate volume shipments for size-constrained platforms. Custom SBCs command premium margins as defense primes require application-specific I/O configurations and security-hardened firmware that standard products cannot accommodate.
FAA certification requirements for military derivative aircraft and FCC Part 15 emissions standards constrain hardware designs for dual-use aerospace applications. The U.S. Department of Defense's Cybersecurity Maturity Model Certification and EU NIS2 directives are tightening supplier qualification protocols for embedded computing vendors. Stakeholders must monitor how export control revisions under the Wassenaar Arrangement affect cross-border technology transfers for high-performance processing boards.
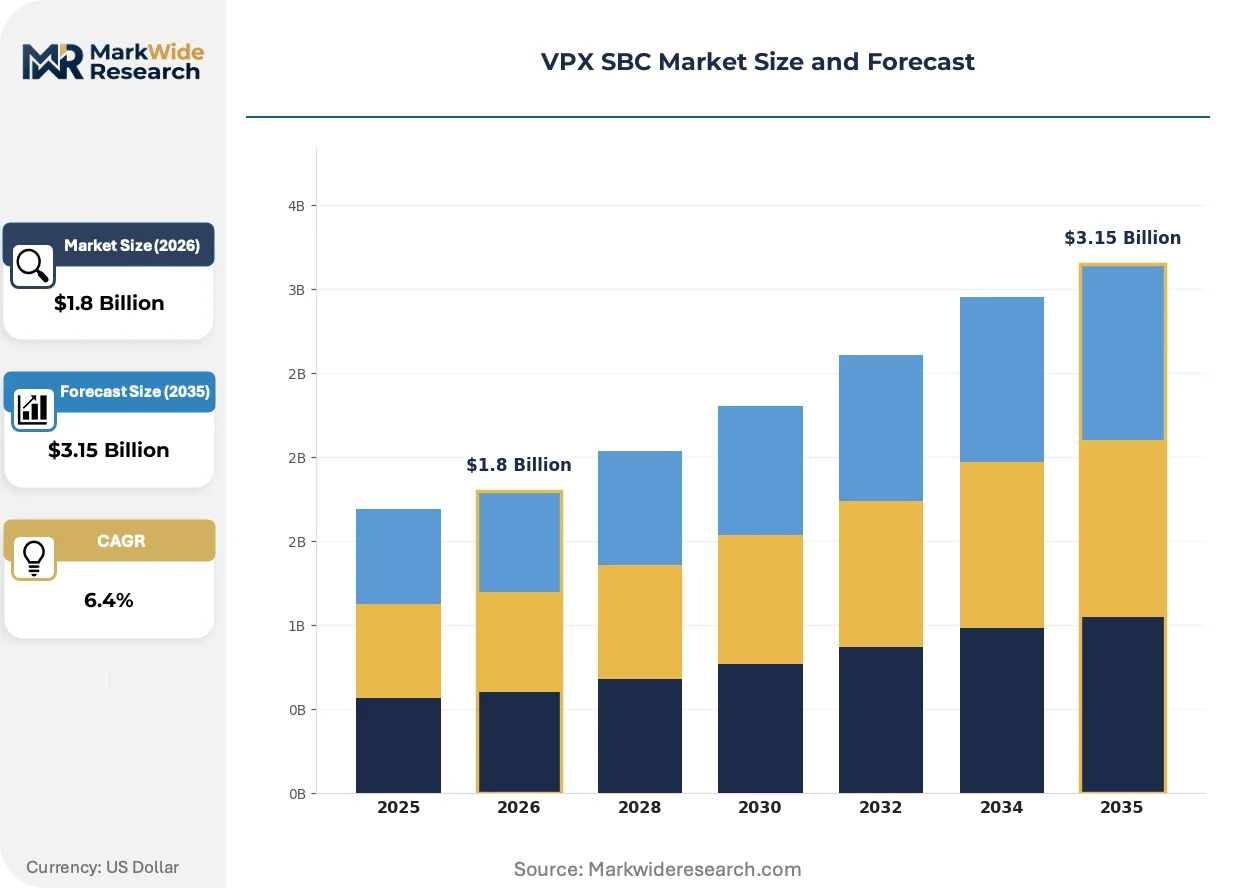
Market Dynamics
The OpenVPX interoperability mandate from the U.S. Department of Defense is forcing prime contractors to abandon proprietary backplane architectures and consolidate supplier relationships around standardized, multi-vendor computing ecosystems.
Growth Catalysts
- CMMC 2.0 certification tiers:The Cybersecurity Maturity Model Certification creates qualified supplier pools that favor established embedded computing vendors with hardened firmware capabilities.
- Electronic warfare modernization:Next-generation radar and signals intelligence platforms require VPX SBCs with specialized FPGA-based signal processing modules.
- Germany's Zeitenwende defense spending:Accelerated procurement timelines for tactical communications systems are expanding ruggedized computing requirements across Bundeswehr platforms.
Market Restraints
- Aluminum conduction-cooling chassis costs:Aerospace-grade 6061-T6 aluminum with precision-machined thermal interfaces faces price volatility from energy-intensive smelting operations.
- FPGA supply concentration:Advanced programmable logic devices for military signal processing depend on a concentrated foundry base in Taiwan.
- ITAR classification friction:U.S. State Department export controls on high-performance processing boards delay cross-border technology transfers to allied defense programs.
Strategic Opportunities
- Japan's counterstrike capability buildup:Standoff missile defense programs require compact VPX3 form factor computers for size-constrained naval and air platforms.
- EU Green Deal embodied carbon tracking:Defense supply chain sustainability mandates favor energy-efficient embedded architectures with documented lifecycle emissions.
- PCIe Gen5 backplane convergence:Integration of CXL memory coherence protocols with existing VPX fabric standards enables heterogeneous computing configurations.
Industry Challenges
- DO-254 avionics hardware certification timelines:FAA design assurance processes for military derivative aircraft extend product qualification cycles by 18-24 months.
- Legacy VMEbus integration complexity:Fielded platforms with decades-old backplane architectures require bridge solutions that increase system weight and power consumption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | VPX SBC Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Board Computers, VPX Modules, Custom SBCs, Development Kits End User: Defense, Aerospace, Telecommunications, Industrial Automation Technology: OpenVPX, VPX3, VPX4, Embedded Processing Application: Signal Processing, Real-Time Computing, Robotics, Data Acquisition |
| Companies Covered | Extreme Engineering Solutions, ADLINK Technology, Curtiss-Wright, Concurrent Technologies, Elma Electronic, Abaco Systems, Kontron, Connect Tech, Mercury Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
VPX SBC Market Evolving Landscape
Ruggedized embedded computing is converging with commercial high-performance interconnect standards, compressing the traditional gap between defense-aerospace reliability requirements and enterprise-class data throughput capabilities.
OpenVPX Slot Profile 14.6 is integrating CXL 2.0 memory expansion capabilities into 3U form factors, enabling cache-coherent shared memory across heterogeneous processing nodes. Naval combat system integrators in the United States and United Kingdom are adopting this configuration for real-time sensor fusion applications. The technology is integrating previously separate compute, storage, and accelerator domains into unified chassis architectures that reduce SWaP-C metrics by eliminating redundant memory subsystems.
The EU NIS2 directive mandates cybersecurity risk management across critical defense supply chains, compelling embedded computing vendors to implement hardware root-of-trust architectures and attestation protocols. Component suppliers must now document secure boot implementations and firmware update mechanisms to maintain qualified supplier status. German and French prime contractors are prioritizing vendors with pre-certified security postures to accelerate platform accreditation timelines.
Defense procurement offices are consolidating supplier bases through multi-year framework agreements that bundle SBC supply with lifecycle support services. Traditional spot-buying through distributor channels is contracting as primes seek sole-source relationships with vendors capable of 15-20 year product sustainment. This concentration is most pronounced in U.S. Navy and Air Force electronic warfare programs, where platform life extensions demand guaranteed component availability through 2040.
VPX SBC Market Segmentation
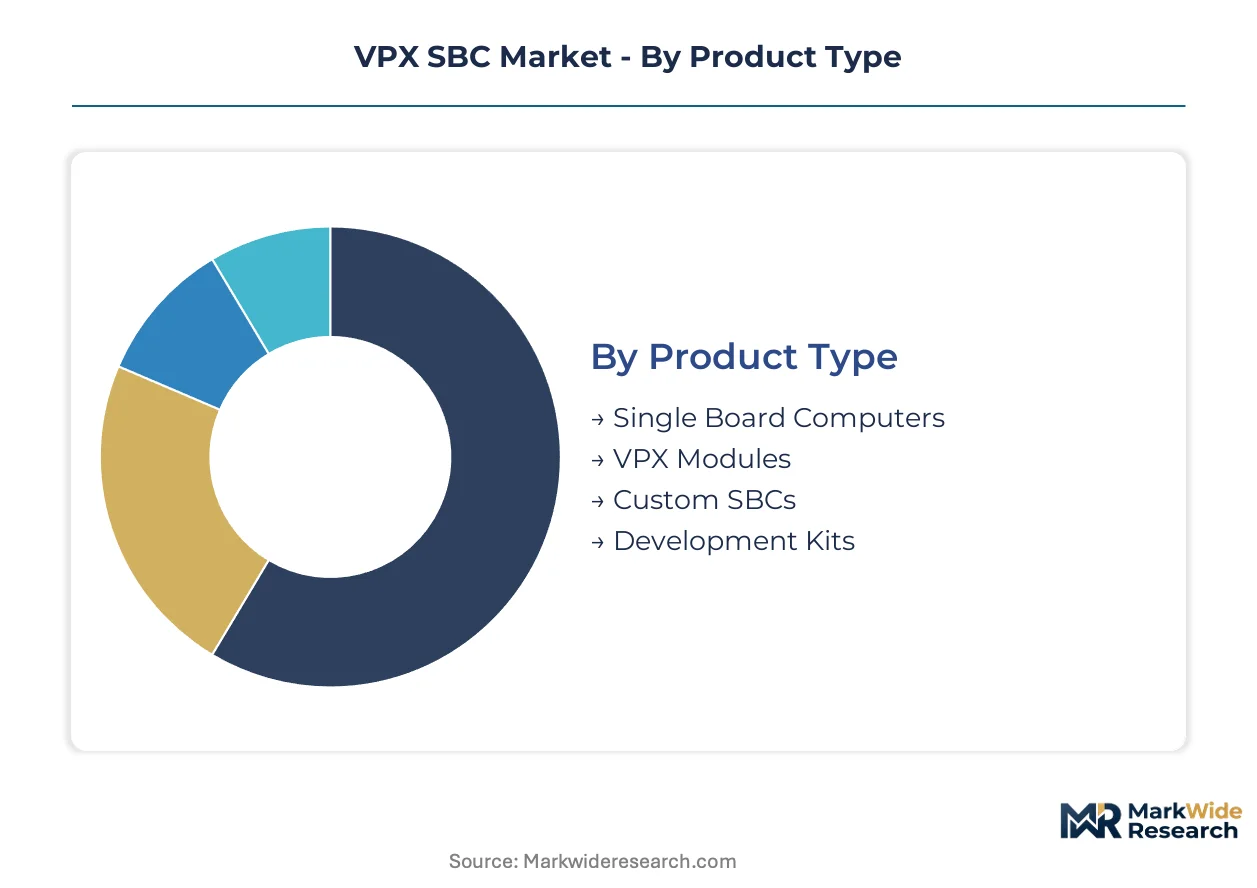
VPX SBC segmentation reveals divergent integration strategies across defense and commercial applications. Standalone computing nodes dominate volume deployments, while deeply embedded configurations command premium positioning in size-constrained platforms.
Product Type:
Integration depth varies sharply across product categories, with standalone boards serving rapid deployment scenarios and custom architectures anchoring long-life military programs.
- Single Board Computers:Standardized 3U and 6U form factors with fixed I/O configurations serve as drop-in replacements for legacy VMEbus systems. Defense primes in the United States favor these for platform retrofits where qualification timelines compress procurement cycles.
- Custom SBCs:Application-specific designs with tailored thermal interfaces and security-hardened firmware accommodate unique payload requirements. Germany's Zeitenwende spending acceleration is driving demand for Bundeswehr-specific configurations with classified processing enclaves.
- VPX Modules:Modular compute, storage, and accelerator cards integrate into unified chassis architectures.
- Development Kits:Reference platforms with debug interfaces and software toolchains accelerate subsystem qualification.
Volume placements concentrate in Single Board Computers; the faster expansion belongs to Custom SBCs.
End User:
Customer type segmentation exposes divergent procurement rhythms, with defense programs operating on decade-long sustainment horizons and commercial adopters cycling hardware on enterprise refresh schedules.
- Defense:Electronic warfare and radar modernization programs require conduction-cooled architectures with guaranteed component availability through 2040. U.S. Navy and Air Force framework agreements are consolidating supplier relationships around vendors with CMMC 2.0 certification.
- Aerospace:Military derivative aircraft and UAV platforms demand DO-254 design assurance and FAA certification compliance. Dual-use applications face FCC Part 15 emissions constraints that extend hardware validation timelines.
- Telecommunications:Industrial-temperature variants serve base station and edge computing infrastructure.
- Industrial Automation:Ruggedized controllers for manufacturing and process industries.
Defense absorbs the highest unit volumes; aerospace programs are climbing the fastest as UAV proliferation accelerates.
Technology:
Technology segmentation tracks the displacement of proprietary backplane architectures by standardized interconnect fabrics with multi-vendor interoperability mandates.
- OpenVPX:The U.S. Department of Defense interoperability mandate forces prime contractors toward standardized slot profiles and defined pin assignments. Slot Profile 14.6 with CXL 2.0 memory expansion is gaining traction in U.S. and U.K. naval combat systems for real-time sensor fusion.
- VPX3:Compact 3U form factors dominate size-constrained platforms where SWaP-C optimization is critical. Japan's counterstrike capability buildup is driving procurement for standoff missile defense applications with severe space limitations.
- VPX4:Larger 6U configurations accommodate higher thermal budgets and expanded I/O.
- Embedded Processing:Heterogeneous compute architectures integrating CPUs, GPUs, and FPGAs on unified boards.
OpenVPX claims the dominant placement share; VPX3 is gaining share fastest as compact platforms multiply across allied defense programs.
Application:
Application segmentation maps processing workloads to architectural requirements, with compute-intensive tasks driving heterogeneous configurations and deterministic control favoring homogeneous designs.
- Signal Processing:FPGA-accelerated architectures with high-speed ADC/DAC interfaces execute radar and electronic warfare algorithms in real time. Taiwan's concentrated foundry base for advanced programmable logic creates supply vulnerability for this segment.
- Real-Time Computing:Deterministic operating systems with hardware-level interrupt prioritization support mission-critical control loops. Naval combat system integrators prioritize these configurations for weapons release authorization chains.
- Robotics:Autonomous platform guidance and manipulation controllers.
- Data Acquisition:High-channel-count sensor interfaces for test and measurement.
Signal Processing leads current deployments; Real-Time Computing shows the steepest expansion trajectory as autonomous systems proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Diego anchors defense electronics procurement for naval combat systems requiring ruggedized embedded computing platforms with extended lifecycle support.
United States
U.S. Navy electronic warfare programs and Air Force radar modernization drive procurement of conduction-cooled VPX architectures. The Department of Defense's CMMC 2.0 certification tiers filter qualified supplier pools toward vendors with hardened firmware capabilities. Huntsville, Alabama concentrates prime contractor activity for missile defense platforms demanding compact 3U form factors.
Germany
Bundeswehr tactical communications upgrades under Zeitenwende spending acceleration expand ruggedized computing requirements across land and naval platforms. The EU NIS2 directive mandates cybersecurity risk management protocols for defense supply chain qualification. Munich hosts prime contractor engineering centers prioritizing energy-efficient embedded architectures with documented lifecycle emissions.
Japan
Standoff missile defense programs for counterstrike capability buildup require size-constrained VPX3 computers for naval and air platforms. METI industrial standards guide domestic procurement specifications for military-grade embedded systems. Yokohama clusters systems integrators specializing in real-time sensor fusion for maritime patrol aircraft.
United Kingdom
Royal Navy combat system integrators adopt OpenVPX Slot Profile 14.6 with CXL 2.0 memory expansion for unified chassis architectures. UK defense procurement offices consolidate supplier bases through multi-year framework agreements bundling hardware with lifecycle support. Portsmouth anchors naval electronics integration for Type 26 frigate programs.
France
Dassault Aviation and Thales drive demand for DO-254 certified avionics hardware in military derivative aircraft programs. The EU Green Deal's embodied carbon tracking requirements shift procurement criteria toward documented supply chain sustainability. Toulouse concentrates aerospace electronics engineering for UAV and fighter platforms.
VPX SBC Market Competitive Landscape
The competitive structure tilts toward established defense-aerospace specialists with long-standing prime contractor relationships and multi-decade product sustainment capabilities. Tiered supplier concentration favors vendors holding CMMC 2.0 certification and pre-qualified security postures. Two strategic archetypes dominate: full-system integrators delivering chassis-to-software stacks, and modular specialists supplying compute, storage, and accelerator cards. Competitive moves center on sole-source framework agreements replacing spot-buying channels, and backward integration into FPGA-based signal processing modules.
Among U.S.-based defense specialists, Curtiss-Wright and Mercury Systems exemplify the full-system integrator archetype through sustained program-level design wins with Navy and Air Force electronic warfare divisions. Abaco Systems occupies a position within the modular specialist tier, anchoring supply relationships for signal processing-intensive applications. Kontron represents European industrial-temperature capabilities, sitting within the telecommunications and defense crossover segment with specialized variants for base station infrastructure.
| Leading Market Players |
|---|
| Extreme Engineering Solutions |
| ADLINK Technology |
| Curtiss-Wright |
| Concurrent Technologies |
| Elma Electronic |
| Abaco Systems |
| Kontron |
| Connect Tech |
| Mercury Systems |
| Others |
Value Network & Pricing Analysis
Defense prime contractors operating under U.S. Navy and Air Force framework agreements command sole-source relationships that anchor value-based pricing around guaranteed lifecycle sustainment rather than per-unit hardware costs. CMMC 2.0 certification tiers filter qualified supplier pools toward vendors with hardened firmware capabilities, compressing competitive bidding and sustaining premium positioning for security-hardened architectures.
Pricing Analysis
Value-based pricing anchored to guaranteed component availability through 2040 dominates defense procurement, with U.S. prime contractors paying sustained premiums for vendors holding CMMC 2.0 certification and pre-qualified security postures. Price differentiation separates custom SBCs with classified processing enclaves from standard 3U/6U configurations, with Bundeswehr-specific designs commanding the widest premiums. Cost compression in aluminum conduction-cooling chassis is intensifying because energy-intensive smelting operations face EU Green Deal embodied carbon tracking requirements. Telecommunications infrastructure buyers exhibit the highest price sensitivity, while electronic warfare program offices show minimal elasticity due to sole-source dependency.
Supply Chain Analysis
Aerospace-grade 6061-T6 aluminum supply rests on U.S., German, and Japanese specialty metal producers with precision-machined thermal interface capabilities. Advanced FPGA devices for military signal processing draw from Taiwan's concentrated foundry base, while conduction-cooling chassis fabrication feeds from European and North American precision manufacturing clusters. Single-source vulnerability in advanced programmable logic creates supply risk for radar and electronic warfare platforms. Distribution runs through multi-year framework agreements bundling hardware with lifecycle support services, replacing traditional spot-buying through distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OpenVPX architectures are displacing proprietary backplane standards across military avionics and radar modernization programs, forcing a technology-transition phase that rewards vendors with pre-certified interoperability and security postures.
For Market Incumbents: To counter FPGA supply concentration in Taiwan, secure alternative foundry relationships with South Korean or U.S. qualified suppliers while deepening backward integration into signal processing module design. Invest in CMMC 2.0 Level 3 certification to maintain qualified supplier status under consolidated U.S. Navy and Air Force framework agreements.
For New Entrants and Emerging Players: Launch via specialized development kit partnerships with German and Japanese systems integrators seeking rapid subsystem qualification for Zeitenwende and counterstrike capability programs. Target the telecommunications crossover segment with industrial-temperature VPX variants for base station infrastructure, where procurement cycles run shorter and certification barriers sit lower than defense-aerospace tiers.
For Investors and Strategic Acquirers: The window for entry favors modular specialists with FPGA-based signal processing capabilities and pre-certified security postures. Acquisition targets should demonstrate 15-20 year product sustainment track records with at least one U.S. prime contractor. Watch CXL 2.0 memory expansion adoption in naval combat systems as the inflection indicator for heterogeneous computing configuration demand.
| Strategic Initiative | Industry Significance |
|---|---|
| CMMC 2.0 Certification Investment | Pre-qualified security postures accelerate U.S. Navy and Air Force sole-source selection timelines. |
| CXL 2.0 Memory Expansion Integration | OpenVPX Slot Profile 14.6 enables cache-coherent shared memory for U.S. and U.K. naval sensor fusion. |
| Backward Integration into FPGA Modules | In-house signal processing design reduces Taiwan foundry dependency for radar and electronic warfare. |
| EU Green Deal Compliance Documentation | Embodied carbon tracking satisfies Bundeswehr and French procurement sustainability mandates. |
| Multi-Year Framework Agreement Negotiation | Sole-source relationships with lifecycle support bundling displace spot-buying distributor channels. |
Research Methodology
Defense procurement databases, VITA standards documentation, and customs trade records formed the secondary backbone, supplemented by primary interviews with VPX systems integrators, prime contractor procurement officers, embedded computing vendor sales directors, and CMMC compliance consultants. Bottom-up shipment data triangulated against top-down defense budget allocation analysis across the analysis window.
Historical trendline analysis of platform retrofit cycles and radar modernization program timelines informed the projection framework, with segmentation modeling across product type, end user, technology, and application dimensions. CAGRs derived from shipment volume trajectories weighted by average selling price evolution, incorporating FPGA supply constraints and aluminum cost volatility as industry-specific forecast inputs throughout the forecast period.
The model assumes a particular technology adoption path; alternative pathways for proprietary backplane retention or CXL protocol displacement would alter the outlook. Forecasts reflect assumptions regarding OpenVPX interoperability mandate adherence, CMMC 2.0 implementation timelines, and Taiwan foundry capacity allocation. A small set of triggers—Wassenaar Arrangement export control revisions, EU NIS2 directive enforcement intensity, and Japan METI procurement specification shifts—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Electric Fuse Market
Electronic Components
Cordless Phone Battery Market
Electronic Components
Hydrogen Thyratron Market
Electronic Components
Camera Battery Charger Market
Electronic Components
Aluminum Electrolytic Capacitor Market
Electronic Components
2D Electronics Market
Electronic Components
Discrete Capacitors Market
Electronic Components
Coin Battery Holder Market
Electronic Components
Impulse Relays Market
Electronic Components
PTC Resettable Device Market
Electronic Components
Pneumatic Components Market
Electronic Components
Capacitive Stylus Pen Market
Electronic Components
Single Layer Capacitors Market
Electronic Components
Global Suction Tube Market
Electronic Components
Circuit Protection Kits Market
Electronic Components
Fuse Bases Market