
 Duodenal Ulcer Treatment Market | 2026-2036
Duodenal Ulcer Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Duodenal Ulcer Treatment Market Foresight
CE marking under the EU Medical Device Regulation is unwinding the competitive landscape for endoscopic delivery devices used in duodenal ulcer management. Pfizer leverages its manufacturing scale to supply proton pump inhibitor APIs across multiple continents. AstraZeneca sustains technology leadership in potassium-competitive acid blockers. Takeda Pharmaceutical anchors its position in Asian markets through deep hospital formulary relationships.
Duodenal ulcer treatment encompasses pharmaceutical and procedural interventions targeting mucosal erosions in the proximal small intestine, typically involving acid suppression through proton pump inhibition at therapeutic doses of 20-40 mg daily to promote mucosal healing. The primary purpose is to eradicate Helicobacter pylori infection, neutralize gastric acid secretion, and prevent perforation or bleeding complications. Proton Pump Inhibitors command the largest revenue share due to superior healing rates and once-daily dosing convenience. Combination Therapy is gaining fastest traction as triple and quadruple regimens improve eradication rates against antibiotic-resistant H. pylori strains. Oral delivery dominates volume, though intravenous formulations capture premium pricing in acute bleeding management within hospital settings.
FDA bioequivalence standards and EMA quality guidelines govern generic proton pump inhibitor approval pathways, directly shaping pricing dynamics and manufacturer entry timelines. India's CDSCO and China's NMPA enforce local clinical trial requirements that filter which multinational products reach their national formularies. WHO essential medicines list inclusion drives procurement prioritization in low and middle-income health systems. Stakeholders must monitor antibiotic stewardship policies and H. pylori resistance surveillance data to align R&D portfolios with evolving first-line regimen recommendations.
Market Dynamics
Hospital procurement departments are consolidating purchasing power around combination therapy regimens, while antibiotic stewardship programs are compressing prescriber discretion on H. pylori eradication protocols. This dual pressure is restructuring formulary negotiations and R&D prioritization simultaneously.
Growth Catalysts
- India's CDSCO formulary expansion:National reimbursement programs are broadening patient access to acid suppression therapies across tier-2 and tier-3 cities.
- Potassium-competitive acid blocker innovation:Next-generation P-CABs offer faster onset and longer duration than conventional proton pump inhibitors, attracting hospital pharmacy committees.
- Endoscopic hemostasis device proliferation:CE marking under the EU Medical Device Regulation is validating new delivery mechanisms for acute bleeding management.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient manufacturing for proton pump inhibitors clusters in specific coastal Chinese provinces, exposing buyers to geopolitical and logistics disruption.
- Antibiotic resistance surveillance:Rising clarithromycin resistance rates are forcing regimen switches before patent-protected combination products reach scale.
- FDA bioequivalence barriers:Stringent pharmacokinetic requirements for generic proton pump inhibitors are delaying competitive entry and sustaining incumbent pricing power.
Strategic Opportunities
- China's NMPA accelerated pathways:Local clinical trial waivers for certain acid suppression categories are shortening time-to-market for reformulated products.
- Intravenous-to-oral step-down protocols:Hospital systems are unbundling acute and maintenance therapy purchasing, creating separate contract opportunities.
- WHO essential medicines alignment:Prequalification status is unlocking procurement prioritization in low and middle-income health systems across sub-Saharan Africa and Southeast Asia.
Industry Challenges
- Specialized gastroenterology training gaps:Endoscopic hemostasis technique certification bottlenecks are limiting device adoption in community hospital settings.
- Legacy EMR integration friction:H. pylori resistance surveillance data systems require costly interoperability upgrades to connect with pharmacy decision-support tools.
- Patent cliff coordination complexity:Managing portfolio transitions across multiple proton pump inhibitor molecules demands precise supply chain reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Duodenal Ulcer Treatment Market |
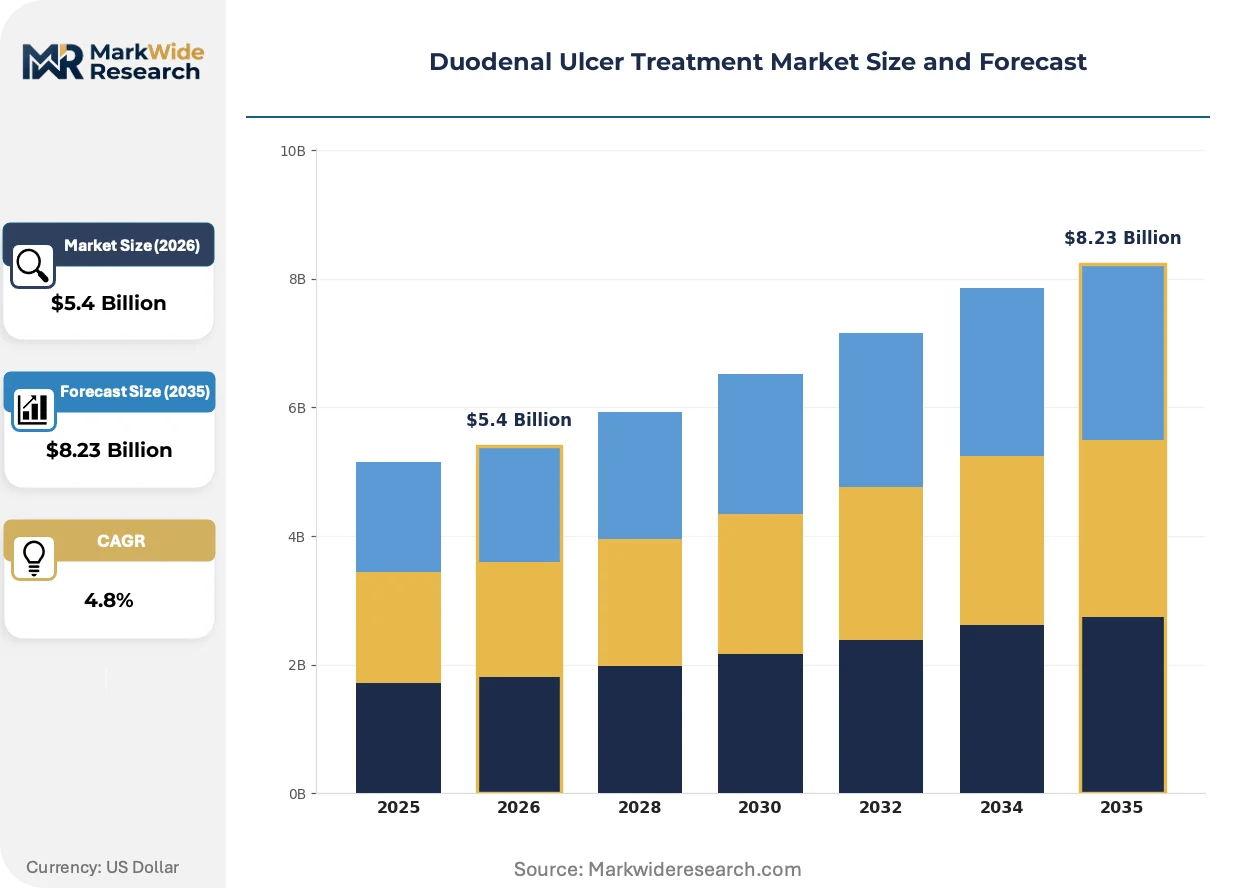
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $8.23 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proton Pump Inhibitors, Antacids, H2 Antagonists, Antibiotics Delivery Mode: Oral, Injectable, Topical, Intravenous End User: Hospitals, Clinics, Homecare, Pharmacies Treatment Regimen: Acid Suppression Therapy, Combination Therapy, Maintenance Therapy, Rescue Therapy |
| Companies Covered | Pfizer, AstraZeneca, GlaxoSmithKline, Novartis, Boehringer Ingelheim, Merck, Takeda Pharmaceutical, Abbott Laboratories, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Duodenal Ulcer Treatment Market Shifts & Advancements
Treatment protocols are fragmenting across severity tiers, with technology and regulatory forces operating on different clock speeds. This divergence is forcing manufacturers to maintain parallel development tracks for acute and chronic care pathways.
Potassium-competitive acid blocker chemistry is bifurcating the acid suppression landscape. Hospital formularies in Germany and Japan are adopting P-CABs for refractory cases at accelerating rates. This adoption is compressing the clinical trial endpoint advantages that proton pump inhibitors held for decades.
EMA's Medical Device Regulation is tightening post-market surveillance requirements for endoscopic delivery systems. Manufacturers must now submit periodic safety update reports that extend far beyond traditional device categories. European hospital procurement groups are responding by consolidating supplier lists to those with full MDR technical documentation.
Prescriber behavior is rotating toward resistance-guided therapy selection. Gastroenterology practices in urban India are deploying rapid molecular testing to tailor eradication regimens before first-line failure. This shift is compressing the window for empirical triple therapy and elevating diagnostic device attach rates.
Duodenal Ulcer Treatment Market Segmentation
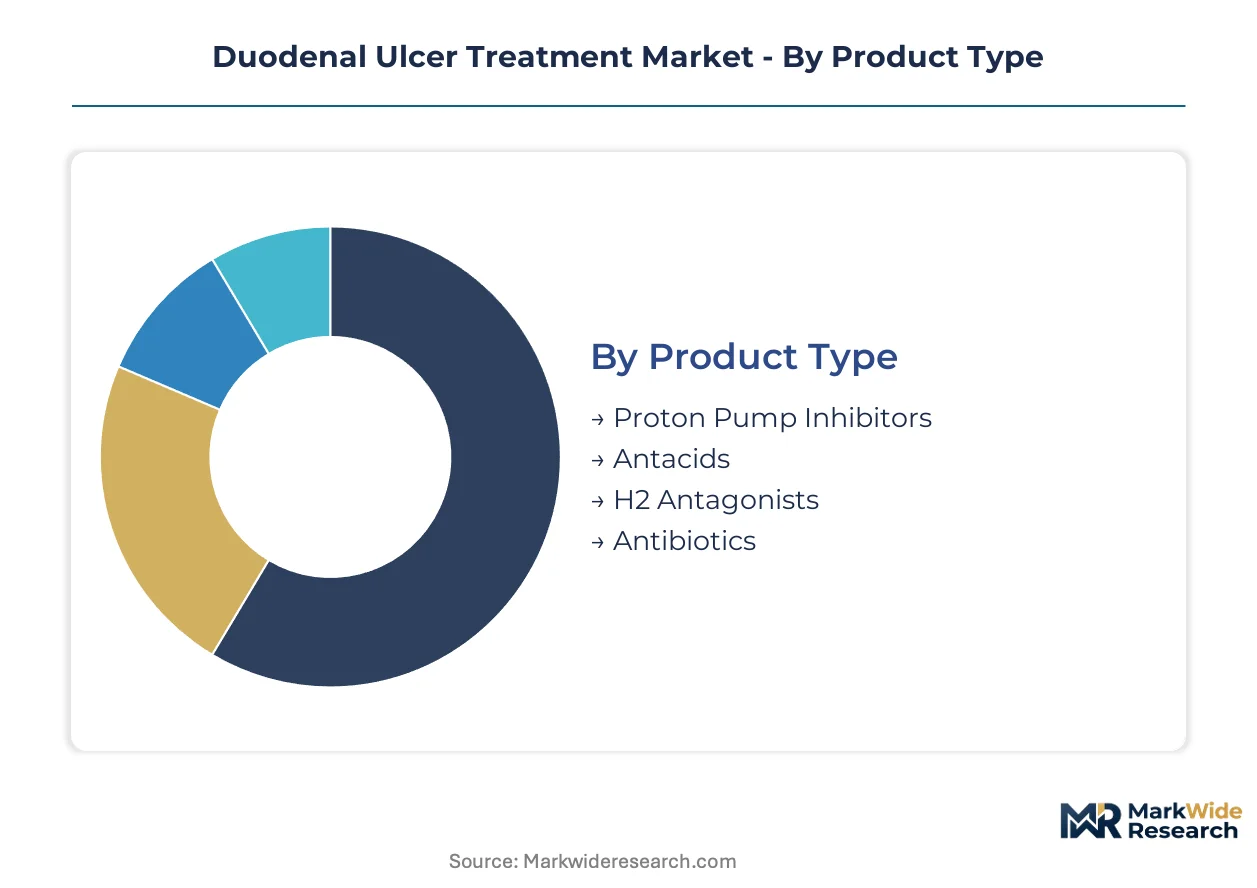
Duodenal ulcer treatment segmentation reflects divergent regulatory pathways for pharmaceuticals versus devices, with reimbursement tiers and hospital procurement protocols fragmenting demand across acute and chronic care settings. Manufacturers must align formulation strategies with distinct bioequivalence requirements and delivery constraints governing each category.
Product Type:
FDA bioequivalence standards and EMA quality guidelines create divergent approval timelines across molecular categories, directly affecting competitive entry and pricing power.
- Proton Pump Inhibitors:Omeprazole, esomeprazole, and lansoprazole formulations suppress gastric acid secretion through irreversible H+/K+ ATPase inhibition. Hospital procurement departments in Germany and Japan concentrate purchasing around once-daily dosing regimens that reduce nursing burden and improve adherence metrics.
- Antibiotics:Clarithromycin, amoxicillin, and metronidazole combinations target H. pylori eradication. India's CDSCO formulary expansion is broadening access to triple therapy across tier-2 and tier-3 cities, though rising clarithromycin resistance is forcing regimen switches before patent-protected products reach scale.
- Antacids:Aluminum and magnesium hydroxide formulations provide rapid symptomatic relief without prescription requirements.
- H2 Antagonists:Ranitidine alternatives and famotidine compete on cost in maintenance therapy segments.
Proton Pump Inhibitors handle the majority of throughput; Antibiotics is expanding most quickly as resistance-guided protocols elevate combination therapy priority.
Delivery Mode:
Cost tiering separates acute intervention from chronic management, with intravenous formulations commanding premium hospital contracts.
- Oral:Tablets and capsules dominate outpatient prescribing through once-daily convenience and pharmacy formulary alignment. China's NMPA accelerated pathways are shortening time-to-market for reformulated oral products with modified release profiles.
- Intravenous:Pantoprazole and esomeprazole infusions manage acute bleeding in emergency departments. Hospital systems in the United States unbundle acute and maintenance therapy purchasing, creating separate contract opportunities for IV step-down protocols.
- Injectable:Subcutaneous and intramuscular alternatives serve patients with compromised enteral access.
- Topical:Limited mucosal protective applications in specific endoscopic adjunct settings.
Oral formulations capture the highest volume base; Intravenous delivery climbs the fastest on acute care protocol adoption.
End User:
Customer type determines reimbursement complexity, with institutional purchasers consolidating around resistance surveillance integration requirements.
- Hospitals:Integrated delivery networks negotiate enterprise contracts spanning emergency, endoscopy, and discharge protocols. WHO essential medicines alignment is unlocking procurement prioritization in low and middle-income health systems across sub-Saharan Africa and Southeast Asia.
- Clinics:Gastroenterology practices deploy rapid molecular testing to tailor eradication regimens before first-line failure, elevating diagnostic device attach rates.
- Homecare:Post-discharge maintenance therapy relies on oral formulation adherence support.
- Pharmacies:Retail channels face margin compression from generic proton pump inhibitor substitution mandates.
Hospitals manage the dominant share of value; Clinics gain share fastest on resistance-guided therapy expansion.
Treatment Regimen:
Maturity gradients separate established maintenance protocols from emerging combination approaches addressing antibiotic resistance.
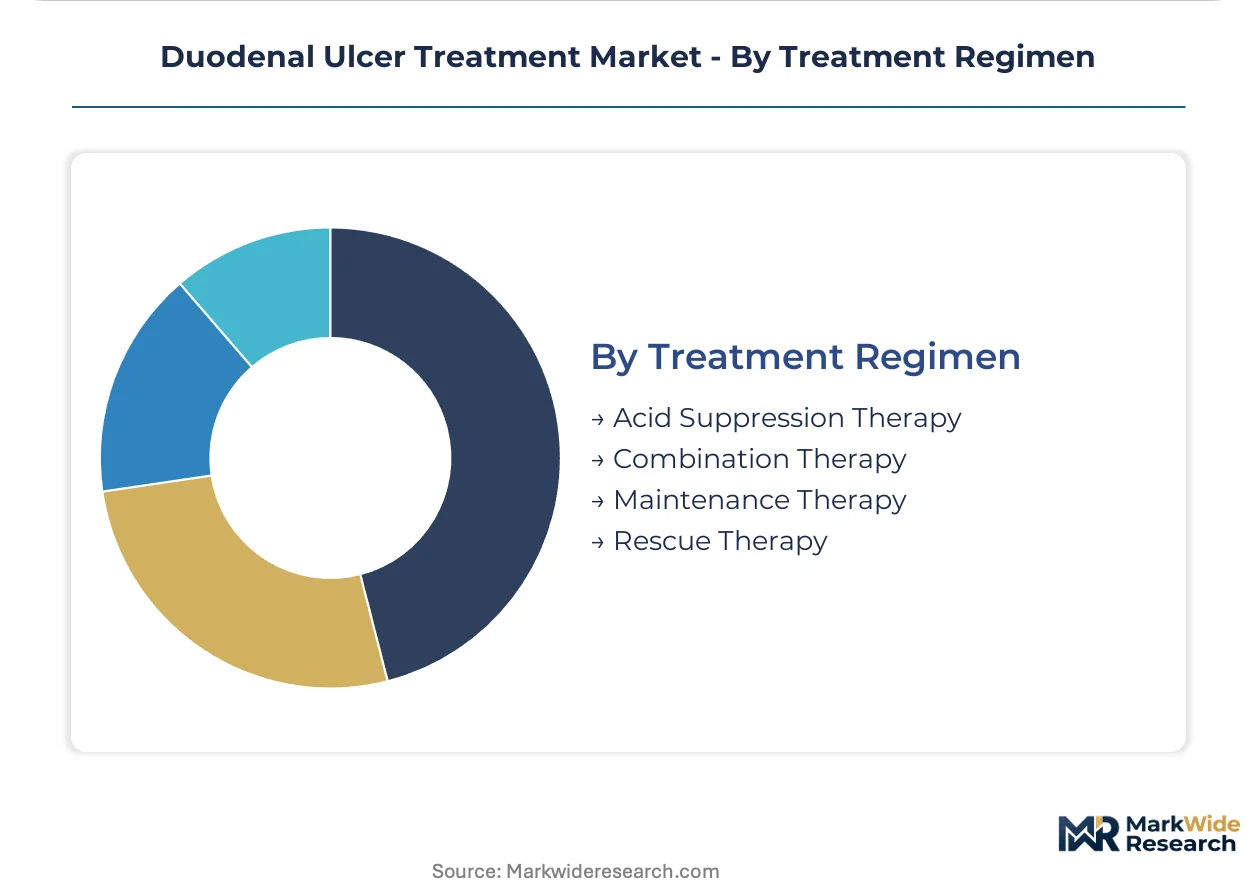
- Combination Therapy:Triple and quadruple regimens integrate proton pump inhibitors with multiple antibiotics to overcome H. pylori resistance. CE marking under the EU Medical Device Regulation is validating new delivery mechanisms for acute bleeding management within combination protocols.
- Acid Suppression Therapy:Monotherapy with proton pump inhibitors or H2 antagonists manages uncomplicated cases.
- Maintenance Therapy:Long-term acid suppression prevents recurrence in high-risk patients.
- Rescue Therapy:Salvage regimens address treatment failure with alternative antibiotic spectra.
Acid Suppression Therapy retains the largest installed base; Combination Therapy shows the steepest expansion trajectory as stewardship programs mandate resistance-tailored approaches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's CDSCO formulary expansion and China's NMPA accelerated pathways are redistributing duodenal ulcer treatment demand toward Asian hospital systems. National reimbursement programs and local clinical trial requirements are filtering which acid suppression therapies reach patient populations.
United States
Hospital procurement departments unbundle acute and maintenance therapy purchasing, creating separate contract opportunities for IV step-down protocols. FDA bioequivalence standards for generic proton pump inhibitors delay competitive entry and sustain incumbent pricing power. The Northeast corridor concentrates integrated delivery network negotiations spanning emergency, endoscopy, and discharge protocols.
Germany
Hospital formularies adopt potassium-competitive acid blockers for refractory cases at accelerating rates, compressing clinical trial endpoint advantages that proton pump inhibitors held for decades. EMA quality guidelines and CE marking under the EU Medical Device Regulation govern endoscopic delivery device validation. The North Rhine-Westphalia cluster anchors procurement consolidation around resistance surveillance integration requirements.
China
National reimbursement programs broaden access to acid suppression therapies across tier-2 and tier-3 cities. NMPA local clinical trial requirements filter which multinational products reach national formularies, though accelerated pathways shorten time-to-market for reformulated oral products. Coastal provinces concentrate active pharmaceutical ingredient manufacturing for proton pump inhibitors, exposing buyers to logistics disruption.
India
Gastroenterology practices in urban centers deploy rapid molecular testing to tailor eradication regimens before first-line failure, elevating diagnostic device attach rates. CDSCO formulary expansion prioritizes WHO essential medicines list inclusion for procurement in low and middle-income health systems. The Maharashtra-Gujarat pharmaceutical corridor supplies proton pump inhibitor APIs across multiple continents.
Duodenal Ulcer Treatment Market Competitive Landscape
Listed leaders compete with private specialists across manufacturing scale and hospital formulary penetration dimensions. The vendor base organizes around three tiers: multinational pharmaceutical conglomerates with API-to-formulation integration, regional specialists with deep hospital pharmacy relationships, and generic manufacturers competing on bioequivalence certification speed. Strategic archetypes include scale-driven API suppliers, innovation-focused P-CAB developers, and stewardship-aligned combination therapy packagers. Competitive moves concentrate on M&A for manufacturing capacity and strategic partnerships for resistance surveillance data integration.
Among the scale-driven pharmaceutical conglomerates, Pfizer and AstraZeneca occupy positions reflecting distinct competitive archetypes. Pfizer exemplifies the API supply anchor with manufacturing footprint spanning multiple continents. AstraZeneca sits within the innovation-tier, representing potassium-competitive acid blocker technology leadership. Takeda Pharmaceutical anchors the regional specialist archetype through its position in Asian hospital formulary networks.
| Leading Market Players |
|---|
| Pfizer |
| AstraZeneca |
| GlaxoSmithKline |
| Novartis |
| Boehringer Ingelheim |
| Merck |
| Takeda Pharmaceutical |
| Abbott Laboratories |
| Sanofi |
| Others |
Supply & Pricing Matrix
Multi-continent API manufacturing scale at Pfizer and Takeda Pharmaceutical anchors price floors across proton pump inhibitor categories, concentrating supply leverage in coastal Chinese provinces and the Maharashtra-Gujarat corridor while compressing margins for non-integrated formulators.
Pricing Analysis
Certification level (FDA-grade vs. EMA-grade vs. national-only) creates the primary spread between premium intravenous formulations and economy oral generics. Three-tier pricing structure across premium, standard, and economy levels reflects bioequivalence validation speed and hospital formulary penetration depth. Cost compression in the generic oral segment is intensifying because CDSCO and NMPA local trial waivers accelerate competitive entry. Hospital procurement departments exhibit the lowest price sensitivity due to bundled emergency-to-discharge contracting, while retail pharmacies face the highest substitution pressure from payer mandates.
Supply Chain Analysis
Just-in-time inventory strategies dominate oral formulation distribution, while strategic stockpiling of intravenous proton pump inhibitors buffers hospital systems against acute bleeding demand surges. Active pharmaceutical ingredient manufacturing concentrates in coastal Chinese provinces, India, and Switzerland, drawing from specialty chemical precursors, enteric coating polymers, and sterile fill-finish capacity. Single-source vulnerability in H. pylori antibiotic APIs exposes combination therapy packagers to clarithromycin supply interruption. Distribution runs through hospital group purchasing organizations and regional pharmaceutical distributors with cold-chain capabilities for biologic adjuncts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Potassium-competitive acid blocker chemistry is disrupting decades of proton pump inhibitor dominance, creating asymmetric reward for manufacturers with FDA breakthrough therapy designation or EMA PRIME eligibility.
For Market Incumbents: Shield formulary position by securing backward integration into API supply for combination therapy regimens, and accelerate CE marking documentation for endoscopic delivery devices ahead of EU MDR enforcement waves. Clarithromycin resistance surveillance integration represents the priority defensive lever against stewardship-driven regimen switches. For New Entrants and Emerging Players: Lead with resistance-guided diagnostic device bundling in urban Indian and tier-2 Chinese gastroenterology clinics, where rapid molecular testing penetration remains below hospital system levels. White-space concentration in sub-Saharan Africa WHO prequalification pathways offers the most penetrable geographic entry point. Go-to-market execution should anchor on GPO contract bidding alongside essential medicines list inclusion campaigns. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturers with hospital pharmacy committee relationships spanning acute-to-maintenance protocol integration. Long-term viability over the 5-10 year horizon rests on portfolio breadth across P-CAB, PPI, and antibiotic categories rather than single-molecule concentration. Acquisition targeting should prioritize regional specialists with NMPA accelerated pathway experience. The signal to watch is clarithromycin resistance rate thresholds triggering national guideline revisions.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation unlocks procurement consolidation by European hospital groups. |
| Hospital System Partnership | Integrated delivery network contracts span emergency, endoscopy, and discharge protocol bundling. |
| Backward Integration into API Supply | Captive manufacturing of proton pump inhibitor precursors insulates against coastal China logistics disruption. |
| Reimbursement Strategy | WHO essential medicines list inclusion drives prioritization in sub-Saharan Africa and Southeast Asia procurement. |
| Software Companion Development | H. pylori resistance surveillance data integration with pharmacy decision-support tools elevates diagnostic attach rates. |
Research Methodology
Initial hypotheses were tested against primary input from hospital procurement managers, formulary directors, regulatory affairs leads, and gastroenterology clinicians and refined through secondary validation across FDA filings, EMA submission databases, ClinicalTrials.gov records, and CDSCO approval registries. Bottom-up demand modeling from individual hospital system contracts was triangulated against top-down pharmaceutical shipment data and national reimbursement program expansion timelines.
Variance decomposition across the projection horizon isolates volume, price, and mix effects within each modeled segment spanning product type, delivery mode, end user, and treatment regimen dimensions. CAGRs were derived from regression-based trend extrapolation calibrated to historical bioequivalence approval velocity and formulary access expansion curves. Resistance surveillance data integration rates and P-CAB hospital adoption thresholds served as industry-specific forecast sensitivity inputs.
Forecasts assume regulatory continuity in FDA bioequivalence standards and EMA quality guidelines; material policy shifts would require re-modeling. Antibiotic stewardship mandate intensity and H. pylori resistance surveillance system deployment pace constitute specific risk factors. Revision becomes warranted when clarithromycin resistance rates in major markets cross guideline-switch thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gastroenterology
Helicobacter Pylori Infections Treatment Market
Gastroenterology
Pouchitis Treatment Market
Gastroenterology
Ulcerative Colitis (UC) Treatment Market
Gastroenterology
Chronic Liver Diseases Therapeutics Market
Gastroenterology
Hyperemesis Gravidarum Treatment Market
Gastroenterology
Necrotic Enteritis Treatment Market
Gastroenterology
Hirschsprung Disease Treatment Market
Gastroenterology
Digestive Health Products Market
Gastroenterology
Stomach Cancer Market
Gastroenterology
Peptic Ulcer Market
Gastroenterology
Colon Hydrotherapy Market
Gastroenterology
Gallstone Market
Gastroenterology
Digestive Health Market
Gastroenterology
Chile Gastric Cancer Treatment Market
Gastroenterology
Gastritis Treatment Market
Gastroenterology
Gastroesophageal Reflux Disease Therapeutics Market