
 Dry Dog Food Market | 2026-2036
Dry Dog Food Market Size, Share, and Industry Trends Forecast 2026-2036
Dry Dog Food Market Analytics
Veterinary nutritionist talent is collapsing across North American manufacturing hubs, forcing brands to automate formulation or outsource to university research partnerships. Mars Petcare leverages captive supply chains for raw protein sourcing across multiple continents. Hill's Pet Nutrition sustains clinical credibility through prescription diet channels anchored by veterinary hospital networks. Nestlé Purina PetCare competes on manufacturing scale, operating some of the largest extrusion facilities serving mass retail distribution.
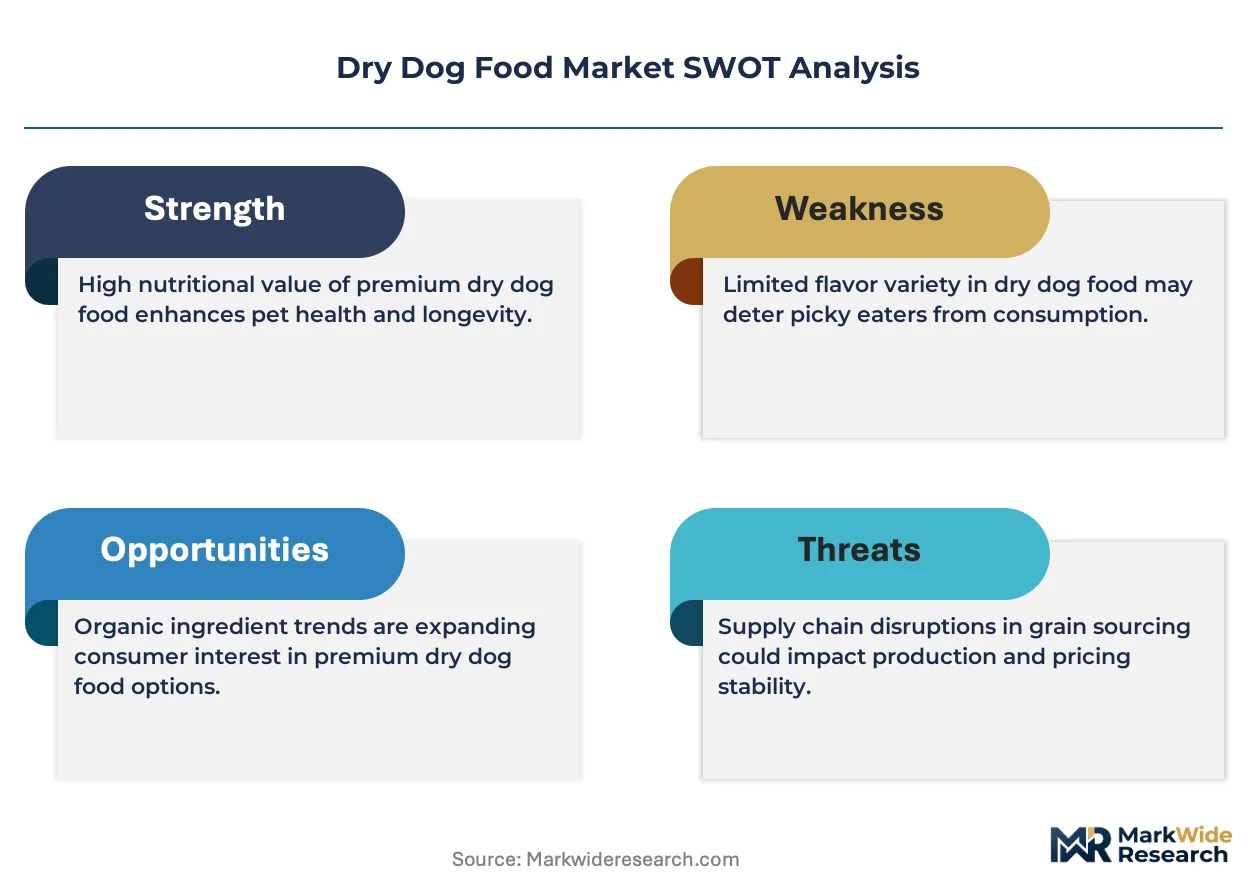
Dry dog food consists of shelf-stable kibble produced through extrusion cooking, typically containing 10-12% moisture content with protein, carbohydrate, fat, vitamin, and mineral matrices formulated to AAFCO nutrient profiles. The primary commercial purpose centers on convenient, calorie-dense daily nutrition for domestic canines across life stages from puppy growth to senior maintenance. Grain-free formulations command premium shelf positioning as consumers link carbohydrate reduction to ancestral dietary patterns, though veterinary scrutiny of dilated cardiomyopathy associations has shifted some demand toward ancient grain alternatives. High-protein segments attract margin concentration from performance and working dog owners willing to pay ingredient-grade premiums.
AAFCO nutrient profiles, FDA Center for Veterinary Medicine oversight, and state feed control officials collectively govern ingredient safety claims and manufacturing sanitation across the United States. The European Union enforces feed hygiene regulation through EFSA guidance and national competent authorities, while FEDIAF codes shape commercial formulation standards. Stakeholders must monitor evolving regulatory positions on novel proteins and cellular agriculture inputs as these technologies approach commercial scale for pet food applications.
Market Dynamics
Veterinary nutritionist scarcity across North American manufacturing hubs is forcing brands toward automated formulation systems and university research partnerships, fundamentally altering how premium dry dog food gets developed and validated.
Growth Catalysts
- FDA ingredient disclosure mandates:Tightening labeling standards under FDA Center for Veterinary Medicine oversight are compelling manufacturers toward cleaner formulations and transparent sourcing claims that command retail premium positioning.
- Grain-free ancestral dietary positioning:Consumer association of carbohydrate reduction with canine evolutionary nutrition is expanding shelf space allocation for alternative formulations in specialty retail channels.
- Brazil veterinary endorsement networks:Developing clinical credibility infrastructure across Brazilian veterinary hospitals is accelerating prescription and recommendation-driven purchasing for therapeutic dry formulations.
Market Restraints
- Protein input cost volatility:Fluctuations in poultry and fish meal commodity markets compress margin predictability for high-protein premium segments dependent on ingredient-grade sourcing.
- AAFCO dilated cardiomyopathy scrutiny:Veterinary investigation into grain-free formulations and heart disease associations has chilled consumer confidence and triggered formulation pivots toward ancient grain alternatives.
- Extrusion equipment supplier concentration:Limited domestic manufacturing capacity for industrial-scale extrusion systems extends equipment procurement timelines and concentrates supplier bargaining power.
Strategic Opportunities
- German specialized retail channel development:Underpenetrated independent pet specialty stores in secondary German cities offer whitespace for premium brand establishment ahead of mass retail saturation.
- Cellular agriculture protein convergence:Cultivated meat technology approaching commercial scale for pet food applications enables novel protein sourcing independent of conventional livestock supply chains.
- Direct-to-consumer subscription models:Veterinary-customized delivery platforms bypass traditional retail markup structures while capturing recurring revenue through life-stage tailored formulation programs.
Industry Challenges
- Clinical nutritionist talent pipeline collapse:Declining veterinary specialization in companion animal nutrition limits in-house formulation expertise and extends reliance on external research partnerships.
- EFSA novel protein approval timelines:Extended safety evaluation protocols for insect and cellular agriculture inputs delay product launch schedules and freeze formulation innovation pipelines.
- Legacy ERP integration with automated batching:Manufacturing execution system upgrades for precision nutrient delivery require substantial capital deployment and operational downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry Dog Food Market |
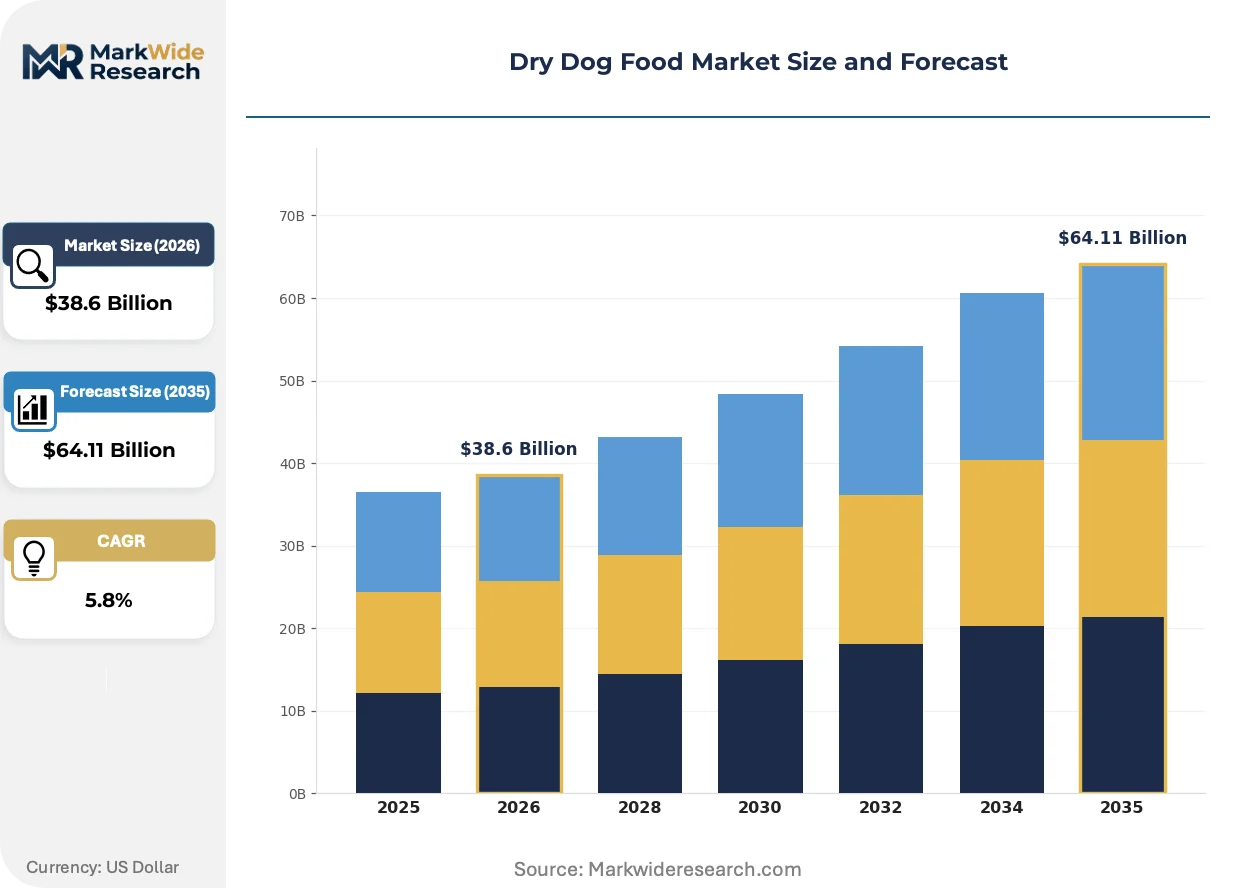
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $64.11 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular, Grain-Free, High-Protein, Organic Customer Type: Pet Owners, Breeders, Shelters, Pet Stores Ingredient Quality: Premium, Standard, Natural, Specific Diet Packaging Type: Bulk Bags, Single Serve, Resealable, Eco-Friendly |
| Companies Covered | Nestlé Purina PetCare, Mars Petcare, Hill’s Pet Nutrition, J.M. Smucker Company, General Mills, Colgate-Palmolive Company, Blue Buffalo, Diamond Pet Foods, Simmons Pet Food, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry Dog Food Market Evolving Landscape
Extrusion technology advancement and protein sourcing diversification are fragmenting traditional manufacturing economics while regulatory scrutiny of novel ingredients accelerates compliance investment requirements.
Cold-pressed manufacturing technology is fragmenting the dominance of conventional high-temperature extrusion by preserving heat-sensitive nutrients and enzymes. Boutique manufacturers and premium-focused contract producers are adopting these systems to differentiate shelf-stable products on bioavailability claims. The technology is fragmenting capital allocation patterns as smaller production footprints enable regional manufacturing models that challenge centralized mass production economics.
EFSA feed hygiene regulation evolution is tightening manufacturing sanitation documentation requirements across European Union production facilities. National competent authorities are intensifying inspection frequency for novel protein handling protocols and cross-contamination prevention systems. German and French manufacturing clusters are responding by consolidating quality assurance functions and investing in environmental monitoring infrastructure ahead of enforcement phase-ins.
Subscription-based veterinary-customized nutrition programs are displacing episodic retail purchasing among performance dog owners and clinical diet adherents. Breed-specific and activity-level tailored formulations delivered on recurring schedules capture lifetime value while reducing customer acquisition costs. This model concentrates most visibly across United States metropolitan markets with established tele-veterinary infrastructure and high pet insurance penetration rates.
Dry Dog Food Market Segmentation
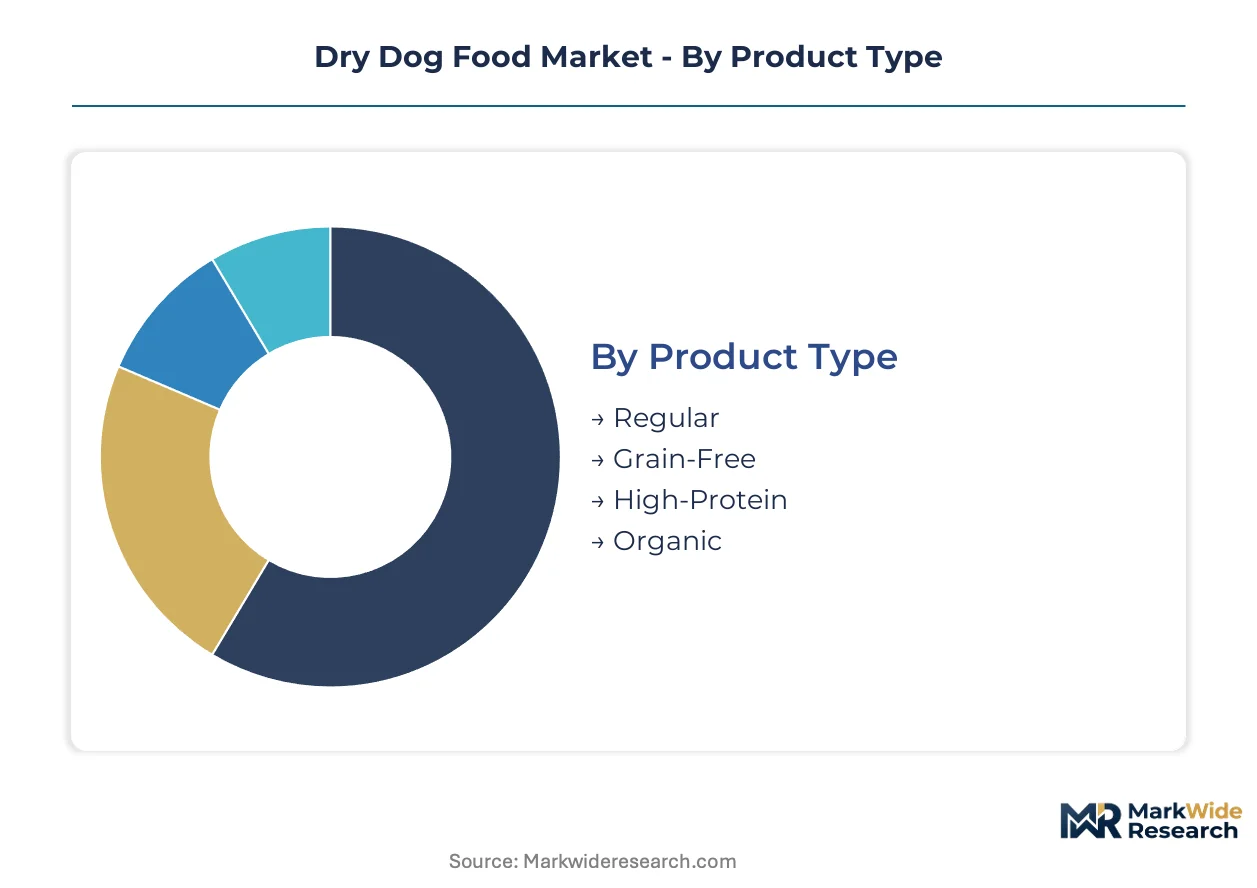
Dry dog food segmentation determines margin architecture and channel strategy for manufacturers. Product type and ingredient quality stratify pricing power, while customer type and packaging format dictate distribution infrastructure requirements.
Product Type:
Channel-mix patterns vary sharply across product types, with grain-free and high-protein formulations concentrating in veterinary clinics and specialty retailers while regular kibble flows through mass retail and warehouse clubs.
- Regular:Standard extruded kibble meeting AAFCO baseline nutrient profiles for maintenance diets. Demand concentrates in suburban United States households purchasing through Walmart and Target locations, constrained by thin margins limiting ingredient upgrade flexibility.
- Grain-Free:Formulations substituting legumes, potatoes, or tapioca for traditional cereal grains. Brazilian and German specialty retailers are expanding shelf allocation fastest, though FDA dilated cardiomyopathy investigations have chilled United States veterinary endorsement.
- High-Protein:Performance-oriented formulations exceeding 30% crude protein content. Working dog owners in rural United States markets and German police K9 units drive procurement, with ingredient-grade poultry meal costs compressing manufacturer margins.
- Organic:Certified organic ingredient chains with prohibited synthetic additives. Natural food co-ops in Portland, Oregon and Austin, Texas anchor distribution, limited by supply chain traceability costs.
Regular formulations dominate installed base. Grain-free is where expansion concentrates.
Customer Type:
Cost tier stratification separates breeders and shelters seeking volume efficiency from pet owners pursuing premium nutrition positioning.
- Pet Owners:Individual household purchasers making discretionary nutrition decisions. United States metropolitan markets with pet insurance penetration above 40% show strongest subscription model adoption for life-stage tailored programs.
- Breeders:Commercial kennel operations requiring consistent bulk supply for multiple animals. Midwestern United States breeding clusters negotiate direct-from-manufacturer pricing, prioritizing formulation stability over ingredient novelty.
- Shelters:Municipal and nonprofit animal welfare organizations operating under constrained budgets. Donor-funded procurement in Texas and Florida shelters favors standard formulations in bulk bag configurations.
- Pet Stores:Independent and chain retailers curating assortment for consumer self-selection. German Fressnapf locations and United States Petco stores are expanding private label premium positioning.
Pet owners represent the largest volume pool. Breeders are climbing the fastest for margin contribution.
Ingredient Quality:
Application context determines quality tier selection, with therapeutic diets demanding premium specification while maintenance feeding accepts standard grades.
- Premium:Human-grade ingredient sourcing with enhanced digestibility claims. German manufacturing clusters supply veterinary hospital networks across Düsseldorf and Munich, validated by clinical feeding trials.
- Standard:Feed-grade ingredient matrices meeting regulatory minimums. Brazilian mass retail channels in São Paulo and Rio de Janeiro concentrate procurement, price-competitive with local manufacturers.
- Natural:No artificial preservatives, colors, or flavors with limited processing claims. United States natural grocery chains including Whole Foods Market are expanding distribution in coastal metropolitan areas.
- Specific Diet:Therapeutic formulations addressing renal, weight management, or gastrointestinal conditions. Hill's Pet Nutrition prescription channels and veterinary endorsement networks in Chicago and Los Angeles anchor demand.
Standard formulations dominate installed base. Specific diet is where expansion concentrates.
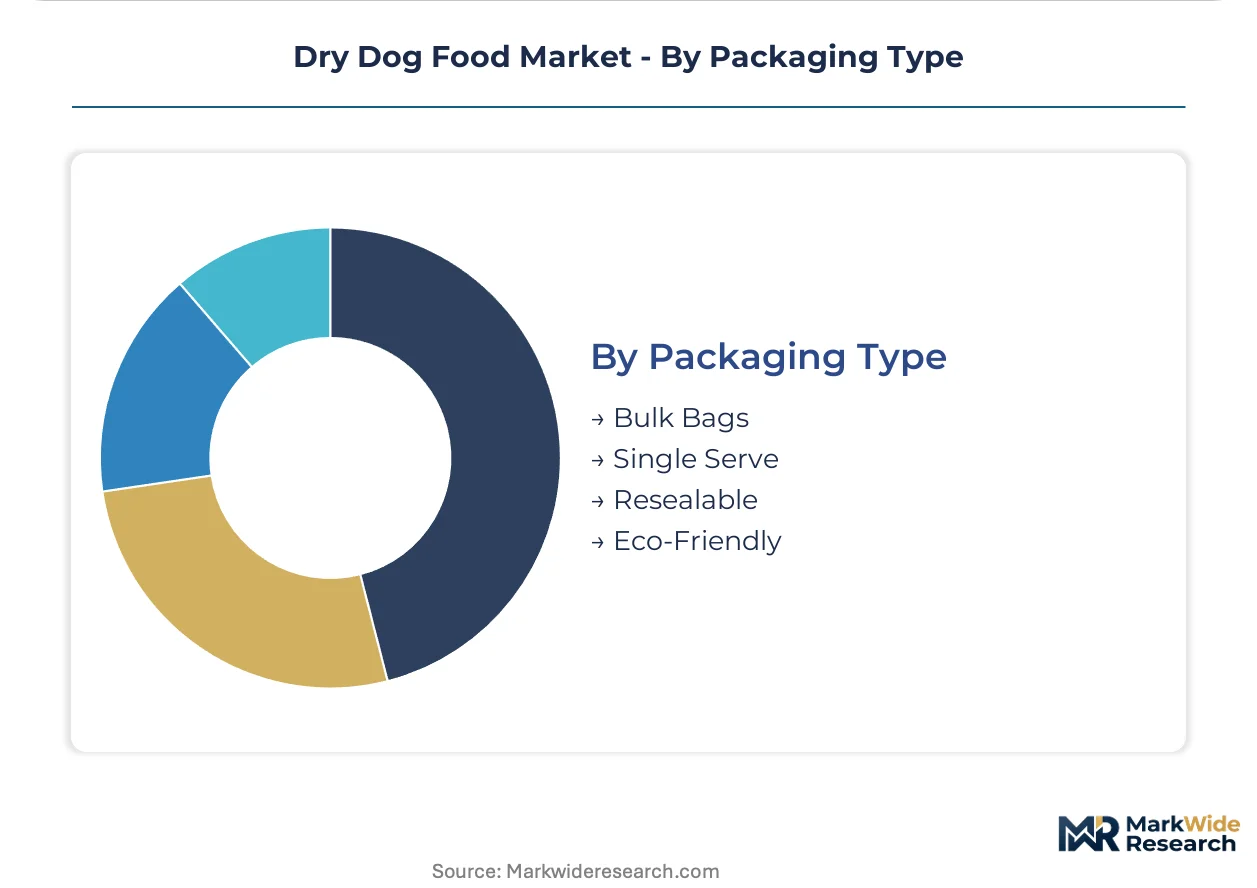
Packaging Type:
Volume and margin profiles diverge across packaging formats, with bulk configurations serving high-throughput customers and single-serve addressing trial and travel occasions.
- Bulk Bags:15-50 pound multi-wall paper or woven polypropylene configurations. Warehouse clubs in United States Sun Belt markets and Brazilian cash-and-carry operations concentrate procurement.
- Single Serve:Individual meal portion packaging for trial, travel, or veterinary sampling. United States direct-to-consumer subscription services are expanding single-serve inclusion for life-stage transition programs.
- Resealable:Zipper-equipped multi-layer films preserving freshness through repeated access. Premium positioning in German Fressnapf and United States Chewy.com fulfillment centers supports margin capture.
- Eco-Friendly:Recyclable, compostable, or reduced-plastic packaging formats. Portland, Oregon and Amsterdam metropolitan markets show strongest consumer willingness to absorb cost premiums.
Bulk bags dominate installed base. Eco-friendly is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium dry dog food commands 40% higher shelf prices in German specialty retail than in Brazilian mass-market channels, creating divergent margin architectures for manufacturers serving each geography.
United States
Veterinary endorsement networks in Chicago and Los Angeles drive prescription diet procurement, while FDA Center for Veterinary Medicine labeling mandates tighten ingredient disclosure requirements. Subscription-based delivery platforms in metropolitan markets with high pet insurance penetration capture recurring revenue through life-stage tailored programs.
Germany
Independent pet specialty stores in secondary cities offer whitespace for premium brand establishment ahead of mass retail saturation. EFSA feed hygiene regulations intensify manufacturing sanitation documentation requirements across production facilities in Düsseldorf and Munich. Manufacturing clusters consolidate quality assurance functions ahead of enforcement phase-ins.
Brazil
Developing clinical credibility infrastructure across São Paulo and Rio de Janeiro veterinary hospitals accelerates recommendation-driven purchasing for therapeutic formulations. ANVISA oversight shapes commercial feed safety standards while cash-and-carry operations concentrate bulk bag procurement. Local manufacturers compete aggressively on price in mass retail channels.
Canada
Health Canada and PMRA oversight govern ingredient safety claims and manufacturing sanitation across provincial feed control systems. Natural food co-ops in Vancouver and Toronto anchor organic formulation distribution, constrained by supply chain traceability costs. Prairie Provinces breeding clusters negotiate direct-from-manufacturer pricing prioritizing formulation stability.
United Kingdom
Pet insurance penetration above 25% in London and Southeast England supports veterinary-customized subscription model adoption. FEDIAF codes shape commercial formulation standards while national competent authorities enforce feed hygiene protocols. Midlands manufacturing locations serve specialty retail expansion across Northern England and Scotland.
Dry Dog Food Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the dry dog food market. The structure consolidates around three global conglomerates with captive supply chains and mass retail distribution, while mid-tier specialists compete through veterinary endorsement networks and premium positioning. Two strategic archetypes dominate: diversified consumer goods conglomerates leveraging manufacturing scale, and clinical nutrition specialists anchoring prescription channels. Competitive moves concentrate on automated formulation partnerships and specialized retail channel development.
Within the diversified conglomerate tier, Nestlé Purina PetCare and Mars Petcare occupy positions defined by manufacturing scale and captive protein sourcing across multiple continents. Hill's Pet Nutrition exemplifies the clinical specialist archetype, anchoring prescription diet credibility through veterinary hospital networks. These three entities collectively represent the structural poles around which competitive positioning organizes.
| Leading Market Players |
|---|
| Nestlé Purina PetCare |
| Mars Petcare |
| Hill's Pet Nutrition |
| J.M. Smucker Company |
| General Mills |
| Colgate-Palmolive Company |
| Blue Buffalo |
| Diamond Pet Foods |
| Simmons Pet Food |
| Others |
Value Network & Pricing Analysis
Ninety-day equipment procurement timelines for industrial-scale extrusion systems concentrate supplier bargaining power and compress margin predictability for manufacturers balancing premium positioning against commodity input costs. This lead-time band exposes brands to protein price volatility while rewarding captive supply chain investments that insulate formulation costs from spot market swings.
Pricing Analysis
Premium dry dog food commands 40% higher shelf prices in German specialty retail than in Brazilian mass-market channels, establishing geographic price spreads that stratify manufacturer margin architectures. Three-tier pricing structure across premium, standard, and economy levels dominates, with ingredient-grade certification and veterinary endorsement driving differentiation. Cost compression in high-protein segments intensifies because poultry meal commodity markets swing unpredictably. Shelter procurement teams show highest price sensitivity, while performance dog owners absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Limited domestic manufacturing capacity for industrial-scale extrusion systems extends equipment procurement timelines and concentrates supplier bargaining power across United States, Germany, and Brazil production hubs. Raw material matrices draw from poultry meal, fish meal, and legume starch inputs tethered to agricultural commodity cycles. Single-source vulnerability runs through concentrated extrusion equipment suppliers in European manufacturing clusters. Distribution runs through veterinary hospital networks, specialty retail channels, and mass retail fulfillment centers in divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cellular agriculture protein convergence approaching commercial scale constitutes a technological inflection reshaping sourcing economics and regulatory validation requirements for novel ingredient pipelines.
For Market Incumbents: Secure captive protein supply agreements across multiple continents to buffer margin exposure from poultry meal commodity volatility. Automate formulation systems through university research partnerships to offset collapsing veterinary nutritionist talent pipelines. Channel control through prescription diet networks anchors pricing power against mass retail price erosion. For New Entrants and Emerging Players: Lead with cold-pressed manufacturing technology to differentiate on bioavailability claims in underpenetrated German secondary cities. Target subscription-based veterinary-customized delivery platforms in United States metropolitan markets with high pet insurance penetration. Go-to-market through tele-veterinary infrastructure partnerships bypasses traditional retail markup capture. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because clinical nutrition specialist archetypes with veterinary endorsement networks command durable premium positioning. Acquisition targets should show captive supply chain development or automated formulation capabilities. Watch EFSA novel protein approval timelines as the signal for formulation innovation pipeline unlock.| Strategic Initiative | Industry Significance |
|---|---|
| Cellular Agriculture Protein Integration | Cultivated meat sourcing bypasses conventional livestock supply chain volatility and EFSA approval bottlenecks. |
| Automated Formulation Partnership | University research collaborations offset veterinary nutritionist scarcity constraining premium product development. |
| Direct-to-Consumer Subscription Launch | Recurring revenue capture through life-stage tailored programs reduces customer acquisition costs in metropolitan markets. |
| Specialized Retail Channel Expansion | German independent pet specialty stores in secondary cities offer whitespace ahead of mass retail saturation. |
| Cold-Pressed Manufacturing Adoption | Heat-sensitive nutrient preservation enables bioavailability differentiation against conventional extrusion economics. |
Research Methodology
A spread of perspectives from veterinary nutritionists, pet food manufacturing executives, specialty retail buyers, and regulatory affairs specialists converged on the working assumptions underlying demand segmentation and pricing dynamics. Secondary validation drew from FDA Center for Veterinary Medicine filings, AAFCO nutrient profile documentation, EFSA feed hygiene regulation updates, and customs trade data tracking protein meal imports. Bottom-up volume modeling and top-down value triangulation anchored the analytical framework.
Segmentation dimensions modeled include product type, ingredient quality tier, customer archetype, packaging format, and regional regulatory cluster across the analysis window. CAGRs were derived from trend extrapolation against historical volume benchmarks and projected penetration rates for subscription delivery models. Forecast inputs incorporated veterinary endorsement network expansion rates and extrusion equipment capacity utilization metrics.
The analysis sits within stated boundaries; outcomes outside sustained pet insurance penetration growth and stable protein commodity input costs would require recalibration. Practitioners should keep alternative scenarios live as EFSA novel protein approval timelines and cellular agriculture commercialization trajectories evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Europe Dog Food Market
Pet Care Products
Frozen and Freeze-Dried Pet Food Market
Pet Care Products
Pet Gadgets Market
Pet Care Products
Pet Car Seat Protectors Market
Pet Care Products
Pet Treats Market
Pet Care Products
Dog Perfume Market
Pet Care Products
Dog Vitamins Market
Pet Care Products
US Dog Food Market
Pet Care Products
Cat Litter Boxes Market
Pet Care Products
Dog Hats Market
Pet Care Products
Pet Treats and Chews Market
Pet Care Products
Pet Water Fountain Market
Pet Care Products
Netherlands Pet Boarding Market
Pet Care Products
Vegan Pet Food Market
Pet Care Products
US and Mexico Cat Litter Market
Pet Care Products
Cat Accessories Market