
 Pet Treats Market | 2026-2036
Pet Treats Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Treats Market Analysis
Market Context
Plant-based proteins and cultured meat alternatives is decoupling treat formulations from conventional livestock supply chains, compressing input cost volatility for early movers. Mars, Incorporated leverages captive ingredient sourcing across multiple continents to insulate margin structures. Nestlé Purina PetCare anchors its position through veterinary channel exclusivity and prescription treat lines. General Mills, Inc. competes by extending human-grade processing standards from its food division into pet applications.
Technical Definition and Segment Structure
Pet treats are edible reward products formulated for companion animals, typically containing moisture levels below 15 percent for shelf-stable biscuits or 20-30 percent for soft and chewy formats, manufactured through extrusion, baking, or dehydration processes designed to deliver palatability, dental abrasion, or nutrient supplementation beyond standard feed. Chews and jerky segments command premium price tiers due to longer engagement times and perceived dental benefits, while soft treats dominate training and senior pet applications where palatability thresholds run highest. Functional ingredient types, spanning probiotics, glucosamine, and omega fatty acid fortification, are capturing disproportionate margin pools as veterinary endorsement validates health claims.
Regulatory Environment and Outlook
The FDA Center for Veterinary Medicine enforces ingredient safety and labeling standards for pet treats distributed in the United States, while the USDA monitors certain meat-based inputs under the Federal Meat Inspection Act; state-level feed control officials supplement federal oversight with facility registration and product registration requirements. The EU's Feed Hygiene Regulation and forthcoming packaging sustainability directives under the EU Green Deal are reshaping export compliance burdens for manufacturers serving European retail channels. Stakeholders must monitor evolving definitions of nutritional adequacy versus snack categorization, as regulatory reclassification could trigger veterinary prescription requirements or restrict retail distribution access.
Market Dynamics
Humanization of companion animals is compressing the gap between human food and pet treat formulation standards, forcing manufacturers to adopt clean-label ingredient sourcing and cold-chain logistics previously reserved for human consumption.
Growth Catalysts
- Functional Ingredient Fortification:Veterinary endorsement of probiotic and glucosamine-enriched formats is validating health claims and expanding prescription-adjacent retail channels. Pet owners increasingly seek treats that deliver measurable physiological benefits beyond basic reward.
- E-commerce Subscription Models:United States-based direct-to-consumer platforms are locking in recurring revenue streams through personalized nutrition algorithms and auto-replenishment schedules. This channel shift reduces customer acquisition costs while building consumption habituation.
- FDA Center for Veterinary Medicine Guidelines:Tightening traceability requirements under evolving pet food safety frameworks are accelerating industry consolidation. Compliant manufacturers gain shelf access while smaller operators face registration barriers.
Market Restraints
- Input Cost Volatility:Conventional livestock protein prices fluctuate with feed grain markets and climate-driven supply disruptions. Plant-based alternatives remain capacity-constrained at commercial scale.
- Supply Concentration Risk:Premium ingredient sourcing clusters in specific agricultural regions, exposing manufacturers to localized drought, disease, or trade policy shocks. Single-source dependencies amplify disruption cascades.
- Regulatory Friction:Divergent definitions of nutritional adequacy versus snack categorization across state feed control officials create compliance fragmentation. Reclassification risks could trigger veterinary prescription requirements.
Strategic Opportunities
- Cultured Meat Scale-Up:Cellular agriculture technologies promise to decouple treat production from conventional livestock supply chains entirely. Early movers in Singapore and Israel are building pilot facilities with regulatory sandbox support.
- Senior Pet Formulations:Aging companion animal demographics in Japan and Western Europe create demand for soft-textured, high-palatability products with joint-support fortification. This segment commands sustained premium pricing.
- EU Green Deal Packaging Mandates:Forthcoming sustainability directives are accelerating compostable and mono-material flexible film development. Compliant packaging becomes a retail access condition for European distribution.
Industry Challenges
- Formulation Science Talent Scarcity:Cross-functional expertise spanning veterinary nutrition, food engineering, and sensory palatability testing remains concentrated at established research institutions. Recruitment competition intensifies.
- Cold-Chain Infrastructure Investment:Human-grade processing standards require refrigerated manufacturing environments and shortened distribution windows. Capital deployment for facility upgrades strains mid-tier operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Treats Market |
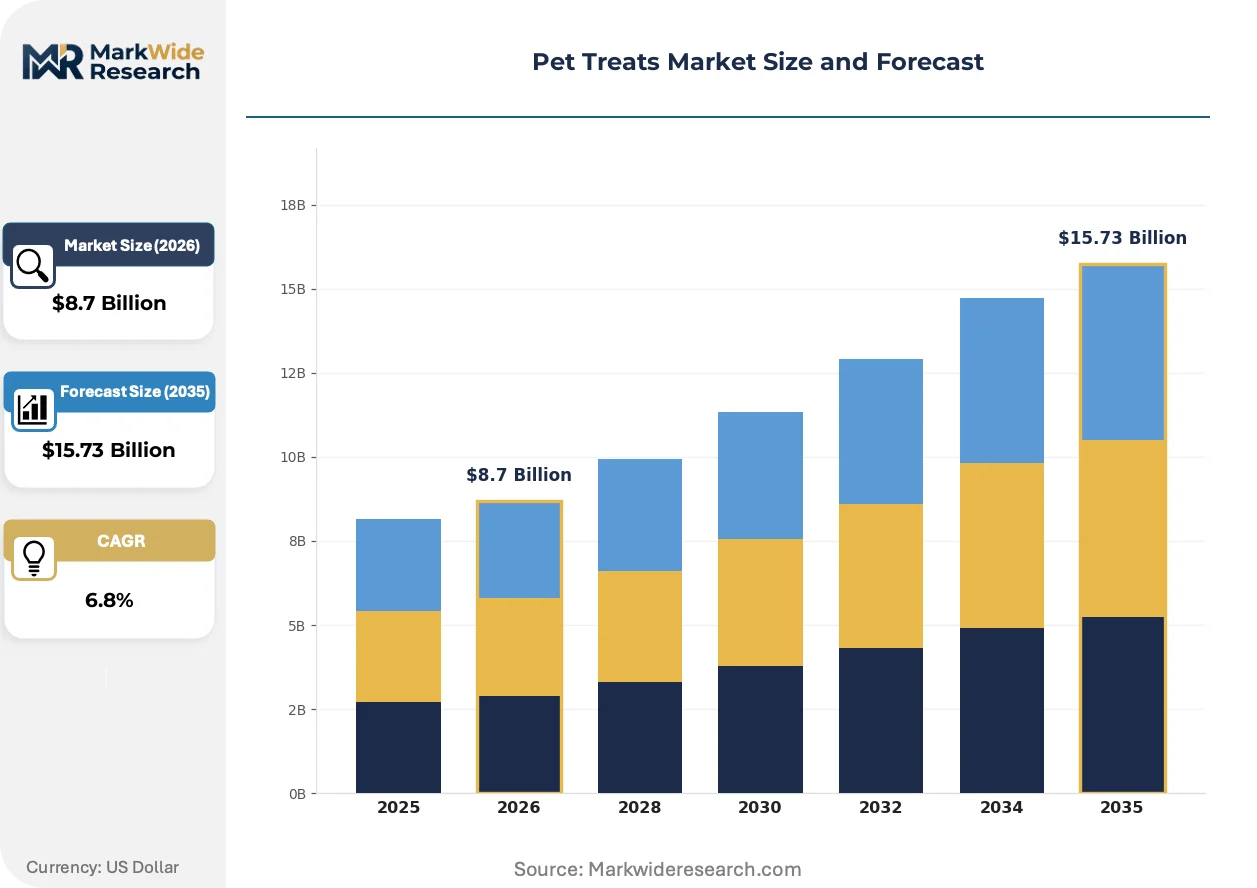
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biscuits, Chews, Jerky, Soft Treats Ingredient Type: Meat-Based, Grain-Free, Organic, Functional Animal Type: Dogs, Cats, Small Mammals, Birds Packaging Type: Pouches, Tubs, Bags, Boxes |
| Companies Covered | Mars, Incorporated, Nestlé Purina PetCare, Colgate-Palmolive Company, General Mills, Inc., The J.M. Smucker Company, Spectrum Brands, Inc., Wellness Pet, LLC, Merrick Pet Care, VAFO Group a.s., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Treats Market Emerging Trajectories
Reformulation priorities are converging on ingredient transparency and processing integrity, with manufacturers racing to substantiate claims through third-party certification and blockchain-enabled supply chain visibility.
Precision fermentation is integrating microbial protein production into treat manufacturing at pilot scale. Specialty ingredient suppliers in Denmark and the Netherlands are commissioning commercial facilities. This technology is integrating novel protein streams that bypass agricultural land use constraints entirely.
The EU Green Deal's packaging sustainability directives are mandating recyclability and recycled content thresholds for flexible materials entering European retail channels. Brand owners face reformulation deadlines and compliance documentation burdens. Wet and fresh treat formats with shorter shelf lives are most affected, driving investment in barrier film innovation.
Subscription-based replenishment models are displacing conventional retail stocking patterns among urban millennial and Gen Z pet owners in the United States. Direct-to-consumer platforms capture preference data that informs personalized product curation. Veterinary endorsement channels remain the loyalty anchor for functional and prescription-adjacent segments.
Pet Treats Market Segmentation
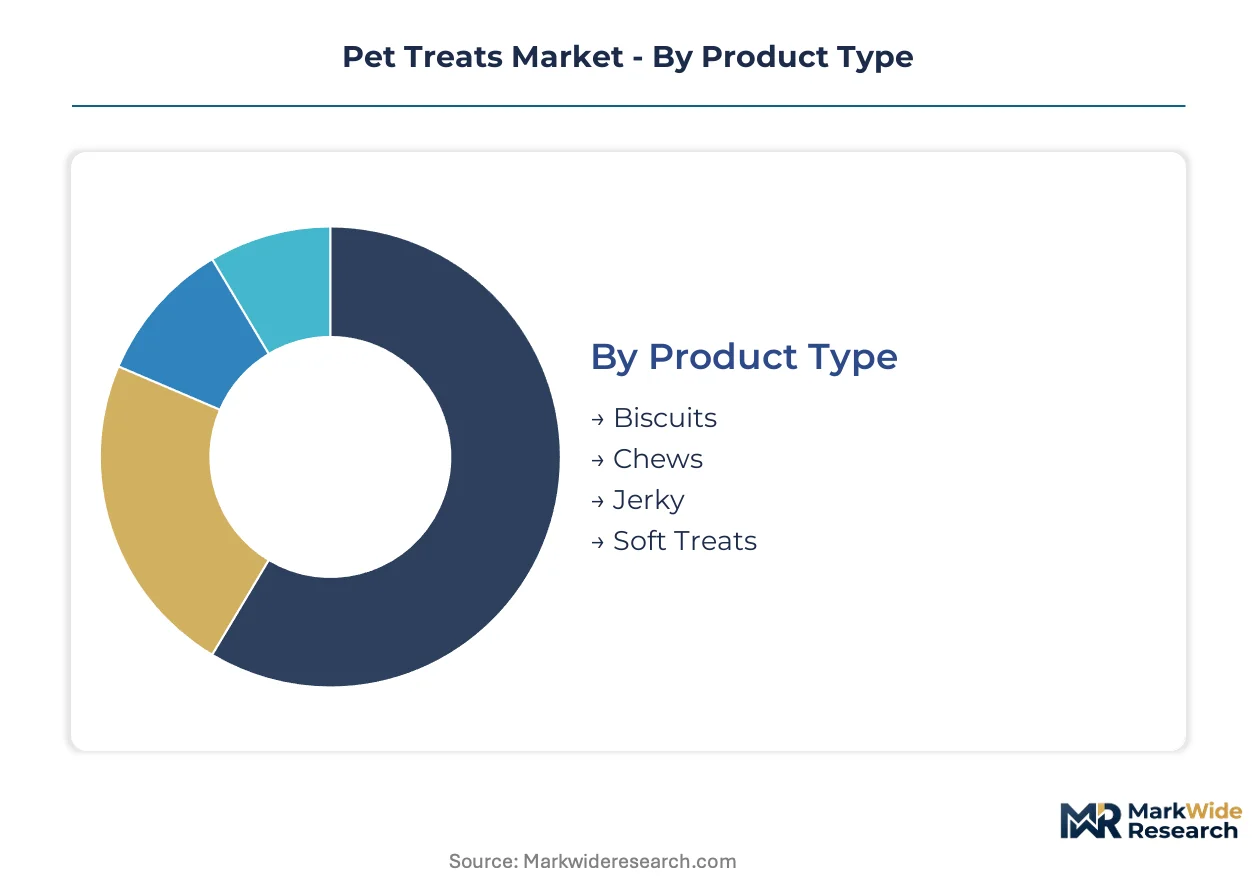
Pet treats manufacturers configure product portfolios around engagement duration, palatability thresholds, and health claim substantiation. Segmentation choices directly determine margin capture, with functional formats commanding veterinary endorsement premiums and soft textures penetrating senior pet demographics.
Product Type:
Volume concentrates in formats with extended shelf stability, while premium pricing accrues to products delivering measurable engagement or dental benefits.
- Biscuits:Shelf-stable formulations with moisture content below 15 percent, manufactured through extrusion or baking processes. Mass-market penetration in the United States runs deepest through grocery and mass merchandise channels, though growth is flattening as consumers migrate toward perceived health benefits.
- Chews:Extended-engagement products designed for dental abrasion and behavioral occupation. Veterinary endorsement in the United States validates premium positioning, with rawhide alternatives and dental chews capturing disproportionate margin pools in subscription e-commerce channels.
- Jerky:Dehydrated meat strips with concentrated protein density and high palatability. Single-ingredient sourcing appeals to clean-label seekers.
- Soft Treats:Moisture-rich formats at 20-30 percent water content, optimized for training applications and senior pets with dental compromise. Texture engineering demands specialized extrusion and enrobing equipment.
Mature deployment sits with Biscuits. Newer deployment is concentrated in Chews.
Ingredient Type:
Cost tier stratification separates commodity livestock inputs from certified specialty streams, with regulatory traceability requirements widening the compliance gap between tiers.
- Meat-Based:Conventional livestock proteins subject to USDA Federal Meat Inspection Act oversight and FDA Center for Veterinary Medicine safety protocols. Input cost volatility tracks feed grain markets and climate-driven supply disruptions in the United States.
- Functional:Probiotic, glucosamine, and omega fatty acid fortification validated through veterinary clinical channels. Prescription-adjacent positioning in the United States commands sustained premium pricing and locks in recurring purchase behavior.
- Grain-Free:Formulations excluding corn, wheat, and soy in response to canine dilated cardiomyopathy concerns and consumer preference shifts. FDA investigation into grain-free cardiomyopathy links has introduced formulation uncertainty.
- Organic:Certified inputs meeting USDA National Organic Program standards, with supply concentration in specific agricultural regions creating sourcing constraints.
Commodity volume anchors Meat-Based. Margin expansion is climbing the fastest in Functional.
Animal Type:
Application focus determines palatability engineering requirements and channel access, with veterinary endorsement channels concentrating on specific species.
- Dogs:Dominant species segment with formulation diversity spanning dental chews, training rewards, and joint-support soft treats. Humanization trends in the United States compress formulation standards toward human-grade processing.
- Cats:Finicky palatability thresholds demand specialized flavor masking and texture optimization. Smaller treat size requirements and concentrated nutrient density differentiate manufacturing parameters.
- Small Mammals:Niche formulations for rabbits, guinea pigs, and hamsters with species-specific digestive constraints. Hay-based and compressed fiber treats dominate.
- Birds:Seed and nut-based reward products with foraging behavior integration. Limited formulation innovation relative to mammalian segments.
Established manufacturing infrastructure serves Dogs. Emerging specialization is concentrating in Cats.
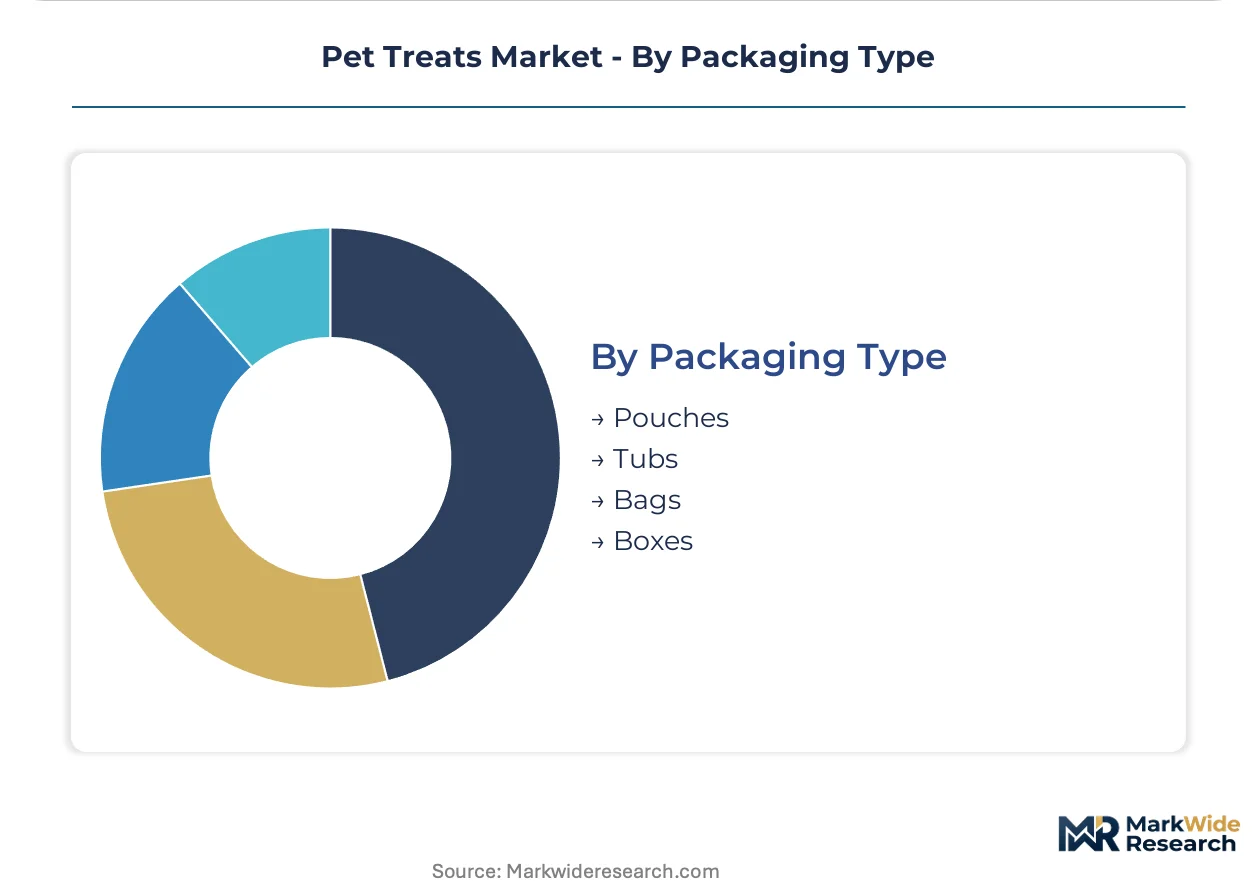
Packaging Type:
Supply concentration in flexible film conversion shapes cost structures, with sustainability mandates in Europe forcing material transitions.
- Pouches:Stand-up and flat flexible formats with resealability for moisture-sensitive soft treats. EU Green Deal recyclability thresholds are accelerating mono-material and compostable film development.
- Bags:Multi-wall paper and plastic laminates for bulk biscuit and dry treat distribution. Established recycling infrastructure in the United States favors this format.
- Tubs:Rigid plastic containers for semi-moist and fresh treat formats requiring barrier protection. Cold-chain compatibility constraints limit distribution radius.
- Boxes:Corrugated and paperboard secondary packaging for gift sets and premium assortment retail presentation. E-commerce shipping durability requirements drive structural specifications.
Conventional volume flows through Bags. Sustainability-driven transition is accelerating in Pouches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones in the United Arab Emirates and bonded logistics parks in Shanghai are accelerating pet treat manufacturing concentration through tariff exemptions and streamlined customs processing.
United States
E-commerce subscription platforms and veterinary endorsement channels concentrate demand in metropolitan corridors stretching from Boston to Atlanta. FDA Center for Veterinary Medicine traceability requirements are compressing compliant manufacturer counts. Kansas and Nebraska host integrated protein processing clusters where captive rendering operations feed treat production lines.
Germany
Human-grade processing standards and clean-label preference premiums drive formulation upgrades across Bavaria and North Rhine-Westphalia. EU Green Deal packaging sustainability directives are mandating mono-material transitions by 2030. Hamburg anchors northern European distribution with cold-chain logistics infrastructure serving fresh treat formats.
China
Domestic pet ownership expansion in tier-one cities is outpacing indigenous supply capacity, opening import substitution opportunities. SAMR feed safety registration requirements are tightening facility inspection protocols. Yangtze River Delta manufacturing zones near Shanghai concentrate contract manufacturing for export markets.
United Kingdom
Post-Brexit veterinary health certificates are fragmenting cross-border supply relationships with EU suppliers. FSA and Defra feed hygiene regulations maintain alignment with retained EU law while permitting divergence. Midlands production clusters around Leicester and Nottingham retain biscuit and extruded treat specialization.
Brazil
Beef byproduct abundance and rendering infrastructure create input cost advantages for meat-based treat exports. MAPA agricultural inspection protocols govern pet food facility licensing and ingredient traceability. São Paulo state industrial parks host the largest concentration of South American pet treat manufacturing capacity.
Pet Treats Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with veterinary-channel exclusivity concentrating margin capture among integrated nutrition houses. Three tiers structure competitive positioning: multinational CPG conglomerates with captive ingredient sourcing, mid-scale regional formulators with veterinary endorsement relationships, and private-label contractors serving retail chains. M&A activity targets functional ingredient capabilities and direct-to-consumer platform assets, while capacity expansion concentrates in USDA-inspected facilities with export certification.
Within the conglomerate tier, Mars, Incorporated and Nestlé Purina PetCare exemplify integrated supply chain control spanning multiple continents. General Mills, Inc. occupies a position bridging human food processing standards with pet applications. These three entities anchor the premium-price segment through veterinary channel access and prescription-adjacent product lines.
| Leading Market Players |
|---|
| Mars, Incorporated |
| Nestlé Purina PetCare |
| Colgate-Palmolive Company |
| General Mills, Inc. |
| The J.M. Smucker Company |
| Spectrum Brands, Inc. |
| Wellness Pet, LLC |
| Merrick Pet Care |
| VAFO Group a.s. |
| Others |
Supply Flow & Price Mechanics
Captive rendering operations across Kansas and Nebraska anchor both supply security and margin defense for integrated manufacturers. Mars, Incorporated and Nestlé Purina PetCare leverage backward integration into protein processing to buffer against livestock input volatility while sustaining veterinary-channel premium positioning.
Pricing Analysis
Volume flows through mass-market biscuits at economy tiers while margin pools concentrate in functional chews and prescription-adjacent soft treats. Three-tier pricing structure across premium, standard, and economy levels separates veterinary-endorsed functional formats from clean-label grain-free mid-tier and commodity meat-based economy products. Cost compression in standard tiers is intensifying because plant-based protein alternatives remain capacity-constrained at commercial scale. Mass-market grocery buyers exhibit highest price sensitivity; subscription e-commerce subscribers and veterinary channel purchasers show lowest.
Supply Chain Analysis
Direct-to-consumer channels handle urban millennial and Gen Z demand through personalized nutrition algorithms and auto-replenishment schedules. Geographic supply concentration clusters in the United States, Brazil, and China; protein rendering draws from Kansas-Nebraska livestock corridors, São Paulo beef byproduct abundance, and Yangtze River Delta contract manufacturing. Raw material dependencies center on conventional livestock proteins, plant-based alternative proteins, and functional additives including probiotics and glucosamine. Single-source vulnerability in premium organic ingredient sourcing amplifies disruption cascades from localized drought or disease.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players are pursuing captive protein rendering and cold-chain infrastructure to defend margin structures against input volatility and human-grade processing standards.
For Market Incumbents: To counter plant-based protein startups and cultured meat pioneers, lock in exclusive veterinary endorsement relationships through clinical validation funding. Expand USDA-inspected rendering capacity in the Kansas-Nebraska corridor to secure captive supply of meat-based inputs. Deepen subscription platform data assets to personalize functional treat curation and reduce churn. For New Entrants and Emerging Players: Begin with senior pet soft treats in Japan and Western Europe where aging demographics and premium pricing tolerance create white-space. Target direct-to-consumer subscription models in United States metropolitan corridors to bypass entrenched retail shelf access barriers. Lead with joint-support fortification and high-palatability texture engineering validated through veterinary sampling programs. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational CPG conglomerates seeking functional ingredient capabilities and DTC platform assets. Long-term viability favors targets with USDA export certification and proprietary veterinary clinical data. Watch FDA reclassification of nutritional adequacy versus snack categorization as the critical inflection signal for prescription-channel access value.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Channel Exclusivity | Locks in prescription-adjacent positioning and validates premium pricing through clinical endorsement. |
| Cold-Chain Infrastructure Investment | Enables human-grade processing standards and fresh treat formats demanded by urban subscribers. |
| Functional Ingredient Integration | Captures margin pools in probiotic and glucosamine fortification with veterinary validation. |
| Subscription Platform Development | Builds recurring revenue and consumption habituation through personalized auto-replenishment algorithms. |
| Sustainable Packaging Transition | Secures European retail access under EU Green Deal mono-material and compostable mandates. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with veterinary nutrition directors, pet food R&D scientists, retail category buyers, and subscription platform operators combined with FDA Center for Veterinary Medicine registration databases, USDA facility inspection records, and SAMR feed safety filings. Bottom-up product-level volume builds triangulated against top-down macroeconomic demand indicators.
Reconciliation of shipment data, import-export flows, and channel inventory movements informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, ingredient category, animal species, packaging format, and distribution channel. CAGRs derived from regression analysis of historical volume trends adjusted for regulatory inflection points and technology adoption curves. Veterinary endorsement penetration rates and e-commerce subscription growth curves served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; functional and prescription-adjacent categories carry tighter precision than commodity meat-based economy tiers. Forecasts reflect assumptions regarding FDA traceability compliance timelines and EU packaging sustainability transition deadlines. Periodic stress-testing of base assumptions is recommended given regulatory reclassification risks and input cost volatility from climate-driven supply disruptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Fresh and Frozen Dog Food Market
Pet Care Products
North America Pet Diet Market
Pet Care Products
Kitten Milk Replacer and Formula Market
Pet Care Products
Pet Sitting Market
Pet Care Products
Pet Waste Removal Services Market
Pet Care Products
Therapeutic Diet for Pet Market
Pet Care Products
Dog Brush Market
Pet Care Products
China Cat Litter Market
Pet Care Products
Spain Pet Boarding Market
Pet Care Products
Cat Accessories Market
Pet Care Products
North America Functional Pet Treat Market
Pet Care Products
Dog Hoodies Market
Pet Care Products
Cat Backpacks Market
Pet Care Products
Dog Vitamins Market
Pet Care Products
Thunder Jacket for Dogs Market
Pet Care Products
Tofu Cat Litter Market