
 Vegan Pet Food Market | 2026-2036
Vegan Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Pet Food Market Outlook
Single-serve pouch formats is rebalancing buyer choice away from bulk bags toward portion-controlled, subscription-friendly configurations. V-Dog leverages its direct-to-consumer channel to sustain recurring revenue in this format. Wild Earth anchors its position through biotechnology-driven protein development that differentiates from commodity plant inputs. Benevo competes in European specialty retail with certified organic formulations that occupy premium shelf space.
Vegan pet food denotes nutritionally complete formulations excluding animal-derived ingredients, typically comprising protein isolates from peas, lentils, or cultured sources alongside supplemented taurine, L-carnitine, and vitamin B12 to meet AAFCO or FEDIAF standards. Dry food leads volume due to logistics efficiency and extended shelf stability, while wet food and treats capture margin pools through premium positioning and palatability advantages that drive repeat purchase rates among discerning pet owners.
The FDA and USDA oversee labeling and safety in the United States, while the EU Green Deal and REACH frameworks govern ingredient sustainability and chemical safety across European supply chains. These bodies elevate compliance costs but simultaneously filter out low-credibility entrants, concentrating market access among substantiated formulations. Stakeholders must monitor evolving amino acid testing protocols and veterinary clinical validation requirements as the threshold for scientific credibility rises.
Market Dynamics
Biotechnology-derived protein platforms are compressing the cost-performance gap between plant-based and conventional animal inputs, forcing incumbent suppliers to recalibrate formulation economics or cede premium positioning to precision-fermentation entrants.
Growth Catalysts
- EU Green Deal sustainability mandates:Binding carbon-reduction targets across European supply chains accelerate ingredient sourcing from domestic legume and grain producers, reducing import dependency and transport emissions.
- Urban millennial pet ownership density:Concentrated demand in Berlin, London, and New York creates viable economies of scale for refrigerated distribution networks previously uneconomical outside coastal metros.
- Precision fermentation protein yields:Cultured fungal and algal biomass achieves amino acid completeness without agricultural land use, unlocking supply expansion independent of crop commodity cycles.
Market Restraints
- Pea protein concentrate price volatility:Competition from human-grade plant meat and aquafeed sectors strains finite North American and Baltic processing capacity.
- Taurine synthesis supply concentration:Three chemical manufacturers in China control pharmaceutical-grade taurine supply, creating input vulnerability for AAFCO-compliant formulations.
- Veterinary clinical validation gaps:Longitudinal feeding studies spanning multi-year feline and canine life stages remain sparse, constraining regulatory submission packages for novel protein sources.
Strategic Opportunities
- Subscription-direct channel penetration:Portion-controlled pouch formats bypass retail slotting fees and capture lifetime value through automated replenishment algorithms.
- Regenerative agriculture certification alignment:USDA Organic and Regenerative Organic Certified standards open premium shelf positioning in natural grocery channels.
- Biotechnology-pharma convergence:Partnerships between pet nutrition formulators and human food biotech platforms transfer intellectual property from cultivated meat R&D into companion animal applications.
Industry Challenges
- AAFCO and FEDIAF protocol harmonization:Divergent amino acid bioavailability testing standards between North American and European regulators force duplicate analytical expenditure for multinational brands.
- Cold-chain infrastructure capex:Wet food and fresh-frozen formats require refrigerated warehousing and last-mile logistics investments that dry-food incumbents lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Pet Food Market |
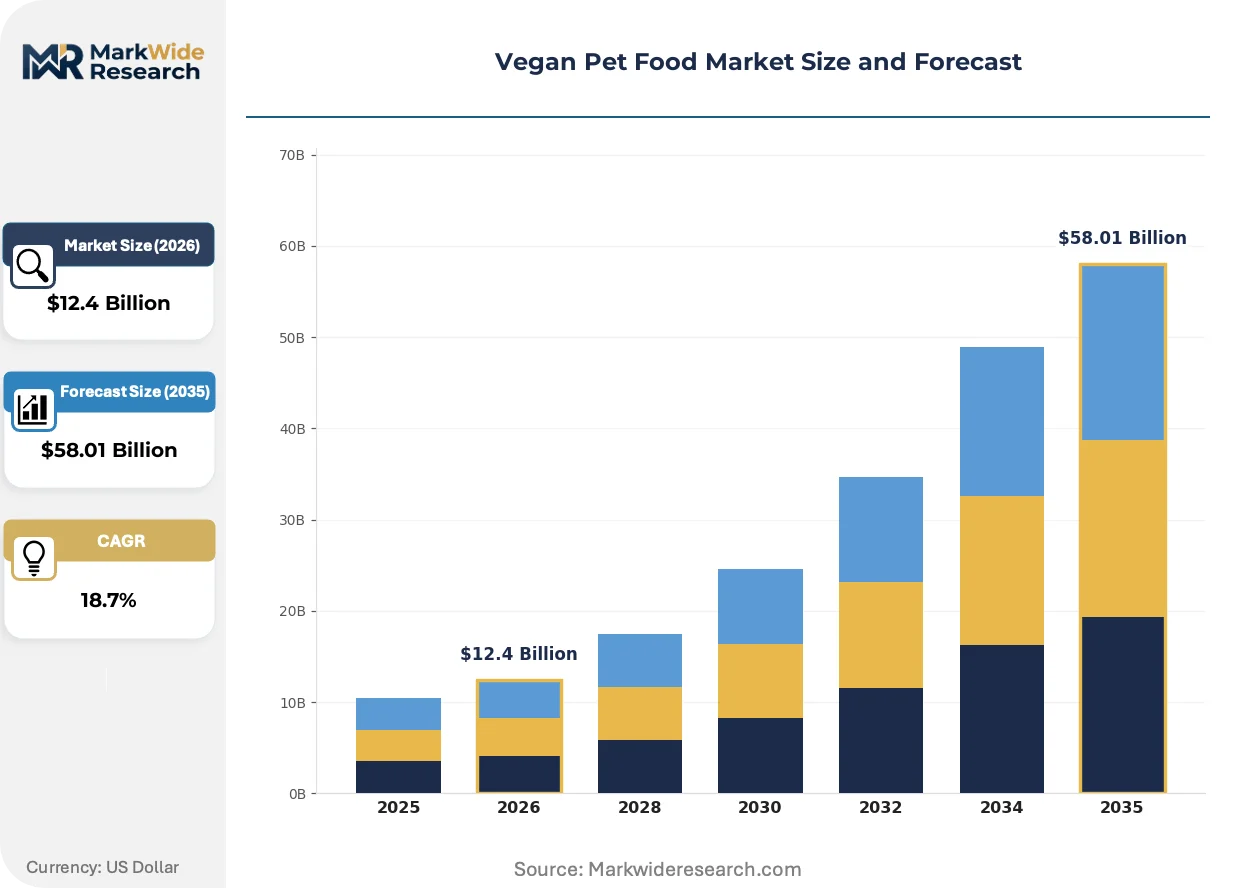
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $58.01 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Supplements End User: Pet Owners, Veterinarians, Retailers, Distributors Packaging Type: Bags, Cans, Pouches, Tubs Ingredient Source: Plant-Based, Whole Foods, Grains, Legumes |
| Companies Covered | V-Dog, Benevo, Wild Earth, Halo Pets, Evolution Diet, Yarrah Organic Petfood, Omni Pet Ltd, Ami Pet Foods, Vegdog, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Pet Food Market Strategic Shifts
Formulation science and distribution infrastructure are evolving in parallel, with biotechnology reducing input constraints while direct-to-consumer platforms compress traditional retail intermediation.
Precision-fermentation protein production is overtaking commodity crop isolates as the dominant technical pathway for complete amino acid profiles. Early adopters in the premium subscription segment are shifting procurement toward biomass-derived inputs at twice the pace of conventional retail buyers. This transition is compressing the price premium between vegan and conventional formulations from triple-digit percentages toward functional parity.
REACH chemical safety frameworks and the EU Green Deal's deforestation-free supply chain requirements are mandating granular ingredient traceability across European import channels. Manufacturers must now document legume and grain origins to batch level, elevating compliance systems investment. Wet food producers with integrated European milling operations are responding fastest, while import-dependent dry-food brands face extended certification timelines.
Subscription-based replenishment models are displacing episodic retail purchasing among urban companion animal owners. Veterinary endorsement channels and specialty pet retailers are losing traffic to algorithm-driven auto-ship platforms that calibrate portion delivery to individual animal metabolic data. This behavioral shift concentrates most visibly in German and United Kingdom metropolitan markets where digital-native millennial ownership rates peak.
Vegan Pet Food Market Segmentation
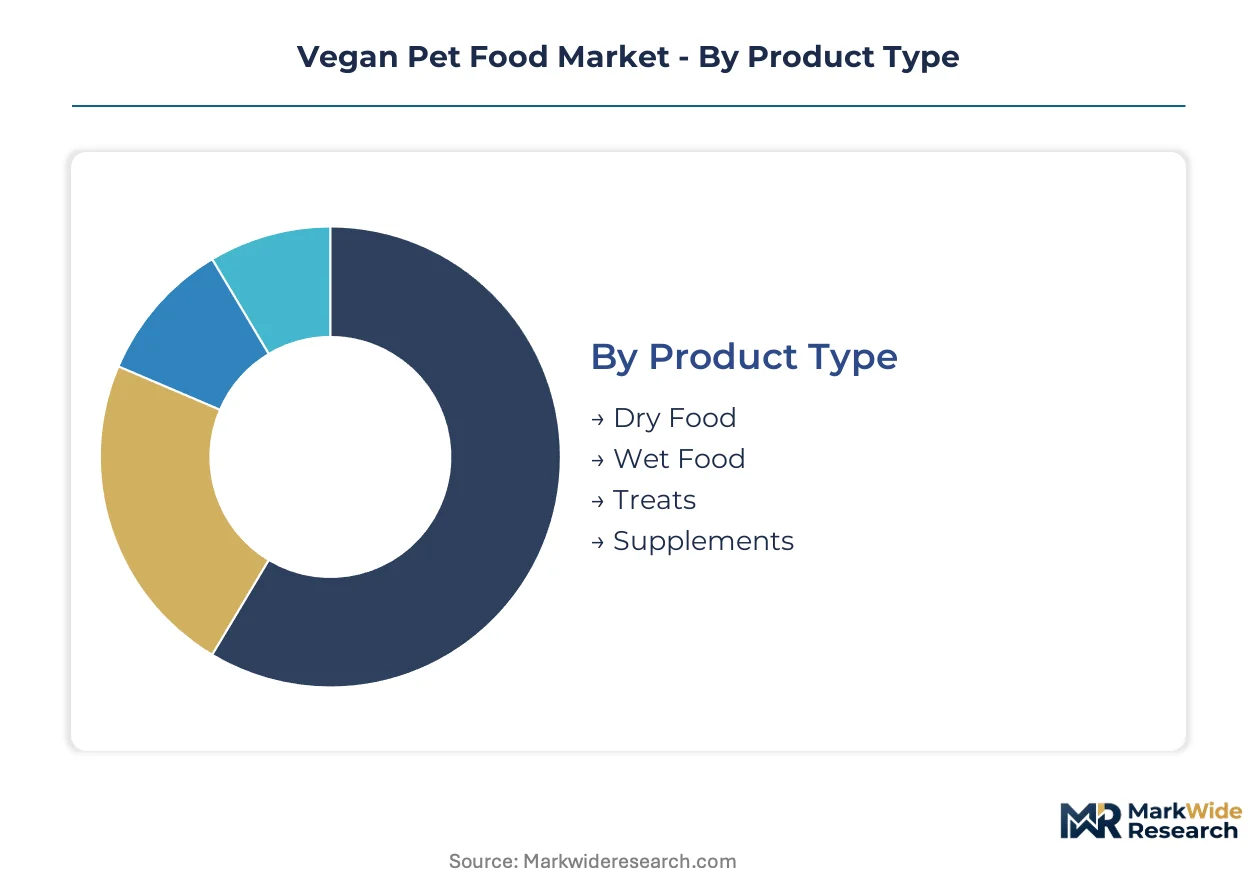
Vegan pet food segmentation reveals how formulation science, distribution channels, and packaging innovation intersect to capture distinct buyer willingness-to-pay thresholds. Category boundaries are blurring as biotechnology-derived proteins and subscription-direct models reshape traditional product hierarchies.
Product Type:
Pet owners prioritize convenience against nutritional completeness when selecting format, with logistics economics and palatability driving divergent purchasing patterns across household types.
- Dry Food:Extruded kibble formulations achieve AAFCO nutrient density through thermal processing of pea protein isolates and fortified vitamin premixes. Demand concentrates in multi-pet households across suburban United States markets where bulk purchasing and extended shelf stability reduce per-meal cost. Logistics efficiency sustains its volume leadership despite lower margins.
- Wet Food:Retorted cans and trays deliver moisture-rich nutrition with enhanced palatability for senior animals and selective eaters. Urban millennial owners in Berlin and London drive adoption through subscription-direct channels that accommodate refrigerated last-mile delivery. Premium positioning captures margin pools unavailable to dry alternatives.
- Treats:Functional rewards and training aids incorporate limited ingredient profiles for allergy-prone companion animals.
- Supplements:Taurine, L-carnitine, and B12 boosters address nutritional gaps in homemade or partial plant-based feeding regimens.
Volume sits with dry food; growth tilts toward wet food.
End User:
Channel control determines pricing power, with veterinary endorsement and algorithm-driven subscription platforms extracting premium capture beyond conventional retail intermediation.
- Pet Owners:Direct purchasers evaluate palatability, ingredient transparency, and subscription convenience when committing to plant-based feeding regimens. German and United Kingdom metropolitan markets exhibit highest digital-native adoption rates for auto-replenishment platforms.
- Veterinarians:Clinical endorsement channels require longitudinal feeding study documentation and AAFCO or FEDIAF substantiation to recommend novel protein formulations. Regulatory submission packages constrain brand access to this high-trust segment.
- Retailers:Specialty pet and natural grocery channels demand certified organic or regenerative agriculture credentials for premium shelf positioning.
- Distributors:Cold-chain logistics providers and conventional dry-goods wholesalers segment by temperature requirement and minimum order thresholds.
Trust concentrates with veterinarians; transaction velocity concentrates with pet owners.
Packaging Type:
Format selection reflects inventory turnover economics against portion control convenience, with single-serve configurations commanding subscription channel preference.
- Bags:Multi-kilogram flexible packaging dominates dry food distribution through retail and e-commerce fulfillment centers. Cost efficiency sustains penetration in price-sensitive segments.
- Cans:Steel and aluminum containers preserve wet food sterility while enabling ambient distribution without refrigerated infrastructure.
- Pouches:Flexible single-serve formats reduce food waste and enable algorithm-driven portion calibration for individual animal metabolic profiles. Urban subscription channels in London and New York show fastest adoption.
- Tubs:Refrigerated fresh-frozen formats target premium positioning in natural grocery and direct-to-consumer channels.
Scale sits with bags; margin expansion sits with pouches.
Ingredient Source:
Supply chain traceability requirements under REACH and EU Green Deal frameworks are elevating sourcing transparency to a competitive differentiator.
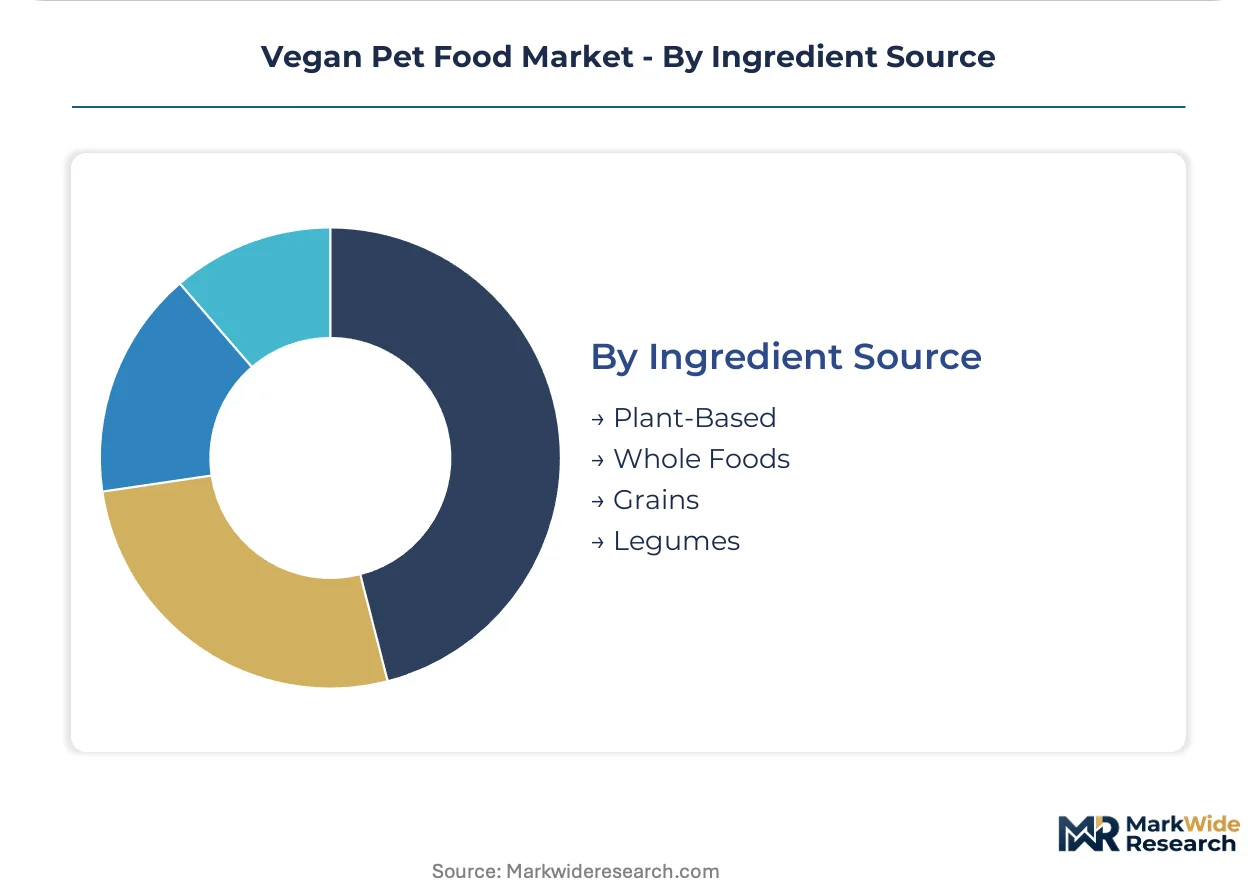
- Plant-Based:Protein isolates from peas, lentils, and fava beans comprise the dominant input category, with North American and Baltic processing capacity constraining supply expansion.
- Whole Foods:Minimally processed vegetables, fruits, and grains appeal to owners seeking ingredient recognizability over engineered nutrition.
- Grains:Oats, rice, and quinoa provide carbohydrate energy and fiber content in dry formulations.
- Legumes:Domestic European sourcing under EU Green Deal sustainability mandates reduces import dependency and transport emissions for regional formulators.
Volume sits with plant-based isolates; differentiation sits with legume traceability credentials.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in North American and European processing hubs while consumption concentrates in urban centers where millennial pet ownership densities sustain premium pricing. This geographic disconnect shapes logistics investments and regulatory compliance strategies across the value chain.
Germany
Berlin and Hamburg drive subscription-direct adoption among digital-native pet owners seeking portion-controlled wet food formats. The EU Green Deal mandates deforestation-free supply chain documentation, forcing domestic formulators to source legumes from certified European growers. Bavarian milling operations integrate traceability systems fastest, capturing premium shelf positioning in natural grocery channels.
United States
Coastal metros including New York, Los Angeles, and Seattle anchor refrigerated last-mile infrastructure for fresh-frozen formats. FDA labeling requirements and AAFCO amino acid testing protocols elevate compliance costs for novel protein entrants. Pacific Northwest biotechnology clusters host precision-fermentation R&D partnerships transferring cultivated meat intellectual property into companion animal applications.
United Kingdom
London metropolitan demand concentrates in algorithm-driven auto-replenishment platforms displacing specialty retail traffic. FEDIAF nutritional substantiation requirements constrain veterinary endorsement access for brands lacking longitudinal feeding studies. Manchester and Birmingham distribution hubs upgrade cold-chain capacity to serve wet food subscription growth.
Netherlands
Amsterdam-Rotterdam logistics corridors leverage port infrastructure for plant protein isolate imports from Baltic and North American processors. REACH chemical safety frameworks mandate batch-level ingredient traceability elevating compliance system investments. Wageningen agricultural research clusters support domestic legume breeding programs reducing import dependency under EU sustainability targets.
Canada
Toronto and Vancouver urban centers exhibit fastest adoption of certified organic formulations among North American markets. Health Canada and CFIA oversight of novel pet food ingredients parallels FDA frameworks while maintaining distinct submission requirements. Prairie province grain production supplies regional dry food manufacturing with oats and pulse crops meeting regenerative agriculture certification standards.
Vegan Pet Food Market Competitive Environment
The competitive structure tilts toward biotechnology-enabled specialists and direct-to-consumer platforms over conventional retail-dependent incumbents. Market access concentrates among formulators achieving AAFCO or FEDIAF substantiation for novel protein sources. Three archetypes dominate: precision-fermentation protein developers, subscription-direct brands with captive customer data, and European organic-certified specialists leveraging regenerative agriculture credentials. Dominant competitive moves include strategic partnerships between pet nutrition formulators and human food biotech platforms, plus cold-chain infrastructure investments enabling fresh-frozen format expansion.
Within the biotechnology-specialist tier, Wild Earth exemplifies precision-fermentation protein development, while V-Dog anchors the direct-to-consumer subscription archetype with recurring revenue models. Benevo occupies the European organic-certified position, representing premium shelf access through sustainability credentials. These three companies illustrate how divergent capability investments—biotechnology R&D, algorithm-driven customer acquisition, and regenerative supply chain certification—create non-overlapping competitive moats despite serving identical end-user segments.
| Leading Market Players |
|---|
| V-Dog |
| Benevo |
| Wild Earth |
| Halo Pets |
| Evolution Diet |
| Yarrah Organic Petfood |
| Omni Pet Ltd |
| Ami Pet Foods |
| Vegdog |
| Others |
Value Chain & Pricing Dynamics
Algorithm-driven auto-replenishment preferences among urban millennial pet owners force supply chains toward refrigerated last-mile infrastructure and portion-calibrated pouch formats, compressing margins for dry-food incumbents while enabling subscription-native brands to capture lifetime value premiums.
Pricing Analysis
Margin tightening in wet food and fresh-frozen tiers reflects cold-chain capex burdens and pharmaceutical-grade taurine synthesis concentration among three Chinese manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates certified organic formulations with regenerative agriculture credentials from commodity plant isolates and private-label alternatives. Pricing pressure stems from pea protein concentrate competition with human-grade plant meat sectors straining finite North American processing capacity. Price-sensitive multi-pet households in suburban United States markets gravitate toward bulk dry formats, while least-sensitive urban owners in Berlin and London absorb premiums for biotechnology-derived protein subscriptions.
Supply Chain Analysis
Regional distribution centers in the Netherlands, Germany, and the United Kingdom anchor hub-and-spoke patterns for European wet food fulfillment, while Pacific Northwest biotechnology clusters in the United States host precision-fermentation R&D partnerships. Raw material dependencies center on Baltic and North American pea protein isolate processing, Chinese pharmaceutical-grade taurine synthesis, and domestic European legume sourcing under EU Green Deal mandates. Supply chain risk concentrates in single-source vulnerability for amino acid premix inputs. Distribution runs through algorithm-driven direct-to-consumer platforms displacing conventional retail intermediation in metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vegan pet food sector sits in a protein-platform transition where precision-fermentation biomass displaces commodity crop isolates as the dominant technical pathway for complete amino acid profiles.
For Market Incumbents: To counter precision-fermentation entrants compressing the cost-performance gap, legacy dry-food manufacturers must backward integrate into cold-chain infrastructure for fresh-frozen format expansion and secure veterinary endorsement through longitudinal feeding study investment. Capacity addition in refrigerated warehousing near London and New York metropolitan markets defends positioning against subscription-native competitors. For New Entrants and Emerging Players: Direct-to-consumer algorithmic replenishment routes offer lowest customer acquisition friction for biotechnology-enabled specialists targeting underserved feline formulations, where clinical validation gaps constrain incumbent access. White-space concentrates in multi-year life-stage studies for novel protein sources, with veterinary endorsement channels in Germany and the United Kingdom representing the most penetrable high-trust segment. For Investors and Strategic Acquirers: The window for entry favors precision-fermentation protein developers with captive intellectual property from human food biotech platforms and subscription-direct brands with algorithmic customer data moats. Long-term viability hinges on regulatory submission packages achieving AAFCO or FEDIAF substantiation for cultured protein sources. Watch for harmonization protocols between North American and European amino acid bioavailability testing standards as the inflection signal for multinational scale economics.| Strategic Initiative | Industry Significance |
|---|---|
| Precision-Fermentation Protein Scale-Up | Wild Earth's biotechnology platform transfers cultivated meat R&D into companion animal applications, compressing vegan-conventional price premiums. |
| Cold-Chain Infrastructure Partnership | Refrigerated last-mile networks in Berlin and London enable wet food subscription models displacing specialty retail traffic. |
| Regenerative Agriculture Certification | Benevo's USDA Organic and Regenerative Organic Certified credentials secure premium shelf positioning in natural grocery channels. |
| Direct-to-Consumer Platform Integration | V-Dog's algorithm-driven auto-ship algorithms capture lifetime value through portion-calibrated pouch formats bypassing slotting fees. |
| Veterinary Clinical Validation Investment | Longitudinal feeding studies spanning multi-year feline and canine life stages unlock high-trust endorsement channels constraining competitor access. |
Study Parameters
Document review covered EU Green Deal implementation frameworks, FDA AAFCO submission guidelines, and REACH chemical safety protocols, complemented by interviews with pet nutrition formulators, veterinary clinical researchers, specialty retail category buyers, cold-chain logistics operators, and precision-fermentation biotechnology executives. Secondary validation drew from FEDIAF nutritional substantiation databases, customs records of plant protein isolate trade flows, and SEC filings of publicly traded pet food manufacturers. Bottom-up segmentation modeling triangulated against top-down demand aggregation from metropolitan pet ownership density data.
Cross-referencing historical adoption curves of human-grade plant meat with panel input from subscription-platform operators shaped the analytical framework across the analysis window. Segmentation dimensions modeled included product format (dry, wet, treats, supplements), distribution channel (direct-to-consumer, veterinary, specialty retail), ingredient source (plant-based isolates, whole foods, biotechnology-derived), and packaging configuration (bags, cans, pouches, tubs). CAGRs derived from iterative convergence of supply-side capacity expansion timelines and demand-side urban millennial ownership projections, with precision-fermentation protein yield curves and EU deforestation-free supply chain compliance costs as industry-specific forecast inputs.
Inputs from regulatory filing databases and biotechnology R&D partnership announcements were available through the study window; gaps in longitudinal clinical feeding study publication introduce uncertainty bands around veterinary endorsement penetration assumptions. Forecasts reflect documented assumptions regarding amino acid bioavailability testing protocol harmonization and cold-chain infrastructure investment cadence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Dog Shampoo Market
Pet Care Products
Dog Muzzle Market
Pet Care Products
Household Pet Water Dispenser Market
Pet Care Products
Cat Window Perches and Wall Shelves Market
Pet Care Products
Cat Litter Market
Pet Care Products
GCC Cat Food Market
Pet Care Products
Pet Hair Care Market
Pet Care Products
Pet Hotels Market
Pet Care Products
Pet Shampoo Market
Pet Care Products
Cat Food Toppers Market
Pet Care Products
Dehydrated Pet Food Market
Pet Care Products
Smart Pet Kennel Market
Pet Care Products
Parrot Cage Market
Pet Care Products
Cat Shampoo Market
Pet Care Products
Europe Pet Smart Tracker Market
Pet Care Products
Indonesia Pet Food Market