
 Cat Accessories Market | 2026-2036
Cat Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Cat Accessories Market Analytics
EU Green Deal material mandates is consolidating demand toward biodegradable and recycled-content accessories across European supply chains. Nestlé Purina leverages its integrated nutrition-to-accessories platform to cross-sell premium SKUs through veterinary channels. KONG Company dominates durable chew-toy engineering with proprietary rubber formulations that sustain repeat purchase rates. Petco Animal Supplies Inc. controls omnichannel distribution, anchoring private-label expansion through its 1,500-plus store network and same-day delivery infrastructure.
Cat accessories encompass functional and enrichment products engineered to feline behavioral specifications, including tensile-strength-tested collars with quick-release buckles and litter boxes optimized for particle size preference and odor encapsulation. The primary commercial purpose centers on pet welfare management, household hygiene maintenance, and owner emotional bonding through interactive play systems. Toys and scratching posts lead volume contribution as pet owners prioritize indoor enrichment, while eco-friendly quality grade segments attract margin concentration from sustainability-positioned buyers. Plastic material formulations face substitution pressure as wood and fabric alternatives capture premium positioning.
FDA oversees pet product safety labeling in the United States, while REACH governs chemical substance restrictions in European accessory manufacturing, and ISO 8124 shapes physical safety testing protocols for toys across export markets. These frameworks elevate compliance costs for smaller manufacturers while creating market access barriers that favor scaled producers with dedicated regulatory affairs functions. Stakeholders must monitor evolving extended producer responsibility mandates and biodegradable certification standards as determinants of future category segmentation and pricing architecture.
Market Dynamics
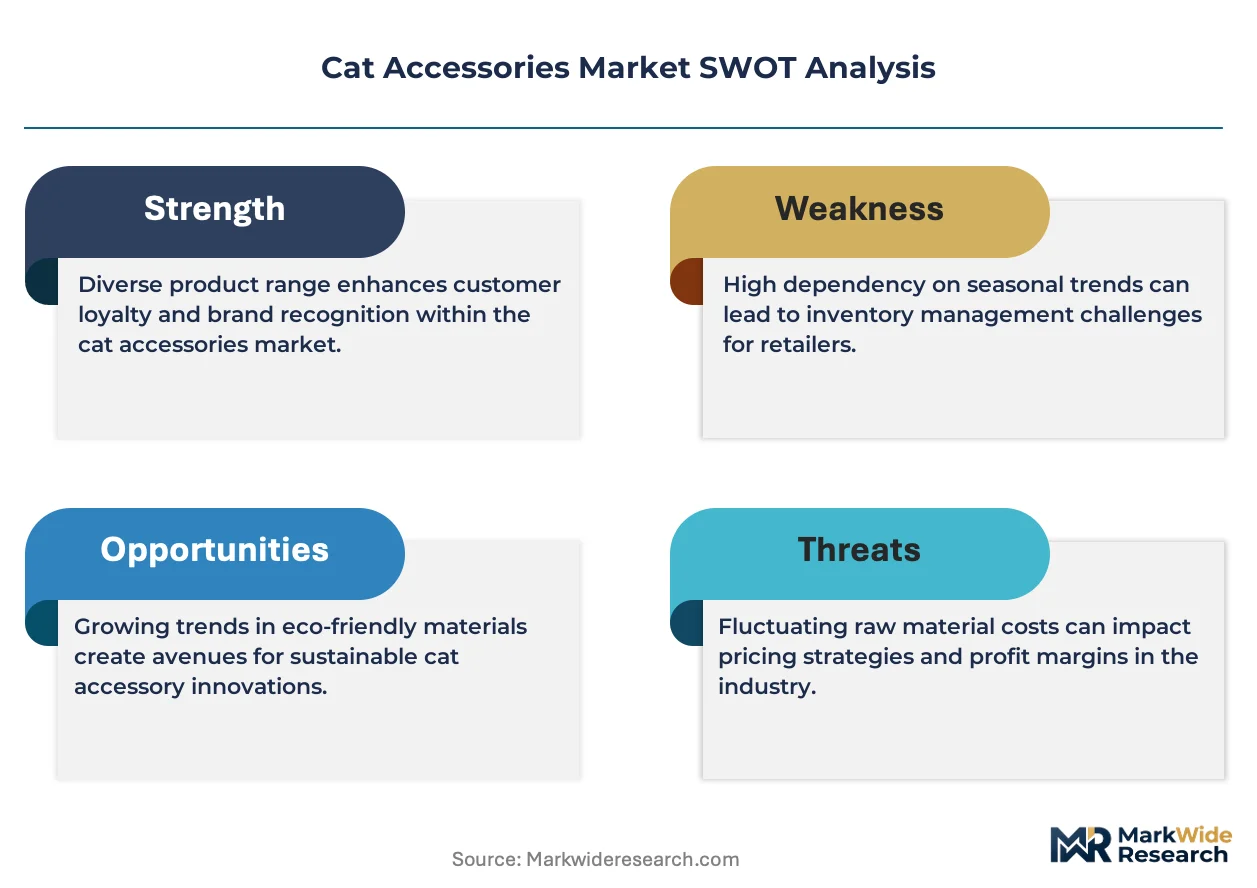
EU Green Deal material mandates are compressing plastic-dependent supply chains while redirecting sourcing capital toward biodegradable certification infrastructure. REACH chemical restrictions and extended producer responsibility frameworks are elevating compliance thresholds that favor scaled manufacturers with dedicated regulatory functions.
Growth Catalysts
- REACH chemical substance restrictions:European manufacturers are accelerating reformulation of rubber compounds and textile treatments to eliminate restricted phthalates and heavy metals, opening certified product premiums.
- Pet humanization in United States urban centers:Metropolitan cat owners are expanding spending on enrichment systems and wellness-calibrated accessories through specialized retail infrastructure.
- Recycled ocean plastic feedstock:Material recovery partnerships with coastal waste collection networks are securing lower-cost inputs for collar and toy production.
Market Restraints
- Natural rubber price volatility:Southeast Asian plantation supply disruptions and climate-induced yield compression are destabilizing input costs for chew-toy manufacturers.
- Biodegradable certification timeline friction:Multi-year OECD testing protocols for compostability claims are delaying product launches and freezing marketing claims.
- Silicone substitute threat:Medical-grade silicone formulations in premium feeding accessories are capturing margin share from conventional plasticware.
Strategic Opportunities
- EU Green Deal circular economy mandates:Extended producer responsibility schemes are creating first-mover advantage for closed-loop take-back program operators.
- Smart home integration convergence:RFID-enabled feeding systems and app-connected litter monitoring are unifying pet care with residential automation platforms.
- Veterinary channel direct distribution:Bypassing conventional retail through clinic-anchored subscription models is capturing wellness-positioned buyer segments.
Industry Challenges
- Feline behavioral science talent scarcity:Product development teams lack sufficient ethologists and veterinary behaviorists to validate enrichment efficacy claims.
- ISO 8124 toy safety testing backlog:Third-party laboratory capacity constraints are extending certification timelines for export-bound interactive products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cat Accessories Market |
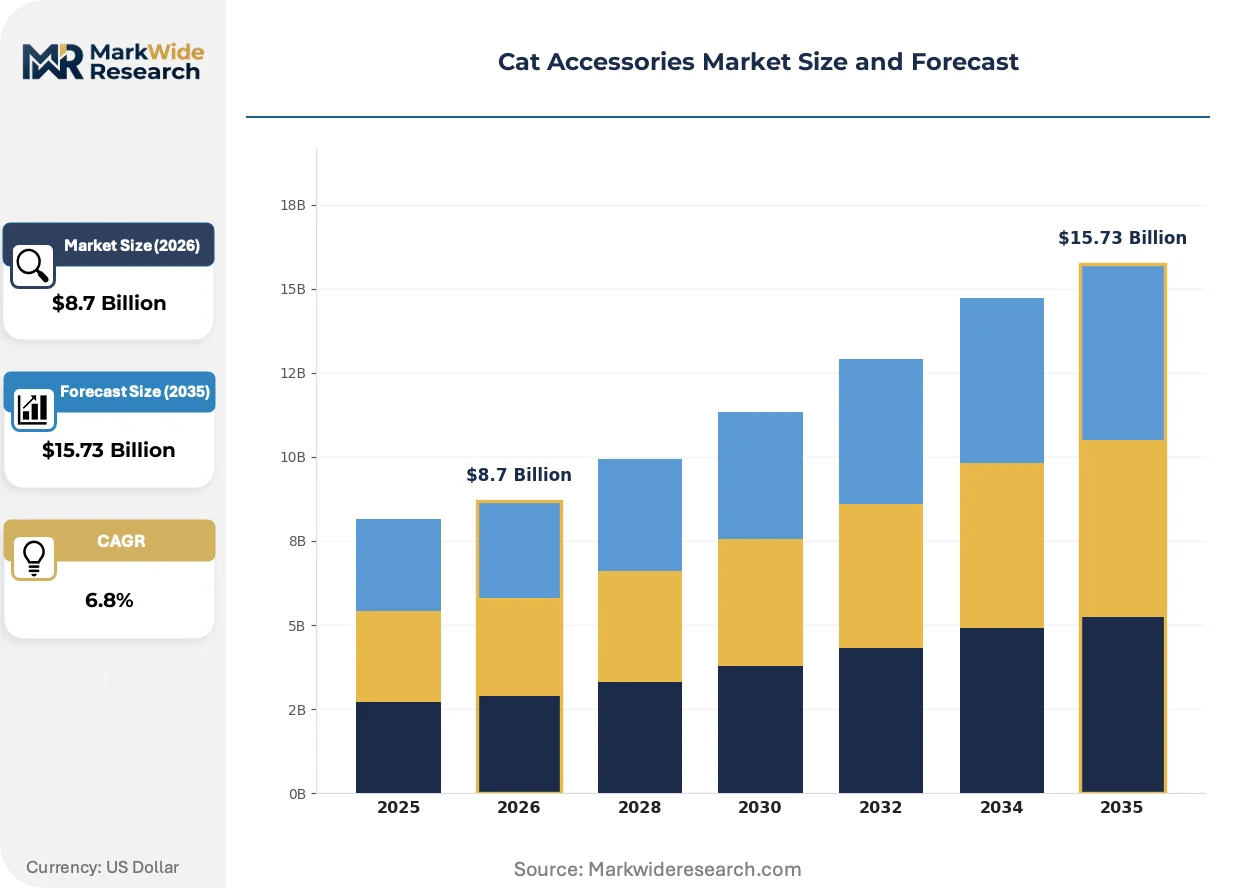
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Collars, Toys, Litter Boxes, Scratching Posts Material: Plastic, Fabric, Wood, Metal End User: Pet Owners, Retailers, Veterinarians, Groomers Quality Grade: Premium, Standard, Basic, Eco-Friendly |
| Companies Covered | PET PARENT, Simply Fido, Nestlé Purina, Petco Animal Supplies Inc., KONG Company, Coastal Pet Products Inc., Ferplast Spa, The Hartz Mountain Corporation, Spectrum Brands, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cat Accessories Market Evolving Landscape
Material science advances and regulatory chemistry restrictions are compressing conventional plastic formulations while elevating bio-based alternatives. Distribution is fragmenting across veterinary direct-to-consumer platforms and smart home integration channels.
Proprietary bio-rubber compounds derived from dandelion root latex are unifying sustainable sourcing with tensile performance specifications previously exclusive to petroleum-based formulations. Premium manufacturers in Germany and the Netherlands are adopting these materials for chew-toy lines at accelerated pace. The technology is unifying circular economy compliance with durability guarantees that sustain repeat purchase economics.
EU Green Deal extended producer responsibility mandates are requiring manufacturers to finance end-of-life collection and recycling infrastructure for plastic accessories sold in European markets. Compliance costs are compressing margins for small-batch producers while creating scale advantages for integrated operators with captive logistics networks. Collar and litter box categories face the steepest compliance burden due to polymer complexity and volume concentration.
Subscription-based replenishment models for consumable accessories—litter, treats, disposable liners—are displacing episodic retail purchasing among United States millennial and Gen Z cat owners. Direct-to-consumer platforms with predictive reorder algorithms are capturing loyalty and expanding basket size through bundled enrichment products. Urban coastal markets show the highest subscription penetration, with San Francisco and New York metropolitan areas leading adoption curves.
Cat Accessories Market Segmentation
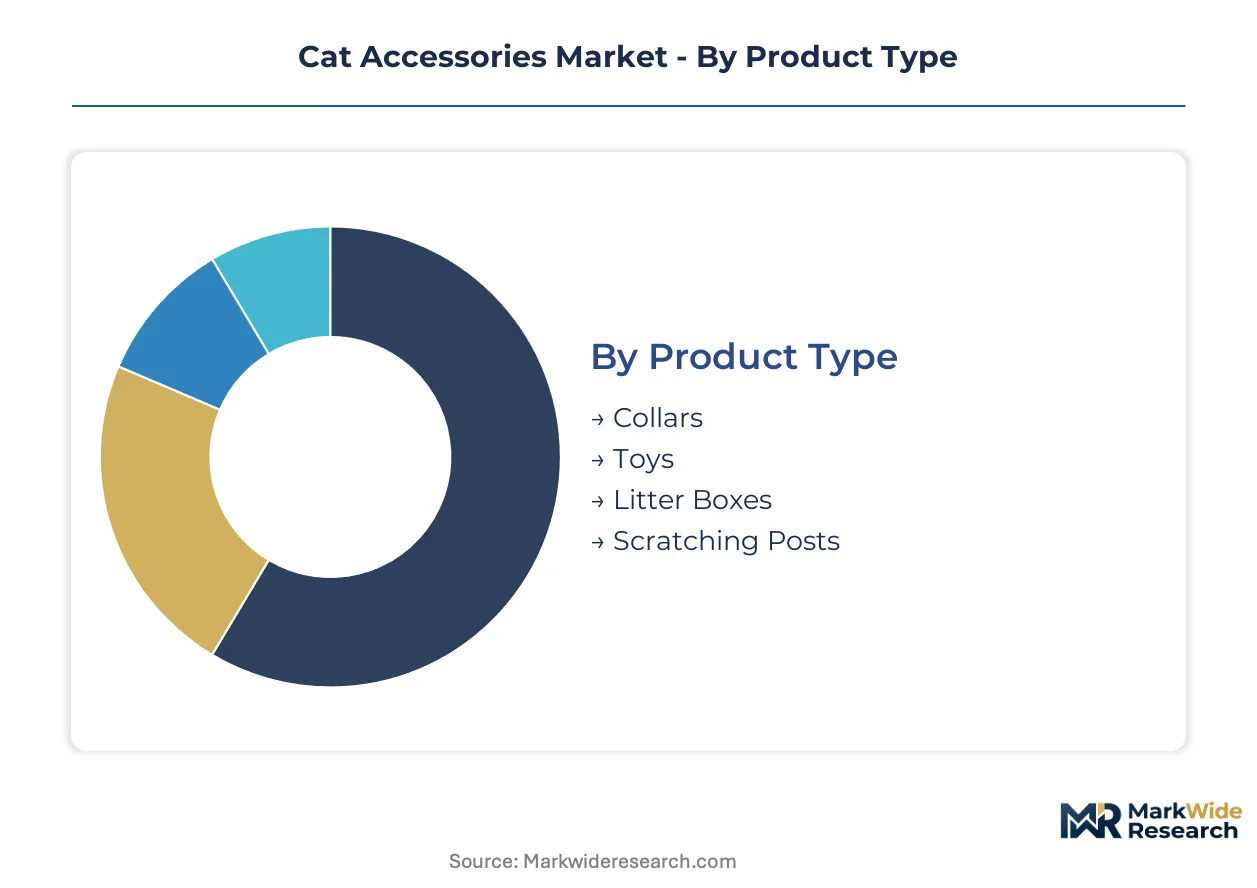
Cat accessories segment along four intersecting dimensions that determine margin capture and channel strategy. Product type and material composition anchor manufacturing decisions, while quality grade stratification separates sustainability premiums from volume economics.
Product Type:
Volume concentrates in enrichment and hygiene categories, while premium positioning clusters around durable engineering and behavioral optimization.
- Collars:Quick-release buckle mechanisms and tensile-strength-tested webbing address feline safety specifications. Demand clusters in United States urban centers where leash-training ordinances and identification requirements drive replacement cycles.
- Toys:Interactive systems incorporating motion sensors and treat-dispensing mechanics command the steepest price premiums. Coastal metropolitan markets show highest penetration of app-connected and automated enrichment platforms.
- Litter Boxes:Particle-size-optimized geometries and odor-encapsulation materials dominate household hygiene positioning. Hooded and self-cleaning variants capture margin from space-constrained apartment dwellers.
- Scratching Posts:Vertical and horizontal configurations with sisal-wrapped surfaces satisfy territorial marking behaviors. Basic corrugated cardboard units anchor mass-market volume while furniture-integrated designs command architectural premiums.
Mature deployment sits with scratching posts and litter boxes. Newer deployment is concentrated in connected toy systems and GPS-enabled collar variants.
Material:
EU Green Deal mandates are compressing petroleum-based formulations while elevating bio-sourced alternatives across European supply chains.
- Plastic:Injection-molded ABS and polypropylene formulations face substitution pressure from recycled ocean plastic feedstocks. REACH chemical restrictions are accelerating reformulation away from phthalate-containing compounds.
- Fabric:Organic cotton and hemp textiles capture sustainability premiums in collar and bedding applications. Certification friction around biodegradable claims is delaying marketing timelines for compostable fabric lines.
- Wood:FSC-certified birch and bamboo substrates anchor scratching post construction. German and Dutch manufacturers are integrating dandelion-root latex binders to unify renewable sourcing with durability guarantees.
- Metal:Stainless steel feeding accessories and litter box frames target veterinary and clinical channels. Medical-grade formulations face silicone substitution threats in premium hydration and feeding segments.
Plastic and fabric anchor current volume. Wood and certified bio-rubber alternatives are climbing the fastest as circular economy compliance hardens.
End User:
Channel bifurcation separates episodic retail purchasing from subscription-based replenishment and clinical-anchored wellness positioning.
- Pet Owners:Direct-to-consumer platforms with predictive reorder algorithms are displacing conventional retail among millennial and Gen Z demographics. Urban coastal markets show highest subscription penetration for consumable accessories.
- Retailers:Omnichannel operators with same-day delivery infrastructure control inventory placement and private-label expansion. Specialized pet retail chains curate premium SKU assortments through veterinary endorsement partnerships.
- Veterinarians:Clinic-anchored subscription models bypass conventional retail to capture wellness-positioned buyer segments. Cross-selling of enrichment products through nutrition platforms expands basket size.
- Groomers:Service-integrated accessory sales concentrate in collar, harness, and calming product categories. Appointment-based replenishment drives lower-frequency but higher-margin transactions.
Pet owners and retailers dominate transaction volume. Veterinary channels represent the steepest expansion trajectory for premium wellness accessories.
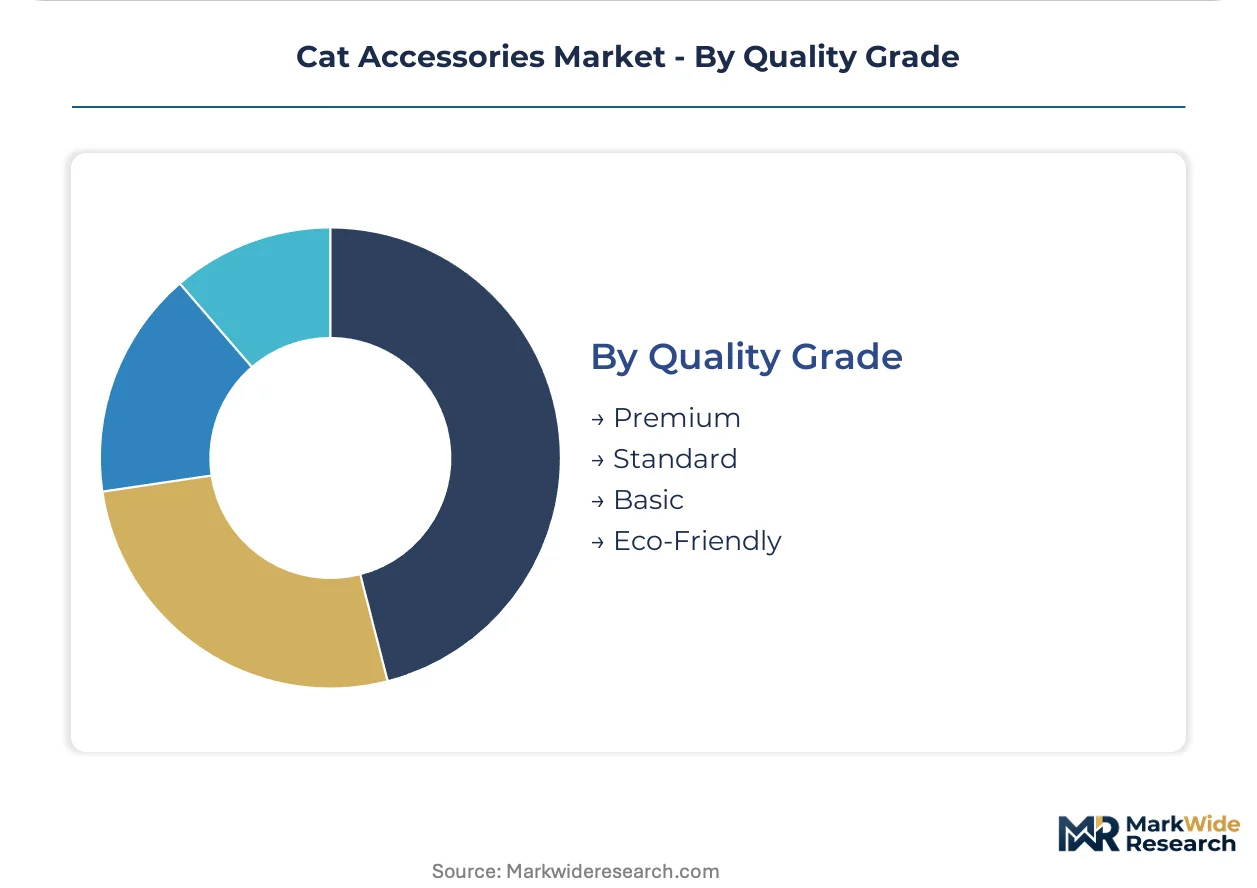
Quality Grade:
Certification infrastructure and extended producer responsibility costs are widening the gap between economy positioning and sustainability premiums.
- Premium:Veterinary behaviorist validation and ISO 8124 safety testing anchor positioning. Smart home integration and RFID-enabled functionality command price multiples over conventional alternatives.
- Standard:Mid-tier formulations balance durability with accessibility across mass retail channels. Private-label expansion by omnichannel operators compresses branded share in this tier.
- Basic:Corrugated cardboard scratchers and simple nylon collars anchor entry-level price points. Thin margins and regulatory compliance costs are driving manufacturer exit from this segment.
- Eco-Friendly:Biodegradable certification and closed-loop take-back programs create first-mover advantage for integrated operators. OECD compostability testing timelines delay product launches and freeze marketing claims.
Standard and basic grades anchor current volume concentration. Eco-friendly positioning is gaining share fastest as EU extended producer responsibility mandates harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco anchors subscription-based accessory replenishment, with millennial cat owners driving predictive reorder algorithm adoption through direct-to-consumer platforms.
United States
Metropolitan cat owners in New York and Los Angeles expand spending on enrichment systems and wellness-calibrated accessories. FDA pet product safety labeling elevates compliance costs for imported interactive toys. Chicago's specialized retail infrastructure sustains above-average category spending through veterinary endorsement partnerships.
Germany
EU Green Deal circular economy mandates redirect manufacturer sourcing toward recycled plastics and organic fabrics. REACH chemical substance restrictions accelerate reformulation of rubber compounds and textile treatments. Düsseldorf and Hamburg host integrated operators with captive logistics networks for closed-loop take-back programs.
United Kingdom
Urban pet humanization trends concentrate demand in London and Manchester for premium enrichment products. ECHA chemical restrictions govern accessory manufacturing standards for export-bound goods. Birmingham's distribution clusters support omnichannel operators with same-day delivery infrastructure.
Netherlands
Sustainability-positioned buyers in Amsterdam and Rotterdam drive margin concentration for eco-friendly quality grade segments. Extended producer responsibility frameworks require manufacturers to finance end-of-life collection infrastructure. Eindhoven's material science clusters advance dandelion-root latex bio-rubber formulations for chew-toy applications.
Japan
Space-constrained apartment dwellers in Tokyo and Osaka capture margin from hooded and self-cleaning litter box variants. METI standards shape domestic product safety protocols while ISO 8124 governs export toy testing. Nagoya's industrial corridors supply precision-engineered feeding accessories for clinical channels.
Cat Accessories Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification infrastructure and veterinary channel access. The vendor base stratifies into three tiers: integrated nutrition-to-accessories platforms with cross-selling capabilities, specialized durable-goods engineers with proprietary material formulations, and omnichannel distributors anchoring private-label expansion through physical store networks. Strategic archetypes include veterinary-anchored wellness platforms, bio-material specialists, and predictive-reorder algorithm operators. Dominant competitive moves encompass subscription model deployment and closed-loop take-back program establishment.
Among integrated nutrition-to-accessories platforms, Nestlé Purina occupies a position exemplifying cross-selling architecture through veterinary channels. Petco Animal Supplies Inc. sits within the omnichannel distribution archetype, anchoring private-label expansion through extensive store networks and same-day delivery infrastructure. KONG Company represents the specialized durable-goods engineer tier, with proprietary rubber formulations sustaining repeat purchase economics in chew-toy categories.
| Leading Market Players |
|---|
| PET PARENT |
| Simply Fido |
| Nestlé Purina |
| Petco Animal Supplies Inc. |
| KONG Company |
| Coastal Pet Products Inc. |
| Ferplast Spa |
| The Hartz Mountain Corporation |
| Spectrum Brands |
| Others |
Value Network & Pricing Analysis
EU Green Deal material mandates are forcing manufacturers to absorb biodegradable certification costs and reformulate petroleum-dependent compounds, compressing margins for small-batch producers while rewarding scaled operators with captive compliance infrastructure. This regulatory-driven procurement shift is reshaping supplier economics across European supply chains and redistributing pricing power toward integrated manufacturers with dedicated regulatory affairs functions.
Pricing Analysis
Value-based pricing anchored to veterinary behaviorist validation and ISO 8124 safety certification commands multiples over conventional alternatives in premium tiers. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and smart home integration capability. Cost compression in basic-grade segments is intensifying because regulatory compliance burdens exceed margin absorption capacity for small manufacturers. Millennial and Gen Z pet owners in coastal metropolitan markets show lowest price sensitivity for subscription-based wellness bundles, while mass-market retail channels face highest price elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Southeast Asian natural rubber plantations, where climate-induced yield compression and supply disruptions destabilize input costs for chew-toy manufacturers. Manufacturing concentrates in China, Germany, and the Netherlands, with dandelion-root latex bio-rubber development clustering in Eindhoven and Hamburg. Raw material dependencies include petroleum-based ABS formulations, organic cotton textiles, and FSC-certified birch substrates. Tariff exposure on Chinese-manufactured interactive electronics creates margin risk for app-connected toy lines. Distribution runs through omnichannel operators with same-day delivery infrastructure and veterinary clinic-anchored subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU extended producer responsibility mandates are consolidating the vendor base by eliminating margin-thin basic-grade competitors unable to finance end-of-life collection infrastructure.
For Market Incumbents: Acquire biodegradable certification infrastructure and closed-loop logistics capabilities to defend against regulatory-driven margin compression. Nestlé Purina's cross-selling architecture through veterinary channels offers a template for nutrition-to-accessories platform expansion. KONG Company's proprietary rubber formulation R&D provides defensive moat against silicone substitution threats in premium feeding segments. For New Entrants and Emerging Players: Enter via veterinary direct-to-consumer subscription models bypassing conventional retail gatekeepers. White-space opportunity concentrates in RFID-enabled feeding systems and app-connected litter monitoring for smart home integration. San Francisco and New York metropolitan areas represent the most penetrable geographic clusters for predictive reorder algorithm adoption among millennial cat owners. For Investors and Strategic Acquirers: The window for entry favors integrated operators with captive logistics networks and bio-material R&D capabilities. Long-term viability hinges on circular economy compliance infrastructure rather than commodity manufacturing scale. Watch biodegradable certification timeline friction as the signal for competitive positioning shifts—accelerated OECD testing approvals will separate first-movers from laggards.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Take-Back Program Establishment | EU Green Deal extended producer responsibility mandates require manufacturers to finance end-of-life collection infrastructure. |
| Bio-Rubber Formulation R&D Investment | Dandelion-root latex alternatives unify REACH compliance with durability specifications previously exclusive to petroleum-based compounds. |
| Veterinary Channel Direct Distribution | Clinic-anchored subscription models bypass Petco's omnichannel dominance to capture wellness-positioned buyer segments. |
| Smart Home Integration Partnership | RFID-enabled feeding systems and app-connected litter monitoring converge pet care with residential automation platforms. |
| Biodegradable Certification Acceleration | OECD compostability testing timelines delay product launches; accelerated certification creates first-mover advantage in EU markets. |
Research Methodology
Multi-period observation of EU Green Deal implementation timelines, REACH chemical restriction enforcement patterns, and subscription model adoption curves anchored the trend analysis, supplemented by interviews with product development executives at integrated pet care platforms, regulatory affairs leads at durable-goods manufacturers, category buyers at omnichannel retailers, and veterinary behaviorists at clinic networks. Secondary validation drew from FDA pet product safety filings, ECHA chemical restriction databases, customs records of recycled ocean plastic feedstock imports, and ISO 8124 toy safety testing protocols. Bottom-up demand modeling triangulated against top-down market sizing across material composition and quality grade segments.
Input-output matrices mapped raw material cost trajectories—natural rubber price volatility, recycled plastic feedstock availability, bio-rubber formulation yields—against finished goods pricing across premium, standard, and economy tiers throughout the forecast period. Segmentation dimensions modeled included product type, material composition, quality grade stratification, and end-user channel bifurcation. CAGRs derived from regression analysis of historical pricing elasticity and procurement pattern shifts. Industry-specific forecast inputs incorporated biodegradable certification pipeline data and veterinary channel expansion rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU extended producer responsibility enforcement or breakthrough silicone substitution in premium feeding accessories. Forecasts reflect documented assumptions regarding regulatory timeline adherence and material science advancement rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Cat Litter Market
Pet Care Products
Europe Farrier Products Market
Pet Care Products
China Pet Food Market
Pet Care Products
Europe Organic and Natural Pet Food Market
Pet Care Products
Indonesia Pet Food Market
Pet Care Products
Pet Tech Market
Pet Care Products
Pet Clean-Up and Odor-Control Products Market
Pet Care Products
Pet Water Dispenser Market
Pet Care Products
Mink Oil Market
Pet Care Products
United Kingdom Cat Litter Market
Pet Care Products
Aquarium Supplies Market
Pet Care Products
Cat Window Perches and Wall Shelves Market
Pet Care Products
Plant-Based Dog Food Market
Pet Care Products
Cat Diffuser Market
Pet Care Products
South Korea Dog Food Market
Pet Care Products
Smart Pet Collar Market