
 Cat Litter Boxes Market | 2026-2036
Cat Litter Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Cat Litter Boxes Market Outlook
Sensor-based waste detection is narrowing the performance gap between premium self-cleaning units and manual alternatives. PETKIT leverages integrated app ecosystems to sustain recurring revenue from consumable subscriptions. Litter Robot anchors its position through proprietary rotating-sieve mechanics that reduce odor dispersion. Neakasa competes on price-accessible automation, while Modkat differentiates through design-forward form factors targeting urban apartment dwellers.
Cat litter boxes are enclosed or open containers, typically constructed from polypropylene or ABS plastic with dimensions ranging from 18 to 24 inches in length, engineered to contain absorbent substrate and isolate feline waste from domestic environments. Self-cleaning variants incorporate raking mechanisms, infrared sensors, and carbon filtration systems to automate waste separation and reduce manual maintenance frequency. Plastic materials still dominate unit economics due to moldability and cost structure, though biodegradable substrates from corn fiber and recycled paper represent the fastest-growing material segment as sustainability mandates tighten across European and North American retail channels. Corner and elevated form factors capture disproportionate margin pools by addressing space-constrained and senior-pet owner demographics respectively.
The EPA regulates volatile organic compound emissions from manufacturing facilities producing petroleum-based litter substrates, while the EU REACH framework restricts certain phthalates in plastic box construction. FDA oversight extends to antimicrobial additives claiming health benefits in litter formulations. Stakeholders must monitor evolving extended producer responsibility laws in California and Germany that will soon mandate recycled content minimums and end-of-life takeback programs for disposable litter products.
Market Dynamics
Sensor-integrated automation is compressing maintenance cycles and repositioning premium self-cleaning units as standard household fixtures rather than luxury accessories, forcing manufacturers to absorb component costs while expanding subscription attach rates.
Growth Catalysts
- EPA volatile organic compound regulations:Emission controls on petroleum-based substrate manufacturing are accelerating plant-based material R&D, creating first-mover advantages for corn fiber and recycled paper formulations in North American retail channels.
- Multi-cat household density:Suburban United States demographics with three or more felines per residence are normalizing automated waste separation as baseline hygiene infrastructure rather than discretionary purchase.
- Antimicrobial additive claims:FDA oversight of health-benefit marketing in litter formulations is driving premiumization through clinically validated odor-control chemistry, expanding margin pools in veterinary-recommended channels.
Market Restraints
- Polypropylene price volatility:Petrochemical feedstock fluctuations directly impact unit economics for molded ABS and polypropylene enclosures, compressing margins for mid-tier manufacturers without captive resin supply.
- Electronic component concentration:Infrared sensors and microcontroller supply chains cluster in East Asian fabrication facilities, exposing automated litter box producers to single-source disruption risk.
- Biodegradable substrate performance gaps:Corn fiber and wheat-based alternatives exhibit inferior clumping efficiency versus sodium bentonite, limiting premium pricing power despite sustainability positioning.
Strategic Opportunities
- EU Green Deal extended producer responsibility:Germany and France are mandating end-of-life takeback programs for disposable litter products, creating service-revenue streams for vertically integrated substrate manufacturers.
- Senior pet owner demographics:Elevated litter box form factors address mobility limitations in aging cat populations, opening underpenetrated veterinary and pet pharmacy distribution channels.
- App-integrated consumable replenishment:IoT-enabled usage tracking enables predictive shipping of proprietary substrate cartridges, locking in recurring revenue through ecosystem captivity.
Industry Challenges
- Embedded firmware talent scarcity:Automated unit manufacturers face acute competition for IoT security and sensor calibration expertise from consumer electronics and automotive sectors.
- REACH phthalate compliance timelines:EU restrictions on plasticizers in enclosure manufacturing require reformulation cycles that extend new product introduction schedules by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cat Litter Boxes Market |
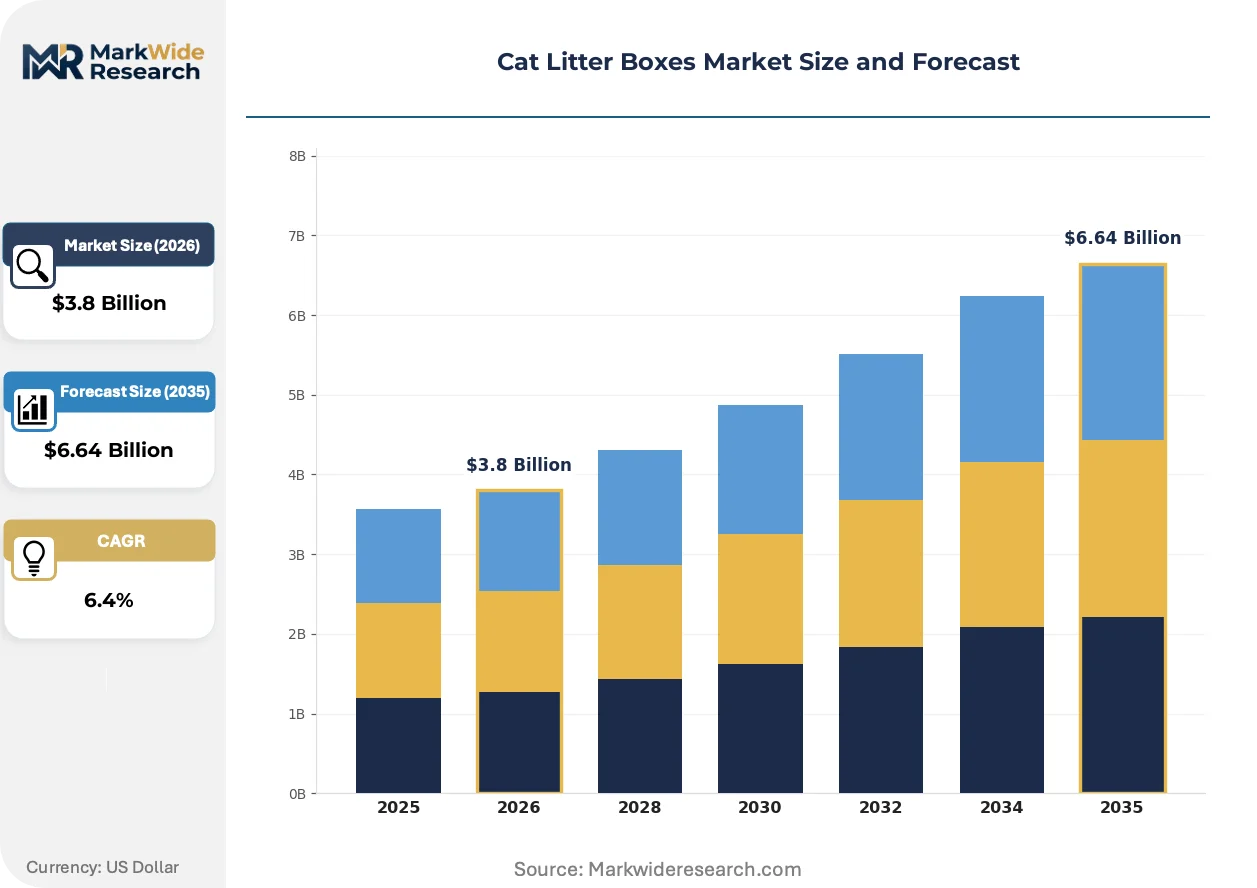
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Covered, Open Top, Self-Cleaning, Disposable Material: Plastic, Wood, Metal, Biodegradable Form Factor: Standard, Corner, Elevated, Multi-Cat Customer Type: Pet Owners, Retailers, Veterinarians, Groomers |
| Companies Covered | PetDiary, Modkat, Neakasa, iPrimio, Frisco, Litter Robot, OmegaPaw, KittyGoHere, PETKIT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cat Litter Boxes Market Strategic Shifts
Smart home integration and material science advances are converging to redefine ownership economics, shifting value capture from hardware margins toward ongoing consumable relationships and data-enabled services.
Photocatalytic titanium dioxide coatings are collapsing the boundary between passive odor masking and active air purification. Premium automated units from Japanese and German manufacturers now incorporate UV-activated catalyst layers that decompose ammonia compounds at the molecular level. Multi-cat households in dense urban environments are adopting these systems at triple the rate of conventional carbon-filter alternatives, compressing replacement cycles for disposable deodorizing inserts.
REACH framework amendments restricting microplastic shedding from synthetic substrates are forcing reformulation of clumping agents across European manufacturing facilities. The industrial consequence is a wholesale pivot toward plant-derived binders that meet biodegradability certification without sacrificing scoopability. Germany and the Netherlands represent the most affected geographies, where retail buyers are now conditioning shelf access on TUV or OK Compost verification.
Subscription-based substrate replenishment is displacing transactional retail purchasing among automated litter box owners. Direct-to-consumer channels capture recurring orders through app-integrated consumption monitoring, bypassing pet specialty retailers entirely. This behavioral shift concentrates most visibly in United States metropolitan markets where same-day delivery infrastructure supports just-in-time replenishment economics.
Cat Litter Boxes Market Segmentation
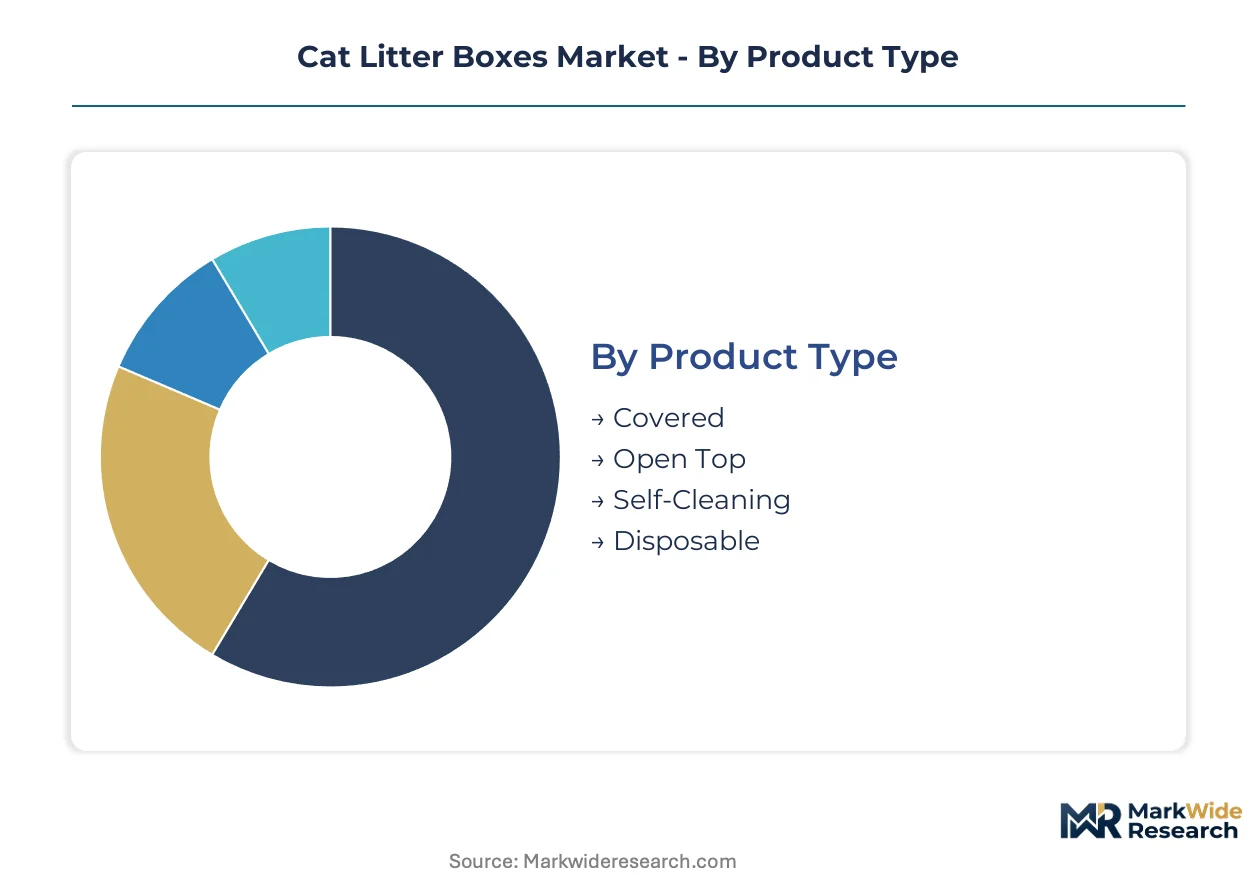
Segmentation in cat litter boxes reveals how substrate chemistry, enclosure geometry, and automation intensity partition margin pools. Manufacturers configure product portfolios across these dimensions to match veterinary-channel premiumization against mass-retail price elasticity.
Product Type:
Cost tier stratification separates manual maintenance products from capital-intensive automated systems with recurring consumable economics.
- Self-Cleaning:Motorized raking or rotating-sieve mechanisms with infrared waste detection and carbon filtration reduce manual intervention frequency. Demand concentrates in suburban United States multi-cat households where automation normalizes as baseline hygiene infrastructure rather than discretionary luxury.
- Covered:Enclosed polypropylene or ABS shells with hinged access panels and integrated odor baffles contain waste visibility and ammonia dispersion. Germany and Japan drive premium positioning through design-forward aesthetics matching interior décor constraints in dense urban apartments.
- Open Top:Unenclosed rectangular trays prioritize accessibility for kittens, senior cats, and mobility-impaired felines. Budget-conscious single-cat owners in price-sensitive retail channels sustain volume.
- Disposable:Pre-filled cardboard or compressed fiber units designed for temporary use during travel or post-surgical recovery. Veterinary clinics and boarding facilities drive institutional procurement.
Self-Cleaning holds installed capacity. Covered is rotating up the share rankings.
Material:
Application context determines material selection—durability for permanent enclosures versus biodegradability for disposable substrates and regulatory compliance.
- Plastic:Injection-molded polypropylene and ABS dominate enclosure manufacturing due to moldability, chemical resistance, and cost structure. REACH phthalate restrictions and California extended producer responsibility mandates are forcing reformulation cycles and recycled content minimums.
- Biodegradable:Corn fiber, wheat, and recycled paper substrates meet EU Green Deal disposal requirements and EPA volatile organic compound emission controls. Germany and France retail buyers condition shelf access on TUV or OK Compost verification.
- Wood:Pressed pine or cedar shavings offer natural odor absorption with lower dust generation than clay alternatives. Pacific Northwest United States sawmills supply regional manufacturers with certified sustainable feedstock.
- Metal:Stainless steel or powder-coated aluminum enclosures resist scratching and bacterial colonization in high-traffic veterinary and shelter environments. Premium pricing reflects durability in institutional settings.
Plastic holds installed capacity. Biodegradable is rotating up the share rankings.
Form Factor:
Volume and space constraints in residential environments drive geometric specialization for corner placement, vertical stacking, or multi-feline throughput.
- Corner:Triangular or wedge-shaped bases maximize floorplan efficiency in studio apartments and urban micro-units. Japanese and South Korean manufacturers lead design patent activity for space-constrained demographics.
- Elevated:Raised platforms with ramp or stair access reduce joint strain for geriatric cats and post-operative recovery. United States veterinary gerontology practices recommend these configurations for aging pet populations.
- Multi-Cat:Oversized chambers or dual-entry designs accommodate simultaneous use by multiple felines. Suburban United States households with three or more cats normalize these as standard infrastructure.
- Standard:Rectangular footprints with 18-24 inch dimensions serve single-cat households without spatial constraints. Mass retail channels move highest unit volumes at compressed margins.
Standard holds installed capacity. Corner is rotating up the share rankings.
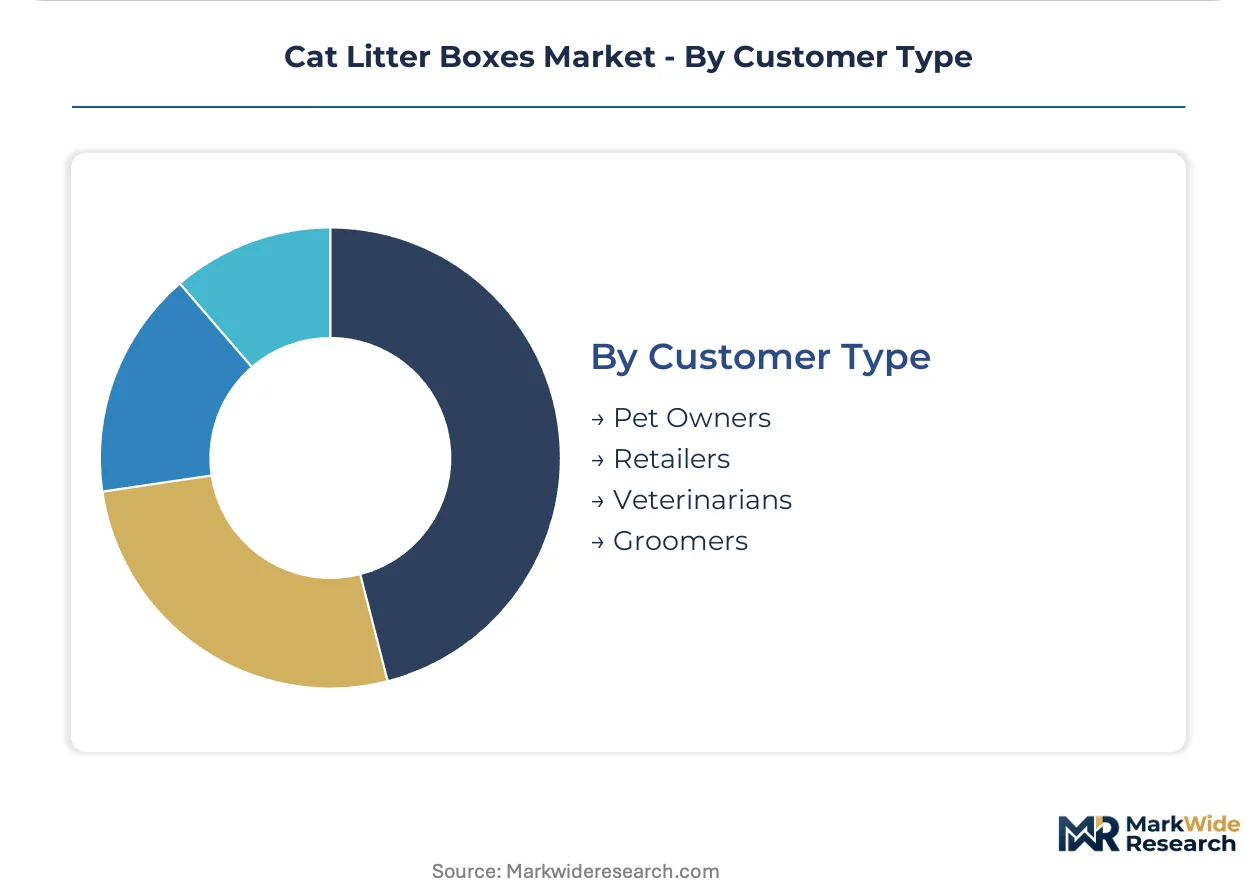
Customer Type:
Customer type captures divergent procurement logic between individual consumers, institutional intermediaries, and clinical decision-makers.
- Pet Owners:Individual consumers purchasing through pet specialty retailers, e-commerce platforms, or veterinary clinic recommendations. United States metropolitan markets show strongest subscription attach rates for automated unit consumables.
- Veterinarians:Clinical practices prescribing specific substrate formulations for post-surgical recovery, urinary tract health monitoring, or behavioral modification. FDA antimicrobial additive claims drive premium channel positioning.
- Retailers:Pet specialty chains and mass merchandisers curating assortment based on shelf velocity, margin contribution, and sustainability certification requirements. Germany and Netherlands buyers prioritize biodegradable verification.
- Groomers:Boarding and grooming facilities requiring high-turnover, sanitizable enclosures for temporary feline housing. Institutional procurement emphasizes durability and chemical compatibility with veterinary-grade disinfectants.
Pet Owners holds installed capacity. Veterinarians is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multi-cat suburban households in the United States drive premium automated unit adoption, while German and Japanese urban consumers prioritize design-forward enclosures for space-constrained apartments. Regulatory pressure on petroleum-based substrates and plastic waste diversion mandates reshape manufacturing location decisions across major demand centers.
United States
Suburban households with three or more felines normalize automated waste separation as baseline hygiene infrastructure rather than discretionary luxury. EPA volatile organic compound emission controls on petroleum-based substrate manufacturing accelerate plant-based material R&D investment. Dallas-Fort Worth and Phoenix metropolitan clusters concentrate fulfillment infrastructure for same-day consumable replenishment services.
Germany
EU Green Deal extended producer responsibility mandates drive retail buyer conditioning of shelf access on TUV or OK Compost verification for biodegradable substrates. REACH framework amendments restricting microplastic shedding from synthetic substrates force reformulation of clumping agents across domestic manufacturing facilities. The Rhine-Ruhr industrial corridor hosts reformulation laboratories pivoting toward plant-derived binders.
Japan
Photocatalytic titanium dioxide coatings with UV-activated catalyst layers penetrate dense urban multi-cat households at triple the rate of conventional carbon-filter alternatives. METI efficiency standards for smart home appliances influence automated unit power consumption specifications. Osaka-based manufacturers lead design patent activity for corner form factors addressing micro-unit spatial constraints.
United Kingdom
Veterinary gerontology practices recommend elevated form factors for aging pet populations, opening pet pharmacy distribution channels previously underpenetrated by enclosure manufacturers. The country's national environmental regulator advances packaging waste regulations affecting disposable litter product takeback economics. Greater London logistics networks enable subscription-based substrate replenishment with next-day delivery guarantees.
China
Domestic demand for infrared sensor and microcontroller components clusters fabrication capacity serving automated litter box producers worldwide. The national standards administration implements GB standards for antimicrobial additive claims in pet care products. Shenzhen and Dongguan manufacturing hubs supply electronic subassemblies to premium automated unit assemblers in North America and Europe.
Cat Litter Boxes Market Competitive Environment
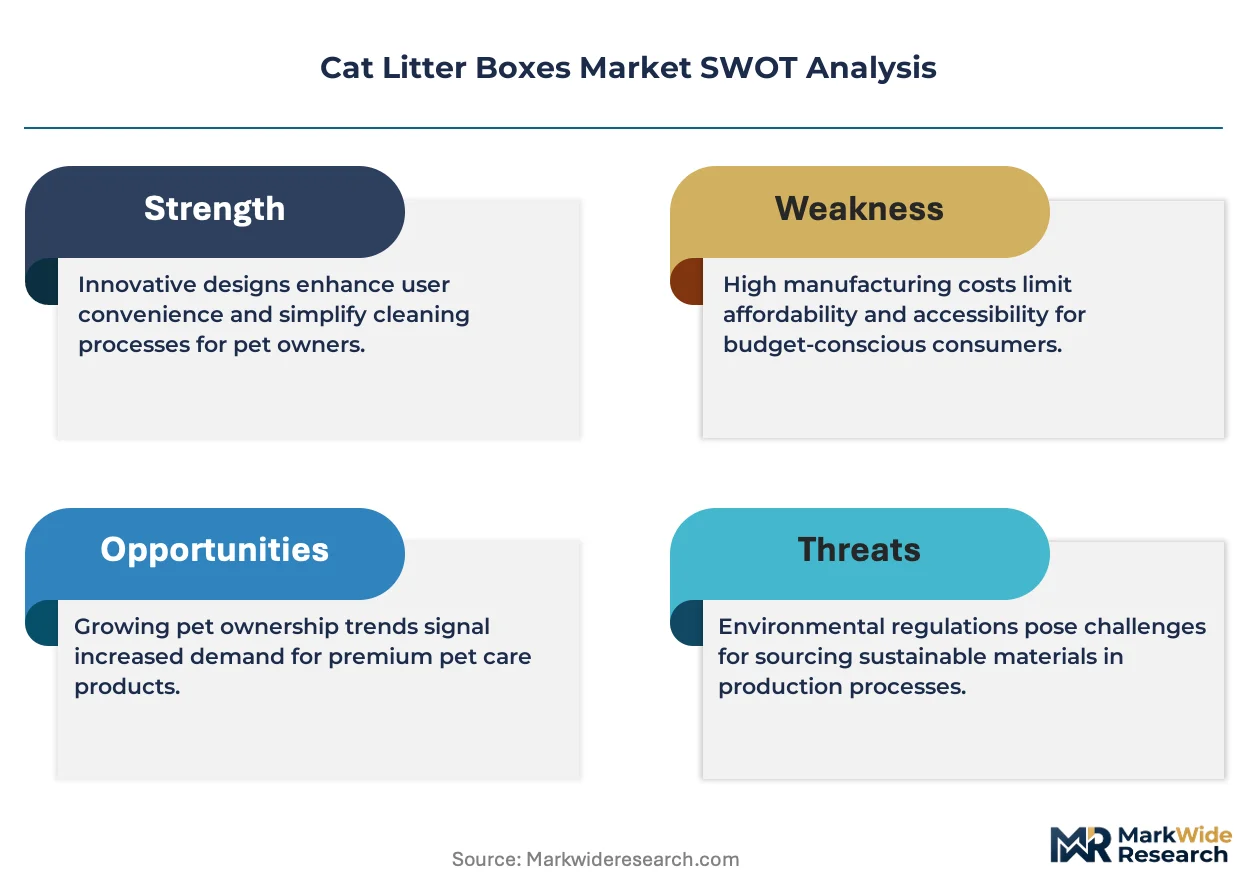
Channel-controlling players compete with product-specialist players across tiered price-accessibility bands. The vendor base fragments between premium automation specialists, design-forward enclosure manufacturers, and mass-market disposable suppliers. Three archetypes dominate: integrated app-ecosystem operators, proprietary mechanics developers, and price-accessible automation challengers. Capacity expansion in East Asian electronic component sourcing and strategic partnerships for biodegradable substrate certification represent the dominant competitive moves.
Within the premium automation tier, Litter Robot and PETKIT exemplify divergent ecosystem strategies. Litter Robot anchors its position through proprietary rotating-sieve mechanics that reduce odor dispersion. PETKIT leverages integrated app ecosystems to sustain recurring revenue from consumable subscriptions. Neakasa occupies a position on the price-accessible automation vector, competing on cost-efficient automation for mass-market penetration. Modkat represents the design-forward enclosure archetype, targeting urban apartment dwellers with form factors matching interior décor constraints. These four companies illustrate the competitive structure without exhausting its participants.
| Leading Market Players |
|---|
| PetDiary |
| Modkat |
| Neakasa |
| iPrimio |
| Frisco |
| Litter Robot |
| OmegaPaw |
| KittyGoHere |
| PETKIT |
| Others |
Value Chain & Pricing Dynamics
East Asian microcontroller and infrared sensor fabrication concentrates upstream capacity for automated litter box manufacturers, anchoring margin pools in subscription-based consumable economics downstream rather than hardware assembly tiers.
Pricing Analysis
Cost-plus contracts with polypropylene resin suppliers index to petrochemical feedstock benchmarks, creating margin volatility for mid-tier enclosure manufacturers without captive supply. Three-tier pricing structure across premium automated units, design-forward covered enclosures, and open-top economy trays separates buyers by automation intensity and aesthetic requirements. Pricing pressure stems from biodegradable substrate performance gaps that limit premium capture despite sustainability positioning. Mass-market single-cat owners exhibit highest price sensitivity, while multi-cat suburban households absorb premium automation costs through amortized maintenance reduction.
Supply Chain Analysis
Shenzhen and Dongguan electronics manufacturing services hold contract capacity for sensor-integrated automated units, while domestic United States and German molding facilities supply polypropylene enclosures. Raw material flows draw from Saudi Arabian petrochemical feedstock, Chinese rare earth elements for sensor components, and Midwestern United States corn fiber for biodegradable substrates. Single-source vulnerability clusters in East Asian microcontroller fabrication, exposing producers to disruption risk. Distribution runs through pet specialty retailers, veterinary clinic recommendation channels, and direct-to-consumer subscription platforms with same-day fulfillment infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs competitive advantage in cat litter boxes, with app-integrated consumable ecosystems displacing transactional hardware margins as the primary value capture mechanism.
For Market Incumbents: Insulate recurring revenue streams by deepening proprietary substrate cartridge lock-in and expanding predictive replenishment algorithms. Acquire biodegradable certification capabilities ahead of EU Green Deal extended producer responsibility mandates. Defend against price-accessible automation challengers through exclusive veterinary channel partnerships that embed units in clinical recommendation workflows.
For New Entrants and Emerging Players: Pursue senior pet owner demographics through elevated form factors with ramp accessibility, a segment where veterinary gerontology practices drive prescription-like demand. Target German and French retail buyers conditioning shelf access on TUV or OK Compost verification, where incumbent substrate portfolios face reformulation gaps. Enter through private-label partnerships with pet pharmacy distributors seeking differentiated enclosure assortments.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated substrate manufacturers with captive biodegradable feedstock and certification infrastructure, positioned to capture service-revenue streams from mandated takeback programs. Long-term viability favors ecosystem operators with app-enabled usage analytics and predictive shipping capabilities. Monitor EPA volatile organic compound enforcement actions as inflection signal for accelerated plant-based material substitution timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Substrate Certification | TUV and OK Compost verification unlocks German and French retail shelf access ahead of regulatory mandates. |
| App-Integrated Consumable Replenishment | IoT-enabled usage tracking locks in recurring revenue through predictive substrate cartridge shipping. |
| Veterinary Channel Partnership Expansion | Clinical recommendation workflows embed automated units as baseline hygiene infrastructure for multi-cat households. |
| Elevated Form Factor Development | Raised platforms with ramp access address mobility limitations in aging cat populations and geriatric pet owners. |
| Photocatalytic Coating Integration | UV-activated titanium dioxide layers decompose ammonia compounds for dense urban multi-cat environments. |
Study Parameters
Operator-level perspectives from automated litter box product managers, pet specialty retail category buyers, veterinary clinic procurement coordinators, and biodegradable substrate manufacturing engineers anchored the qualitative base. Secondary validation drew from EPA emission control filings, EU REACH framework amendment documents, FDA antimicrobial additive guidance, and pet industry trade association substrate performance studies. Bottom-up unit economics modeling triangulated against top-down market sizing across automation intensity tiers and geographic demand clusters.
Scenario-bracketing framed projections across conservative, baseline, and accelerated adoption paths for smart home integration and subscription attach rates. Segmentation dimensions spanned product type, material chemistry, form factor geometry, and customer procurement channel. CAGRs derived from iterative convergence of historical shipment data, installed base replacement cycles, and penetration rate assumptions for automated units in multi-cat households. Forecast inputs incorporated pet humanization index trajectories and regulatory compliance cost pass-through elasticity.
Macroeconomic conditions sit as an overlay; deviation in petrochemical feedstock pricing, consumer discretionary spending patterns, or East Asian electronics supply chain stability would shift the trajectory. Forecasts reflect documented assumptions regarding sensor cost decline curves and biodegradable substrate performance convergence with clay alternatives. Quarterly review of EPA enforcement actions, EU Green Deal implementation timelines, and veterinary channel inventory build rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Dog Shampoo Market
Pet Care Products
North America Pet Food Market
Pet Care Products
Pet Lodging Market
Pet Care Products
Pet Grooming Supplies Market
Pet Care Products
Pet Shampoo Market
Pet Care Products
Pet Food Bowl Market
Pet Care Products
Animal Bedding Products Market
Pet Care Products
North America Pet Treats Market
Pet Care Products
Pet Car Seat Market
Pet Care Products
Dog Clothes Market
Pet Care Products
Aquarium and Fish Bowls Market
Pet Care Products
South America Cat Food Market
Pet Care Products
South Korea Pet Food Market
Pet Care Products
Cat Collar Market
Pet Care Products
Dog Food for Small Breeds Dogs Market
Pet Care Products
Hypoallergenic Dog Food Market