
 Pet Gadgets Market | 2026-2036
Pet Gadgets Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Gadgets Market Analytics
The EU Green Deal is broadening compliance obligations for pet electronics manufacturers importing into Europe. PETKIT leverages in-house app ecosystems to sustain recurring revenue beyond hardware sales. Central Garden & Pet Company anchors mass-market distribution through big-box retail partnerships. PetSafe competes on veterinary channel credibility, while Cheerble differentiates through compact robotic toy design.
Pet gadgets encompass electromechanical devices engineered for animal care, typically incorporating sensors with 2.4 GHz wireless connectivity, lithium-polymer power systems, and IPX5–IPX7 ingress protection ratings for moisture resistance. Their primary commercial purpose centers on automating feeding, location tracking, behavioral stimulation, or physiological monitoring to reduce owner intervention frequency. Smart feeders command the largest revenue pool among product types, reflecting subscription-compatible replenishment models. GPS collars represent the fastest-expanding application segment, driven by geofencing software and cellular-LPWAN hybrid tracking. Health trackers are concentrating margin pools in the veterinary clinic end-user channel, where diagnostic data integration commands premium pricing.
The US FDA regulates ingestible pet health sensors as animal health devices, while the FCC governs RF emissions for all connected collars and feeders sold domestically. The EU REACH framework restricts phthalates and heavy metals in chewable toy housings, directly influencing supplier qualification criteria. California's Proposition 65 labeling mandates create a de facto national compliance floor for US-bound products. Stakeholders must monitor evolving interoperability standards between proprietary IoT platforms and third-party smart home ecosystems.
Market Dynamics
The EU Green Deal's extended producer responsibility rules are forcing pet electronics manufacturers to redesign housings and establish take-back infrastructure, restructuring cost allocation across the value chain.
Growth Catalysts
- Millennial and Gen Z pet humanization:Younger cohorts treat companion animals as family members, accelerating purchases of connected care devices that automate feeding, tracking, and health monitoring functions.
- Smart home ecosystem integration:Demand for 2.4 GHz wireless connectivity with Alexa, Google Home, and Apple HomeKit is pulling pet gadgets into unified automation architectures.
- EU Green Deal circular economy mandates:Extended producer responsibility rules create competitive advantage for manufacturers with modular, recyclable designs and certified repair networks.
Market Restraints
- Lithium-polymer battery supply concentration:Cell production clusters in East Asian manufacturing hubs, exposing brands to logistics disruptions and input cost volatility.
- IPX5–IPX7 certification complexity:Moisture resistance testing for chewable and outdoor devices extends product development timelines and raises qualification costs.
- Veterinary channel gatekeeping:Health tracker adoption depends on diagnostic data integration with clinic management systems, creating dependency on third-party software vendors.
Strategic Opportunities
- Subscription-compatible replenishment models:Smart feeders with automated food ordering create recurring revenue streams beyond one-time hardware sales.
- Cellular-LPWAN hybrid tracking:GPS collars combining geofencing software with low-power wide-area networks address rural coverage gaps that pure cellular fails to reach.
- Veterinary diagnostic data premiums:Health trackers with FDA-recognized physiological monitoring commands pricing power in clinic procurement channels.
Industry Challenges
- Interoperability standardization delays:Proprietary IoT platforms resist integration with third-party smart home ecosystems, fragmenting user experience and raising switching costs.
- California Proposition 65 compliance:Labeling mandates for phthalates and heavy metals create a de facto national compliance floor, complicating SKU management for US-bound products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Gadgets Market |
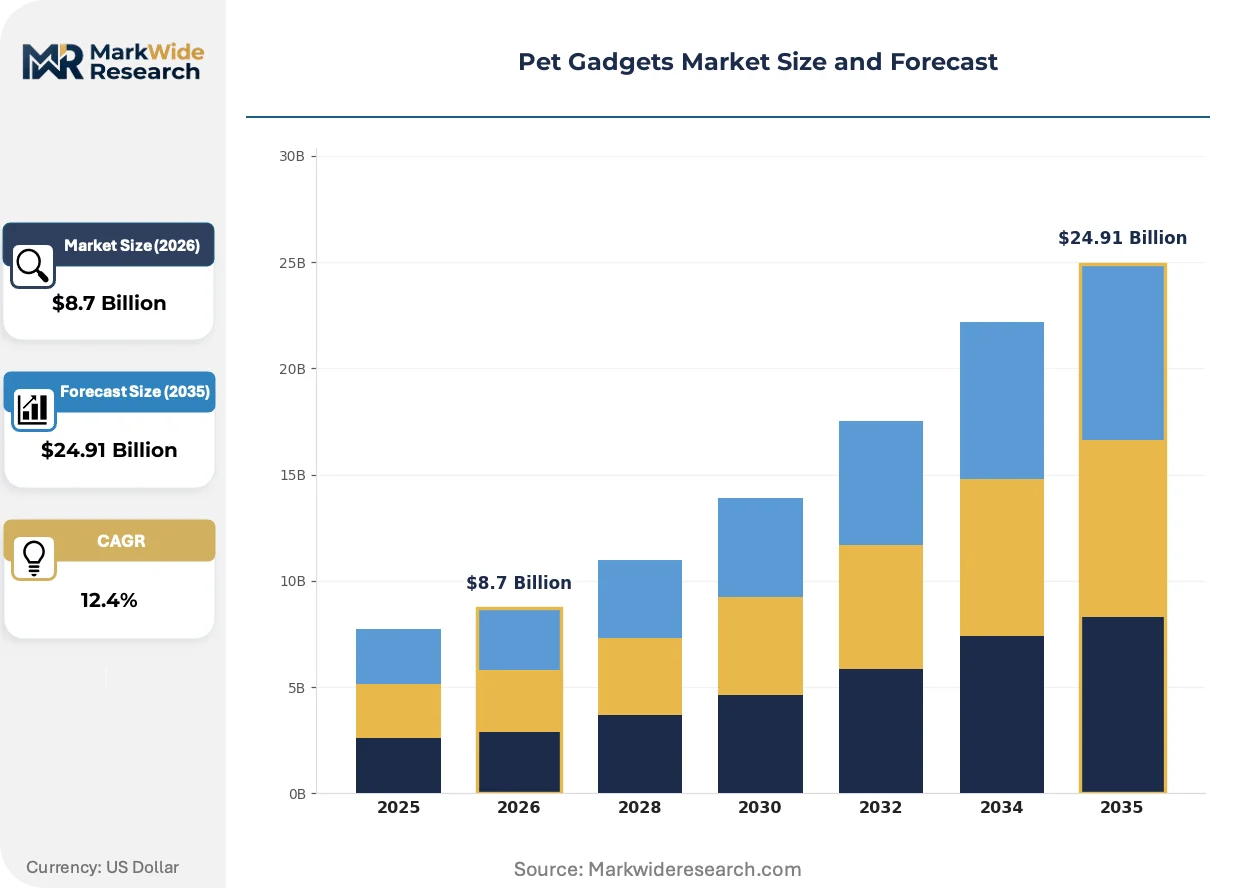
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $24.91 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Feeders, GPS Collars, Automated Toys, Health Trackers Application: Pet Safety, Training, Health Monitoring, Entertainment End User: Pet Owners, Veterinary Clinics, Pet Retailers, Animal Shelters Technology: IoT, Bluetooth, AI, Machine Learning |
| Companies Covered | Central Garden & Pet Company, Hartz Mountain, PETKIT, Swift Paws, BistroCat, PetSafe, Ferplast, Cheerble, Rolf C Hagen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Gadgets Market Evolving Landscape
Three interconnected developments are compressing product cycles and redrawing competitive boundaries: materials science advances in electronics housings, regulatory pressure on chemical content, and the unbundling of hardware from service revenue.
Biodegradable polymer composites are absorbing traditional ABS and polycarbonate in chewable toy housings. European brands facing REACH restrictions on phthalates are accelerating adoption of plant-fiber reinforced thermoplastics. This material transition is absorbing margin from conventional petrochemical suppliers and concentrating it with compounders holding compostability certifications.
The EU REACH framework is tightening restrictions on heavy metals in devices with oral contact exposure. Manufacturers must now qualify alternative stabilizers and pigments, extending supplier audit timelines. Veterinary-grade health trackers with chewable housings face the steepest reformulation burden, with some brands delaying European launches pending ECHA substance evaluations.
Pet owners are unbundling after-sales service from hardware purchases, demanding standalone app subscriptions for behavioral analytics and tele-vet consultations. Direct-to-consumer channels are capturing this spend previously retained by retailers. The United States exhibits the sharpest channel shift, where Chewy and Amazon subscription programs now influence feeder and collar brand selection ahead of in-store availability.
Pet Gadgets Market Segmentation
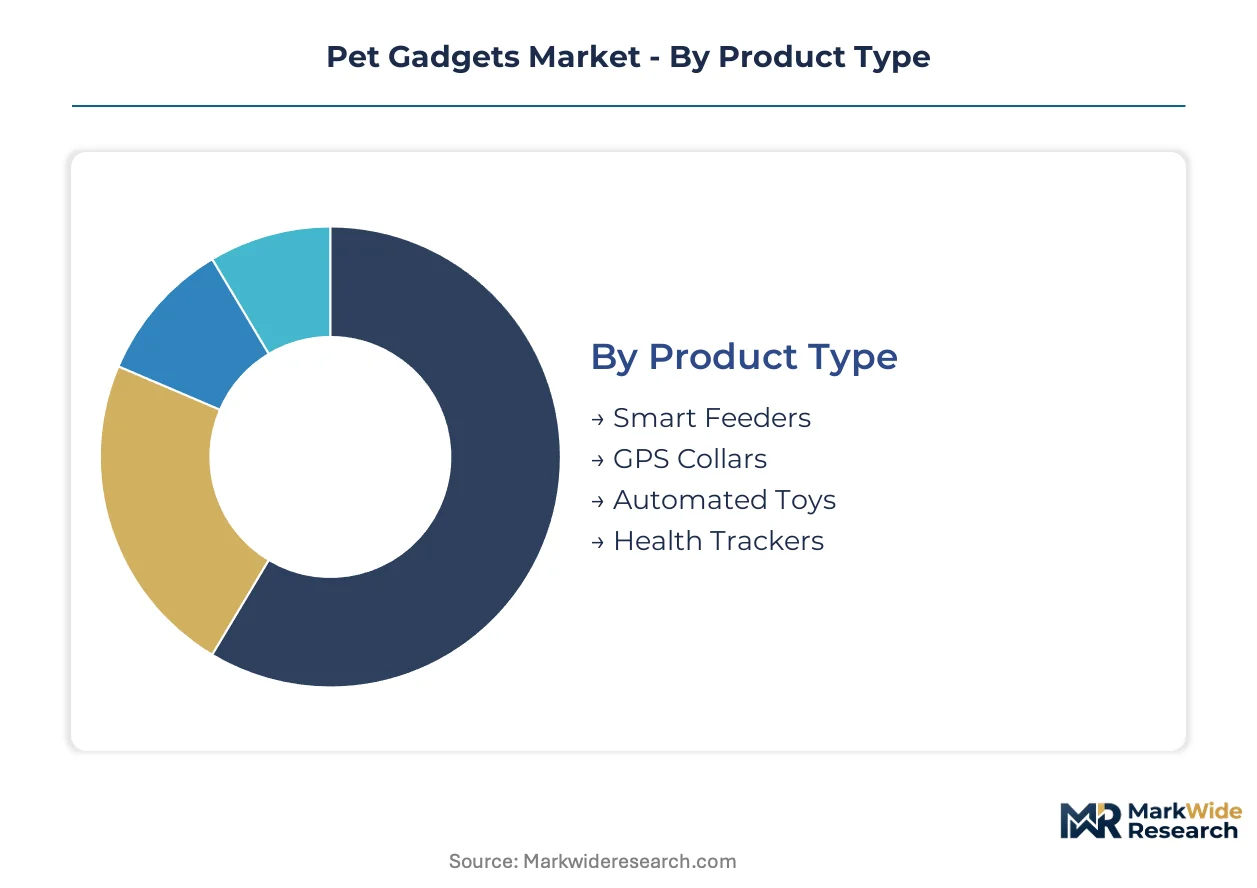
Pet gadgets manufacturers align R&D investment and distribution partnerships around distinct product architectures and use-case intensity. Segmentation reveals where subscription economics concentrate versus where one-time hardware sales dominate.
Product Type:
Supply concentration clusters around electromechanical assemblies with cellular connectivity and cloud backend dependencies.
- Smart Feeders:These devices incorporate load-cell portion control, 2.4 GHz Wi-Fi modules, and companion apps enabling remote scheduling. Demand concentrates in US suburban households with dual-income pet owners seeking automated replenishment tied to subscription food delivery. FDA oversight of feed-containment materials shapes supplier qualification timelines.
- GPS Collars:Hybrid cellular-LPWAN transceivers with geofencing firmware dominate technical specifications. Rural US markets with spotty cellular coverage drive fastest uptake, where satellite backup justifies premium pricing over Bluetooth-only alternatives. FCC RF emissions certification extends development cycles.
- Automated Toys:Lithium-polymer powered robotics with obstacle avoidance sensors occupy the mid-price tier. Japanese and South Korean design houses supply compact motor assemblies.
- Health Trackers:Physiological sensors with veterinary diagnostic data integration command clinic procurement channels. EU REACH compliance for chewable housings constrains material sourcing.
Smart feeders absorb the bulk of installed capacity; GPS collars are expanding most quickly.
Application:
Cost tier stratification separates premium diagnostic deployments from mass-market behavioral devices.
- Pet Safety:Geofencing and escape-alert systems rely on real-time location APIs with sub-10-meter accuracy. US fenceless property owners in Texas and Florida represent the densest demand clusters.
- Training:Clicker-integrated wearables with tone and vibration feedback address obedience reinforcement. Professional trainer endorsements in California and New York metropolitan areas accelerate adoption.
- Health Monitoring:Continuous glucose, heart-rate, and activity sensors with tele-vet dashboard integration. Veterinary clinic procurement in Germany and France concentrates margin pools here.
- Entertainment:Automated laser and treat-dispensing units with app-controlled variability. Mass-market retail channels in UK and US big-box stores dominate volume.
Health monitoring captures the steepest pricing premiums; entertainment applications drive the highest unit volumes.
End User:
Customer type determines channel configuration and service attachment rates.
- Pet Owners:Direct-to-consumer purchases through Amazon and Chewy subscription programs. US millennial and Gen Z cohorts exhibit strongest attachment to app-ecosystem brands.
- Veterinary Clinics:Diagnostic-grade device procurement with EHR integration requirements. German and French clinic chains enforce CE-MDR compliance for physiological monitoring claims.
- Pet Retailers:Mass-market SKU assortment with private-label pressure. UK and US specialty chains negotiate exclusive distribution windows.
- Animal Shelters:Cost-optimized tracking and feeding solutions with bulk procurement terms. Municipal shelter networks in California and Texas represent concentrated demand.
Pet owners generate the majority of recurring service revenue; veterinary clinics anchor premium hardware pricing.
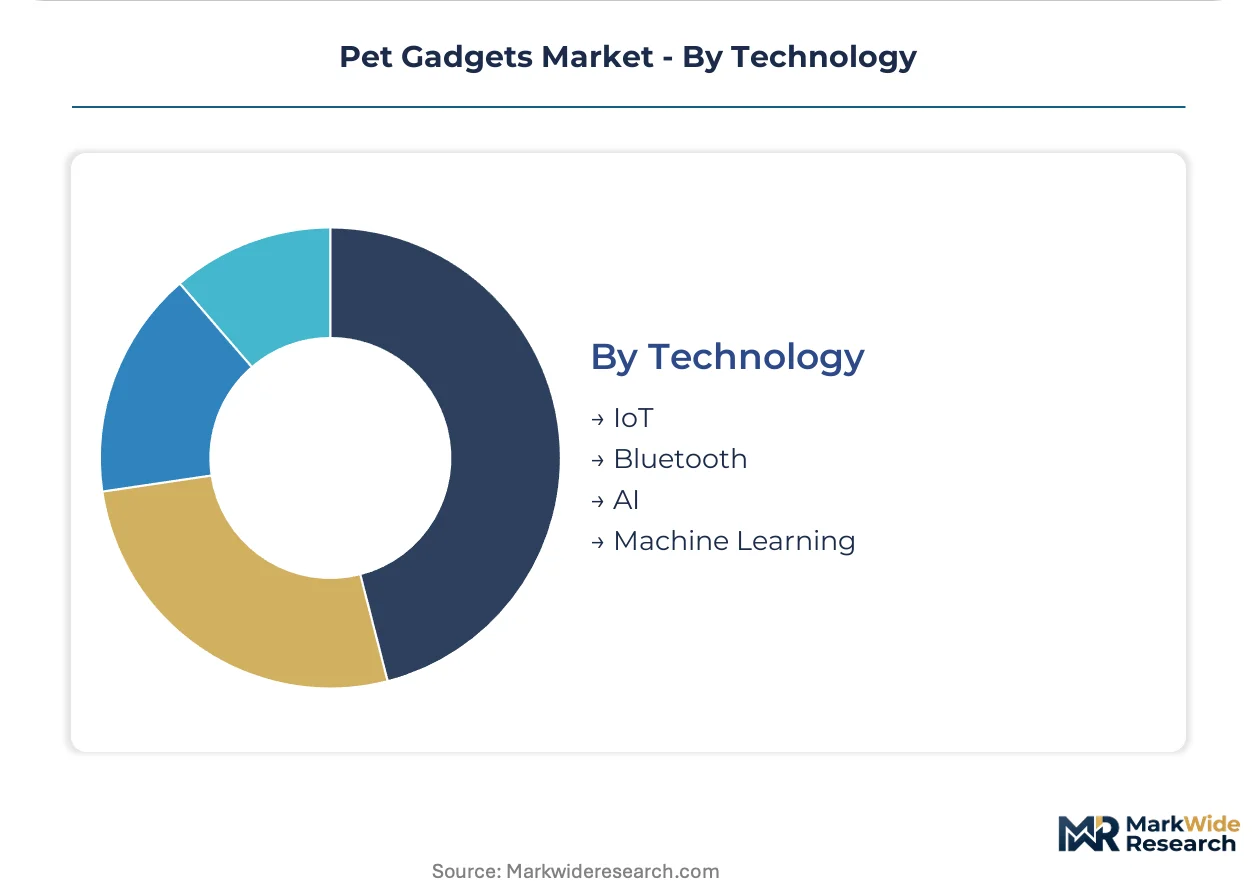
Technology:
Volume concentration favors mature wireless standards over emerging AI inference deployments.
- IoT:Cloud-connected device architectures with proprietary backend infrastructure. AWS and Azure hosting costs concentrate operational expenditure for mid-size brands.
- Bluetooth:Low-energy proximity protocols for indoor tracking and feeder pairing. Smartphone ubiquity eliminates gateway requirements, reducing BOM cost.
- AI:Behavioral pattern recognition and anomaly detection in health data streams. Edge inference on-device remains rare; most processing routes through cloud APIs.
- Machine Learning:Predictive feeding algorithms and activity baseline establishment. Training data scarcity limits model accuracy for niche breeds.
IoT and Bluetooth dominate current installed base; AI implementations are climbing the fastest among new product introductions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pet gadget manufacturing concentrates in East Asian electronics clusters while consumption tilts toward Western markets with high pet ownership rates and smart home penetration. The United States absorbs the largest share of finished devices, though final assembly and lithium-polymer cell production remain concentrated overseas.
United States
Dual-income suburban households in Texas and Florida drive GPS collar adoption for fenceless properties. The FCC enforces RF emissions certification for all connected feeders and wearables. Austin and Seattle host the densest software engineering clusters for pet IoT platform development.
Germany
Veterinary clinic chains in Bavaria and North Rhine-Westphalia anchor procurement of diagnostic-grade health trackers. The EU Green Deal's extended producer responsibility rules force housing redesigns for chewable devices. Stuttgart's automotive sensor suppliers are pivoting into pet wearable component manufacturing.
China
Shenzhen and Dongguan electronics corridors supply compact motor assemblies for automated toys and lithium-polymer cells for collars. MIIT governs wireless module certification for domestic and export-bound devices. Domestic demand concentrates in Shanghai and Beijing among affluent millennial pet owners.
United Kingdom
London and Southeast England exhibit strongest attachment to subscription-compatible smart feeders tied to Chewy and Amazon programs. REACH compliance for phthalate-free housings constrains supplier qualification. Manchester hosts emerging direct-to-consumer brand headquarters targeting EU export markets.
Japan
Tokyo and Osaka metropolitan areas drive compact robotic toy demand with premium design expectations. METI oversees technical standards for household electronics with animal interaction features. Nagoya's precision motor manufacturers supply obstacle-avoidance systems for automated entertainment devices.
Pet Gadgets Market Competitive Landscape
The competitive structure tilts toward vertically integrated specialists with proprietary app ecosystems and mass-market distributors with big-box retail scale. The vendor base spans three tiers: premium connected-care brands with recurring revenue models, mid-market electronics specialists with component sourcing advantages, and private-label suppliers serving price-sensitive retail channels. Dominant competitive moves include backward integration into lithium-polymer cell supply and exclusive distribution partnerships with veterinary clinic networks.
Among Asia-Pacific-based connected-care specialists, PETKIT exemplifies the app-ecosystem archetype with recurring service attachment, while Cheerble occupies the compact robotics design tier. Central Garden & Pet Company anchors the mass-market distribution archetype through big-box retail penetration. These three players represent the strategic poles—proprietary platform control, industrial design differentiation, and channel scale—that structure competitive positioning across price tiers.
| Leading Market Players |
|---|
| Central Garden & Pet Company |
| Hartz Mountain |
| PETKIT |
| Swift Paws |
| BistroCat |
| PetSafe |
| Ferplast |
| Cheerble |
| Rolf C Hagen |
| Others |
Value Network & Pricing Analysis
Veterinary clinic procurement in Germany and France anchors premium pricing for diagnostic-grade health trackers, while mass-market pet owners through Amazon and Chewy subscription programs drive volume-tier economics for smart feeders.
Pricing Analysis
Margin tightening in the mass-market tier reflects lithium-polymer cell cost volatility and IPX5–IPX7 certification overhead. Three-tier pricing structure across premium, standard, and economy levels separates FDA-recognized veterinary devices from consumer-grade trackers and private-label alternatives. Pricing pressure stems from REACH compliance costs for phthalate-free housings in EU-bound products. Clinic procurement channels exhibit lowest price sensitivity; big-box retail SKU managers demonstrate highest elasticity.
Supply Chain Analysis
EU REACH substance evaluations and FCC RF emissions certification function as qualification gates that extend supplier audit timelines. Manufacturing concentrates in China, South Korea, and Japan for lithium-polymer cells, compact motor assemblies, and wireless modules. Raw material dependencies include plant-fiber reinforced thermoplastics, rare-earth magnets, and cellular transceiver chipsets. Single-source vulnerability clusters around East Asian battery cell production. Distribution runs through direct-to-consumer platforms and veterinary clinic networks with diverging service attachment models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pet gadgets sector sits at a connectivity transition phase, where cellular-LPWAN hybrid tracking displaces Bluetooth-only location systems and cloud-based behavioral analytics replace standalone hardware sales.
For Market Incumbents: Anticipate margin compression from modular, repairable designs mandated by EU Green Deal extended producer responsibility rules. Prioritize backward integration into lithium-polymer cell supply to reduce exposure to East Asian logistics disruptions. Defend clinic channel position through FDA-recognized diagnostic data integration that emerging entrants cannot rapidly replicate.
For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models targeting US millennial and Gen Z pet owners with app-ecosystem bundling. White-space opportunity concentrates in rural GPS collar markets with satellite backup where cellular coverage gaps persist. Penetrate through tele-vet consultation partnerships that incumbent hardware vendors underinvest in.
For Investors and Strategic Acquirers: The window for entry favors vertically integrated specialists with proprietary IoT platforms and recurring service revenue attachment. Long-term viability hinges on regulatory compliance infrastructure that compounds competitive moats. Watch for ECHA substance evaluation outcomes on alternative stabilizers as inflection indicators for European market access costs.
| Strategic Initiative | Industry Significance |
|---|---|
| Subscription-Compatible Hardware Launch | Chewy and Amazon programs now influence brand selection ahead of retail availability. |
| EU REACH Compliance Investment | ECHA substance evaluations on phthalate alternatives determine European launch timelines. |
| Veterinary Diagnostic Data Integration | FDA-recognized physiological monitoring commands premium pricing in clinic procurement. |
| Cellular-LPWAN Hybrid Tracking Deployment | Geofencing software with satellite backup addresses rural coverage gaps pure cellular cannot reach. |
| Modular Design and Take-Back Infrastructure | Extended producer responsibility rules restructure cost allocation across the value chain. |
Research Methodology
Multi-period observation of subscription attachment rates, certification timeline extensions, and material substitution patterns anchored the trend analysis, supplemented by interviews with pet IoT platform engineers, veterinary clinic procurement managers, big-box retail category buyers, lithium-polymer cell sourcing directors, and EU regulatory affairs specialists. Secondary validation drew from FCC equipment authorization databases, ECHA substance registration dossiers, AWS and Azure hyperscaler capex disclosures, and customs records of wireless module imports. Bottom-up unit economics modeling triangulated against top-down market sizing across product type, application, end user, and technology dimensions.
Segment-weighting approaches applied differential growth assumptions to subscription-compatible smart feeders versus one-time hardware sales for automated toys. Product type, application intensity, end-user channel configuration, and connectivity technology stratification structured the analytical framework across the projection horizon. CAGRs derived from installed base expansion curves and replacement cycle compression in health monitoring segments. Forecast inputs incorporated EU Green Deal implementation timelines and veterinary software vendor partnership exclusivity patterns.
REACH substance evaluation delays, lithium-polymer supply disruptions, and smart home interoperability standardization failures are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and platform ecosystem consolidation trajectories. A model refresh is warranted upon material change in ECHA prioritization of alternative stabilizers for chewable device housings.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Pet Grooming Products Market
Pet Care Products
Tofu Cat Litter Market
Pet Care Products
Cat Litter Market
Pet Care Products
Dog Boot for Winters Market
Pet Care Products
Asia-Pacific Pet Food Market
Pet Care Products
Smart Cat Eye Market
Pet Care Products
Plant-Based Pet Food Market
Pet Care Products
UK Pet Training Services Market
Pet Care Products
Paw Plunger Market
Pet Care Products
Japan Pet Food Market
Pet Care Products
Pet Dental Health Market
Pet Care Products
Pet Slow Feeder Bowl Market
Pet Care Products
Toy Dog Market
Pet Care Products
Organic Pet Food Market
Pet Care Products
Japan Dog Food Market
Pet Care Products
Dry Dog Food Market