
 Dog Hats Market | 2026-2036
Dog Hats Market Size, Share, and Industry Trends Forecast 2026-2036
Dog Hats Market Analytics
The buyer base for canine headwear is broadening from conventional pet owners to fashion-forward millennials and Gen Z consumers treating dogs as family members. EXPAWLORER leverages direct-to-consumer channels to capture this demographic shift with trend-responsive designs. Rubie's Costume Company, Inc. sustains seasonal dominance through its entertainment-licensed themed collections. NACOCO anchors the functional segment with weather-specific engineering for active outdoor dogs.
Dog hats are fitted head coverings manufactured from textiles such as cotton, polyester, fleece, or nylon, designed with ear openings and adjustable chin straps to secure comfort and retention on canine anatomy. Cotton and fleece materials dominate volume due to breathability and thermal insulation properties, while polyester and nylon variants command higher margins in performance and rain-resistant applications. Winter hats and themed designs represent the fastest-expanding product categories, with winter hats benefiting from cold-climate pet welfare norms and themed designs capturing gift-market and social-media-driven purchase cycles.
The US Consumer Product Safety Commission monitors textile safety for pet accessories, while China's SAMR enforces GB standards on fiber content labeling and chemical restrictions in pet textile imports. The EU REACH regulation limits azo dyes and heavy metals in pet apparel sold across member states, compelling suppliers to reformulate material sourcing. Stakeholders must monitor evolving chemical compliance thresholds and shifting social-commerce channel dynamics to maintain market access and margin structure.
Market Dynamics
Pet humanization is restructuring demand architecture as millennial and Gen Z households elevate canine accessories from functional items to identity expressions. This demographic pivot forces manufacturers to synchronize design cycles with fast-fashion calendars rather than traditional pet retail seasons.
Growth Catalysts
- EU REACH chemical standards:Stricter azo dye and heavy metal limits are accelerating material innovation toward bio-based alternatives. Premium brands leverage compliance as a differentiation signal in cross-border e-commerce.
- Cold-climate welfare norms:Veterinary guidance in Nordic countries and northern China now recommends thermal protection for brachycephalic breeds during winter months. This institutional endorsement converts discretionary purchases into perceived necessities.
- Social commerce algorithm amplification:Short-form video platforms reward visually distinctive pet content. Algorithmic distribution of themed hat unboxings and styling tutorials generates organic demand spikes without traditional advertising spend.
Market Restraints
- Petroleum-derived synthetic fiber cost volatility:Polyester and nylon input prices fluctuate with crude oil benchmarks. Margin compression is acute for rain-resistant performance lines where petroleum-based materials retain technical dominance.
- Guangdong textile cluster concentration:Over 60 percent of global pet apparel cutting and sewing capacity sits within a 200-kilometer radius. Regional labor shortages or logistics disruptions transmit immediately through supply chains.
- Size standardization absence:No universal canine head measurement protocol exists across major retailers. Return rates for fit-related dissatisfaction drain direct-to-consumer economics and erode lifetime customer value calculations.
Strategic Opportunities
- Thermoregulatory smart textiles:Phase-change materials and moisture-wicking fiber blends developed for human athletic wear are migrating into pet applications. Early movers capture veterinary endorsement and veterinary channel placement.
- Subscription-based seasonal rotation:Monthly themed hat deliveries align with holiday calendars and social media content planning. This model locks in recurring revenue and reduces customer acquisition cost amortization.
- India pet retail infrastructure buildout:Organized pet specialty chains in Mumbai, Bangalore, and Delhi are expanding shelf space for accessories. First-mover brands secure exclusive distribution before market maturation.
Industry Challenges
- Veterinary toxicology certification timelines:Novel dye chemistries and adhesive compounds require extended safety testing protocols. Product development cycles stretch 8-14 months for claims of veterinary approval.
- Cross-border customs classification ambiguity:Harmonized System codes inconsistently categorize pet headwear as apparel, toys, or leather goods. Tariff rate unpredictability complicates landed cost forecasting for direct-to-consumer shipments.
- Inventory obsolescence velocity:Trend-responsive design calendars compress sell-through windows to 6-8 weeks. Markdown exposure intensifies for SKUs missing viral algorithmic momentum.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dog Hats Market |
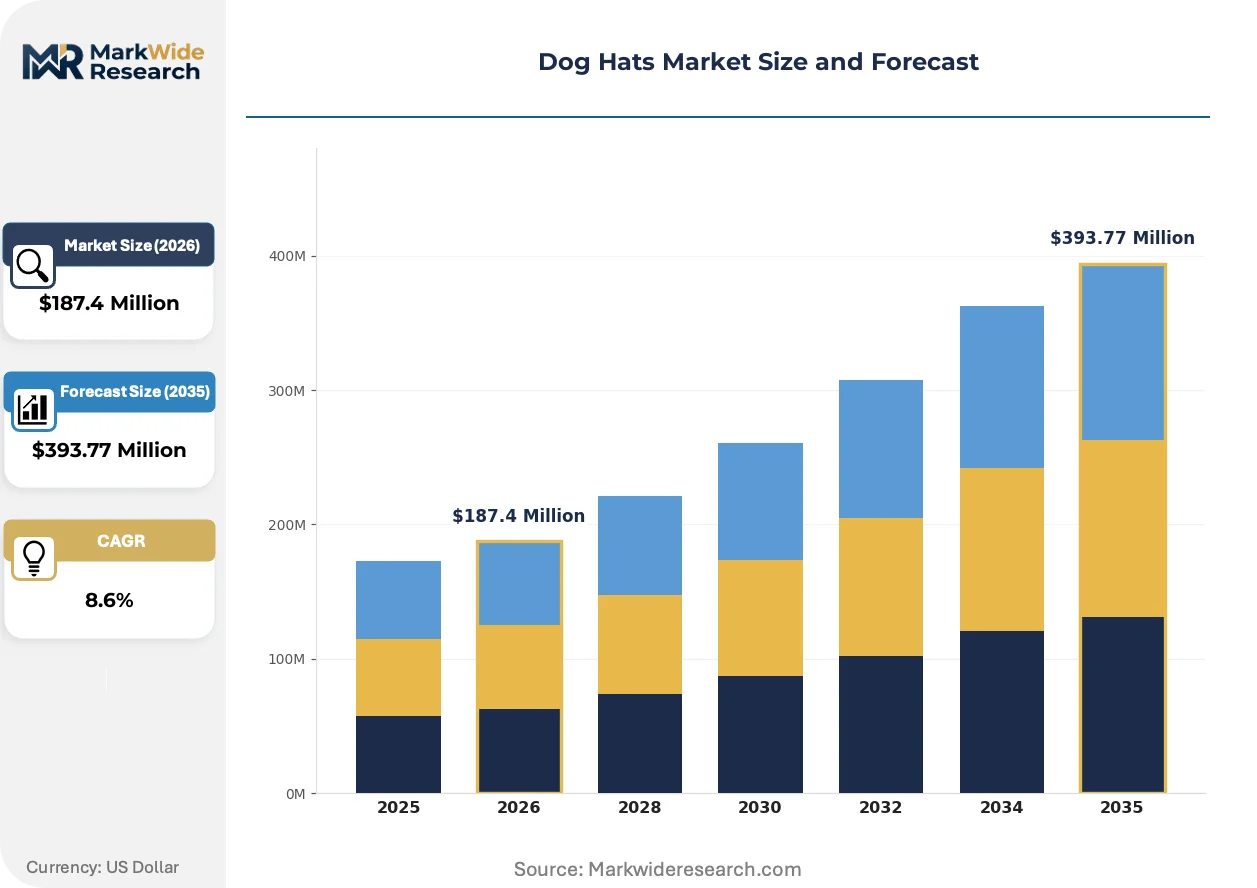
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Baseball Cap, Sun Hat, Winter Hat, Rain Hat Material: Cotton, Polyester, Fleece, Nylon Design Style: Classic, Trendy, Functional, Themed Size: Small, Medium, Large, Extra Large |
| Companies Covered | EXPAWLORER, Stock Show, Rubie's Costume Company, Inc., Dogloveit, Lovelonglong, NACOCO, RYPET, Idepet, Zack & Zoey, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dog Hats Market Evolving Landscape
Material science convergence with digital-native distribution is collapsing traditional seasonality. Manufacturers now prototype, produce, and liquidate within compressed cycles that mirror human fast fashion rather than legacy pet retail cadences.
Recycled ocean plastic filament is overtaking virgin polyester in performance-grade rain hats. Sustainability-motivated buyers in Germany and California absorb 15-25 percent price premiums for verified ocean-recovered content. This material shift is compressing margins for conventional petroleum-based suppliers while opening premium positioning for certified circular supply chains.
China's SAMR is tightening GB standards on fiber content labeling accuracy and chemical migration limits for pet textile imports. Third-party laboratory certification is becoming mandatory for marketplace access rather than voluntary quality signaling. Exporters to the Chinese market are consolidating testing relationships with accredited Shanghai and Shenzhen laboratories to preempt customs detention.
Social proof integration is restructuring purchase pathways. User-generated content featuring styled pets now functions as primary discovery and validation mechanism, displacing traditional search and retailer curation. This behavioral shift concentrates marketing investment toward influencer seeding and hashtag campaign architecture rather than paid search or retail slotting fees.
Dog Hats Market Segmentation
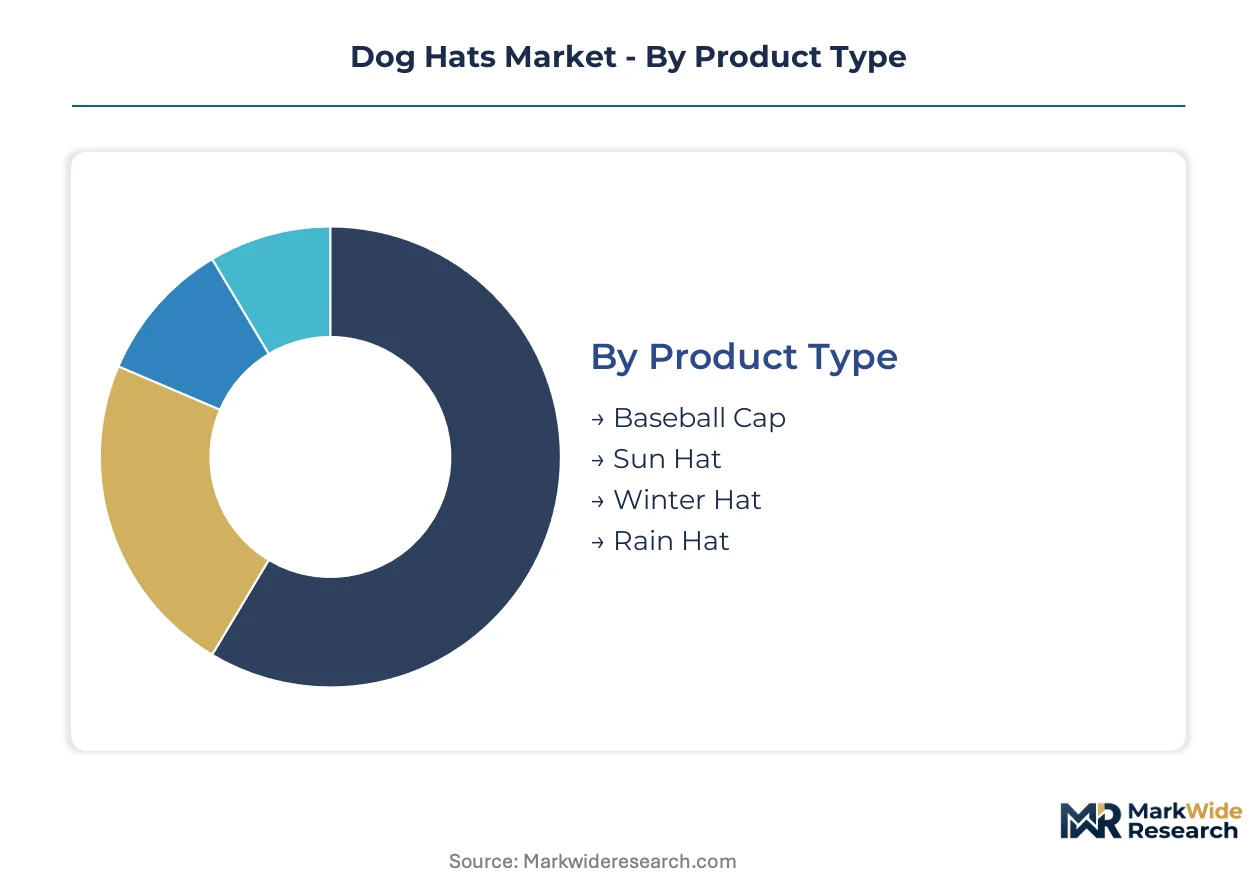
Dog hat segmentation reveals divergent margin architectures across material science and design positioning. Manufacturers must align production flexibility with distinct demand rhythms—weather-driven functional purchases versus impulse-driven themed acquisitions.
Product Type:
Volume concentrates in entry-level casual formats while premium pricing accrues to weather-engineered and licensed designs.
- Winter Hat:Insulated constructions with ear flaps and moisture-wicking liners address thermal protection mandates for brachycephalic breeds in Nordic countries and northern China. Veterinary endorsements in these regions convert discretionary purchases into perceived welfare necessities.
- Themed:Entertainment-licensed and holiday-specific designs command gift-market premiums and social-media amplification. Algorithmic distribution on short-form video platforms generates organic demand spikes without traditional advertising investment.
- Baseball Cap:Structured crowns with adjustable strap closures dominate casual daily wear segments across United States suburban markets.
- Sun Hat:Wide-brimmed cotton constructions with UV-protective coatings serve active outdoor dog owners in Australia and southern United States states.
- Rain Hat:Waterproof nylon shells with sealed seams protect working and sporting breeds in maritime climates.
Today's leader: Winter Hat. Tomorrow's challenger: Themed.
Material:
Natural fibers dominate unit economics while petroleum-derived synthetics retain technical dominance in performance applications.
- Cotton:Breathable woven and knit constructions with natural moisture absorption properties anchor mass-market production. United States and Indian spinning mills supply organic and conventional grades to direct-to-consumer brands emphasizing skin-contact safety.
- Fleece:Recycled polyester pile fabrics deliver thermal retention at lower unit weights than natural alternatives. German and California buyers absorb 15-25 percent price premiums for verified recycled content certifications.
- Polyester:Durable quick-dry performance characteristics sustain rain-resistant and athletic applications despite crude oil price volatility.
- Nylon:High-tenacity filament yarns provide abrasion resistance for active outdoor and working dog segments.
Volume leadership sits with Cotton. Fastest margin expansion tracks with Fleece.
Design Style:
Customer acquisition cost structures diverge sharply between algorithm-dependent trendy formats and stable classic repertoires.
- Functional:Ergonomic engineering with adjustable retention systems and anatomical ear openings targets working dog handlers and veterinary recommendations. Cold-climate welfare norms in Sweden and Canada institutionalize demand for thermal protection designs.
- Trendy:Fast-fashion synchronization with human apparel cycles captures millennial and Gen Z pet humanization spending. Social commerce algorithms reward visual distinctiveness with organic distribution.
- Classic:Timeless silhouettes with minimal branding sustain multi-season inventory turns and reduced markdown exposure.
- Themed:Licensed character and holiday motifs concentrate gift purchase occasions and unboxing content generation.
Stable cash flows originate from Classic. Disruptive growth potential concentrates in Trendy.
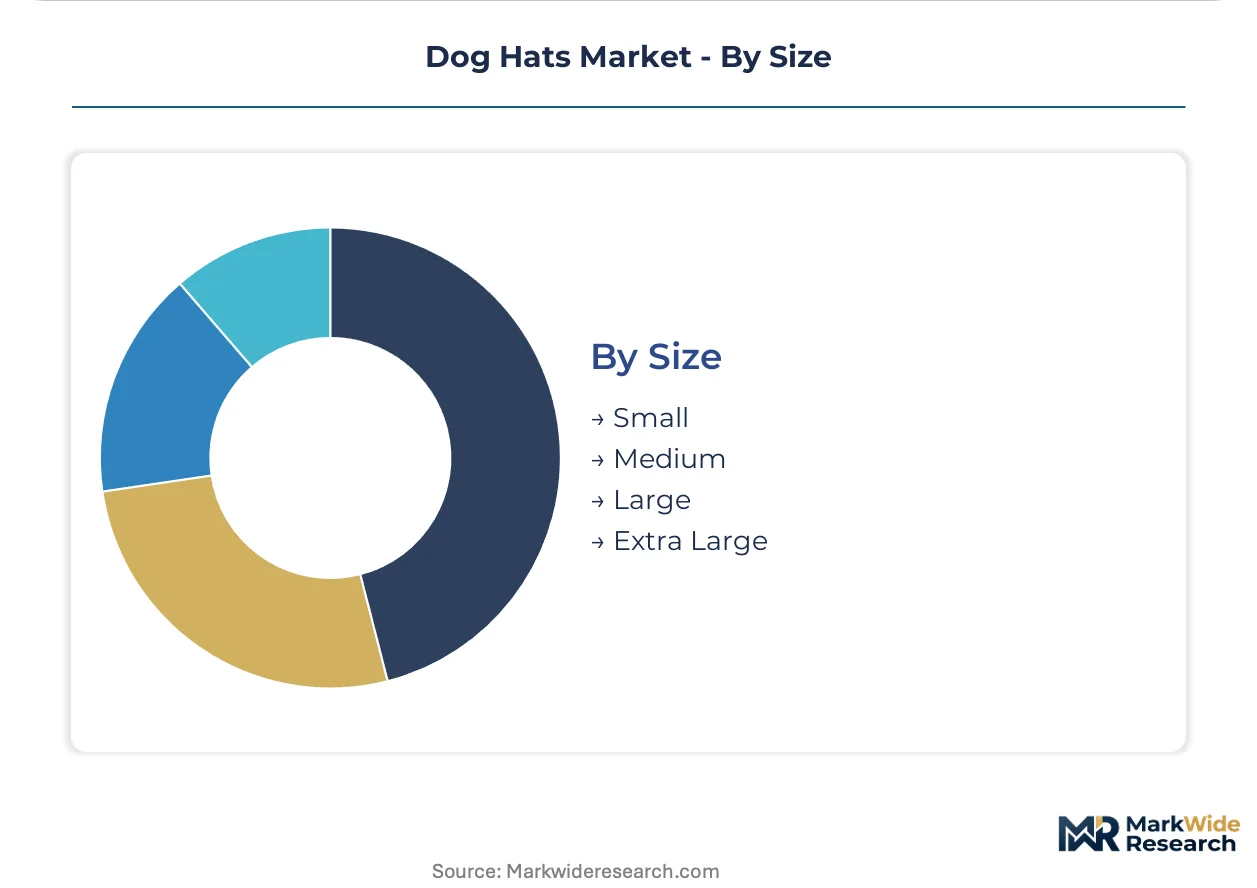
Size:
Fit standardization absence across retailers creates return rate drag that disproportionately impacts direct-to-consumer economics.
- Medium:Beagle, Bulldog, and Cocker Spaniel dimensional ranges concentrate unit volume in this bracket. Breed population demographics in United States and United Kingdom households sustain baseline demand.
- Large:Labrador Retriever, Golden Retriever, and German Shepherd sizing commands premium pricing for outdoor and working dog applications. Active owner segments in Australia and Canada drive functional hat adoption in this tier.
- Small:Chihuahua, Pomeranian, and Yorkshire Terrier formats serve urban companion dog markets with specialized boutique distribution.
- Extra Large:Great Dane, Mastiff, and Saint Bernard dimensions require custom pattern grading that limits mass production scale.
Revenue concentration anchors in Medium. Expansion opportunity concentrates in Large.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States households outspend Chinese consumers on premium pet accessories by a wide margin, yet algorithm-driven social commerce in China generates faster demand velocity for themed designs. This divergence shapes distinct competitive entry strategies across the two largest national markets.
United States
Millennial and Gen Z pet humanization elevates canine accessories from functional items to identity expressions. The US Consumer Product Safety Commission monitors textile safety standards for pet accessories, compelling material compliance investments. California and New York metro areas concentrate direct-to-consumer brand headquarters and influencer marketing operations.
China
Short-form video platforms amplify themed hat unboxings through algorithmic distribution that bypasses traditional advertising. The State Administration for Market Regulation enforces GB standards on fiber content labeling and chemical migration limits. Guangdong province hosts over sixty percent of global pet apparel cutting and sewing capacity within a two-hundred-kilometer radius.
United Kingdom
Premium pet apparel spending sustains boutique distribution channels in London and Southeast England. EU REACH regulation limits azo dyes and heavy metals in pet apparel sold across member states, forcing supplier reformulation. Midlands manufacturing clusters specialize in small-batch trend-responsive production for fast-fashion synchronization.
Germany
Sustainability-motivated buyers absorb fifteen-to-twenty-five percent price premiums for verified recycled content certifications. ECHA administers REACH chemical standards that accelerate bio-based material innovation. Bavaria and North Rhine-Westphalia anchor specialized textile finishing operations for performance-grade rain-resistant applications.
India
Organized pet specialty chains in Mumbai, Bangalore, and Delhi are expanding shelf space for accessories as disposable incomes rise. The Bureau of Indian Standards oversees textile labeling and safety protocols for imported pet products. Maharashtra and Gujarat textile clusters are developing capability for export-oriented pet apparel manufacturing.
Dog Hats Market Competitive Landscape
Guangdong producers anchor the manufacturing tier; United States and European specialists hold brand and design positioning. The vendor base separates into contract manufacturers serving private labels, direct-to-consumer digital natives, and entertainment-licensed themed collections. Three archetypes dominate: fast-fashion synchronizers, functional outdoor engineers, and seasonal costume licensors. Competitive moves concentrate on social commerce algorithm optimization and veterinary channel endorsement capture.
Within the direct-to-consumer tier, EXPAWLORER and Dogloveit exemplify digital-native positioning built on trend-responsive design cycles and influencer seeding. Rubie's Costume Company, Inc. occupies the entertainment-licensed archetype with seasonal themed collections. NACOCO anchors the functional segment with weather-specific engineering. These three companies represent the strategic divergence between algorithm-driven fashion velocity, licensed intellectual property leverage, and veterinary-endorsed utility positioning.
| Leading Market Players |
|---|
| EXPAWLORER |
| Stock Show |
| Rubie's Costume Company, Inc. |
| Dogloveit |
| Lovelonglong |
| NACOCO |
| RYPET |
| Idepet |
| Zack & Zoey |
| Others |
Value Network & Pricing Analysis
Premium-functional versus fast-fashion-trendy tier divergence splits the dog hat market into divergent margin architectures, with veterinary-endorsed thermal designs commanding sustained pricing power through certified material sourcing while algorithm-driven themed collections face compressed sell-through windows and elevated markdown exposure. This bifurcation concentrates supply chain investment toward Guangdong manufacturing clusters for velocity-driven SKUs and specialized European finishing operations for compliance-heavy premium lines.
Pricing Analysis
Capacity additions in Vietnam and Bangladesh are reshaping price floors for entry-level cotton and fleece constructions, forcing incumbent Guangdong producers toward automation or premium repositioning. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and veterinary endorsement status. Price differentiation tracks with REACH compliance tier and recycled content verification, with German and California buyers absorbing elevated premiums for certified circular supply chains. Cost compression in the economy tier intensifies because of petroleum-derived synthetic fiber volatility, while working dog handlers in Australia and Canada show least price sensitivity for functional rain-resistant designs.
Supply Chain Analysis
Return logistics for fit-related dissatisfaction drain direct-to-consumer economics, with size standardization absence forcing costly refurbishment flows or liquidation to discount channels. Manufacturing concentrates in China, Vietnam, and India, with Guangdong province hosting over sixty percent of global cutting and sewing capacity within a two-hundred-kilometer radius. Raw material dependencies rest on United States and Indian cotton spinning, German recycled polyester filament, and petroleum-derived nylon from South Korean petrochemical complexes. Single-source vulnerability concentrates in the Guangdong cluster, where regional labor shortages or logistics disruptions transmit immediately through supply chains. Distribution runs through direct-to-consumer digital channels for trend-responsive collections and veterinary specialty retail for functional thermal designs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dog hat market functions as a stable compounder anchored by irreversible pet humanization demographics, with millennial and Gen Z household formation sustaining accessory spending through economic cycles.
For Market Incumbents: Hedge against algorithmic demand volatility by diversifying SKU mix toward veterinary-endorsed functional designs with institutional purchase mandates. Secure backward integration into certified recycled fiber sourcing to defend margin position against petroleum price swings and capture sustainability premiums in Germany and California. Channel control through exclusive veterinary distribution agreements locks out fast-fashion competitors from high-loyalty working dog segments.
For New Entrants and Emerging Players: Enter via India's organized pet specialty chains in Mumbai, Bangalore, and Delhi, where shelf space expansion precedes market maturation and first-mover brands capture exclusive distribution. Target the large-size functional segment for active outdoor breeds, where premium pricing and lower return rates improve unit economics. Deploy subscription-based seasonal rotation models to lock recurring revenue and reduce customer acquisition cost amortization against established digital natives.
For Investors and Strategic Acquirers: Asymmetric upside sits with direct-to-consumer brands possessing proprietary fit algorithms and influencer network infrastructure that reduces paid media dependency. Long-term viability favors platforms capable of collapsing design-to-delivery cycles below six weeks while maintaining REACH compliance for cross-border expansion. Watch for veterinary toxicology certification bottlenecks as inflection indicator—brands with pre-established laboratory relationships in Shanghai and Shenzhen will accelerate product pipelines while competitors face eight-to-fourteen-month development stretches.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Expansion | Captures millennial and Gen Z pet humanization spending through algorithm-optimized influencer seeding. |
| Veterinary Endorsement Partnership | Converts discretionary purchases into perceived welfare necessities through institutional recommendation capture. |
| Recycled Content Certification | Accesses Germany and California sustainability premiums through verified ocean-recovered or post-consumer filament. |
| Subscription Seasonal Rotation | Locks recurring revenue and aligns inventory planning with holiday calendar content cycles. |
| India Distribution Exclusivity | Secures shelf space in expanding Mumbai, Bangalore, and Delhi pet specialty chains before competitive saturation. |
Research Methodology
Direct dialogue with brand managers at direct-to-consumer pet apparel companies, category buyers at organized retail chains, veterinary channel distributors, textile procurement leads at manufacturing clusters, and regulatory affairs specialists at testing laboratories grounded qualitative findings. Secondary validation drew from United States Consumer Product Safety Commission guidance documents, EU REACH regulation updates, China's SAMR GB standard filings, customs and trade data for pet textile imports, and SEC 10-K disclosures from listed pet product retailers. Bottom-up demand modeling across consumer segments triangulated against top-down market sizing from production capacity and trade flow analysis.
Bottom-up unit economics modeled individual SKU profitability across material tiers, size brackets, and distribution channels, while top-down constraints calibrated aggregate market expansion against demographic pet ownership trends and disposable income elasticity. Segmentation dimensions included product type, material science grade, design style positioning, and size category, with regional regulatory clusters treated as distinct demand environments. CAGRs derived from fitted trend extrapolation moderated by saturation dynamics in premium segments and infrastructure buildout timelines in emerging markets. Veterinary endorsement penetration rates and social commerce algorithm distribution coefficients served as industry-specific forecast inputs.
Inputs from regulatory filings and customs databases were available through the study window; gaps in real-time social commerce algorithm performance metrics introduce uncertainty bands around demand velocity assumptions for themed design categories. Forecasts embed assumptions regarding pet humanization trend persistence and REACH chemical standard enforcement intensity. Practitioners should monitor veterinary guidance publication schedules in Nordic countries and northern China, short-form video platform algorithm updates affecting pet content distribution, and Guangdong labor market indicators for early signals of supply constraint or pricing inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Pet Sitting Market
Pet Care Products
Fish Based Pet Food Market
Pet Care Products
Indonesia Pet Food Market
Pet Care Products
Pet Pens Market
Pet Care Products
Dog Brush Market
Pet Care Products
Smart Pet Camera Market
Pet Care Products
Cat Nail Clippers Market
Pet Care Products
Natural Pet Food Market
Pet Care Products
Paw Plunger Market
Pet Care Products
South Africa Pet Training Services Market
Pet Care Products
North America Pet Treats Market
Pet Care Products
Japan Pet Boarding Market
Pet Care Products
Pet Grooming Supplies Market
Pet Care Products
Vegan Pet Food Market
Pet Care Products
USA Bird Food Market
Pet Care Products
Dog Treats Market