
 Europe Dog Food Market | 2026-2036
Europe Dog Food Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Dog Food Market Insights
Modular portion packaging is pivoting how European households purchase dog food, shifting bulk buyers toward single-serve and subscription-configured formats. Mars Incorporated leverages its pan-European manufacturing footprint to sustain cost advantages across multiple price tiers. Nestlé Purina PetCare anchors its position through specialized veterinary diet channels. Colgate-Palmolive Company (Hill's Pet Nutrition Inc.) differentiates via prescription-grade formulations that command clinic-level pricing.
Europe dog food comprises nutritionally formulated products manufactured to specific protein, fat, fiber, and moisture parameters, with extrusion and retort processing defining dry and wet categories respectively. The primary purpose is species-appropriate canine nutrition delivered through convenient retail and clinical channels. Dry food dominates volume across supermarkets and online retail due to shelf stability and lower logistics costs. Wet food captures disproportionate margin pools in premium and veterinary-directed segments. Raw food represents the fastest-growing product type, though regulatory scrutiny from EFSA and national food safety agencies constrains its expansion.
EFSA sets maximum residue limits and additive permissions that directly determine formulation options across EU member states. REACH and the EU Green Deal mandate progressive reductions in packaging waste and carbon intensity, forcing reformulation of supply chains and material choices. ECHA chemical restrictions further narrow permissible preservatives and processing aids. Stakeholders must monitor evolving national interpretations of these frameworks, as Germany's Bundesamt für Verbraucherschutz und Lebensmittelsicherheit and France's DGCCRF enforce divergent compliance timelines that reshape cross-border product strategies.
Market Dynamics
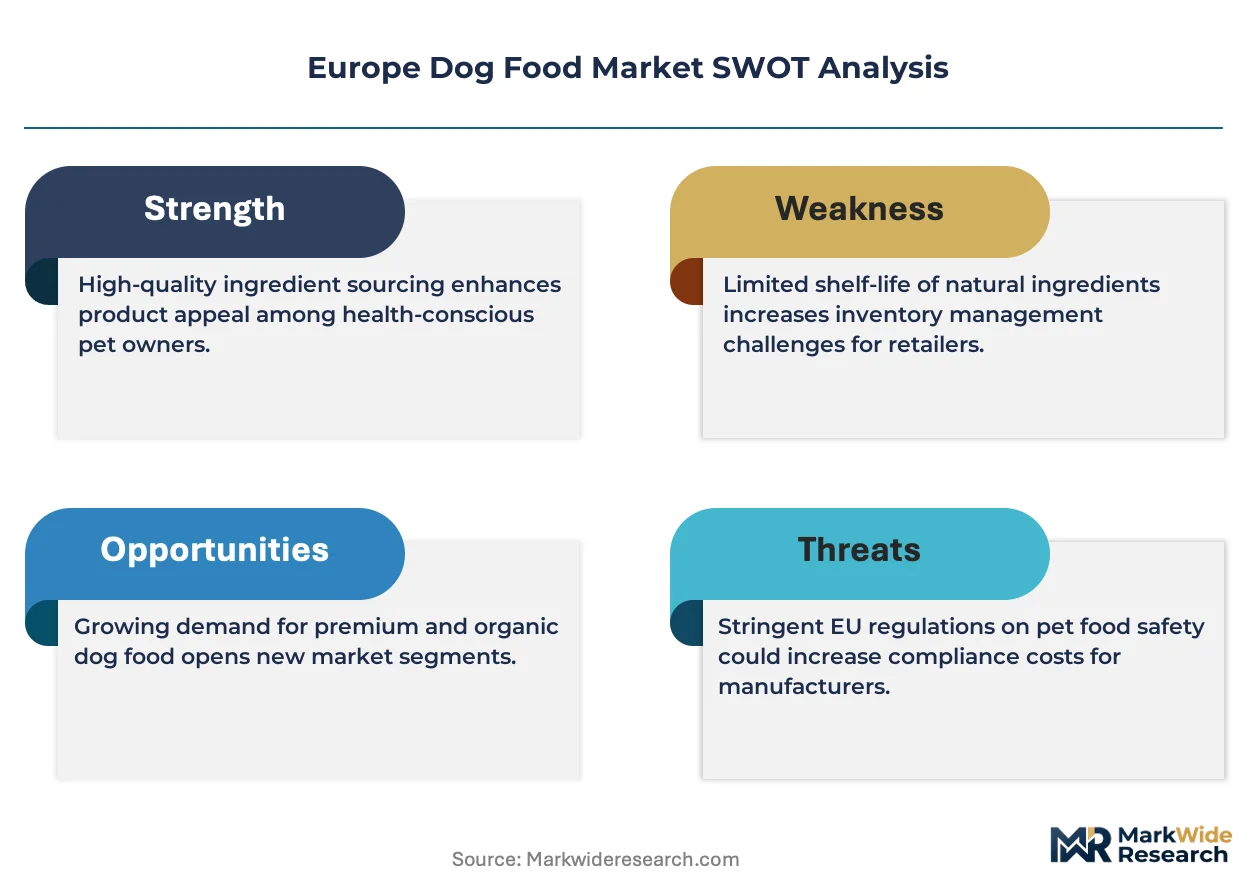
Premiumization pressure from urban pet owners is fragmenting Europe's dog food value chain, forcing manufacturers to reconfigure formulations, sourcing, and packaging simultaneously. The EU Green Deal's carbon accounting requirements now cascade through ingredient procurement decisions.
Growth Catalysts
- EU Green Deal carbon mandates:Binding emissions targets are accelerating investment in low-carbon protein sourcing and renewable energy integration across manufacturing facilities.
- Humanization of pet nutrition:Owners in France, Germany, and the United Kingdom now apply personal dietary preferences—grain-free, organic, functional ingredients—to canine purchasing decisions.
- EFSA additive approvals:Expanded clearance for novel preservatives and nutritional enhancers enables cleaner-label formulations that command shelf price premiums.
Market Restraints
- Animal protein cost volatility:Chicken and fish meal prices fluctuate with aquaculture yields and avian influenza cycles, compressing margin predictability for mid-tier producers.
- Single-source packaging concentration:Flexible film supply concentrates among German and Dutch converters, creating vulnerability to polymer feedstock disruptions.
- Raw food regulatory friction:EFSA and national food safety agencies impose divergent pathogen testing protocols that stall cross-border distribution of freeze-dried and fresh-frozen segments.
Strategic Opportunities
- Underpenetrated Eastern European veterinary channels:Poland, Romania, and Hungary show low penetration of prescription-grade therapeutic diets relative to Western European benchmarks.
- Insect protein regulatory tailwind:EFSA novel food approvals for black soldier fly larvae create a pathway to ultra-low-carbon protein inclusion in premium formulations.
- Subscription-direct channel innovation:Algorithm-driven portion customization and auto-replenishment models bypass supermarket slotting fees while capturing lifetime value data.
Industry Challenges
- Formulation chemist scarcity:Expertise in balancing palatability, shelf stability, and clean-label requirements under REACH constraints commands premium compensation and extends R&D timelines.
- Packaging reconfiguration friction:Transitioning from multi-layer flexible films to mono-material or compostable alternatives requires capital-intensive line retrofits and validation against F-Gas Regulation compliance timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Dog Food Market |
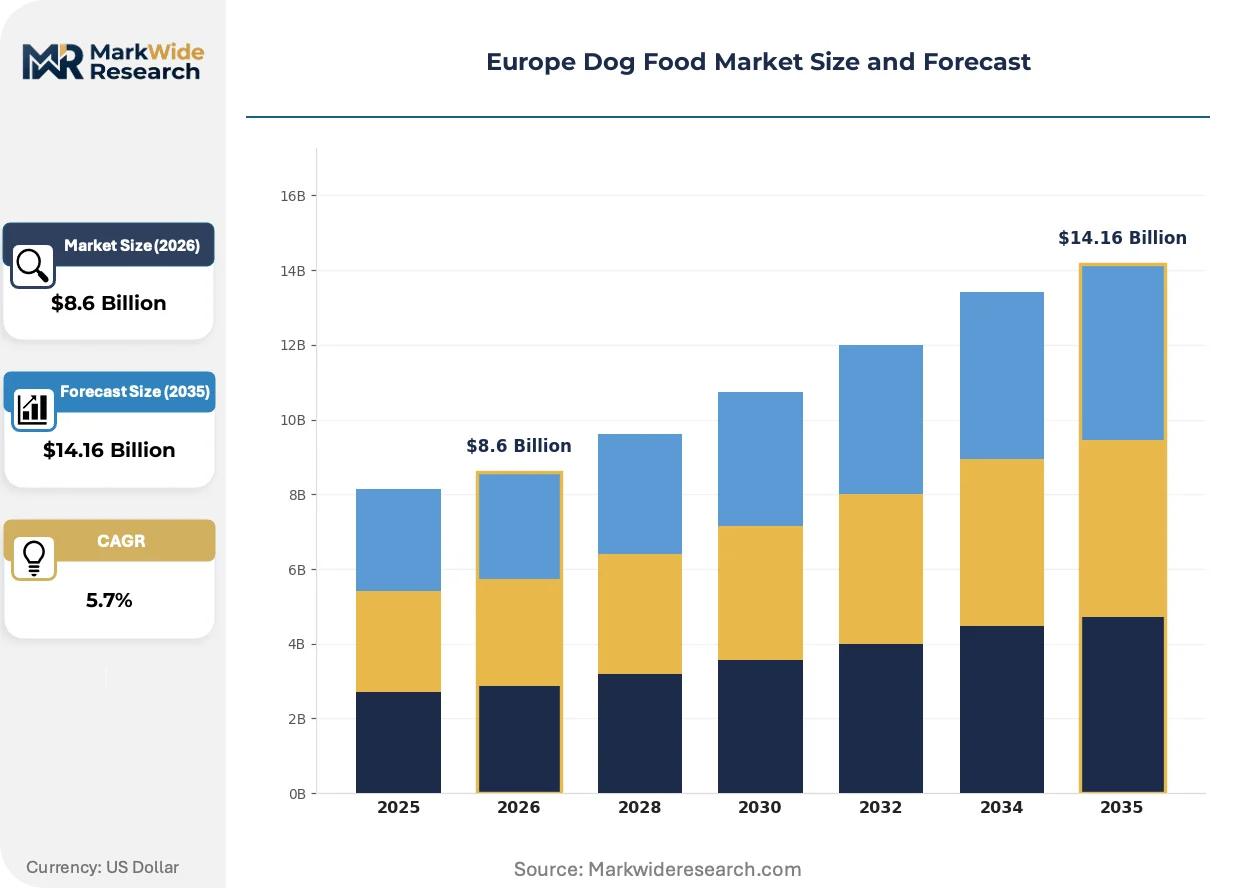
| Market Size in 2026 | $8.6 Billion |
| Market Size in 2035 | $14.16 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Raw Food Customer Type: Pet Owners, Breeders, Pet Stores, Veterinarians Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Veterinarian Clinics Ingredient Quality: Organic, Grain-Free, Natural, Premium |
| Companies Covered | Mars Incorporated, Nestlé Purina PetCare, Colgate-Palmolive Company (Hill's Pet Nutrition Inc.), Affinity Petcare SA, Archer Daniels Midland Company, General Mills Inc., United Petfood, Farmina Pet Foods, Heristo Aktiengesellschaft, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Dog Food Market Trends and Innovations
Digital integration and sustainability mandates are converging to reshape how dog food is formulated, produced, and delivered to European households. Three distinct vectors now determine competitive differentiation.
Extrusion process control systems deploying real-time moisture and density sensors are automating quality consistency across high-volume dry food production. Mid-scale manufacturers in Spain and Italy are adopting these platforms to reduce giveaway and rework rates. The technology is automating the shift from batch-adjustment protocols to continuous-process optimization, compressing the quality gap between specialized and commodity producers.
REACH chemical restrictions are narrowing the preservative toolkit available to European formulators, with ECHA evaluations of specific antioxidant classes triggering preemptive reformulation cycles. Manufacturers must now validate alternative shelf-life extension mechanisms—modified atmosphere packaging, natural extract blends—before regulatory deadlines force abrupt transitions. Wet food and semi-moist segments face the steepest compliance curves given their moisture-dependent spoilage risk profiles.
Urban pet owners are consolidating purchases through specialized e-commerce platforms that bundle veterinary consultation, personalized feeding plans, and auto-delivery logistics. These integrated services disaggregate the traditional supermarket-veterinarian split in pet care procurement. France and the United Kingdom exhibit the highest concentration of platform-native brands that bypass conventional retail entirely.
Europe Dog Food Market Segmentation
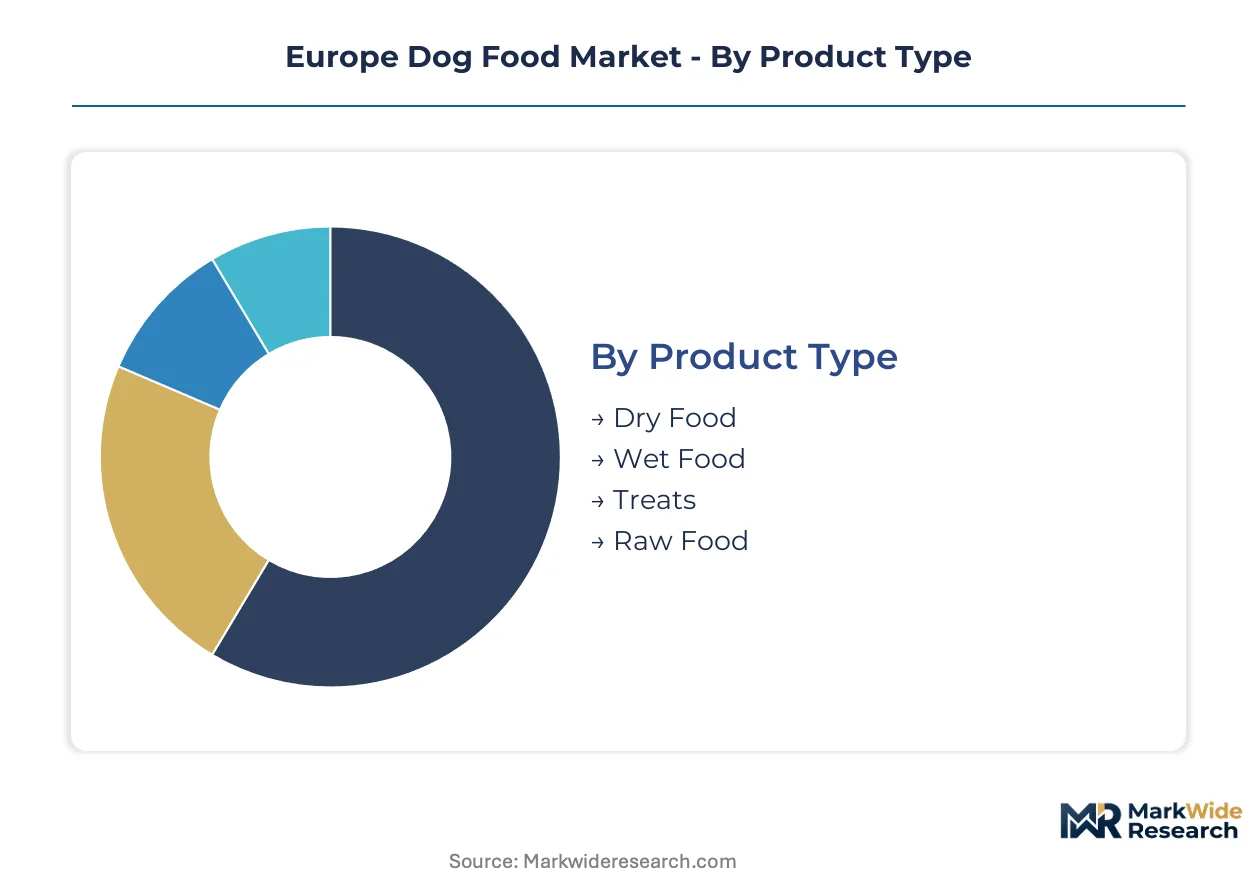
European dog food manufacturers must configure production assets against four intersecting dimensions—product format, buyer category, channel access, and ingredient positioning—each demanding distinct capital allocation and regulatory compliance profiles. Segmentation choices directly determine exposure to EFSA additive rules, REACH packaging mandates, and the EU Green Deal's carbon accounting requirements.
Product Type:
Capital intensity varies sharply across processing technologies, with extrusion and retort systems requiring the heaviest upfront manufacturing investment.
- Dry Food:Extrusion-based production demands high-capacity thermal processing lines with real-time moisture and density control systems. France, Germany, and the United Kingdom concentrate volume demand due to shelf stability preferences and lower logistics costs in urban distribution networks.
- Wet Food:Retort sterilization and canning infrastructure commands premium capital deployment per unit output. Margin pools concentrate in veterinary-directed and premium household segments where moisture-rich formulations justify clinic-level pricing structures.
- Treats:Mid-scale baking and coating equipment serves functional reward and training applications.
- Raw Food:Freeze-drying and cold-chain infrastructure faces EFSA pathogen testing divergence across member states.
Most installed capacity flows through Dry Food. Expansion is steepest in Raw Food.
Customer Type:
Buyer sophistication determines formulation complexity and channel access requirements, with veterinary and breeder segments driving the steepest R&D investment.
- Pet Owners:Urban households in France, Germany, and the United Kingdom apply human dietary preferences—grain-free, organic, functional ingredients—to canine purchasing decisions, fragmenting SKU requirements.
- Breeders:Volume purchasers prioritize consistent nutritional specifications and bulk pricing for kennel operations.
- Pet Stores:Independent and chain retailers demand private-label flexibility and promotional margin structures.
- Veterinarians:Prescription-grade therapeutic diets require clinical validation and specialized distribution protocols.
Volume concentrates with Pet Owners. Value capture is highest through Veterinarians.
Distribution Channel:
Channel selection dictates packaging format, shelf-life engineering, and margin retention, with online and clinic routes offering superior pricing control.
- Online Retail:Algorithm-driven subscription models bypass supermarket slotting fees while capturing lifetime value data. France and the United Kingdom exhibit the highest platform-native brand concentration.
- Supermarkets:Mass-market dry food dominates volume through centralized procurement and promotional calendar dependence.
- Specialty Stores:Premium natural and grain-free segments command dedicated shelf space and trained staff consultation.
- Veterinarian Clinics:Prescription diets require clinical endorsement and controlled dispensing protocols.
Supermarkets handle the greatest volume throughput. Online Retail is expanding most quickly.
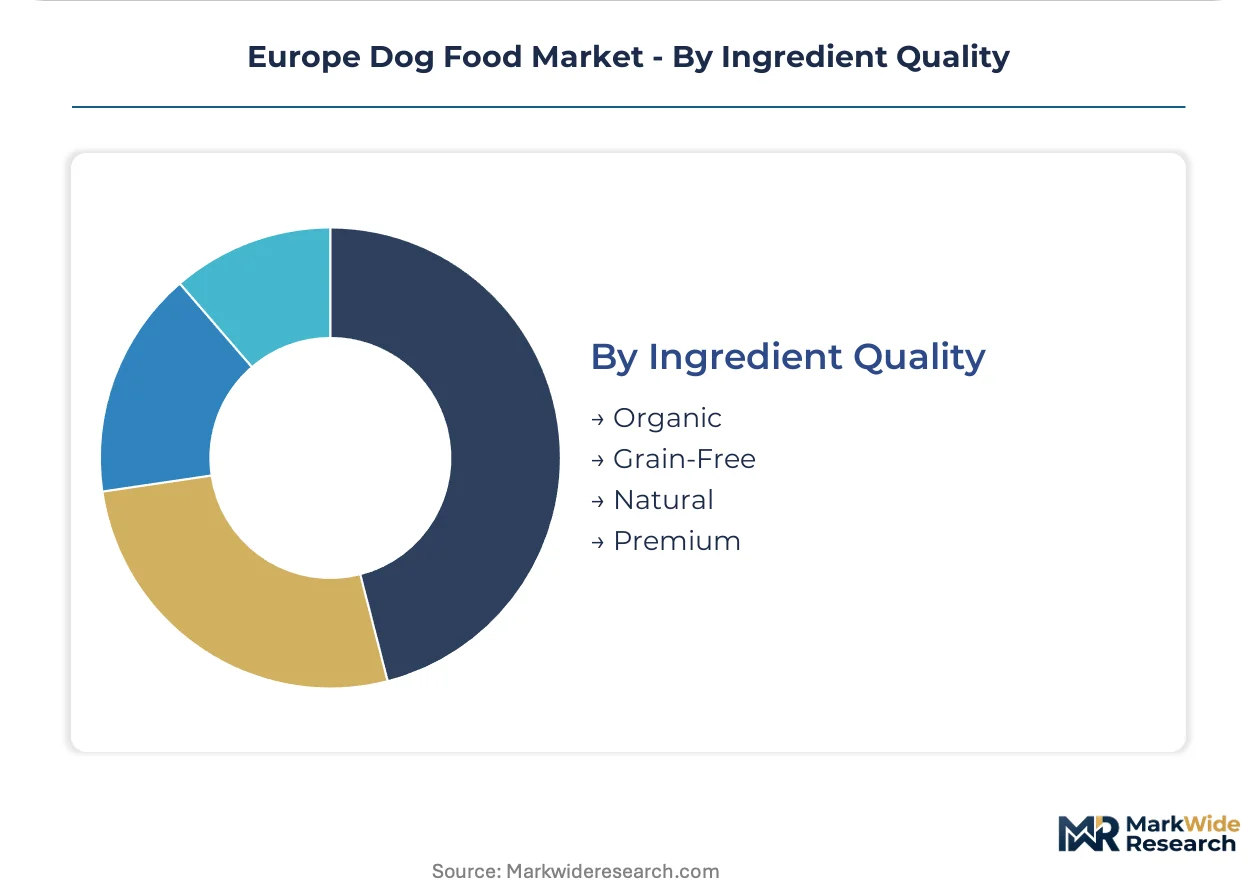
Ingredient Quality:
Certification tier determines sourcing radius, supplier audit intensity, and permissible formulation claims under EFSA and national food safety frameworks.
- Organic:EU organic regulation compliance mandates certified supply chains and prohibited additive lists, constraining formulation flexibility.
- Grain-Free:Tapioca, pea, and potato starch substitutions respond to DCM-linked scrutiny from veterinary nutritionists.
- Natural:Clean-label positioning limits preservative options under REACH chemical restrictions.
- Premium:Named protein sourcing and enhanced palatability drive ingredient cost structures.
Natural claims dominate shelf positioning. Organic is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dog food manufacturing first achieved industrial scale in the United Kingdom during the 1860s with the founding of Spratt's Patent, establishing Europe as the historical cradle of commercial pet nutrition. This legacy continues to shape regional production clusters and regulatory frameworks across the continent.
Germany
Urban pet ownership in Berlin, Munich, and Hamburg drives premiumization across grain-free and organic segments. The Bundesamt für Verbraucherschutz und Lebensmittelsicherheit enforces strict additive compliance timelines that exceed baseline EU requirements. Manufacturing concentrates in North Rhine-Westphalia, where retort canning facilities serve veterinary-directed wet food demand.
United Kingdom
Subscription-direct models capture disproportionate growth in London and Southeast England as algorithm-driven portioning displaces supermarket bulk purchasing. The Food Standards Agency coordinates with EFSA on novel protein approvals including insect-based formulations. Production clusters around Melton Mowbray and Peterborough leverage heritage pet food infrastructure.
France
Parisian households anchor demand for functional ingredients and breed-specific nutrition. The DGCCRF imposes divergent pathogen testing protocols for raw and freeze-dried segments that complicate cross-border distribution. Manufacturing in Brittany and the Loire Valley focuses on high-margin wet food and semi-moist categories.
Italy
Northern Italian pet owners in Lombardy and Emilia-Romagna demonstrate rising acceptance of alternative proteins including pea and insect meal. National interpretations of REACH chemical restrictions narrow preservative options faster than EU-wide deadlines. Extrusion equipment suppliers concentrate around Bologna, serving mid-scale dry food producers.
Poland
Rising disposable incomes in Warsaw and Kraków expand addressable demand for mid-tier natural formulations. The Chief Veterinary Officer aligns national food safety enforcement with EFSA maximum residue limits while maintaining flexibility on raw food distribution. Western Polish manufacturing zones near the German border attract contract packaging investment.
Europe Dog Food Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and channel access, with veterinary-directed portfolios commanding clinic-level pricing while mass-market dry food competes on logistics efficiency. The vendor base fragments across multinational CPG conglomerates, specialized pet food pure-plays, and private-label manufacturers serving retail chains. Three archetypes dominate: diversified nutrition conglomerates leveraging pan-European manufacturing footprints, veterinary-specialist firms anchored in prescription-grade formulations, and agile platform-native brands bypassing traditional retail entirely. Competitive moves concentrate on M&A to capture alternative protein capabilities and strategic partnerships to secure mono-material packaging supply.
Within the diversified conglomerate tier, Mars Incorporated and Nestlé Purina PetCare occupy positions defined by manufacturing scale and multi-price-tier portfolio breadth. Colgate-Palmolive Company, through its Hill's Pet Nutrition Inc. subsidiary, represents the veterinary-specialist archetype with prescription-grade positioning. These three entities exemplify how historical pet nutrition lineage translates into contemporary competitive structure across European markets.
| Leading Market Players |
|---|
| Mars Incorporated |
| Nestlé Purina PetCare |
| Colgate-Palmolive Company (Hill's Pet Nutrition Inc.) |
| Affinity Petcare SA |
| Archer Daniels Midland Company |
| General Mills Inc. |
| United Petfood |
| Farmina Pet Foods |
| Heristo Aktiengesellschaft |
| Others |
Pricing and Supply Chain Analysis
Premium-commodity bifurcation between veterinary-directed therapeutic diets and mass-market dry food creates divergent margin architectures across European manufacturing. Clinic-level pricing for prescription-grade formulations in Germany and France funds specialized R&D and controlled distribution infrastructure, while supermarket dry food competes on logistics efficiency and polymer feedstock cost management.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments buyer access by certification grade and channel control. Premium tiers leverage EFSA novel food approvals for insect protein and organic claims to justify shelf price premiums, while economy tiers absorb volatility in chicken and fish meal costs. Cost compression in mid-tier natural formulations is intensifying because REACH chemical restrictions force preemptive preservative reformulation. Supermarket bulk buyers exhibit highest price sensitivity; veterinarian clinic clients demonstrate lowest sensitivity due to clinical endorsement lock-in.
Supply Chain Analysis
Reverse-logistics flows for subscription-direct packaging returns concentrate quality feedback loops with German and Dutch converters. Raw material sourcing draws from North Sea fish meal operations, Brazilian poultry byproduct streams, and emerging black soldier fly larvae facilities in France and the Netherlands. Single-source packaging concentration among German flexible film suppliers creates vulnerability to polymer feedstock disruptions. Distribution runs through algorithm-driven subscription platforms in the United Kingdom and France alongside traditional supermarket procurement in Germany and Poland.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in European dog food rests on insect protein cost curves flattening and prescription-grade penetration deepening in Eastern European veterinary channels.
For Market Incumbents: Deepen captive supply of alternative protein processing capacity before EFSA novel food approvals trigger competitor entry. Secure mono-material packaging validation partnerships with Dutch converters to outpace F-Gas Regulation compliance deadlines. Incumbent market positions face erosion from platform-native brands bypassing supermarket slotting fees entirely. For New Entrants and Emerging Players: Capture underpenetrated prescription-grade therapeutic diet demand in Polish and Romanian veterinary clinics where Western European benchmarks remain distant. Algorithm-driven subscription models in London and Paris offer the most penetrable go-to-market angle for direct consumer relationship building without retail gatekeeper dependence. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale manufacturers lack backward integration into alternative protein sourcing and face stranded asset risk from packaging line retrofits. Long-term viability favors vertically integrated specialists with captive insect protein supply and veterinary channel certification depth. Watch EFSA approval timelines for black soldier fly larvae inclusion as inflection indicator for premium tier repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Insect Protein Supply Integration | EFSA novel food approvals for black soldier fly larvae enable ultra-low-carbon premium formulation positioning. |
| Mono-Material Packaging Transition | F-Gas Regulation compliance timelines force capital-intensive line retrofits at German and Dutch converters. |
| Veterinary Channel Expansion | Prescription-grade therapeutic diet penetration in Poland and Romania lags Western European benchmarks substantially. |
| Subscription-Direct Platform Launch | Algorithm-driven portioning in France and the United Kingdom bypasses supermarket slotting fee structures. |
| Alternative Protein R&D Partnership | Pea and insect meal formulation expertise addresses DCM-linked scrutiny from veterinary nutritionists. |
Research Methodology
Multiple input streams — formulation chemist interviews, veterinary procurement manager panels, and packaging converter technical assessments — were reconciled against customs trade data, EFSA additive approval databases, and Nielsen retail audit records. Primary engagement spanned R&D directors at diversified nutrition conglomerates, category buyers at French and German supermarket chains, and regulatory affairs leads navigating REACH chemical restrictions. Bottom-up volume modeling triangulated against top-down macroeconomic absorption capacity checks.
Historical volume trajectories were cross-referenced against panel input from industry stakeholders to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include product format, buyer sophistication tier, channel access route, and ingredient certification grade. CAGRs emerged from iterative reconciliation of production capacity expansion announcements, EFSA regulatory timeline probabilities, and urban pet ownership density projections in Paris, Berlin, and London metropolitan zones.
Avian influenza cycles, polymer feedstock price volatility, and divergent national interpretations of EU Green Deal carbon accounting are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions about EFSA approval velocities and REACH enforcement harmonization across member states. Practitioners should monitor ECHA chemical restriction calendars and Bundesamt für Verbraucherschutz und Lebensmittelsicherheit compliance deadline announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Europe Organic Pet Food for Cats and Dogs Market
Pet Care Products
Animal-Based Pet Protein Market
Pet Care Products
Smart Pet Leash Market
Pet Care Products
Vegan Cat Food Market
Pet Care Products
Pet Lodging Market
Pet Care Products
Automatic Dog Feeder Market
Pet Care Products
Smart Connected Pet Collar Market
Pet Care Products
Dog Clothing and Accessories Market
Pet Care Products
Pet GPS Tracker Market
Pet Care Products
Canned Dog Food Market
Pet Care Products
Dog Litter Boxes Market
Pet Care Products
Fresh and Frozen Dog Food Market
Pet Care Products
Saudi Arabia Pet Food Market
Pet Care Products
Spain Pet Boarding Market
Pet Care Products
Frozen and Freeze-Dried Pet Food Market
Pet Care Products
UK Pet Grooming Market