
 Pet Treats and Chews Market | 2026-2036
Pet Treats and Chews Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Treats and Chews Market Analytics
Thailand's expanding pet food manufacturing base is reshaping regional supply dynamics for rawhide and jerky exports. Mars Petcare leverages integrated protein sourcing across Southeast Asia to sustain cost advantages in bulk production. Nestlé Purina PetCare anchors North American distribution through veterinary clinic partnerships and mass retail shelf placement. Wellness Pet Company differentiates via grain-free and limited-ingredient positioning in premium pet specialty channels.
Pet treats and chews comprise formulated consumable products designed for oral health benefits, behavioral enrichment, or nutritional supplementation, typically manufactured through extrusion, dehydration, or cold-pressing processes with specified moisture content below twenty percent to ensure shelf stability. Dental chews represent the fastest-growing product type as veterinary endorsement drives recurring purchase behavior among preventive-health-focused owners. Protein-rich ingredient sourcing commands disproportionate margin pools as consumers trade up from commodity biscuits to single-animal-protein formulations. Online retail distribution is displacing supermarket dominance for subscription-based treat replenishment, particularly in functional and organic subcategories.
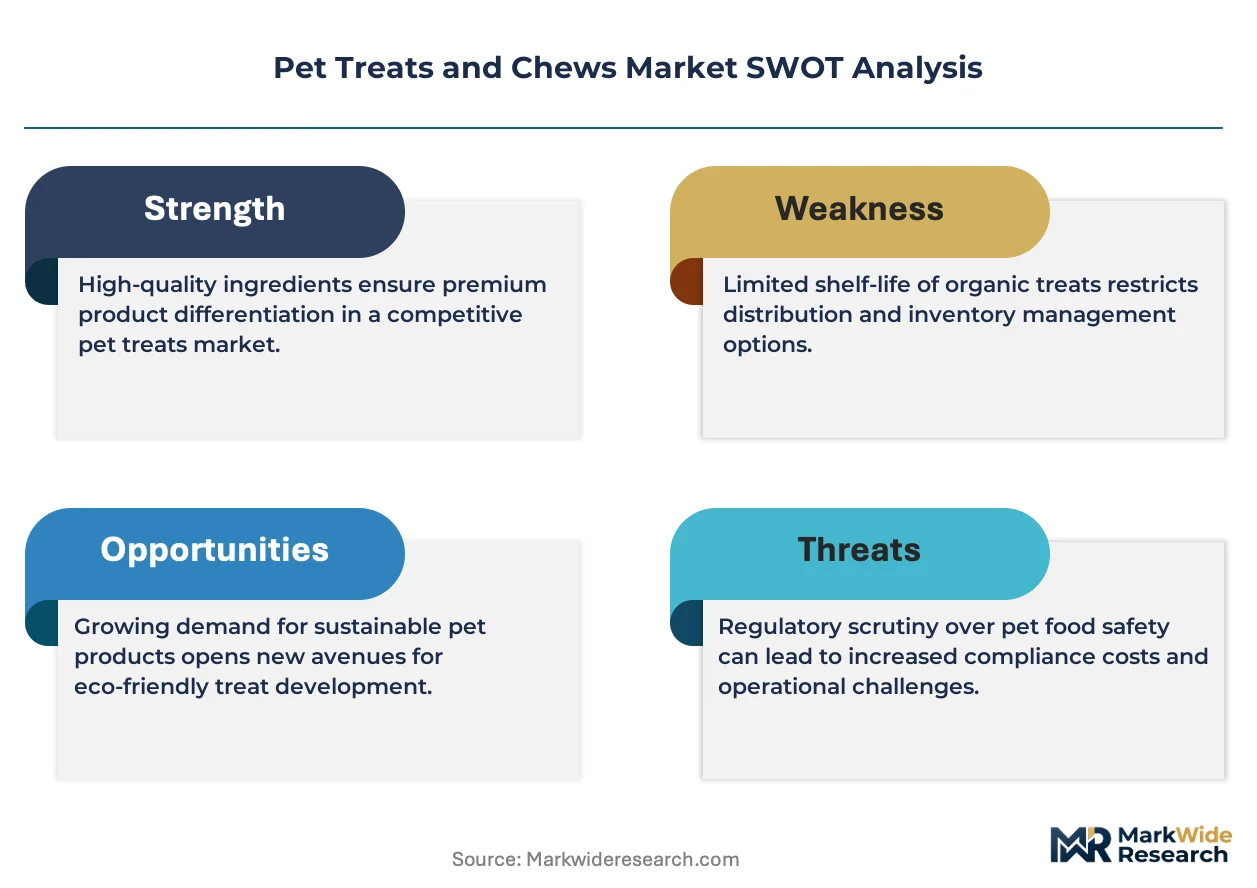
FDA Center for Veterinary Medicine oversight and AAFCO model feed regulations govern ingredient safety claims and nutritional adequacy statements in the United States, while the EU's Feed Hygiene Regulation and FEDIAF nutritional guidelines shape product standards across European markets. These frameworks elevate compliance costs for imported formulations but simultaneously create market access barriers that favor established players with dedicated regulatory affairs capabilities. Stakeholders must monitor evolving state-level packaging mandates and veterinary channel credentialing requirements as gatekeepers to premium positioning intensify.
Market Dynamics
Pet humanization among urban households is restructuring treat purchasing from discretionary indulgence to preventive health expenditure, compressing price elasticity and elevating veterinary endorsement as a gatekeeper function.
Growth Catalysts
- AAFCO Labeling Harmonization:The FDA Center for Veterinary Medicine's alignment with AAFCO model regulations is streamlining interstate commerce and reducing formulation compliance redundancy for multi-state distributors.
- Single-Animal-Protein Formulations:Limited-ingredient diets targeting food-sensitive dogs are commanding premium shelf placement in specialty pet retail channels.
- Thailand:Bangkok's integrated protein processing infrastructure is capturing regional rawhide and jerky contract manufacturing from Australian and Japanese brand owners.
Market Restraints
- Behide Supply Volatility:Cattle byproduct availability fluctuates with meatpacking plant throughput, exposing margin pressure on rawhide-dependent SKUs during processing slowdowns.
- EU Feed Hygiene Regulation:FEDIAF nutritional guideline compliance creates non-tariff barriers for US and Southeast Asian exporters without dedicated European regulatory affairs staffing.
- Plant-Based Substitutes:Sweet potato and yam-based dental chews are eroding volume share in price-sensitive suburban households.
Strategic Opportunities
- Veterinary Clinic Channel:Prescription treat protocols for post-surgical and weight-management cases remain underdeveloped outside North American metropolitan markets.
- Cold-Pressing Technology:Low-temperature nutrient preservation is hybridizing with functional ingredient infusion to create novel therapeutic positioning.
- Subscription Replenishment:Direct-to-consumer auto-ship models are capturing recurring revenue from preventive-health-focused dog owners in Germany and France.
Industry Challenges
- Veterinary Nutritionist Talent Scarcity:Formulation science expertise capable of bridging clinical efficacy claims with regulatory substantiation commands premium compensation and extended recruitment cycles.
- State-Level Packaging Mandate Fragmentation:California's extended producer responsibility laws and emerging Northeast recycling requirements force SKU-specific packaging redesigns.
- Ingredient Traceability Systems:Blockchain-enabled supply chain verification demands capital investment disproportionate to mid-tier manufacturer cash flow profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Treats and Chews Market |
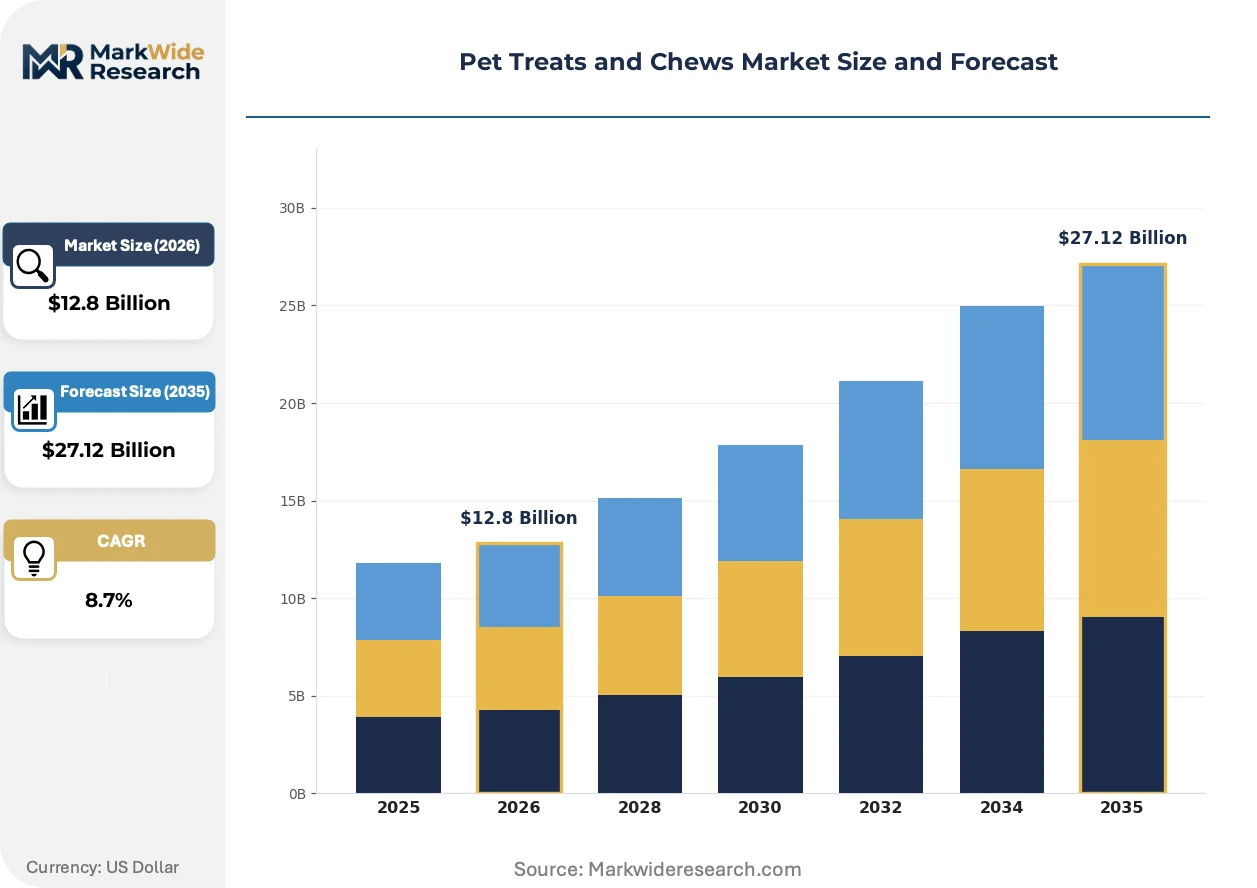
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biscuits, Jerky, Rawhide, Dental Chews Ingredient Source: Organic, Grain-Free, Protein-Rich, Functional Target Animal: Dogs, Cats, Small Pets, Horses Distribution Channel: Online Retail, Supermarkets, Pet Specialty Stores, Distributors |
| Companies Covered | Nestlé Purina PetCare, Mars Petcare, Hill's Pet Nutrition, Spectrum Brands, J.M. Smucker Company, General Mills, Wellness Pet Company, Merrick Pet Care, Stella & Chewy’s, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Treats and Chews Market Evolving Landscape
Functional ingredient science and distribution channel reconfiguration are converging to reposition pet treats from reward commodities to integrated wellness protocols with recurring purchase mechanics.
Cold-pressed manufacturing is preserving heat-sensitive probiotics and omega fatty acids through sub-42°C processing temperatures. Premium-positioned manufacturers in Germany and the Netherlands are adopting these lines to support digestive health and coat quality claims. This low-temperature capability is hybridizing with extrusion efficiency to narrow cost gaps with conventional baking.
The EU's Feed Hygiene Regulation is mandating hazard analysis critical control point documentation across all pet food manufacturing facilities. Small-to-midscale producers without dedicated quality systems personnel face facility upgrade costs or contract manufacturing migration. Italian and Spanish exporters are consolidating through third-party audited co-manufacturers to maintain market access.
Veterinary endorsement is displacing retail shelf visibility as the primary purchase trigger among urban dog owners with preventive health orientation. Clinic-dispensed dental chews and therapeutic treats are capturing volume from supermarket biscuit categories. This channel migration is most pronounced in US coastal metropolitan areas and Australian capital cities.
Pet Treats and Chews Market Segmentation
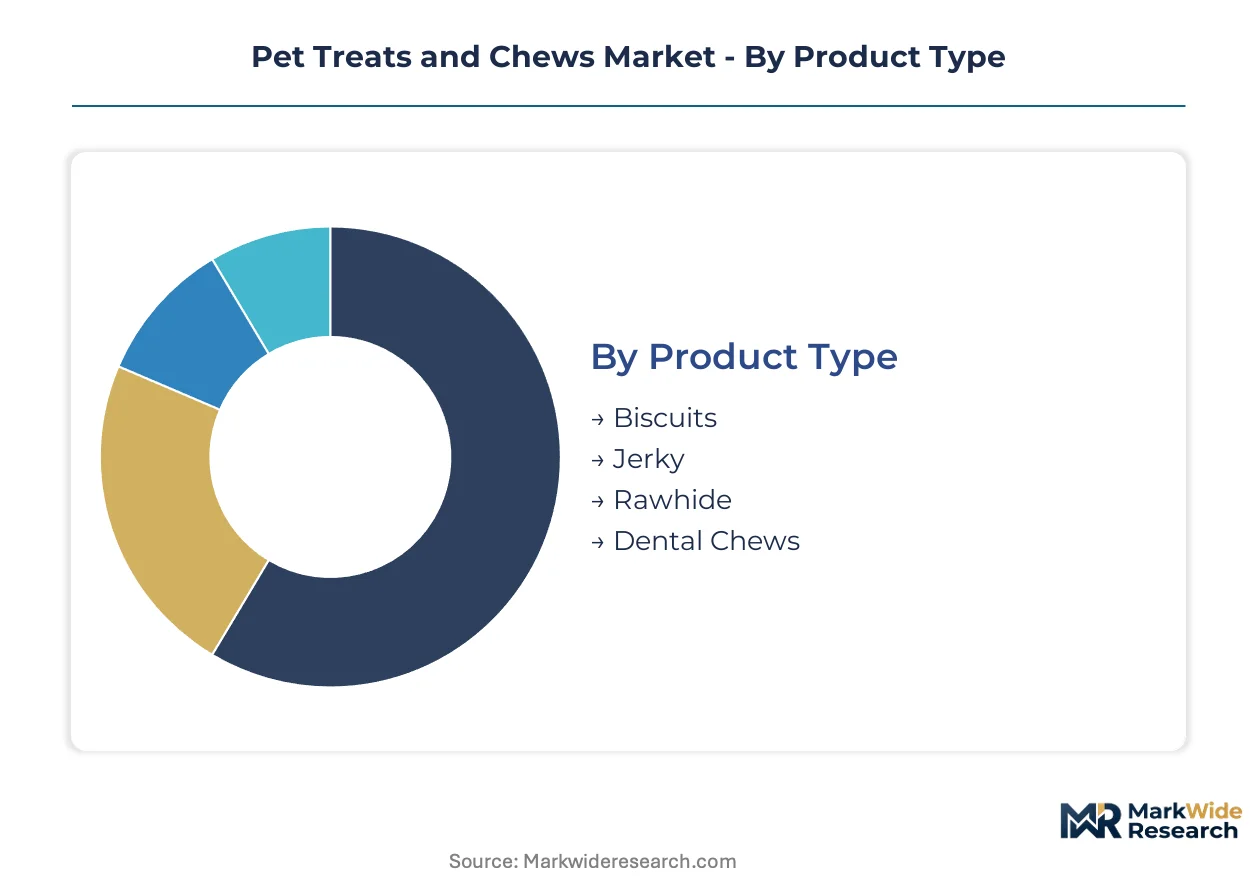
Pet treats and chews fragment across four distinct axes that shape formulation priorities, margin capture, and channel access. Product type and ingredient source dominate purchasing decisions among premium-seeking owners, while distribution channel determines pricing power and repeat purchase mechanics.
Product Type:
Oral health applications span the use-case spectrum from behavioral reward to preventive veterinary protocol.
- Dental Chews:Extruded or molded formulations with specified abrasive indexes target plaque reduction through mechanical action. Demand concentrates in US metropolitan veterinary clinics where preventive health expenditure compresses price elasticity. Veterinary endorsement drives recurring subscription purchases.
- Jerky:Dehydrated muscle tissue strips with moisture content below fifteen percent deliver high-value protein density. Thailand's Bangkok processing clusters capture contract manufacturing for Australian and Japanese brand owners seeking cost-efficient single-animal-protein sourcing.
- Biscuits:Baked flour-based formulations with shelf stability exceeding eighteen months serve mass-market price-sensitive households.
- Rawhide:Cattle hide derivatives processed through liming and drying sequences face supply volatility tied to meatpacking plant throughput fluctuations.
The dominant share belongs to Biscuits, while Dental Chews is closing the gap fastest.
Ingredient Source:
Cost tiers separate commodity formulations from clinically positioned premium alternatives.
- Protein-Rich:Single-animal-protein formulations with specified amino acid profiles command premium shelf placement in specialty pet retail. US urban owners trade up from commodity blends to limited-ingredient diets targeting food-sensitive dogs.
- Functional:Probiotic, omega fatty acid, and glucosamine infusions support digestive, coat quality, and joint health claims. German and Dutch manufacturers deploy cold-pressing technology below 42°C to preserve heat-sensitive actives.
- Grain-Free:Tapioca, pea, and potato starch substitutes replace wheat and corn in formulations targeting allergen-conscious purchasers.
- Organic:Certified ingredient sourcing with full traceability documentation satisfies EU Feed Hygiene Regulation hazard analysis requirements.
Protein-Rich formulations hold the largest volume position, with Functional ingredients climbing the fastest.
Target Animal:
Application intensity varies dramatically by species physiology and owner expenditure patterns.
- Dogs:Omnivore-adapted formulations with dental abrasion specifications and behavioral enrichment designs capture the deepest per-pet spending. US coastal metropolitan areas show the steepest expansion trajectory for preventive-health-positioned treats.
- Cats:Obligate carnivore requirements drive higher protein concentration and palatability engineering through spray-dried plasma coatings.
- Small Pets:Rodent and rabbit formulations emphasize gnawing mechanics for dental health with compressed hay and vegetable matrices.
- Horses:Large-animal treats with controlled sugar content address metabolic syndrome risks in recreational riding stock.
Dogs command the dominant share, while Cats are gaining share fastest through premium wet-format introductions.
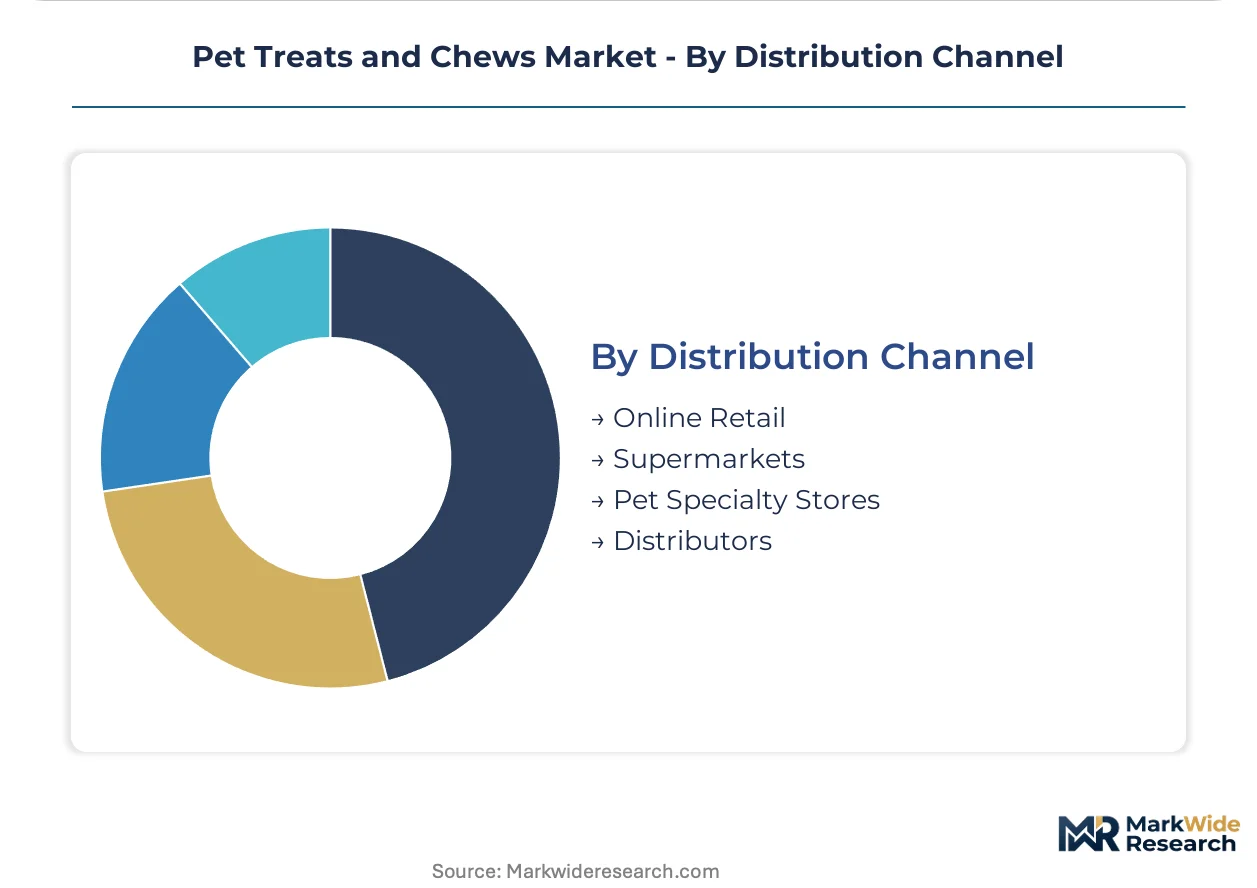
Distribution Channel:
Customer type and purchase occasion determine margin capture and brand control.
- Online Retail:Direct-to-consumer auto-ship models with subscription replenishment mechanics capture recurring revenue from preventive-health-focused owners in Germany and France. Cold-pressed functional formats concentrate here.
- Pet Specialty Stores:Grain-free and limited-ingredient positioning with trained staff consultation supports premium pricing.
- Supermarkets:Mass-market biscuit and rawhide SKUs face price compression and private-label substitution.
- Distributors:Veterinary clinic channel access requires credentialing compliance and prescription treat protocol development.
Supermarkets retain the largest volume position, while Online Retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's integrated protein processing infrastructure anchors rawhide and jerky contract manufacturing for brand owners across Japan and Australia. Bangkok's export-oriented clusters leverage cost-efficient cattle byproduct sourcing to capture regional supply chain share.
United States
Urban dog owners in coastal metropolitan areas compress price elasticity through preventive health expenditure patterns. FDA Center for Veterinary Medicine oversight and AAFCO model feed regulations govern interstate commerce and ingredient safety claims. Veterinary clinic channels in New York and Los Angeles concentrate prescription treat dispensing for post-surgical and weight-management protocols.
Germany
Cold-pressed functional treat adoption accelerates among preventive-health-focused owners in Berlin and Munich. EU Feed Hygiene Regulation mandates hazard analysis critical control point documentation across manufacturing facilities. Dutch-German border regions concentrate probiotic and omega fatty acid formulation expertise with sub-42°C processing capabilities.
Thailand
Bangkok's meatpacking byproduct streams sustain cost-efficient rawhide and jerky export production for Australian and Japanese contract clients. National feed hygiene standards align with destination market requirements to maintain market access. Integrated protein processing parks in the capital region capture regional manufacturing migration from higher-cost Northeast Asian facilities.
Japan
Metropolitan pet humanization trends in Tokyo and Osaka elevate veterinary endorsement as the primary purchase trigger for dental chew categories. METI standards and JIS quality frameworks shape import compliance requirements for foreign suppliers. Osaka-Kobe industrial corridors concentrate palatability engineering capabilities for obligate carnivore feline formulations.
Australia
Capital city veterinary channels displace supermarket dominance for subscription-based functional treat replenishment. Biosecurity regulations and import permit requirements create non-tariff barriers for Southeast Asian exporters without dedicated compliance staffing. Sydney and Melbourne metropolitan areas show steepest expansion for clinic-dispensed preventive health protocols.
Pet Treats and Chews Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in ingredient sourcing and co-manufacturing relationships. The vendor base stratifies across three tiers: multinational CPG conglomerates with veterinary channel integration, mid-scale premium specialists with limited-ingredient positioning, and regional rawhide processors with export contract dependence. Archetypes include integrated protein platform owners, cold-pressed functional formulators, and veterinary credentialing gatekeepers. Capacity expansion into Southeast Asian contract manufacturing and M&A-driven portfolio diversification into therapeutic treat categories constitute dominant competitive vectors.
Within the multinational platform tier, Nestlé Purina PetCare and Mars Petcare anchor North American distribution infrastructure through mass retail shelf placement and veterinary clinic partnerships. Wellness Pet Company occupies a position exemplifying grain-free and limited-ingredient specialists in premium pet specialty channels. These three entities represent distinct strategic postures: integrated CPG scale, protein sourcing verticality, and premium positioning through ingredient restraint.
| Leading Market Players |
|---|
| Nestlé Purina PetCare |
| Mars Petcare |
| Hill's Pet Nutrition |
| Spectrum Brands |
| J.M. Smucker Company |
| General Mills |
| Wellness Pet Company |
| Merrick Pet Care |
| Stella & Chewy's |
| Others |
Value Network & Pricing Analysis
Cattle byproduct availability volatility determines both the pricing tier spreads across rawhide-dependent SKUs and the geographic shape of contract manufacturing migration toward Bangkok's integrated protein processing parks. This input risk compresses margins in commodity biscuit categories while elevating premium capture for single-animal-protein formulations with supply chain redundancy.
Pricing Analysis
AAFCO labeling harmonization dictates the pricing tier structure by elevating compliance costs that stratify market access. Three-tier pricing structure across premium, standard, and economy levels separates veterinary-credentialed therapeutic treats from grain-free specialty formats and mass-market biscuits. Cost compression in rawhide SKUs is intensifying because meatpacking plant throughput fluctuations expose single-source dependencies. Suburban households with price-sensitive purchasing patterns show highest sensitivity, while urban preventive-health-focused owners exhibit inelastic demand for clinic-dispensed dental chews.
Supply Chain Analysis
Bangkok's contract-manufacturing clusters hold dominant capacity for rawhide and jerky exports serving Australian and Japanese brand owners. Protein sourcing concentrates in Thailand, the United States, and Germany, with each node feeding distinct formulation tiers. Manufacturing draws from cattle hide derivatives, dehydrated muscle tissue, and cold-pressed functional actives as core inputs. Single-source vulnerability in cattle byproduct streams threatens margin stability during meatpacking slowdowns. Distribution runs through veterinary clinic channels for premium tiers and mass retail for commodity SKUs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits cyclical recovery characteristics anchored to pet humanization expenditure waves that compress price elasticity during economic expansion phases.
For Market Incumbents: Entrench veterinary channel control through credentialing investment and prescription treat protocol development. Mars Petcare and Nestlé Purina PetCare should deepen backward integration into Southeast Asian protein sourcing to defend against Bangkok contract manufacturers capturing margin. Cold-pressing technology acquisition represents the priority capability lever for functional claim substantiation. For New Entrants and Emerging Players: Australian capital city veterinary channels present underpenetrated white space for subscription-based functional treat replenishment. Target post-surgical and weight-management prescription protocols outside North American metropolitan markets. Go-to-market execution should leverage direct-to-consumer auto-ship mechanics with probiotic and omega fatty acid positioning. For Investors and Strategic Acquirers: EU Feed Hygiene Regulation reshapes the acquisition landscape by forcing facility upgrade investments that consolidate mid-tier producers. Long-term viability centers on therapeutic treat portfolios with recurring revenue mechanics. Cold-pressed manufacturing capability with sub-42°C processing serves as the signal to watch for premium positioning inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Channel Credentialing | Clinic dispensing protocols in New York and Los Angeles capture recurring purchase behavior from preventive-health-focused owners. |
| Cold-Pressing Technology Adoption | German and Dutch manufacturers preserve heat-sensitive probiotics through sub-42°C processing for digestive health claims. |
| Southeast Asian Contract Manufacturing | Bangkok's integrated protein parks capture regional rawhide and jerky production from Australian and Japanese brand owners. |
| Subscription Replenishment Models | Direct-to-consumer auto-ship in Germany and France locks in recurring revenue from functional treat purchasers. |
| Single-Animal-Protein Formulation | Limited-ingredient diets command premium shelf placement in specialty pet retail channels targeting food-sensitive dogs. |
Research Methodology
A spread of perspectives from veterinary nutritionists, regulatory affairs specialists at FDA Center for Veterinary Medicine, pet specialty retail category buyers, and contract manufacturing procurement leads converged on the working assumptions. Primary interview insights combined with secondary validation from AAFCO model feed regulations, EU Feed Hygiene Regulation documentation, FEDIAF nutritional guidelines, and customs trade data for rawhide and jerky exports. Bottom-up SKU-level analysis and top-down market sizing triangulated volume and value estimates.
Demand-supply balance framing anchored the analytical approach across the analysis window. Segmentation dimensions modeled include product type, ingredient source, target animal species, and distribution channel. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and channel migration patterns. Veterinary endorsement intensity and cold-pressed manufacturing adoption curves served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by multinational CPG conglomerates or rapid clinic channel consolidation by emerging specialists would shift outcomes. Quarterly review of veterinary credentialing expansion rates and cold-pressing capacity buildout announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
UAE Cat Food Market
Pet Care Products
Dog Bowl Market
Pet Care Products
Europe Organic Pet Food for Cats and Dogs Market
Pet Care Products
UK Pet Diet Market
Pet Care Products
Dog Vest Market
Pet Care Products
Cat Diffuser Market
Pet Care Products
Europe Cat Food Market
Pet Care Products
Dog Hoodies Market
Pet Care Products
Pet Tick and Flea Prevention Market
Pet Care Products
Spain Pet Boarding Market
Pet Care Products
Italy Pet Food Market
Pet Care Products
Automatic and Smart Pet Feeder Market
Pet Care Products
Pet Furniture Market
Pet Care Products
Dog Coats for Winter Market
Pet Care Products
Argentina Pet Food Market
Pet Care Products
Cat Diets Market