
 US and Mexico Cat Litter Market | 2026-2036
US and Mexico Cat Litter Market Size, Share, and Industry Trends Forecast 2026-2036
US and Mexico Cat Litter Market Analytics
Plant-based fiber is recalibrating cost structures across the US and Mexico Cat Litter Market as manufacturers reformulate away from strip-mined bentonite. Nestlé Purina Petcare leverages its R&D network to develop mixed-substrate blends that reduce clay dependence. Oil-Dri Corporation of America anchors its position through captive mineral reserves in Mississippi and Georgia. Church & Dwight Co Inc differentiates via Arm & Hammer baking soda integration for odor-neutralization chemistry.
Cat litter comprises absorbent granular or clumping substrates placed in litter boxes to capture feline waste moisture and control ammonia odor, with formulations ranging from sodium bentonite clay with liquid-activated clumping to silica gel with micropore desiccation and plant-based pellets with enzymatic biodegradation. Clay formulations still dominate volume across mass retail channels, though biodegradable segments are expanding fastest in pet specialty and online retail as sustainability premiums attract affluent urban pet owners. The granular form maintains broad household penetration, while clumping variants command higher per-unit margins through repeat-purchase loyalty and subscription-based replenishment models.
The EPA regulates bentonite mining under the Clean Water Act and Resource Conservation and Recovery Act, pushing producers toward lower-impact extraction or alternative feedstocks. The FTC monitors environmental marketing claims through its Green Guides, constraining how brands label "natural" or "biodegradable" positioning. State regulators in California and Texas enforce additional disposal and packaging requirements that shape regional product availability. Stakeholders must track how evolving federal mining permits and state-level extended producer responsibility frameworks will reshape raw material sourcing economics and brand compliance costs.
Market Dynamics
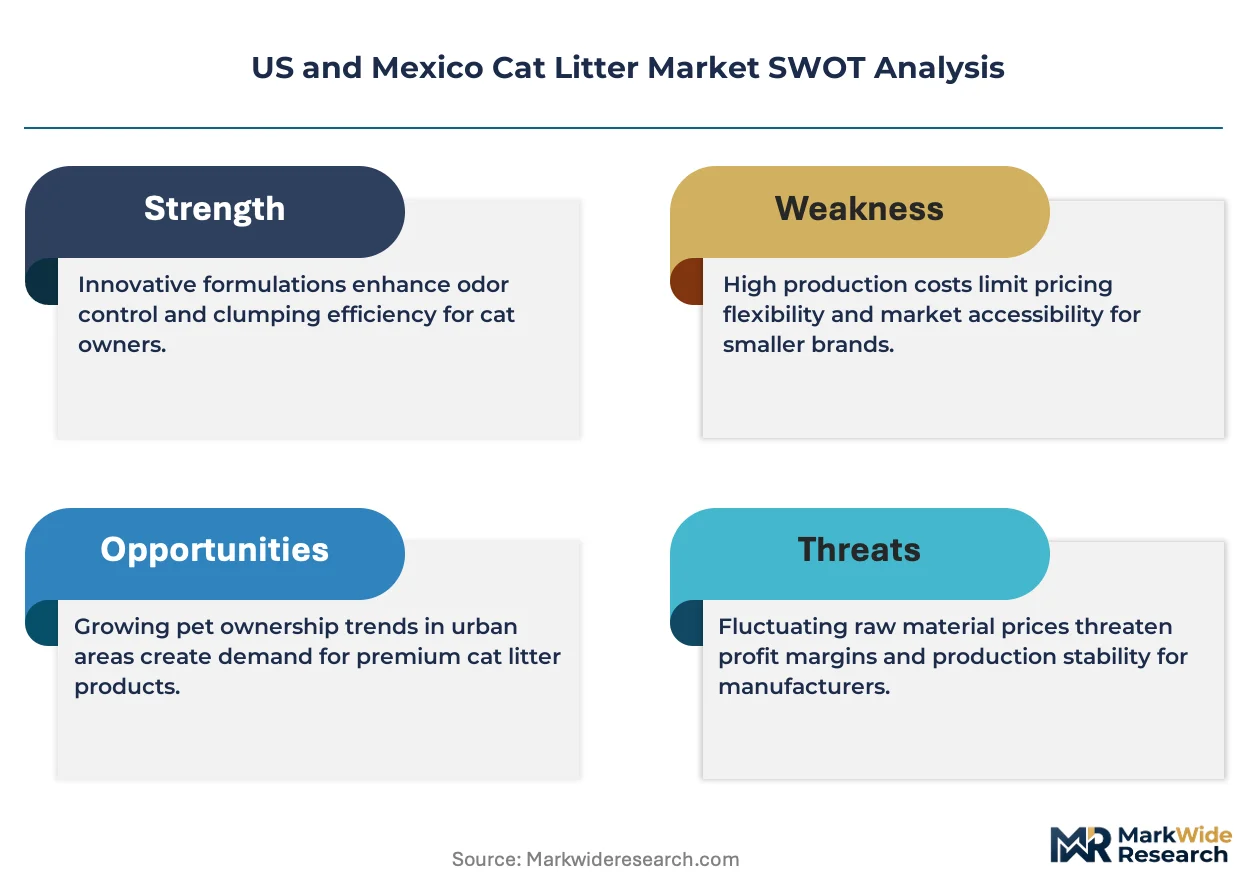
The US and Mexico Cat Litter Market faces structural pressure from EPA mining restrictions on sodium bentonite clay, which is forcing manufacturers to reformulate around plant-based fibers and silica gel alternatives while maintaining clumping performance standards.
Growth Catalysts
- Extended Producer Responsibility frameworks:California and Texas state regulations mandate sustainable packaging and disposal pathways, accelerating retailer adoption of biodegradable litter lines in urban centers.
- Multi-cat household density:Southwest US metropolitan areas with high apartment concentration drive repeat-purchase volume for premium odor-control formulations.
- Silica gel micropore technology:Desiccant-based absorption systems reduce per-use volume and extend change intervals, appealing to time-constrained urban consumers.
Market Restraints
- Strip-mining permit scarcity:EPA Clean Water Act enforcement restricts new bentonite extraction sites in Wyoming and Montana, compressing domestic clay supply.
- Plant fiber input cost volatility:Wheat, corn, and pine pellet pricing fluctuates with agricultural commodity markets, destabilizing biodegradable product margins.
- Performance gap in clumping:Biodegradable substrates rarely match sodium bentonite's liquid-activated cohesion, limiting full substitution in mass retail channels.
Strategic Opportunities
- Subscription replenishment models:Direct-to-consumer auto-ship platforms bypass retail slotting fees and capture lifetime value from urban multi-cat households.
- Mexico manufacturing expansion:Proximity to US Southwest demand centers and lower bentonite transport costs enable regional production hubs.
- FTC Green Guides compliance differentiation:Brands with verified biodegradable claims command shelf space as retailers face greenwashing liability exposure.
Industry Challenges
- Reformulation R&D timelines:Developing clay-alternative clumping chemistry requires 18-24 month testing cycles before retail distribution.
- Legacy packaging retrofit costs:Transitioning to post-consumer recycled content for California SB 54 compliance demands capital-intensive line upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US and Mexico Cat Litter Market |
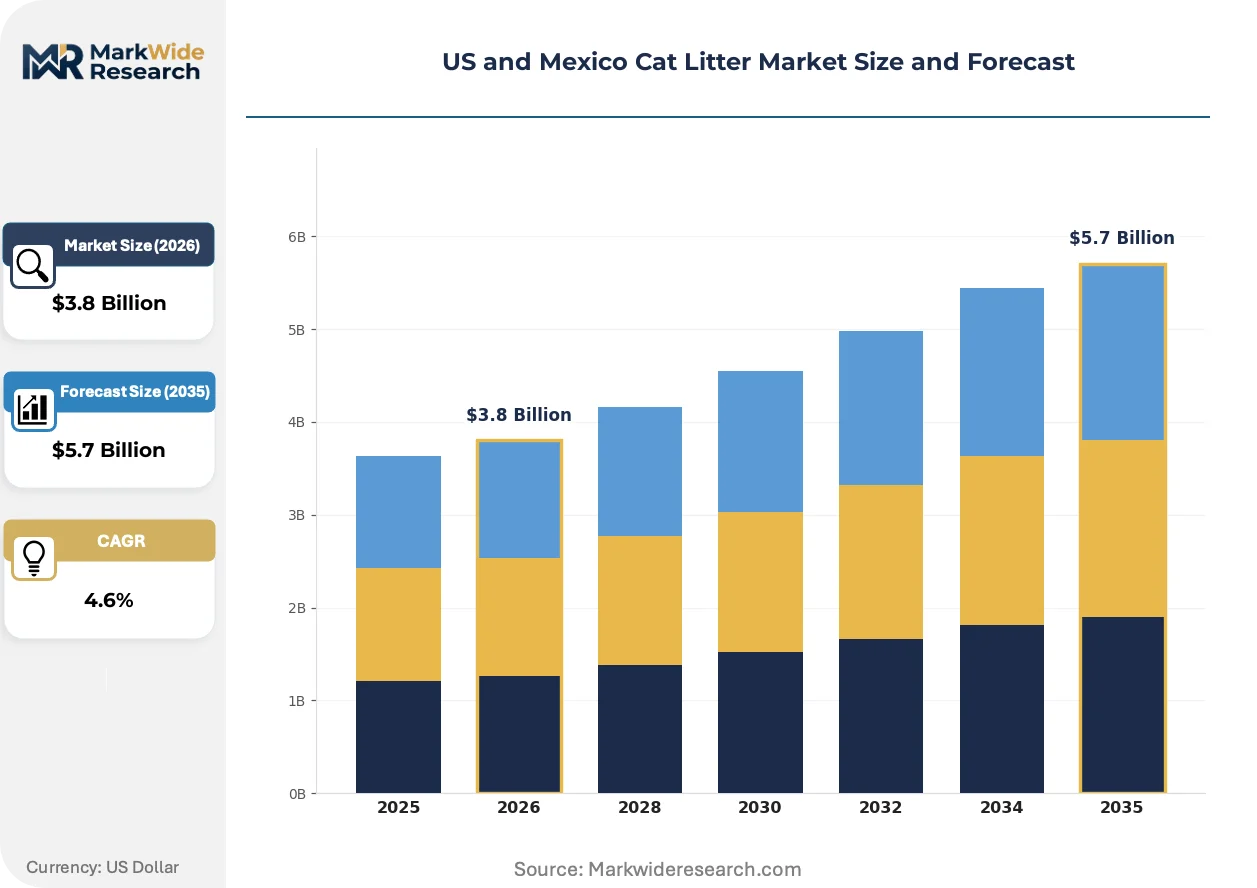
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clay, Biodegradable, Crystal, Silica Gel Distribution Channel: Supermarkets, Pet Stores, Online Retail, Wholesale Customer Type: Pet Owners, Veterinarians, Shelters, Breeders Form: Granular, Pellets, Powder, Clumping |
| Companies Covered | The Clorox Company, Nestlé Purina Petcare, Oil-Dri Corporation of America, Church & Dwight Co Inc, Dr. Elsey's, Kent Corporation, Intersand Group, Pettex Limited, Nestle SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US and Mexico Cat Litter Market Evolving Landscape
Formulation science and distribution infrastructure are converging to reshape how cat litter reaches households, with sustainability credentials now functioning as a gating factor for retail access rather than a premium add-on.
Enzymatic biodegradation systems embedded in plant-fiber substrates are decentralizing odor control away from chemical additives. Multi-cat households in Austin and Phoenix metro areas are adopting these formulations fastest, drawn by reduced dust and composting compatibility. The technology is decentralizing supply chain power from bentonite mining regions toward agricultural processing centers in the Midwest and Southeast.
The EPA's Resource Conservation and Recovery Act enforcement is tightening disposal classifications for spent clay litter. Industrial consequence includes mandatory landfill diversion testing for large-volume generators such as veterinary clinics and shelters. Pet specialty retailers in California are responding by private-labeling biodegradable alternatives to preempt liability exposure.
Auto-replenishment algorithms tied to smart litter box sensors are compressing purchase cycles from monthly to bi-weekly for high-absorption silica formulations. Subscription platforms displace mass retail for tech-adopting millennials in Dallas-Fort Worth and San Diego. This shift concentrates demand data with platform operators, reducing brand visibility into end-user behavior.
US and Mexico Cat Litter Market Segmentation
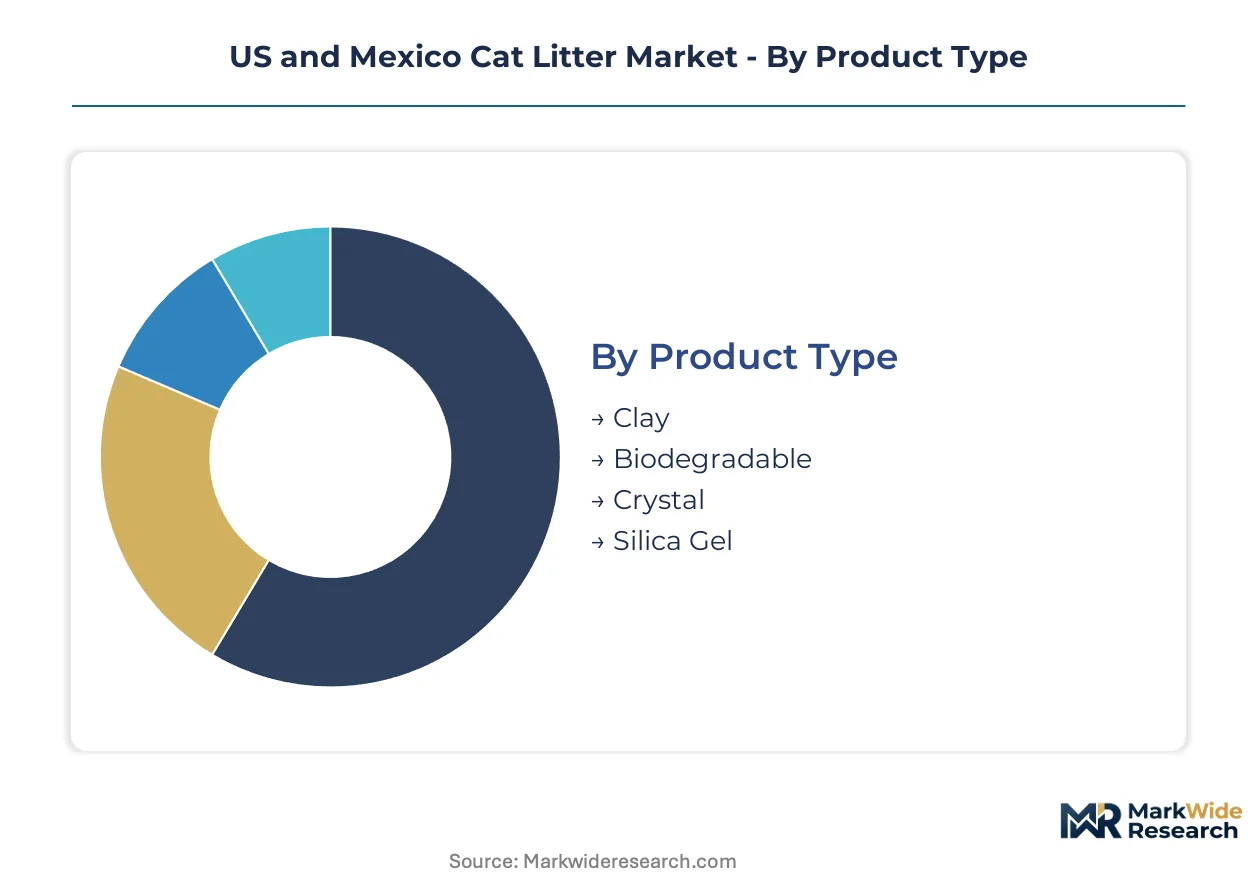
Cat litter segmentation reveals how capital deployment and regulatory pressure reshape competitive advantage across the US and Mexico market. Formulation chemistry and distribution infrastructure determine which players capture margin in a market transitioning from mined clay toward engineered substrates.
Product Type:
Capital intensity varies sharply across substrate technologies, with mining operations requiring heavy fixed investment while plant-based processing demands flexible manufacturing networks.
- Clay:Sodium bentonite extraction in Wyoming and Mississippi demands strip-mining permits, heavy equipment fleets, and EPA Clean Water Act compliance infrastructure. Texas and California mass retailers still move the highest tonnage, though EPA permit scarcity compresses domestic supply and elevates sourcing costs.
- Biodegradable:Wheat, corn, and pine pellet formulations require lower capital barriers but face agricultural commodity price volatility. Urban multi-cat households in Austin and Phoenix metro areas drive fastest adoption, drawn by composting compatibility and reduced dust exposure.
- Crystal:Silica gel manufacturing leverages desiccant industry infrastructure with moderate capital requirements.
- Silica Gel:Micropore absorption technology extends change intervals and reduces per-use volume, appealing to time-constrained consumers in Southwest apartment markets.
Most installed capacity flows through Clay. Expansion is steepest in Biodegradable.
Distribution Channel:
Channel economics separate volume scale from margin capture, with digital platforms disrupting traditional retail slotting fee structures.
- Supermarkets:Mass retail chains in California and Texas command shelf space through slotting fees and promotional allowances, concentrating clay litter volume in high-frequency grocery trips. Walmart and Kroger networks anchor household penetration for standard formulations.
- Pet Stores:PetSmart and Petco specialty channels in Dallas-Fort Worth and San Diego metro areas curate premium and biodegradable assortments, capturing higher per-unit margins through educated staff recommendations and private-label expansion.
- Online Retail:Auto-replenishment algorithms and smart litter box sensor integration compress purchase cycles, with Chewy and Amazon subscription models displacing mass retail for tech-adopting millennials.
- Wholesale:Veterinary clinics and shelters in high-volume corridors purchase through distributors, with EPA Resource Conservation and Recovery Act disposal classifications shaping procurement toward biodegradable alternatives.
Volume concentrates in Supermarkets. Margin expansion is accelerating in Online Retail.
Customer Type:
End-use segmentation maps demand intensity to usage patterns, with commercial operators facing stricter disposal compliance than residential buyers.
- Pet Owners:Residential households in Southwest metropolitan areas generate repeat-purchase loyalty through odor-control performance, with multi-cat density in Phoenix and Austin driving premium formulation uptake.
- Veterinarians:Clinical practices in California face EPA-mandated landfill diversion testing for spent litter, accelerating biodegradable procurement to preempt liability exposure.
- Shelters:High-volume animal welfare operations in Texas prioritize cost-per-use efficiency, with silica gel formulations reducing labor-intensive change frequency.
- Breeders:Cattery operations demand consistent substrate quality for health monitoring, with clumping performance standards influencing supplier selection.
Transaction volume flows through Pet Owners. Compliance pressure is intensifying for Veterinarians.
Form:
Physical substrate configuration determines manufacturing equipment requirements and shipping economics, with clumping chemistry demanding the most specialized production assets.
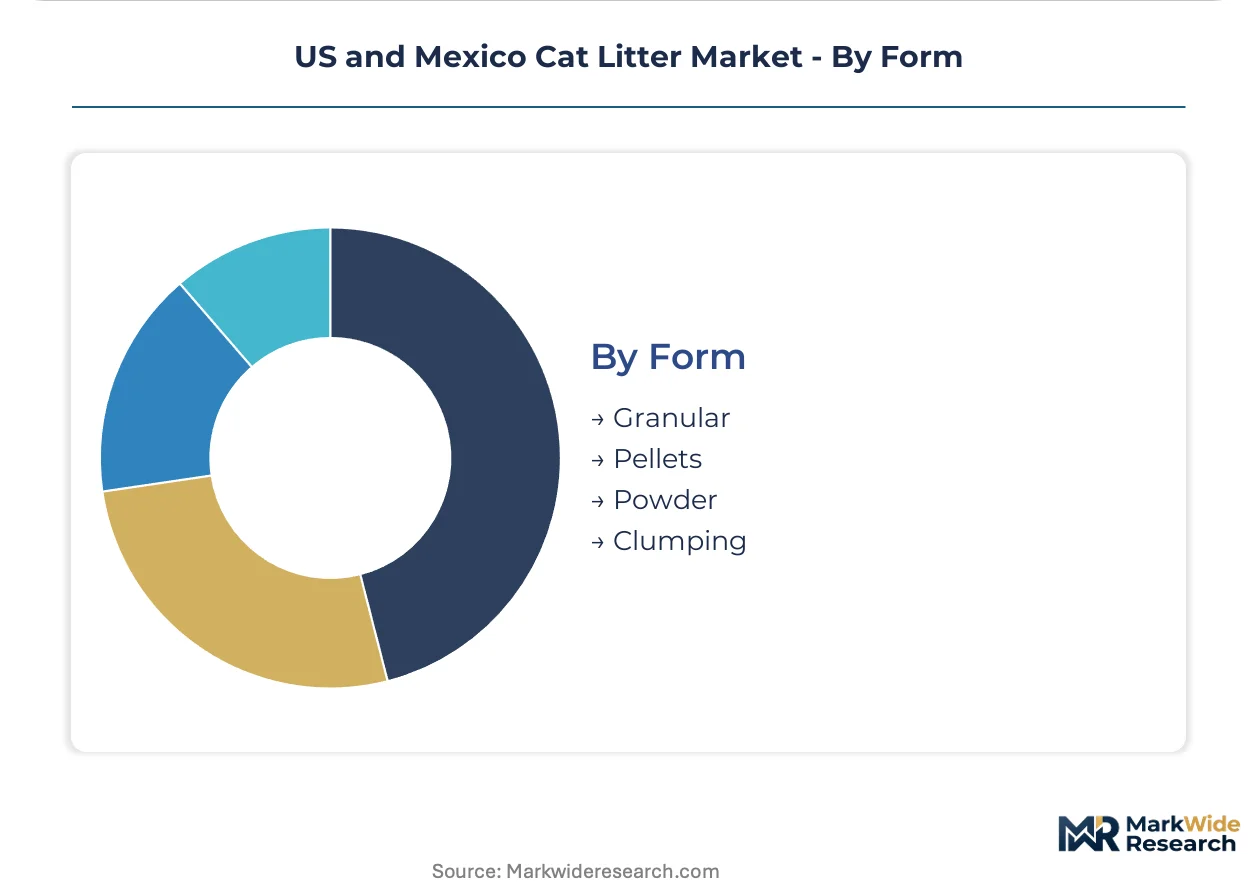
- Granular:Standard particle size distribution maintains broad household penetration across mass retail channels, with lower packaging density increasing freight costs per functional unit.
- Pellets:Compressed plant-fiber cylinders reduce dust and tracking, gaining share in biodegradable segments where enzymatic odor control systems integrate into substrate structure.
- Powder:Fine-grain formulations serve specialized veterinary and breeding applications requiring rapid moisture absorption and minimal particle size variation.
- Clumping:Liquid-activated cohesion chemistry, historically dominated by sodium bentonite, now extends to silica gel and advanced plant-fiber blends through extended R&D timelines. This form commands highest per-unit margins and subscription loyalty.
Household penetration is deepest in Granular. Technology investment is concentrating in Clumping.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Southwest anchors demand concentration for the US and Mexico Cat Litter Market, with EPA mining restrictions and multi-cat household density reshaping regional supply chains toward biodegradable and silica gel alternatives.
United States — California
Urban multi-cat households in Los Angeles and San Francisco metro areas drive premium biodegradable uptake, with composting-compatible formulations gaining shelf space at pet specialty retailers. The state's SB 54 extended producer responsibility framework mandates post-consumer recycled packaging, forcing reformulation investments. EPA Region 9 enforcement of Resource Conservation and Recovery Act disposal classifications accelerates veterinary clinic procurement shifts away from spent clay litter.
United States — Texas
Dallas-Fort Worth and Houston apartment density sustains repeat-purchase volume for odor-control formulations, with subscription auto-replenishment platforms capturing millennial pet owners. State environmental agencies enforce disposal pathway documentation for high-volume generators including shelters and breeding operations. PetSmart and Petco distribution hubs in the Dallas metro area anchor Southwest supply chain logistics for premium and private-label lines.
United States — Southwest Corridor
Phoenix and Austin metro areas exhibit fastest silica gel micropore technology adoption, with desiccant-based absorption reducing per-use volume for time-constrained consumers. EPA Clean Water Act permitting scarcity in neighboring Wyoming and Montana compresses domestic bentonite supply, elevating transport costs for clay-dependent formulations. Regional retailers are expanding private-label biodegradable assortments to preempt greenwashing liability exposure under FTC Green Guides scrutiny.
Mexico — Northern Border States
Chihuahua and Nuevo León manufacturing zones leverage proximity to Texas demand centers, with lower bentonite transport costs enabling regional production hubs for clay-based formulations. The country's federal environmental regulator enforces mining waste discharge standards that parallel EPA frameworks, pushing producers toward alternative feedstock qualification. Monterrey industrial clusters host contract manufacturing for US brands seeking tariff-advantaged supply chain reconfiguration.
Mexico — Central Mexico
Mexico City metropolitan area consumption concentrates in mass retail channels, with Walmart de México and Soriana networks distributing standard granular formulations to price-sensitive households. The capital's veterinary clinic density drives compliance-oriented procurement for biodegradable alternatives as landfill diversion mandates tighten. Puebla and Toluca manufacturing corridors attract plant-fiber processing investment from agricultural waste streams including corn and wheat residues.
US and Mexico Cat Litter Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers reposition around EPA mining restrictions and state-level extended producer responsibility frameworks. The vendor base concentrates among diversified consumer goods conglomerates with captive mineral reserves, specialty pet care operators with formulation R&D capabilities, and agricultural processors leveraging plant-fiber feedstock access. Three strategic archetypes define competitive positioning: mining-anchored clay specialists, biotechnology-integrated biodegradable developers, and subscription-platform-enabled direct-to-consumer brands. M&A activity targets captive bentonite reserves and enzymatic odor-control technology licensing, while geographic expansion focuses on Mexico manufacturing hubs serving US Southwest demand corridors.
Among diversified consumer goods conglomerates, Nestlé Purina Petcare and Church & Dwight Co Inc exemplify the R&D-integrated archetype, with the former leveraging global pet nutrition networks and the latter anchoring positioning through household brand equity in odor-neutralization chemistry. Oil-Dri Corporation of America represents the mining-anchored specialist model, with corporate nomenclature indicating captive mineral reserve dependence in southeastern US extraction zones. These three entities occupy distinct competitive vectors: multinational scale with substrate diversification, brand-driven chemistry integration, and upstream resource control respectively.
| Leading Market Players |
|---|
| The Clorox Company |
| Nestlé Purina Petcare |
| Oil-Dri Corporation of America |
| Church & Dwight Co Inc |
| Dr. Elsey's |
| Kent Corporation |
| Intersand Group |
| Pettex Limited |
| Nestle SA |
| Others |
Value Network & Pricing Analysis
California's SB 54 extended producer responsibility framework gates both qualified supply and premium-tier pricing access by mandating post-consumer recycled packaging and documented disposal pathways, compressing margins for non-compliant producers while rewarding verified biodegradable formulations with retail shelf space and pricing power.
Pricing Analysis
Input-cost pass-through from agricultural commodity markets destabilizes biodegradable product margins, with wheat and corn pellet pricing volatility forcing frequent adjustments. Three-tier pricing structure across premium, standard, and economy levels separates silica gel micropore formulations from clay-based standards and private-label economy lines. Price differentiation hinges on odor-control certification and clumping performance tier. Cost compression in the biodegradable segment is intensifying because plant fiber inputs lack long-term contract hedging. Mass retail channels exhibit highest price sensitivity, while subscription-based auto-replenishment platforms capture least price-sensitive urban multi-cat households.
Supply Chain Analysis
Warehouse-distribution layer concentration in Dallas-Fort Worth and San Diego metro areas anchors Southwest supply chain logistics for premium and private-label lines. Raw material sourcing draws from Wyoming and Montana bentonite deposits, Midwest wheat and corn processing centers, and Southeast pine pellet manufacturing. Distribution runs through pet specialty retailer regional distribution centers and mass retail hub-and-spoke networks. Single-source vulnerability in domestic bentonite supply compresses clay-dependent formulation availability. Contract manufacturing in Chihuahua and Nuevo León enables tariff-advantaged supply chain reconfiguration for US Southwest demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US and Mexico Cat Litter Market reads as a late-cycle quality story, with urban multi-cat household density in Southwest metropolitan areas shifting demand toward premium odor-control specifications that command subscription loyalty and repeat-purchase margins.
For Market Incumbents: Acquire captive mineral reserves in Mississippi and Georgia to secure bentonite supply continuity against EPA permit scarcity. Invest in enzymatic biodegradation R&D to close clumping performance gaps in plant-fiber formulations. Oil-Dri Corporation of America's upstream resource control demonstrates how mining-anchored positioning defends against substitute technology encroachment. Channel control through pet specialty private-label expansion preempts greenwashing liability exposure under FTC Green Guides scrutiny. For New Entrants and Emerging Players: Begin with silica gel micropore technology targeting time-constrained apartment dwellers in Phoenix and Austin metro areas, where change-interval extension commands premium pricing. Mexico manufacturing hubs serving US Southwest demand corridors offer lowest barrier-to-entry production footprint. Direct-to-consumer auto-replenishment platforms bypass retail slotting fees and capture lifetime value data from tech-adopting millennials. For Investors and Strategic Acquirers: Roll-up economics work for agricultural processors with plant-fiber feedstock access because EPA mining restrictions are structurally compressing clay supply and elevating alternative substrate valuations. Five-to-ten year viability hinges on enzymatic odor-control technology licensing positions. The signal to watch is FTC enforcement actions against unsubstantiated biodegradable claims, which will concentrate shelf space among verified-compliant brands.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Platform Integration | Auto-replenishment algorithms compress purchase cycles and capture millennial household lifetime value in Dallas-Fort Worth. |
| Backward Integration into Mineral Reserves | Captive bentonite deposits in Mississippi and Georgia secure supply continuity against EPA Clean Water Act permit scarcity. |
| Enzymatic Odor-Control Licensing | Technology acquisition accelerates plant-fiber clumping performance parity with sodium bentonite standards. |
| Mexico Manufacturing Footprint | Chihuahua and Nuevo León production hubs reduce transport costs to Texas demand centers and enable tariff optimization. |
| FTC Green Guides Compliance Certification | Verified biodegradable claims preempt retailer greenwashing liability and secure shelf space in California pet specialty channels. |
Research Methodology
Multiple input streams — primary interviews with plant managers and procurement leads at downstream retailers, regulatory affairs specialists at EPA Region 9, and category buyers at pet specialty chains — were reconciled against secondary validation from customs records, Nielsen retail audit data, and SEC 10-K filings. Bottom-up and top-down triangulation cross-referenced substrate-level production volumes with channel shipment data.
Historical consumption patterns were cross-referenced against panel input from industry stakeholders to derive expansion trajectories across the analysis window. Segmentation dimensions modeled include formulation chemistry, distribution channel, customer type, and physical form. CAGRs were synthesized from installed capacity trends and demand elasticity estimates. Forecast inputs incorporated EPA permit issuance timelines and agricultural commodity price correlation coefficients.
Several conditions sit outside the modeled scope, including unforeseen EPA enforcement escalations, trade policy modifications affecting Mexico manufacturing economics, and breakthrough clumping technologies that collapse performance gaps overnight. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Indonesia Pet Food Market
Pet Care Products
Pet Collar Market
Pet Care Products
Pet Water Dispenser Market
Pet Care Products
Pet Supplement Market
Pet Care Products
Dog Pen Market
Pet Care Products
Spain Pet Food Market
Pet Care Products
Cat Cage Market
Pet Care Products
Asia-Pacific Pet Travel Services Market
Pet Care Products
Philippines Pet Food Market
Pet Care Products
UAE Pet Food Market
Pet Care Products
Japan Pet Boarding Market
Pet Care Products
Mexico Pet Food Market
Pet Care Products
Canada Pet Food Market
Pet Care Products
Canada Pet Boarding Market
Pet Care Products
UAE Cat Food Market
Pet Care Products
Electric Pet Clippers Market