
 US Dog Food Market | 2026-2036
US Dog Food Market Size, Share, and Industry Trends Forecast 2026-2036
US Dog Food Market Insights
Multi-source ingredient procurement is expanding across the US dog food industry as manufacturers diversify protein and grain suppliers to mitigate input cost volatility. Nestlé Purina PetCare leverages extensive in-house milling and rendering infrastructure to control quality from farm to bag. Mars Petcare Inc. sustains dominance through vertical integration into veterinary nutrition science, while Blue Buffalo differentiates via specialized grain-free positioning targeting health-conscious owners.
US dog food comprises formulated nutritional products meeting AAFCO profiles for canine maintenance, growth, or therapeutic needs, typically manufactured through extrusion, canning, or cold-press processes to preserve protein integrity and shelf stability. Dry food occupies the largest volume share due to convenience and cost efficiency for mass-market consumers. Wet food commands premium shelf positioning and higher per-unit margins in specialty retail. Raw food, though smallest by volume, attracts the fastest-growing customer segment among owners seeking minimally processed diets.
The FDA Center for Veterinary Medicine enforces ingredient safety standards and facility inspections under the Food Safety Modernization Act, while AAFCO model regulations govern nutritional adequacy claims across state lines. USDA oversight of meat and poultry inputs further constrains sourcing flexibility for domestic producers. State-level feed control officials in California, Texas, and New York maintain supplemental labeling requirements that fragment compliance burdens. Stakeholders must monitor pending FDA guidance on raw pet food pathogen controls and evolving state definitions of "human-grade" claims.
Market Dynamics
Millennial pet ownership patterns are forcing formulation shifts across the US dog food industry, as demand for grain-free, organic, and raw diets reconfigures manufacturing infrastructure and ingredient sourcing networks.
Growth Catalysts
- AAFCO Profile Alignment:State feed control officials in California, Texas, and Florida enforce nutritional adequacy standards that validate premium positioning and justify shelf price premiums for compliant manufacturers.
- Urban Pet Density Concentration:Metropolitan clusters in Los Angeles, Dallas-Fort Worth, and Miami generate concentrated demand pools that reduce distribution cost per unit for specialty formulations.
- Cold-Press Processing Adoption:Minimally processed manufacturing techniques preserve protein integrity and attract owners seeking alternatives to extruded dry food, expanding addressable premium volume.
Market Restraints
- Protein Input Volatility:Rendering facility closures and livestock supply fluctuations destabilize chicken meal and beef tallow pricing, compressing margin predictability for mid-tier producers.
- FDA Pathogen Oversight:Pending FDA Center for Veterinary Medicine guidance on raw pet food safety mandates HACCP expansion and testing infrastructure that smaller facilities cannot absorb.
- Grain-Free Substitution Risk:Veterinary cardiologists link certain legume-heavy formulations to dilated cardiomyopathy, triggering owner migration back to grain-inclusive diets and stranding specialized inventory.
Strategic Opportunities
- Veterinary Channel Penetration:Prescription therapeutic diets distributed through clinic networks capture recurring revenue streams and build switching costs unavailable in mass retail.
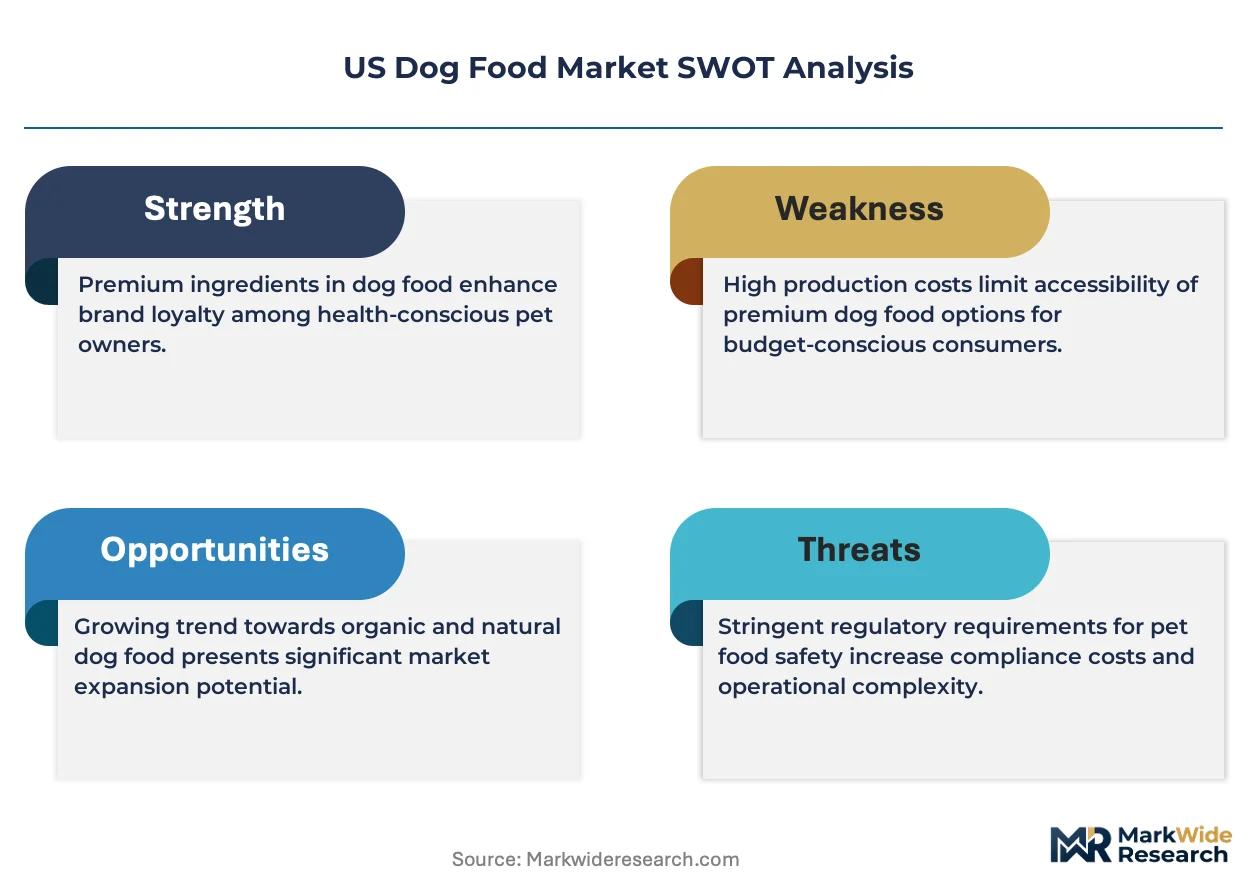
- USDA-Inspected Human-Grade Sourcing:Facilities achieving USDA meat and poultry certification unlock "human-grade" labeling claims that command 40-60% price premiums in specialty retail.
- Direct-to-Consumer Subscription Models:Portioned fresh food delivery bypasses retail slotting fees and captures first-party consumption data for formulation optimization.
Industry Challenges
- Extrusion Engineering Talent Scarcity:Retiring process engineers with 20-plus years of thermal processing expertise leave knowledge gaps in moisture control and die design optimization.
- Multi-State Labeling Fragmentation:California's Proposition 65 warning requirements and New York's feed control supplemental mandates force SKU proliferation and compliance auditing costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Dog Food Market |
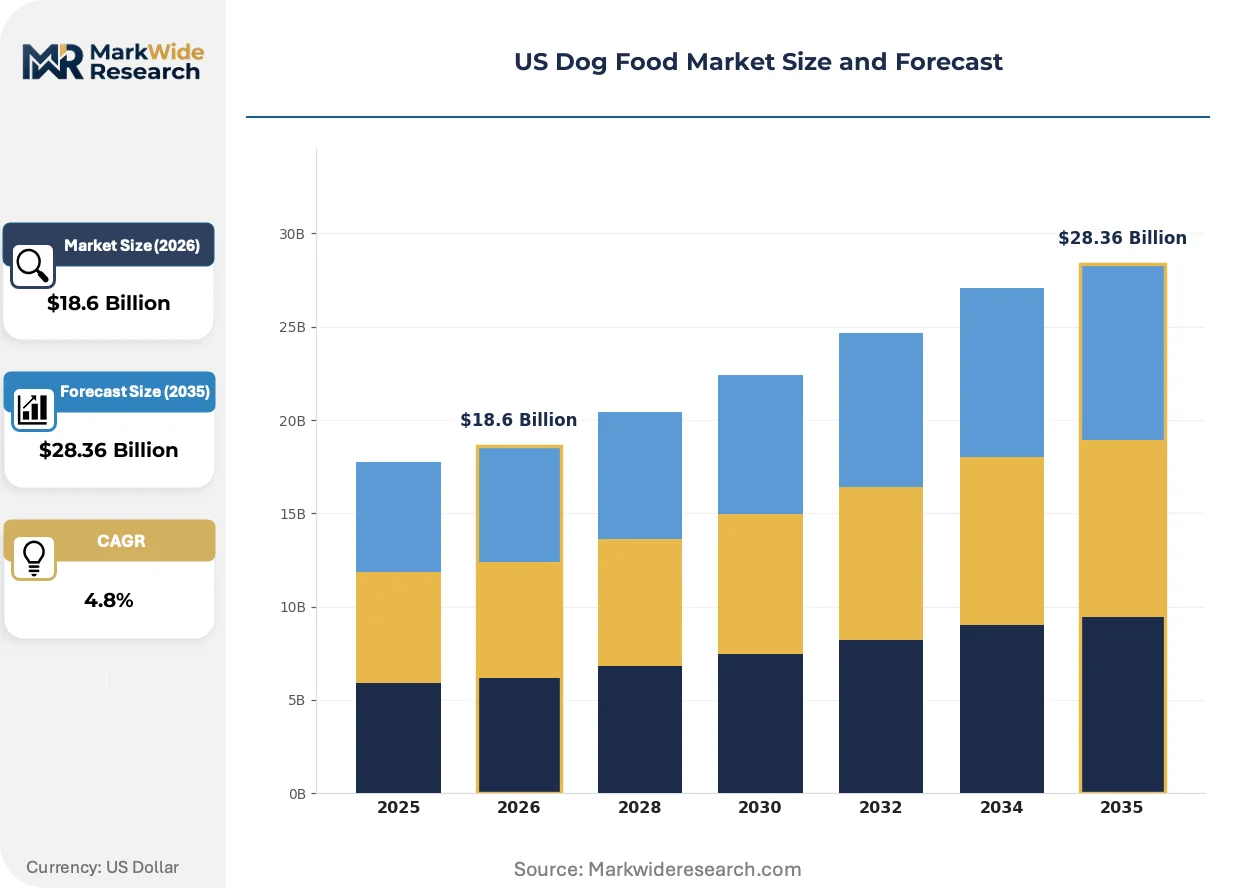
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $28.36 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Raw Food, Treats Ingredient Type: Meat-Based, Grain-Free, Organic, Non-GMO Target Customer: Pet Owners, Veterinarians, Pet Retailers, Online Shoppers Distribution Channel: Supermarkets, Specialty Pet Stores, E-Commerce, Wholesalers |
| Companies Covered | Nestlé Purina PetCare, Mars Petcare Inc., Hill's Pet Nutrition, General Mills, The J.M. Smucker Company, Blue Buffalo, Diamond Pet Foods, Freshpet, Royal Canin, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Dog Food Market Trends and Innovations
Formulation science and manufacturing technology are converging to enable mass customization of canine nutrition, collapsing the traditional trade-off between production scale and dietary specificity.
High-pressure processing (HPP) is modularizing raw pet food safety protocols by eliminating pathogens without thermal degradation of amino acid profiles. Premium manufacturers in Colorado and Oregon adopt HPP lines to satisfy FDA pathogen reduction expectations while preserving raw diet positioning. This technology is modularizing what was previously artisan-scale production into regionally distributed manufacturing nodes.
The FDA Food Safety Modernization Act's preventive controls rule is tightening facility registration and hazard analysis requirements for domestic renderers and extrusion plants. Compliance investments concentrate among multi-state operators with dedicated quality assurance teams, while single-facility producers face consolidation pressure. Raw food specialists in the Pacific Northwest and Northeast are responding by constructing dedicated HPP-capable plants rather than co-packing through conventional facilities.
Subscription-based fresh food purchasing is displacing periodic retail stock-up behavior among urban millennial owners. Direct-to-consumer brands capture recurring revenue and consumption data that mass-market labels cannot access, forcing retail-dependent manufacturers to develop companion digital platforms. This shift concentrates in coastal metropolitan markets where delivery logistics density supports refrigerated last-mile economics.
US Dog Food Market Segmentation
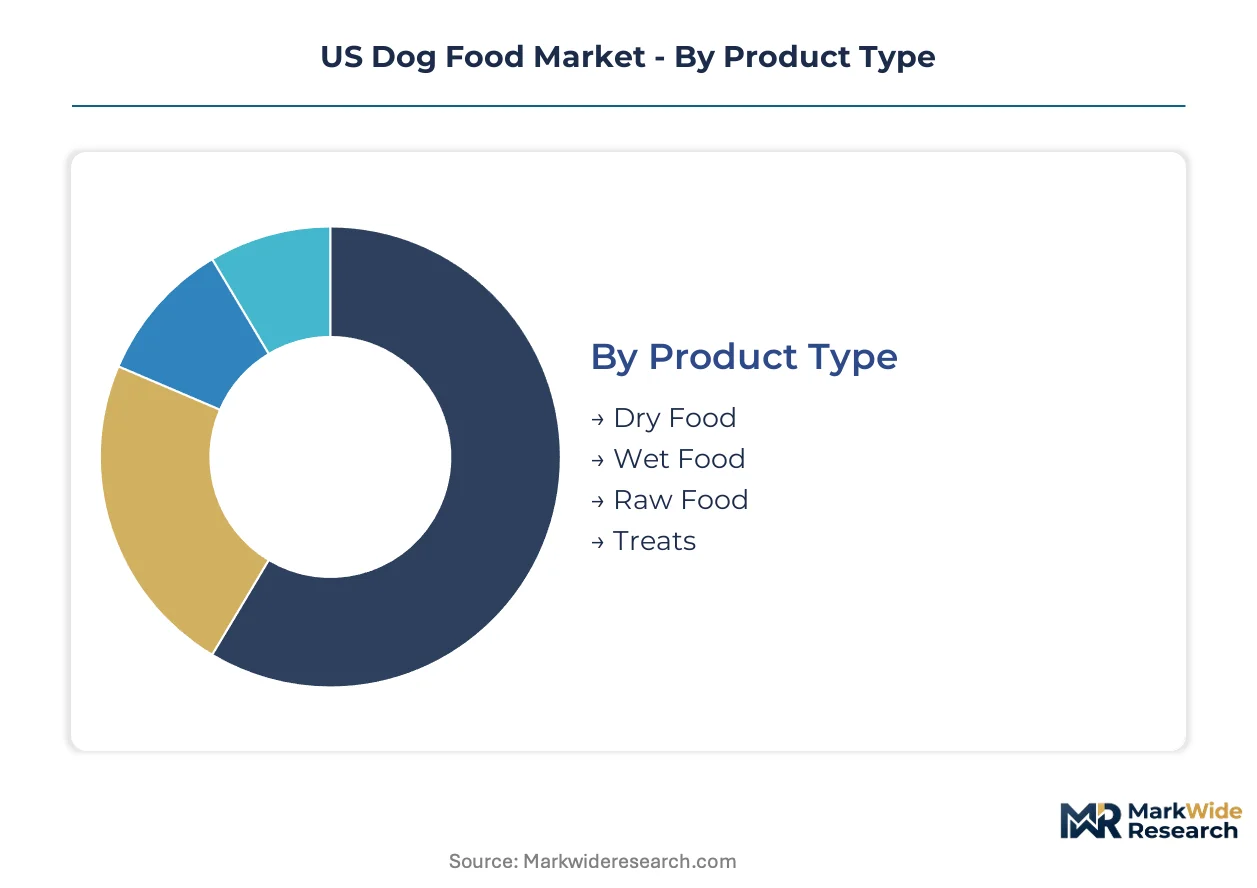
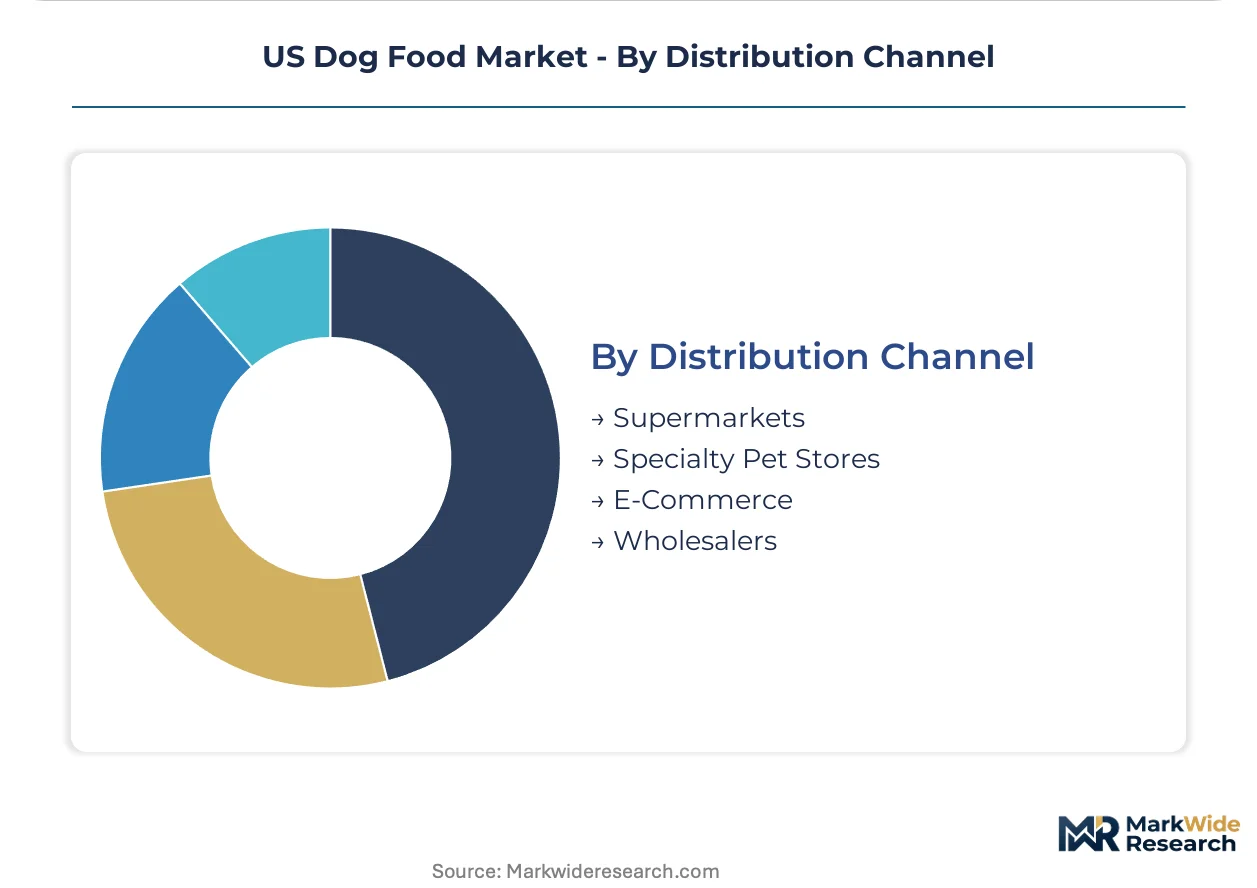
Segmentation in the US dog food market determines compliance pathways, margin structures, and channel access. Manufacturers align formulation investments with certification requirements that vary sharply across product categories and customer touchpoints.
Product Type:
Dry food carries baseline AAFCO nutritional adequacy requirements, while raw and wet formulations trigger additional FDA Center for Veterinary Medicine pathogen controls and processing facility registrations.
- Dry Food:Extruded kibble formulations achieve 18-24 month shelf stability through thermal processing and moisture reduction below 10%. Mass-market penetration concentrates in suburban Texas and Florida households where multi-dog ownership drives volume purchasing and storage efficiency.
- Wet Food:Canned or pouched products with 75-85% moisture content deliver palatability advantages for senior dogs and medical conditions. California and New York urban owners sustain premium positioning through refrigerated retail distribution and veterinary clinic recommendations.
- Raw Food:Minimally processed frozen or freeze-dried products requiring HACCP-compliant facilities and batch-level pathogen testing.
- Treats:Supplementary nutrition products with functional positioning around dental health or training rewards.
Dry food sits at the top of the volume ranking, with raw food climbing the fastest.
Ingredient Type:
Ingredient positioning stratifies across cost tiers, with organic and non-GMO segments commanding certification premiums that reshape procurement geography and supplier qualification timelines.
- Meat-Based:Formulations with animal protein as the primary ingredient, sourced through USDA-inspected rendering facilities or fresh meat suppliers. Midwestern production clusters in Kansas and Nebraska leverage proximity to livestock processing infrastructure.
- Grain-Free:Legume and potato-based carbohydrate substitutes developed in response to owner sensitivity concerns. Pacific Northwest and Colorado manufacturers pioneered these formulations before FDA cardiomyopathy investigations triggered formulation recalibration.
- Organic:USDA National Organic Program certified ingredients requiring segregated supply chains and annual third-party audits.
- Non-GMO:Verified absence of genetically modified organisms through supply chain documentation and testing protocols.
Meat-based formulations retain dominant volume share, with organic certification gaining share fastest among coastal metropolitan purchasers.
Target Customer:
Customer segmentation determines pricing authority and switching costs, with veterinary and direct-to-consumer channels capturing recurring revenue unavailable in transactional retail environments.
- Pet Owners:End consumers making purchase decisions based on palatability, price, and health positioning. Millennial owners in Austin, Denver, and Seattle demonstrate highest willingness to pay for subscription fresh food services.
- Veterinarians:Licensed practitioners prescribing therapeutic diets for obesity, renal, or gastrointestinal conditions. Prescription authorization requirements create switching costs and margin protection unavailable in mass retail.
- Pet Retailers:Independent and chain specialty stores providing curated assortment and staff consultation.
- Online Shoppers:Digital-native purchasers prioritizing convenience, auto-replenishment, and direct brand relationships.
Pet owners represent the largest addressable base, with online shoppers expanding most quickly as refrigerated last-mile infrastructure matures.
Distribution Channel:
Channel selection constrains temperature requirements, slotting fee exposure, and data capture capabilities that differentiate manufacturer competitive position.
- Supermarkets:Mass-market retail with high foot traffic and competitive price positioning. Kroger and Walmart distribution networks in Ohio and Arkansas prioritize national-brand dry food with efficient turnover metrics.
- Specialty Pet Stores:Curated assortment environments with trained staff and premium positioning. Independent retailers in California and Massachusetts sustain margin through exclusive distribution agreements and private label development.
- E-Commerce:Direct and platform-based digital sales with subscription mechanics and first-party data capture.
- Wholesalers:B2B distribution to independent retailers, veterinary clinics, and kennel operations.
Supermarkets hold the volume lead, with e-commerce posting the steepest expansion trajectory as fulfillment economics improve in dense metropolitan markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping where US dog food production concentrates, as facilities migrate toward states with lower compliance burdens and stronger agricultural input access. California's Proposition 65 labeling requirements and New York's supplemental feed control mandates push mid-tier manufacturers toward Texas and Florida, where state-level oversight remains less fragmented.
California
Urban pet density in Los Angeles and San Francisco sustains premium pricing power for fresh and organic formulations. The state's Office of Environmental Health Hazard Assessment enforces Proposition 65 warning requirements that complicate ingredient labeling for national brands. Sacramento Valley distribution hubs serve as consolidation points for Pacific Northwest raw food specialists seeking California market access.
Texas
Metropolitan clusters in Dallas-Fort Worth and Houston generate concentrated demand pools that reduce per-unit distribution costs for mass-market dry food. The Texas Department of State Health Services maintains feed control regulations aligned with AAFCO models, avoiding the supplemental mandates seen in coastal states. Amarillo and Lubbock rendering infrastructure supplies chicken meal and beef tallow to regional extrusion plants.
Florida
Miami and Tampa Bay urban pet ownership drives wet food and refrigerated fresh product demand through specialty retail channels. The Florida Department of Agriculture and Consumer Services coordinates with FDA under Food Safety Modernization Act frameworks without imposing state-specific labeling overlays. Orlando distribution centers serve as Southeast regional hubs for national brands.
Colorado
Denver-Boulder millennial pet owners demonstrate highest willingness to pay for subscription-based fresh food services and grain-free formulations. The Colorado Department of Agriculture enforces feed safety standards while permitting raw food production under HACCP-compliant facility registrations. Front Range manufacturing nodes specialize in cold-press and high-pressure processing technologies for minimally processed diets.
Pacific Northwest
Seattle and Portland owners prioritize organic certification and human-grade sourcing claims that command 40-60% price premiums. Oregon and Washington state feed control officials supplement AAFCO standards with organic handling requirements that align with USDA National Organic Program audits. Portland-area facilities pioneered high-pressure processing adoption for raw food pathogen control.
US Dog Food Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer fresh food and veterinary prescription channels. The US dog food market exhibits consolidated mass-market dominance alongside fragmented specialty segments. Three archetypes define competitive positioning: vertically integrated multinationals with captive rendering infrastructure, digital-native subscription brands with refrigerated logistics, and veterinary-channel specialists with prescription authorization networks. Capacity expansion and backward integration into protein rendering represent the dominant competitive moves as input cost volatility intensifies.
Within the multinational tier, Nestlé Purina PetCare and Mars Petcare Inc. exemplify scale-driven archetypes with in-house milling and nutritional science capabilities. Among veterinary-channel specialists, Hill's Pet Nutrition occupies a position defined by prescription diet authorization and clinic network penetration. Blue Buffalo represents the premium natural positioning archetype that targets health-conscious millennial owners through specialty retail. These companies anchor competitive dynamics without exhausting the full spectrum of market participants.
| Leading Market Players |
|---|
| Nestlé Purina PetCare |
| Mars Petcare Inc. |
| Hill's Pet Nutrition |
| General Mills |
| The J.M. Smucker Company |
| Blue Buffalo |
| Diamond Pet Foods |
| Freshpet |
| Royal Canin |
| Others |
Pricing and Supply Chain Analysis
Mass-market suburban households in Texas and Florida anchor transactional purchasing patterns that sustain commodity-style dry food pricing, while coastal millennial owners absorb subscription premiums for refrigerated fresh formats.
Pricing Analysis
Retailer markup layers in specialty pet channels sustain 40-60% premiums for human-grade certified formulations against mass-market dry alternatives. Price differentiation stems from USDA inspection tier and cold-chain delivery cost. Pricing pressure intensifies in mid-tier extruded kibble as protein input volatility compresses margin predictability. Price sensitivity concentrates among multi-dog suburban owners, while single-pet urban households demonstrate lowest elasticity for subscription fresh services.
Supply Chain Analysis
Animal protein supply rests on Midwestern rendering infrastructure in Kansas, Nebraska, and Texas, with organic ingredient sourcing drawing from Pacific Northwest and California agricultural networks. Key inputs include chicken meal, beef tallow, and certified organic grains. Single-source vulnerability concentrates in rendering facility consolidation, where livestock supply fluctuations destabilize input costs. Distribution runs through Orlando and Sacramento regional hubs serving Southeast and West Coast metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in US dog food hinges on cold-chain logistics maturation enabling subscription fresh formats to capture price-insensitive urban cohorts.
For Market Incumbents: Deploy captive rendering infrastructure to buffer protein input volatility and protect margin predictability. Nestlé Purina and Mars Petcare should consolidate co-packing relationships in Texas and Florida to reduce compliance fragmentation. The FDA's pending raw food pathogen guidance threatens smaller facility viability, creating acquisition opportunities for HACCP-compliant plants. For New Entrants and Emerging Players: Veterinary clinic networks represent the most penetrable channel for prescription therapeutic authorization. White-space exists in USDA-inspected human-grade sourcing for Pacific Northwest and Colorado metropolitan markets. Direct-to-consumer subscription mechanics with first-party data capture offer defensible positioning against retail-dependent incumbents. For Investors and Strategic Acquirers: Pet food multinationals with captive milling infrastructure are the most active acquirers in this space, targeting HPP-capable raw food specialists and subscription platforms with refrigerated logistics. Long-term viability favors assets with veterinary channel penetration or USDA human-grade certification. Watch FDA raw food guidance finalization as inflection indicator for facility compliance costs and consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rendering | Captive protein supply insulates margin from livestock price volatility in Midwestern production clusters. |
| HPP Facility Construction | High-pressure processing adoption satisfies FDA pathogen expectations while preserving raw diet premium positioning. |
| Veterinary Channel Penetration | Prescription authorization networks build recurring revenue streams unavailable in transactional retail environments. |
| Direct-to-Consumer Platform Launch | Subscription mechanics bypass slotting fees and capture consumption data for formulation optimization. |
| USDA Human-Grade Certification | Inspection tier unlocks labeling claims commanding specialty retail premiums in coastal metropolitan markets. |
Research Methodology
Coverage spans California, Texas, Florida, Colorado, and Pacific Northwest states, with primary inputs from each region's manufacturing and distribution clusters. The analysis combines interviews with plant operations managers, procurement leads at rendering facilities, specialty retail category buyers, and state feed control officials with secondary validation from FDA Center for Veterinary Medicine guidance documents, AAFCO model regulations, USDA inspection records, and state-level feed safety filings. Bottom-up facility capacity assessments triangulate against top-down retail audit data.
Rate-of-change decomposition separates volume growth from mix-shift effects across the projection horizon. The analytical framework models segmentation dimensions including product type, ingredient certification tier, distribution channel, and metropolitan market density. CAGRs derive from historical trajectory analysis adjusted for regulatory inflection points and channel migration patterns. Forecast inputs incorporate protein input cost indices and refrigerated last-mile logistics expansion timelines.
Revisions become necessary when FDA raw food pathogen guidance finalizes, rendering facility closures accelerate, or state labeling mandates proliferate beyond current AAFCO alignment. Forecasts reflect documented assumptions about regulatory stability and protein supply continuity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Vegan Pet Food Market
Pet Care Products
Pet Hair Brush Market
Pet Care Products
US Pet Daycare Market
Pet Care Products
High Protein Dog Food Market
Pet Care Products
Europe Pet Treats Market
Pet Care Products
Pet Car Seat Protectors Market
Pet Care Products
Pet Noise Anxiety Market
Pet Care Products
Europe Pet Food Market
Pet Care Products
Plant-Based Dog Food Market
Pet Care Products
South America Cat Food Market
Pet Care Products
Aquarium Market
Pet Care Products
US Pet Food Market
Pet Care Products
Pet Accessories Market
Pet Care Products
Insulated Dog House Market
Pet Care Products
Canada Pet Training Services Market
Pet Care Products
Europe Cat Food Market