
 Dog Perfume Market | 2026-2036
Dog Perfume Market Size, Share, and Industry Trends Forecast 2026-2036
Dog Perfume Market Analytics
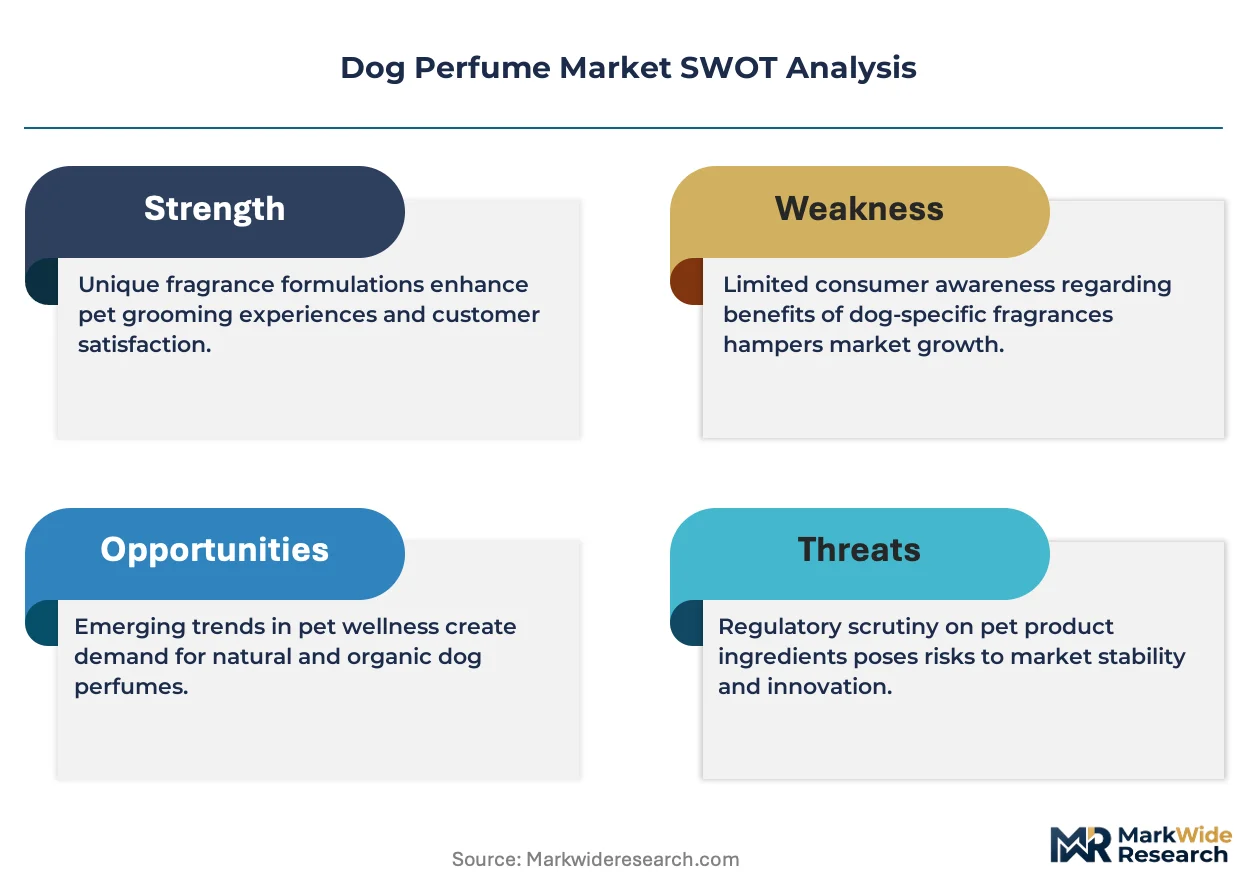
EU REACH chemical registration rules is repositioning how manufacturers source fragrance compounds for canine applications. TropiClean Pet Products leverages botanical supply chains to sustain its natural-ingredient positioning across North American retail. Isle of Dogs anchors premium salon distribution through breed-specific formulations that command higher shelf placement. Pawfume competes on direct-to-consumer velocity, using subscription models to lock in recurring revenue from urban dog owners.
Dog perfume comprises alcohol-free or low-volatility fragrance formulations designed for topical application to canine coats, typically incorporating pH-balanced carriers between 6.2 and 7.5 to match dog skin chemistry. The category serves pet owners seeking odor control between grooming appointments without irritating sensitive dermal layers. Sprays dominate volume due to convenience and dosing precision, though perfumed oils capture disproportionate margin from boutique and veterinary channels. Natural ingredients segment growth outpaces synthetic alternatives as clean-label expectations migrate from human cosmetics to pet care, with essential oils sub-segment benefiting from aromatherapy cross-marketing.
EPA regulates volatile organic compound emissions from aerosol pet products, while FDA Center for Veterinary Medicine monitors cosmetic claims that imply therapeutic benefit. State-level California Proposition 65 enforcement adds compliance cost for fragrance houses supplying West Coast distribution. Stakeholders must monitor evolving ingredient disclosure mandates at both federal and state levels to anticipate reformulation timelines and avoid channel restrictions.
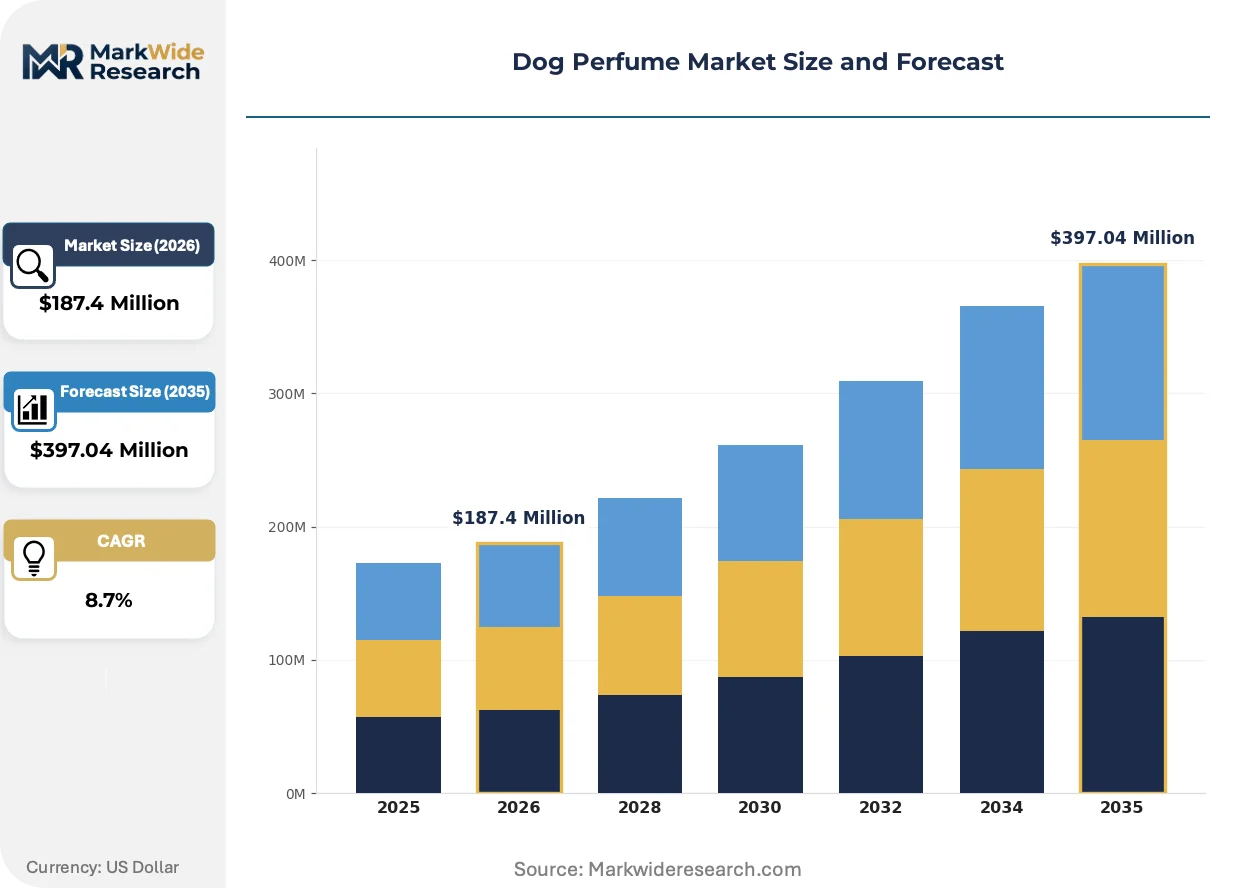
Market Dynamics
Pet humanization is compressing purchase cycles for premium grooming accessories as millennial and Gen Z owners treat canine odor control as a lifestyle extension rather than functional necessity. This behavioral shift is forcing formulation houses to reposition fragrance chemistry around skin-safe botanicals.
Growth Catalysts
- REACH chemical registration:EU ECHA mandates are accelerating R&D investment in biodegradable fragrance carriers, pushing manufacturers toward pH-balanced formulations that preempt regulatory rejection.
- Subscription commerce infrastructure:Direct-to-consumer platforms are locking urban dog owners into recurring replenishment models that stabilize revenue predictability for niche fragrance brands.
- Veterinary channel expansion:Clinic-based retail is capturing premium margin through breed-specific SKUs that command professional endorsement and higher per-unit pricing.
Market Restraints
- Essential oil input volatility:Climate-driven supply disruptions in lavender and chamomile growing regions are compressing gross margins for natural-positioned brands.
- Aerosol propellant restrictions:EPA volatile organic compound emission caps are forcing costly reformulation of spray-dominant product lines.
- California Proposition 65 enforcement:West Coast distribution requires additional fragrance compound testing that adds compliance overhead without market expansion benefit.
Strategic Opportunities
- Clean-label convergence:Human cosmetics ingredient disclosure norms are migrating to pet care, creating first-mover advantage for brands publishing full botanical sourcing maps.
- Veterinary dermatology partnership:Collaboration with skin-sensitive formulation research opens access to hypoallergenic positioning and prescription-adjacent distribution.
- Aromatherapy cross-marketing:Essential oil sub-segments can leverage human wellness retail shelf placement to reduce customer acquisition costs.
Industry Challenges
- Fragrance chemist talent scarcity:Specialized expertise in species-specific pH chemistry commands premium compensation that strains mid-cap R&D budgets.
- Multi-jurisdiction label harmonization:Divergent FDA cosmetic claims rules and state-level disclosure mandates force SKU proliferation that fragments production runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dog Perfume Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sprays, Perfumed Oils, Solid Perfumes, Scented Wipes Ingredient Type: Natural Ingredients, Synthetic Fragrance, Essential Oils, Alcohol-Free Packaging Type: Glass Bottles, Plastic Bottles, Sachets, Metal Cans Distribution Channel: Online Retail, Pet Stores, Supermarkets, Veterinary Clinics |
| Companies Covered | TropiClean Pet Products, Pawfume, Earthbath, Bodhi Dog, Pet Head, Isle of Dogs, Captain Zack, Odo-Rite, Petveda, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dog Perfume Market Evolving Landscape
Formulation science and distribution architecture are diverging sharply between mass retail and premium channels. Technology investment concentrates on precision dosing systems, while regulatory pressure accelerates natural ingredient substitution.
Micro-encapsulation technology is automating controlled-release fragrance delivery in canine coat applications. Boutique grooming salons are adopting these systems at twice the rate of mass retailers, drawn by extended odor-control claims that justify service premiums. The technology is automating the shift from alcohol-based carriers to water-soluble suspension systems that reduce dermal irritation incidents.
EU REACH substance evaluation is forcing fragrance houses to retire synthetic musk compounds ahead of sunset dates. Manufacturers serving European distribution are reformulating entire SKU lines around botanical alternatives, absorbing six-to-twelve month certification delays. The policy is compressing synthetic ingredient demand most severely in export-oriented production facilities.
Urban dog owners are unbundling grooming services from fragrance purchase, treating odor control as a between-appointment home ritual. Specialty pet retailers are capturing this behavior shift through sampling programs that convert trial to subscription, displacing veterinary channel dominance in premium fragrance. This pattern concentrates in United States metropolitan markets where apartment living amplifies odor sensitivity.
Dog Perfume Market Segmentation
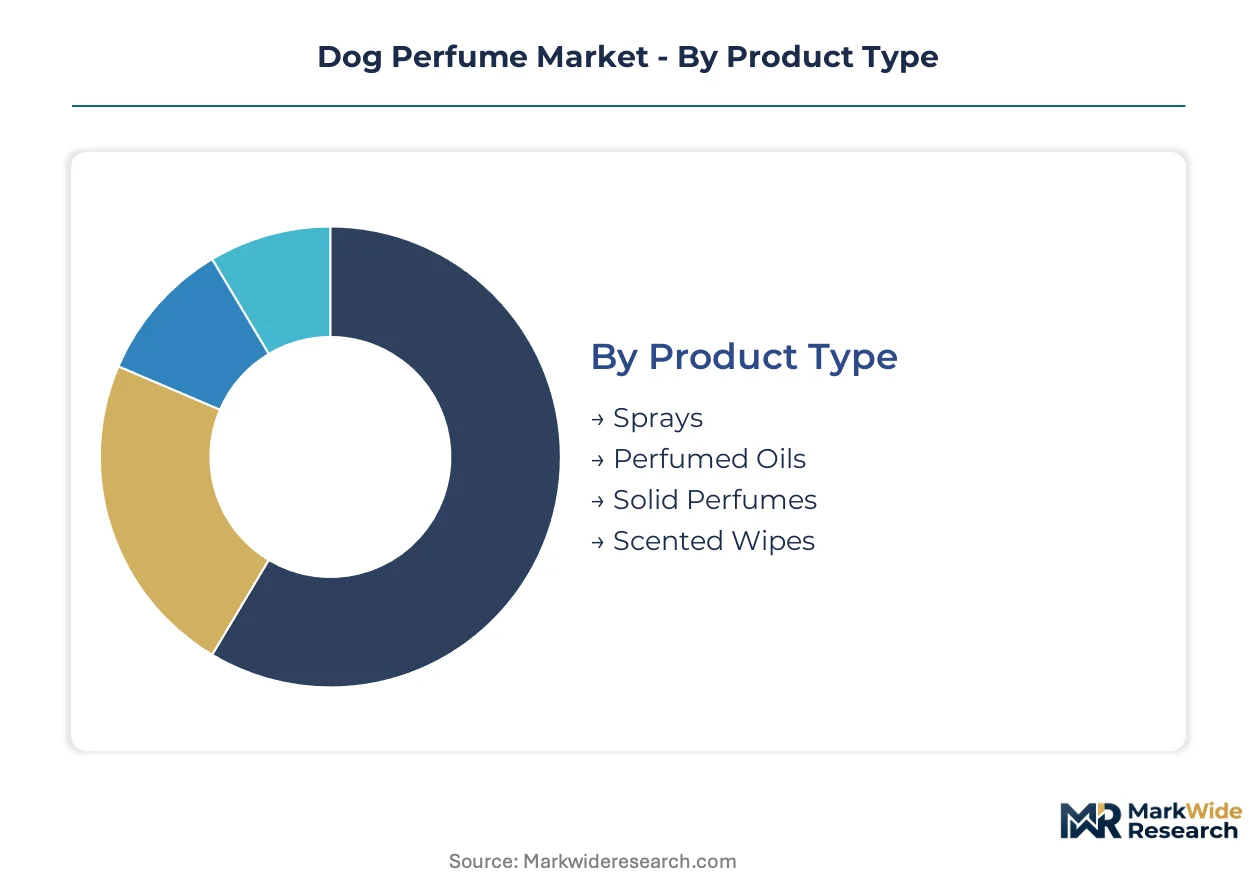
Dog perfume segmentation reflects divergent capital requirements across formulation science, packaging engineering, and channel infrastructure. Manufacturers must calibrate investment intensity against margin profiles that vary sharply between mass retail and premium salon distribution.
Product Type:
Capital intensity peaks with precision dosing systems and aerosol propellant compliance infrastructure. Spray formulations demand the heaviest upfront investment in volatile organic compound emission controls and micro-encapsulation R&D.
- Sprays:Alcohol-free or low-volatility aqueous suspensions with pH-balanced carriers between 6.2 and 7.5. Demand concentrates in United States urban markets where apartment living amplifies odor sensitivity and convenience purchasing. EPA emission caps are forcing costly reformulation of propellant-based lines, compressing margins for legacy manufacturers.
- Perfumed Oils:Concentrated lipid-based formulations requiring breed-specific viscosity grading and extended skin-contact safety testing. Veterinary clinics and boutique grooming salons in metropolitan France and Germany capture disproportionate margin through professional endorsement and higher per-unit pricing.
- Solid Perfumes:Wax-matrix carriers with controlled melting points for dermal safety.
- Scented Wipes:Non-woven substrate impregnation with preservative-free fragrance solutions.
Most installed capacity flows through Sprays. Expansion is steepest in Perfumed Oils.
Ingredient Type:
Raw material sourcing complexity separates segments by supply chain length and climate dependency. Natural ingredient procurement requires the longest capital lockup due to growing seasonality and geographic concentration of botanical production.
- Natural Ingredients:Botanical extracts and plant-derived carriers subject to EU REACH substance evaluation and biodegradable certification timelines. Clean-label expectations migrating from human cosmetics are compressing purchase cycles for premium-positioned brands in United Kingdom and Netherlands retail.
- Synthetic Fragrance:Laboratory-engineered aromatic compounds facing accelerated sunset dates for musk derivatives under ECHA mandates. Export-oriented production facilities in Germany and Belgium are absorbing six-to-twelve month reformulation delays.
- Essential Oils:Steam-distilled or cold-pressed terpenoid fractions from lavender, chamomile, and cedarwood. Climate-driven supply disruptions in Provence and Bulgarian growing regions are compressing gross margins for aromatherapy-crossover brands.
- Alcohol-Free:Glycerin or propylene glycol substituted carriers formulated for sensitive dermal layers and regulatory preemption in California Proposition 65 jurisdictions.
Volume concentration sits with Synthetic Fragrance. Steepest expansion trajectory belongs to Natural Ingredients.
Packaging Type:
Unit economics diverge sharply between premium glass positioning and mass-market plastic throughput. Glass bottle manufacturing demands the highest fixed-capital deployment in molding and decoration equipment.
- Glass Bottles:Borosilicate or soda-lime containers with UV-protective tinting and precision spray pump integration. Specialty pet retailers in Paris, London, and Milan use sampling programs to convert trial to subscription, locking urban dog owners into recurring replenishment.
- Plastic Bottles:PET or HDPE blow-molded containers optimized for supermarket and big-box retail velocity. United States mass-market distribution favors this format for shipping efficiency and breakage reduction.
- Sachets:Single-use laminated film pouches for travel and trial-size distribution.
- Metal Cans:Aerosol-compatible aluminum or tinplate cylinders with corrosion-resistant internal lining.
Plastic Bottles carry the highest shipment volumes. Glass Bottles are gaining share fastest in premium channels.
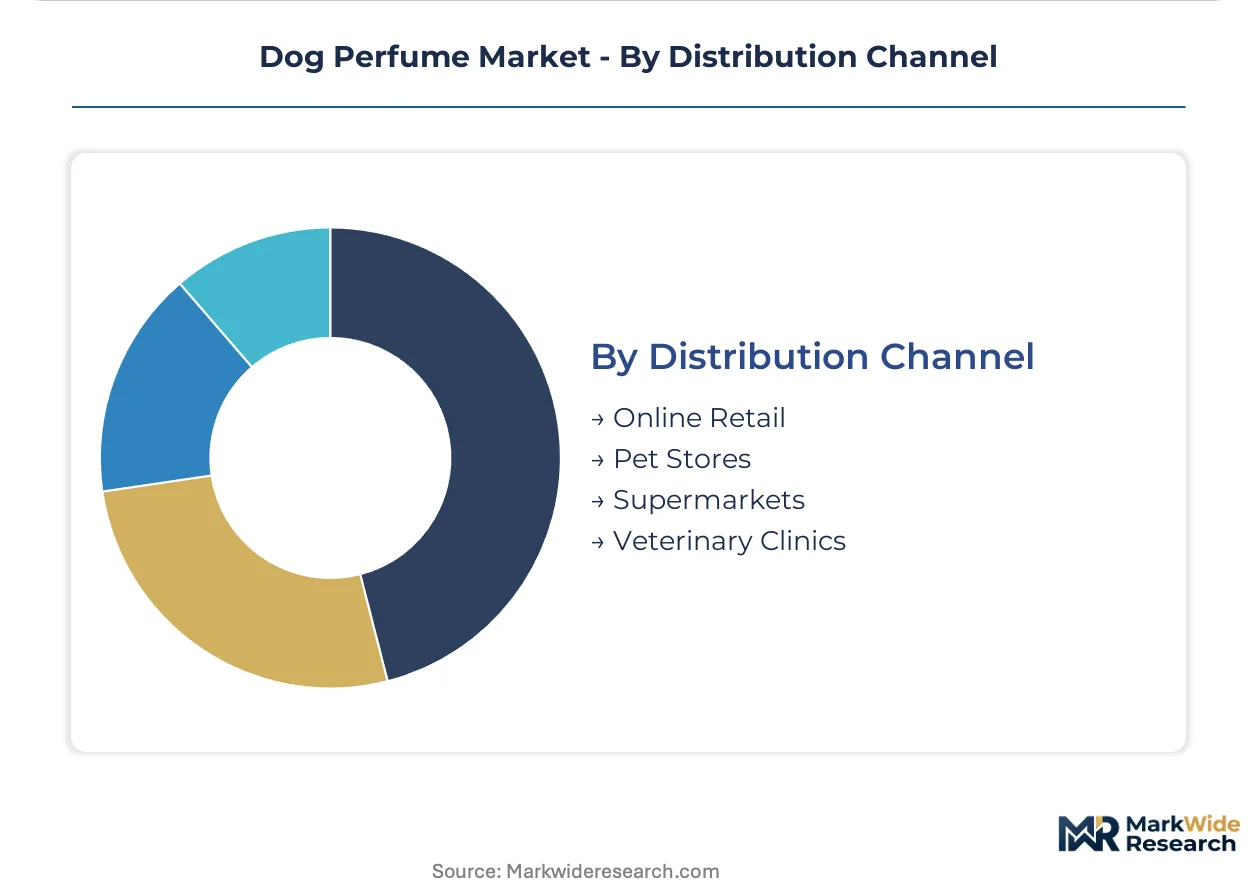
Distribution Channel:
Customer acquisition cost structures separate channels by digital infrastructure investment versus physical footprint amortization. Online retail demands the heaviest technology spend in subscription platform architecture and last-mile logistics.
- Online Retail:Direct-to-consumer platforms with automated replenishment algorithms and social media-native customer acquisition. Urban dog owners in United States metropolitan markets are unbundling grooming services from fragrance purchase, treating odor control as a between-appointment home ritual.
- Pet Stores:Specialty retail with trained staff consultation and cross-merchandising adjacent to grooming tools and premium nutrition. United Kingdom and Germany chains are expanding breed-specific SKU placement.
- Supermarkets:Mass-market velocity with price-promotional cadence and placement in pet care aisles.
- Veterinary Clinics:Professional endorsement channel with hypoallergenic positioning and prescription-adjacent distribution access.
Pet Stores and Supermarkets combined move the highest unit volumes. Online Retail is climbing the fastest as subscription commerce infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fragrance chemists specializing in species-specific pH chemistry concentrate in Germany, France, and the United States, anchoring formulation R&D for canine applications.
United States
Urban dog owners in New York, Los Angeles, and Chicago treat odor control as between-appointment home rituals. FDA Center for Veterinary Medicine monitors cosmetic claims implying therapeutic benefit. Specialty pet retailers in Manhattan and Brooklyn convert trial to subscription through sampling programs.
Germany
Boutique grooming salons in Berlin and Munich adopt micro-encapsulation systems at twice the rate of mass retailers. EU REACH substance evaluation forces fragrance houses to retire synthetic musk compounds ahead of sunset dates. Export-oriented production facilities in Hamburg absorb six-to-twelve month reformulation delays.
France
Veterinary clinics in Paris and Lyon capture premium margin through breed-specific SKUs commanding professional endorsement. ECHA mandates accelerate R&D investment in biodegradable fragrance carriers. Provence lavender growing regions face climate-driven supply disruptions compressing gross margins.
United Kingdom
Clean-label expectations migrating from human cosmetics compress purchase cycles for premium-positioned brands in London and Manchester retail. Trading Standards enforces cosmetic product safety regulations for pet applications. Isle of Dogs anchors premium salon distribution through breed-specific formulations.
Japan
Metropolitan Tokyo and Osaka pet owners drive demand for alcohol-free formulations suited to apartment living. METI oversees chemical substance management under CSCL frameworks. Aromatherapy cross-marketing from human wellness retail reduces customer acquisition costs in Kanto region.
Dog Perfume Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the dog perfume market, with formulation houses investing in REACH-compliant R&D while direct-to-consumer brands deploy subscription commerce infrastructure. The vendor base spans multinational pet care conglomerates, regional grooming specialists, and digitally native fragrance startups. Three strategic archetypes dominate: botanical-positioned natural brands, veterinary-channel premium formulators, and velocity-driven direct-to-consumer operators. M&A activity concentrates on acquiring subscription platform capabilities, while capacity expansion focuses on micro-encapsulation manufacturing for controlled-release delivery systems.
Among North American botanical specialists, TropiClean Pet Products exemplifies supply chain investment in sustainable sourcing, while Pawfume occupies a position within the direct-to-consumer velocity tier. Isle of Dogs represents the veterinary-channel premium archetype through professional salon distribution. These three anchors illustrate how geographic origin and channel focus stratify competitive positioning without requiring uniform capital intensity.
| Leading Market Players |
|---|
| TropiClean Pet Products |
| Pawfume |
| Earthbath |
| Bodhi Dog |
| Pet Head |
| Isle of Dogs |
| Captain Zack |
| Odo-Rite |
| Petveda |
| Others |
Value Network & Pricing Analysis
Urban millennial and Gen Z dog owners concentrated in United States metropolitan markets anchor demand for subscription-priced fragrance replenishment, locking brands into recurring revenue models that stabilize unit economics against volatile raw material costs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the dog perfume market. Price differentiation hinges on certification grade for EU REACH compliance and brand premium tied to veterinary endorsement. Cost compression in the natural ingredients tier is intensifying because climate-driven supply disruptions in lavender and chamomile growing regions have tightened botanical availability. Mass-market supermarket buyers exhibit the highest price sensitivity, while veterinary clinic procurement demonstrates the lowest due to professional endorsement requirements.
Supply Chain Analysis
Dual-sourcing mandates from European fragrance houses require simultaneous qualification of botanical suppliers across France, Bulgaria, and Morocco to mitigate climate-driven harvest volatility. Raw material procurement draws from steam-distilled essential oils, pH-balanced aqueous carriers, and biodegradable suspension agents. Single-source vulnerability concentrates in Provence lavender harvests exposed to drought frequency. Distribution runs through specialty pet retail chains in metropolitan France and Germany, direct-to-consumer platforms in United States urban corridors, and veterinary clinic networks in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dog perfume market functions as a stable compounder underpinned by pet humanization trends that compress purchase cycles for premium grooming accessories across successive owner generations.
For Market Incumbents: Hedge against essential oil input volatility by securing backward integration into lavender and chamomile cultivation in Bulgaria and Morocco. Preempt FDA cosmetic claims scrutiny by investing in species-specific pH chemistry R&D that generates proprietary formulation data. Channel control through veterinary clinic exclusivity agreements protects margin against direct-to-consumer entrants. For New Entrants and Emerging Players: Capture white-space in alcohol-free solid perfume formats for Japanese metropolitan apartment dwellers under METI chemical substance frameworks. The most penetrable segment lies in subscription commerce for urban United States dog owners unbundling grooming from home fragrance rituals. Go-to-market execution should leverage aromatherapy cross-marketing from human wellness retail shelf placement. For Investors and Strategic Acquirers: Pet care conglomerates with existing grooming portfolios are the most active acquirers in this space, seeking subscription platform capabilities and REACH-compliant formulation assets. Long-term viability rests on clean-label convergence tailwinds migrating from human cosmetics. Target acquisition archetypes include digitally native fragrance startups with automated replenishment algorithms. The signal to watch is California Proposition 65 enforcement intensity as a proxy for compliance cost escalation across West Coast distribution.| Strategic Initiative | Industry Significance |
|---|---|
| Botanical Supply Chain Integration | Backward control over lavender cultivation in Bulgaria hedges climate-driven margin compression. |
| REACH-Compliant Formulation Certification | ECHA-aligned R&D preempts regulatory rejection and unlocks European veterinary channel access. |
| Subscription Platform Deployment | Automated replenishment algorithms lock urban United States owners into recurring revenue streams. |
| Veterinary Dermatology Partnership | Collaboration with skin-sensitive research opens prescription-adjacent distribution in Germany. |
| Micro-Encapsulation Manufacturing Scale-Up | Controlled-release technology justifies service premiums in Paris and Milan boutique salons. |
Research Methodology
Bottom-up pet owner demand modeling reconciled against top-down fragrance compound supply tracking forms the analytical core of this study. Primary interviews with formulation chemists, veterinary dermatologists, specialty pet retail category managers, and direct-to-consumer brand operators were cross-validated against secondary sources including FDA Center for Veterinary Medicine guidance documents, ECHA substance evaluation databases, EPA volatile organic compound emission standards, and customs trade data for essential oil imports. Triangulation between consumption-side sampling programs and production-side SKU proliferation patterns ensures segment-level precision.
Input-output matrices map fragrance formulation inputs across product type, ingredient source, packaging format, and distribution channel dimensions over the projection horizon. CAGRs were derived from modeled adoption curves for subscription commerce infrastructure and regulatory-driven reformulation cycles. Industry-specific forecast inputs include climate volatility indices for lavender growing regions and metropolitan pet ownership density metrics.
Underlying measurement precision varies by segment; synthetic fragrance formulations carry tighter precision than natural ingredient alternatives due to standardized laboratory production. Forecasts reflect documented assumptions regarding REACH sunset date adherence and EPA emission cap enforcement trajectories. Deviation in California Proposition 65 litigation frequency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Pet Perfume Market
Pet Care Products
Pet Stairs Market
Pet Care Products
UTI Cat Food Market
Pet Care Products
Pet Grooming Products Market
Pet Care Products
Cat Litter Product Market
Pet Care Products
Vegan Dog Food Market
Pet Care Products
Pet Dental Health Market
Pet Care Products
Smart Cat Eye Market
Pet Care Products
Global Pet Companion Robots Market
Pet Care Products
South Korea Organic and Natural Pet Food Market
Pet Care Products
South America Pet Food Market
Pet Care Products
Thunder Jacket for Dogs Market
Pet Care Products
High Fiber Dog Food Market
Pet Care Products
Modern Cat Furniture Market
Pet Care Products
Pet Bathing Supplies Market
Pet Care Products
Poland Pet Food Market