
 Mexico Plastic Caps and Closures Market | 2026-2036
Mexico Plastic Caps and Closures Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Plastic Caps and Closures Market Foresight
Direct-to-brewery supply contracts are reshaping how closure vendors secure volume commitments in Mexico's beverage heartland. Silgan Holdings Inc. leverages its multi-plant footprint to sustain just-in-time delivery across central Mexico. Amcor anchors premium dispensing formats for personal care brands in Querétaro. BERICAP North America Inc. specializes in tamper-evident designs that dominate pharmaceutical and food safety applications.
Plastic caps and closures are injection-molded or compression-molded thermoplastic components, typically threaded or snap-fit, that seal containers against contamination, leakage, and oxidation while enabling controlled dispensing or reclosure. Screw caps occupy the largest volume share due to universal compatibility with carbonated and still beverages across Mexico's bottling infrastructure. Polypropylene leads material demand for hot-fill and retort applications, while polyethylene sustains cost-sensitive water and dairy segments where thread integrity requirements are moderate.
PROFEPA enforces extended producer responsibility frameworks that compel converters to certify recyclability pathways, while NOM-252-SSA1-2011 governs food-contact polymer safety and migration limits. COFEPRIS pharmaceutical packaging regulations mandate child-resistant and senior-friendly closure performance for OTC and prescription products. Stakeholders must monitor how pending state-level waste segregation mandates in Mexico City and Guanajuato will alter collection economics and resin qualification criteria for closure producers.
Market Dynamics
PROFEPA's extended producer responsibility framework is redirecting converter capital toward mono-material recyclable designs, compressing PVC demand while elevating polypropylene and polyethylene qualification requirements across Mexico's beverage and pharmaceutical bottling corridors.
Growth Catalysts
- Tamper-evident mandate expansion:COFEPRIS pharmaceutical packaging regulations now require child-resistant and senior-friendly closure performance for OTC products, pulling specialized dispensing formats into Jalisco and Nuevo León production clusters.
- Automotive chemical packaging localization:Bajío industrial corridor manufacturers are sourcing specialized closure formats for antifreeze and brake fluid containers domestically rather than importing from US Gulf Coast suppliers.
- Hot-fill polypropylene adoption:Retort-compatible grades are capturing sauce and prepared meal segments as Mexican food processors upgrade bottling lines for export-ready shelf-stable formats.
Market Restraints
- Resin price volatility:Polypropylene feedstock costs track propylene monomer swings tied to Pemex refinery output fluctuations, compressing converter margins on fixed-price beverage contracts.
- Import dependency for high-performance grades:Specialty polyethylene for pharmaceutical induction seals concentrates among US Gulf Coast resin producers, exposing Mexican molders to cross-border logistics friction.
- Mechanical recycling contamination limits:NOM-252-SSA1-2011 migration thresholds for food-contact polymers restrict post-consumer resin incorporation rates below technical feasibility levels.
Strategic Opportunities
- Guanajuato state waste segregation mandates:Pending collection infrastructure investments will create closed-loop supply chains for post-industrial polypropylene regrind, lowering virgin resin exposure for Querétaro molders.
- Dispensing closure premiumization:Personal care brands in Mexico City are specifying flip-top and pump formats previously imported from Europe, creating domestic mold qualification opportunities.
- Mono-material flexible-to-rigid conversion:PROFEPA circular economy guidelines are hybridizing pouch and bottle formats, enabling all-polyethylene closure-body systems that simplify mechanical recycling streams.
Industry Challenges
- Mold flow simulation expertise scarcity:Compression molding optimization for thin-wall beverage closures requires specialized CAE talent concentrated among Guadalajara engineering consultancies.
- Multi-site COFEPRIS certification timelines:Pharmaceutical closure producers face synchronized audit windows across Jalisco and Estado de México facilities, stretching quality assurance bandwidth.
- Legacy PVC line conversion costs:Retooling existing injection cells for polypropylene processing demands screw and barrel replacements that strain mid-cap converter balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Plastic Caps and Closures Market |
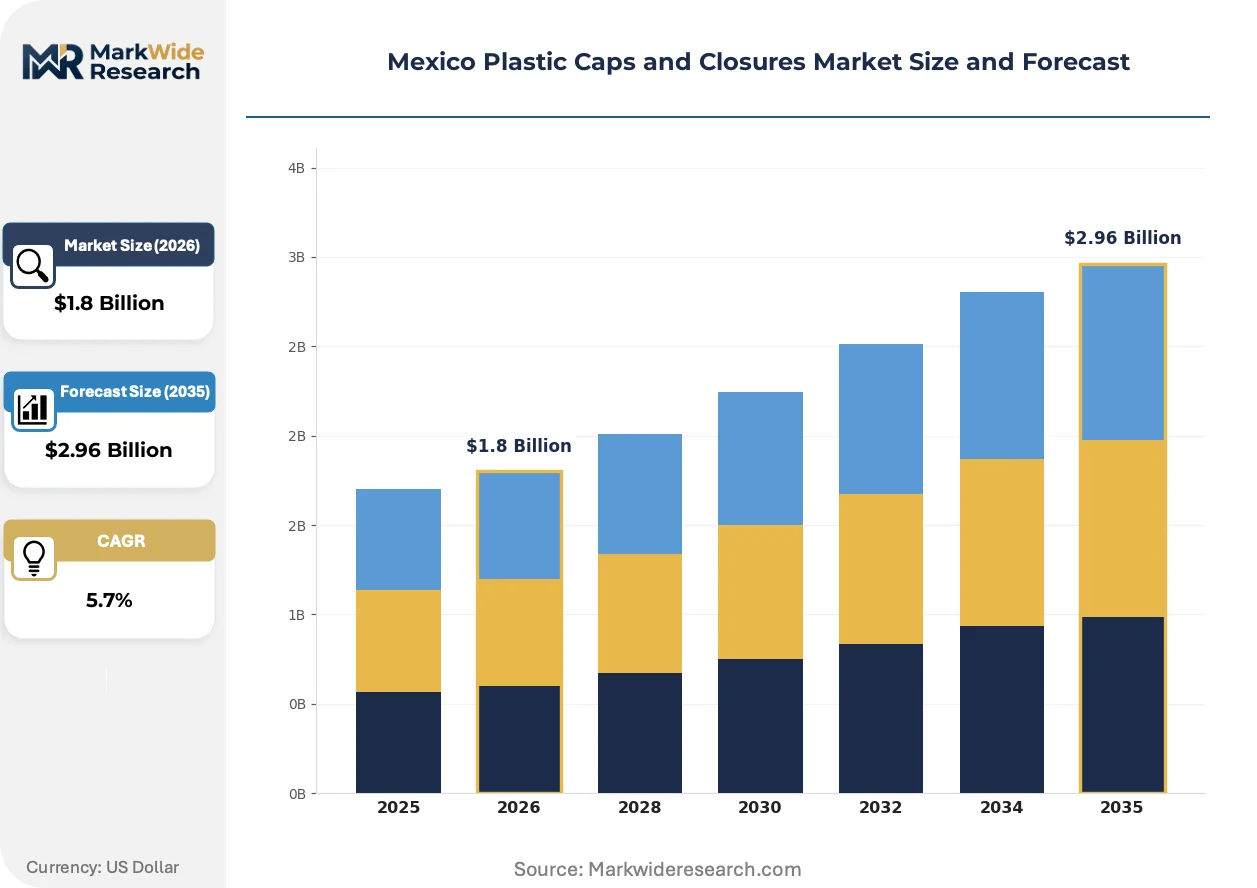
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Screw Caps, Snap-on Caps, Dispensing Caps, Tamper-evident Caps Material: Polyethylene, Polypropylene, PVC, PET Application: Beverages, Personal Care, Pharmaceuticals, Household Products End User: Food & Beverage, Cosmetic Manufacturers, Pharmaceutical Companies, Household Goods |
| Companies Covered | Silgan Holdings Inc., Amcor, Berry Global, Albéa Reynosa, BERICAP North America Inc., Guala Closures Mexico, AptarGroup, Closure Systems International, ALPLA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Plastic Caps and Closures Market Shifts & Advancements
Closure design in Mexico is converging around three vectors: material simplification for recyclability, regulatory compliance for pharmaceutical safety, and dispensing functionality for premium personal care positioning.
Mono-material polyethylene closures are hybridizing traditional screw-cap function with integrated tamper-evident bands, eliminating multi-component assembly. Beverage bottlers in Jalisco are adopting these designs at line-speed parity with legacy formats. The technology is compressing post-consumer sorting complexity while maintaining carbonation retention performance.
PROFEPA's circular economy certification pathway now mandates recyclability documentation for all food-contact packaging placed on the Mexican market. Industrial consequence: converters must qualify resin grades through approved mechanical recycling streams before volume procurement. Pharmaceutical and dairy segments are responding fastest, locking in polypropylene homopolymer specifications that dominate European sorting infrastructure.
Direct contracting between CPG brands and specialized molders is displacing distributor-mediated procurement in Querétaro and Nuevo León. Large beverage and household chemical buyers are consolidating supplier panels to capture design-to-delivery accountability. The pattern is most visible in automotive chemical clusters, where just-in-time delivery requirements favor geographically proximate molding operations over legacy import channels.
Mexico Plastic Caps and Closures Market Segmentation
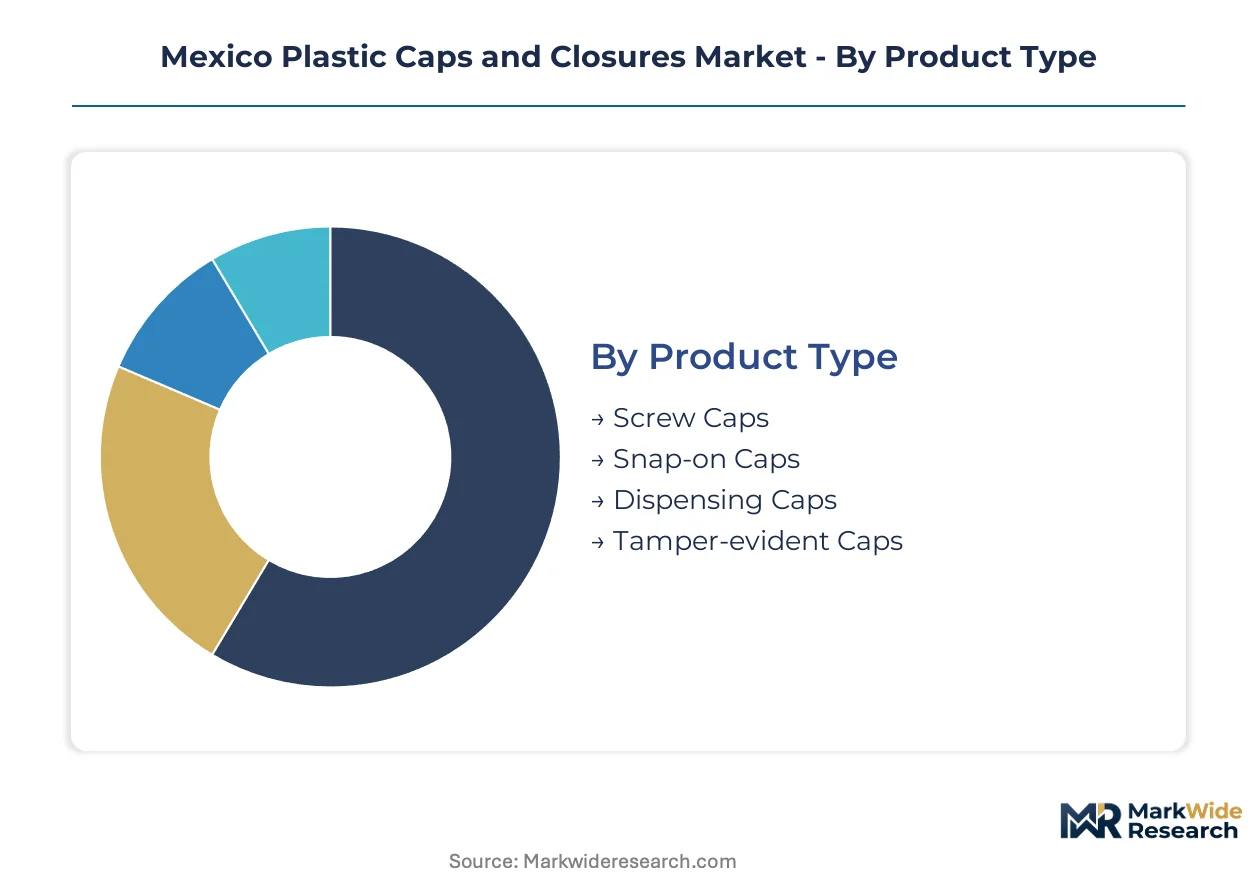
Closure specification in Mexico diverges sharply across end-use channels, with beverage bottlers prioritizing line-speed compatibility while pharmaceutical and personal care buyers demand certified tamper-evidence and dispensing precision. Converter tooling investments must align to these divergent performance tiers rather than pursuing universal platforms.
Product Type:
After-sales service intensity varies dramatically across closure formats, with dispensing and tamper-evident designs requiring mold maintenance partnerships and technical support that screw and snap formats rarely demand.
- Screw Caps:Threaded thermoplastic closures with standardized 28mm and 38mm neck finishes dominate carbonated and still beverage bottling across Jalisco and Nuevo León. Bajío automotive chemical clusters are pulling specialized vented screw formats for antifreeze containers as domestic sourcing replaces US Gulf Coast imports.
- Dispensing Caps:Flip-top, disc-top, and pump-integrated designs enable controlled product release for personal care and household chemical applications. Querétaro cosmetic manufacturers are qualifying domestic molders for premium dispensing formats previously imported from European suppliers, compressing lead times and customs exposure.
- Snap-on Caps:Press-fit closures with integral sealing rings serve cost-sensitive water and dairy segments where thread integrity requirements are moderate and reclosure frequency is low.
- Tamper-evident Caps:Break-band or shrink-sleeve integrated designs provide visual integrity assurance for pharmaceutical and food safety applications under COFEPRIS regulations.
By volume, Screw Caps leads. By growth pace, Dispensing Caps is ahead.
Material:
Resin selection in Mexico tracks thermal performance requirements and PROFEPA recyclability mandates, with converters requalifying grades to maintain food-contact certifications under NOM-252-SSA1-2011.
- Polypropylene:Homopolymer and random copolymer grades deliver hot-fill and retort compatibility for sauce and prepared meal processors upgrading export-ready bottling lines. PROFEPA circular economy guidelines are accelerating homopolymer specification to align with European mechanical recycling infrastructure.
- Polyethylene:HDPE and LDPE grades sustain cost-sensitive water, dairy, and household chemical segments where moderate thread strength suffices. Mono-material all-PE closure-body systems are emerging under PROFEPA pressure to simplify post-consumer sorting streams.
- PVC:Legacy material for certain pharmaceutical and chemical resistance applications, now contracting as converters retool injection cells to avoid extended producer responsibility penalties.
- PET:Specialty applications in pharmaceutical blister lidding and high-clarity cosmetic packaging where resin transparency and barrier performance are specified.
Polypropylene captures the largest volume position. Polyethylene is expanding most quickly as beverage bottlers adopt mono-material designs.
Application:
Application-level demand in Mexico concentrates where CPG brands are localizing supply chains and direct-contracting specialized molders for design-to-delivery accountability.
- Beverages:Carbonated soft drinks, bottled water, juices, and ready-to-drink beverages drive the highest closure consumption volumes, with Jalisco bottlers expanding tamper-evident procurement under retailer food safety mandates.
- Pharmaceuticals:OTC and prescription packaging demands child-resistant and senior-friendly closure performance under COFEPRIS regulations, pulling specialized dispensing formats into Estado de México production clusters.
- Personal Care:Shampoo, conditioner, lotion, and cosmetic applications specify premium dispensing formats, with Mexico City brands driving domestic mold qualification for flip-top and pump designs.
- Household Products:Cleaners, disinfectants, and automotive chemicals require chemical-resistant closures, with Bajío manufacturers sourcing specialized formats domestically rather than importing.
Beverages dominates absolute volume. Pharmaceuticals shows the steepest expansion trajectory as regulatory compliance tightens.
End User:
End-user procurement patterns in Mexico are consolidating around geographically proximate molding operations capable of just-in-time delivery and synchronized quality audits.
- Food & Beverage:Integrated bottlers and co-packers across Jalisco, Nuevo León, and the Bajío corridor specify closures at line-speed parity requirements, favoring multi-plant vendors with central Mexico distribution networks.
- Pharmaceutical Companies:Domestic and multinational drug manufacturers demand COFEPRIS-certified closure performance with documented child-resistance testing, concentrating supplier panels among audited Jalisco and Estado de México molders.
- Cosmetic Manufacturers:Querétaro and Mexico City personal care brands are displacing European imports with domestically qualified dispensing closures, capturing premium positioning through localized supply chains.
- Household Goods:Automotive chemical and cleaning product packagers in Guanajuato prioritize chemical compatibility and venting specifications for aggressive formulations.
Food & Beverage leads by volume. Pharmaceutical Companies is gaining share fastest as safety regulations harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Manzanillo anchors Pacific logistics for resin imports serving Mexico's closure molding corridor, while the Ferromex rail network distributes polypropylene feedstock to central Mexico's industrial belt.
Nuevo León
Automotive chemical packagers in Monterrey are sourcing vented screw closures domestically for antifreeze and brake fluid containers. PROFEPA's extended producer responsibility framework is accelerating PVC line conversions toward polypropylene homopolymer specifications. The Apodaca industrial park hosts molders qualifying just-in-time delivery contracts with Bajío-bound automotive suppliers.
Jalisco
Beverage bottlers in Guadalajara are expanding tamper-evident closure procurement under retailer food safety mandates. COFEPRIS pharmaceutical regulations pull child-resistant dispensing formats into local production clusters for OTC packaging. The El Salto corridor concentrates compression molding operations optimized for thin-wall carbonated beverage closures at line-speed parity.
Bajío Region
Querétaro cosmetic manufacturers are displacing European imports with domestically qualified flip-top and pump dispensing closures. Pending Guanajuato state waste segregation mandates will create closed-loop supply chains for post-industrial polypropylene regrind. Silao's automotive assembly ecosystem is pulling specialized chemical-resistant closure formats for captive parts cleaning and maintenance fluids.
Mexico City Metro
Personal care brands in Tlalnepantla are specifying premium dispensing formats previously imported from European suppliers. NOM-252-SSA1-2011 food-contact polymer safety standards restrict post-consumer resin incorporation rates for dairy and prepared meal segments. The Cuautitlán Izcalli corridor anchors household chemical packaging demand for cleaners and disinfectants requiring chemical-resistant vented designs.
Northern Border States
Maquiladora operations in Tijuana and Ciudad Juárez are cross-dosing pharmaceutical closures for US FDA-regulated export markets. Pemex refinery output fluctuations in the region expose molders to propylene monomer price volatility on fixed-price beverage contracts. The Reynosa industrial cluster concentrates induction seal specialists serving US Gulf Coast pharmaceutical resin qualification requirements.
Mexico Plastic Caps and Closures Market Competitive Landscape
On the supply side, the industry is consolidating around multi-plant operators capable of synchronized COFEPRIS certification across Jalisco and Estado de México facilities. Tier-one vendors anchor premium dispensing and tamper-evident segments, while mid-cap specialists capture automotive chemical and cost-sensitive water categories. Dominant competitive moves include geographic proximity-based supplier panel consolidation by large CPG brands and mold qualification partnerships for previously imported European formats.
Within the premium dispensing tier, AptarGroup and Albéa Reynosa exemplify archetypes positioned for personal care premiumization trends in Querétaro and Mexico City. Silgan Holdings Inc. represents the multi-plant footprint model sustaining just-in-time delivery networks across central Mexico. BERICAP North America Inc. anchors the specialized tamper-evident segment serving pharmaceutical and food safety applications under COFEPRIS mandates.
| Leading Market Players |
|---|
| Silgan Holdings Inc. |
| Amcor |
| Berry Global |
| Albéa Reynosa |
| BERICAP North America Inc. |
| Guala Closures Mexico |
| AptarGroup |
| Closure Systems International |
| ALPLA |
| Others |
Supply & Pricing Matrix
Bajío industrial corridor capacity expansions in Querétaro and Guanajuato are compressing pricing power for Jalisco-based molders serving beverage bottlers with fixed-volume contracts. Pemex propylene monomer volatility feeds directly into polypropylene resin cost structures, forcing converters to absorb margin erosion or renegotiate annual supply agreements with CPG procurement teams.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates Mexican closure procurement. Premium tiers command spreads for COFEPRIS-certified pharmaceutical dispensing formats and hot-fill polypropylene homopolymer grades. Standard tiers capture carbonated beverage screw caps with line-speed parity specifications. Economy tiers serve cost-sensitive water and dairy segments using snap-fit polyethylene designs. Price differentiation hinges on certification grade and volume scale, with automotive chemical buyers showing lowest sensitivity due to just-in-time delivery premiums. Cost compression in standard beverage tiers is intensifying because fixed-price contracts expose molders to propylene feedstock swings.
Supply Chain Analysis
US export-control restrictions on advanced compression molding simulation software limit Mexican converter access to thin-wall optimization tools concentrated among Guadalajara engineering consultancies. Geographic supply concentration centers on US Gulf Coast specialty polyethylene producers for pharmaceutical induction seals, domestic Pemex-derived polypropylene for beverage applications, and Asian resin traders for cost-sensitive household chemical grades. Raw material dependencies rest on propylene monomer, calcium carbonate fillers, and color masterbatch concentrates. Single-source vulnerability runs through Pemex refinery output fluctuations. Distribution runs through Ferromex rail networks linking Port of Manzanillo to central Mexico's industrial belt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's plastic caps and closures market is entering a cyclical recovery phase as PROFEPA's extended producer responsibility deadlines force converter capital expenditure cycles. Automotive chemical packaging localization in the Bajío corridor provides the demand floor for this recovery.
For Market Incumbents: Entrench multi-plant COFEPRIS certification across Jalisco and Estado de México facilities before synchronized audit windows compress quality assurance bandwidth. Capture backward integration into post-industrial polypropylene regrind operations in Guanajuato as state waste segregation mandates create closed-loop supply chains. Defensive priority: lock in direct-to-brewery supply contracts before distributor-mediated procurement channels reassert.
For New Entrants and Emerging Players: Pursue domestic mold qualification for premium dispensing formats previously imported from European suppliers, targeting Querétaro cosmetic manufacturers and Mexico City personal care brands. White-space concentration sits in flip-top and pump designs where lead time compression commands procurement attention. Go-to-market angle: partner with Guadalajara engineering consultancies for CAE talent access rather than building in-house simulation capability.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because direct contracting trends favor geographically proximate molding operations with synchronized quality audit capacity. Acquisition target archetype: mid-cap converters with existing COFEPRIS certification and compression molding expertise for thin-wall beverage closures. Signal to watch: Pemex propylene pricing volatility triggering distressed asset opportunities among fixed-price contract holders.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Regrind Operations | Guanajuato state mandates create captive supply of post-industrial polypropylene for Querétaro molders. |
| COFEPRIS Certification Expansion | Multi-site pharmaceutical closure producers secure synchronized audit capacity across Jalisco and Estado de México. |
| Domestic Mold Qualification Partnership | European-import displacement captures premium dispensing format demand from Mexico City personal care brands. |
| Direct-to-Brewery Contract Consolidation | Jalisco and Nuevo León beverage bottlers lock in design-to-delivery accountability with closure vendors. |
| Compression Molding CAE Talent Acquisition | Thin-wall beverage closure optimization requires specialized simulation expertise concentrated in Guadalajara consultancies. |
Research Methodology
Desk research of customs trade data, PROFEPA circular economy guidelines, and NOM-252-SSA1-2011 regulatory filings preceded structured interviews with procurement directors at beverage bottlers, quality assurance managers at pharmaceutical packagers, plant engineers at automotive chemical manufacturers, and resin sourcing leads at converter operations. Secondary validation drew from COFEPRIS certification databases, Ferromex rail freight disclosures, and Pemex petrochemical output reports. Bottom-up closure demand modeling triangulated against top-down CPG packaging expenditure estimates.
Assumptions held fixed include PROFEPA extended producer responsibility enforcement timelines, Pemex refinery operating rates, and COFEPRIS audit synchronization patterns across the analysis window. Variables included propylene monomer price volatility bands, Guanajuato waste segregation mandate implementation pacing, and European dispensing format import displacement rates. Segmentation dimensions encompassed product type, material grade, application channel, and end-user procurement pattern. CAGRs derived from regression against historical resin consumption and bottling line investment cycles, with cross-reference to automotive assembly output in Silao and prepared meal export growth.
Sensitivities concentrate around Pemex operational disruptions, US Gulf Coast resin export restrictions, and state-level waste collection infrastructure delays. Forecasts reflect assumptions about regulatory enforcement consistency and CPG localization commitment durability. Cross-checking against Mexican Association of Packaging Industry (AMEE) production surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Metal Closures Market
Caps and Closures
Crimp-On Spouts Market
Caps and Closures
Ribbed Phenolic Caps Market
Caps and Closures
Laminated Tube Closure Market
Caps and Closures
Plastic Sifter Caps Market
Caps and Closures
Ribbed Closures Market
Caps and Closures
Morocco Plastic Caps and Closures Market
Caps and Closures
Handheld Induction Cap Sealers Market
Caps and Closures
Brush and Dauber Caps Market
Caps and Closures
US Caps and Closure Market
Caps and Closures
Spouted Dispensing Closures Market
Caps and Closures
Peelable Lid Stock Market
Caps and Closures
Flat Valve Caps and Closures Market
Caps and Closures
Flip Top Caps and Closures Market
Caps and Closures
Gable Top Cap and Closures Market
Caps and Closures
Crown Caps Market