
 Protective Fluid Market | 2026-2036
Protective Fluid Market Size, Share, and Industry Trends Forecast 2026-2036
Protective Fluid Market Analytics
High-performance synthetic grade formulations is redrawing competitive boundaries across the protective fluid landscape. ExxonMobil leverages its upstream petrochemical integration to secure base stock supply chains for advanced lubricant series. Shell anchors its position through marine sector partnerships spanning North Sea and Gulf of Mexico operations. 3M differentiates via fluoropolymer additive technology that extends service intervals in aerospace hydraulic circuits.
Protective fluids are chemically engineered liquid preparations formulated with base oils, synthetic esters, or aqueous solutions combined with corrosion inhibitors, extreme-pressure additives, and viscosity modifiers, manufactured through controlled blending and filtration processes to achieve precise kinematic viscosity and pour point specifications. Their primary commercial purpose is to form boundary films that reduce friction, dissipate thermal loads, and prevent oxidative degradation across mechanical systems operating under sustained stress. Hydraulic fluids command the largest volume pool within product type segmentation due to entrenched infrastructure across heavy machinery fleets, while specialty grade formulations capture disproportionate margin concentration driven by military and food-contact certification requirements. Metalworking application demand is accelerating fastest as precision manufacturing tolerances tighten and coolant recycling regulations proliferate.
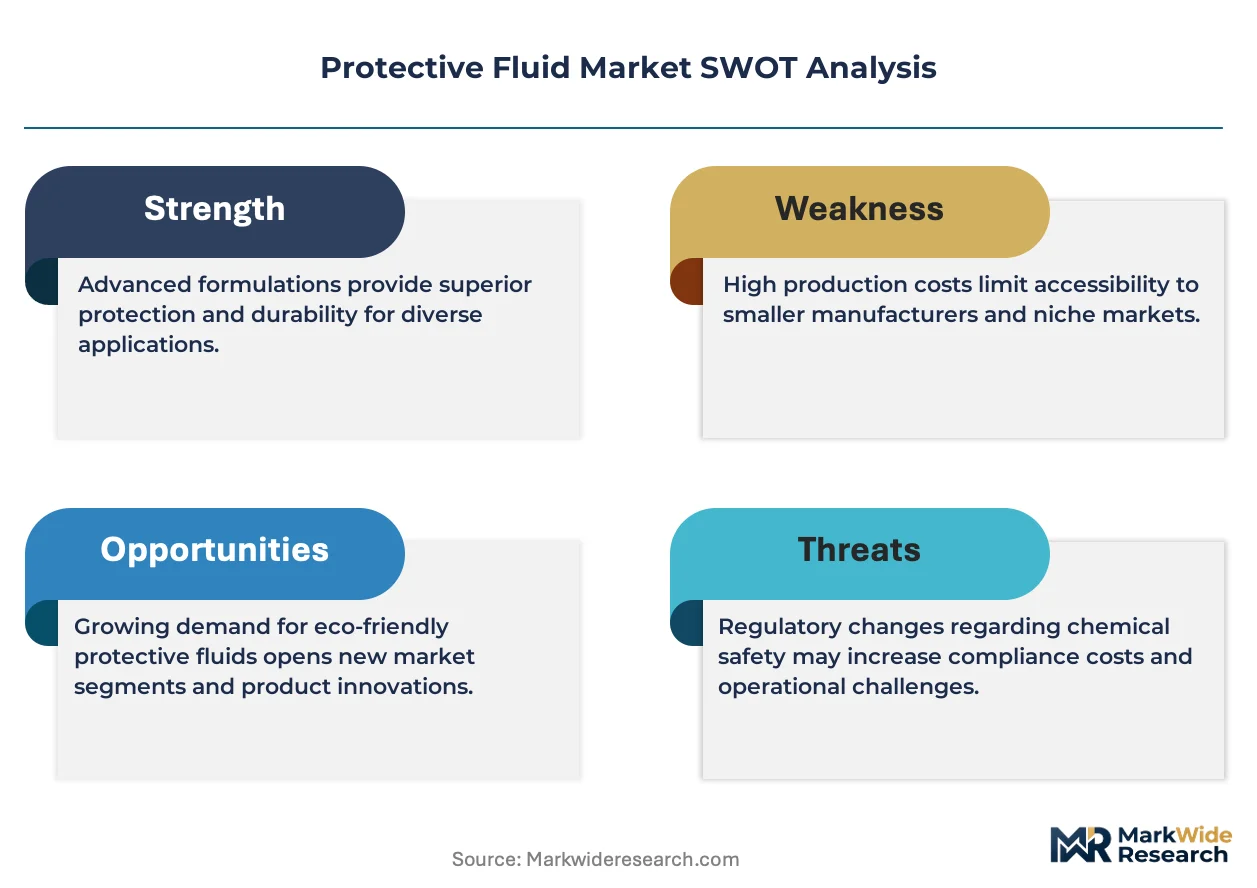
EPA registration requirements under FIFRA govern antimicrobial and corrosion-preventive claims for metalworking fluids sold in the United States, while REACH dossier compliance in Europe mandates full substance disclosure across additive packages. FDA food-contact notification rules constrain lubricant composition for packaging and processing equipment, creating dual-certification premiums for food grade suppliers. Military-grade specifications under MIL-PRF standards further fragment procurement channels through qualified products list requirements. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across multiple jurisdictions, as these chemistries underpin high-performance segments and their phase-out timelines will force reformulation investments and supplier qualification resets.
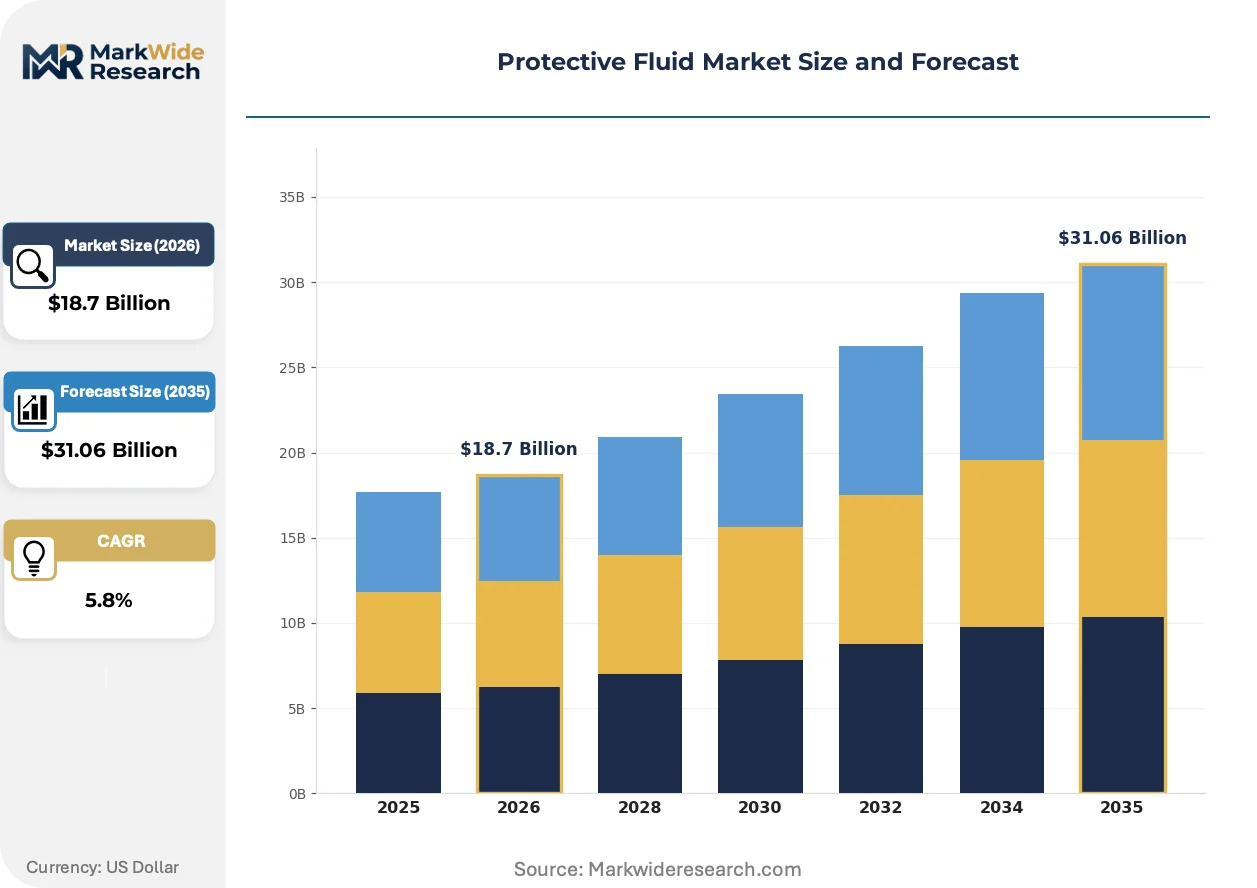
Market Dynamics
REACH and EU Green Deal compliance requirements are forcing wholesale reformulation of additive packages across the protective fluid value chain, compressing legacy chemistries while elevating bio-based esters and synthetic alternatives in procurement specifications.
Growth Catalysts
- MIL-PRF Qualified Products List expansion:Aerospace maintenance programs in Germany and the United States are mandating military-grade hydraulic formulations for next-generation fleet upgrades, tightening supplier qualification standards.
- Metalworking coolant recycling mandates:EPA FIFRA registration requirements for antimicrobial claims are accelerating closed-loop system investments across precision manufacturing facilities in Ohio and Michigan.
- Fluoropolymer additive performance gaps:3M's proprietary chemistry is extending service intervals in aerospace hydraulic circuits, creating specification lock-in for high-performance segments.
Market Restraints
- Base stock supply concentration:ExxonMobil's upstream petrochemical integration controls critical synthetic ester feedstocks, creating bottleneck risk for mid-tier blenders without backward integration.
- PFAS phase-out timelines:ECHA restriction proposals under REACH are targeting per- and polyfluoroalkyl substances that underpin extreme-pressure additive performance, forcing premature R&D redirection.
- Food-contact dual-certification cost:FDA notification rules combined with NSF H1 standards impose compositional constraints that add 15-25% to formulation development budgets for packaging equipment suppliers.
Strategic Opportunities
- India PLI scheme manufacturing incentives:Production-linked incentive schemes for precision engineering are drawing metalworking fluid suppliers to Gujarat and Tamil Nadu industrial corridors.
- Marine sector service bundling:Shell's North Sea and Gulf of Mexico partnerships demonstrate how fluid supply can integrate with vessel maintenance contracts, capturing lifecycle value.
- Bio-based ester technology convergence:Synthetic base stocks combined with plant-derived viscosity modifiers are opening military specification pathways previously closed to renewable chemistries.
Industry Challenges
- Additive package chemist scarcity:Formulation expertise combining tribology, oxidation stability, and regulatory compliance resides with a shrinking cohort of specialists near Leverkusen and Houston.
- REACH dossier substance disclosure:Full additive composition transparency requirements are exposing proprietary formulations to competitive reverse-engineering, compressing intellectual property protection windows.
- Legacy system compatibility testing:New synthetic grades require extensive seal material validation against incumbent mineral oil infrastructures, extending qualification cycles for industrial hydraulic retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Protective Fluid Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Fluids, Lubricants, Coolants, Release Agents End User: Aerospace, Automotive Manufacturing, Marine Industry, Heavy Machinery Application: Engine Components, Hydraulic Systems, Metalworking, Corrosion Prevention Grade: Industrial Grade, Food Grade, Military Grade, Specialty Grade |
| Companies Covered | Angus, Dukare, Branopac, 3M, Polyanswer, Noble Company, ExxonMobil, Shell, TotalEnergies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Protective Fluid Market Evolving Landscape
Bio-based synthetic esters are displacing Group III mineral oils in high-temperature hydraulic applications, while digital fluid condition monitoring and perfluorinated chemistry restrictions are simultaneously reshaping product development roadmaps and service delivery models.
Polyalkylene glycol (PAG) water-glycol blends are decomposing the traditional mineral oil dominance in fire-resistant hydraulic fluids. Steel mills and aluminum smelters in Germany's industrial corridor are specifying these formulations for furnace proximity operations. The technology is decomposing incumbent market positions by enabling higher operating temperatures without compromising seal compatibility.
EU F-Gas Regulation amendments are accelerating hydrofluorocarbon phase-down timelines that indirectly pressure fluorinated lubricant chemistries. Industrial fluid suppliers are reformulating extreme-pressure additives around sulfur-phosphorus and borate ester alternatives. Metalworking applications in Cologne-Leverkusen manufacturing clusters are experiencing the most acute substitution pressure due to concentrated regulatory enforcement.
Condition-based monitoring contracts are displacing scheduled fluid replacement programs among heavy machinery fleet operators. Caterpillar and Komatsu dealers are bundling sensor hardware with fluid supply agreements, capturing aftermarket value previously held by independent distributors. This pattern is most visible in German construction equipment markets where telematics penetration exceeds North American benchmarks.
Protective Fluid Market Segmentation
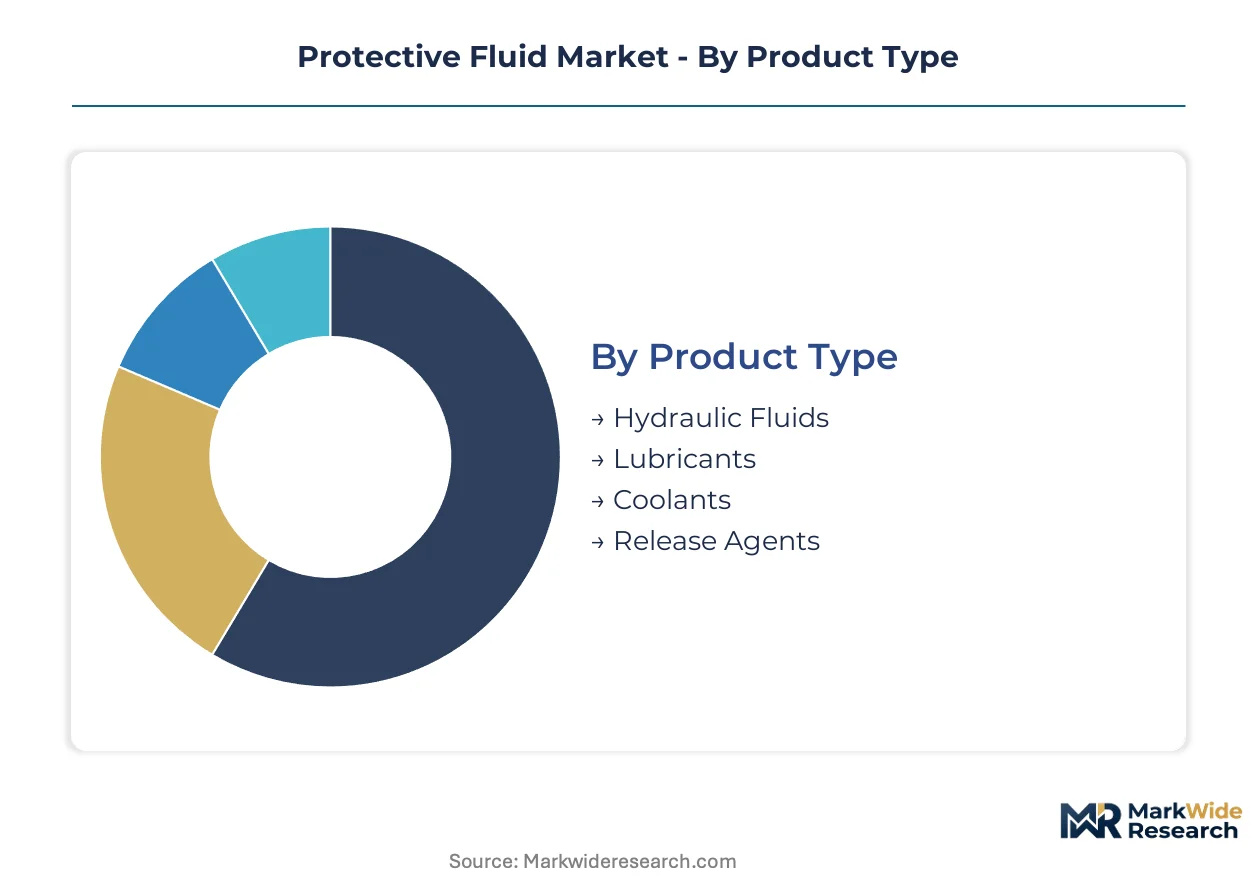
Segmentation in protective fluids reveals how formulation chemistry, certification requirements, and end-use stress conditions create distinct profit pools. Procurement specifications diverge sharply between commodity industrial volumes and premium certified grades where regulatory compliance commands price premiums.
Product Type:
Hydraulic fluids face intensifying substitution pressure from polyalkylene glycol water-glycol blends in furnace-proximity applications, while lubricant segments confront bio-based synthetic ester displacement in high-temperature machinery fleets.
- Hydraulic Fluids:Formulated with mineral oil, synthetic ester, or water-glycol bases to transmit power in enclosed systems under pressures exceeding 3,000 psi. Demand concentrates in German steel mills and aluminum smelters specifying fire-resistant PAG alternatives for furnace operations, driven by EU F-Gas Regulation pressure on fluorinated chemistries.
- Lubricants:Boundary-film forming oils and greases combining base stocks with extreme-pressure additives to reduce friction in bearings and gearboxes. Automotive manufacturing corridors in Stuttgart and Wolfsburg are mandating extended-drain synthetic grades to align with EU Green Deal carbon intensity targets.
- Coolants:Aqueous solutions with corrosion inhibitors and biocides for heat removal in machining operations.
- Release Agents:Surface-active formulations preventing adhesion between molds and cast parts in metal and polymer processing.
Hydraulic fluids retain volume leadership; lubricants hold the steepest expansion curve.
End User:
Cost tier stratification separates aerospace and marine buyers willing to pay certification premiums from automotive and heavy machinery purchasers optimizing total fluid lifecycle cost.
- Aerospace:MIL-PRF qualified hydraulic formulations for flight control systems and landing gear actuators. German and United States maintenance programs are mandating military-grade specifications for next-generation fleet upgrades, tightening supplier qualification standards through qualified products list requirements.
- Automotive Manufacturing:Precision metalworking coolants and stamping lubricants for powertrain and body-in-white production. EPA FIFRA registration requirements for antimicrobial claims are accelerating closed-loop coolant recycling investments across Ohio and Michigan stamping facilities.
- Marine Industry:Vessel hydraulic systems and stern tube lubricants operating in saltwater environments.
- Heavy Machinery:Construction and mining equipment fluids subject to contamination and extreme duty cycles.
Aerospace commands the highest per-liter margins; automotive manufacturing delivers the largest absolute volume.
Application:
Application segmentation tracks how thermal load intensity and precision tolerance requirements dictate additive package complexity and service interval economics.
- Engine Components:Crankcase lubricants and coolant formulations managing combustion chamber proximity temperatures. Precision manufacturing tolerances in German powertrain plants are tightening coolant recycling regulations, accelerating demand for bio-stable formulations with extended sump life.
- Hydraulic Systems:Power transmission fluids for actuators and presses requiring oxidation stability and wear protection. REACH dossier substance disclosure mandates are exposing proprietary additive formulations to competitive reverse-engineering, compressing intellectual property protection for hydraulic fluid suppliers near Leverkusen.
- Metalworking:Cutting and grinding fluids for chip removal and surface finish control.
- Corrosion Prevention:Protective coatings and volatile corrosion inhibitors for storage and transit protection.
Hydraulic systems anchor procurement volume; metalworking is climbing fastest on precision manufacturing investment.
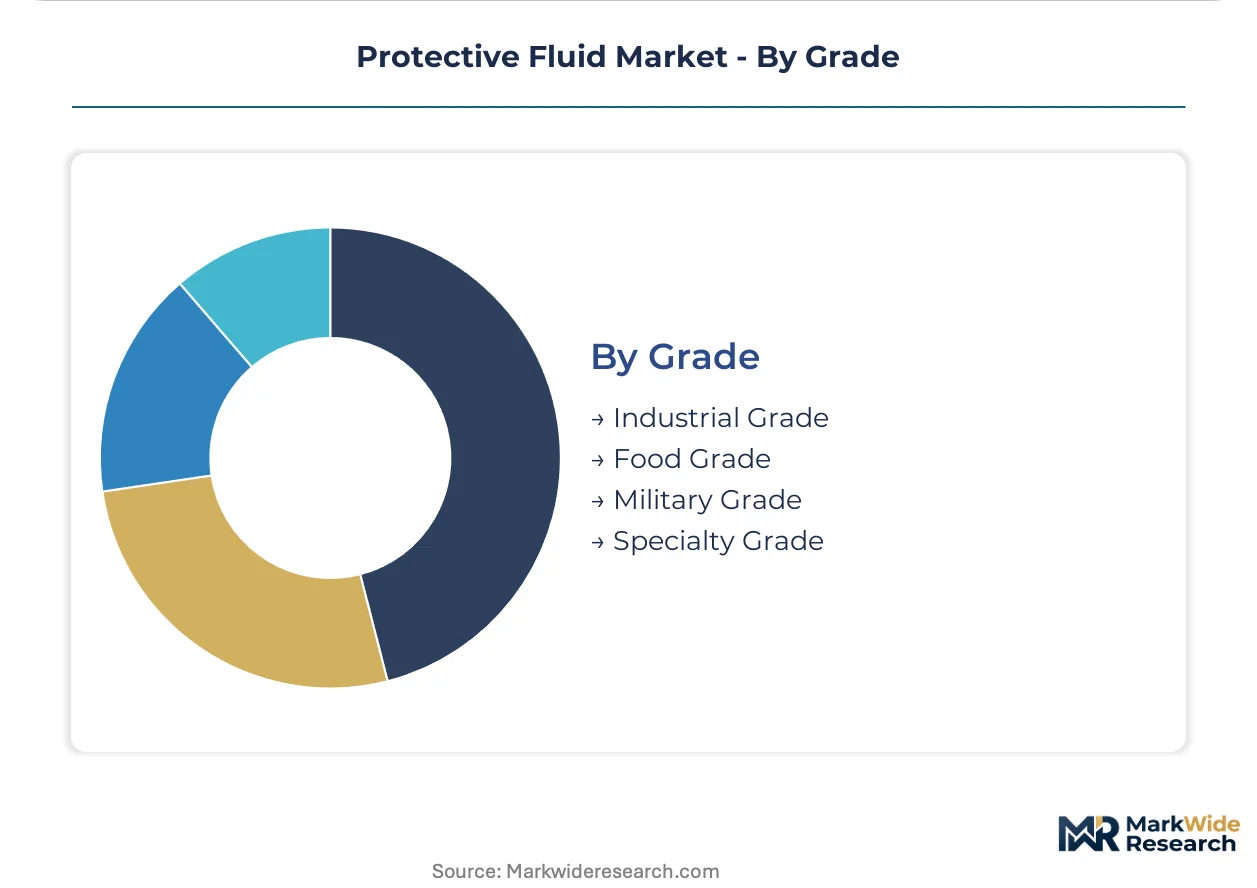
Grade:
Margin concentration stratifies sharply between commodity industrial grades and dual-certified food-military segments where formulation constraints create supply scarcity.
- Industrial Grade:Standard mineral oil and synthetic formulations for general machinery without specialized certification. Base stock supply concentration among upstream-integrated petrochemical producers creates bottleneck risk for mid-tier blenders lacking backward integration into synthetic ester feedstocks.
- Food Grade:NSF H1 registered lubricants with FDA food-contact notification for incidental contact in packaging and processing equipment. FDA notification rules combined with compositional constraints add substantial formulation development costs, creating dual-certification premiums for suppliers serving dairy and beverage packaging lines.
- Military Grade:MIL-PRF qualified products meeting Department of Defense performance specifications.
- Specialty Grade:Custom formulations for unique operating conditions or OEM proprietary requirements.
Industrial grade retains volume leadership; food grade holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Base stock synthesis capacity clusters around petrochemical corridors in Germany, the United States, and China, creating supply bottlenecks for mid-tier blenders lacking captive feedstock access. REACH dossier mandates and EPA FIFRA registration requirements are diverging regulatory pathways across these production centers. Demand concentrates in aerospace maintenance hubs, automotive manufacturing belts, and marine service corridors where certification premiums command price differentiation.
United States
Aerospace hydraulic fluid demand from Boeing and Lockheed Martin maintenance programs is tightening MIL-PRF qualified products list requirements. EPA FIFRA registration governs antimicrobial claims for metalworking fluids sold to Ohio and Michigan stamping facilities. The Gulf Coast petrochemical corridor around Houston anchors synthetic ester base stock production for domestic blender networks.
Germany
Steel mills and aluminum smelters in the Cologne-Leverkusen industrial corridor are specifying fire-resistant PAG water-glycol blends for furnace-proximity operations. ECHA restriction proposals under REACH are targeting PFAS chemistries that underpin extreme-pressure additive performance. Automotive powertrain plants in Stuttgart and Wolfsburg are mandating extended-drain synthetic grades to align with EU Green Deal carbon intensity targets.
China
Precision manufacturing investment in the Yangtze River Delta is accelerating metalworking coolant demand for CNC machining centers. The country's national chemical regulator is tightening substance disclosure requirements for imported additive packages. Heavy machinery fleets in the Pearl River Delta construction equipment market are adopting condition-based monitoring contracts that displace scheduled fluid replacement programs.
India
Production-linked incentive schemes for precision engineering are drawing metalworking fluid suppliers to Gujarat and Tamil Nadu industrial corridors. BIS certification requirements are fragmenting procurement channels for imported synthetic formulations. Automotive component clusters near Pune and Chennai are experiencing fastest coolant demand acceleration as OEM tolerance specifications tighten.
Japan
Shipbuilding hydraulic system specifications in the Nagoya-Chubu corridor are sustaining demand for marine-grade formulations with saltwater corrosion resistance. METI energy efficiency standards are pressuring mineral oil displacement in high-temperature machinery applications. Robotics manufacturing concentration around Osaka is driving demand for ultra-clean hydraulic fluids with particulate contamination controls.
Protective Fluid Market Competitive Landscape
Concentration sits with upstream-integrated petrochemical majors controlling synthetic ester feedstock supply chains for advanced lubricant series. Mid-tier blenders without backward integration face persistent base stock access constraints. The competitive terrain separates into three archetypes: integrated petrochemical majors with captive raw material access, specialty additive technology specialists with fluoropolymer or bio-based ester capabilities, and regional blenders serving certification-constrained niche segments. Dominant competitive moves include strategic partnerships with aerospace maintenance networks and portfolio diversification into condition-based monitoring service contracts.
Among integrated majors, ExxonMobil and Shell exemplify the upstream-anchored archetype with control over critical synthetic base stock pathways. 3M occupies a position within the specialty additive tier, representing fluoropolymer technology convergence that extends service intervals in high-performance hydraulic circuits. These three anchors illustrate how supply chain configuration and formulation IP respectively determine competitive positioning across premium and volume segments.
| Leading Market Players |
|---|
| Angus |
| Dukare |
| Branopac |
| 3M |
| Polyanswer |
| Noble Company |
| ExxonMobil |
| Shell |
| TotalEnergies |
| Others |
Value Network & Pricing Analysis
REACH dossier compliance gates both supplier qualification and price differentiation simultaneously, forcing additive package transparency that fragments procurement into premium-certified tiers versus commodity-grade alternatives. Aerospace maintenance programs and food-contact equipment manufacturers absorb steep certification premiums while industrial machinery fleets optimize total lifecycle cost.
Pricing Analysis
MIL-PRF standards dictate the pricing tier structure across aerospace hydraulic formulations, separating qualified products list suppliers from unqualified blenders. Three-tier pricing structure across premium military-grade, dual-certified food-military, and standard industrial levels captures margin concentration in certification-constrained segments. Cost compression in industrial-grade mineral oil formulations is intensifying because mid-tier blenders lack backward integration into synthetic ester feedstocks. Heavy machinery fleet operators exhibit highest price sensitivity, while aerospace maintenance programs demonstrate lowest sensitivity due to specification lock-in.
Supply Chain Analysis
Synthetic ester feedstock synthesis concentrates in Germany, the United States, and China, creating bottleneck risk for blenders without captive base stock access. Formulation chemistry draws from Group III mineral oils, polyalkylene glycols, and bio-based esters, with additive packages resting on corrosion inhibitors and extreme-pressure chemistries. Single-source vulnerability runs through ExxonMobil's upstream petrochemical integration controlling critical synthetic pathways. Distribution feeds from integrated majors through regional blending facilities to OEM procurement teams and aftermarket service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward aerospace maintenance networks and heavy machinery fleet operators consolidating procurement through qualified products list requirements and condition-based monitoring contracts.
For Market Incumbents: Secure additive package chemist talent pools near Leverkusen and Houston through specialized compensation structures, as formulation expertise combining tribology and regulatory compliance resides with a shrinking cohort. Deepen upstream control over synthetic ester feedstocks to defend against base stock supply concentration that threatens mid-tier blender viability. Counter PFAS phase-out pressures by accelerating sulfur-phosphorus and borate ester alternative development before ECHA restriction proposals force premature R&D redirection. For New Entrants and Emerging Players: Condition-based monitoring service bundling represents the most penetrable white-space where incumbents under-serve, as Caterpillar and Komatsu dealers capture aftermarket value previously held by independent distributors. Target India's Gujarat and Tamil Nadu industrial corridors where production-linked incentive schemes for precision engineering are accelerating metalworking coolant demand with limited qualified supplier presence. Pursue bio-based ester technology convergence to open military specification pathways previously closed to renewable chemistries. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialty additive technology specialists possessing fluoropolymer or bio-based ester capabilities but lacking scale. Long-term viability over a five-to-ten year window favors targets with dual-certification infrastructure spanning NSF H1 and MIL-PRF standards. Watch ECHA restriction proposal timelines on per- and polyfluoroalkyl substances as the inflection indicator forcing reformulation investments and supplier qualification resets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Ester Feedstocks | ExxonMobil's upstream petrochemical integration demonstrates how captive base stock supply secures advanced lubricant series positioning. |
| Condition-Based Monitoring Service Contracts | Caterpillar and Komatsu dealers in Germany bundle sensor hardware with fluid supply to capture lifecycle value from fleet operators. |
| Bio-Based Ester Technology Convergence | Synthetic base stocks combined with plant-derived viscosity modifiers open military specification pathways previously closed to renewable chemistries. |
| Dual-Certification Infrastructure Investment | NSF H1 and FDA food-contact notification capabilities command 15-25% formulation development premiums from dairy and beverage packaging suppliers. |
| Regional Blending Capacity in India | Production-linked incentive schemes for precision engineering in Gujarat and Tamil Nadu are drawing metalworking fluid suppliers to underserved industrial corridors. |
Research Methodology
Operator-level perspectives from plant engineers at steel mills and aluminum smelters, procurement leads at aerospace maintenance networks, and aftermarket service heads at heavy machinery dealers anchored the qualitative base. Primary interviews combined with secondary validation from customs and trade data, ACC and Cefic industry reports, and SEC 10-K filings from petrochemical majors. Bottom-up volume modeling across hydraulic fluids, lubricants, coolants, and release agents triangulated with top-down market sizing from base stock production capacity.
Sensitivity analysis tested forecast robustness against PFAS phase-out timeline acceleration and bio-based ester adoption curves across the projection horizon. Segmentation dimensions modeled include product type, end user industry, application stress condition, and grade certification tier. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and OEM fleet upgrade cycles. Inputs incorporated REACH dossier compliance cost burdens and EPA FIFRA registration timelines for antimicrobial additive claims.
Underlying assumptions cover sustained aerospace maintenance program expansion, stable base stock supply concentration, and gradual PFAS substitution pace, with deviation risk concentrated in ECHA restriction proposal timing and synthetic ester feedstock availability shocks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Human Airbag Wearable Market
Safety Equipment and Personal Protective Equipment (PPE)
Self-Contained Breathing Apparatus (SCBA) Market
Safety Equipment and Personal Protective Equipment (PPE)
Healthcare Personal Protective Equipment (PPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
N95 Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Smart PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Lightning Protection Technologies Market
Safety Equipment and Personal Protective Equipment (PPE)
South America Protective Coating Market
Safety Equipment and Personal Protective Equipment (PPE)
Gas Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Fall Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
Military Gas Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia-Pacific Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Connection Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safety Instrumented Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
US Smart PPE Technology Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Collision Avoidance System Market
Safety Equipment and Personal Protective Equipment (PPE)
Respiratory Protective Equipment Market