
 Ultra-Long Endurance Drone Market | 2026-2036
Ultra-Long Endurance Drone Market Size, Share, and Industry Trends Forecast 2026-2036
Ultra-Long Endurance Drone Market Insights
Software-defined mission payloads is recalibrating what defense and enterprise buyers purchase, shifting value from airframes to updatable ISR packages. AeroVironment leverages decades of Pentagon contracting relationships to sustain long-term program visibility. Anduril Industries competes through AI-driven autonomous systems that reduce operator burden on extended sorties. Quantum-Systems anchors European demand with its Trinity hybrid VTOL platform optimized for survey-grade photogrammetry.
Ultra-long endurance drones are unmanned aerial systems engineered for flight durations exceeding twelve hours through advanced propulsion architectures including hydrogen fuel cells, solar-electric hybrids, or highly efficient internal combustion powerplants. These platforms achieve operational ranges and loiter times that bridge the gap between tactical UAVs and satellite assets, primarily serving persistent intelligence, surveillance, and reconnaissance missions where station-keeping over target areas supersedes rapid transit. Fixed-wing configurations dominate current defense procurement due to superior lift-to-drag ratios that maximize fuel efficiency, while hybrid VTOL designs are capturing commercial interest where runway independence matters. Hydrogen fuel cell technology leads the fastest-growing propulsion category as energy density advantages translate to multi-day endurance without solar dependency. Surveillance applications concentrate the largest margin pools given classified program budgets and specialized sensor integration requirements.
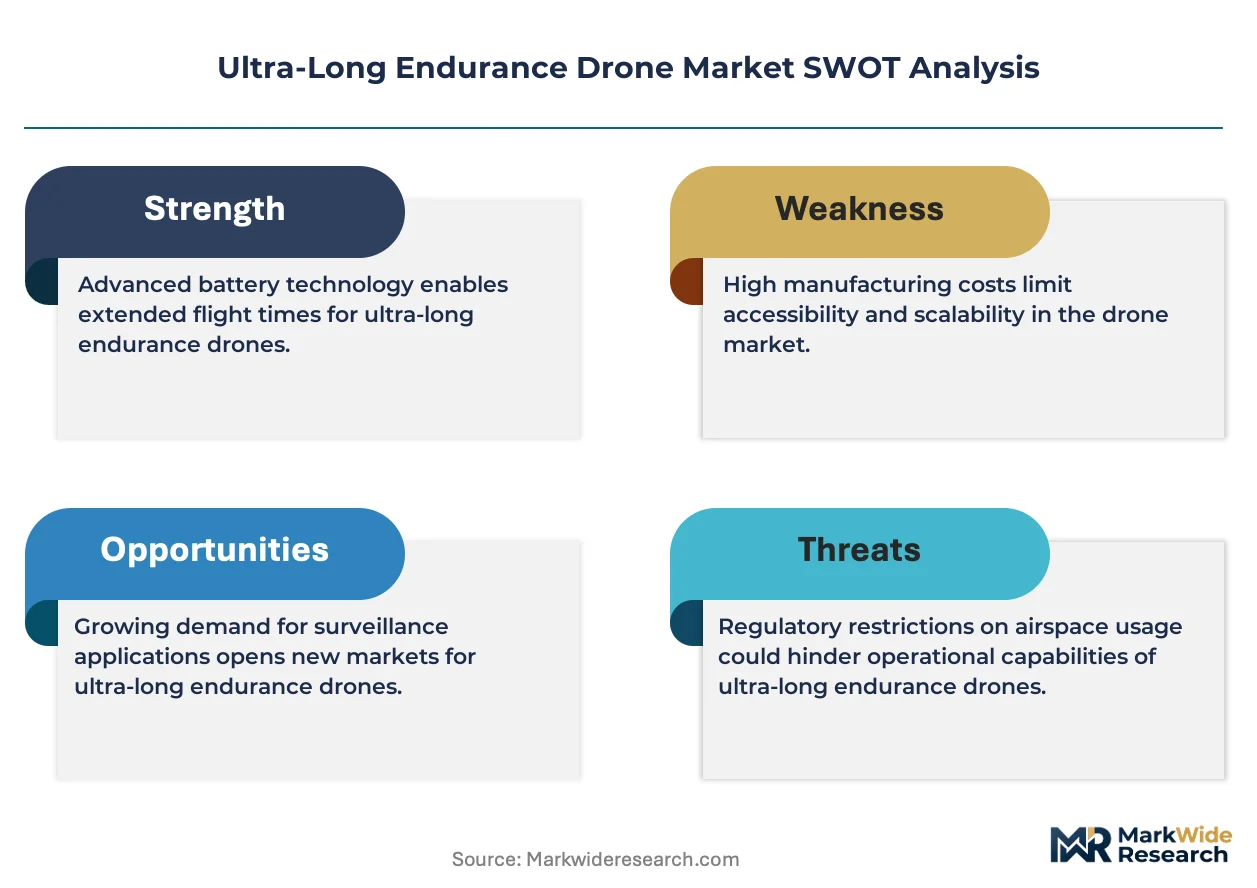
The FAA governs civil airspace integration through Part 107 and emerging beyond-visual-line-of-sight rulemaking that will determine commercial scalability, while EASA's drone regulatory framework in Europe sets certification benchmarks affecting export competitiveness. Defense procurement falls under ITAR and corresponding national security export controls that fragment supplier access across NATO and allied markets. Stakeholders must monitor which propulsion technology achieves military airworthiness qualification first, as this will lock in platform choices for decade-long program cycles.
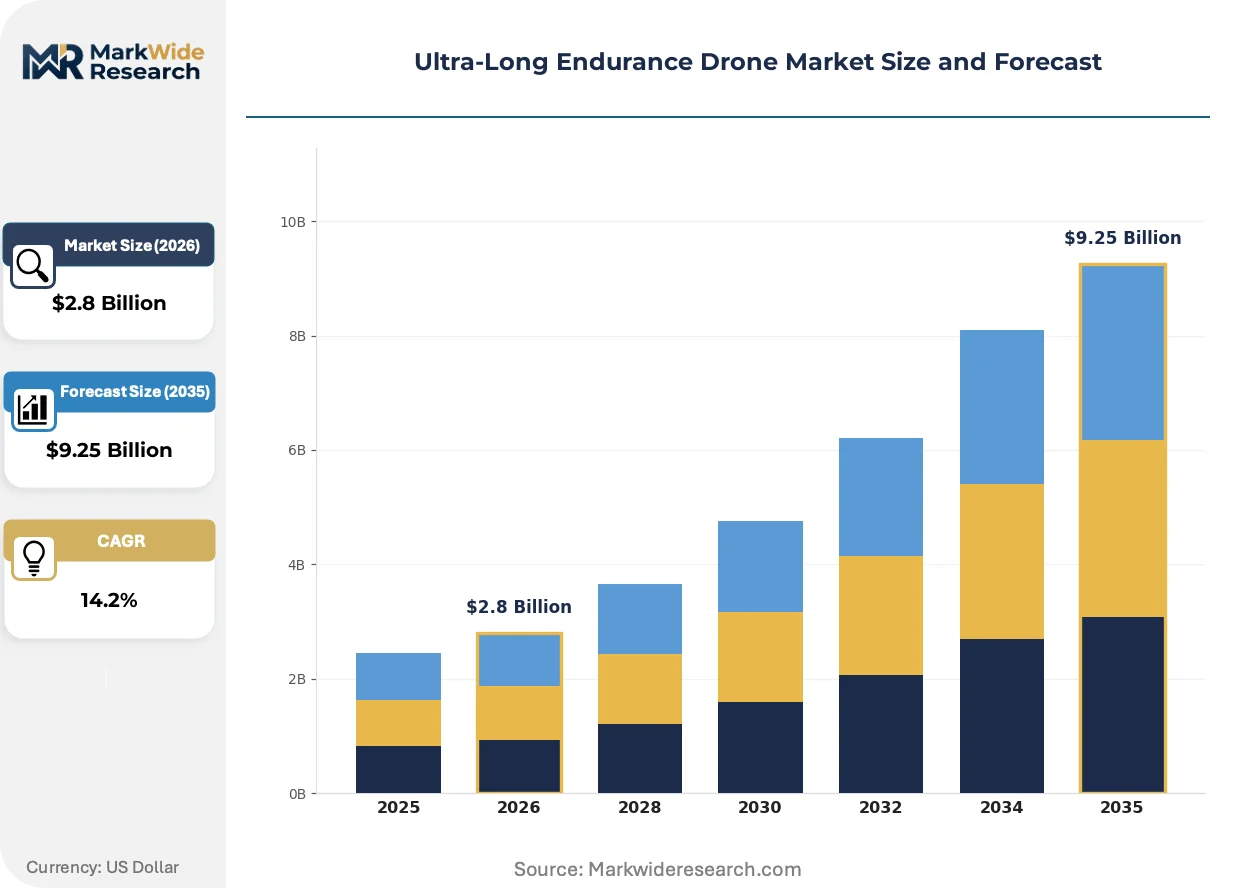
Market Dynamics
Hydrogen fuel cell propulsion is compressing platform development cycles as defense buyers prioritize multi-day endurance over incremental battery improvements. Pentagon program offices now mandate open-architecture payload interfaces that decouple airframe procurement from sensor integration timelines.
Growth Catalysts
- Beyond-Visual-Line-of-Sight rulemaking:FAA Part 107 evolution is unlocking commercial route networks for infrastructure inspection and agricultural monitoring in the United States.
- Defense ISR mission intensification:NATO perimeter surveillance requirements are accelerating fleet modernization across Eastern European member states.
- Hybrid VTOL adoption:Survey-grade photogrammetry applications in Germany are driving demand for runway-independent platforms with precision landing capabilities.
Market Restraints
- ITAR export controls:US national security classification of long-endurance platforms fragments supplier access across allied markets and limits technology transfer.
- Hydrogen infrastructure gaps:Ground refueling station scarcity constrains operational deployment outside established military bases.
- Airworthiness qualification timelines:Military certification cycles for novel propulsion systems extend program development by three to five years versus commercial aviation norms.
Strategic Opportunities
- EASA regulatory harmonization:EU drone framework revisions are creating certification pathways for cross-border commercial operations in France and the Netherlands.
- Maritime patrol applications:Coast guard agencies in Italy and Greece are evaluating solar-electric platforms for Mediterranean border surveillance.
- AI-driven autonomy convergence:Machine-vision navigation paired with satellite communications is enabling reduced-crew operations for extended sorties.
Industry Challenges
- Systems integration engineering scarcity:The specialized workforce for hydrogen fuel cell airframe integration remains concentrated at a handful of defense contractors and national laboratories.
- Legacy ground control interoperability:Existing C4ISR networks require expensive middleware development to accommodate software-defined payload architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultra-Long Endurance Drone Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.25 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing, Rotary-Wing, Hybrid VTOL, Tethered, Solar-Powered Technology: Battery Electric, Hydrogen Fuel Cell, Solar Panels, Hybrid Propulsion, Internal Combustion Engine Application: Surveillance, Agricultural Mapping, Environmental Monitoring, Disaster Management, Infrastructure Inspection End User: Defense & Security, Agricultural Enterprises, Environmental Agencies, Energy Providers, Telecommunications Companies |
| Companies Covered | SenseFly, Edge Autonomy, JOUAV, Skydio, Anduril Industries, AeroVironment, Quantum-Systems, Insitu, Autel Robotics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultra-Long Endurance Drone Market Trends and Innovations
Software-defined architectures are redistributing value creation from hardware manufacturers to payload integrators and mission-system developers. This shift demands new supplier capabilities in firmware deployment and over-the-air update management.
Edge-computing sensor fusion is decentralizing intelligence processing from ground stations to onboard processors. Defense ISR units in Australia and Canada are fielding platforms with real-time target recognition that reduces bandwidth requirements and operator workload. This compression of the sensor-to-shooter timeline is eliminating relay aircraft from certain mission profiles.
EASA's drone regulatory framework is mandating specific design assurance levels for autonomous navigation systems operating in European civil airspace. Manufacturers must now demonstrate equivalent safety to manned aircraft for beyond-visual-line-of-sight certification. German and French aerospace suppliers are investing in formal verification methods to satisfy these airworthiness criteria.
Defense procurement offices are unbundling sensor integration from airframe acquisition through modular payload standards. This disaggregation allows specialized technology firms to compete for ISR subsystem contracts without developing complete platforms. The United Kingdom Ministry of Defence and Norwegian Defense Materiel Agency have adopted this approach for forthcoming maritime surveillance programs.
Ultra-Long Endurance Drone Market Segmentation
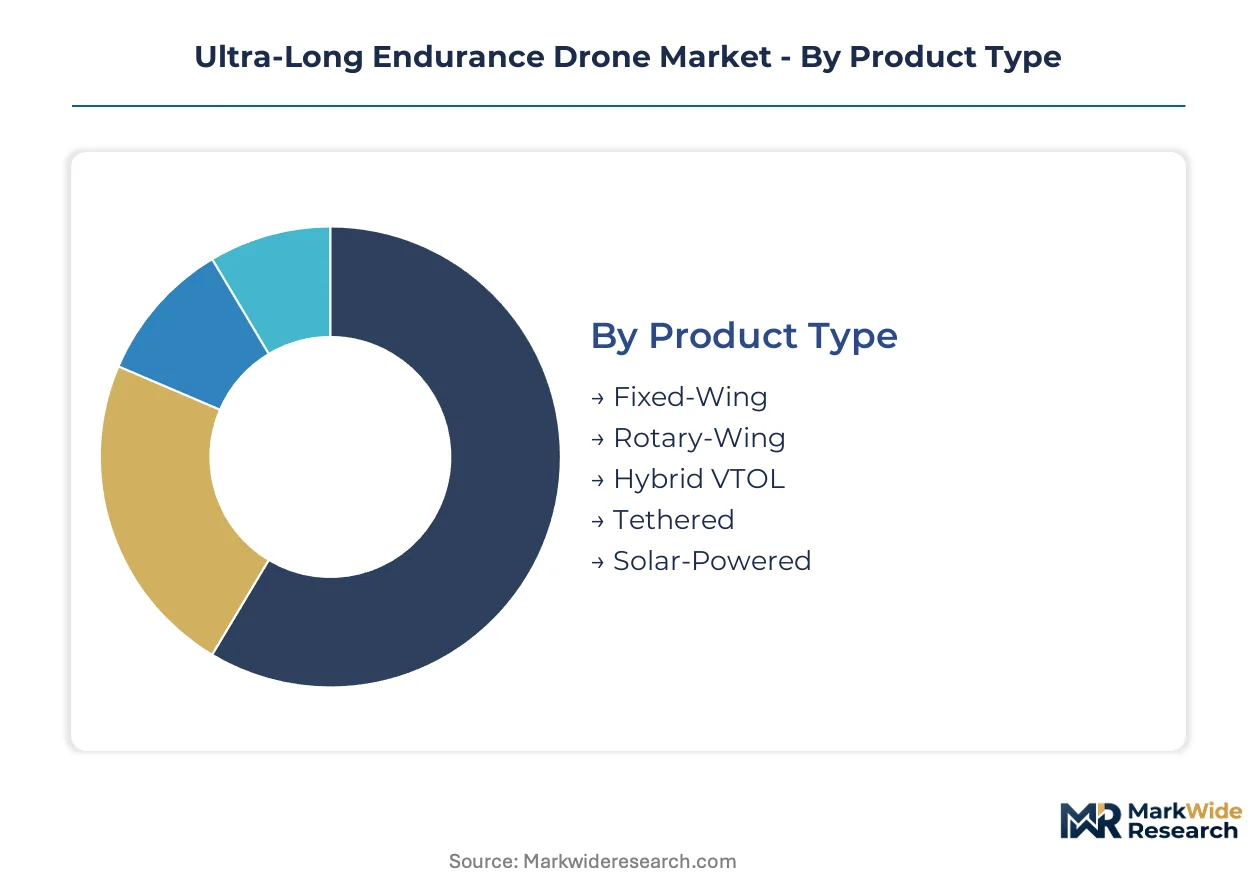
Ultra-long endurance drone procurement decisions cluster around propulsion architecture and operational profile rather than payload flexibility alone. Buyers evaluate platform categories through the lens of runway dependency, energy logistics, and mission duration requirements. This segmentation framework reveals where technology maturity diverges from operational readiness across defense and commercial deployments.
Product Type:
Fixed-wing platforms operate as standalone systems requiring dedicated launch infrastructure, while tethered and hybrid VTOL designs embed into broader operational networks with ground-based power or vertical landing capabilities.
- Fixed-Wing:High aspect-ratio airframes maximize lift-to-drag coefficients for extended loiter missions. Pentagon ISR programs in the United States concentrate procurement here for perimeter surveillance, constrained by runway access requirements at forward operating locations.
- Hybrid VTOL:Tilt-rotor or lift-plus-cruise configurations eliminate runway dependency through electric vertical takeoff transitioning to efficient forward flight. German survey operations and Norwegian coastal patrol units prioritize these platforms for terrain-constrained deployments.
- Rotary-Wing:Conventional helicopter architectures sacrifice endurance for hovering precision in urban or cluttered environments.
- Tethered:Continuous power through fiber-optic cables enables indefinite station-keeping for persistent overwatch at fixed installations.
- Solar-Powered:Photovoltaic wing surfaces extend daytime operations for environmental monitoring missions with low payload mass requirements.
Fixed-wing configurations lead volumes today; hybrid VTOL platforms are gaining share fastest as runway independence becomes a non-negotiable requirement for distributed operations.
Technology:
Propulsion selection follows cost-tier logic: battery electric dominates entry-level commercial applications while hydrogen fuel cell and hybrid systems command premium positioning for defense-grade endurance.
- Hydrogen Fuel Cell:Proton-exchange membrane stacks deliver energy density advantages exceeding lithium-ion by factor of three, enabling multi-day missions without solar exposure. Defense agencies in Australia and the United Kingdom are accelerating qualification programs, bottlenecked by ground refueling infrastructure scarcity.
- Hybrid Propulsion:Combined battery-generator architectures optimize power distribution across mission phases. Italian coast guard evaluations for Mediterranean patrol favor this approach for operational flexibility when hydrogen logistics prove unavailable.
- Battery Electric:Mature supply chains and rapid recharge cycles support short-duration commercial inspection workflows.
- Solar Panels:Integrated photovoltaic arrays supplement primary power for daytime endurance extension in clear-sky conditions.
- Internal Combustion Engine:Conventional heavy-fuel powerplants persist in legacy military platforms requiring NATO-standard logistics compatibility.
Battery electric systems anchor current installed base volumes; hydrogen fuel cell technology is expanding most quickly as military airworthiness certification timelines compress.
Application:
Application segmentation maps directly to customer procurement sophistication: classified defense programs operate on decade-long development cycles while agricultural and infrastructure buyers pursue off-the-shelf deployment.
- Surveillance:Persistent ISR missions demand sensor fusion, encrypted datalinks, and autonomous navigation for reduced crew operations. Classified budgets in the United States and United Kingdom concentrate here, with software-defined payload architectures now mandatory for new program starts.
- Infrastructure Inspection:Linear asset monitoring for pipelines and power transmission requires beyond-visual-line-of-sight regulatory clearance. FAA Part 107 evolution in the United States and EASA framework revisions in France are unlocking route networks for commercial operators.
- Agricultural Mapping:Precision agriculture applications prioritize survey-grade photogrammetry with sub-centimeter ground resolution.
- Environmental Monitoring:Long-duration atmospheric and wildlife observation missions favor solar-electric platforms with minimal acoustic signatures.
- Disaster Management:Rapid deployment requirements for search-and-rescue and damage assessment drive demand for runway-independent platforms with all-weather capability.
Surveillance applications command the largest revenue concentration today; infrastructure inspection is climbing the fastest as civil aviation regulators finalize beyond-visual-line-of-sight certification pathways.
End User:
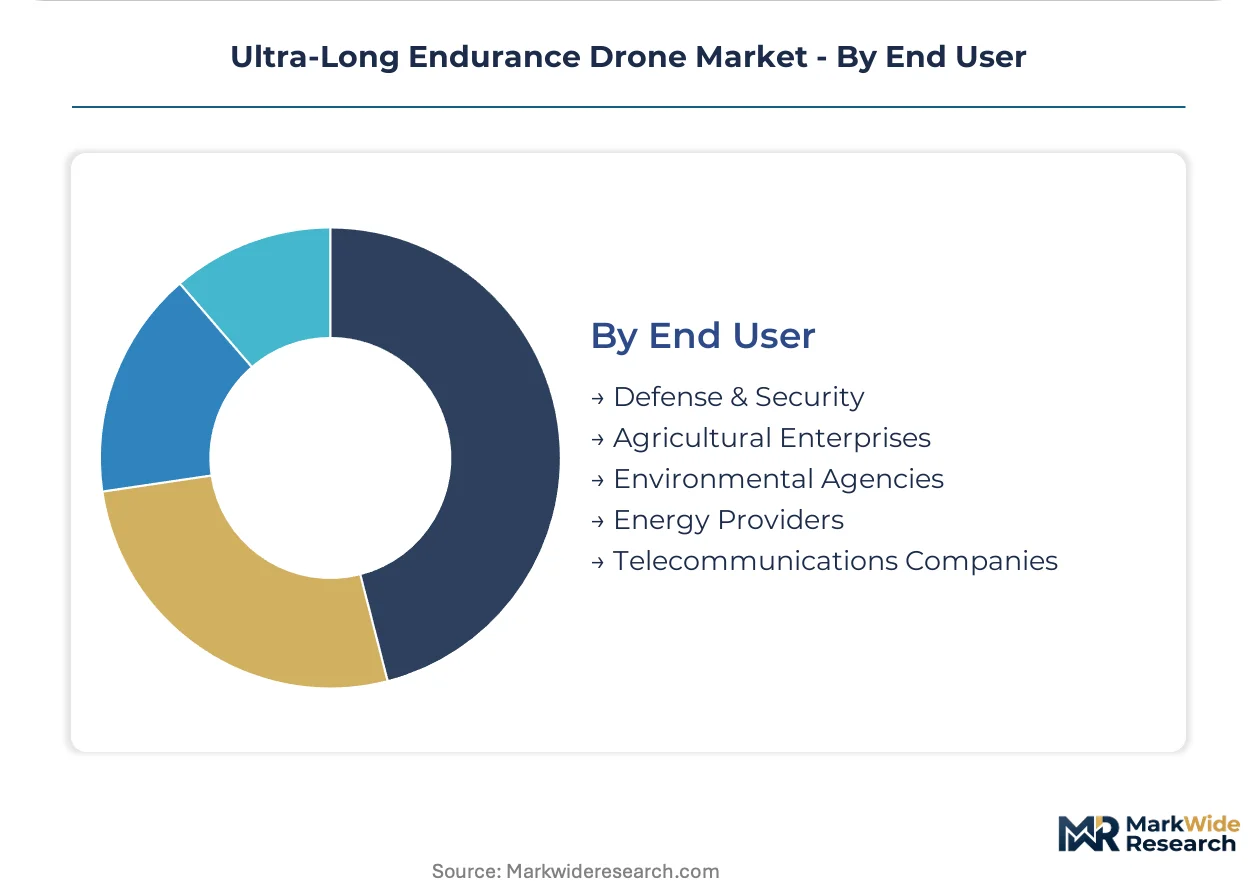
End user segmentation reveals divergent procurement authority structures: defense agencies exercise program-level platform development while commercial buyers purchase through systems integrators or direct manufacturer relationships.
- Defense & Security:National procurement offices mandate open-architecture standards decoupling airframe from sensor acquisition. NATO perimeter surveillance requirements across Eastern European member states are accelerating fleet modernization with multi-day endurance specifications.
- Energy Providers:Oil, gas, and renewable asset operators require corrosion inspection and security patrol across geographically dispersed installations. North Sea operators in Norway and utility companies in Germany are standardizing on hybrid VTOL platforms for offshore and alpine deployments.
- Agricultural Enterprises:Large-scale farming cooperatives purchase mapping services through specialized drone operators rather than owning platforms directly.
- Environmental Agencies:National park services and climate research institutes prioritize acoustic discretion and minimal environmental footprint.
- Telecommunications Companies:Tower inspection and line-of-sight verification for network planning drive recurring commercial demand.
Defense and security agencies dominate current procurement volumes; energy providers are expanding most quickly as operational technology teams internalize aerial inspection capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production footprints as manufacturers relocate engineering and assembly operations toward jurisdictions with streamlined airworthiness certification pathways and lower compliance burdens for hydrogen fuel cell integration.
United States
Pentagon ISR procurement budgets and homeland security perimeter applications concentrate demand in the Southwest and Mid-Atlantic defense corridors. FAA Part 107 evolution toward beyond-visual-line-of-sight operations is unlocking commercial route networks for infrastructure inspection. The Mojave Desert test ranges in California anchor hydrogen fuel cell airworthiness qualification programs for multi-day endurance platforms.
Germany
Survey-grade photogrammetry operations and North Sea energy asset inspections drive hybrid VTOL adoption across Lower Saxony and Bavaria. EASA drone framework revisions mandate design assurance levels for autonomous navigation that German aerospace suppliers address through formal verification methods. Munich and Stuttgart industrial clusters concentrate systems integration engineering for hydrogen fuel cell airframe development.
United Kingdom
Ministry of Defence unbundling of sensor integration from airframe acquisition creates entry points for specialized subsystem contractors. Maritime surveillance requirements for North Atlantic and North Sea domains accelerate fleet modernization specifications. Bristol and Southampton aerospace corridors host open-architecture payload standard development for forthcoming defense programs.
Australia
Defense ISR units field edge-computing sensor fusion platforms with real-time target recognition for Indo-Pacific surveillance missions. The country's civil aviation safety authority adapts certification frameworks for beyond-visual-line-of-sight hydrogen fuel cell operations. Adelaide and Melbourne defense technology clusters concentrate workforce for systems integration engineering.
Italy
Coast guard agencies evaluate solar-electric and hybrid propulsion platforms for Mediterranean border surveillance and maritime patrol applications. National airworthiness authorities align with EASA drone regulatory framework revisions for cross-border commercial certification. Rome and Turin aerospace corridors anchor Italian participation in NATO perimeter surveillance modernization programs.
Ultra-Long Endurance Drone Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with defense procurement favoring integrated platform developers while commercial applications disaggregate toward payload integrators. Market structure tilts toward consolidation at the prime contractor tier for classified programs, with fragmentation persisting in subsystem and component supply. Three archetypes dominate: Pentagon-anchored legacy contractors with program office relationships, AI-native autonomy developers reducing operator burden, and European platform specialists optimized for survey-grade commercial deployment. Competitive moves concentrate on strategic partnerships for hydrogen fuel cell airworthiness qualification and geographic expansion toward EASA-aligned certification jurisdictions.
Within the defense-prime tier, AeroVironment and Anduril Industries occupy positions shaped by contrasting capability accumulation strategies, while Quantum-Systems anchors European commercial demand through Germany-based platform development. SenseFly exemplifies the survey-specialist archetype with concentrated presence in precision photogrammetry applications. Edge Autonomy and JOUAV represent scale-oriented fabricators with structural positions in fixed-wing and hybrid VTOL configurations respectively. These five entities collectively illustrate how supplier positioning fragments across propulsion technology maturity curves and regulatory certification domains rather than consolidating around unified platform standards.
| Leading Market Players |
|---|
| SenseFly |
| Edge Autonomy |
| JOUAV |
| Skydio |
| Anduril Industries |
| AeroVironment |
| Quantum-Systems |
| Insitu |
| Autel Robotics |
| Others |
Pricing and Supply Chain Analysis
Pentagon program offices and allied defense procurement agencies concentrate buying power around multi-year platform contracts, anchoring a project-based pricing model where hydrogen fuel cell airframes command substantial premiums over battery-electric alternatives. This buyer concentration creates asymmetric negotiating leverage that compresses margins for subsystem suppliers while prime contractors retain pricing power through airworthiness certification exclusivity.
Pricing Analysis
Capacity additions in Germany and Australia are reshaping price floors for hydrogen fuel cell integration kits as specialized engineering labor pools expand. Three-tier pricing structure across premium, standard, and economy levels separates military-grade platforms with ITAR-compliant supply chains from commercial survey units and entry-level agricultural mapping systems. Price differentiation hinges on airworthiness certification tier—FAA military qualification versus EASA civil design assurance—and vertical integration depth in fuel cell stack manufacturing. Pricing pressure stems from modular payload standards that decouple sensor costs from airframe acquisition, forcing hardware OEMs to compete on endurance specifications alone. Defense agencies exhibit lowest price sensitivity given decade-long program horizons, while agricultural cooperatives and infrastructure operators face acute budget constraints.
Supply Chain Analysis
Systems integration engineering scarcity in Munich, Stuttgart, and Adelaide clusters constrains production scaling for hydrogen fuel cell airframe programs. Manufacturing concentrates in the United States, Germany, and Australia where defense technology corridors anchor qualified supplier networks. Raw material dependencies center on platinum-group catalysts for proton-exchange membrane stacks, carbon-fiber prepreg for high aspect-ratio wings, and lithium-ion cells for hybrid power distribution systems. Single-source vulnerability in membrane electrode assembly production creates supply chain risk given limited qualified vendors outside established military contractor ecosystems. Distribution runs through prime contractor direct sales for defense programs and specialized systems integrators for commercial survey and inspection deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in ultra-long endurance platforms rest on hydrogen fuel cell cost curves and software-defined payload architectures that shift value capture toward mission-system developers.
For Market Incumbents: Hedge against modular payload disaggregation by deepening captive supply of flight-critical subsystems including autonomous navigation processors and encrypted datalink modules. Counter emerging AI-native autonomy developers through accelerated airworthiness qualification timelines for hydrogen propulsion systems that lock in platform selection for NATO procurement cycles. Prioritize certification investment in EASA-aligned jurisdictions to capture cross-border commercial route networks as FAA-EASA regulatory harmonization advances. For New Entrants and Emerging Players: Launch via payload-integrator partnerships targeting infrastructure inspection verticals where FAA Part 107 beyond-visual-line-of-sight rulemaking is unlocking commercial scale fastest. White-space opportunities concentrate in maritime patrol applications for Mediterranean and North Atlantic coast guard agencies evaluating solar-electric and hybrid platforms. Survey-grade photogrammetry services for North Sea energy asset operators present the most penetrable entry segment given runway-independent operational requirements and established procurement relationships with German hybrid VTOL specialists. For Investors and Strategic Acquirers: Defense prime contractors with established Pentagon program office relationships are the most active acquirer in this space, targeting hydrogen fuel cell airworthiness qualification capabilities and open-architecture payload software stacks. Long-term viability favors platform developers with dual-use positioning across military ISR and commercial inspection segments that smooth demand cyclicality. Watch EASA drone framework implementation timelines as the critical inflection signal—accelerated certification pathways for autonomous navigation systems will determine which technology configurations achieve scalable deployment across European civil airspace.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Fuel Cell Airworthiness Qualification | Military certification unlocks decade-long Pentagon program cycles and NATO allied procurement. |
| Open-Architecture Payload Standard Adoption | Modular interfaces decouple sensor integration timelines from airframe development cycles. |
| EASA Regulatory Certification Investment | Design assurance levels for autonomous navigation enable cross-border European commercial operations. |
| Edge-Computing Sensor Fusion Development | Onboard real-time target recognition reduces bandwidth requirements and operator workload for extended sorties. |
| Hybrid VTOL Platform Expansion | Runway-independent configurations capture terrain-constrained defense and energy inspection demand. |
Research Methodology
Bottom-up defense and energy end-use modeling reconciled against top-down propulsion technology supply tracking forms the analytical core of this study. Primary interviews with Pentagon program officers, EASA certification engineers, hydrogen fuel cell systems integrators, and coastal guard procurement directors combined with secondary validation against FAA rulemaking dockets, EASA drone framework revisions, NATO defense procurement databases, and customs trade records for unmanned aerial system components. Triangulation across stakeholder perspectives and documentary sources ensures segmentation integrity across propulsion architecture, operational profile, and end-user procurement authority structures.
Input-output matrices map hydrogen fuel cell stack production capacity, battery electric system manufacturing volumes, and solar-electric platform deployment rates against defense ISR budget allocations and commercial infrastructure inspection contract flows across the analysis window. Segmentation dimensions include propulsion technology maturity, airframe configuration, application mission profile, and end-user procurement sophistication. CAGRs derive from fitted growth curves calibrated to airworthiness qualification timelines and regulatory pathway clarity. Industry-specific forecast inputs incorporate EASA design assurance implementation schedules and Pentagon open-architecture mandate adoption rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated FAA beyond-visual-line-of-sight rulemaking or extended hydrogen infrastructure deployment delays. Forecasts reflect assumptions regarding regulatory harmonization trajectories, military airworthiness certification compression, and propulsion technology cost curves. Material deviation in EASA autonomous navigation standards or Pentagon modular payload procurement mandates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Europe Tactical UAV Market
UAV
Fixed-Wing VTOL UAV Market
UAV
Multirotor Drones Market
UAV
Drone Telematics Market
UAV
Solar Powered Drones Market
UAV
Drone Leasing Market
UAV
Asia Pacific Commercial Drone Market
UAV
Drone Delivery Services Market
UAV
Inspection Drones in Confined Space Market
UAV
Drone Payload Market
UAV
UAV Lidar Market
UAV
Drone Wireless Charging Station Market
UAV
Toy Drones Market
UAV
UAV Navigation Systems Market
UAV
Europe Commercial Drones Market
UAV
Firefighting Drone Market