
 Asia-Pacific Drone Light Shows Market | 2026-2036
Asia-Pacific Drone Light Shows Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Drone Light Shows Market Insights
LED matrix technology is shifting from imported phosphor-based modules to domestically sourced gallium nitride substrates, cutting per-drone illumination costs by roughly half for large fleet operators. Shenzhen HighGreat Innovation Technology Development Co., Ltd leverages captive semiconductor foundry partnerships to control upstream LED supply. SKYMAGIC LIVE. PTE. Ltd anchors its competitive position through permanent venue installations across Singapore and Bangkok entertainment districts. CollMot specializes in swarm choreography algorithms that reduce pilot staffing requirements for complex aerial formations.
Asia-Pacific drone light shows are coordinated aerial performances using GPS-stabilized multi-rotor platforms equipped with programmable RGB LED arrays, typically operating in formations of 100 to 5,000 units synchronized via mesh-networked flight controllers. Commercial drones dominate fleet procurement for recurring entertainment contracts, while industrial-grade platforms with enhanced payload capacity and weatherproofing capture the highest margin pools in outdoor festival deployments. LED technology leads hardware segmentation due to its luminous efficiency and color granularity, though AI-driven autonomous collision avoidance is the fastest-growing capability layer as regulators mandate reduced human oversight density over populated areas.
China's MIIT enforces real-name registration and no-fly zone geofencing for all commercial UAV fleets above specified weight thresholds, while Japan's METI and Australia's CASA impose separate night-operation certification regimes that shape cross-border service scalability. India's DGFT drone import restrictions and domestic PLI scheme incentives are redirecting fleet procurement toward locally assembled platforms. Stakeholders must monitor divergence between national airspace management systems and build modular compliance architectures that adapt to fragmented certification timelines across the region.
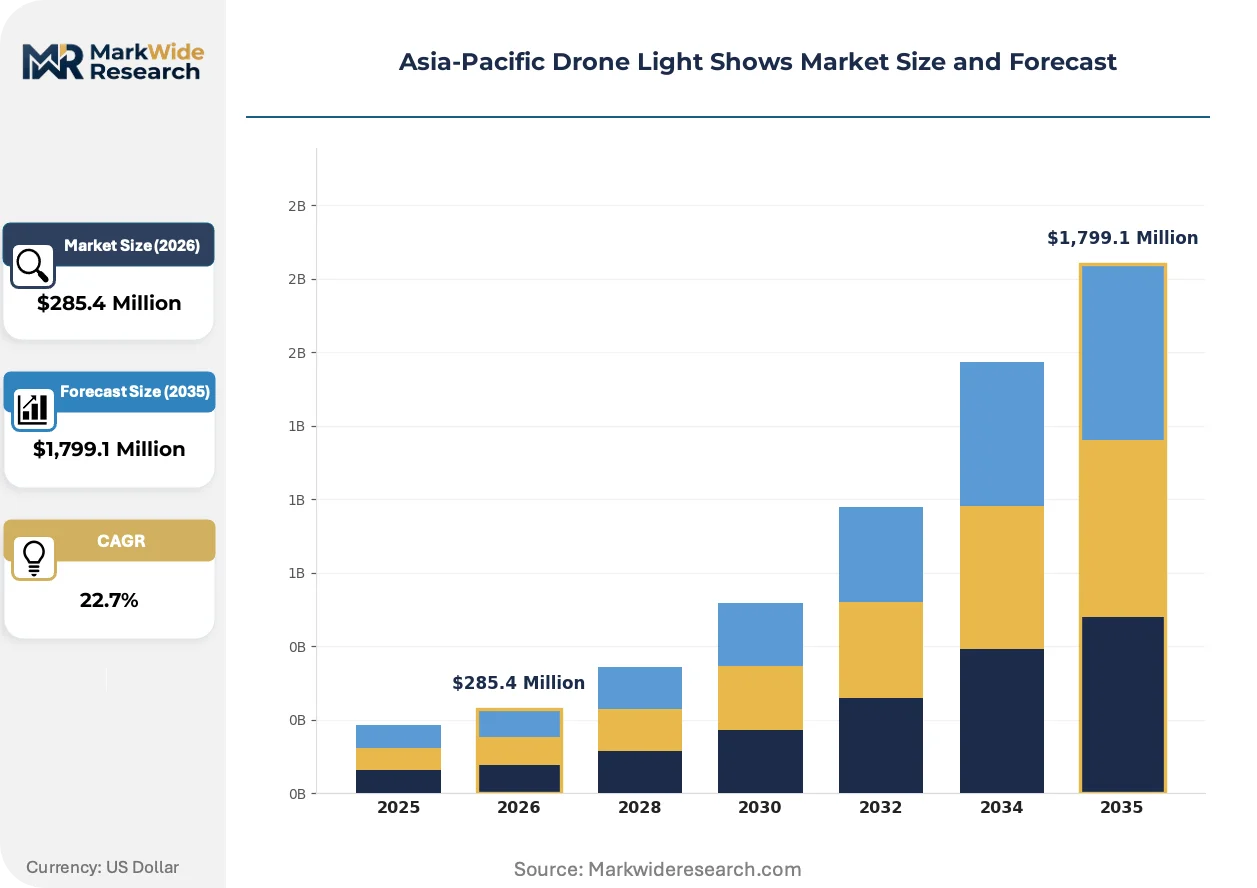
Market Dynamics
China's MIIT real-name registration mandate and no-fly zone geofencing requirements are compressing operational flexibility for fleet operators while simultaneously accelerating investment in autonomous collision-avoidance systems that reduce pilot density over populated areas.
Growth Catalysts
- Tourism board substitution:Southeast Asian cultural festivals are replacing pyrotechnics with drone formations, creating recurring demand anchors in Thailand, Vietnam, and Indonesia.
- Japan's METI night-operation certification:Standardized safety frameworks enable cross-border service portability and reduce insurer risk premiums for outdoor festival deployments.
- Gallium nitride LED substrates:Domestic sourcing of semiconductor-grade illumination modules halves per-unit hardware costs for large fleet operators based in Shenzhen manufacturing clusters.
Market Restraints
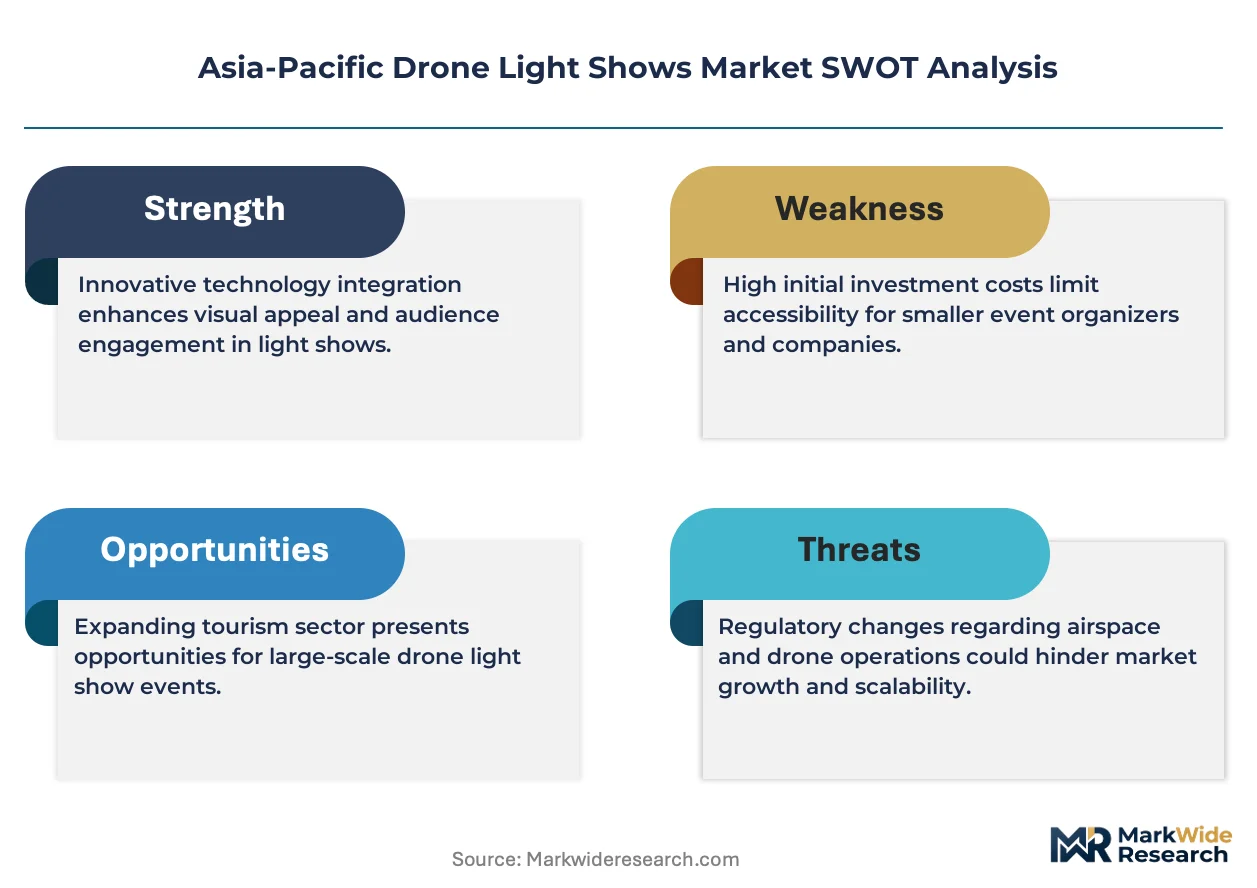
- Geofencing fragmentation:Divergent national airspace management systems between China's MIIT, Japan's METI, and Australia's CASA create compliance architecture costs that scale with cross-border operations.
- Weatherproofing input volatility:Industrial-grade payload housings require aerospace-grade composites subject to supply concentration in specific East Asian foundry networks.
- Fireworks residual preference:Traditional pyrotechnic suppliers retain cost advantages for single-use municipal celebrations in price-sensitive Indian and Indonesian municipalities.
Strategic Opportunities
- India's PLI scheme redirection:Domestic assembly incentives and DGFT import restrictions are creating captive demand pools for locally manufactured swarm platforms in Mumbai and Bangalore entertainment corridors.
- Permanent venue installations:Entertainment districts in Singapore and Bangkok are converting temporary festival contracts into recurring revenue through dedicated launch infrastructure.
- AI-mesh convergence:Integration of autonomous collision algorithms with GPS-stabilized flight controllers enables reduced staffing ratios for complex aerial choreography.
Industry Challenges
- Pilot certification bottlenecks:Night-operation licensing timelines under Japan's METI and Australia's CASA regimes create workforce scaling friction during peak festival seasons.
- Fleet synchronization complexity:Mesh-networked flight controllers require specialized RF engineering talent concentrated in Shenzhen and Seoul technology clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Drone Light Shows Market |
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $1,799.1 Million |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Consumer Drones, Commercial Drones, Industrial Drones, Agricultural Drones End User: Entertainment, Events, Advertising, Military Technology: LED, LiDAR, GPS, AI Application: Live Performances, Festivals, Marketing Campaigns, Public Displays |
| Companies Covered | CollMot, Shenzhen HighGreat Innovation Technology Development Co., Ltd, SKYMAGIC LIVE. PTE. Ltd, Great Lakes Drone Company, LLC, Verge, Inc., BotLab Dynamics, Sky Elements, LLC, Celestial Labs Ltd., Dronisos, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Drone Light Shows Market Trends and Innovations
Autonomous swarm coordination and domestic semiconductor sourcing are compressing cost structures while regulatory mandates around populated-area operations force capability upgrades across fleet operators.
Gallium nitride substrate technology is rewriting the economics of large-scale LED illumination. Domestic Chinese foundries now supply phosphor-free substrates that cut thermal management overhead and extend flight endurance. Tier-one city festival operators in Beijing, Shanghai, and Shenzhen are adopting these modules at scale, collapsing the cost gap between mid-size and mega-fleet formations.
Japan's METI drone safety guidelines are mandating redundant collision-avoidance systems for night operations above designated population density thresholds. Industrial-grade platform manufacturers must now integrate dual-band RF and optical flow sensors to maintain certification eligibility. Australian festival operators under CASA jurisdiction are adopting identical hardware specifications to streamline cross-border equipment deployment.
Buyer contracting patterns are compressing from multi-year equipment purchases toward performance-based service agreements. Tourism boards and municipal event planners in Thailand and Vietnam now specify guaranteed formation outcomes rather than fleet ownership. This shift favors operators with permanent venue infrastructure and captive maintenance capabilities over asset-light rental providers.
Asia-Pacific Drone Light Shows Market Segmentation
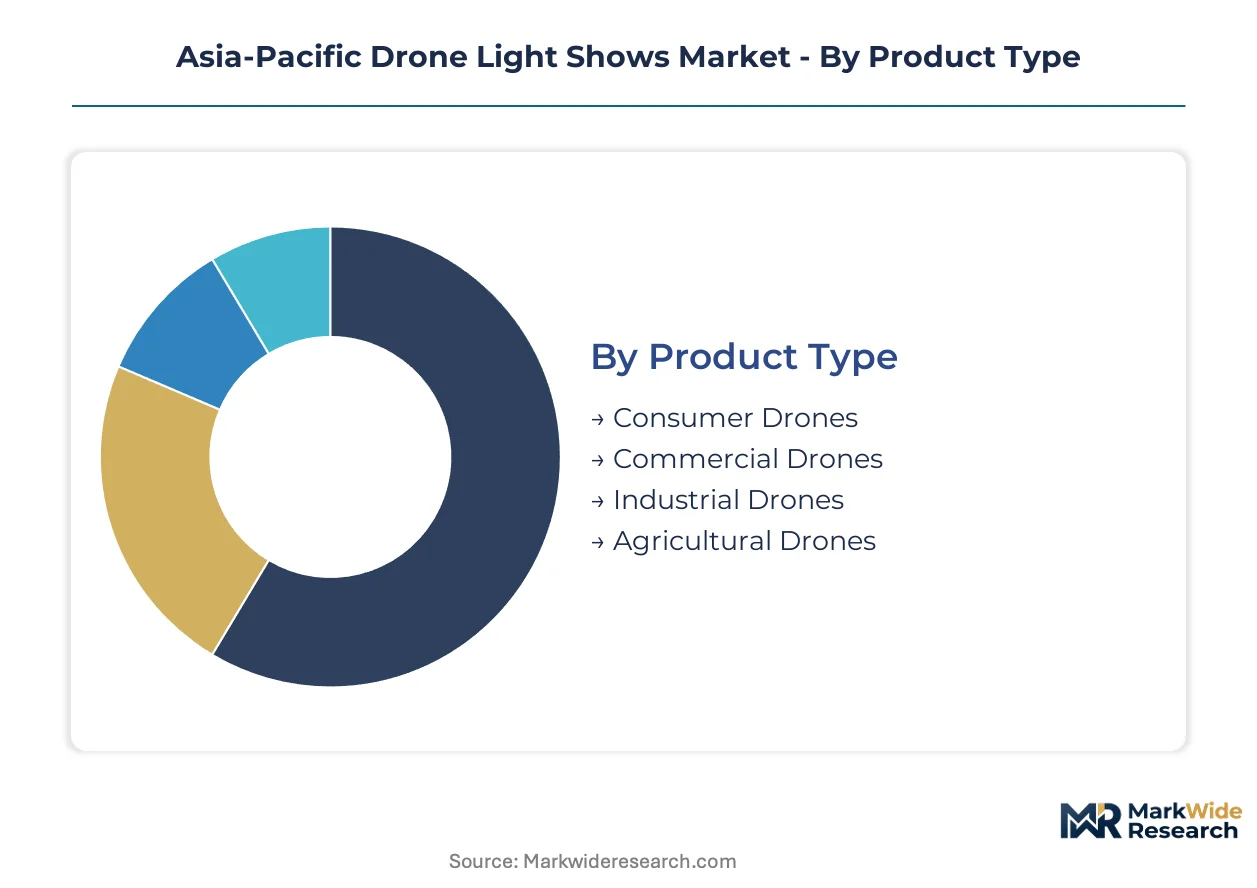
Drone light show economics diverge sharply across hardware tiers, with fleet operators optimizing procurement between recurring entertainment contracts and one-off municipal deployments. Segmentation reveals how regulatory mandates and venue infrastructure reshape technology adoption patterns across the Asia-Pacific.
Product Type:
Shenzhen manufacturing clusters concentrate component supply for GPS-stabilized multi-rotor platforms, with domestic gallium nitride substrate sourcing compressing hardware costs for high-volume fleet operators.
- Commercial Drones:GPS-stabilized multi-rotor platforms equipped with programmable RGB LED arrays dominate recurring entertainment contracts in Bangkok and Singapore entertainment districts. Tourism boards specify these units for guaranteed formation outcomes under performance-based service agreements.
- Industrial Drones:Weatherproofed platforms with enhanced payload capacity and aerospace-grade composite housings capture premium margins in outdoor festival deployments across Japan and Australia. METI and CASA night-operation certifications mandate redundant collision-avoidance systems that drive hardware specification.
- Consumer Drones:Entry-level platforms lack the mesh-networked flight controllers and luminous output density required for professional choreography.
- Agricultural Drones:Payload-optimized designs prioritize spray systems over LED matrix integration, limiting crossover applicability to aerial performance markets.
Commercial drones absorb the bulk of installed capacity; industrial drones are expanding most quickly as regulators tighten populated-area operational requirements.
End User:
Contracting patterns compress toward outcome-based agreements, with municipal buyers shifting from equipment ownership to guaranteed formation performance.
- Entertainment:Permanent venue installations in Singapore and Bangkok entertainment districts convert temporary festival contracts into recurring revenue streams through dedicated launch infrastructure and captive maintenance capabilities.
- Events:Seasonal demand concentrates around Thailand's cultural festival calendar and Vietnam's municipal celebrations, with operators scaling pilot staffing around METI and CASA certification bottlenecks.
- Advertising:Corporate buyers specify brand-integrated aerial choreography for product launches, though campaign frequency remains below entertainment sector baselines.
- Military:Defense applications prioritize surveillance payload integration over LED illumination systems, creating minimal overlap with commercial light show operations.
Entertainment commands the deepest fleet deployment; events demonstrate the steepest expansion trajectory as pyrotechnic substitution accelerates across Southeast Asia.
Technology:
Capability layering determines competitive positioning, with autonomous systems reducing regulatory compliance costs over populated areas.
- LED:Gallium nitride substrate technology cuts thermal management overhead and extends flight endurance for large formations. Domestic Chinese foundries now supply phosphor-free substrates that halve per-unit illumination costs compared to imported phosphor-based modules.
- AI:Autonomous collision-avoidance algorithms reduce pilot density requirements for complex aerial choreography. Japan's METI mandates and Australia's CASA guidelines are accelerating adoption of AI-mesh convergence for night operations above population density thresholds.
- GPS:Stabilization systems provide baseline formation synchronization, though differentiation now concentrates in mesh-networked controller integration.
- LiDAR:Optical ranging systems supplement RF-based collision avoidance in high-obstacle environments, adding hardware cost without mandatory regulatory status.
LED retains the dominant installed base; AI is gaining share fastest as regulators mandate reduced human oversight density.
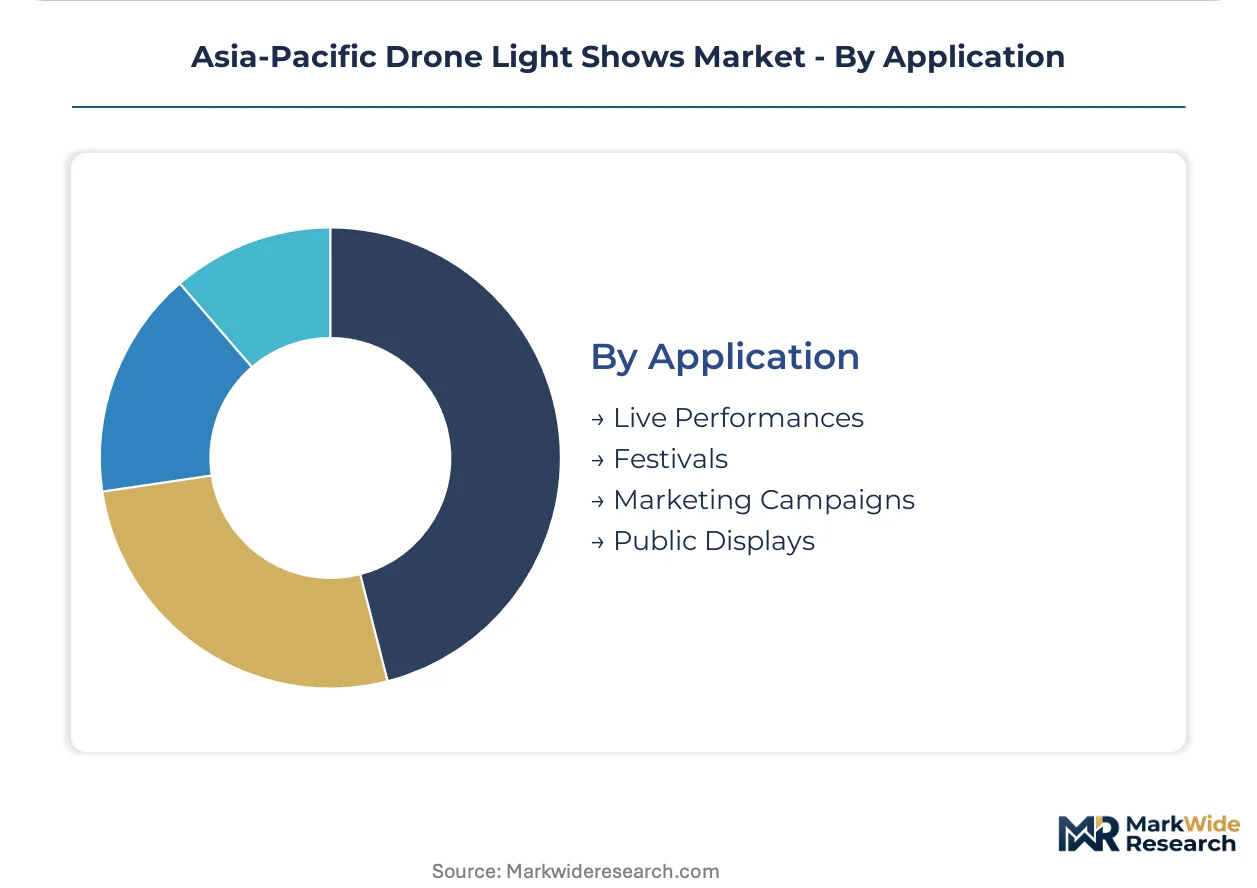
Application:
Buyer specifications increasingly separate temporary festival deployments from permanent infrastructure investments.
- Festivals:Outdoor cultural celebrations in Thailand, Vietnam, and Indonesia are replacing traditional fireworks with drone formations, creating recurring demand anchors that favor operators with cross-border equipment portability.
- Live Performances:Theater-integrated shows in China's tier-one cities leverage permanent venue infrastructure to reduce per-performance setup costs and enable tighter rehearsal schedules.
- Marketing Campaigns:Corporate buyers demand brand-specific aerial choreography with shorter lead times than municipal festival procurement cycles.
- Public Displays:Government-sponsored celebrations in Indian and Indonesian municipalities face residual cost competition from traditional pyrotechnic suppliers.
Festivals absorb the majority of fleet operating hours; live performances are climbing the fastest as permanent venue infrastructure spreads across entertainment districts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's Qianhai Special Economic Zone concentrates drone manufacturing capacity through bonded logistics and R&D tax incentives that anchor regional supply chains for LED-integrated aerial platforms.
China
Beijing, Shanghai and Shenzhen municipal tourism bureaus commission recurring drone formations for national holiday celebrations. MIIT real-name registration and no-fly zone geofencing compress operational flexibility while accelerating autonomous collision-avoidance adoption. Shenzhen manufacturing clusters supply gallium nitride LED substrates that halve illumination costs for fleet operators.
Japan
Tokyo and Osaka entertainment districts drive demand for theater-integrated aerial choreography. METI night-operation certification mandates redundant collision-avoidance systems for populated-area deployments. Kanto region operators adopt hardware specifications that streamline cross-border equipment portability with Australian festival circuits.
Australia
Sydney and Melbourne festival organizers replace pyrotechnics with drone formations for major cultural events. CASA night-operation licensing creates workforce scaling friction during peak seasons. Victorian entertainment corridors adopt METI-equivalent hardware specifications to enable equipment deployment across Asia-Pacific contracts.
Thailand
Bangkok entertainment districts convert temporary festival contracts into recurring revenue through permanent launch infrastructure. Tourism board substitution of fireworks with drone formations creates demand anchors during cultural festival calendars. Metropolitan venue operators specify guaranteed formation outcomes under performance-based service agreements.
India
Mumbai and Bangalore entertainment corridors redirect fleet procurement toward locally assembled platforms. DGFT drone import restrictions and PLI scheme incentives create captive demand pools for domestic manufacturers. Maharashtra-based operators scale pilot staffing around certification bottlenecks during municipal celebration peaks.
Asia-Pacific Drone Light Shows Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated fleet operators capturing recurring entertainment contracts while component suppliers serve rental-heavy municipal markets. The vendor base concentrates around three strategic archetypes: Shenzhen-based manufacturers with captive LED supply, Singapore-anchored venue operators with permanent infrastructure, and European algorithm specialists reducing pilot density requirements. Competitive moves center on backward integration into semiconductor sourcing and permanent venue installations that convert temporary contracts into recurring revenue streams.
Among Shenzhen-based manufacturers, Shenzhen HighGreat Innovation Technology Development Co., Ltd exemplifies the captive-supply archetype through semiconductor foundry partnerships. SKYMAGIC LIVE. PTE. Ltd occupies a position within the permanent-infrastructure tier, anchoring competitive presence across Singapore and Bangkok entertainment districts. CollMot represents the algorithm-specialist vector, with swarm choreography capabilities that reduce staffing requirements for complex aerial formations.
| Leading Market Players |
|---|
| CollMot |
| Shenzhen HighGreat Innovation Technology Development Co., Ltd |
| SKYMAGIC LIVE. PTE. Ltd |
| Great Lakes Drone Company, LLC |
| Verge, Inc. |
| BotLab Dynamics |
| Sky Elements, LLC |
| Celestial Labs Ltd. |
| Dronisos |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between METI-compliant industrial platforms and standard commercial units splits both pricing power and sourcing strategies across the Asia-Pacific drone light show market. Fleet operators purchasing for Japan's night-operation mandates face aerospace-grade composite premiums and dual-band RF sensor requirements that domestic Chinese buyers circumvent through Shenzhen-sourced gallium nitride substrates.
Pricing Analysis
Volume-driven commercial formations absorb thin margins while industrial-grade certifications capture premium pools. Three-tier pricing structure across premium, standard, and economy levels separates METI-certified platforms with redundant collision systems from geofenced commercial fleets and entry-level rental units. Cost compression in the commercial tier intensifies because Shenzhen manufacturers pass through gallium nitride substrate savings. Municipal tourism boards in Thailand and Vietnam exhibit highest price sensitivity; permanent venue operators in Singapore accept premium positioning for guaranteed formation outcomes.
Supply Chain Analysis
Dual-sourcing requirements from Japanese and Australian regulators force fleet operators to qualify both Shenzhen gallium nitride foundries and Seoul RF controller specialists for cross-border deployment flexibility. Geographic supply concentration centers on China for LED substrates and flight controllers, South Korea for mesh-networked RF engineering talent, and Japan for aerospace-grade composite housings. Raw material dependencies include phosphor-free semiconductor wafers, GPS stabilization modules, and weatherproofed payload enclosures. Single-source vulnerability concentrates in Shenzhen's bonded logistics zones where Qianhai Special Economic Zone incentives anchor component flows. Distribution runs through permanent venue infrastructure operators in entertainment districts rather than asset-light rental channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific drone light show market is becoming a vertical-integration race as fleet operators pursue captive semiconductor sourcing to collapse illumination costs and lock in margin expansion against component volatility.
For Market Incumbents: Anchor competitive position through permanent venue installations in Bangkok and Singapore entertainment corridors that convert temporary festival contracts into recurring revenue streams. Invest in backward integration into gallium nitride substrate partnerships with Shenzhen foundries to defend against emerging domestic assemblers in India. Pursue dual METI-CASA certification portfolios to streamline cross-border equipment portability as regulatory fragmentation intensifies. For New Entrants and Emerging Players: India's PLI scheme and DGFT import restrictions open a window for domestic assembly operations targeting Mumbai and Bangalore entertainment corridors with locally manufactured swarm platforms. Focus initial penetration on price-sensitive municipal celebrations in Indonesian and Indian public display segments where fireworks residual preference creates white-space opportunity. Deploy performance-based service agreements rather than fleet ownership models to bypass capital barriers and align with tourism board contracting shifts. For Investors and Strategic Acquirers: Re-rating potential sits with algorithm-specialist targets given AI-mesh convergence mandates from Japan's METI and Australia's CASA that reduce pilot density requirements. Long-term viability hinges on permanent venue infrastructure ownership that generates recurring revenue through dedicated launch sites and captive maintenance capabilities. Watch for inflection in cross-border equipment portability standardization across Asia-Pacific regulators as signal for scalable platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Semiconductor Sourcing | Gallium nitride substrate partnerships with Shenzhen foundries halve illumination costs for fleet operators. |
| Permanent Venue Infrastructure | Dedicated launch sites in Singapore and Bangkok entertainment districts convert temporary contracts into recurring revenue. |
| Dual Certification Portfolio | Simultaneous METI and CASA compliance streamlines cross-border equipment deployment across Asia-Pacific festival circuits. |
| AI-Mesh Convergence Investment | Autonomous collision-avoidance algorithms reduce pilot staffing ratios for complex aerial choreography mandates. |
| Domestic Assembly Localization | India PLI scheme alignment redirects fleet procurement toward Mumbai and Bangalore manufacturing corridors. |
Research Methodology
Multi-period observation of fleet procurement patterns, regulatory certification timelines, and venue infrastructure investments anchored the trend analysis, supplemented by interviews with fleet operators, semiconductor sourcing managers, tourism board procurement officers, and RF engineering specialists. Secondary validation drew from MIIT registration databases, METI safety guideline publications, CASA licensing records, and Shenzhen customs export data. Bottom-up fleet deployment counts across tier-one Chinese cities and top-down entertainment sector revenue estimates were triangulated to establish market sizing.
Input-output matrix modeling connected gallium nitride substrate cost curves, pilot certification bottlenecks, and permanent venue installation economics to formation-scale projections across the analysis window. Segmentation dimensions included hardware tier, end-use application, technology capability layer, and national regulatory cluster. CAGRs were derived from fitted adoption curves for pyrotechnic substitution rates and autonomous system penetration. Industry-specific forecast inputs incorporated METI night-operation certification expansion timelines and India's PLI scheme incentive phase structures.
The model assumes a particular technology adoption path; alternative pathways for AI-driven autonomous collision avoidance would alter the outlook if regulatory mandates accelerate or stall. Forecasts reflect assumptions about cross-border equipment portability standardization and domestic semiconductor sourcing substitution rates. Deviation in national airspace management system convergence would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Europe Small UAV Market
UAV
Global Drone Analytics Market
UAV
Rotary Blade UAV Drones Market
UAV
Commercial Drone Market
UAV
Solar Powered Drones Market
UAV
Industrial Drones Market
UAV
Short-Range Delivery Drone Market
UAV
Middle-East and Africa Drones Market
UAV
Nano Drones Market
UAV
Global Inspection Drones Market
UAV
Small UAV Market
UAV
Drone Wireless Charging Station Market
UAV
Europe Drone Services Market
UAV
Drone Tracking Antenna Market
UAV
Drone Identification System Market
UAV
Home Security Drone Market