
 Cordless Power Drill Market | 2026-2036
Cordless Power Drill Market Size, Share, and Industry Trends Forecast 2026-2036
Cordless Power Drill Market Insights
The capital-intensity divergence between in-house motor manufacturing and outsourced assembly is unwinding competitive hierarchies across the cordless power drill industry. Robert Bosch GmbH leverages its captive production of brushless motor systems to command premium positioning in professional channels. Makita Corporation sustains manufacturing scale across multiple Asian facilities, enabling cost discipline in mid-tier product lines. Techtronic Industries Co. Ltd. competes through aggressive channel control in North American retail, extending its private-label and branded reach simultaneously.
A cordless power drill is a handheld rotary tool powered by rechargeable battery packs, typically delivering torque outputs from 15 Nm for household tasks to over 130 Nm for heavy-duty construction, with brushless motor variants offering 50% longer runtime than brushed equivalents. Its primary commercial purpose is to bore holes and drive fasteners across wood, metal, masonry, and composite substrates without tethering to AC power sources. Brushless motor drill configurations now lead value generation due to superior thermal efficiency and extended service intervals demanded by contractor end users. Lithium-ion battery technology anchors the installed base as nickel-cadmium chemistries retreat from new product introductions under environmental compliance pressure.
FCC certification governs electromagnetic emissions for cordless power drills sold in the United States, while the EU's CE marking and RoHS directives restrict hazardous substances in battery and electronic assemblies. China's GB standards and MIIT regulations enforce safety testing protocols for lithium-ion cell integration, shaping export eligibility for manufacturers based in Asia. Stakeholders must monitor battery recycling mandates and chemistry disclosure requirements as regulatory frameworks tighten across multiple jurisdictions.
Market Dynamics
Brushless motor technology and lithium-ion battery chemistry are compressing replacement cycles while the EU's F-Gas Regulation and REACH directives force retooling of supply chains toward cleaner material sourcing.
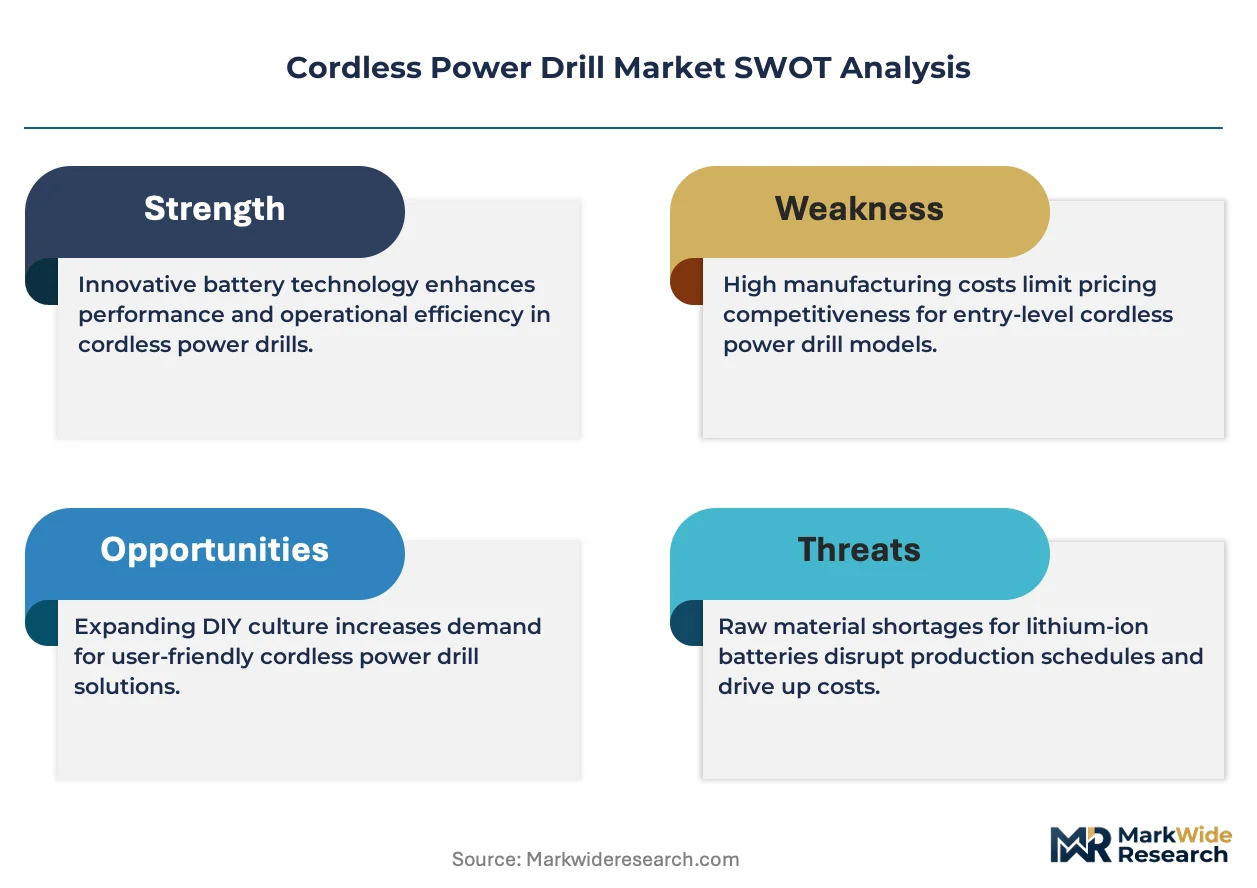
Growth Catalysts
- Residential renovation spending:DIY enthusiasts in North America and Western Europe are expanding tool ownership rates as home improvement project frequency rises post-pandemic.
- REACH directive compliance:European chemical disclosure mandates are accelerating nickel-cadmium phase-out and lithium-ion adoption across manufacturer lineups.
- Brushless motor efficiency:Thermal performance gains of 50% over brushed equivalents are extending runtime for contractor-grade applications.
Market Restraints
- Lithium supply concentration:Battery cell production concentrates in China, creating geopolitical exposure for brands dependent on imported power packs.
- Raw material volatility:Cobalt and lithium carbonate pricing fluctuations compress margin stability for mid-tier product lines.
- CE marking complexity:Extended testing timelines for electromagnetic compatibility slow new product introductions in European markets.
Strategic Opportunities
- India construction acceleration:Urban infrastructure investment and BIS certification alignment create entry pathways for brands establishing local assembly.
- Battery-as-a-service models:Subscription-based power pack programs are emerging in professional contractor channels to reduce upfront capital burden.
- Solid-state battery convergence:Next-generation cell chemistry paired with brushless architectures promises further energy density gains for heavy-duty applications.
Industry Challenges
- Motor control firmware expertise:Scarce embedded systems engineering talent delays brushless controller optimization and thermal management refinement.
- FCC certification bottlenecks:Electromagnetic testing queue lengths at accredited laboratories extend product launch timelines by four to six months.
- Reverse logistics complexity:Lithium-ion battery recycling mandates in multiple jurisdictions require investment in collection infrastructure and chemistry tracking systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cordless Power Drill Market |
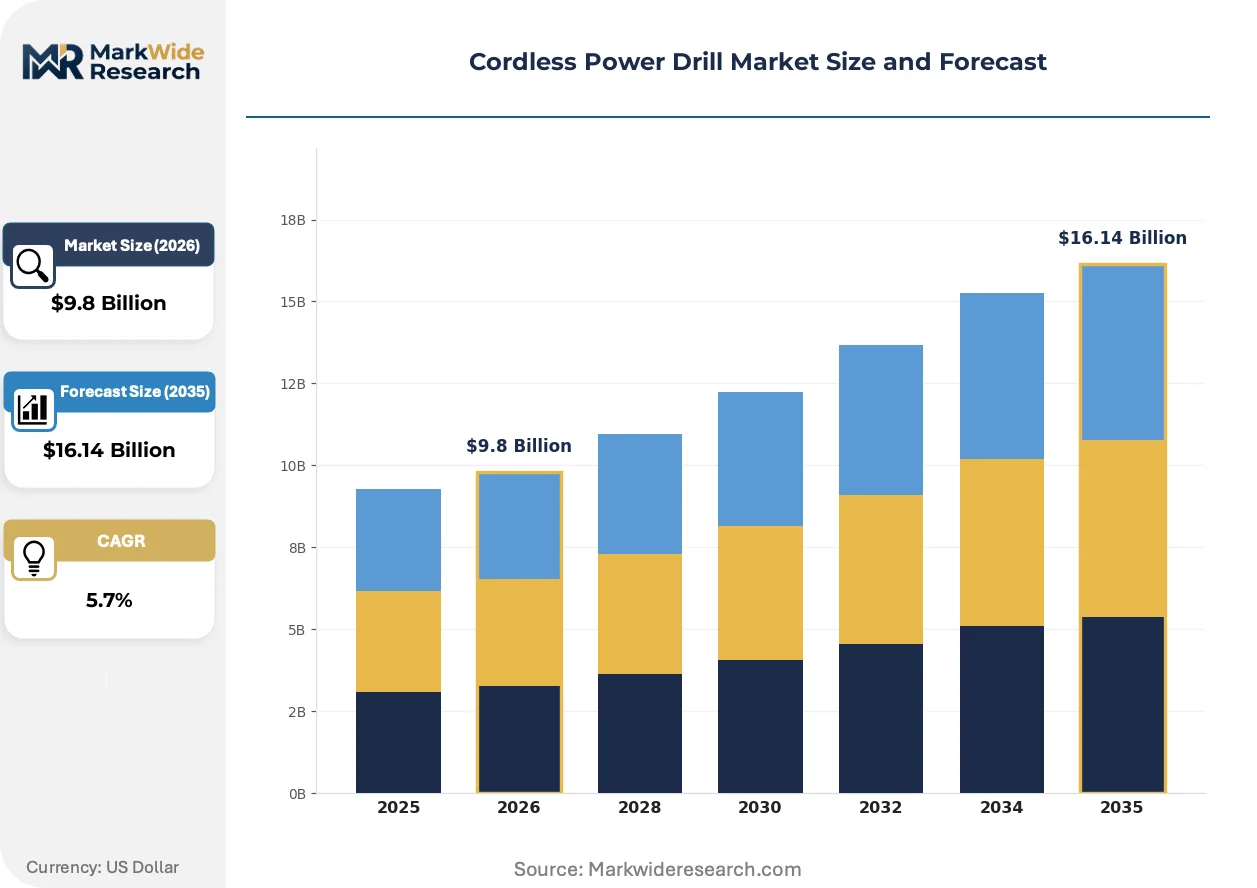
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $16.14 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brushless Motor Drill, Hammer Drill, Impact Driver, Angle Drill, SDS Drill, Rotary Hammer Battery Technology: Lithium-ion, Nickel-Cadmium, Nickel-Metal Hydride, Lithium Polymer, Zinc-Air Application: Home Improvement, Construction Sites, Woodworking, Metal Fabrication, Electrical Installation, Plumbing End User: Contractors, DIY Enthusiasts, Maintenance Crews, Specialty Technicians, Facility Managers |
| Companies Covered | DeWalt Industrial Tool Company, Makita Corporation, Robert Bosch GmbH, Milwaukee Electric Tool Corporation, Stanley Black & Decker, Inc., Techtronic Industries Co. Ltd., Hilti Corporation, Koki Holdings Co., Ltd., Festool GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cordless Power Drill Market Trends and Innovations
Power density optimization and regulatory chemistry mandates are forcing simultaneous hardware redesign and supply chain reconfiguration across the cordless tool sector.
Compact brushless motor architectures are miniaturizing stator and rotor assemblies while maintaining torque output above 100 Nm for professional-grade drills. Renovation contractors and facility maintenance teams are specifying these lighter configurations for overhead drilling applications. The reduction in motor mass is compressing tool chassis dimensions and enabling single-hand operation for previously two-handed tasks.
REACH Annex XVII restrictions on nickel-cadmium content are eliminating legacy battery chemistries from new product introductions across EU member states. Manufacturers must redesign battery management systems and thermal runaway protection to comply with updated ECHA substance restrictions. Professional-grade product lines face the steepest compliance costs due to higher cell counts and discharge rate requirements.
Direct-to-contractor e-commerce platforms are fragmenting traditional distributor relationships as buyers research specifications independently before purchasing. Big-box retail partners are responding with exclusive product variants and extended warranty bundles to defend shelf space. This channel tension is most acute in North American metropolitan markets where same-day delivery options from industrial supply aggregators have gained traction.
Cordless Power Drill Market Segmentation
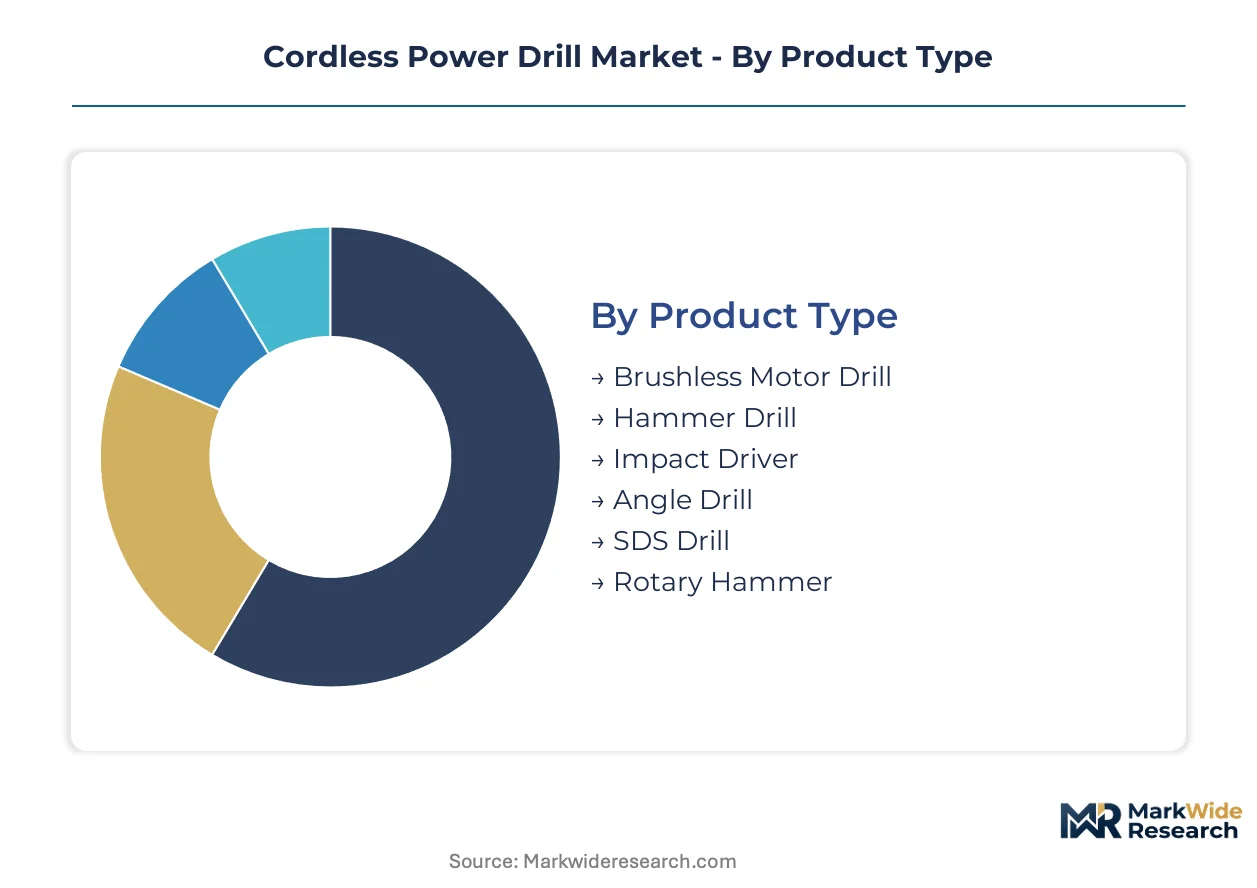
Segmentation in the cordless power drill market reveals how motor architecture, battery chemistry, and user workflow shape procurement patterns. Contractors prioritize runtime density and thermal management, while DIY purchasers weigh upfront cost against project frequency. Understanding these divides clarifies where manufacturers must defend margin versus chase volume.
Product Type:
Substitution pressure from cordless platforms threatens corded alternatives most acutely in hammer and rotary configurations, where battery energy density now satisfies intermittent heavy-duty cycles.
- Brushless Motor Drill:Electronic commutation eliminates brush friction losses, cutting heat generation by half versus brushed equivalents. Demand concentrates among renovation contractors in Germany and the United States who bill by project completion and cannot tolerate mid-job battery swaps. Thermal efficiency gains compress total cost of ownership calculations for fleet purchasers.
- Hammer Drill:Percussion mechanisms add axial impact to rotary motion for masonry penetration. Construction crews in India and China's tier-two cities specify these for reinforced concrete drilling where portable power outweighs corded convenience. The segment faces margin pressure from commoditized brushed motor variants in entry price bands.
- Impact Driver:Hex-collet fastening tools optimized for high-torque screw driving without reactionary kickback.
- Angle Drill:Offset gearheads enabling bore access in confined spaces between studs and joists.
- SDS Drill:Slotted drive system chucks accepting specialized masonry bits with active hammer action.
- Rotary Hammer:Pneumatic hammer mechanisms delivering sustained impact energy for demolition-scale concrete work.
Brushless motor drill configurations anchor the volume base while hammer drill variants gain share at the steepest rate.
Battery Technology:
Cost tier stratification separates professional-grade lithium-ion packs from residual nickel-cadmium inventory in developing market retail channels.
- Lithium-ion:Cobalt-oxide and iron-phosphate cathode chemistries dominate cell architectures, with cylindrical 18650 and 21700 form factors standardizing across major brands. REACH Annex XVII restrictions in the European Union and China's MIIT safety protocols are eliminating competitive alternatives for export-bound manufacturers. Cell production concentration in Fujian and Jiangsu provinces creates supply chain exposure for brands without captive battery assembly.
- Nickel-Cadmium:Legacy nickel-cadmium packs persist in price-sensitive retail segments where environmental regulations remain unenforced. Remaining demand concentrates in Southeast Asian hardware markets and African distributor channels where upfront cost dominates lifecycle calculations. Cadmium toxicity liabilities are forcing inventory liquidation by original equipment manufacturers.
- Nickel-Metal Hydride:Intermediate energy density chemistry occupying diminishing niche between lithium-ion performance and nickel-cadmium cost.
- Lithium Polymer:Pouch cell configurations enabling non-cylindrical pack geometries for ultra-compact tool designs.
- Zinc-Air:Experimental primary cell chemistry with theoretical energy density advantages but limited recharge cycle viability.
Lithium-ion technology captures the steepest expansion trajectory while nickel-cadmium retreats to residual replacement markets.
Application:
Customer type determines specification intensity, with commercial construction specifying torque reserves that residential users rarely exhaust.
- Construction Sites:General contracting applications demand IP-rated housings and all-weather battery performance. Demand concentrates in China's state-owned construction enterprises and India's infrastructure megaprojects where tool standardization reduces training overhead. Dust ingress protection and drop resistance certifications filter supplier eligibility.
- Home Improvement:Residential renovation and repair tasks favor lighter chassis weights and integrated work lights. DIY purchasers in the United States and United Kingdom drive seasonal demand spikes aligned with spring remodeling cycles. Retail bundling with accessory kits and extended warranties defends margin against online price transparency.
- Woodworking:Precision drilling and countersinking for furniture and cabinetry fabrication.
- Metal Fabrication:High-torque applications in steel and aluminum assembly with specialized cutting lubricants.
- Electrical Installation:Compact form factors for panel work and conduit fastening in commercial buildings.
- Plumbing:Corrosion-resistant housings for wet environment pipe installation and fixture mounting.
Home improvement anchors the volume base while construction site applications climb the fastest.
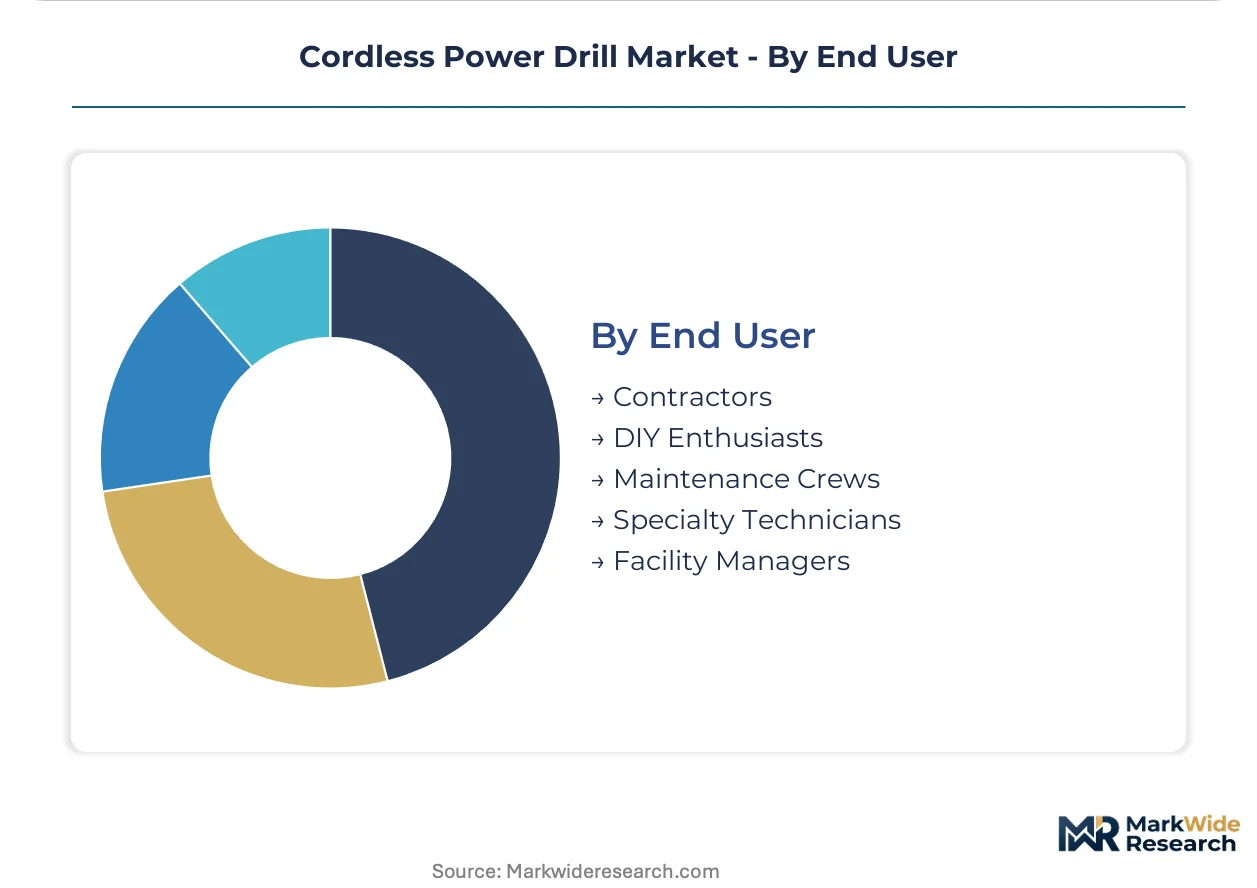
End User:
Procurement authority splits between fleet managers optimizing total cost of ownership and individual purchasers responding to point-of-sale promotion.
- Contractors:Professional tradespeople purchasing tools as revenue-generating capital equipment. Demand concentrates in Germany's mittelstand construction sector and Japan's specialized renovation cooperatives where brand loyalty reflects service network density. Fleet standardization on single battery platforms reduces charger inventory and simplifies field logistics.
- DIY Enthusiasts:Non-professional users acquiring tools for personal residential projects. Big-box retail partnerships in the United States and do-it-yourself superstores in France drive brand visibility and trial conversion. Social media tutorial content is expanding project ambition and tool specification expectations among this cohort.
- Maintenance Crews:In-house facility teams performing reactive and preventive building upkeep.
- Specialty Technicians:Niche installers of HVAC, security, and telecommunications infrastructure.
- Facility Managers:Procurement officers standardizing tool fleets across multi-site commercial property portfolios.
DIY enthusiasts anchor the volume base while contractors gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German contractors pay 40% premiums for brushless fleet standardization while Indonesian retail channels absorb nickel-cadmium liquidation inventory at 60% discounts. This pricing-power asymmetry reflects divergent regulatory enforcement and construction wage structures.
United States
Residential renovation spending by DIY enthusiasts sustains seasonal demand spikes aligned with spring remodeling cycles. FCC certification governs electromagnetic emissions for cordless power drills sold domestically. Tool demand concentrates in Texas and Florida metropolitan markets where suburban expansion drives home improvement project frequency.
Germany
Renovation contractors in the mittelstand construction sector prioritize fleet standardization on single battery platforms to reduce charger inventory. REACH Annex XVII restrictions and the EU's F-Gas Regulation accelerate nickel-cadmium phase-out and lithium-ion adoption. Industrial demand clusters in Bavaria and North Rhine-Westphalia where specialized renovation cooperatives maintain dense service networks.
China
State-owned construction enterprises and tier-two city development sustain high tool replacement rates across general contracting applications. MIIT regulations and GB standards enforce safety testing protocols for lithium-ion cell integration. Manufacturing output concentrates in Fujian and Jiangsu provinces where cell production creates supply chain exposure for brands without captive battery assembly.
India
Urban infrastructure investment and BIS certification alignment create entry pathways for brands establishing local assembly operations. The country's national construction regulator mandates safety equipment standards for public works projects. Demand clusters in Maharashtra and Gujarat where infrastructure megaprojects drive specification intensity for IP-rated housings.
Japan
Specialized renovation cooperatives maintain brand loyalty reflecting service network density and thermal management reliability. METI efficiency standards and JIS certification requirements shape product development priorities. Precision manufacturing concentrates in the Chubu region around Nagoya where compact brushless motor architectures serve overhead drilling applications.
Cordless Power Drill Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the cordless power drill industry. The vendor base clusters around three strategic tiers: integrated motor manufacturers commanding premium positioning, scaled Asian fabricators driving mid-tier cost discipline, and retail-channel specialists controlling North American distribution. Consolidation pressure intensifies as battery platform standardization and firmware expertise requirements raise barriers for marginal competitors. Dominant competitive moves include backward integration into brushless motor production and exclusive retail partnerships defending shelf space.
Among German-based industrial conglomerates, Robert Bosch GmbH and Festool GmbH exemplify the technology-leadership archetype through captive production systems. Makita Corporation anchors the scale-driven tier with manufacturing presence across multiple Asian facilities. Techtronic Industries Co. Ltd. occupies a position within the channel-control archetype, extending reach through simultaneous private-label and branded distribution strategies.
| Leading Market Players |
|---|
| DeWalt Industrial Tool Company |
| Makita Corporation |
| Robert Bosch GmbH |
| Milwaukee Electric Tool Corporation |
| Stanley Black & Decker, Inc. |
| Techtronic Industries Co. Ltd. |
| Hilti Corporation |
| Koki Holdings Co., Ltd. |
| Festool GmbH |
| Others |
Pricing and Supply Chain Analysis
Lithium-ion cell chemistry substitution for nickel-cadmium packs simultaneously concentrates supply geography in China's Fujian and Jiangsu provinces and compresses pricing economics for mid-tier product lines dependent on imported power packs. REACH Annex XVII restrictions and China's MIIT safety protocols eliminate competitive alternatives, tethering brand margins to volatile cobalt and lithium carbonate input costs.
Pricing Analysis
The customization-premium spread separates configured-to-order brushless fleet packages from standard retail SKUs. Three-tier pricing structure across premium, standard, and economy levels reflects motor architecture sophistication and battery platform compatibility. Cost compression in entry-tier brushed motor variants intensifies because Chinese OEMs flood Southeast Asian channels with liquidated nickel-cadmium inventory. DIY enthusiasts exhibit highest price sensitivity, while German renovation contractors absorb 40% premiums for thermal efficiency and runtime density.
Supply Chain Analysis
Strait of Malacca transit underwrites cylindrical cell delivery from Chinese gigafactories to ASEAN assembly plants. Battery cell production concentrates in China, South Korea, and Japan, with brushless motor stators sourcing from Japanese precision manufacturers and Chinese rare-earth processors. Single-source vulnerability in lithium hydroxide refining creates exposure for brands without captive cathode material agreements. Distribution runs through big-box retail partnerships in North America and specialized industrial distributors in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brushless motor efficiency gains and REACH-mandated chemistry transitions constitute a dual inflection disrupting competitive hierarchies across the cordless power tool sector. Manufacturers and capital allocators must reposition around firmware expertise and battery platform control.
For Market Incumbents: Fortify backward integration into brushless motor production to defend premium positioning against scaled Asian fabricators. Captive controller firmware development and thermal management IP create switching costs for contractor fleet standardization. Prioritize exclusive retail partnerships in North American metropolitan markets where same-day delivery aggregators threaten distributor relationships.
For New Entrants and Emerging Players: Anchor in India's BIS-certified local assembly pathways for infrastructure megaprojects in Maharashtra and Gujarat. Battery-as-a-service subscription models for professional contractor channels reduce upfront capital barriers and bypass established brand loyalty. Target facility management procurement officers standardizing multi-site commercial portfolios with compact brushless architectures for overhead applications.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed mid-tier fabricators lacking lithium-ion cell integration. Five-to-ten-year viability hinges on solid-state battery convergence timelines and brushless controller optimization capabilities. Monitor FCC certification queue lengths at accredited laboratories as an inflection indicator for new product introduction velocity and working capital efficiency.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brushless Motor Production | Captive stator and rotor manufacturing secures thermal efficiency IP and defends contractor-grade pricing power. |
| Battery Platform Standardization | Fleet-wide charger compatibility reduces field logistics overhead for German mittelstand construction cooperatives. |
| Direct-to-Contractor E-commerce Launch | Bypassing traditional distributors captures specification research behavior among independent tradespeople. |
| Solid-State Battery R&D Partnership | Next-generation cell chemistry paired with brushless architectures promises energy density gains for heavy-duty rotary hammers. |
| Local Assembly in India | BIS certification alignment and proximity to Maharashtra infrastructure megaprojects reduce import duty exposure. |
Research Methodology
Desk research of customs trade data, MIIT battery safety filings, and REACH Annex XVII substance restriction updates preceded structured interviews with OEM procurement directors, aftermarket service heads, and industrial distributor category managers. Primary fieldwork with renovation contractors in Germany and facility maintenance directors in the United States validated specification intensity and fleet standardization behavior. Secondary sources included SEC 10-K disclosures, ECHA chemical inventory databases, and GB standards documentation. Bottom-up demand modeling triangulated against top-down construction spending forecasts.
Variance decomposition across motor architecture, battery chemistry, and end-user procurement authority shaped analytical framework construction over the projection horizon. Segmentation dimensions modeled included product type, battery technology tier, application intensity, and regional regulatory cluster. CAGRs derived from weighted average of historical replacement cycle compression and forward-looking brushless adoption curves. Industry-specific inputs incorporated lithium carbonate price volatility indices and FCC certification timeline distributions.
Material uncertainties — cobalt supply concentration, REACH enforcement variance across EU member states, and solid-state battery commercialization delays — sit outside the modeled envelope. Forecasts reflect assumptions on contractor fleet refresh rates and DIY project frequency persistence. Practitioners should keep alternative scenarios live as F-Gas Regulation amendments and China's dual carbon goals evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Laser Engraving Machine Market
Tools
Striking Tools Market
Tools
Fastening Power Tools Market
Tools
Assembly Fastening Tool Market
Tools
Technical Drawing Tools Market
Tools
Brazing Torch Market
Tools
Tool Hammer Market
Tools
Automatic Heat Press Machines Market
Tools
Fixed Cutter Bits Market
Tools
Floor Scraper Market
Tools
Diamond Hole Saw Market
Tools
Garden Digging Tools Market
Tools
Power Tool Gears Market
Tools
Quick Release Pins Market
Tools
Air Hammer Market
Tools
Global Tool Holder Adapters Market