
 Thickness Planers Market | 2026-2036
Thickness Planers Market Size, Share, and Industry Trends Forecast 2026-2036
Thickness Planers Market Analytics
Equipment leasing and asset-light operating models is rewriting competitive dynamics for smaller woodworking enterprises that previously avoided capital-intensive machinery purchases. Makita leverages its cordless power tool ecosystem to extend brand loyalty into benchtop planer categories. Felder anchors premium positioning through Austrian-built industrial planer-molder combinations. Grizzly Industrial competes on catalog breadth and direct-to-shop pricing across portable and stationary configurations.
A thickness planer is a woodworking machine that employs a rotating cutterhead with multiple knives to remove material from the underside of a board while a feed mechanism advances stock past the blades, producing uniform dimensional thickness across variable raw lumber. Its primary industrial purpose is dimensioning rough-sawn timber to precise specifications for furniture, flooring, and millwork production. Stationary planers dominate margin pools in high-volume furniture manufacturing, while portable planers sustain growth among construction contractors performing finish carpentry on job sites. The compact size tier captures hobbyist spending through benchtop electric units, though industrial-grade large machines concentrate aftermarket revenue from cutterhead replacement and spiral knife upgrades.
OSHA machine guarding regulations mandate emergency stop systems and chip collection enclosures, pushing manufacturers toward integrated dust management designs. The EU Machinery Directive and CE marking requirements enforce noise limits and operator safety interlocks that add engineering cost but create barrier to entry for low-cost imports. Stakeholders must monitor evolving ISO standards for wood dust exposure limits, as these will determine whether centralized extraction systems or self-contained filtration becomes the dominant product architecture.
Market Dynamics
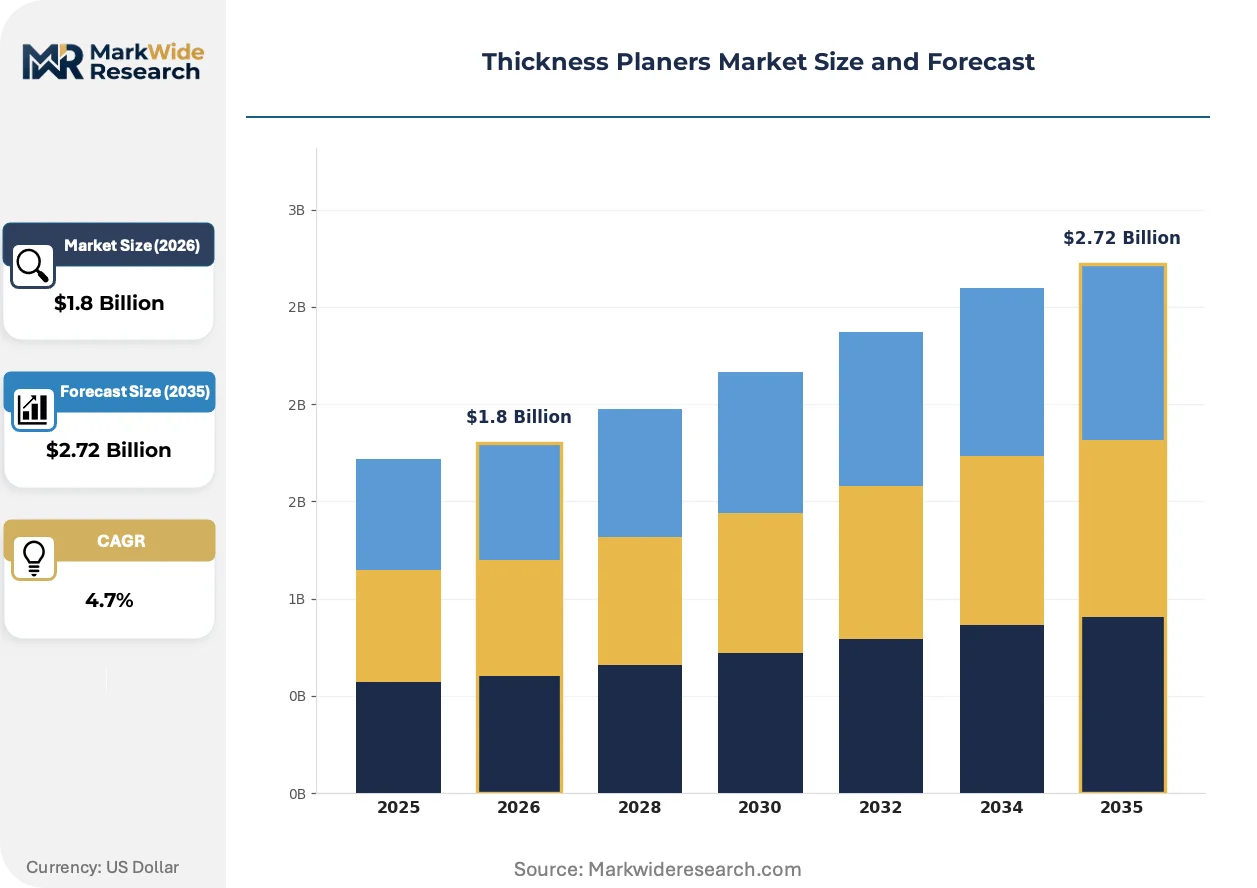
Equipment leasing models are dismantling capital barriers for small woodworking shops while OSHA and EU machinery directives force redesigns of cutterhead guarding and dust extraction systems, compressing margins for manufacturers serving price-sensitive segments.
Growth Catalysts
- Furniture Manufacturing Expansion:Precision-milled component demand from cabinet and flooring producers drives replacement cycles for high-capacity stationary units in industrial woodworking clusters.
- OSHA Machine Guarding Standards:Mandated emergency stop systems and chip collection enclosures push integrated safety designs that command premium positioning in professional segments.
- EU Machinery Directive Enforcement:CE marking requirements for noise limits and operator safety interlocks create technical barriers that protect established European manufacturers from low-cost import competition.
Market Restraints
- Steel and Cast Iron Input Volatility:Foundry capacity constraints and energy costs for ductile iron bed castings compress margins on mid-tier stationary planer production.
- German Industrial Cluster Concentration:Stuttgart and Hannover regions anchor high-capacity replacement demand, creating geographic revenue concentration risk for suppliers dependent on Central European automotive-furniture supply chains.
- Spiral Cutterhead Substitution Pressure:Carbide insert systems extend service intervals versus traditional HSS knife setups, threatening aftermarket blade revenue streams for legacy equipment installed bases.
Strategic Opportunities
- Equipment-as-a-Service Penetration:Asset-light leasing models unlock contractor and small-shop segments previously excluded by capital intensity, particularly in North American construction finish carpentry.
- ISO Wood Dust Exposure Alignment:Evolving international standards for airborne particulate limits favor centralized extraction architectures that integrate planer, jointer, and table saw ventilation through common manifold designs.
- Cordless Power Tool Ecosystem Convergence:Battery platform compatibility with existing jobsite tool inventories enables portable planer category entry for construction contractors without redundant charging infrastructure.
Industry Challenges
- Mechatronics Skill Scarcity:Servo-feed mechanism calibration and variable-frequency drive programming exceed traditional millwright training, forcing manufacturers to internalize field service capabilities.
- CE Certification Timeline Compression:Notified body backlogs for machinery directive conformity assessment delay product launches by 8-14 months, penalizing development schedules for modular planer-molder combinations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thickness Planers Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Planers, Manual Planers, Portable Planers, Stationary Planers End User: Woodworking Shops, Furniture Manufacturers, Construction Contractors, Hobbyists Size: Compact, Medium, Large, Industrial Mechanism: Planer Molding, Thicknessing, Reversible, Joinery |
| Companies Covered | DeWalt, Makita, JET, WEN, Grizzly Industrial, Scheppach, Triton, Lumberjack, Felder, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thickness Planers Market Evolving Landscape
Digital feed control systems and automated thickness sensing are transforming operator workflows while regulatory pressure on airborne particulates reshapes ventilation integration requirements across industrial and portable product tiers.
Helical cutterhead technology with four-sided carbide inserts is digitizing surface finish consistency and reducing tear-out on figured hardwoods. High-end furniture manufacturers in Italy and Japan are specifying these systems for figured walnut and curly maple processing. The technology is digitizing quality control workflows by eliminating manual feed rate adjustments previously required for grain direction changes.
The EU F-Gas Regulation and associated refrigerant phase-down measures are pressuring manufacturers to eliminate hydrofluorocarbon-based cooling systems from motor thermal management designs. Industrial planer producers are migrating to liquid-cooled permanent magnet motors or passive heat sink architectures. German and Austrian equipment builders face the steepest redesign costs due to their concentration of high-horsepower three-phase induction motor legacy platforms.
Job site rental and short-term equipment subscription models are displacing traditional distributor inventory financing for portable planer procurement. Construction contractors in the United States and Australia increasingly source benchtop units through national rental chains for specific project phases rather than capitalizing permanent shop equipment. This shift concentrates purchasing influence with procurement teams at United Rentals and Sunbelt rather than individual woodworking subcontractors.
Thickness Planers Market Segmentation
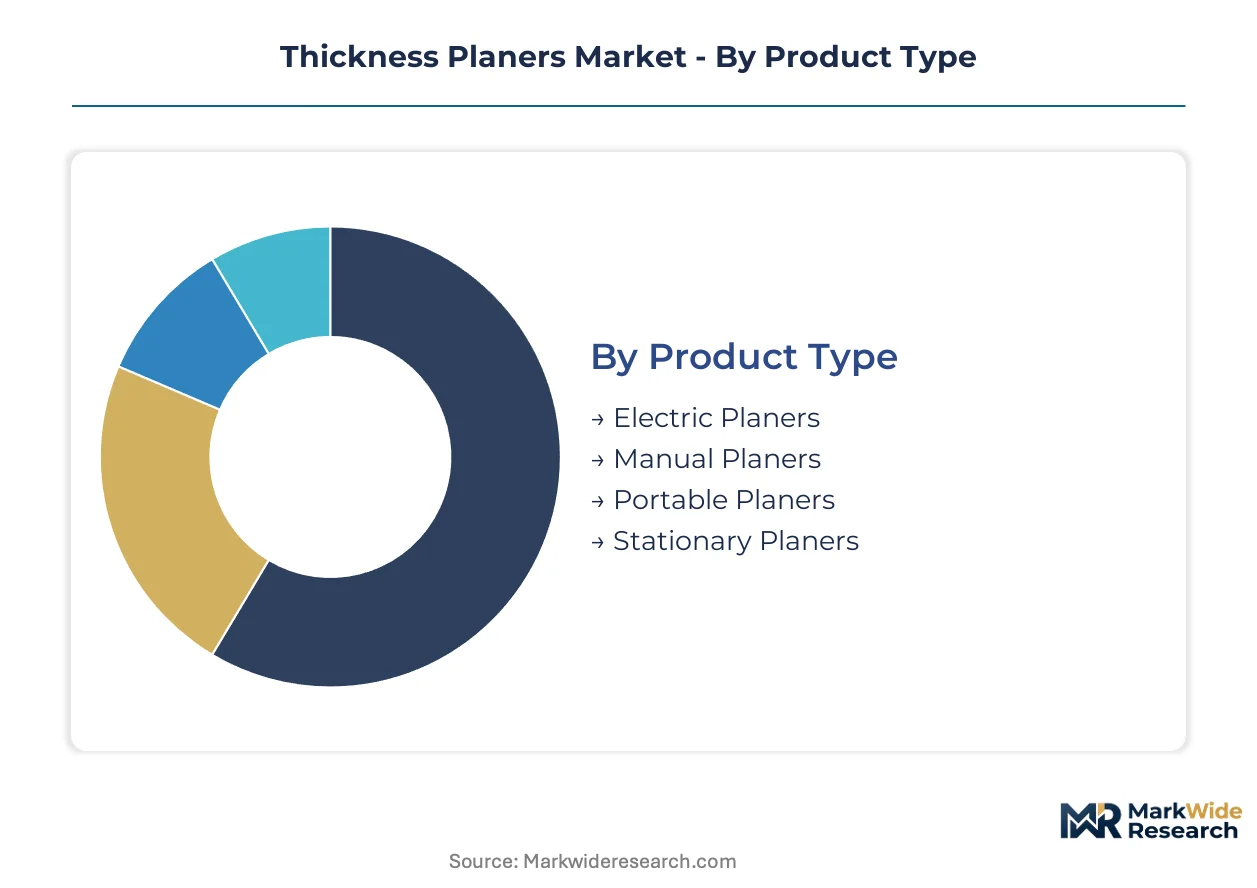
Segmentation in thickness planers reveals how capital intensity, workspace constraints, and regulatory exposure split demand across divergent equipment tiers. Each dimension—product type, end user, size, and mechanism—carries distinct margin profiles and aftermarket revenue potential that reshape competitive positioning.
Product Type:
Cost tier differentiation separates hobbyist-accessible units from industrial-grade systems with integrated dust management and helical cutterhead architectures.
- Electric Planers:Corded and cordless motor platforms power benchtop and handheld units through brushed or brushless architectures. Demand clusters among construction contractors in North American finish carpentry segments where Makita's 18V LXT battery ecosystem reduces redundant charging infrastructure.
- Stationary Planers:Cast iron bed designs with three-knife cutterheads and variable-frequency drive feed systems dominate high-volume furniture manufacturing. German industrial clusters around Stuttgart and Hannover drive replacement cycles for 20-inch and wider capacity units with spiral cutterhead upgrades.
- Manual Planers:Hand-powered steel body designs with adjustable frog mechanisms serve restoration specialists and traditional craft training programs. Japanese pull-stroke variants maintain niche demand among bespoke furniture makers.
- Portable Planers:Jobsite-configured units with folding infeed/outfeed tables and wheeled bases target contractors performing millwork installation. United Rentals and Sunbelt procurement teams increasingly specify these for short-term project deployment.
Stationary planers hold installed capacity. Portable planers are rotating up the share rankings.
End User:
Application focus determines whether buyers prioritize dust extraction integration, cutterhead serviceability, or cordless platform compatibility.
- Furniture Manufacturers:Precision-milled component producers in Italy and Japan specify helical cutterhead systems for figured walnut and curly maple processing. ISO wood dust exposure compliance drives centralized extraction manifold designs integrating planer, jointer, and table saw ventilation.
- Construction Contractors:Finish carpentry crews on commercial and residential job sites demand battery-compatible benchtop units with automated thickness sensing. Equipment-as-a-Service leasing models unlock segments previously excluded by capital intensity.
- Woodworking Shops:Small-to-mid capacity operations balance spiral cutterhead upgrade costs against reduced HSS knife maintenance. OSHA machine guarding mandates push these buyers toward integrated emergency stop and chip enclosure designs.
- Hobbyists:Entry-level benchtop electric units with fixed cutterheads and limited dust port connectivity dominate consumer retail channels. Price sensitivity limits attachment rates for carbide insert upgrades.
Furniture manufacturers hold installed capacity. Construction contractors are rotating up the share rankings.
Size:
Volume throughput and bed casting weight define four distinct equipment classes with divergent foundry input exposure and freight economics.
- Industrial:24-inch and wider capacity units with three-phase permanent magnet motors and liquid-cooled thermal management serve mass production flooring mills. EU F-Gas Regulation pressures German and Austrian builders to eliminate hydrofluorocarbon-based cooling from legacy induction motor platforms.
- Large:15-to-20-inch capacity stationary designs with segmented infeed rollers and digital thickness displays anchor mid-tier professional shops. Steel and cast iron input volatility compress margins on ductile iron bed production.
- Medium:12-to-15-inch benchtop and floor-standing hybrids target serious hobbyists and small commercial operations. Carbide insert spiral systems extend service intervals versus traditional HSS setups, threatening aftermarket blade revenue.
- Compact:6-to-12-inch portable and benchtop units with single-speed direct drive motors dominate entry-level procurement. Cordless power tool ecosystem convergence enables category entry without redundant charging infrastructure.
Industrial units hold installed capacity. Compact units are rotating up the share rankings.
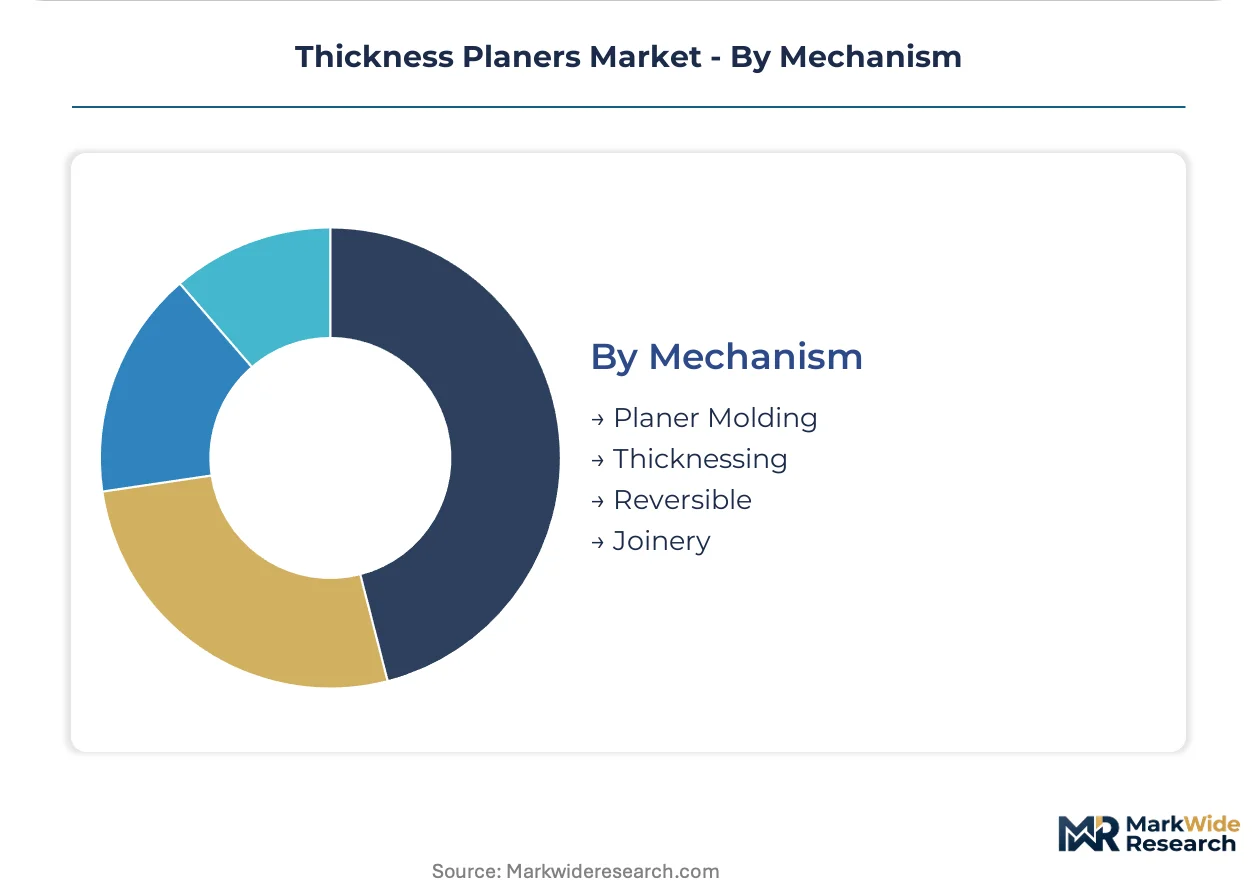
Mechanism:
Functional specialization determines whether equipment serves dimensioning, surfacing, or combined operations with corresponding cutterhead complexity.
- Thicknessing:Dedicated material removal systems with bottom-mounted cutterheads and pressure bar feed mechanisms produce uniform dimensional stock from rough-sawn timber. Furniture and flooring producers drive specification for automated thickness sensing variants.
- Planer Molding:Combination machines with interchangeable cutterhead profiles for raised panels, crown molding, and architectural millwork command premium positioning. CE certification timeline compression for modular designs penalizes Austrian and German development schedules.
- Reversible:Dual-function units switching between thicknessing and jointer configurations through tilting bed or cutterhead repositioning. Space-constrained European workshops favor these for footprint efficiency.
- Joinery:Specialized tongue-and-groove, rabbet, and dado cutting attachments for flooring and cabinet assembly. Demand concentrates in hardwood flooring mills requiring precise edge preparation.
Thicknessing systems hold installed capacity. Planer molding configurations are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in woodworking machinery tilt toward surplus in precision-manufacturing economies while deficit markets absorb portable equipment through distributor channels. Germany and Italy anchor high-value stationary planer shipments to furniture manufacturing clusters across Asia and North America. Tariff exposure on steel castings and motor assemblies is reshaping regional sourcing strategies for mid-tier producers.
Germany
Stuttgart and Hannover industrial clusters drive replacement cycles for 20-inch capacity stationary units with helical cutterhead specifications. CE marking requirements under the EU Machinery Directive enforce noise limits and safety interlocks that protect domestic manufacturers from low-cost import competition. Felder and other Austrian-German equipment builders concentrate premium planer-molder production in Baden-Württemberg and Bavaria.
United States
Construction contractors in Texas and Florida demand battery-compatible portable planers for finish carpentry on commercial job sites. OSHA machine guarding standards mandate emergency stop systems and chip collection enclosures that add engineering cost to imported equipment. Equipment-as-a-Service leasing models through United Rentals and Sunbelt concentrate purchasing influence in the Southeast and Southwest construction corridors.
Italy
High-end furniture manufacturers in Lombardy and Veneto specify helical cutterhead systems for figured walnut and curly maple processing. REACH compliance for surface coatings and lubricants adds regulatory overhead to export-bound equipment. The Brianza furniture district north of Milan anchors precision-milled component demand that drives specification for automated thickness sensing variants.
Japan
Pull-stroke manual planer variants maintain niche demand among bespoke furniture makers in Tokyo and Osaka metropolitan areas. METI industrial standards for woodworking machinery safety create technical barriers for non-domestic suppliers. The Higashikawa woodworking cluster in Hokkaido sustains traditional craft training programs that preserve hand-powered steel body planer techniques.
China
Mass production flooring mills in the Yangtze River Delta absorb industrial-grade 24-inch capacity units for hardwood processing. GB standards for machinery safety and electromagnetic compatibility delay product launches for European and North American exporters. Zhejiang and Jiangsu provinces concentrate foundry capacity for ductile iron bed castings that supply both domestic and export-oriented planer assembly.
Thickness Planers Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in cutterhead, feed mechanism, and motor supply. The vendor base organizes around three strategic archetypes: cordless power tool ecosystem extenders, premium industrial equipment builders, and catalog breadth competitors serving price-sensitive segments. Austrian and German manufacturers leverage CE certification complexity as defensive moats. Asian fabricators compete on foundry integration and motor assembly scale. Consolidation pressure concentrates in the portable segment where rental channel procurement favors national account suppliers.
Within the premium industrial tier, Felder exemplifies Austrian-built positioning through planer-molder combinations. Makita anchors the cordless ecosystem archetype, extending 18V LXT battery platform loyalty into benchtop categories. Grizzly Industrial occupies the catalog breadth position, competing on direct-to-shop pricing across portable and stationary configurations.
| Leading Market Players |
|---|
| DeWalt |
| Makita |
| JET |
| WEN |
| Grizzly Industrial |
| Scheppach |
| Triton |
| Lumberjack |
| Felder |
| Others |
Value Network & Pricing Analysis
Zhejiang and Jiangsu foundry clusters anchor ductile iron bed casting supply for stationary planer manufacturers, with their capacity utilization rates directly transmitting into pricing power for mid-tier equipment builders serving North American and European distributors.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on CE certification grade and helical cutterhead specification, with Austrian and German builders commanding brand premiums for planer-molder combinations. Cost compression in standard-tier benchtop units is intensifying because of cordless platform commoditization among construction contractors. Hobbyist segments exhibit highest price sensitivity, while furniture manufacturers demonstrate lowest sensitivity to upfront capital outlay.
Supply Chain Analysis
EU Machinery Directive technical barriers and associated CE marking requirements limit equipment flows from non-compliant Asian fabricators, protecting established European manufacturers. Foundry capacity concentrates in China, Germany, and Austria, with steel and cast iron input volatility threatening margin stability. Raw material dependencies center on ductile iron bed castings, carbide insert blanks, and permanent magnet motor assemblies. Single-source vulnerability runs through helical cutterhead machining centers concentrated in Baden-Württemberg. Distribution runs through industrial machinery distributors in Europe and rental channel procurement teams in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
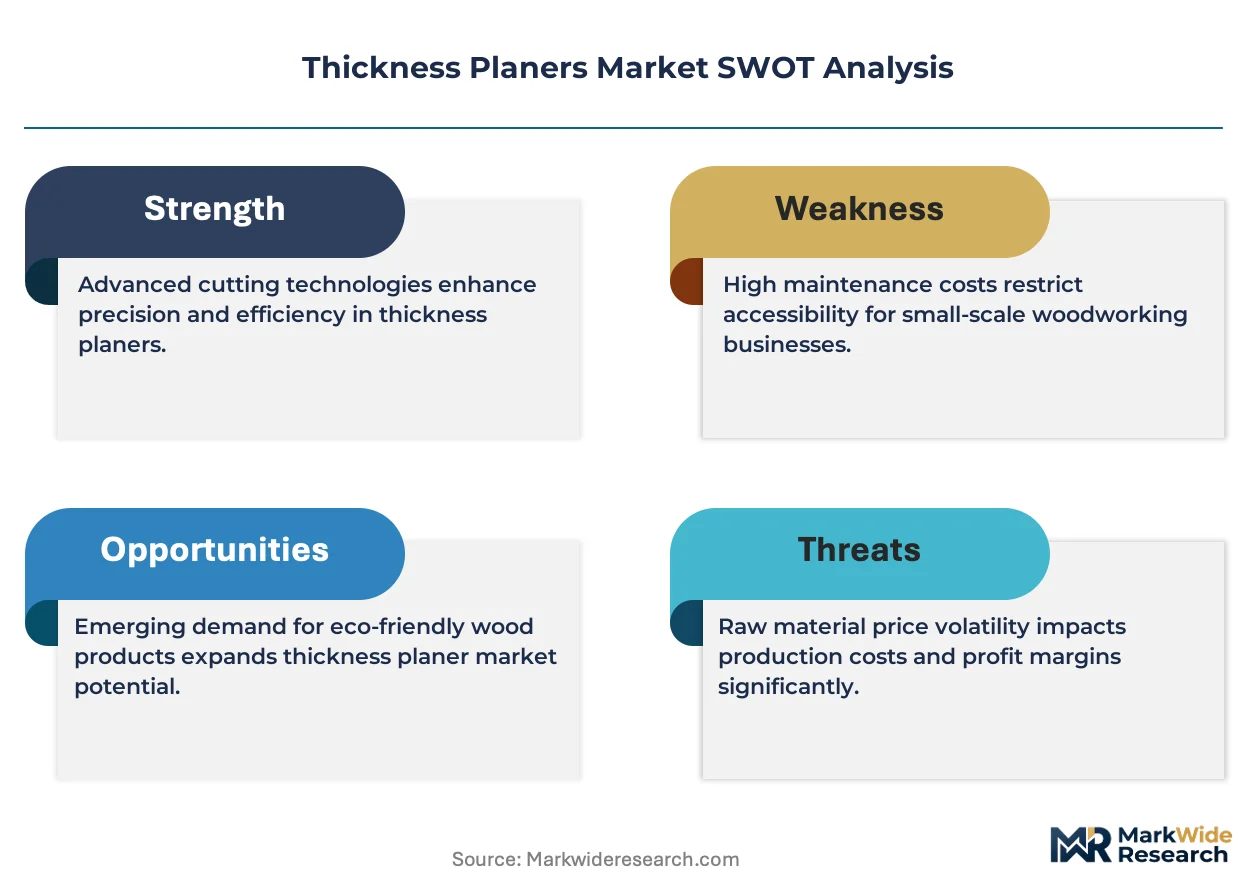
Spiral cutterhead substitution pressure threatens legacy HSS knife aftermarket revenue, forcing incumbents to defend installed base relationships while new entrants exploit cordless ecosystem gaps.
For Market Incumbents: Harden service network density in German industrial clusters to capture helical cutterhead upgrade cycles. Deepen backward integration into carbide insert supply through captive machining capacity, insulating margin from raw material volatility. Prioritize CE certification pipeline acceleration to outpace notified body backlogs threatening product launch timelines. For New Entrants and Emerging Players: Pursue equipment-as-a-service penetration among North American construction contractors excluded by traditional capital intensity. Target battery-compatible benchtop segments where Makita ecosystem loyalty has not yet fully consolidated. Deploy through United Rentals and Sunbelt national account structures rather than fragmented subcontractor direct sales. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors helical cutterhead specialists with established Italian and Japanese furniture industry relationships. Long-term viability hinges on aftermarket service revenue capture rather than equipment shipment volume alone. Monitor ISO wood dust exposure standard evolution as inflection indicator for centralized extraction system demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Helical Cutterhead Platform Migration | Italian furniture manufacturers specify carbide insert systems for figured hardwood processing. |
| Battery Ecosystem Convergence | Makita 18V LXT compatibility reduces redundant charging infrastructure for contractors. |
| Equipment-as-a-Service Expansion | United Rentals procurement teams concentrate purchasing influence for short-term project deployment. |
| CE Certification Pipeline Investment | Notified body backlog reduction accelerates planer-molder combination launch timelines. |
| Centralized Extraction Integration | ISO wood dust compliance favors manifold designs integrating planer, jointer, and table saw ventilation. |
Research Methodology
The analysis maps stationary planer, portable planer, and benchtop electric sub-sectors, each validated through maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads. Primary interview findings triangulated against customs and trade data, SEC 10-K filings, woodworking machinery association reports, and distributor inventory records. Bottom-up equipment shipment aggregation reconciled with top-down furniture manufacturing capacity expansion estimates.
Assumptions held fixed include OSHA machine guarding standard enforcement timelines and EU F-Gas Regulation phase-down schedules, while steel casting input costs and rental channel penetration rates varied across sensitivity scenarios. Segmentation modeling incorporated product type, end user, size tier, and cutterhead mechanism dimensions. CAGRs derived from replacement cycle analysis in German industrial clusters and greenfield capacity additions in North American construction corridors.
Sensitivities concentrate around foundry capacity constraints, notified body certification delays, and cordless platform standardization outcomes. Forecasts reflect documented assumptions regarding helical cutterhead substitution velocity and equipment-as-a-service adoption curves. Material shifts in ISO wood dust exposure limits or EU Machinery Directive enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Horizontal Milling Machine Market
Tools
Machine Vise Market
Tools
Mold Racks Market
Tools
Portable Grinders Market
Tools
Edge Banding Machine Market
Tools
Telescopic Tool Boxes Market
Tools
Woodworking Tools Market
Tools
Power Tools Market
Tools
Global Scarifiers Market
Tools
3D Milling Machines Market
Tools
Vise-Grip Pliers Market
Tools
Garden Digging Tools Market
Tools
Boring-Milling Machines Market
Tools
Gear Honing Machines Market
Tools
Global Standard Parts for Tool Making Market
Tools
Edging Tool Market