
 Wood-Sanding Machine Market | 2026-2036
Wood-Sanding Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Wood-Sanding Machine Market Analytics
Germany is narrowing its historic capacity advantage in precision abrasive machinery as Asian producers scale automated lines. Bosch leverages its power-tool ecosystem to sustain brand loyalty among professional woodworkers across European retail channels. Festool differentiates through premium dust-extraction integration that anchors its positioning in high-end cabinetry workshops. Makita competes on battery-platform compatibility, extending its cordless dominance into job-site sanding applications.
A wood-sanding machine is a powered abrasive-finishing device that uses rotating belts, discs, drums, or orbital pads to remove material from timber surfaces, typically operating at speeds between 3,000 and 12,000 RPM depending on the substrate hardness and desired finish quality. Its primary industrial purpose is to prepare lumber and engineered panels for coating, laminating, or final assembly by achieving precise thickness tolerances and surface smoothness. Belt sanders occupy the largest installed base among product types due to their throughput advantage in dimensioning operations, while orbital sanders capture expanding share in fine-finish furniture manufacturing where swirl-free output commands price premiums. The electric technology segment leads volume but pneumatic systems retain margin pools in heavy-duty industrial settings where sustained load duty cycles exceed motor durability limits.
ISO 19085 safety standards for woodworking machinery and the EU Machinery Directive 2006/42/EC shape product design by mandating emergency-stop integration, noise reduction, and dust-collection interface specifications that increase engineering costs but also filter out low-cost non-compliant imports. EPA particulate-matter regulations in the United States and REACH chemical restrictions on abrasive coatings in Europe further constrain material choices and supplier qualification. Stakeholders must monitor how evolving silica-exposure thresholds and carbon-border adjustment mechanisms reshape total cost of ownership calculations for equipment sourcing decisions.
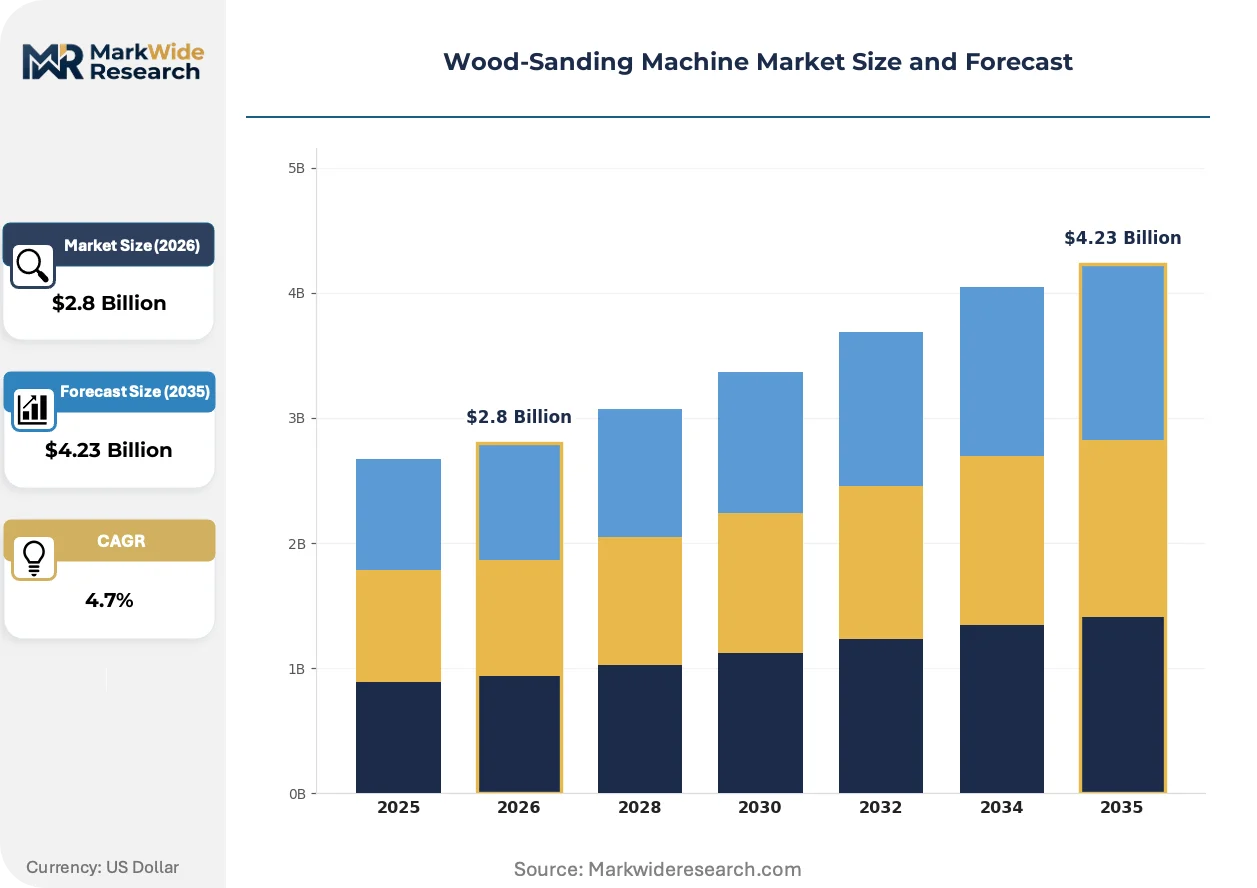
Market Dynamics
Automation in wide-belt sanding systems is compressing labor dependency across European and North American furniture manufacturing, as ISO 19085 safety mandates and EU Machinery Directive 2006/42/EC compliance costs filter out manual-equipment suppliers.
Growth Catalysts
- EU Machinery Directive 2006/42/EC:Mandatory emergency-stop integration and dust-collection interfaces are accelerating replacement cycles among German and Italian panel producers seeking certified equipment.
- Engineered wood substrates:Cross-laminated timber and medium-density fiberboard expansion in North American construction is pulling precision thickness-calibration demand from commercial millwork shops.
- Robotic load/unload integration:Automated material handling in high-volume German cabinetry lines is extending machine utilization rates beyond traditional shift boundaries.
Market Restraints
- Abrasive belt cost volatility:Ceramic and zirconia alumina raw material prices fluctuate with energy-intensive fused-mineral production concentrated in China's Henan province.
- REACH chemical restrictions:European coatings regulations on phenol-formaldehyde resin binders constrain abrasive belt sourcing to qualified suppliers with ECHA-registered formulations.
- Pneumatic infrastructure dependency:Heavy-duty industrial drum sanders require compressed-air systems that limit retrofit potential in electrically-dominant North American job shops.
Strategic Opportunities
- Indian furniture manufacturing clusters:Tamil Nadu and Gujarat export-oriented woodworking zones show underpenetrated automated-finishing adoption as BIS machinery safety standards mature.
- Battery-platform convergence:Cordless orbital sander compatibility with existing construction-tool ecosystems opens job-site finishing applications previously served by pneumatic equipment.
- Carbon Border Adjustment Mechanism:EU import levies on embodied carbon are creating first-mover advantage for European-manufactured wide-belt systems with verified lifecycle emissions data.
Industry Challenges
- Mechatronics technician scarcity:Servo-driven sanding head calibration and PLC programming skills lag demand in Midwestern US industrial woodworking corridors.
- Legacy dust-collection retrofit complexity:Existing central vacuum systems in older European facilities often lack airflow capacity for wide-belt sanders with integrated extraction hoods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wood-Sanding Machine Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Belt Sanders, Orbital Sanders, Disc Sanders, Drum Sanders End User: Woodworking Shops, Furniture Manufacturers, DIY Enthusiasts, Construction Contractors Technology: Electric, Pneumatic, Hydraulic, Manual Size: Compact, Standard, Industrial, Heavy-Duty |
| Companies Covered | Ingersoll Rand, Bosch, Makita, DEWALT, BLACK & DECKER, Timesavers, Festool, 3M Company, Hutchins Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wood-Sanding Machine Market Evolving Landscape
Sensor-integrated abrasive finishing is compressing quality-variance tolerance bands while regulatory pressure on occupational silica exposure is forcing equipment redesign across industrial woodworking.
Machine-vision surface inspection paired with real-time belt-pressure adjustment is rendering obsolete manual operator judgment in thickness-calibration operations. High-volume German panel producers are adopting these closed-loop systems fastest, with several Bavarian facilities completing full-line retrofits within eighteen-month windows. The technology is rendering obsolete traditional wide-belt sanders dependent on periodic manual gauge verification, compressing capital-equipment replacement cycles toward five-year horizons.
REACH restrictions on crystalline silica in abrasive coatings are compelling reformulation of ceramic grain bonding agents across European supply chains. ECHA-registered alternatives using engineered ceramic oxides now dominate new-equipment specifications from Italian and Spanish OEMs. German precision-machinery specialists face the steepest compliance cost absorption, as their premium positioning depends on abrasive longevity claims now requiring renewed toxicological dossier submission.
Leasing-based equipment procurement is displacing outright purchase among North American custom-furniture manufacturers facing working-capital constraints. Cincinnati and High Point job shops increasingly bundle sanding equipment with maintenance and abrasive-supply contracts through distributor finance arms. This shift concentrates most visible in mid-Atlantic states where commercial-bank equipment-lending terms have tightened relative to manufacturer-captive financing.
Wood-Sanding Machine Market Segmentation
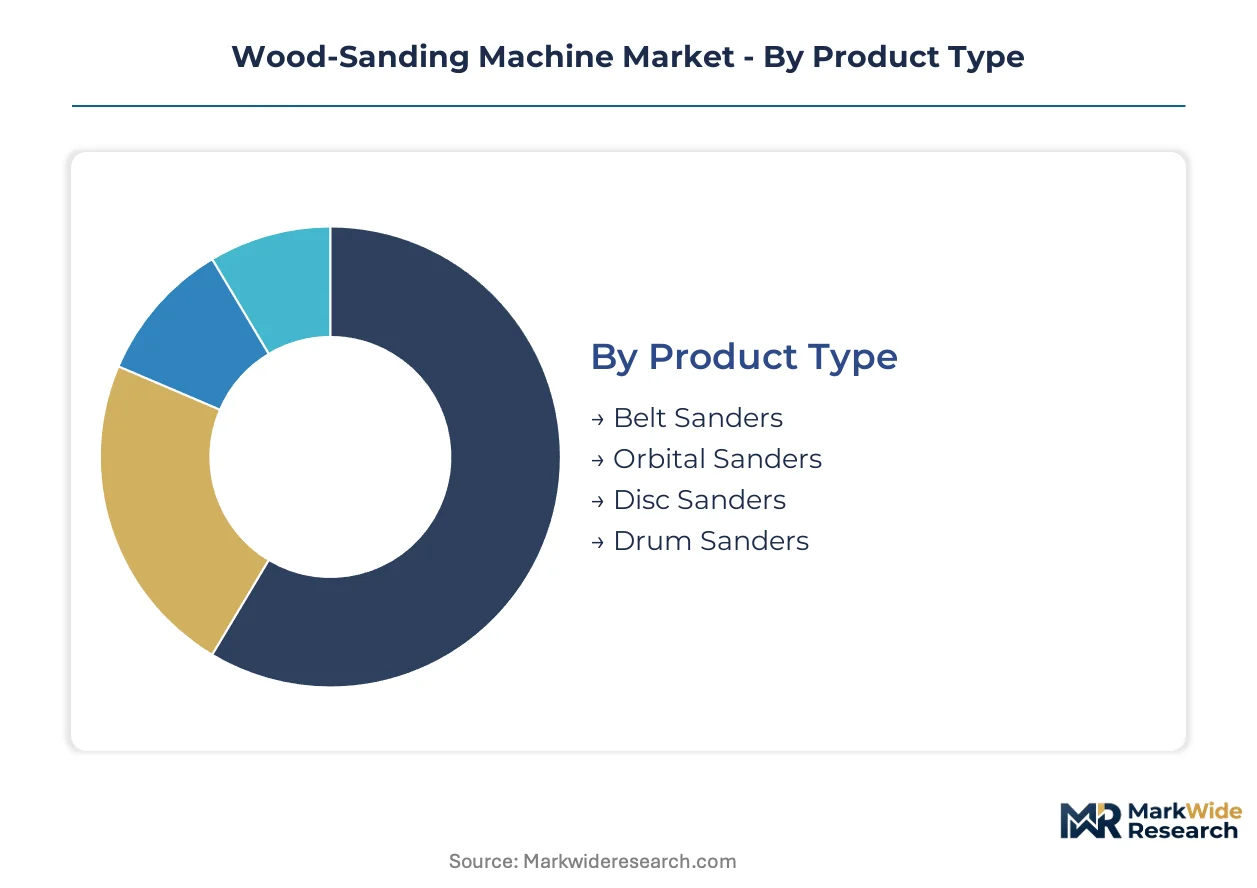
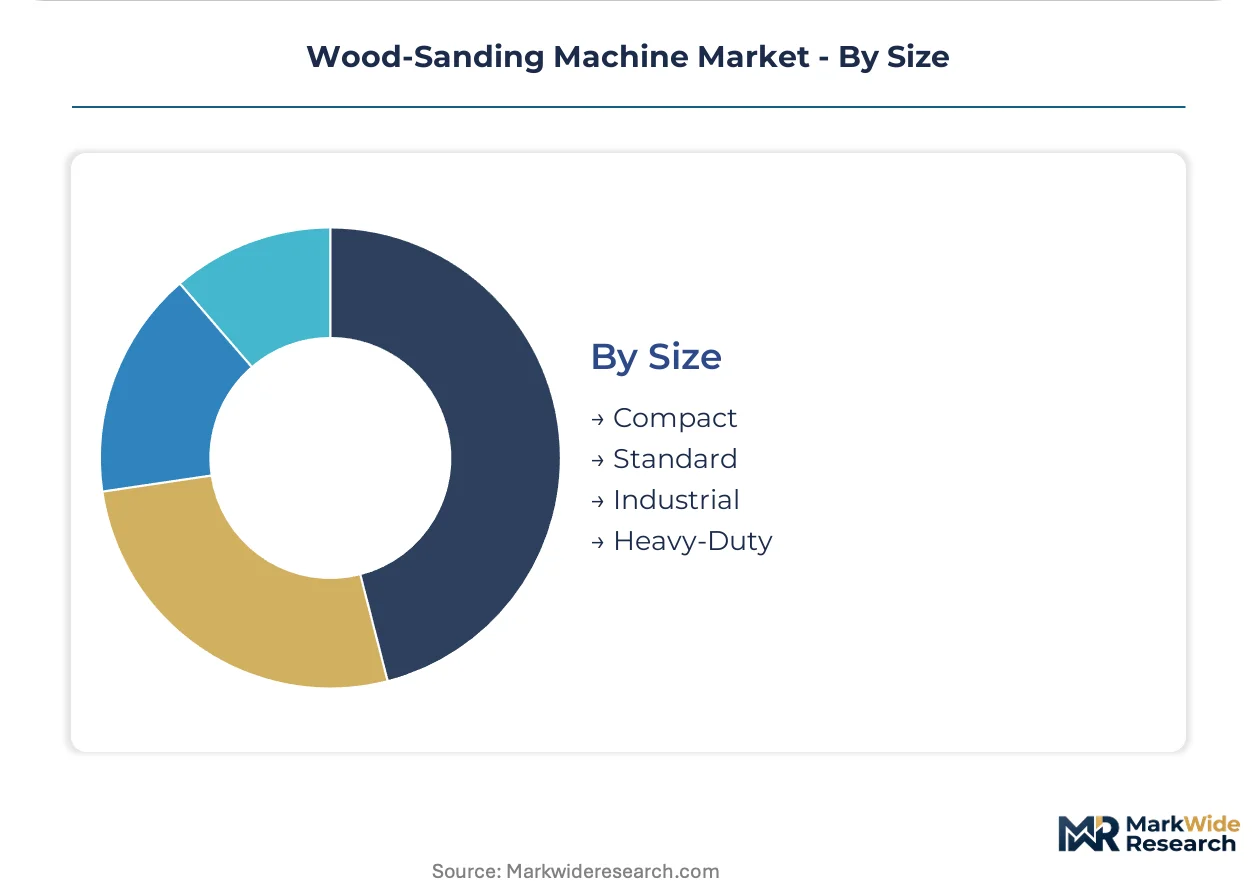
Segmentation in wood-sanding machinery reveals distinct replacement cycles and margin profiles. Equipment turnover ranges from five-year horizons for industrial wide-belt systems to decade-plus lifespans in compact DIY units, reshaping how suppliers allocate service resources and inventory.
Product Type:
Cycle times vary dramatically: belt sanders in high-throughput panel mills face accelerated wear-driven replacement, while orbital units in fine-finish cabinetry operate on longer depreciation schedules.
- Belt Sanders:Continuous-loop abrasive belts spanning 1,500 to 3,000 millimeters deliver material removal rates exceeding 20 meters per minute in dimensioning operations. German and Italian panel producers drive replacement demand as ISO 19085 compliance deadlines force certified equipment upgrades.
- Orbital Sanders:Eccentric orbital motion at 4,000 to 12,000 RPM produces swirl-free surfaces essential for premium lacquer finishes. North American custom furniture manufacturers in North Carolina and Quebec are expanding orbital capacity to serve designer cabinetry contracts demanding flawless substrate preparation.
- Disc Sanders:Rotating abrasive discs excel at edge chamfering and localized material removal in joinery shops.
- Drum Sanders:Cylindrical abrasive drums maintain thickness tolerances within 0.05 millimeters for solid-wood flooring manufacturers.
Belt sanders dominate installed base. Orbital sanders are where expansion concentrates.
End User:
Cost tier stratification separates capital-intensive automated lines from price-sensitive portable equipment procurement.
- Furniture Manufacturers:Automated wide-belt finishing lines with robotic load-unload integration command capital allocations exceeding 500,000 dollars per installation. High-volume German cabinetry producers in Bavaria and Baden-Württemberg anchor demand for servo-driven thickness-calibration systems.
- Woodworking Shops:Mid-scale commercial millwork operations balance versatility against floor-space constraints, driving demand for combination belt-disc machines.
- Construction Contractors:Battery-platform compatibility with existing cordless ecosystems determines purchasing logic among job-site finishing crews.
- DIY Enthusiasts:Entry-level random-orbit units priced below 150 dollars move through home-center retail channels with minimal service attachment.
Furniture manufacturers absorb the highest equipment value per installation. Woodworking shops represent the broadest addressable population.
Technology:
Application environment dictates power-source selection, with sustained load duty cycles and portability requirements creating divergent specification paths.
- Electric:Brushless motor systems delivering 2 to 5 kilowatts dominate new-equipment specifications across residential and light-commercial settings. North American job shops favor electric infrastructure to avoid compressed-air capital investment.
- Pneumatic:Air-powered drum sanders withstand continuous operation in heavy-duty industrial environments where motor thermal limits would constrain electric alternatives. REACH-compliant European facilities maintain pneumatic legacy systems despite retrofit complexity.
- Hydraulic:Fluid-power systems persist in specialized high-torque applications such as shipyard timber preparation.
- Manual:Non-powered sanding blocks and hand planes retain niche demand in restoration woodworking and heritage craft instruction.
Electric systems lead volume shipments. Pneumatic retains margin concentration in industrial duty cycles.
Size:
Customer scale and facility constraints segment equipment dimensions, from benchtop portability to building-integrated production lines.
- Industrial:Wide-belt systems with 1,350-millimeter abrasive widths process full-size engineered panels at throughputs exceeding 100 pieces per hour. German precision-machinery specialists engineer these platforms for cross-laminated timber producers.
- Heavy-Duty:Reinforced frame construction and continuous-duty motors serve solid-wood flooring mills and structural timber processors.
- Standard:400 to 600-millimeter belt widths accommodate general-purpose commercial woodworking with flexible material handling.
- Compact:Benchtop and handheld configurations target space-constrained workshops and mobile finishing operations.
Industrial-class equipment commands the highest average selling prices. Compact units are gaining share fastest in cordless job-site applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German furniture factories deploy wide-belt systems for engineered panel calibration, while Indian job shops favor compact belt-disc combinations for solid-wood craftsmanship, revealing a consumption-mix split between automated dimensioning and versatile hand-finishing.
United States
EPA particulate-matter enforcement and OSHA silica-exposure thresholds are accelerating dust-collection retrofits in North Carolina furniture corridors. Commercial millwork shops around High Point and Greensboro are replacing legacy drum sanders with ISO 19085-compliant wide-belt systems ahead of inspection cycles.
Germany
EU Machinery Directive 2006/42/EC certification deadlines and REACH chemical restrictions on abrasive binders are compressing replacement cycles among Bavarian panel producers. Servo-driven thickness-calibration systems from Baden-Württemberg precision-machinery specialists now dominate CLT manufacturing lines around Rosenheim.
China
MIIT industrial-upgrade subsidies and tightening GB machinery safety standards are pulling automated finishing adoption into Zhejiang and Jiangsu furniture export zones. Wenzhou-based manufacturers are scaling robotic load-unload integration for engineered-wood flooring destined for North American construction markets.
India
BIS machinery safety standard maturation and PLI scheme incentives for wood-product exports are penetrating Tamil Nadu and Gujarat woodworking clusters. Coimbatore job shops are transitioning from manual spindle sanders to electric wide-belt systems for European contract furniture orders.
Italy
ECHA-registered abrasive coating requirements and CE marking enforcement are filtering non-compliant imports from Lombardy and Veneto supply chains. Brianza cabinetry producers are consolidating procurement around certified OEMs with verified lifecycle emissions documentation for EU Carbon Border Adjustment Mechanism compliance.
Wood-Sanding Machine Market Competitive Landscape
Capability concentration sits with German precision-machinery specialists engineering servo-calibration systems; scale advantage sits with Asian producers leveraging integrated abrasive supply chains and modular platform economics. The vendor base stratifies across three archetypes: integrated power-tool conglomerates with battery-platform ecosystems, standalone wide-belt system OEMs serving industrial panel mills, and abrasive-materials suppliers backward-integrating into equipment distribution. Dominant competitive moves include geographic expansion through distributor finance arms and technology licensing for sensor-integrated finishing systems.
Among integrated power-tool conglomerates, Bosch and Makita exemplify divergent platform strategies, with the former leveraging European retail channel density and the latter extending cordless construction-tool compatibility into job-site sanding. Festool occupies a position within the premium-tier specialist archetype, anchoring high-end cabinetry workshop demand through dust-extraction integration. Timesavers represents the industrial-system fabricator tier, serving North American panel producers with wide-belt configurations.
| Leading Market Players |
|---|
| Ingersoll Rand |
| Bosch |
| Makita |
| DEWALT |
| BLACK & DECKER |
| Timesavers |
| Festool |
| 3M Company |
| Hutchins Manufacturing |
| Others |
Value Network & Pricing Analysis
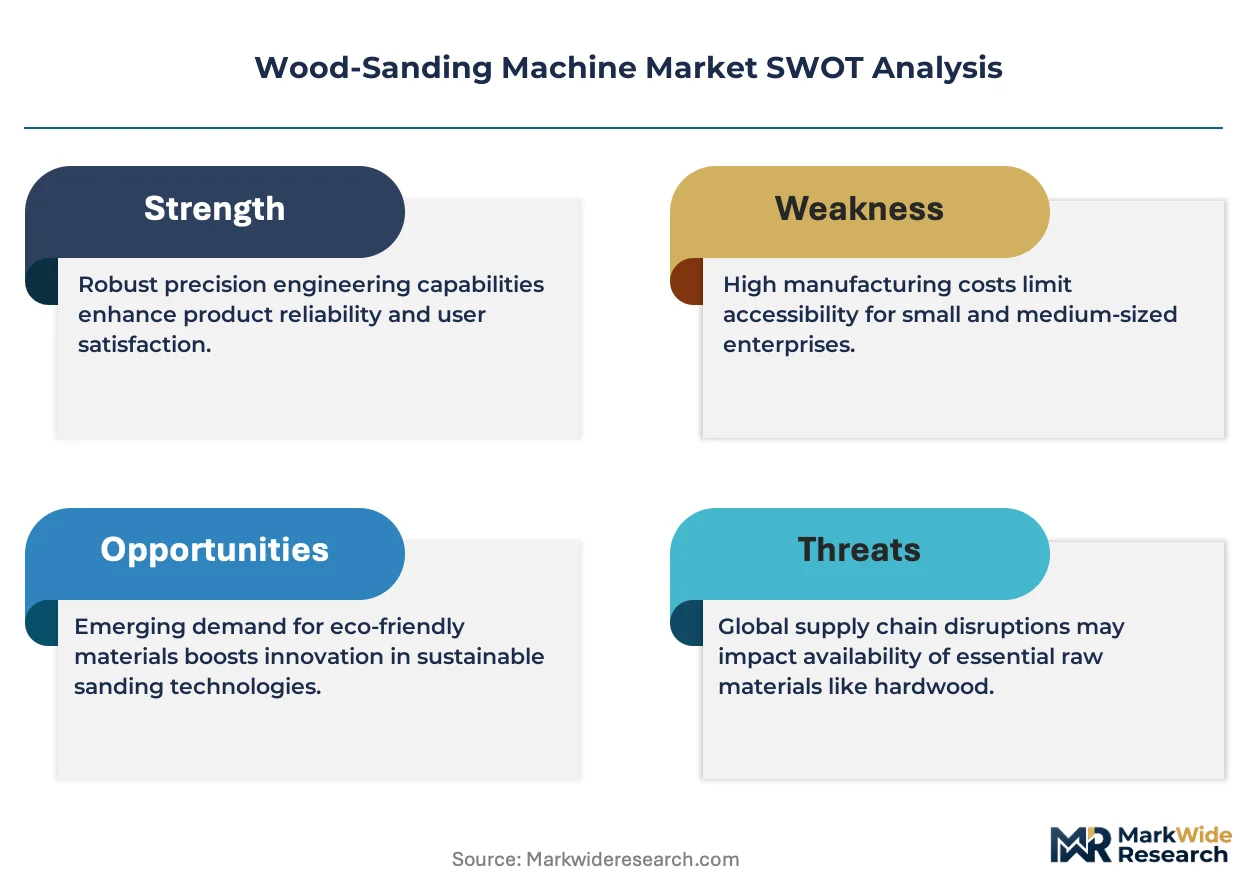
Henan province's ceramic and zirconia alumina fused-mineral concentration anchors abrasive belt cost volatility, transmitting downstream into margin compression for European OEMs dependent on premium longevity positioning. German precision-machinery specialists absorb the steepest cost pass-through limitations, as their certified equipment specifications lock them into ECHA-registered abrasive formulations with limited supplier flexibility.
Pricing Analysis
Contract-based long-term offtake agreements dominate industrial wide-belt system procurement, with German panel producers locking in multi-year abrasive-supply bundles to hedge against ceramic grain volatility. Price differentiation rests on ISO 19085 certification tier and servo-calibration precision grade, with Bavarian OEMs commanding premiums for verified lifecycle emissions documentation. Pricing pressure stems from REACH-compliant abrasive reformulation costs intensifying across European supply chains. DIY enthusiasts exhibit highest price sensitivity, while furniture manufacturers absorbing automated finishing lines show lowest elasticity due to compliance-driven replacement imperatives.
Supply Chain Analysis
Extended payment terms from German distributor finance arms are restructuring working-capital flows for North American custom-furniture manufacturers facing tightened commercial-bank equipment lending. Supply concentration spans China's Henan province for fused-mineral production, Germany's Baden-Württemberg for precision-machinery engineering, and Italy's Lombardy for abrasive coating formulation. Raw material dependencies encompass ceramic grains, phenol-formaldehyde resin binders, and servo-drive components. Single-source vulnerability concentrates in ECHA-registered abrasive suppliers with validated toxicological dossiers. Distribution runs through captive finance arms of industrial OEMs and power-tool retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mechatronics technician scarcity for servo-driven sanding head calibration and PLC programming constrains capacity expansion across Midwestern US industrial woodworking corridors, creating asymmetric advantage for vendors with established training infrastructure.
For Market Incumbents: Pre-empt Asian producer scaling by embedding sensor-integrated surface inspection as standard configuration before modular platform economics erode precision-machinery premiums. Consolidate aftermarket service capacity in High Point and Cincinnati corridors where legacy dust-collection retrofit complexity locks in multi-year maintenance contracts. Vertical integration into ECHA-registered abrasive supply secures margin pools threatened by REACH reformulation costs. For New Entrants and Emerging Players: Establish a beachhead in Tamil Nadu and Gujarat export-oriented woodworking zones where BIS machinery safety standard maturation is accelerating automated-finishing adoption ahead of qualified local supply. Target battery-platform convergence for cordless orbital sanders compatible with existing construction-tool ecosystems, penetrating job-site finishing applications previously served by pneumatic equipment. Leverage distributor finance arms to bundle equipment with maintenance contracts, mirroring North American leasing-based procurement shifts. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed German precision-machinery specialists carrying servo-calibration technology portfolios ripe for platform consolidation. Long-term viability hinges on carbon-border adjustment mechanism positioning, where verified lifecycle emissions documentation creates durable competitive moats. Monitor EU import levy implementation timelines as inflection indicator for European-manufactured wide-belt system demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Integrated Surface Inspection | Machine-vision calibration renders manual gauge verification obsolete in Bavarian panel mills. |
| ECHA-Registered Abrasive Backward Integration | Captive supply of REACH-compliant ceramic coatings secures OEM margin pools against reformulation cost pass-through. |
| Battery-Platform Convergence | Cordless orbital sander compatibility with construction-tool ecosystems penetrates pneumatic-dominated job sites. |
| Distributor Finance Arm Expansion | Equipment-leasing bundling in High Point and Cincinnati addresses working-capital constraints among custom-furniture manufacturers. |
| Carbon Border Adjustment Positioning | Verified lifecycle emissions documentation creates first-mover advantage for EU-manufactured wide-belt systems. |
Research Methodology
A standing panel of plant engineers at German panel producers, aftermarket service heads at North American distributors, procurement leads at Italian cabinetry OEMs, and maintenance directors in Midwestern woodworking corridors provided ongoing calibration across the study. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, customs and trade data for abrasive material flows, machinery safety certification databases, and industry association capacity surveys. Bottom-up equipment shipment tallies triangulated against top-down furniture production indices.
Scenario bracketing around EU Machinery Directive compliance deadlines, REACH reformulation timelines, and carbon-border adjustment implementation framed the projection horizon. Segmentation dimensions encompassed product type, end-user scale tier, technology architecture, and equipment size class, with additional modeling of regional regulatory cluster effects. CAGRs derived from installed-base replacement cycle analysis and penetration-rate extrapolation for emerging applications. Forecast inputs incorporated abrasive belt cost volatility indices and mechatronics technician supply constraints.
Stress conditions across ceramic grain price bands, silica-exposure threshold revisions, and battery-platform adoption curves were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory implementation schedules and technology substitution rates. Macroeconomic contraction, accelerated REACH restrictions, or breakthrough solid-state sanding technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Surface Planer Market
Tools
Woodworking Power Tools Market
Tools
Brazing Torch Market
Tools
Jade Engraving Machines Market
Tools
Woodworking CNC Tools Market
Tools
Engraver Machine Market
Tools
Boring-Milling Machines Market
Tools
Belt File Sander Market
Tools
Air Drills Market
Tools
Spray Painting Machine Market
Tools
Handheld Pipe Cutter Market
Tools
Automotive Torque Tools Market
Tools
Laser Engraving Machine Market
Tools
Drain Cleaning Equipment Market
Tools
Power Drill Market
Tools
Manual Cutting Equipment Market