
 Mexico Oil and Gas Market | 2026-2036
Mexico Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Oil and Gas Market Outlook
A capital-intensity divergence between Pemex and private entrants is bifurcating competitive dynamics in Mexico's hydrocarbon sector. Pemex leverages its legacy pipeline network and mature onshore fields to sustain domestic refining throughput. Talos Energy competes through deepwater exploration expertise in the Gulf of Mexico. Chevron Corporation anchors its position via integrated upstream-downstream coordination across Mexican assets.
Mexico oil and gas encompasses crude petroleum extraction, natural gas recovery, and hydrocarbon processing for fuels and chemical feedstocks, with sulfur content and API gravity serving as key quality benchmarks for trade and refining configuration. The sector supplies transportation fuels, power generation feedstock, and petrochemical precursors to industrial consumers. Upstream applications dominate investment flows as operators target deepwater reserves off the Gulf Coast, while downstream refining capacity remains structurally constrained by aging infrastructure. Petrochemicals represents the fastest-expanding application segment, driven by polymer demand from automotive and packaging industries in Querétaro and Puebla.
CNH regulates hydrocarbon exploration and production licensing, while ASEA oversees environmental compliance for offshore and onshore operations, and CRE sets tariffs for pipeline transport and storage access. These frameworks shape market entry timelines, technical standards for well integrity, and third-party access to midstream infrastructure. Stakeholders must monitor constitutional amendments affecting private investment terms and local content requirements that determine supply chain sourcing obligations.
Market Dynamics
The Mexico oil and gas sector is bifurcating around capital efficiency as Pemex's legacy infrastructure competes against private deepwater entrants deploying subsea tieback technologies. This structural tension between state-operated mature fields and international deepwater exploration is redirecting investment flows toward the Gulf of Mexico offshore blocks.
Growth Catalysts
- Energy Reform Framework:Constitutional amendments permit private upstream investment in hydrocarbon exploration and production licensing, opening blocks previously restricted to state control.
- Automotive Petrochemical Demand:Polymer consumption from vehicle manufacturers in Querétaro and Puebla is expanding feedstock requirements for ethylene and propylene derivatives.
- Gulf of Mexico Deepwater Reserves:Unexplored offshore formations near Veracruz and Tamaulipas contain substantial untapped crude and natural gas deposits.
Market Restraints
- Refining Infrastructure Age:Downstream processing capacity remains constrained by decades-old equipment requiring substantial refurbishment investment.
- Input Cost Volatility:Steel and specialized drilling equipment prices fluctuate with global commodity cycles, pressuring project economics.
- Regulatory Friction:Local content requirements under CNH licensing terms mandate domestic supply chain sourcing that extends procurement timelines.
Strategic Opportunities
- Southeastern Shale Formations:Unconventional onshore resources in Tamaulipas and Coahuila remain underexplored relative to Permian analogs.
- Carbon Capture Integration:Industrial clusters in Veracruz offer geological sequestration potential for enhanced oil recovery and emissions reduction.
- Midstream Third-Party Access:CRE tariff regulations create entry points for independent pipeline transport and storage operators.
Industry Challenges
- Deepwater Technical Expertise Gap:Specialized subsea engineering and well integrity capabilities remain concentrated among a limited pool of international contractors.
- Environmental Compliance Timelines:ASEA permitting processes for offshore operations create multi-month approval cycles that compress drilling windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Oil and Gas Market |
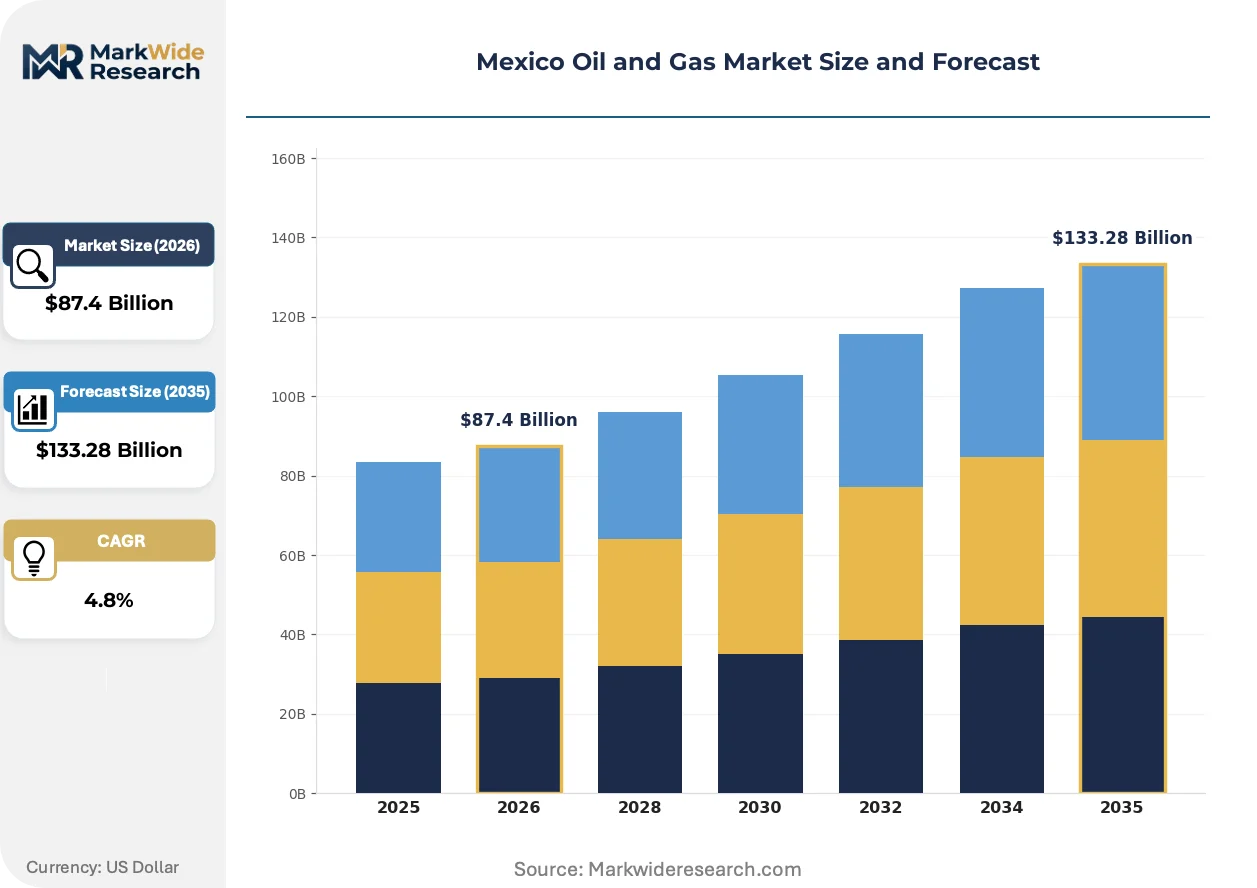
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $133.28 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Exploration, Production, Refining, Distribution Application: Upstream, Midstream, Downstream, Petrochemicals Technology: Drilling, Reservoir Management, Separation, Transportation End User: Utilities, Industrial, Commercial, Automotive |
| Companies Covered | Pemex, Chevron Corporation, Exxon Mobil Corporation, BP p.l.c., Shell International B.V., Citla Energy, Talos Energy, Marathon Petroleum Corporation, TotalEnergies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Oil and Gas Market Strategic Shifts
Digital reservoir characterization and subsea processing technologies are compressing development timelines in Mexico's deepwater frontier. These advances are reshaping how operators assess field economics and deploy capital across the Gulf of Mexico.
Subsea multiphase pumping systems are displacing conventional platform-based processing infrastructure in deepwater developments. Pemex and private block operators are adopting these systems to reduce topside weight and accelerate first oil from complex reservoirs. This technology is displacing fixed-platform construction demand and redirecting fabrication contracts toward subsea equipment specialists.
ASEA has tightened offshore environmental compliance protocols for well integrity and produced water discharge, extending permitting review cycles. Operators must now submit real-time monitoring data and enhanced spill response plans before drilling authorization. Deepwater exploration blocks near Veracruz face the most stringent application of these standards, with several projects adjusting completion schedules to accommodate regulatory timelines.
Integrated service contracts are consolidating drilling, completion, and production operations under single-vendor arrangements. National oil companies and private leaseholders are shifting from discrete service procurement to performance-based partnerships that transfer operational risk. This restructuring is most visible in the Gulf of Mexico blocks, where Talos Energy and similar operators have renegotiated supplier relationships to align contractor incentives with production targets.
Mexico Oil and Gas Market Segmentation
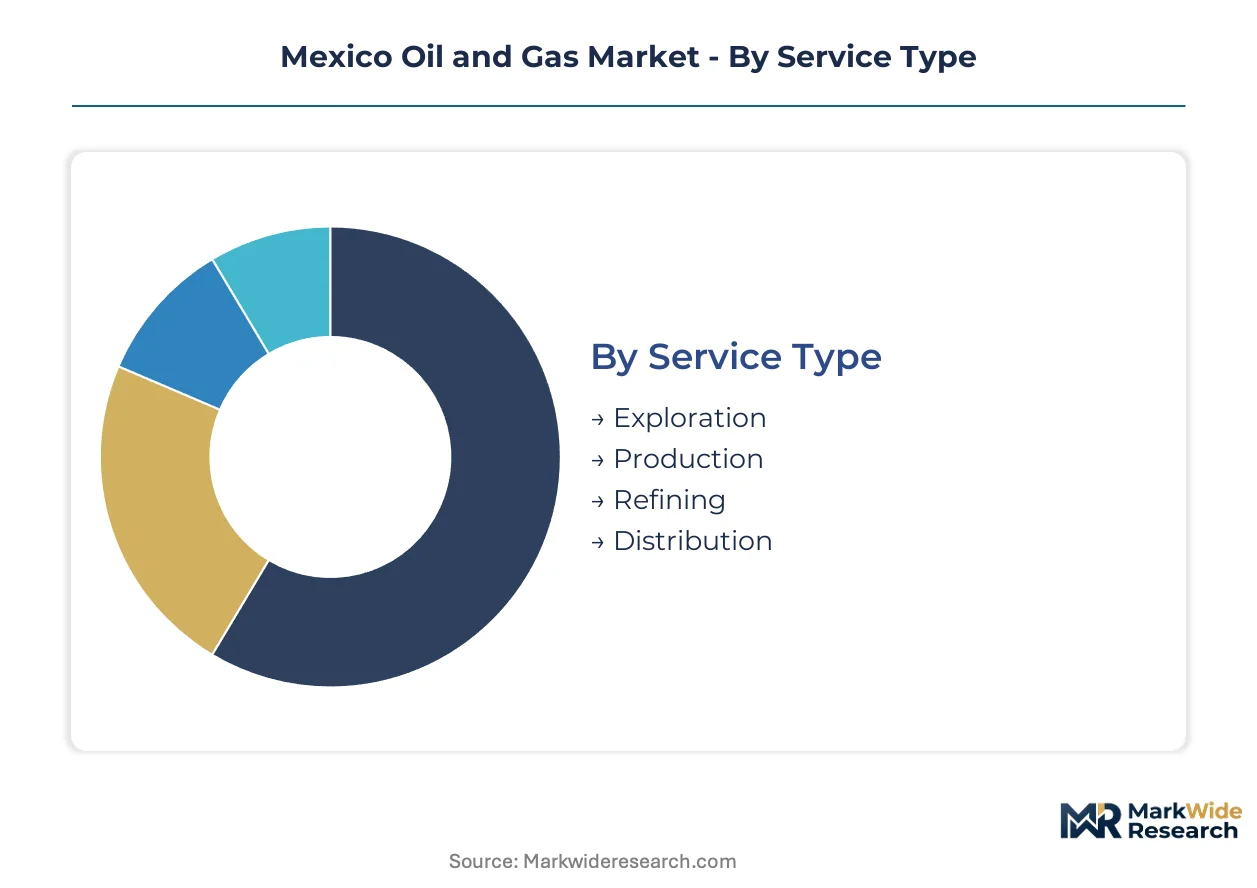
Segmentation in Mexico's oil and gas sector reveals how capital flows distribute across the value chain. Each dimension exposes different pressure points—from upstream licensing terms to downstream infrastructure constraints—that determine competitive positioning.
Service Type:
Upstream services flow through integrated operator contracts, while downstream services route through CRE-regulated tariff structures.
- Exploration:Seismic surveying and wildcat drilling target untapped formations in the Gulf of Mexico. Demand concentrates in deepwater blocks off Veracruz, where constitutional reform permits private licensing alongside Pemex acreage.
- Production:Field development and extraction operations span mature onshore assets and subsea tieback installations. Operators in Tamaulipas deploy multiphase pumping to accelerate output from complex reservoirs.
- Refining:Crude processing into transportation fuels and feedstocks operates through legacy infrastructure requiring substantial refurbishment. Domestic throughput remains constrained by equipment age at facilities serving central Mexico demand.
- Distribution:Pipeline transport and storage services operate under CRE tariff regulations that mandate third-party access. Independent operators leverage this framework to capture midstream margins on routes between production clusters and industrial consumers.
By volume, Production leads. By growth pace, Exploration is climbing the fastest.
Application:
Margin profiles diverge sharply: upstream captures resource rents, petrochemicals capture polymer premiums, while midstream and downstream operate on regulated returns.
- Upstream:Hydrocarbon extraction from licensed blocks encompasses both onshore mature fields and deepwater frontier developments. Private operators target Gulf of Mexico reserves where subsea technologies reduce development timelines.
- Midstream:Pipeline gathering, processing, and storage infrastructure connects production sites to refining and export terminals. ASEA environmental compliance requirements extend permitting cycles for new construction near coastal zones.
- Downstream:Refining and marketing of finished petroleum products serves domestic transportation and industrial fuel demand. Capacity limitations force continued product imports despite local crude availability.
- Petrochemicals:Polymer and chemical precursor manufacturing from hydrocarbon feedstocks supplies automotive manufacturers in Querétaro and packaging producers in Puebla. Ethylene and propylene derivative demand expands with vehicle production growth.
Upstream commands the largest capital allocation. Petrochemicals delivers the steepest expansion trajectory.
Technology:
Technology selection tracks reservoir characteristics: conventional drilling for onshore carbonate formations, subsea systems for deepwater pressure regimes.
- Drilling:Rotary and directional drilling systems penetrate target formations across onshore and offshore environments. Extended-reach capabilities access subsea reservoirs from platform or land-based positions.
- Reservoir Management:Digital characterization and simulation tools optimize recovery factors from complex geology. Real-time monitoring systems guide injection strategies for enhanced oil recovery in mature fields.
- Separation:Multiphase processing equipment handles crude, gas, and water mixtures at surface facilities or subsea installations. Compact separation units reduce topside weight on floating production systems.
- Transportation:Pipeline networks, tanker vessels, and rail systems move hydrocarbons from production to processing and consumption points. CRE-regulated tariffs govern third-party access to pipeline infrastructure.
Drilling absorbs the highest equipment spend. Reservoir Management is gaining share fastest through digital adoption.
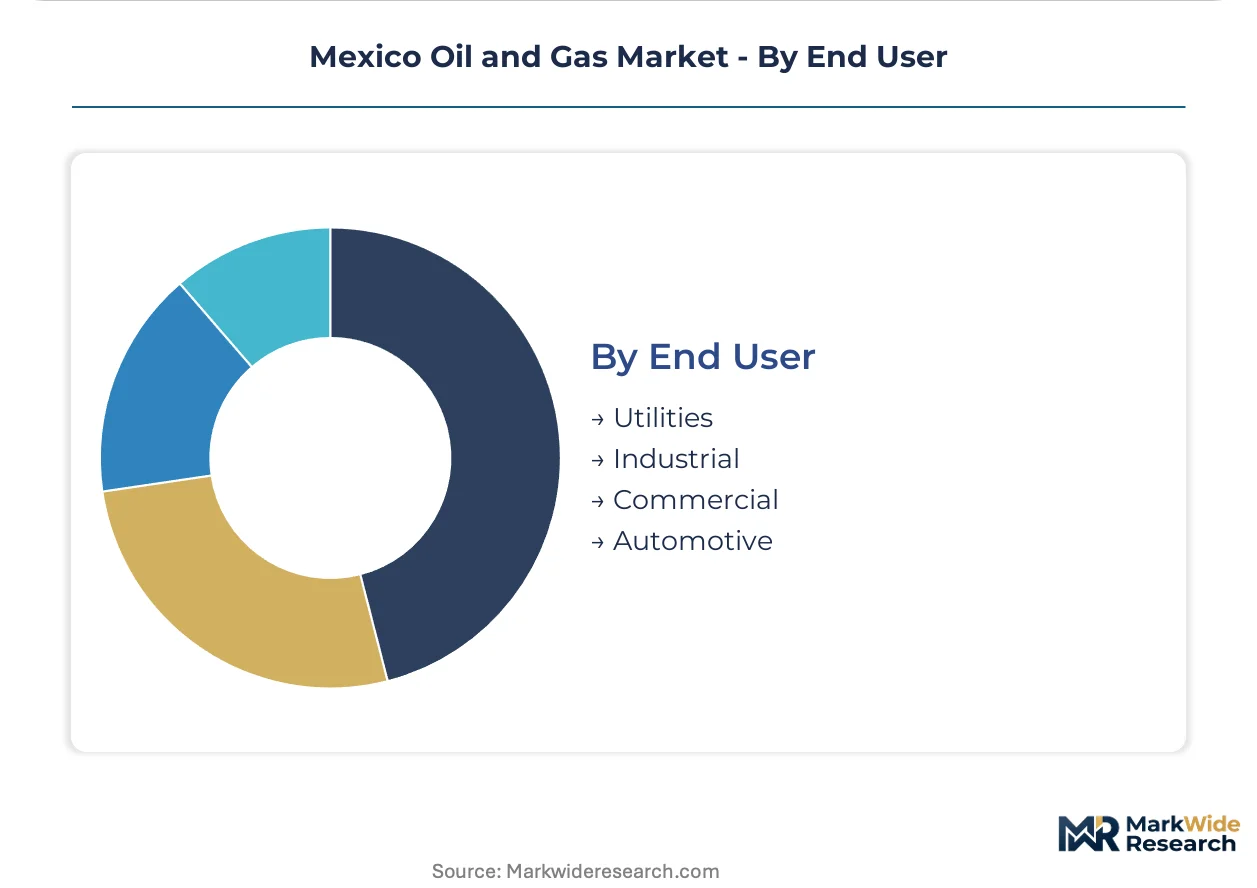
End User:
Demand concentration varies by fuel type: power generators anchor natural gas consumption, vehicle fleets anchor gasoline and diesel, chemical plants anchor feedstock volumes.
- Utilities:Electricity generators consume natural gas for combined-cycle power plants serving grid demand. CFE procurement contracts structure long-term supply arrangements with upstream producers.
- Industrial:Manufacturing facilities utilize process heat, feedstocks, and power generation fuels across steel, cement, and chemical sectors. Energy cost sensitivity drives fuel-switching behavior between natural gas and alternatives.
- Commercial:Retail fuel stations, heating systems, and distributed power applications consume refined petroleum products. Geographic coverage of distribution networks determines market access for independent retailers.
- Automotive:Vehicle manufacturers and fleet operators demand transportation fuels and polymer feedstocks for component production. OEM supply contracts in central Mexico specify petrochemical sourcing requirements.
Industrial users represent the largest volume segment. Automotive demand is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Veracruz commands pricing leverage over northern supply basins due to Gulf of Mexico deepwater proximity and concentrated petrochemical demand. Tamaulipas fields trade at transport discounts that Pemex legacy infrastructure partially offsets. This geographic asymmetry shapes investment allocation across Mexican hydrocarbon provinces.
Veracruz
Offshore exploration blocks attract private licensing activity under CNH framework terms. ASEA environmental protocols extend permitting cycles for subsea developments. The Coatzacoalcos petrochemical cluster processes ethylene and propylene derivatives for automotive supply chains.
Tamaulipas
Burgos Basin shale formations and offshore shallow-water fields sustain dual production profiles. Local content requirements under energy reform legislation mandate domestic supply chain sourcing. Matamoros-Reynosa industrial corridor anchors natural gas processing for northern manufacturing demand.
Nuevo León
Monterrey metropolitan manufacturing base consumes pipeline natural gas for steel and cement production. CRE tariff regulations govern third-party access to transport infrastructure serving the state. García-Santa Catarina industrial parks specify petrochemical feedstock requirements for polymer component suppliers.
Tabasco
Onshore mature fields deliver heavy crude feedstock to domestic refineries through Pemex pipeline networks. Constitutional hydrocarbon ownership provisions reserve subsurface resources to the nation. Paraíso-Comalcalco production zone targets enhanced oil recovery from declining carbonate reservoirs.
Campeche
Bay of Campeche shallow-water platforms sustain declining output from Cantarell field legacy assets. ASEA offshore discharge standards tighten produced water management requirements. Ciudad del Carmen service base concentrates subsea equipment fabrication and drilling contractor logistics.
Mexico Oil and Gas Market Competitive Environment
Concentration sits with state-backed incumbents holding legacy infrastructure positions against private entrants deploying specialized deepwater capabilities. Pemex retains integrated control across upstream licensing, pipeline transport, and refining capacity that reform-era competitors cannot replicate. Two strategic archetypes define competitive positioning: capital-efficient subsea specialists targeting frontier blocks, and integrated majors coordinating upstream-downstream value capture. Dominant competitive moves include integrated service contract restructuring to transfer operational risk, and portfolio diversification into petrochemical feedstock integration.
Among Mexico City and Houston-based operators, Pemex, Talos Energy, and Chevron Corporation occupy distinct archetype positions. Pemex exemplifies the state-integrated incumbent with captive infrastructure access. Talos Energy represents the subsea specialist archetype focused on deepwater exploration execution. Chevron Corporation anchors the integrated major tier with coordinated upstream-downstream positioning. These three entities collectively illustrate how reform-era licensing has stratified competitive roles without displacing legacy state presence.
| Leading Market Players |
|---|
| Pemex |
| Chevron Corporation |
| Exxon Mobil Corporation |
| BP p.l.c. |
| Shell International B.V. |
| Citla Energy |
| Talos Energy |
| Marathon Petroleum Corporation |
| TotalEnergies |
| Others |
Value Chain & Pricing Dynamics
Scale economies at Pemex's legacy refining complexes anchor domestic price floors for transportation fuels, while private deepwater operators face steeper breakeven thresholds that compress margin buffers during crude volatility. This capacity-utilization asymmetry concentrates pricing power with integrated state infrastructure and fragments price discovery across the Gulf of Mexico offshore blocks.
Pricing Analysis
The customization-premium spread separates configured-to-order subsea equipment packages from standardized drilling services. Contract-based long-term offtake dominates upstream crude sales, while spot-indexed pricing governs refined product imports filling domestic supply gaps. Price differentiation hinges on API gravity quality grades and CRE-regulated pipeline access tariffs. Cost compression in standard drilling tiers is intensifying because steel input volatility and extended CNH permitting timelines erode project returns. National refiners exhibit highest price sensitivity due to aging equipment conversion costs, whereas international deepwater specialists absorb premium pricing for subsea multiphase pumping systems.
Supply Chain Analysis
Inventory lead times for subsea trees and blowout preventers stretch procurement cycles, compressing drilling windows during favorable weather periods. Equipment fabrication concentrates in the United States, South Korea, and Norway, with specialized contractors anchoring logistics at Ciudad del Carmen service bases. Raw material dependencies include high-grade steel alloys, subsea electronics, and synthetic drilling fluids. Single-source vulnerability runs through limited-qualified subsea engineering contractors capable of ASEA-compliant well integrity systems. Distribution runs through CRE-regulated pipeline networks and coastal marine terminals serving Veracruz and Tamaulipas production clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Mexico oil and gas sector functions as a service-attach opportunity where integrated production contracts and real-time reservoir monitoring subscriptions expand faster than standalone hardware sales. Performance-based partnerships now transfer operational risk while embedding recurring technical service layers.
For Market Incumbents: Fortify captive infrastructure positions by deepening backward integration into subsea equipment maintenance capabilities and securing exclusive pipeline access rights under CRE tariff regulations. Pemex legacy networks face substitution pressure from private midstream entrants leveraging third-party access rules, making channel control over coastal storage terminals the priority defensive lever. For New Entrants and Emerging Players: Anchor in Tamaulipas Burgos Basin shale formations where unconventional resource development remains underpenetrated relative to Permian analogs. The southeastern onshore segment offers lowest competitive density for hydraulic fracturing service providers. A go-to-market angle targeting polymer feedstock integration with Querétaro automotive OEMs bypasses direct upstream licensing competition. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among subsea equipment specialists with multi-year field service contracts tied to production targets. Long-term viability across the analysis window favors operators with integrated digital reservoir management platforms. Acquisition target archetype: mid-cap exploration companies holding contiguous deepwater block positions near Veracruz. The signal to watch is constitutional amendment proposals affecting hydrocarbon ownership terms and local content enforcement.| Strategic Initiative | Industry Significance |
|---|---|
| Subsea Technology Licensing | Talos Energy deploys proprietary multiphase pumping systems to accelerate first oil from complex Gulf of Mexico reservoirs. |
| Backward Integration into Equipment Fabrication | Pemex captures margin from subsea tree manufacturing through captive supply relationships with Ciudad del Carmen yards. |
| Long-term Supply Agreement | CFE structures natural gas procurement contracts anchoring demand for northern Tamaulipas production. |
| Joint Venture | International operators partner with Mexican service firms to satisfy CNH local content requirements for drilling contracts. |
| Green Certification Program | ASEA environmental compliance investments open carbon credit monetization for Veracruz industrial cluster sequestration projects. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with upstream project managers, subsea equipment procurement leads, CNH licensing specialists, ASEA environmental compliance officers, and petrochemical plant directors. Secondary validation drew from CNH hydrocarbon production databases, CRE tariff filings, ASEA environmental permits, customs trade records, and Pemex operational disclosures. Bottom-up field development economics were triangulated against top-down sector expenditure estimates.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning service type, application, technology, and end user, with additional granularity on deepwater versus onshore resource characteristics. CAGRs were derived from production volume trajectories and capital expenditure patterns across the analysis window. Industry-specific forecast inputs included well completion rates and refinery utilization assumptions.
Material uncertainties — constitutional amendment reversals, ASEA permitting timeline extensions, and crude price volatility — sit outside the modeled envelope. Forecasts reflect documented assumptions about energy reform continuity and local content enforcement intensity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Nigeria Upstream Oil Sector Market
Oil & Gas
Bunker Liners Market
Oil & Gas
North America Oil and Gas Electric Submersible Pump Market
Oil & Gas
Sucker Rod Market
Oil & Gas
Brazil Oil and Gas Market
Oil & Gas
Africa Oil and Gas Market
Oil & Gas
Dissolvable Frac Plug Market
Oil & Gas
Oil and Gas Engineering Services Market
Oil & Gas
Global LNG Liquefaction Terminals Market
Oil & Gas
Downhole Drilling Tools Market
Oil & Gas
Liquefied Natural Gas Market
Oil & Gas
Seismic Survey Equipment Market
Oil & Gas
Netherlands LNG Bunkering Market
Oil & Gas
Europe Oil and Gas Storage Tank Market
Oil & Gas
United States Onshore Drilling Fluid Market
Oil & Gas
Italy Oil and Gas Upstream Market