
 Dough Processing System Market | 2026-2036
Dough Processing System Market Size, Share, and Industry Trends Forecast 2026-2036
Dough Processing System Market Foresight
ISO 22000 certification for food safety management systems is collapsing the supplier base as smaller fabricators fail audit cycles. Bühler Group leverages its Swiss engineering heritage to sustain premium positioning in automated sheeting lines. GEA Group anchors European supply through captive manufacturing of hygienic design mixers. Rheon Automatic Machinery Co., Ltd. competes on precision dividing technology for high-moisture dough formulations.
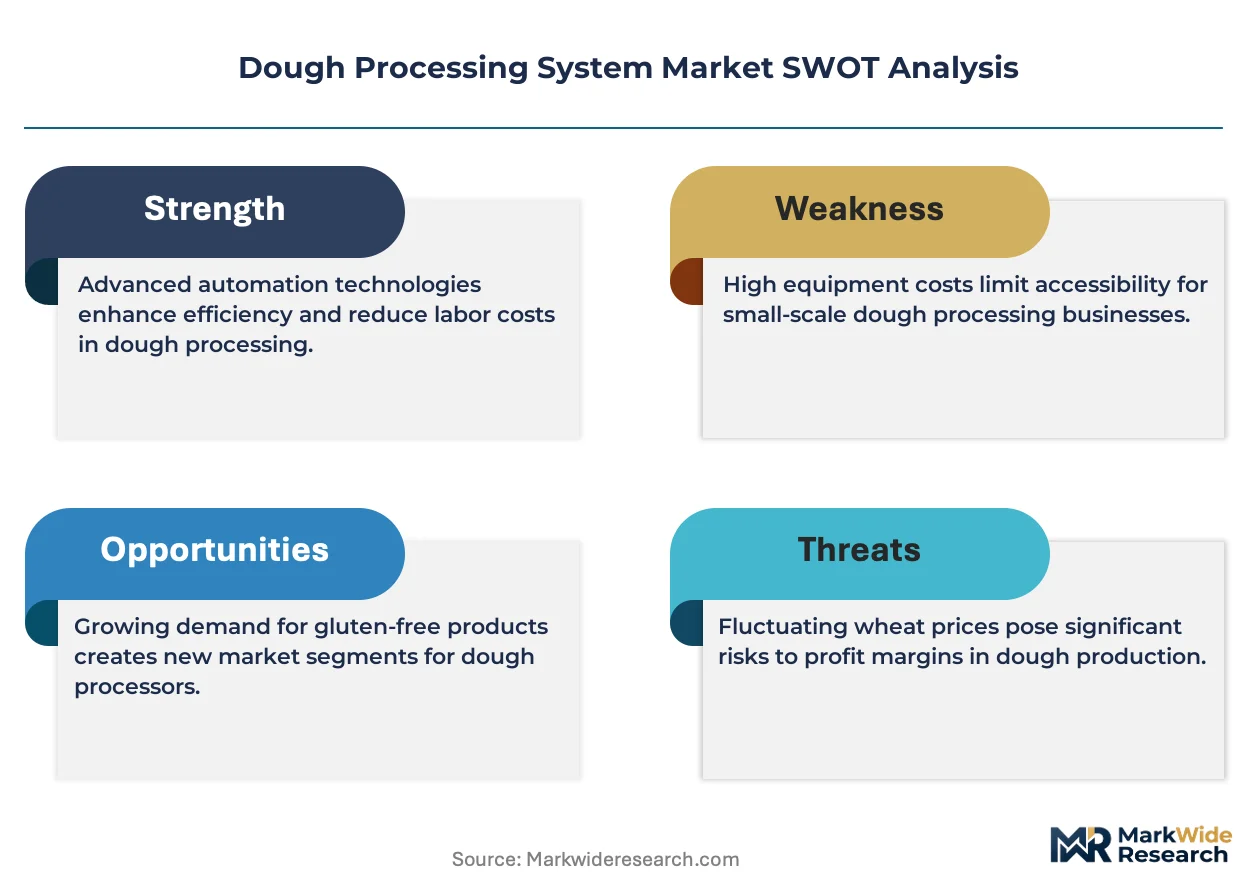
A dough processing system encompasses mechanical equipment that transforms bulk dough into uniform intermediate or final products through controlled mixing, sheeting, dividing, and proofing operations, typically operating at temperatures between 18°C and 24°C to preserve gluten network integrity. These systems serve industrial bakeries and food manufacturing facilities requiring consistent throughput, portion accuracy, and compliance with sanitary design standards. Mixers and sheeters occupy the largest installed base due to their universal necessity across bread, pastry, and pizza applications, while automated solutions command the fastest replacement cycle as labor scarcity intensifies in North American and Western European plants. Hybrid systems that blend batch flexibility with continuous throughput are emerging as the margin-rich segment for mid-cap bakeries seeking to defer full automation capital outlays.
The FDA enforces Current Good Manufacturing Practice regulations that dictate equipment surface finish, cleanability, and allergen control protocols for dough contact surfaces in U.S. facilities. EFSA and national regulators under the EU Hygiene Package mandate HACCP-integrated machinery design, pressuring non-compliant Asian exporters to redesign for European market access. NSF International certification has become a de facto gate for equipment placement in U.S. quick-service restaurant commissaries. Stakeholders must weigh sanitary design upgrade costs against the contracting window for manual processing exemptions in major import jurisdictions.
Market Dynamics
Continuous processing technology is displacing batch operations across industrial bakeries as labor scarcity and hygiene mandates force capital redeployment toward automated sheeting and dividing lines.
Growth Catalysts
- ISO 22000 audit cycles:Food safety certification mandates are eliminating non-compliant fabricators, concentrating procurement among validated suppliers in Germany and Switzerland.
- High-moisture dough formulations:Precision dividing technology for artisan pizza and specialty bread applications is pulling equipment upgrades in U.S. quick-service restaurant commissaries.
- Hybrid system architecture:Mid-cap bakeries in France and Italy are deploying batch-flexible continuous lines to defer full automation capital outlays.
Market Restraints
- Stainless steel input volatility:Grade 316L price swings compress margins for hygienic design fabricators during procurement cycles.
- European supply concentration:Captive manufacturing of sanitary mixers by dominant German and Swiss groups limits second-source availability for mid-scale buyers.
- Allergen control protocol complexity:FDA Current Good Manufacturing Practice surface-finish requirements extend validation timelines for Asian exporters seeking U.S. market entry.
Strategic Opportunities
- NSF International certification gap:U.S. quick-service restaurant chains are mandating third-party validated equipment, creating tiered supplier qualification tiers.
- Retrofit automation kits:Sheeting line sensor integration and programmable logic controller upgrades are penetrating installed bases in Canadian industrial bakeries.
- EU Hygiene Package redesign services:HACCP-integrated machinery consulting for Asian exporters is emerging as a high-margin advisory segment.
Industry Challenges
- Sanitary welding certification scarcity:Qualified orbital welders for 3-A sanitary standards command premium wages, constraining fabricator expansion.
- Legacy control system integration:Proprietary batch management software in 1990s-era plants resists interface with modern continuous processing architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dough Processing System Market |
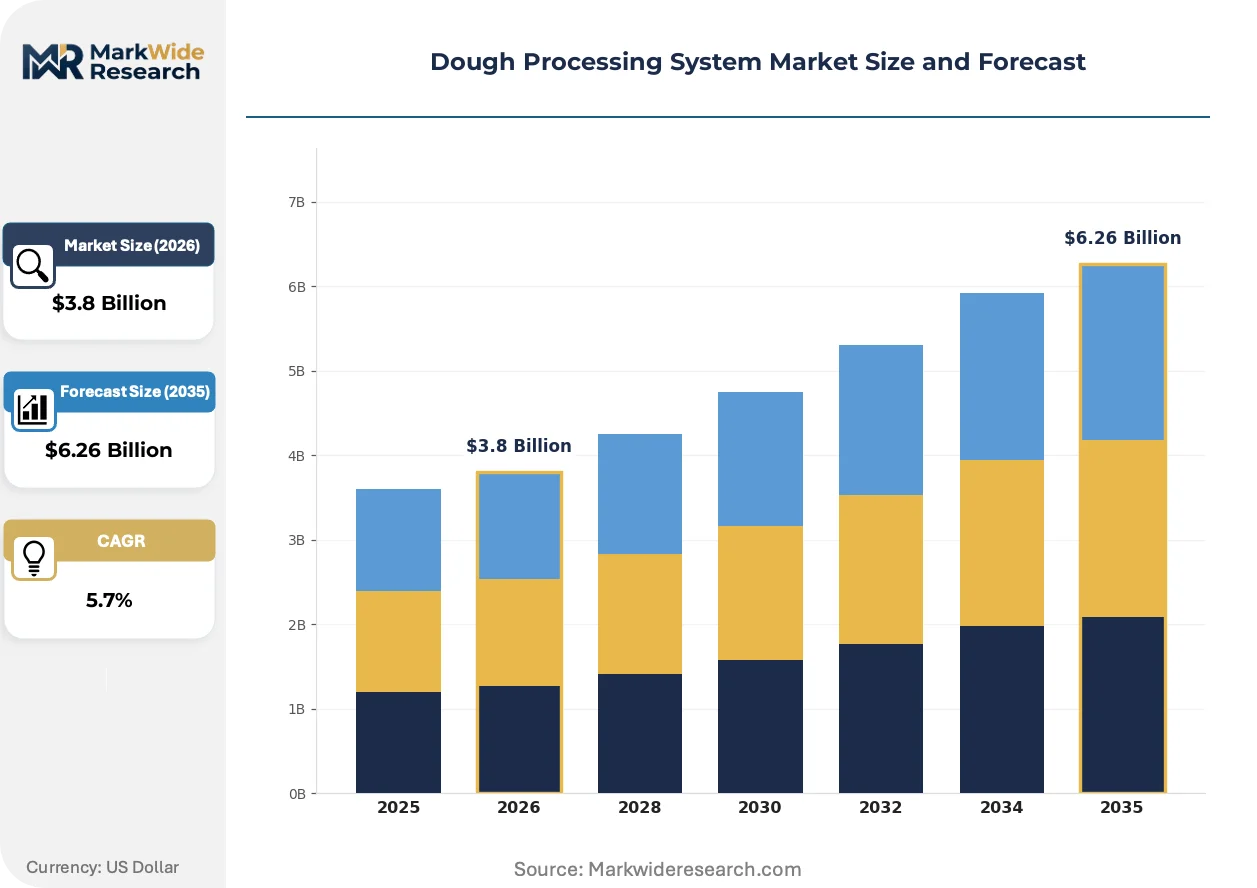
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mixers, Sheeters, Dividers, Proofers Technology: Batch Processing, Continuous Processing, Hybrid Systems, Automated Solutions Application: Bread, Pastry, Pizza, Snacks End User: Bakeries, Restaurants, Food Processing Plants, Catering Services |
| Companies Covered | GEA Group AG, Bühler Group, Ali Group, Middleby Corporation, Rheon Automatic Machinery Co., Ltd., AMF Bakery Systems, John Bean Technologies Corporation, Rademaker BV, WP Bakery Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dough Processing System Market Shifts & Advancements
Equipment architecture is pivoting toward modular, sensor-integrated platforms that compress commissioning timelines and enable predictive maintenance contracts.
Inductive torque sensing in mixer drives is miniaturizing. These embedded load cells enable real-time dough rheology monitoring without invasive sampling ports. Artisan and industrial bakeries in the Netherlands and Belgium are piloting retrofit kits at replacement-cycle velocity. The technology is miniaturizing quality-control infrastructure, collapsing the gap between batch artisan flexibility and continuous-line consistency.
REACH substance restrictions on food-contact lubricants are forcing reformulation of bearing greases and chain oils in European-sourced equipment. Machinery OEMs are validating synthetic ester alternatives through EFSA-compliant migration testing. High-speed sheeting lines for laminated dough applications face the steepest compliance cost escalation, with German fabricators absorbing certification overhead into premium pricing tiers.
After-sales service unbundling is fragmenting buyer-supplier relationships. Large-scale U.S. industrial bakeries are separating maintenance contracts from original equipment procurement, awarding multi-vendor service agreements to specialized third-party technicians. Channel intermediaries in Texas and California are building captive field-service capabilities, compressing OEM recurring revenue streams and accelerating parts-standardization lobbying.
Dough Processing System Market Segmentation
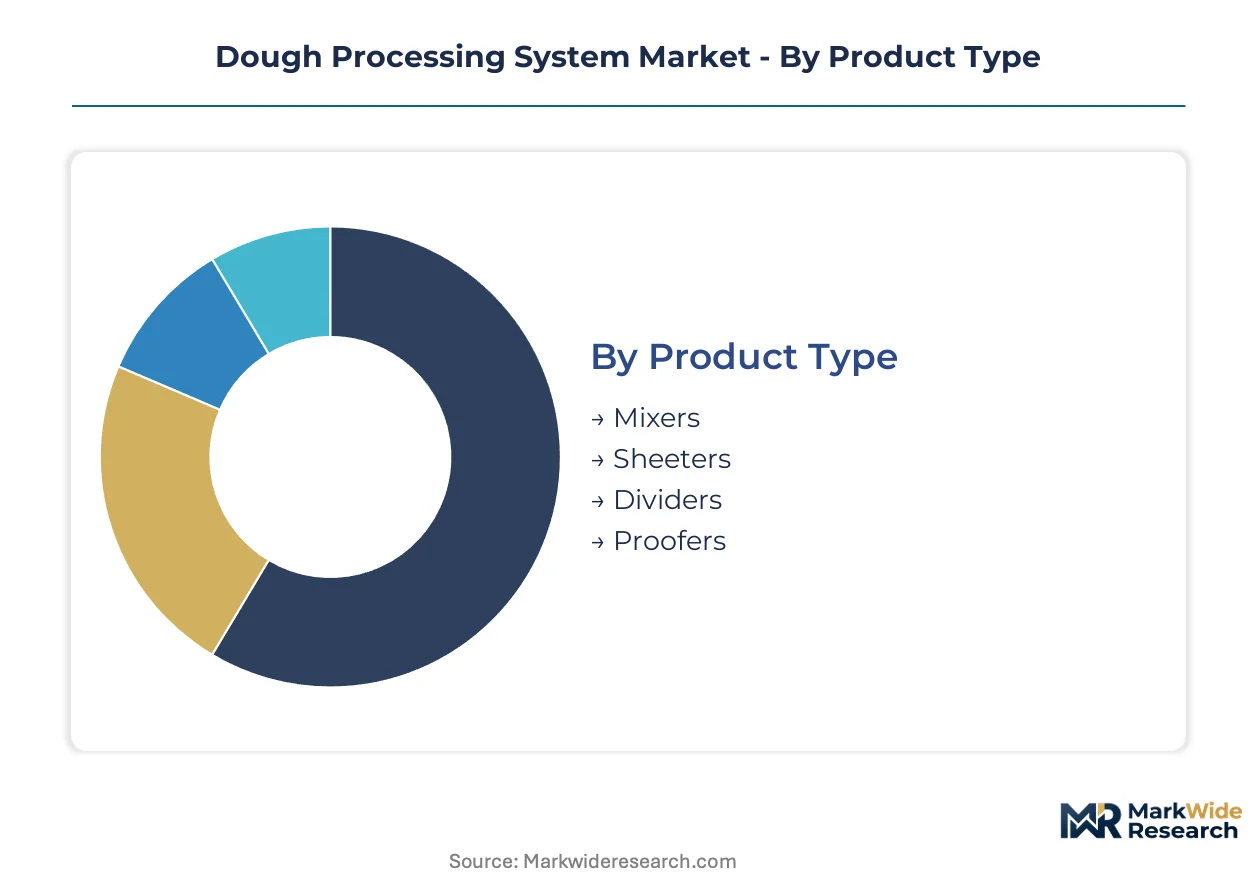
Equipment segmentation in dough processing reveals stark substitution pressures where hybrid architectures threaten pure batch systems, and automated lines displace manual operations. Understanding these cross-segment dynamics illuminates capital allocation priorities for fabricators and procurement timing for end-users.
Product Type:
Substitution pressure runs strongest against standalone proofers as integrated lines absorb fermentation control, while precision dividers face encroachment from robotic portioning technologies in high-volume plants.
- Mixers:These machines employ planetary, spiral, or twin-arm agitation mechanisms to develop gluten networks in dough masses ranging from 50 kg to 2,000 kg. German industrial bakeries and U.S. quick-service restaurant commissaries are concentrating procurement here as hydration precision becomes a competitive differentiator in high-moisture formulations.
- Sheeters:Roller-gap systems reduce dough to calibrated thickness sheets for laminated and flatbread applications, operating at belt speeds up to 30 meters per minute. French and Italian mid-cap bakeries are driving replacement demand as these units enable hybrid batch-continuous flexibility without full line automation.
- Dividers:Volumetric or weight-based portioning equipment cuts bulk dough into uniform pieces for individual product forming.
- Proofers:Controlled-humidity chambers maintain 35°C to 40°C environments for yeast activation and dough relaxation prior to baking.
Mixers retain volume leadership; automated sheeter integrations hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium continuous lines from mid-market hybrid deployments, with batch systems increasingly relegated to artisan and specialty applications.
- Batch Processing:Discrete-cycle operations process defined dough quantities through sequenced mixing, resting, and forming stages, offering formulation flexibility. Artisan bakeries in Belgium and the Netherlands sustain demand here for specialty bread varieties requiring frequent recipe changes.
- Continuous Processing:Uninterrupted dough flow from ingredient feeding through forming eliminates intermediate handling and reduces labor exposure. Large-scale manufacturers in Germany and the United States are expanding these installations as hygiene mandates tighten and labor scarcity intensifies.
- Hybrid Systems:Modular architectures combine batch mixing front-ends with continuous sheeting and dividing downstream.
- Automated Solutions:Sensor-integrated platforms with programmable logic controllers and predictive maintenance capabilities.
Continuous processing commands the premium price tier; hybrid systems are climbing fastest as mid-cap bakeries defer full automation capital outlays.
Application:
Volume concentration in bread processing creates margin pressure, while pizza and snack applications generate equipment upgrade premiums through precision and speed requirements.
- Bread:Pan bread, artisan loaves, and specialty varieties requiring fermentation control and crust development protocols. Industrial bakeries across the United States and Germany anchor demand here, though growth rates trail specialty segments.
- Pastry:Laminated doughs, puff pastries, and viennoiserie demanding precise butter-layer integration and temperature control. French and Belgian producers drive premium equipment specifications for these applications.
- Pizza:High-moisture dough formulations requiring precision dividing and sheeting for consistent base thickness.
- Snacks:Crackers, pretzels, and flatbread variants with specialized forming and cutting requirements.
Bread processing retains installed base dominance; pizza applications are gaining share fastest on quick-service restaurant commissary expansion.
End User:
Customer type determines sanitary design intensity, with food processing plants facing the strictest audit protocols and restaurants prioritizing footprint minimization.
- Bakeries:Artisan and industrial operations ranging from single-unit craft producers to multi-line manufacturing facilities. German and Swiss industrial bakeries are concentrating procurement of ISO 22000-validated equipment as audit cycles eliminate non-compliant suppliers.
- Food Processing Plants:Large-scale integrated facilities supplying retail and foodservice channels with standardized product volumes. U.S. and Canadian plants are driving automated solution demand as NSF International certification becomes mandatory for quick-service restaurant supply contracts.
- Restaurants:On-premise and commissary operations requiring compact, rapid-cycle equipment.
- Catering Services:High-volume event and institutional feeding operations with batch-flexibility requirements.
Food processing plants anchor premium equipment demand; artisan bakeries are expanding fastest as hygiene mandates penetrate smaller-scale operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA enforcement of Current Good Manufacturing Practice regulations and EFSA's EU Hygiene Package are reshaping capital deployment patterns across major baking economies. Equipment procurement concentrates in jurisdictions with stringent audit cycles and elevated labor costs.
United States
Quick-service restaurant commissaries in Texas and California are driving automated sheeting line demand as NSF International certification becomes mandatory for supplier qualification. FDA surface-finish requirements for allergen control extend validation timelines for imported equipment. Chicago and Minneapolis industrial bakery clusters are retrofitting 1990s-era plants with sensor-integrated programmable logic controllers.
Germany
Industrial bakeries in North Rhine-Westphalia and Bavaria are expanding continuous processing installations as ISO 22000 audit cycles eliminate non-compliant fabricators. EFSA HACCP-integrated machinery design mandates pressure equipment redesign for European market access. Stuttgart and Munich manufacturing corridors anchor captive production of hygienic design mixers by dominant domestic groups.
France
Mid-cap bakeries in Île-de-France and Auvergne-Rhône-Alpes are deploying hybrid batch-continuous systems to defer full automation capital outlays. REACH substance restrictions on food-contact lubricants force bearing grease reformulation in high-speed sheeting lines. Lyon and Paris artisan producers sustain demand for specialty bread equipment requiring frequent recipe changes.
Italy
Laminated dough specialists in Lombardy and Emilia-Romagna are specifying premium pastry equipment with precise butter-layer integration. EU Hygiene Package redesign services are emerging as a high-margin advisory segment for Asian exporters seeking market entry. Milan and Bologna industrial zones concentrate procurement of modular, sensor-integrated platforms.
Netherlands
Artisan and industrial bakeries in Randstad are piloting inductive torque sensing retrofit kits at replacement-cycle velocity. EFSA-compliant migration testing for synthetic ester lubricants absorbs certification overhead into premium pricing tiers. Rotterdam and Eindhoven equipment clusters are compressing commissioning timelines through predictive maintenance contract offerings.
Dough Processing System Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers, creating a bifurcated structure where scale-driven groups anchor premium continuous lines and mid-cap fabricators occupy retrofit automation niches. Swiss and German engineering heritage sustains pricing power in automated sheeting and hygienic design segments. Three archetypes dominate: vertically integrated conglomerates with captive manufacturing, precision technology specialists, and regional retrofit service providers. Competitive moves concentrate on sanitary welding certification acquisition and multi-vendor maintenance contract capture.
Among Swiss-based engineering groups, Bühler Group exemplifies the premium-tier archetype through its heritage positioning in automated sheeting lines. German conglomerate GEA Group AG anchors European supply concentration through captive manufacturing capabilities. Japanese precision specialist Rheon Automatic Machinery Co., Ltd. occupies a distinct position in high-moisture dough dividing technology. These three represent divergent strategic paths: heritage engineering premiumization, supply chain vertical control, and formulation-specific precision specialization.
| Leading Market Players |
|---|
| GEA Group AG |
| Bühler Group |
| Ali Group |
| Middleby Corporation |
| Rheon Automatic Machinery Co., Ltd. |
| AMF Bakery Systems |
| John Bean Technologies Corporation |
| Rademaker BV |
| WP Bakery Group |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation contracts with German and Swiss fabricators lock in stainless steel 316L supply visibility while insulating premium-tier buyers from spot-market volatility in commodity-grade equipment. These arrangements concentrate procurement power among ISO 22000-validated suppliers as FDA and EFSA audit cycles eliminate second-source alternatives for hygienic design mixers and sheeters.
Pricing Analysis
Certification level creates the primary spread between premium Swiss-engineered continuous lines and commodity Asian imports. Three-tier pricing structure across validated, mid-market, and unvalidated equipment tiers reflects audit-cycle elimination of non-compliant fabricators. Cost compression in the mid-tier intensifies because REACH-compliant lubricant reformulations absorb certification overhead. Artisan bakeries in Belgium and the Netherlands exhibit highest price sensitivity, while U.S. quick-service restaurant commissaries prioritize NSF International validation over unit economics.
Supply Chain Analysis
Port congestion on Hamburg-Rotterdam trade lanes elevates inbound logistics costs for stainless steel 316L mill shipments from German and Austrian suppliers. Captive manufacturing concentrates in Germany, Switzerland, and Japan, with precision dividing technology drawing from Japanese specialist engineering. Single-source vulnerability runs through qualified orbital welders certified to 3-A sanitary standards. Distribution runs through OEM-direct channels for large industrial bakeries and specialized foodservice equipment distributors for mid-cap buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across FDA, EFSA, and national hygiene mandates fragments vendor qualification, creating white-space niches for retrofit automation specialists and certification consulting services.
For Market Incumbents: Fortify captive manufacturing positions in Stuttgart and Munich corridors through backward integration into stainless steel 316L processing. Acquire scarce 3-A sanitary welding certification capacity before labor shortages constrain expansion. Defend against Asian exporters redesigning for EU Hygiene Package compliance by accelerating HACCP-integrated machinery advisory services.
For New Entrants and Emerging Players: Anchor in Canadian industrial bakery retrofit demand for sensor-integrated programmable logic controller upgrades on 1990s-era sheeting lines. Target the NSF International certification gap for U.S. quick-service restaurant supply contracts through third-party validation partnerships. Pursue go-to-market alignment with Texas and California channel intermediaries building captive field-service capabilities.
For Investors and Strategic Acquirers: Precision automation specialists with inductive torque sensing retrofit kits represent the most defensible acquisition archetype as replacement-cycle velocity accelerates in the Netherlands and Belgium. Monitor EFSA-compliant synthetic ester lubricant validation timelines as an inflection signal for German fabricator margin expansion. Long-term viability hinges on regulatory compliance service bundling rather than pure equipment manufacturing.
| Strategic Initiative | Industry Significance |
|---|---|
| Sanitary Welding Certification Acquisition | 3-A standard compliance unlocks premium pricing in FDA-regulated U.S. commissary contracts. |
| Retrofit Automation Kit Development | Sensor-integrated PLC upgrades capture replacement-cycle demand in Canadian industrial bakeries. |
| HACCP-Integrated Machinery Consulting | EU Hygiene Package redesign services generate high-margin advisory revenue from Asian exporters. |
| Predictive Maintenance Contract Unbundling | After-sales service separation compresses OEM recurring revenue but opens third-party technician channels. |
| Synthetic Ester Lubricant Validation | REACH-compliant bearing grease reformulation absorbs certification overhead into German premium pricing tiers. |
Research Methodology
Desk research of trade association technical standards, customs import records, and regulatory filing databases preceded structured interviews with plant engineers at industrial bakeries, procurement leads at quick-service restaurant commissaries, aftermarket service heads, and certification auditors. Primary fieldwork with equipment fabricators in Germany, Switzerland, and Japan validated secondary data on stainless steel input costs and sanitary design compliance timelines. Bottom-up equipment shipment analysis and top-down bakery capacity expansion tracking were triangulated against FDA and EFSA enforcement patterns.
Variance decomposition across product type, technology architecture, application segment, and end-user scale informed volume and value projections throughout the forecast period. CAGRs were derived from replacement-cycle velocity analysis and capital expenditure intention surveys. Modeled inputs included ISO 22000 audit cycle elimination rates, REACH substance restriction compliance costs, and labor scarcity indices in North American and Western European manufacturing corridors.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory enforcement intensity and stainless steel price volatility within historical bands; material deviation would warrant model refresh. Specific risks include accelerated manual processing exemption phase-outs, breakthroughs in non-metallic food-contact surfaces, and trade policy disruptions affecting German-Japanese precision component flows. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Food Recycler Market
Food Processing Equipment
Pet Food Extrusion Market
Food Processing Equipment
Food Waste Disposal Equipment Market
Food Processing Equipment
Magnetic Grill Market
Food Processing Equipment
Electric Chicken Scalder Market
Food Processing Equipment
Ice Cream Equipment Market
Food Processing Equipment
Food Automation Market
Food Processing Equipment
Craft Brewery Equipment Market
Food Processing Equipment
Frozen Food Processing Machinery Market
Food Processing Equipment
Automatic Evisceration System Market
Food Processing Equipment
Water Cooled Cube Ice Machines Market
Food Processing Equipment
Glass Processing Equipment Market
Food Processing Equipment
Europe Commercial Sous Vide Machine Market
Food Processing Equipment
Commercial Tunnel Oven Market
Food Processing Equipment
Dry Ice Market
Food Processing Equipment
Electric Meat Saw Market