
 Dog Clothing and Accessories Market | 2026-2036
Dog Clothing and Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Dog Clothing and Accessories Market Analysis
Veterinary textile engineering talent is rotating from equine and livestock supply chains into companion animal apparel, unlocking technical garment development previously absent in pet fashion. Chewy, Inc. leverages its direct-to-consumer platform to control digital shelf space for seasonal collections. Ruffwear Inc. anchors the performance sub-segment with technical sportswear designed for trail and working dogs. TRIXIE Heimtierbedarf GmbH & Co. KG sustains European manufacturing scale through specialized distribution to independent pet retailers.
Dog clothing and accessories encompass functional and decorative garments engineered from woven, knitted, or bonded textiles with specifications including waterproof ratings measured in millimeters of hydrostatic head, breathability indices in grams per square meter per twenty-four hours, and reflective tape coverage meeting visibility standards for low-light safety. The primary commercial purpose spans thermoregulation, injury protection, identification, and anthropomorphic expression by pet owners. Coats and sweaters occupy the mature volume base of the market, while sportswear captures expanding margin pools as active outdoor recreation with dogs proliferates. Waterproof and reflective features command premium positioning, whereas cotton and fleece materials dominate unit economics in mass-market channels.
The US Consumer Product Safety Commission and the EU's REACH regulation govern chemical content and flammability in pet textiles, with California's Proposition 65 creating de facto national compliance thresholds for brands distributing in North America. The OEKO-TEX Standard 100 certification is displacing unverified material claims as a baseline procurement filter among specialty retailers and discerning pet owners. Stakeholders must monitor how evolving extended producer responsibility frameworks for textiles reshape cost structures and sourcing geography for synthetic materials.
Market Dynamics
EU REACH chemical restrictions and California Proposition 65 compliance thresholds are forcing pet textile manufacturers to requalify entire material libraries, creating a bifurcation between certified and uncertified supply bases.
Growth Catalysts
- REACH textile amendments:The EU's tightening limits on azo dyes and heavy metals in consumer textiles are accelerating OEKO-TEX Standard 100 adoption across pet apparel supply chains.
- Urban pet density:Coastal metropolitan clusters in the United States with high companion animal ownership per capita are concentrating demand for functional outerwear.
- Veterinary textile engineering migration:Technical talent from equine and livestock equipment sectors is transferring advanced thermoregulation and biomechanical fit knowledge into companion animal garments.
Market Restraints
- Polyester price volatility:Synthetic fiber costs fluctuate with crude oil derivatives, compressing margin stability for mass-market fleece and shell producers.
- East Asian dye house concentration:Specialty colorant and finishing capacity clusters in Zhejiang and Guangdong provinces create single-source vulnerability for Western brands.
- Flammability testing bottlenecks:CPSC 16 CFR Part 1610 compliance timelines extend product development cycles by four to eight weeks for coated fabrics.
Strategic Opportunities
- Extended producer responsibility frameworks:Pending EU textile waste directives will reward closed-loop material recovery systems with preferential market access.
- Biomechanical sportswear:Trail running and canine agility participation is creating demand for articulated joint patterns and compression textiles previously reserved for human athletic wear.
- Veterinary channel integration:Post-surgical recovery garments represent an underdeveloped prescription-accessory hybrid category with reimbursement potential.
Industry Challenges
- Pattern grading expertise:The scarcity of technical designers capable of translating canine anatomical variation into scalable size runs limits SKU expansion.
- Multi-certification stacking:Simultaneous OEKO-TEX, bluesign, and Proposition 65 compliance requires redundant testing budgets that strain emerging brand cash flows.
- Reflective tape supply fragmentation:High-visibility trim sourcing spans automotive, construction, and apparel sectors, creating allocation conflicts during peak seasonal demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dog Clothing and Accessories Market |
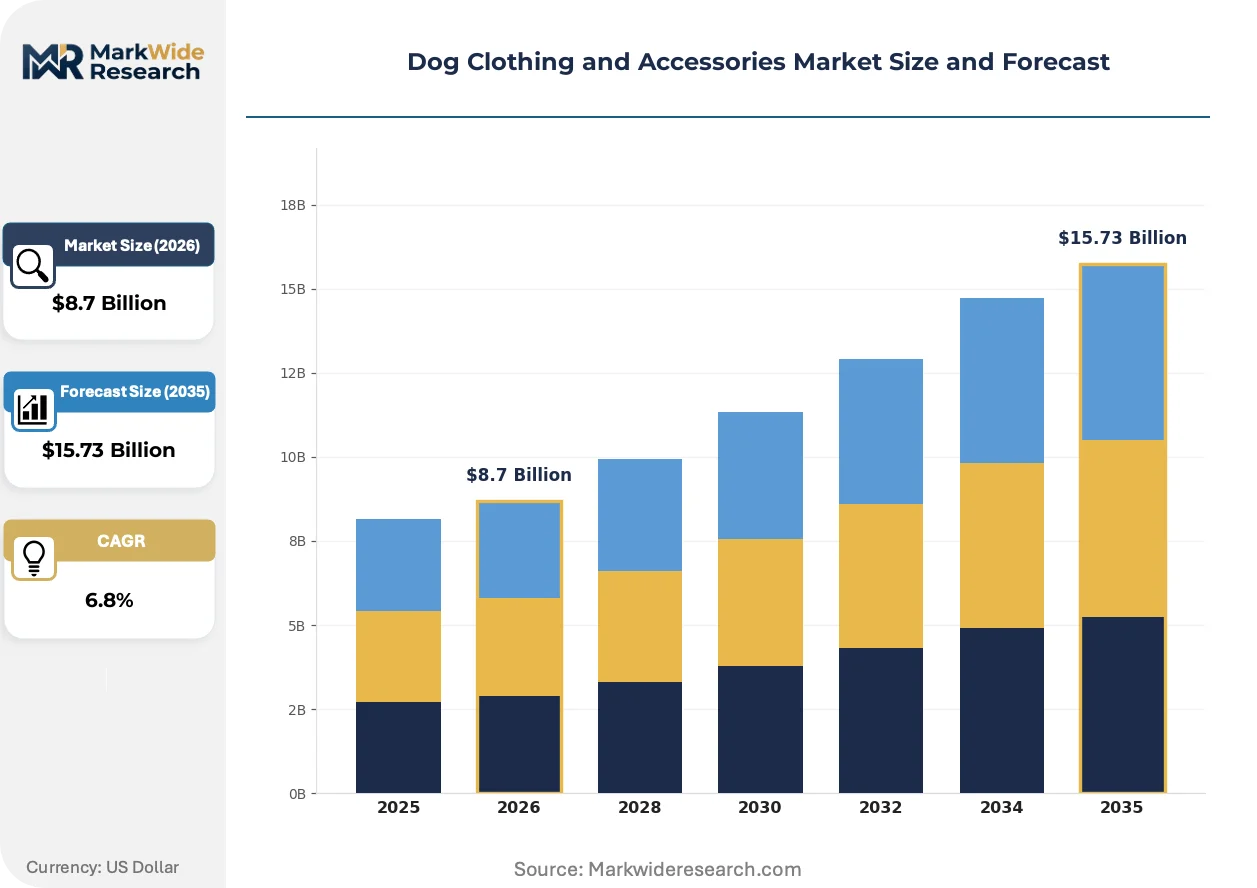
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coats, Sweaters, Costumes, Sportswear Material: Cotton, Polyester, Nylon, Fleece Feature: Waterproof, Reflective, Adjustable, Breathable End User: Pet Owners, Pet Shops, Online Retailers, Grooming Salons |
| Companies Covered | Petco Animal Supplies, Inc., PetSmart, Chewy, Inc., Ruffwear Inc., Canada Pooch, Moshiqa, Bitch New York, Milk & Pepper, TRIXIE Heimtierbedarf GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dog Clothing and Accessories Market Emerging Trajectories
Material science convergence with veterinary medicine is redefining performance specifications, while regulatory chemistry constraints and generational ownership patterns are reshaping how pet apparel reaches end users.
Seamless knitting technology derived from medical compression hosiery is supplanting cut-and-sew construction in base-layer categories. Premium pet owners in Germany and the Netherlands are adopting these garments for senior dogs with circulation limitations. The shift eliminates seam abrasion points and enables zoned compression mapping previously unavailable in pet markets.
California's Proposition 65 warning label requirements are de facto nationalizing chemical disclosure standards for brands distributing through US retail channels. The regulation forces reformulation of polyurethane coatings and flame-retardant treatments. Waterproof breathable membrane suppliers are accelerating PFAS-free alternatives to maintain shelf placement in specialty outdoor retailers.
Subscription-based seasonal wardrobe replenishment is displacing transactional e-commerce for core apparel categories. Millennial pet owners in urban United States markets are prioritizing curated delivery over search-based purchasing. Chewy, Inc. and independent direct-to-consumer brands are capturing lifetime value through size-prediction algorithms and automated replacement cycles for outgrown garments.
Dog Clothing and Accessories Market Segmentation
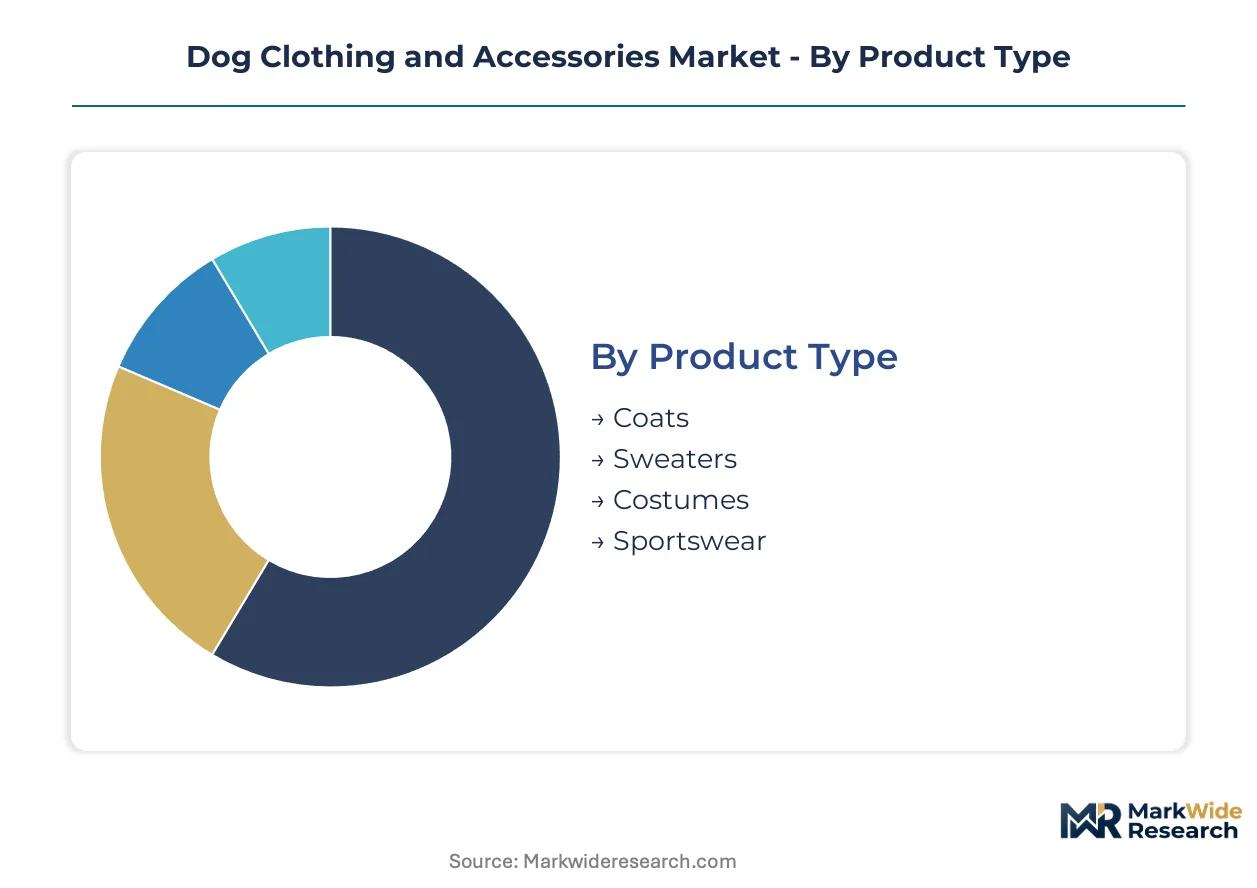
Segmentation in dog clothing and accessories reveals how margin pools concentrate in performance-driven categories while mass-market volumes anchor unit economics. Understanding these divisions exposes where technical specifications command premium positioning versus where commoditized materials dominate procurement.
Product Type:
Premium positioning concentrates in technical sportswear and seasonal outerwear, while costumes capture impulse-driven margin spikes.
- Coats:Waterproof and insulated shell garments engineered with taped seams and hydrostatic head ratings. Urban coastal markets in the United States with high pet ownership density drive replacement cycles for weather-damaged units.
- Sportswear:Technical trail and working dog apparel incorporating articulated joint patterns and compression textiles. Canine agility and trail running participation in Germany and the Netherlands is accelerating demand for biomechanical fit specifications previously reserved for human athletic wear.
- Sweaters:Knitted thermoregulation layers in wool and acrylic blends for indoor comfort and senior dog circulation support.
- Costumes:Seasonal and event-driven decorative garments with short purchase windows and high social media visibility.
The dominant share belongs to Coats, while Sportswear is closing the gap fastest.
Material:
Cost tier stratification separates certified sustainable fibers from commodity synthetics facing regulatory pressure.
- Polyester:Dominant synthetic fiber for fleece linings and shell fabrics, with price volatility tied to crude oil derivatives. EU REACH restrictions on heavy metals in dyes are forcing reformulation of conventional polyester finishing treatments.
- Cotton:Natural fiber base for breathable base layers and mass-market knitwear. California Proposition 65 compliance requirements are elevating testing costs for cotton garment producers distributing through US retail channels.
- Nylon:High-tenacity fiber for abrasion-resistant performance outerwear and leash hardware integration.
- Fleece:Recycled and virgin polyester pile fabrics dominating thermoregulation layers in mid-market price bands.
Polyester retains volume leadership, though cotton is gaining share fastest among OEKO-TEX certified supply chains.
Feature:
Functional specifications determine price band placement more than aesthetic differentiation in specialty retail.
- Waterproof:Membrane and coating technologies measured in millimeters hydrostatic head, with PFAS-free alternatives accelerating to replace legacy chemistries. Specialty outdoor retailers are gatekeeping shelf placement based on environmental chemistry compliance.
- Reflective:High-visibility trim meeting automotive and construction sector visibility standards for low-light safety. Supply fragmentation across multiple industrial sectors creates allocation conflicts during peak seasonal demand.
- Adjustable:Modular fit systems accommodating canine anatomical variation across breed types.
- Breathable:Moisture vapor transmission rates measured in grams per square meter per twenty-four hours for active use scenarios.
Waterproof specifications anchor premium pricing, while Reflective features are expanding most quickly into urban safety-conscious segments.
End User:
Channel structure shapes procurement specifications, with veterinary and professional grooming channels demanding higher compliance standards than mass retail.
- Pet Owners:Direct consumers purchasing through e-commerce and specialty retail, with subscription-based seasonal replenishment displacing transactional buying. Millennial and Gen Z demographics in US urban coastal metros prioritize curated delivery over search-based purchasing.
- Pet Shops:Independent and chain retailers requiring OEKO-TEX Standard 100 certification as baseline procurement filters.
- Online Retailers:Digital-native platforms controlling shelf space through algorithmic curation and size-prediction automation.
- Grooming Salons:Professional service providers integrating post-grooming apparel sales with service appointments.
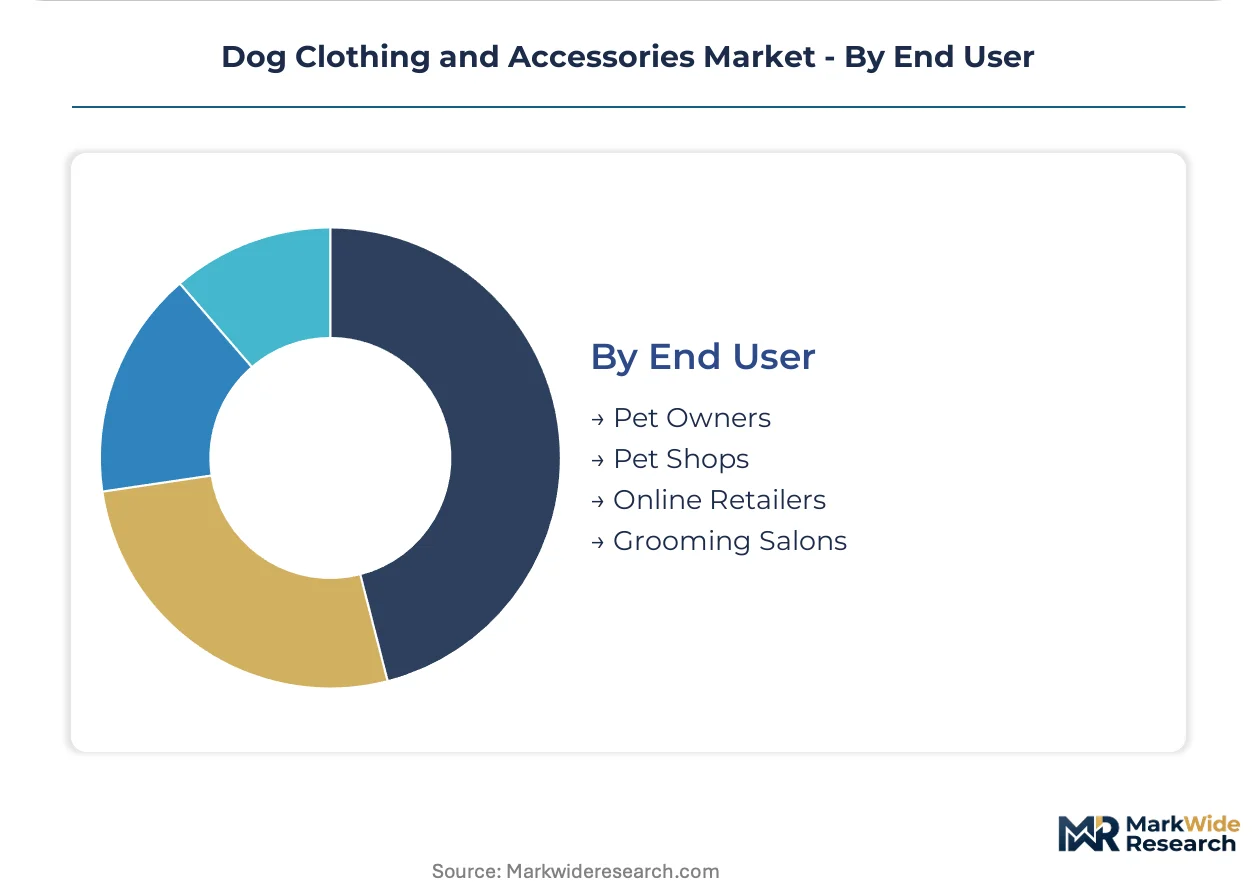
Pet Owners command the largest addressable base, while Online Retailers are capturing share fastest through direct-to-consumer platform economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States Consumer Product Safety Commission and California's Proposition 65 establish de facto compliance thresholds that shape material sourcing decisions across North American pet textile supply chains.
United States
Urban coastal metros including New York, Los Angeles, and Seattle concentrate companion animal ownership density and drive replacement cycles for weather-damaged outerwear. The CPSC's 16 CFR Part 1610 flammability standard extends product development timelines by four to eight weeks for coated fabrics. Pacific Northwest manufacturing clusters near Portland specialize in waterproof breathable membrane assembly for trail-oriented sportswear brands.
Germany
Canine agility participation and trail running with dogs accelerates demand for biomechanical fit specifications in technical garments. ECHA's REACH enforcement tightens limits on azo dyes and heavy metals in consumer textiles, forcing reformulation of conventional finishing treatments. Bavarian textile engineering firms near Munich transfer medical compression hosiery technology into seamless knitting applications for senior dog circulation support.
United Kingdom
Subscription-based seasonal wardrobe replenishment displaces transactional e-commerce among millennial pet owners in London and Greater Manchester. The UK's post-Brexit regulatory alignment with EU REACH maintains chemical compliance burdens for imported pet textiles. Midlands manufacturing retains specialized capacity for reflective trim integration meeting automotive sector visibility standards.
Netherlands
Premium pet owners in Amsterdam and Rotterdam adopt seamless base-layer garments for aging companion animals with thermoregulation needs. The EU Green Deal's textile sustainability directives accelerate OEKO-TEX Standard 100 adoption across independent pet retailer procurement. Eindhoven-region technical textile developers pioneer zoned compression mapping previously unavailable in companion animal markets.
Canada
Cold-climate functional outerwear demand concentrates in Toronto, Vancouver, and Calgary metropolitan areas with high pet ownership density. Health Canada and PMRA oversight of chemical treatments in imported textiles elevates testing costs for brands distributing through North American retail channels. Quebec-based manufacturing clusters specialize in insulated shell garments with hydrostatic head ratings for extreme weather exposure.
Dog Clothing and Accessories Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the dog clothing and accessories market. Direct-to-consumer platforms and specialty outdoor retailers command differentiated shelf space through algorithmic curation and technical specification gatekeeping. Three archetypes dominate: vertically integrated pet supply conglomerates, technical performance apparel specialists, and European manufacturing-scale distributors. Competitive moves concentrate on digital platform control and closed-loop material certification stacking.
Within the integrated conglomerate tier, Chewy, Inc. and Petco Animal Supplies, Inc. represent the platform-dominant archetype. Ruffwear Inc. and TRIXIE Heimtierbedarf GmbH & Co. KG occupy positions exemplifying technical specialization and European manufacturing scale respectively. These named entities anchor industry-level commentary on how direct-to-consumer automation and OEKO-TEX procurement filtering reshape competitive positioning.
| Leading Market Players |
|---|
| Petco Animal Supplies, Inc. |
| PetSmart |
| Chewy, Inc. |
| Ruffwear Inc. |
| Canada Pooch |
| Moshiqa |
| Bitch New York |
| Milk & Pepper |
| TRIXIE Heimtierbedarf GmbH & Co. KG |
| Others |
Supply Flow & Price Mechanics
OEKO-TEX Standard 100 certification gates both supplier qualification and price tier placement in pet apparel procurement, forcing brands to absorb testing costs or forfeit shelf space at specialty retailers. This dual-filter mechanism stratifies the market into certified premium supply chains and uncertified commodity channels, with California Proposition 65 compliance layering additional cost burdens on brands distributing through US retail.
Pricing Analysis
Geographic price spreads widen between EU-certified supply chains and mass-market Asian production, with German and Dutch specialty retailers commanding premiums for seamless compression garments. Pricing stratifies across premium, standard, and economy tiers based on certification grade and waterproof membrane technology, with PFAS-free alternatives capturing margin premiums as specialty outdoor retailers gatekeep shelf placement. Cost compression in polyester fleece segments intensifies because crude oil derivative volatility feeds directly into synthetic fiber input costs. Mass-market pet owners in suburban US markets exhibit highest price sensitivity, while urban coastal millennials prioritize subscription-based curation over unit economics.
Supply Chain Analysis
Inventory strategy preferences favor just-in-time replenishment for seasonal collections, though reflective tape suppliers maintain strategic stockpiles against allocation conflicts during peak demand windows. Manufacturing concentrates in China, Vietnam, and Bangladesh for cut-and-sew assembly, with Portuguese and Italian mills supplying certified technical textiles for premium tiers. Raw material dependencies center on petroleum-derived polyester chips, Zhejiang-district specialty dyes, and automotive-sector reflective trim. Single-source vulnerability in East Asian dye house concentration threatens color consistency for Western brands. Distribution runs through direct-to-consumer platforms, independent pet retailers, and veterinary channel partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment, where multi-certification compliance creates switching costs that trap incumbents and deter marginal entrants simultaneously.
For Market Incumbents: Fortify supply chain control through backward integration into certified textile milling or captive dye house partnerships, eliminating third-party OEKO-TEX testing redundancy. Deepen platform data advantages at Chewy, Inc. by training size-prediction algorithms on replacement cycle patterns, raising switching costs for subscription customers. Threats from veterinary-channel entrants with prescription-accessory hybrids demand preemptive category expansion into post-surgical recovery garments. For New Entrants and Emerging Players: Lead with biomechanical sportswear for trail running and canine agility segments in Germany and the Netherlands, where technical specifications command price premiums and incumbent R&D lags. Target underdeveloped prescription-accessory hybrids through veterinary channel partnerships, leveraging reimbursement potential absent in retail. Go-to-market execution should prioritize direct-to-consumer automation with size-prediction algorithms rather than competing for shelf space at established specialty retailers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across seamless knitting technology and PFAS-free membrane development, favoring scaled platforms with R&D amortization capacity over capital-constrained specialists. Long-term viability across the projection horizon rests on closed-loop material recovery systems aligned with pending EU textile waste directives. Acquisition targets should display OEKO-TEX certification stacking capability and veterinary channel relationships. Watch for inflection when extended producer responsibility frameworks trigger preferential market access for circular supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Membrane Transition | Specialty outdoor retailers gatekeep shelf placement based on environmental chemistry compliance thresholds. |
| Seamless Knitting Technology Adoption | Bavarian medical textile engineers transfer compression hosiery expertise into senior dog circulation garments. |
| Veterinary Channel Integration | Post-surgical recovery garments unlock prescription-accessory hybrid category with reimbursement potential. |
| Subscription Platform Automation | Size-prediction algorithms at Chewy, Inc. capture lifetime value through automated replacement cycles. |
| Closed-Loop Material Recovery | EU textile waste directives reward circular supply chains with preferential market access. |
Methodological Framework
Desk research of trade customs records, SEC filings from pet supply platforms, and EU regulatory databases preceded structured interviews with veterinary textile engineers, specialty pet retailer buyers, and direct-to-consumer brand operations leads. Primary fieldwork combined with secondary validation from OEKO-TEX certification registries and California Proposition 65 enforcement actions. Bottom-up SKU-level modeling triangulated against top-down market sizing from platform revenue disclosures and import volume tracking.
Variance decomposition across product type, material certification tier, feature specification, and end-user channel shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate blending weighted by revenue concentration. Industry-specific inputs included canine agility participation rates, urban pet ownership density indices, and veterinary prescription garment reimbursement eligibility patterns.
The analysis sits within stated boundaries; outcomes outside sustained millennial pet ownership trends or stable EU regulatory enforcement would require recalibration. Forecasts reflect assumptions about REACH textile amendment timelines and Proposition 65 warning label expansion. Revision becomes warranted when polyester feedstock volatility or East Asian dye house consolidation crosses thresholds that alter margin structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Cat Furniture and Scratchers Market
Pet Care Products
Dog Muzzle Market
Pet Care Products
Cat Litter Boxes Market
Pet Care Products
Global Kennel Software Market
Pet Care Products
Automatic and Smart Pet Feeder Market
Pet Care Products
Dog Raincoats Market
Pet Care Products
Dog Food for Small Breeds Dogs Market
Pet Care Products
North America Pet Food Market
Pet Care Products
Raw Meat Pet Food Market
Pet Care Products
DTC Pet Food Market
Pet Care Products
Italy Pet Food Market
Pet Care Products
Thailand Pet Food Market
Pet Care Products
Europe Organic and Natural Pet Food Market
Pet Care Products
Dog Litter Boxes Market
Pet Care Products
Europe Organic Pet Food for Cats and Dogs Market
Pet Care Products
UK Pet Training Services Market