
 Pet Pee Pads Market | 2026-2036
Pet Pee Pads Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Pee Pads Market Analytics
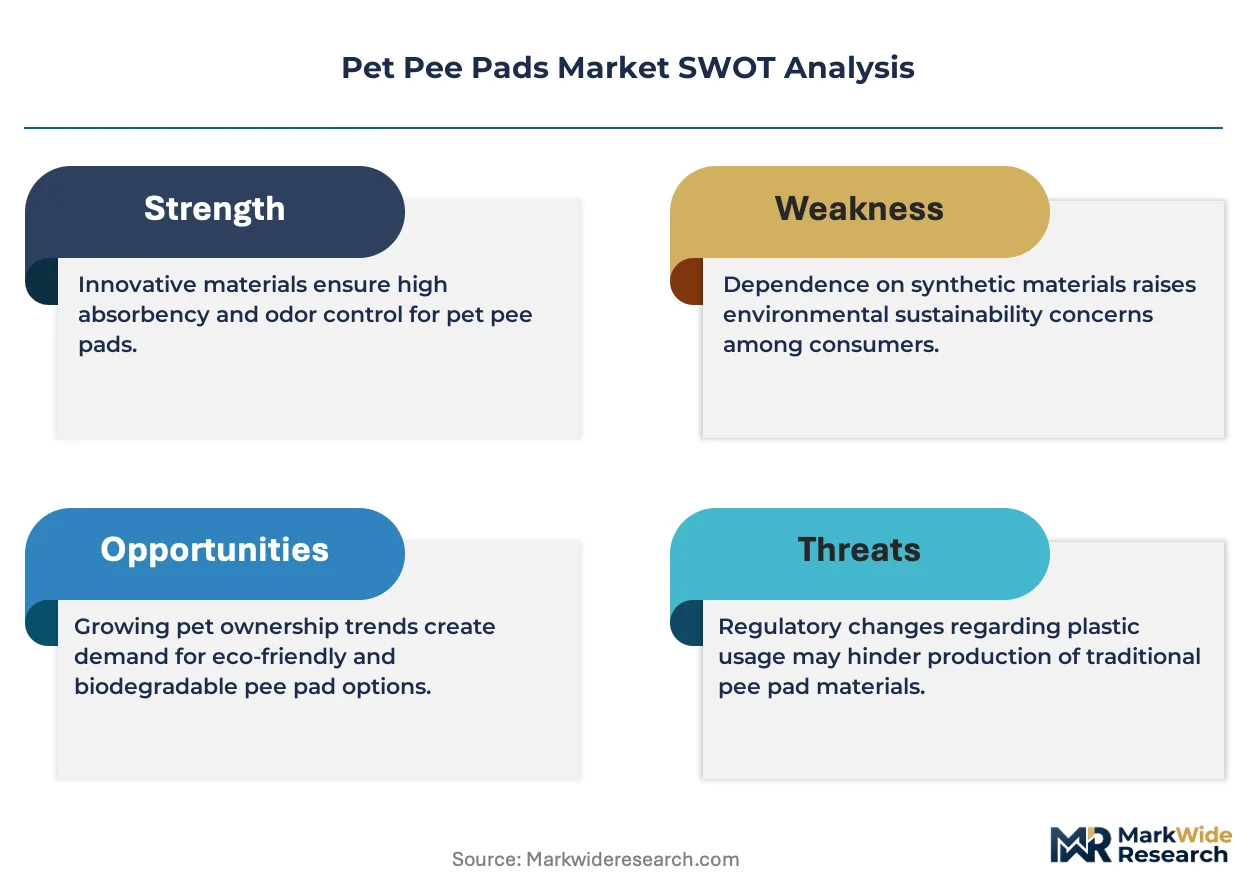
Asset-light contract manufacturing is tilting competitive economics toward brands that outsource production rather than build captive mills. Hartz leverages Unicharm's polymer science heritage to sustain absorbency performance across climate variations. IRIS USA anchors its position through direct control over North American distribution channels. JiangXi SenCen specializes in bamboo-fiber substrates that differentiate its environmental profile against petroleum-based rivals.
Pet pee pads are multi-layer absorbent mats engineered with a permeable top sheet, fluff pulp or polymer core, and waterproof polyethylene or plant-derived backing, designed to capture animal urine while protecting flooring surfaces. Disposable variants dominate volume due to convenience-driven purchasing by urban pet owners, though bamboo and cotton materials are gaining structural share as biodegradability becomes a procurement filter for veterinary clinics and animal shelters. Washable pads command higher per-unit economics but lower purchase frequency, concentrating margin pools in the premium tier of the product type segmentation.
The EPA oversees landfill impact standards for saturated disposable products in the United States, while REACH compliance in Europe restricts certain adhesive and plasticizer chemistries used in pad construction. China's SAMR enforces GB standards on imported absorbent hygiene products, creating a compliance threshold for cross-border suppliers. Stakeholders must monitor how fragmented national bioplastics certification regimes reshape raw material sourcing decisions and manufacturing location choices.
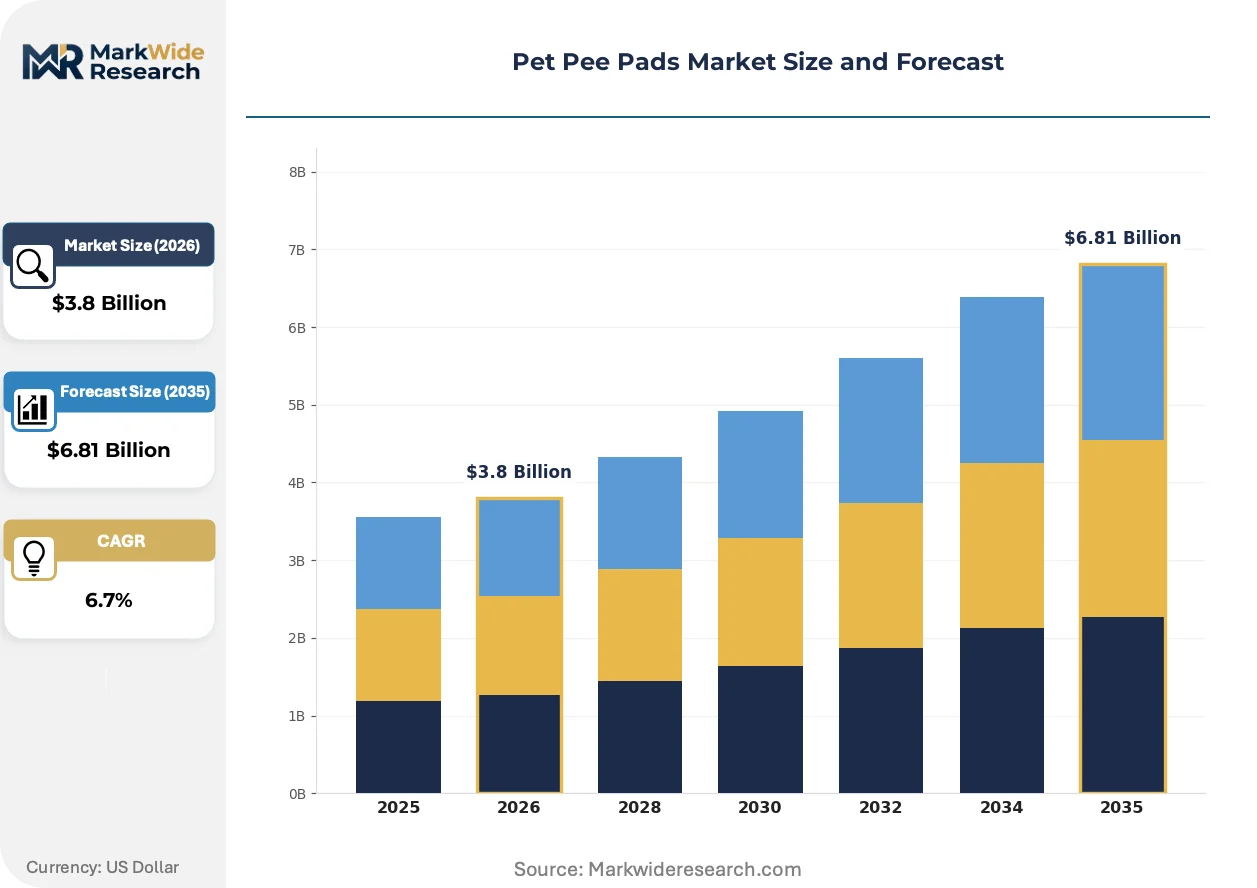
Market Dynamics
Biodegradable substrate chemistry is restructuring raw material sourcing as veterinary clinics and municipal shelters in Germany, France, and the Netherlands convert procurement specifications to plant-derived absorbency cores under EU Green Deal compliance timelines.
Growth Catalysts
- REACH chemical restrictions:European adhesive and plasticizer bans force reformulation toward bio-based binders, opening premium positioning for compliant domestic manufacturers.
- Urban apartment density:United States metropolitan household formation concentrates repeat purchase volume for disposable convenience formats among time-constrained pet owners.
- Superabsorbent polymer advances:Japanese polymer science heritage enables thinner core architectures that reduce shipping cube and warehousing costs for distributors.
Market Restraints
- Fluff pulp supply concentration:Brazilian and Scandinavian softwood pulp mills control input pricing for conventional pad cores, exposing converters to freight and fiber cost volatility.
- Polyethylene backing dependency:Petrochemical supply chain concentration in Gulf Coast refineries creates single-source vulnerability for waterproof layer integrity.
- Biodegradation certification fragmentation:Competing national compostability standards in Germany, Italy, and France force redundant testing spend for cross-border suppliers.
Strategic Opportunities
- India veterinary channel underpenetration:Rising pet ownership in Mumbai, Bangalore, and Delhi creates first-mover advantage for localized absorbency pad distribution.
- Subscription direct-to-consumer models:Auto-replenishment platforms bypass traditional pet specialty retail markup structures and capture lifetime value data.
- China dual carbon policy alignment:SAMR bioplastics certification pathways reward domestic manufacturing of bamboo-fiber substrates with preferential procurement status.
Industry Challenges
- Polymer science talent scarcity:Formulation chemists with superabsorbent hydrogel expertise command premium compensation, constraining mid-tier manufacturer R&D bandwidth.
- Compostability testing timeline compression:Multi-month biodegradation validation cycles delay product launches and tie up working capital in pre-commercial inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Pee Pads Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Washable, Training, Extra Large Material: Plastic, Cotton, Microfiber, Bamboo End User: Pet Owners, Veterinary Clinics, Pet Stores, Animal Shelters Distribution Channel: Online Retail, Supermarkets, Pet Specialty Stores, Distributors |
| Companies Covered | DoggyMan, IRIS USA, Hartz (Unicharm), JiangXi SenCen, U-PLAY, Tianjin Yiyihygiene, Richell, WizSmart (Petix), Jiangsu Zhongheng, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Pee Pads Market Evolving Landscape
Material science convergence with circular economy mandates is compressing product development cycles and forcing simultaneous performance and sustainability validation before commercial launch.
Superabsorbent polymer chemistry is migrating from petroleum-derived sodium polyacrylate to bio-based polysaccharide hydrogels. German veterinary clinics now specify plant-derived cores for municipal shelter contracts. This transition is compressing margin structures for conventional petrochemical-dependent converters while enabling premium pricing for certified bio-alternatives.
EU Green Deal packaging waste directives are accelerating end-of-life accountability requirements. Manufacturers must now document compostability pathways or pay extended producer responsibility fees. Small-format private label suppliers in Italy and Spain face disproportionate compliance cost burdens relative to integrated multinationals with in-house certification laboratories.
Urban pet owners are consolidating purchase decisions around subscription platforms that bundle pee pads with nutrition and grooming categories. Direct-to-consumer channels in New York, Los Angeles, and Chicago capture recurring revenue streams that pet specialty retailers cannot match. This disintermediation forces traditional distributors to add value through same-day delivery infrastructure or surrender volume to platform aggregators.
Pet Pee Pads Market Segmentation
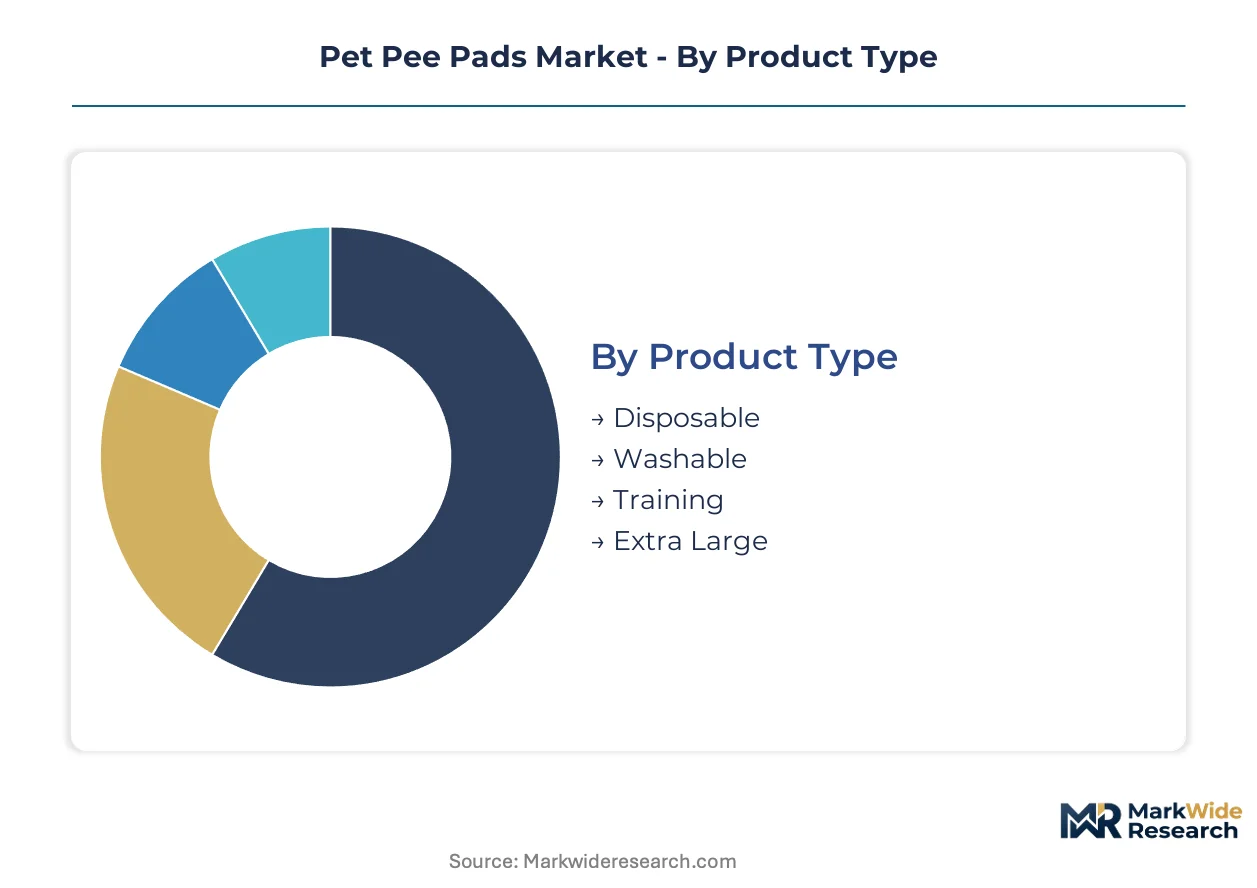
Segmentation in pet pee pads reveals how convenience preferences, sustainability mandates, and channel economics split demand across divergent purchasing behaviors. Manufacturers must align R&D and distribution investments to the specific performance and procurement criteria governing each segment cluster.
Product Type:
Use-case spectrum spans single-use convenience through multi-cycle durability, with size specialization addressing breed-specific containment needs.
- Disposable:Multi-layer construction with fluff pulp or polymer cores and polyethylene backing dominates urban apartment purchases. United States metropolitan households drive repeat volume through convenience-driven subscription replenishment.
- Washable:Cotton or microfiber substrates with waterproof PUL layers support 200+ wash cycles. Premium pricing concentrates margin pools among eco-conscious pet owners in Germany and France seeking landfill diversion.
- Training:Scent-attractant formulations with pheromone additives accelerate housebreaking for puppies and rescue animals. Veterinary behaviorists in Japan specify these for post-surgical recovery protocols.
- Extra Large:Expanded surface area accommodates giant breeds and multi-pet households. Demand clusters in suburban United States markets with higher dog ownership density.
The dominant share belongs to Disposable, while Washable is closing the gap fastest as EU Green Deal compliance timelines accelerate biodegradable procurement.
Material:
Raw material selection determines regulatory compliance pathways, end-of-life accountability, and margin compression exposure across geographies.
- Plastic:Petroleum-derived polyethylene backings and sodium polyacrylate cores face REACH restrictions in Europe. Gulf Coast petrochemical concentration creates supply vulnerability for converters dependent on conventional chemistries.
- Cotton:Natural fiber absorbency with biodegradable certification supports municipal shelter contracts in France and Italy. Higher unit costs limit penetration to premium veterinary channels.
- Microfiber:Synthetic polyester blends offer rapid-dry properties for washable pad architectures. Chinese manufacturers leverage domestic textile infrastructure for cost-competitive export supply.
- Bamboo:Rapid-renewable cellulose fibers align with China's dual carbon policy and SAMR bioplastics certification. JiangXi SenCen anchors specialized production for EU veterinary clinic specifications.
Plastic retains volume leadership, though Bamboo exhibits the steepest expansion trajectory as plant-derived cores displace petroleum substrates in regulated European markets.
End User:
Customer-type concentration shapes pricing power, with institutional procurement favoring certified biodegradability and retail channels prioritizing unit economics.
- Pet Owners:Individual purchasers in United States urban apartments drive disposable convenience formats through subscription platforms. Time-constrained demographics prioritize absorbency performance over environmental certification.
- Veterinary Clinics:German clinics now mandate higher-absorbency biodegradable pads under EU Green Deal shelter contract requirements. REACH-compliant adhesive formulations command procurement premiums.
- Pet Stores:Specialty retailers in Los Angeles and Chicago bundle pads with nutrition categories. Same-day delivery infrastructure defends volume against platform disintermediation.
- Animal Shelters:Municipal facilities in the Netherlands and France convert specifications to plant-derived cores. Budget constraints favor bulk procurement of certified compostable alternatives.
Pet Owners command the largest addressable base, while Veterinary Clinics are expanding most quickly as regulatory compliance reshapes institutional procurement.
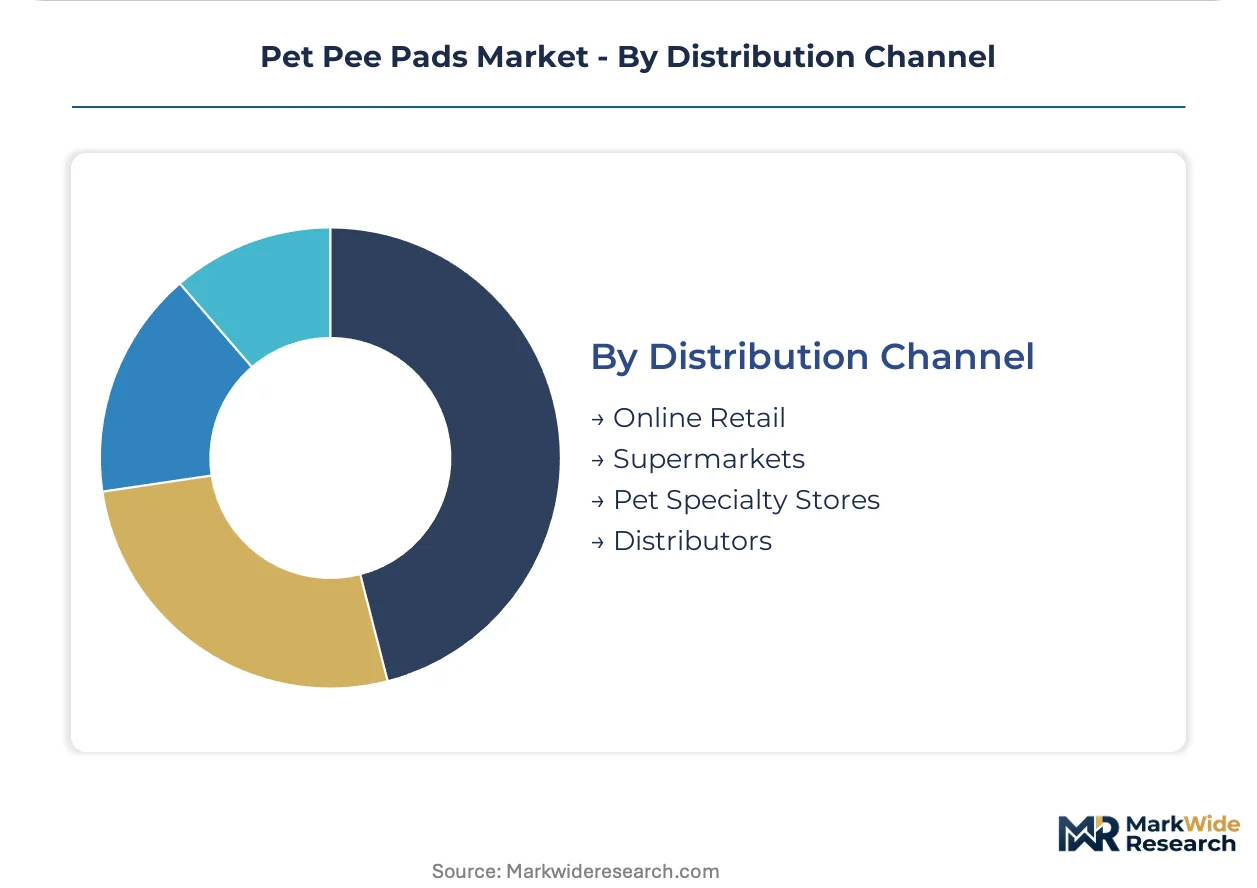
Distribution Channel:
Channel configuration determines margin capture, with direct platforms eroding traditional retail markup structures through recurring revenue models.
- Online Retail:Amazon and Chewy subscription auto-replenishment captures lifetime value data from United States metropolitan households. IRIS USA defends position through direct distribution control.
- Supermarkets:Mass-market placement in Walmart and Target stores reaches price-sensitive first-time pet owners. Private label suppliers face working capital pressure from extended payment terms.
- Pet Specialty Stores:Independent retailers in New York and Chicago add value through staff consultation and same-day delivery. Differentiation erodes as platform aggregators consolidate demand.
- Distributors:Regional wholesalers serve veterinary clinics and shelter networks with bulk logistics. European distributors absorb redundant compostability testing costs from fragmented national certification regimes.
Online Retail holds the dominant position, while Distributors are gaining share fastest as institutional procurement consolidates through specialized supply agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from Chinese bamboo-fiber substrate producers now exceed inbound fluff pulp shipments to European converters, reversing historical trade patterns as plant-derived cores displace petroleum-based imports under EU Green Deal timelines.
United States
Urban apartment formation in New York, Los Angeles, and Chicago drives subscription auto-replenishment volume for disposable convenience formats. EPA landfill impact standards for saturated hygiene products shape domestic manufacturing compliance costs. Dallas-Fort Worth distribution clusters anchor North American logistics networks for direct-to-consumer platform fulfillment.
Germany
Veterinary clinics in Munich and Berlin now mandate REACH-compliant biodegradable pads for municipal shelter contracts. EU Green Deal packaging waste directives accelerate end-of-life accountability documentation requirements. North Rhine-Westphalia industrial zones concentrate adhesive reformulation R&D for bio-based binder alternatives.
China
SAMR bioplastics certification pathways reward domestic bamboo-fiber production with preferential procurement status under dual carbon policy frameworks. GB standards enforcement on imported absorbent hygiene products creates compliance thresholds for cross-border suppliers. Yangtze River Delta manufacturing hubs specialize in rapid-renewable cellulose fiber processing for EU export markets.
France
Municipal animal shelters in Paris and Lyon convert specifications to certified compostable cores ahead of fragmented national biodegradation deadlines. ANSM oversight of veterinary product safety influences pad formulation standards for clinic procurement. Auvergne-Rhône-Alpes textile infrastructure supports cotton-based absorbency layer production for premium veterinary channels.
Japan
Superabsorbent polymer chemistry heritage from METI-supported materials science programs enables thinner core architectures for export markets. PMDA-aligned veterinary product standards shape domestic clinic procurement specifications. Osaka-Kobe industrial corridors concentrate hydrogel formulation expertise that reduces shipping cube costs for distributors.
Pet Pee Pads Market Competitive Landscape
On the supply side, the industry is bifurcating between asset-light brand licensors and integrated substrate specialists. Tiered competitive positioning separates polymer-science heritage players from bamboo-fiber regionalists and contract-manufacturing platforms. Dominant competitive moves include strategic partnerships for raw material security and direct distribution control to bypass retail markup structures.
Within the integrated manufacturing tier, JiangXi SenCen anchors Chinese bamboo-fiber specialization for EU veterinary clinic specifications, while IRIS USA exemplifies North American distribution control through captive logistics networks. Hartz occupies a position leveraging Unicharm's polymer science heritage across climate-variable absorbency performance requirements.
| Leading Market Players |
|---|
| DoggyMan |
| IRIS USA |
| Hartz (Unicharm) |
| JiangXi SenCen |
| U-PLAY |
| Tianjin Yiyihygiene |
| Richell |
| WizSmart (Petix) |
| Jiangsu Zhongheng |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese bamboo-fiber substrate mills is compressing unit economics for plant-derived absorbency cores while simultaneously enabling aggressive pricing postures against petroleum-based rivals. This utilization dynamic forces European converters to absorb margin pressure or surrender volume to lower-cost Asian suppliers.
Pricing Analysis
Veterinary clinic procurement teams anchor tiered pricing structures across the pet pee pads market, with three-tier pricing separating REACH-certified biodegradable pads from standard disposable variants and economy private-label offerings. Price differentiation rests on certification grade and absorbency performance tier, with EU Green Deal compliance commanding procurement premiums. Cost compression in the standard disposable tier is intensifying because Brazilian fluff pulp freight volatility feeds through to converter margins. Municipal shelter buyers exhibit highest price sensitivity, while German veterinary clinics demonstrate lowest sensitivity due to mandated sustainability specifications.
Supply Chain Analysis
Extended payment terms from Walmart and Target are squeezing working capital for private-label suppliers, forcing reliance on supply-chain finance facilities. Raw material sourcing draws from Chinese bamboo-fiber processors, Brazilian and Scandinavian fluff pulp mills, and Gulf Coast polyethylene refineries. Single-source vulnerability concentrates in waterproof backing supply from petrochemical complexes. Distribution runs through Amazon and Chewy subscription platforms, veterinary clinic distributors, and mass-market retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pet pee pads market functions as a service-attach opportunity where subscription auto-replenishment platforms capture lifetime value data and recurring revenue streams expanding faster than one-time hardware purchases.
For Market Incumbents: Insulate margin pools by securing captive supply of superabsorbent polymer chemistries through backward integration into hydrogel formulation capabilities. Accelerate SAMR bioplastics certification for Chinese manufacturing assets to defend procurement position against domestic bamboo-fiber specialists. Channel control through same-day delivery infrastructure defends volume against platform disintermediation. For New Entrants and Emerging Players: India veterinary channel underpenetration offers first-mover positioning in Mumbai, Bangalore, and Delhi metropolitan markets. Localized absorbency pad distribution partnerships with regional wholesalers bypass established multinational logistics networks. Direct-to-consumer subscription bundling with nutrition categories captures recurring revenue without retail markup surrender. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among subscription platform operators with auto-replenishment algorithms and lifetime value data assets. Long-term viability over a five-to-ten-year horizon favors acquirers of bamboo-fiber substrate specialists with SAMR certification and EU veterinary clinic contract relationships. Monitor compostability certification timeline compression as inflection signal for working capital stress among mid-tier converters.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Core Transition | REACH-compliant adhesive reformulation opens premium positioning for German veterinary clinic contracts. |
| Subscription Platform Integration | Auto-replenishment algorithms capture lifetime value data from United States metropolitan households. |
| Backward Integration into Polymer Science | In-house hydrogel formulation reduces dependency on Japanese superabsorbent polymer suppliers. |
| SAMR Bioplastics Certification | Domestic Chinese manufacturing gains preferential procurement status under dual carbon policy frameworks. |
| Same-Day Delivery Infrastructure | Pet specialty retailers in Chicago and Los Angeles defend volume against Amazon platform erosion. |
Research Methodology
Desk research of trade customs data, veterinary procurement databases, and absorbent hygiene product certification registries preceded structured interviews with polymer formulation chemists, veterinary clinic procurement managers, pet specialty retail category buyers, and bamboo-fiber substrate plant managers. Secondary validation drew from EPA landfill impact filings, ECHA REACH substance registrations, SAMR GB standard publications, and EU Green Deal implementation timelines. Bottom-up demand modeling triangulated against top-down market sizing across product type, material, end user, and distribution channel dimensions.
Forecast assumptions held fixed the EU Green Deal compliance timeline, SAMR bioplastics certification pathway duration, and fluff pulp freight cost structures while varying urban pet ownership density, subscription platform penetration rates, and municipal shelter procurement conversion speed. Segmentation modeling spanned disposable versus washable formats, petroleum-derived versus plant-derived substrates, individual pet owners versus institutional buyers, and online retail versus traditional distribution channels. CAGRs derived from regression analysis of historical volume trends against demographic and regulatory drivers, with superabsorbent polymer chemistry advancement rates and bamboo-fiber processing cost curves as industry-specific inputs.
Macroeconomic conditions sit as an overlay; deviation in petrochemical pricing volatility, container shipping rates, or currency exchange movements would shift the trajectory. Forecasts reflect documented assumptions about regulatory implementation schedules and raw material supply continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Dog Biscuit Market
Pet Care Products
Asia Pacific Pet Diet Market
Pet Care Products
UK Pet Grooming Market
Pet Care Products
Raw Meat Pet Food Market
Pet Care Products
Cat Diets Market
Pet Care Products
Smart Pet Collar Market
Pet Care Products
Dog Seat Belt Market
Pet Care Products
DTC Pet Food Market
Pet Care Products
Mink Oil Market
Pet Care Products
Pet Corrector Spray Market
Pet Care Products
Pet Apparel Market
Pet Care Products
UK Pet Diet Market
Pet Care Products
Pet Grooming Services Market
Pet Care Products
Dog Clothing and Accessories Market
Pet Care Products
Pet Noise Anxiety Market
Pet Care Products
Dog Hoodies Market