
 Pet Care Ingredients Market | 2026-2036
Pet Care Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Care Ingredients Market Analytics
North American rendering and protein processing capacity is restructuring as pet food brands demand higher-grade ingredient segregation. Cargill Incorporated leverages its integrated oilseed and animal protein infrastructure to supply consistent fatty acid profiles for coat health formulations. Darling Ingredients anchors the specialty protein segment through its rendering-to-specialty-ingredient pipeline for premium pet nutrition. BASF SE competes on synthetic vitamin stability, extending shelf-life claims that dry food manufacturers require.
Pet care ingredients comprise functional additives, base nutrients, and sensory enhancers formulated into pet food, treats, grooming solutions, and hygiene products, typically specified by crude protein minimums, ash content limits, and digestibility coefficients exceeding 80% for premium grades. Their primary commercial purpose is to deliver label claims—joint support, skin barrier function, oral health—that command retail price premiums. Nutrition Supplements currently leads product type value contribution as owners seek condition-specific formulations for aging pets, while Naturally Derived ingredient sources are gaining fastest as clean-label expectations migrate from human food. Dog Care dominates application type volume, though Cat Care exhibits higher per-unit ingredient intensity due to obligate carnivore protein requirements and taurine fortification mandates.
The FDA Center for Veterinary Medicine enforces ingredient definitions and facility registration under the Food Safety Modernization Act, while the EU Pet Food Industry Federation coordinates with EFSA on additive authorizations that determine market access for novel ingredients. State-level feed control officials in the United States conduct label audits that reject unsubstantiated health claims, forcing reformulation or marketing adjustment. Stakeholders must monitor evolving maximum permissible levels for heavy metals and mycotoxins, as regulatory tightening in major procurement markets will disqualify suppliers lacking certified testing infrastructure.
Market Dynamics
Ingredient traceability mandates from the FDA Center for Veterinary Medicine and EFSA are compressing supplier qualification timelines while fragmenting procurement authority across brand quality teams and regulatory affairs departments.
Growth Catalysts
- Pet Humanization Trajectory:Owners now evaluate ingredient panels against personal dietary standards, creating specification pressure for human-grade sourcing certifications that command retail premiums.
- EFSA Novel Feed Additive Pathway:Accelerated authorization timelines for functional ingredients enable faster market entry for probiotic and postbiotic formulations targeting digestive health claims.
- Aging Pet Demographics:Veterinary geriatric protocols now incorporate condition-specific supplementation, expanding addressable volume for joint support and cognitive function ingredients.
Market Restraints
- Rendering Capacity Concentration:North American specialty protein supply chains depend on a limited processor base, creating bottleneck risk during facility downtime or contamination events.
- Input Cost Volatility:Fishmeal and krill oil prices fluctuate with Antarctic catch quotas and El Niño patterns, compressing margin stability for omega-3 fortified formulations.
- Regulatory Asynchrony:Divergent heavy metal thresholds between FDA and EU Pet Food Industry Federation standards force dual-track testing or market-specific SKU proliferation.
Strategic Opportunities
- Insect Protein Scale-Up:Black soldier fly larvae cultivation in the Netherlands and France offers deforestation-free amino acid sourcing that satisfies ESG procurement criteria.
- Veterinary Channel Integration:Prescription therapeutic diets create captive ingredient demand with multi-year formulation lock-in and premium pricing power.
- Precision Fermentation:Microbial collagen and casein production eliminates animal agriculture dependency while delivering batch-to-batch consistency impossible in conventional rendering.
Industry Challenges
- Traceability Infrastructure Capex:Blockchain-enabled lot tracking and third-party audit certification require seven-figure technology investments that mid-tier suppliers struggle to amortize.
- Formulation Talent Scarcity:Veterinary nutrition PhDs capable of translating clinical research into palatable, shelf-stable matrices command compensation premiums that strain R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Care Ingredients Market |
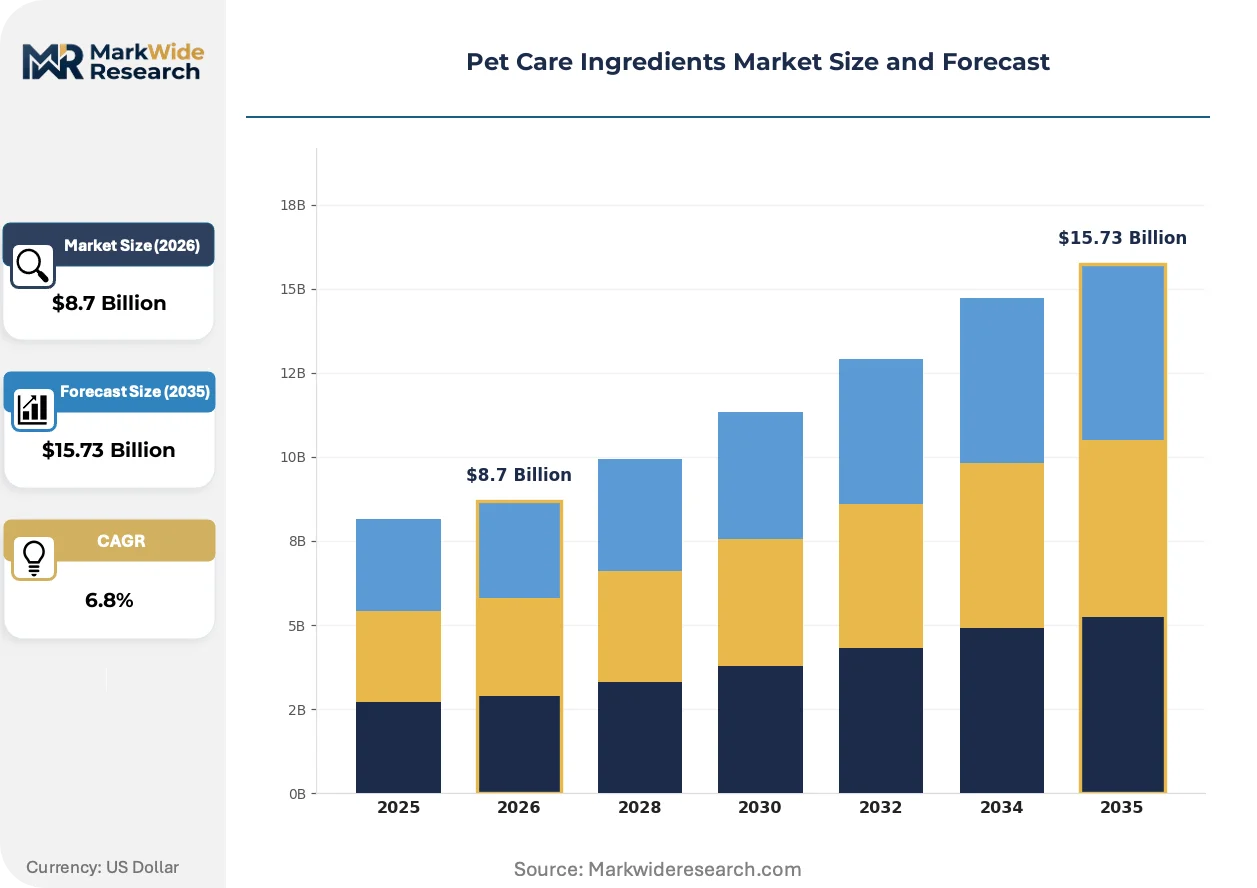
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nutrition Supplements, Grooming Products, Health Additives, Cleaning Agents Ingredient Source: Naturally Derived, Synthetic, Organic, Conventional Application Type: Dog Care, Cat Care, Small Animal Care, Aquatic Care Formulation Type: Liquid, Powder, Solid, Gel |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company, Darling Ingredients, BASF SE, DSM-Firmenich AG, Symrise AG, Tyson Foods, Kemin Industries, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Care Ingredients Market Evolving Landscape
Clean-label migration and biotechnology maturation are restructuring how ingredient value gets created, measured, and communicated through the pet food supply chain.
Spray-dried plasma and hydrolyzed protein isolates are overtaking traditional meat meals as the preferred palatability drivers in premium kibble formulations. Dry food manufacturers in the United States and Germany now specify minimum digestibility coefficients above 90 percent, forcing renderers to invest in low-temperature processing equipment that preserves protein bioavailability. This equipment transition is compressing margins for commodity-grade suppliers unable to justify capital redeployment.
REACH candidate list expansion and EU Green Deal carbon border adjustments are reshaping sourcing economics for synthetic vitamin and amino acid imports. Manufacturers importing Chinese-produced feed-grade additives now face documentation burdens for substance volume tracking and lifecycle emissions verification. The specialty premix segment is responding by accelerating European contract manufacturing partnerships that shorten regulatory distance to end customers.
Direct-to-consumer subscription models for fresh-frozen pet meals are fragmenting traditional distributor relationships that long controlled ingredient specification authority. Brand owners now contract directly with protein processors for custom grind specifications, bypassing regional feed ingredient brokers. This disintermediation concentrates most visibly in urban corridors of the United States where cold-chain logistics infrastructure supports weekly delivery frequencies.
Pet Care Ingredients Market Segmentation
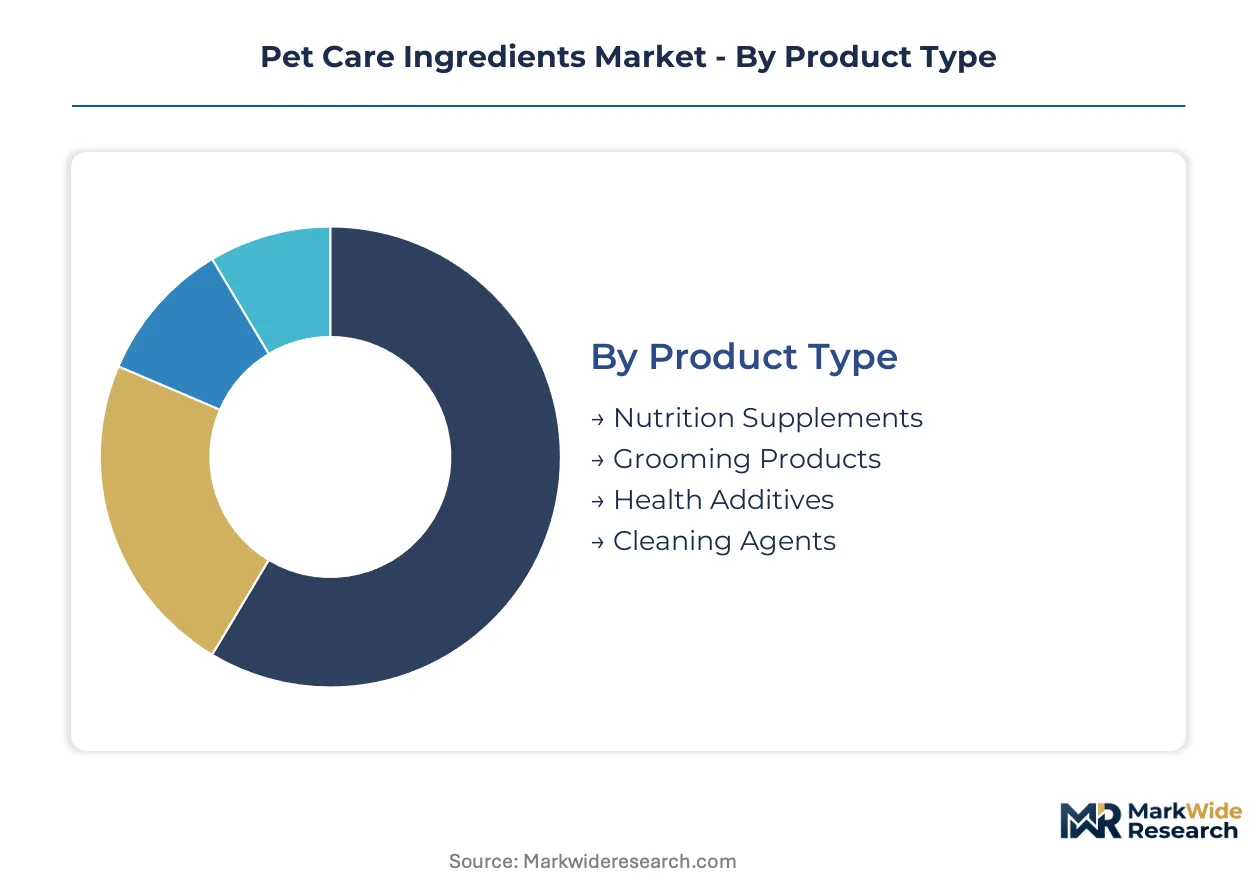
Pet care ingredient procurement follows distinct specification pathways where formulation requirements, regulatory classifications, and end-use performance standards intersect. Each segment carries unique certification burdens and supply chain qualification protocols that determine supplier eligibility and pricing power.
Product Type:
Certification requirements vary sharply across product types, with FDA Center for Veterinary Medicine oversight concentrating on nutrition supplements while grooming products fall under separate cosmetic safety protocols.
- Nutrition Supplements:Condition-specific formulations incorporating glucosamine, omega fatty acids, and probiotics for joint mobility, cognitive function, and digestive health. Demand concentrates in the United States where aging pet demographics drive veterinary-recommended supplementation protocols for geriatric dogs. EFSA novel feed additive authorizations govern European market entry for probiotic strains.
- Grooming Products:Coat conditioners, skin barrier formulations, and oral care solutions containing functional actives like chlorhexidine and essential fatty acids. German and French premium pet retailers specify COSMOS organic certification for surfactant ingredients, creating sourcing bottlenecks for conventional suppliers.
- Health Additives:Preservative systems, palatability enhancers, and digestibility modifiers integrated during extrusion or canning processes.
- Cleaning Agents:Enzymatic stain removers and odor neutralizers for litter boxes, bedding, and habitat maintenance applications.
Nutrition Supplements sits at the top of the volume ranking, with Health Additives climbing the fastest as clean-label preservation systems displace synthetic alternatives.
Ingredient Source:
Cost tier stratification separates premium-positioned sources commanding retail price multiples from commodity-grade alternatives competing on input cost minimization.
- Naturally Derived:Plant extracts, marine proteins, and fermentation-derived actives meeting clean-label procurement criteria. Black soldier fly larvae protein from Dutch and French cultivation facilities supplies deforestation-free amino acid profiles that satisfy ESG mandates from United Kingdom and Scandinavian pet food brands. REACH documentation burdens constrain Chinese-imported natural extracts.
- Synthetic:Laboratory-produced vitamins, amino acids, and preservatives delivering batch-to-batch consistency and extended shelf stability. BASF SE and DSM-Firmenich anchor European synthetic vitamin supply, with EU Green Deal carbon border adjustments reshaping import economics for Asian-manufactured feed-grade additives.
- Organic:USDA Organic or EU Organic certified ingredients requiring segregated handling and third-party audit trails throughout processing.
- Conventional:Standard agricultural and rendering-derived inputs without certification premiums, dominating volume in economy-tier formulations.
Naturally Derived sources sit at the top of the volume ranking, with Organic climbing the fastest as subscription fresh-food brands mandate certified supply chains.
Application Type:
Per-unit ingredient intensity varies dramatically by species physiology, with obligate carnivore requirements mandating higher protein fortification and specific amino acid supplementation.
- Dog Care:Omnivore-tolerant formulations spanning dry kibble, wet food, treats, and dental chews with flexible carbohydrate inclusion. United States dry food manufacturers specify minimum 90 percent digestibility coefficients, forcing renderers toward low-temperature processing equipment investments.
- Cat Care:Taurine fortification mandates and elevated crude protein minimums drive per-kilogram ingredient cost premiums. Japanese and South Korean urban pet owners concentrate demand for single-protein-source formulations addressing food sensitivity concerns.
- Small Animal Care:Rabbit, guinea pig, and rodent formulations emphasizing fiber content and vitamin C stability in extruded pellets.
- Aquatic Care:Specialized binders, color enhancers, and water stability requirements for ornamental fish nutrition.
Dog Care sits at the top of the volume ranking, with Cat Care climbing the fastest as premium wet food and fresh-frozen formats gain share.
Formulation Type:
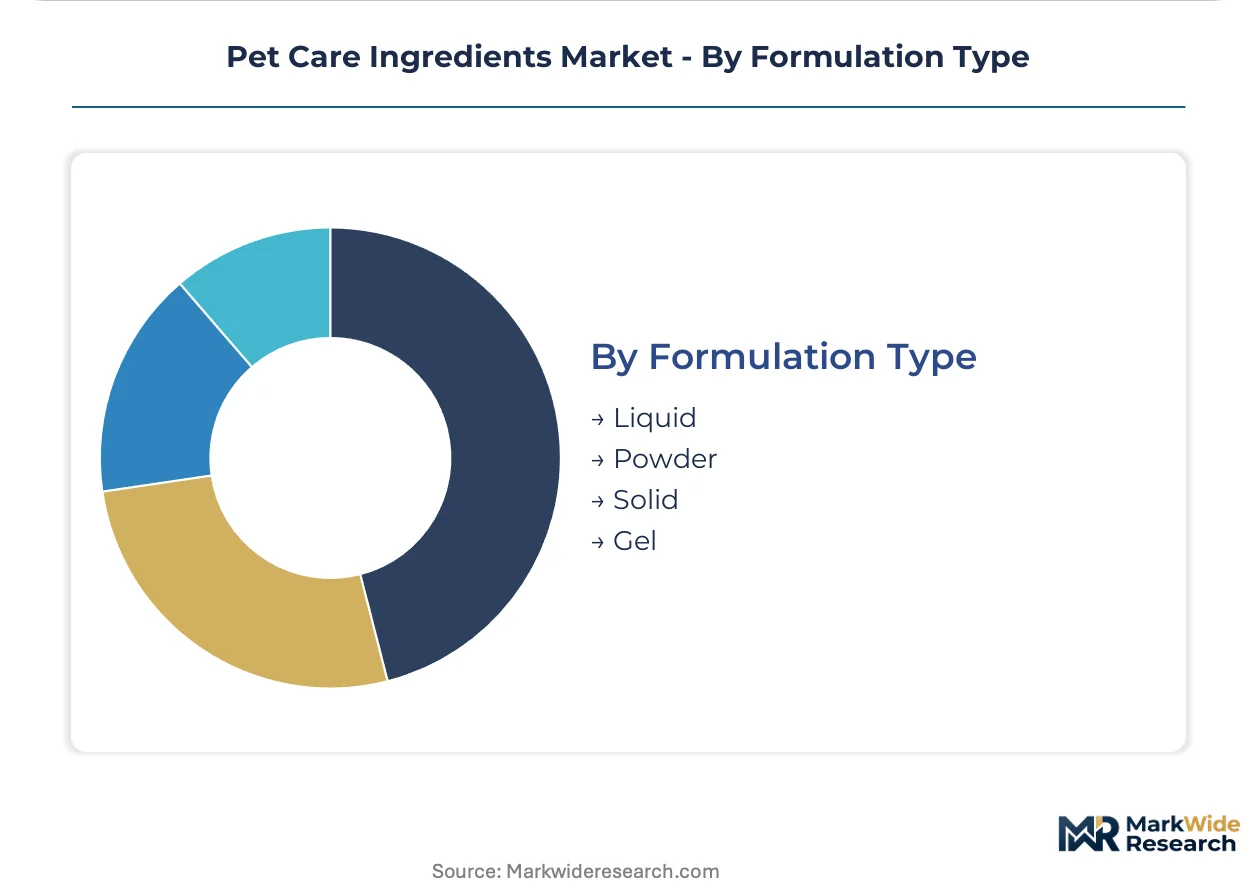
Supply concentration clusters around powder processing infrastructure, with liquid and gel formats requiring specialized equipment that fragments manufacturing capacity.
- Liquid:Oil-based suspensions, emulsions, and aqueous solutions for pump dispensing or coating applications. Omega-3 fish oil and krill oil concentrates face price volatility from Antarctic catch quota fluctuations and El Niño disruption patterns.
- Powder:Spray-dried plasma, hydrolyzed protein isolates, and premix vitamins dominating industrial-scale pet food manufacturing. Powder handling infrastructure concentrates in Midwestern United States rendering corridors and Northern European oilseed processing hubs.
- Solid:Extruded pellets, compressed tablets, and freeze-dried formats for treat and supplement delivery.
- Gel:Semi-solid matrices for topical skin applications and oral administration of medications or supplements.
Powder sits at the top of the volume ranking, with Liquid climbing the fastest as oil-based functional ingredients displace dry alternatives for palatability and bioavailability claims.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ingredient procurement intensity in the United States exceeds that of Germany by roughly threefold, though Dutch and French cultivation facilities now supply deforestation-free protein alternatives that satisfy ESG mandates from United Kingdom and Scandinavian brands.
United States
Pet humanization trends drive premium ingredient procurement across wet food, treats, and supplements, with owners evaluating panels against personal dietary standards. FDA Center for Veterinary Medicine enforces ingredient definitions and facility registration under the Food Safety Modernization Act. Midwestern rendering corridors concentrate powder handling infrastructure as dry food manufacturers specify minimum 90 percent digestibility coefficients.
Germany
Premium pet retailers specify COSMOS organic certification for surfactant ingredients in grooming products, creating sourcing bottlenecks for conventional suppliers. EFSA coordinates with the EU Pet Food Industry Federation on additive authorizations that determine market access. Northern European oilseed processing hubs anchor synthetic vitamin and premix manufacturing capacity serving continental formulation demand.
Netherlands
Black soldier fly larvae cultivation facilities supply deforestation-free amino acid profiles that satisfy ESG procurement criteria from United Kingdom and Scandinavian brands. REACH candidate list expansion and EU Green Deal carbon border adjustments reshape sourcing economics for imported feed-grade additives. Dutch contract manufacturing partnerships shorten regulatory distance to end customers in premium premix segments.
France
Premium wet food and fresh-frozen formats gain share among urban pet owners, driving per-kilogram ingredient cost premiums for taurine fortification and elevated crude protein minimums. EFSA novel feed additive authorizations govern European market entry for probiotic strains targeting digestive health claims. French cultivation facilities expand insect protein scale-up alongside Dutch counterparts.
Japan
Urban pet owners concentrate demand for single-protein-source formulations addressing food sensitivity concerns in obligate carnivore diets. The country's national veterinary regulator enforces taurine fortification mandates and label audits that reject unsubstantiated health claims. Tokyo-Osaka logistics corridors support cold-chain infrastructure for fresh-frozen meal delivery subscriptions.
Pet Care Ingredients Market Competitive Landscape
North American integrated agribusinesses anchor one tier; European chemical and specialty ingredient specialists hold formulation technology positions. The vendor base stratifies across three structural tiers: multinational conglomerates with oilseed and protein infrastructure, rendering-to-specialty processors with segregation capabilities, and synthetic vitamin manufacturers competing on batch stability. Dominant competitive moves include backward integration into rendering capacity and geographic expansion through European contract manufacturing partnerships.
Within the integrated agribusiness tier, Cargill Incorporated exemplifies supply chain control spanning oilseed crushing through animal protein processing. Darling Ingredients occupies a position in the rendering-to-specialty transformation segment, converting raw materials into premium nutrition inputs. BASF SE anchors the synthetic vitamin stability segment where extended shelf-life claims determine dry food manufacturer procurement decisions. These three entities represent distinct archetypes rather than direct competitors, each commanding specification authority across separate ingredient categories.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Darling Ingredients |
| BASF SE |
| DSM-Firmenich AG |
| Symrise AG |
| Tyson Foods |
| Kemin Industries |
| Evonik Industries AG |
| Others |
Value Network & Pricing Analysis
Family-owned rendering specialists in the Midwestern United States anchor specialty protein supply, their consolidation-resistant ownership preserving pricing discipline even as multinational agribusinesses scale adjacent oilseed processing. This ownership pattern concentrates bargaining power upstream while downstream pet food brands fragment procurement authority across quality teams and regulatory affairs departments.
Pricing Analysis
Capacity additions in the Netherlands and France are reshaping price floors for deforestation-free amino acid sourcing as black soldier fly larvae cultivation scales. Three-tier pricing structure across premium, standard, and economy levels separates human-grade certified ingredients from commodity-grade rendered proteins. Cost compression in economy-tier formulations is intensifying because dry food manufacturers specify minimum digestibility coefficients above 90 percent. Small independent pet food brands exhibit highest price sensitivity; prescription therapeutic diet manufacturers show lowest sensitivity due to multi-year formulation lock-in agreements.
Supply Chain Analysis
Frozen logistics costs from Dutch cultivation facilities to United Kingdom and Scandinavian cold-chain hubs constrain margin capture for insect protein suppliers. Geographic supply concentration clusters in the United States, Netherlands, and Germany, with Midwestern rendering corridors feeding North American dry food demand. Raw material dependencies center on fishmeal and krill oil from Antarctic fisheries, oilseed crush byproducts, and rendered animal proteins. Single-source vulnerability runs through concentrated North American specialty protein processing capacity. Distribution runs through regional feed ingredient brokers facing disintermediation from direct-to-consumer subscription brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Pet Care Ingredients Market reads as a late-cycle quality story where pet humanization trends have shifted demand toward human-grade certification standards that command retail price premiums and lock in supplier relationships.
For Market Incumbents: Deepen backward integration into rendering capacity with low-temperature processing equipment that preserves protein bioavailability above 90 percent digestibility thresholds. Consolidate formulation talent pools through veterinary nutrition PhD retention programs before compensation premiums strain R&D budgets further. Threat substitution from precision fermentation collagen and casein production demands defensive patent positioning around palatability matrix technologies.
For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models for fresh-frozen pet meals that bypass established regional feed ingredient broker relationships. Target white-space in single-protein-source cat formulations for Japanese and South Korean urban owners addressing food sensitivity concerns. Pursue EFSA novel feed additive authorization pathways for probiotic strains targeting digestive health claims as the fastest regulatory route to European market entry.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier suppliers lacking blockchain-enabled lot tracking infrastructure required by FDA Center for Veterinary Medicine traceability mandates. Long-term viability favors rendering-to-specialty processors with segregation capabilities and European contract manufacturing partnerships that shorten regulatory distance to end customers. Watch ESG procurement criteria adoption rates among United Kingdom and Scandinavian brands as the inflection signal for insect protein demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Low-Temperature Rendering | Preserves protein bioavailability above 90 percent digestibility thresholds demanded by United States dry food manufacturers. |
| EFSA Novel Feed Additive Authorization | Accelerates European market entry for probiotic and postbiotic formulations targeting digestive health claims. |
| Blockchain-Enabled Lot Tracking Deployment | Satisfies FDA Center for Veterinary Medicine traceability mandates that compress supplier qualification timelines. |
| Precision Fermentation Scale-Up | Eliminates animal agriculture dependency while delivering batch-to-batch consistency impossible in conventional rendering. |
| Veterinary Channel Integration | Creates captive ingredient demand with multi-year formulation lock-in through prescription therapeutic diet partnerships. |
Research Methodology
Coverage spans the United States, Germany, Netherlands, France, and Japan, with primary inputs from each market combined with secondary validation across regulatory filings and trade databases. Primary interviews engaged pet food formulation directors, rendering facility operations managers, veterinary nutrition specialists, EFSA regulatory affairs consultants, and premium retail category buyers. Secondary sources incorporated FDA Center for Veterinary Medicine facility registration records, EU Pet Food Industry Federation additive authorization databases, customs and trade flow data, and SEC 10-K disclosures from publicly traded agribusinesses. Bottom-up volume modeling triangulated against top-down market sizing from industry federation statistics.
Granularity-level framing applied separate modeling for each product type, ingredient source, application type, and formulation type across the analysis window. Segmentation dimensions included condition-specific nutrition supplements versus grooming products, naturally derived versus synthetic versus organic sourcing tiers, dog versus cat versus small animal care applications, and powder versus liquid versus solid delivery formats. CAGRs derived from regression analysis against pet demographic trends, regulatory authorization timelines, and ESG procurement adoption curves. Industry-specific inputs captured Antarctic krill catch quota volatility, El Niño pattern impacts on fishmeal pricing, and REACH candidate list expansion effects on synthetic vitamin import economics.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory asynchrony between FDA and EU heavy metal thresholds or contamination events in concentrated North American rendering capacity. Forecasts reflect assumptions around pet humanization trend sustainability, EFSA authorization pathway efficiency, and cold-chain infrastructure expansion for fresh-frozen formats. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Sensitive Stomach Cat Food Market
Pet Care Products
Canada Pet Boarding Market
Pet Care Products
Dog Box Market
Pet Care Products
Cat Mat Market
Pet Care Products
Pet Care Market
Pet Care Products
Global Pet Supplies Market
Pet Care Products
Europe Organic and Natural Pet Food Market
Pet Care Products
Dog Water Bottle Market
Pet Care Products
North America Dog Food Market
Pet Care Products
Pet Food Nutraceutical Market
Pet Care Products
Dog Bowl Market
Pet Care Products
Pet Corrector Spray Market
Pet Care Products
UAE Dog Food Market
Pet Care Products
Pet Water Dispenser Market
Pet Care Products
Cat Diffuser Market
Pet Care Products
Pet Grooming Market